
 Bridge Expansion Joint Market | 2026-2036
Bridge Expansion Joint Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Expansion Joint Market Analysis
Modular system bundling is pivoting how infrastructure buyers configure expansion joint procurements, shifting from discrete component orders to integrated movement-system packages. Mageba SA leverages its Swiss engineering heritage to dominate complex modular joint tenders for long-span bridges. Watson Bowman Acme sustains its position through deep vertical integration in elastomeric bearing and joint manufacturing. Maurer SE anchors European rail bridge projects with seismic-rated finger joint systems.
A bridge expansion joint is a structural device installed at bridge deck discontinuities to accommodate thermal movement, traffic loading, and seismic displacement while maintaining a continuous riding surface; these assemblies typically incorporate steel reinforcement plates, elastomeric seals, and sliding surfaces engineered for specific movement ranges up to several meters. The primary commercial purpose is to protect superstructure and substructure elements from damage induced by unrestrained deformation, thereby extending service life and reducing lifecycle maintenance costs. Modular joints command premium positioning in high-movement highway applications where multi-directional displacement capacity justifies higher installed cost. Finger joints maintain stable demand in rail bridge contexts where wheel load transfer and drainage control override seal-based alternatives. Compression joints occupy cost-sensitive retrofit segments where limited movement ranges permit simpler elastomeric solutions.
The Federal Highway Administration enforces load-rating and inspection protocols that mandate expansion joint condition assessment within National Bridge Inventory standards, directly shaping replacement scheduling and product specification across US state departments of transportation. European Committee for Standardization frameworks including EN 1990 and EN 1991 govern product performance testing, creating compliance barriers for non-certified suppliers seeking access to EU public procurement channels. Stakeholders must monitor evolving material specifications for ultra-high-performance concrete compatibility and accelerated bridge construction timelines that compress installation windows.
Market Dynamics
Federal infrastructure legislation across the United States is compressing installation timelines for bridge expansion joint systems while simultaneously tightening certification requirements for materials used in accelerated bridge construction projects.
Growth Catalysts
- US Federal Infrastructure Investment:The Infrastructure Investment and Jobs Act mandates systematic bridge condition assessment and replacement scheduling, directly expanding procurement volumes for modular joint systems through state departments of transportation.
- REACH Compliance Expansion:European Committee for Standardization frameworks including EN 1990 and EN 1991 are mandating performance testing protocols that favor certified suppliers with established EU manufacturing footprints.
- Ultra-High-Performance Concrete:Material specification evolution toward UHPC compatibility is creating premium product tiers that command higher installed costs and extend replacement cycles.
Market Restraints
- Steel Price Volatility:Reinforcement plate and structural steel input costs fluctuate with commodity markets, compressing margin stability for manufacturers without backward integration into raw material sourcing.
- German Supply Concentration:Critical elastomeric seal compound production clusters in the Rhineland region, creating geographic vulnerability to regional logistics disruptions or energy cost spikes.
- Modular Joint Cost Premium:Multi-directional displacement capacity systems carry installed costs significantly above compression joint alternatives, limiting penetration in cost-sensitive municipal retrofit budgets.
Strategic Opportunities
- India Highway Modernization:National highway expansion programs under the Ministry of Road Transport and Highways are creating first-time specification opportunities for international joint system suppliers with BIS certification pathways.
- Seismic-Rated Rail Systems:European rail bridge rehabilitation is accelerating demand for finger joint configurations with enhanced wheel load transfer characteristics and integrated drainage control.
- Digital Condition Monitoring:Sensor-embedded joint systems enabling real-time displacement tracking are opening predictive maintenance service revenue streams beyond hardware sales.
Industry Challenges
- Welding Certification Bottlenecks:Qualified structural steel welders for field installation of modular joint systems face acute shortages in North American construction labor markets, compressing project completion schedules.
- Multi-Standard Compliance:Suppliers must simultaneously maintain AASHTO, EN, and ISO certification portfolios, fragmenting quality management resources and extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Expansion Joint Market |
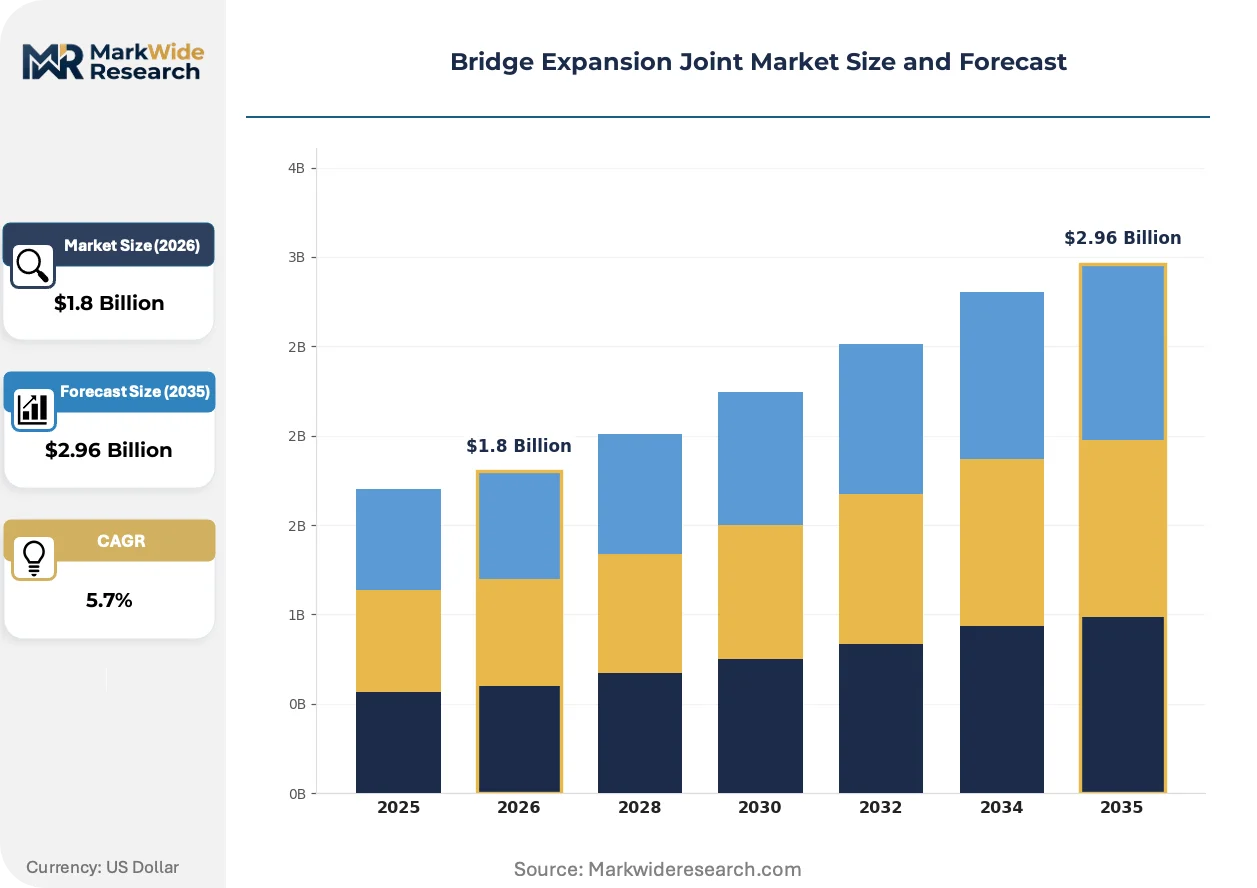
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Joints, Modular Joints, Finger Joints, Compression Joints Material: Rubber, Steel, Silicone, Neoprene Application: Highway Bridges, Rail Bridges, Pedestrian Bridges, Overpasses End User: Government Agencies, Contractors, Infrastructure Developers, Engineers |
| Companies Covered | Mageba SA, Watson Bowman Acme, Maurer SE, RJ Watson, Trelleborg AB, D.S. Brown Company, Gumba GmbH & Co. KG, Ekspan, Canam Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Expansion Joint Market Emerging Trajectories
Material science advances and regulatory pressure on lifecycle performance are forcing product architecture changes across bridge expansion joint categories, with particular acceleration in sensor integration and prefabrication methods.
Self-healing elastomeric compounds with embedded microcapsule repair agents are decentralizing maintenance scheduling for highway expansion joints. State transportation departments in California and Texas are piloting these systems on high-traffic corridors. The technology is decentralizing service contract structures away from reactive replacement toward performance-guaranteed longevity models.
The Federal Highway Administration's National Bridge Inventory standards now mandate documented expansion joint condition assessment at fixed inspection intervals. This regulatory pressure is forcing asset management software adoption among state departments of transportation. Long-span bridge operators with complex modular joint inventories face the steepest compliance cost increases.
Integrated movement-system packages are displacing discrete component procurement across major highway rehabilitation programs. Engineering-procurement-construction contractors now specify complete joint assemblies rather than sourcing seals, bearings, and sliding surfaces separately. This bundling behavior concentrates most visibly in German autobahn bridge tenders where single-source accountability reduces interface risk.
Bridge Expansion Joint Market Segmentation
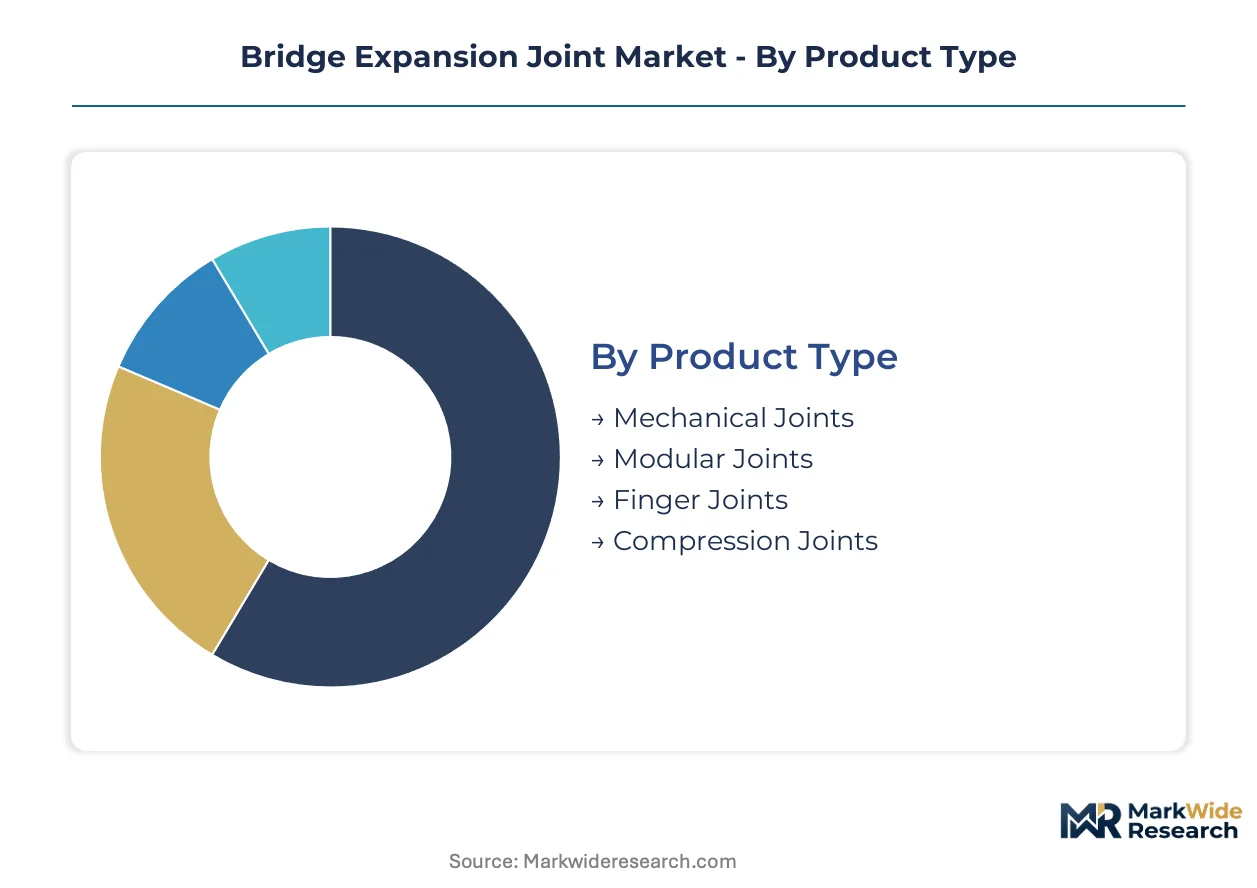
Bridge expansion joint procurement channels fragment sharply across certification regimes, with Federal Highway Administration mandates governing US highway awards while EN 1990 frameworks filter European public tenders. Material specification evolution and installation method requirements create divergent margin structures across segment boundaries.
Product Type:
Certification burden concentrates heaviest on modular and finger joint systems, where seismic-rated performance testing under AASHTO and EN standards extends development timelines and factory audit requirements.
- Modular Joints:Multi-directional displacement assemblies incorporating steel reinforcement plates, elastomeric seals, and sliding surfaces engineered for movement ranges exceeding 500mm. Procurement volumes are concentrating in German autobahn rehabilitation programs where single-source accountability requirements favor integrated system packages.
- Finger Joints:Cantilevered steel plate configurations permitting longitudinal movement while maintaining wheel load transfer integrity. European rail bridge operators in Switzerland and Austria specify these systems where drainage control and seismic displacement capacity override seal-based alternatives.
- Mechanical Joints:Hinged or roller-bearing assemblies for limited movement ranges in low-traffic applications.
- Compression Joints:Elastomeric block systems occupying cost-sensitive municipal retrofit budgets with constrained displacement requirements.
Leading the category by volume: modular joints. Growing fastest: finger joints in rail applications.
Material:
Raw material cost tiers separate premium silicone formulations from commodity rubber compounds, with backward integration into elastomeric seal production determining competitive position.
- Steel:Reinforcement plates and structural members subject to commodity price volatility, with Rhineland-region production clusters creating geographic supply vulnerability.
- Rubber:Conventional elastomeric compounds for compression joint seals in cost-sensitive highway maintenance contracts.
- Silicone:High-performance formulations commanding installed cost premiums for ultra-high-performance concrete compatibility in accelerated bridge construction timelines.
- Neoprene:Chloroprene-based seals maintaining stable demand in moderate-climate installations where temperature cycling extremes remain limited.
Steel dominates absolute tonnage. Silicone formulations are climbing the fastest as UHPC specifications proliferate.
Application:
Movement range requirements and traffic loading intensity create distinct engineering specifications across bridge categories, with inspection protocol stringency varying by infrastructure owner type.
- Highway Bridges:Heavy-vehicle loading and thermal expansion cycles drive specification toward modular systems with multi-directional displacement capacity. California and Texas state transportation departments are piloting self-healing elastomeric compounds on high-traffic corridors.
- Rail Bridges:Wheel load transfer precision and seismic displacement requirements favor finger joint configurations. Swiss Federal Railways and Austrian Federal Railways anchor European demand for seismic-rated installations.
- Pedestrian Bridges:Limited movement ranges permit simpler compression joint solutions with reduced maintenance scheduling.
- Overpasses:Municipal ownership patterns concentrate procurement in standardized elastomeric seal replacements.
Highway bridges command the largest installed base. Rail bridges are expanding most quickly as European network rehabilitation accelerates.
End User:
Procurement authority concentration shapes contract structure, with government agencies mandating certified supplier lists while contractors seek single-source accountability to reduce interface risk.
- Government Agencies:State departments of transportation and federal infrastructure authorities enforcing National Bridge Inventory inspection protocols that mandate documented expansion joint condition assessment at fixed intervals.
- Contractors:Engineering-procurement-construction firms bundling complete joint assemblies rather than sourcing discrete components, concentrating procurement power in German autobahn tenders.
- Infrastructure Developers:Private concession holders for toll bridge operations specifying performance-guaranteed longevity models with sensor-embedded condition monitoring.
- Engineers:Design consultants influencing specification through load-rating calculations and movement range determinations in early project phases.
Government agencies control the largest procurement volumes. Infrastructure developers are gaining share fastest through public-private partnership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for infrastructure manufacturing in Guangdong and Zhejiang provinces concentrate elastomeric seal production capacity serving domestic highway expansion. These zones attract joint system fabricators through tax holidays and expedited environmental permitting for bridge component exports.
United States
The Infrastructure Investment and Jobs Act directs federal funding toward systematic bridge condition assessment and replacement scheduling. FHWA mandates documented expansion joint evaluation under National Bridge Inventory protocols at fixed inspection intervals. State transportation departments in California and Texas pilot self-healing elastomeric compounds on high-traffic corridors.
Germany
Aging autobahn bridge networks require systematic expansion joint replacement across the federal highway system. European Committee for Standardization frameworks including EN 1990 and EN 1991 govern product performance testing for public procurement eligibility. Engineering-procurement-construction contractors in Bavaria and Baden-Württemberg specify complete joint assemblies rather than discrete components.
China
National highway expansion programs under the Ministry of Transport create sustained demand for modular joint systems in long-span bridge construction. GB standards for bridge bearings and expansion joints establish technical compliance thresholds for domestic and imported products. Manufacturing clusters in the Yangtze River Delta supply compression joint assemblies for cost-sensitive municipal retrofit budgets.
India
National highway modernization under the Ministry of Road Transport and Highways generates first-time specification opportunities for international suppliers. BIS certification pathways govern product approval for public infrastructure tenders. Western and southern states including Maharashtra and Karnataka concentrate procurement activity for rail-over-road bridge rehabilitation.
Switzerland
Swiss Federal Railways anchor European demand for seismic-rated finger joint systems in alpine rail bridge contexts. Swissmedic and federal transportation safety frameworks mandate performance documentation for structural movement devices. Engineering consultancies in Zurich and Geneva influence specification through early-phase load-rating calculations for complex modular joint tenders.
Bridge Expansion Joint Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-intensive procurement channels. The vendor base organizes into three tiers: integrated system suppliers with captive elastomeric production, steel fabricators with modular joint assembly capabilities, and regional seal specialists serving maintenance contract markets. Dominant competitive moves include backward integration into raw material sourcing and strategic partnerships with engineering-procurement-construction contractors seeking single-source accountability.
Among Swiss and German engineering heritage groups, Mageba SA and Maurer SE exemplify the integrated system supplier archetype through their positioning in complex modular joint tenders. Watson Bowman Acme anchors the North American tier with its concentration in elastomeric bearing and joint manufacturing. These three entities represent distinct geographic anchoring strategies: Swiss precision engineering for long-span applications, German rail infrastructure specialization, and North American vertical integration in elastomeric compounds.
| Leading Market Players |
|---|
| Mageba SA |
| Watson Bowman Acme |
| Maurer SE |
| RJ Watson |
| Trelleborg AB |
| D.S. Brown Company |
| Gumba GmbH & Co. KG |
| Ekspan |
| Canam Group Inc. |
| Others |
Supply Flow & Price Mechanics
REACH compliance expansion across European manufacturing zones gates qualified supply for premium-tier expansion joint systems while simultaneously elevating certified product pricing floors above commodity alternatives. German autobahn rehabilitation tenders now specify EN 1990-certified modular assemblies exclusively, compressing procurement pools and reinforcing supplier pricing power for compliant manufacturers.
Pricing Analysis
Margin tightening in compression joint tiers reflects steel reinforcement plate cost volatility and Rhineland elastomeric seal compound supply bottlenecks. Three-tier pricing structure across premium modular, standard finger, and economy compression levels separates AASHTO-certified highway systems from municipal retrofit alternatives. Price differentiation hinges on seismic rating certification and backward integration into silicone formulation production. Municipal transportation departments exhibit acute price sensitivity, while Swiss Federal Railways and German federal highway authorities prioritize displacement capacity over installed cost.
Supply Chain Analysis
Domestic-content mandates in Indian BIS certification pathways and Chinese GB standard enforcement are reshaping sourcing patterns for international joint system suppliers. Manufacturing gravity centers on Germany, Switzerland, and the Yangtze River Delta, with elastomeric seal compound production drawing from Rhineland petrochemical clusters and Chinese silicone processing hubs. Single-source vulnerability concentrates in qualified structural steel welding capacity for field modular joint installation. Distribution runs through engineering-procurement-construction contractor bundling rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-healing elastomeric compound technology is displacing conventional seal maintenance schedules across California and Texas highway corridors, compressing replacement cycle revenues while opening performance-guaranteed service contract structures.
For Market Incumbents: Deepen backward integration into silicone formulation production to defend margin position against commodity elastomer price spikes. Capture AASHTO and EN 1991 certification maintenance as a barrier against emerging Indian and Chinese competitors. Prioritize welding certification pipeline investments to alleviate North American field installation bottlenecks threatening project completion schedules. For New Entrants and Emerging Players: Digital condition monitoring platforms offer a direct route to infrastructure developer procurement channels seeking sensor-embedded predictive maintenance capabilities. Target Indian national highway modernization programs where BIS certification pathways remain penetrable for first-time international suppliers. Lead with performance-guaranteed longevity models rather than hardware-only positioning to differentiate from established modular joint manufacturers. For Investors and Strategic Acquirers: Accelerated bridge construction timeline compression in US federal infrastructure programs is the leading indicator that installation-speed technology will command acquisition premiums. Focus on mid-cap specialists with captive elastomeric production and established EPC contractor relationships. Monitor California Department of Transportation pilot program expansion as the signal for self-healing compound commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Formulation | Captive seal production insulates margin from Rhineland petrochemical cost volatility. |
| Digital Condition Monitoring Platform Launch | Sensor-embedded joints unlock recurring predictive maintenance revenue beyond hardware sales. |
| BIS Certification Pathway Investment | Indian Ministry of Road Transport tenders open first-time specification opportunities for compliant entrants. |
| Welding Certification Pipeline Expansion | Qualified installation labor scarcity in North America compresses project schedules and elevates turnkey contractor value. |
| Self-Healing Elastomer Compound Commercialization | California DOT pilot programs validate performance-guaranteed longevity models displacing reactive replacement contracts. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this bridge expansion joint market assessment. Primary interviews with state department of transportation procurement officers, EPC contractor project managers, structural engineering consultants, and elastomeric seal manufacturing technical directors combined with bottom-up project pipeline tracking and top-down infrastructure spending allocation analysis. Secondary validation drew from FHWA National Bridge Inventory condition assessments, EN standard certification databases, and BIS product approval registries.
Reconciliation of unit installation volumes, material tonnage flows, and certified supplier capacity utilization informed the analytical framework across the projection horizon. Segmentation modeling incorporated product type displacement capacity tiers, material grade certification levels, application-specific loading protocols, and end-user procurement authority concentration. CAGRs derived from bridge rehabilitation scheduling mandates, federal infrastructure appropriation trajectories, and replacement cycle compression factors tied to accelerated construction timelines.
Inputs from state transportation department capital improvement plans and European rail infrastructure renewal announcements were available through the study window; gaps in proprietary EPC contractor margin data introduce uncertainty bands around installed cost forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Europe Structural Health Monitoring Market