
 Cold-Formed Steel Market | 2026-2036
Cold-Formed Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Cold-Formed Steel Market Intelligence
Metal buildings manufacturers is reorganizing procurement priorities toward lightweight, high-strength framing systems for warehouse structures and agricultural buildings. Nucor Corporation leverages its electric arc furnace network to supply thin-gauge structural sections with tight dimensional tolerances. ArcelorMittal anchors European distribution through integrated service centers that preprocess coils for regional fabricators. Tata Steel Group competes on coated cold-formed products engineered for humid climates.
Cold-formed steel comprises thin sheet steel shaped at room temperature through roll forming, press braking, or stamping into profiles with yield strengths typically spanning 33 to 80 ksi, serving primarily as load-bearing or non-structural elements in construction and manufacturing. Steel tubes command premium positioning in long-span warehouse structures where torsional rigidity reduces bracing costs, while steel sheets dominate residential frameworks through panelized wall systems that cut on-site labor. Roll forming leads technology adoption for high-volume continuous profiles, though press braking retains margin pools in custom architectural fabrications where batch sizes resist automation economics.
ISO 10799 governs structural hollow section geometry across international trade, while ASTM A1003 and AISI S240 shape North American product standards and installation methodologies. EPA industrial emissions guidelines and EU Green Deal embodied-carbon benchmarks are tightening mill-level disclosure requirements, forcing producers to document scrap-recycling ratios and energy intensity per ton. Stakeholders must monitor how evolving EPD mandates and local building code amendments reshape material qualification pathways before committing to capacity expansion or geographic diversification.
Market Dynamics
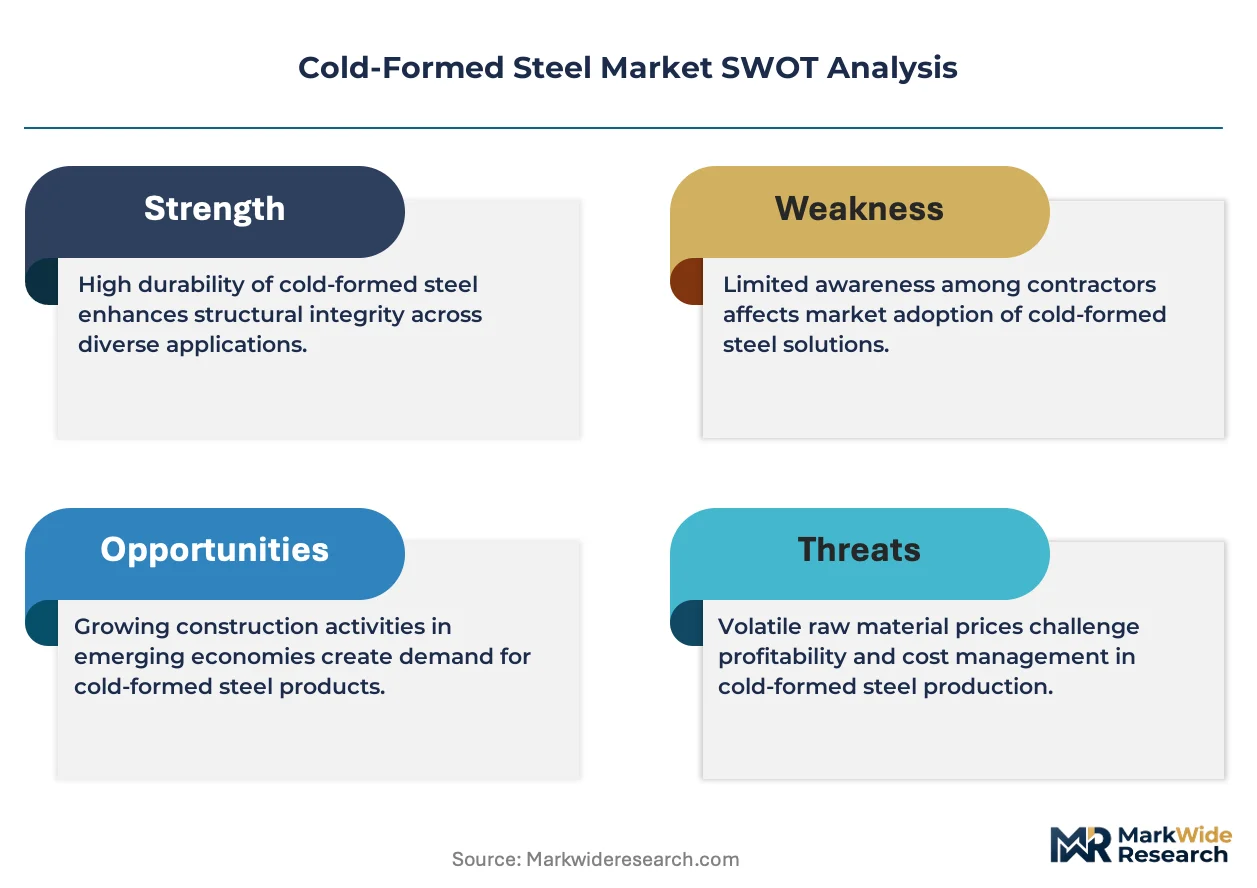
Building code amendments across multiple jurisdictions are accelerating specification shifts toward higher recycled content thresholds, forcing mills to reconfigure melt shop inputs and fabricators to validate supply chain documentation for project compliance.
Growth Catalysts
- EU Green Deal embodied-carbon benchmarks:EU Green Deal embodied-carbon benchmarks tighten mill-level disclosure requirements, compelling producers to document scrap-recycling ratios and energy intensity per ton for qualification.
- Modular construction adoption:Urban housing deficits in India and Southeast Asia concentrate demand for panelized wall systems that cut on-site labor and accelerate project delivery timelines.
- Roll forming technology:Roll forming technology enables high-volume continuous profiles with tight dimensional tolerances, reducing material waste and labor content in residential framework production.
Market Restraints
- Scrap price volatility:Electric arc furnace operators face margin compression when ferrous scrap prices spike, as thin-gauge structural sections cannot absorb input cost swings through pricing power.
- Regional supply concentration:Integrated service centers in Western Europe control preprocessing capacity for regional fabricators, creating bottlenecks when coil availability tightens.
- Dimensional limitations:Cold-formed sections max out at yield strengths around 80 ksi, restricting use in high-rise structural cores where hot-rolled shapes dominate.
Strategic Opportunities
- Coated products for humid climates:Tata Steel Group's coated cold-formed products demonstrate performance validation for Southeast Asian and Indian markets where corrosion resistance extends building lifecycle.
- EPD mandate expansion:EPA industrial emissions guidelines and evolving environmental product declaration mandates create first-mover advantage for mills with verified lifecycle data.
- Agricultural building automation:Metal building manufacturers seek lightweight framing systems for warehouse structures and agricultural buildings, opening specification pathways beyond traditional construction.
Industry Challenges
- Code compliance documentation:ASTM A1003 and AISI S240 installation methodologies require fabricator certification updates, stretching technical training capacity across decentralized contractor networks.
- ISO 10799 geometry validation:Structural hollow section producers must maintain cross-border testing protocols for international trade, adding quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold-Formed Steel Market |
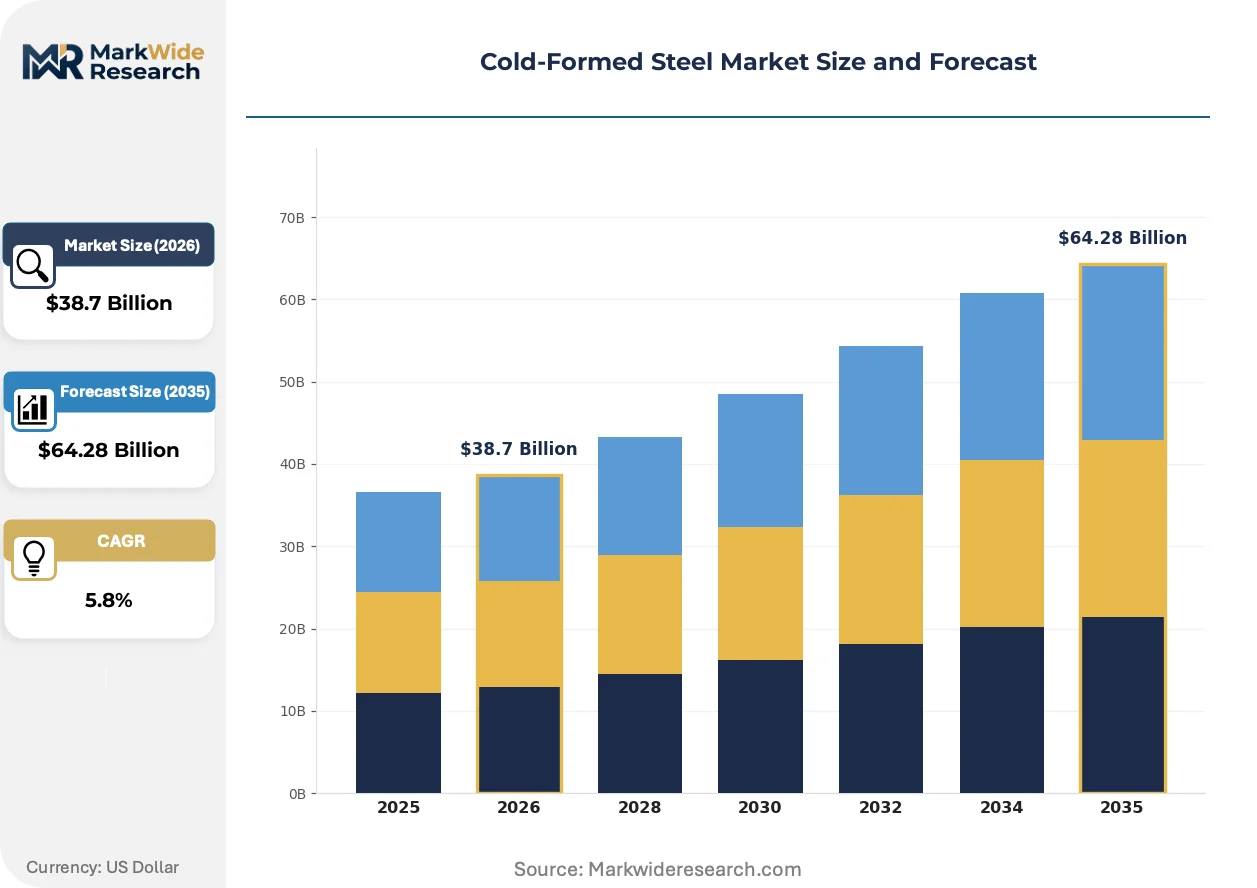
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Sheets, Steel Strips, Steel Coils, Steel Tubes Technology: Roll Forming, Press Braking, Roll Bending, Stamping Application: Warehouse Structures, Commercial Complexes, Agricultural Buildings, Residential Frameworks End User: Construction Companies, Structural Fabricators, Metal Buildings Manufacturers, Steel Distributors |
| Companies Covered | Steel Dynamics, POSCO Holdings, Pinnacle Steel, ArcelorMittal, Tata Steel Group, Nucor Corporation, Nippon Steel Corporation, Jianlong Group, Cleveland-Cliffs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold-Formed Steel Market Strategic Shifts & Innovations
Digital fabrication workflows and automated roll forming lines are compressing lead times for custom profiles, while regulatory pressure on embodied carbon forces material transparency upstream to melt shop operations.
Direct-roll forming with inline punching and notching is displacing traditional press braking for mid-complexity architectural profiles. Warehouse and distribution center developers specify these continuous-formed sections for long-span roof purlins, cutting connection labor by half. The technology is displacing batch fabrication economics in projects above 50 tons of structural steel.
EPA industrial emissions guidelines now require documented scrap-recycling ratios from mills supplying federally funded construction. This disclosure mandate compresses qualification timelines for producers without verified environmental product declarations. Fabricators serving US public infrastructure projects face the steepest compliance ramps.
Buyer concentration among national homebuilders is compressing supplier qualification cycles and unbundling after-sales technical support. Regional roll formers lose specification share to integrated service centers that bundle engineering, coil supply, and panel fabrication. The shift concentrates procurement leverage in the hands of top ten US residential developers.
Cold-Formed Steel Market Segmentation
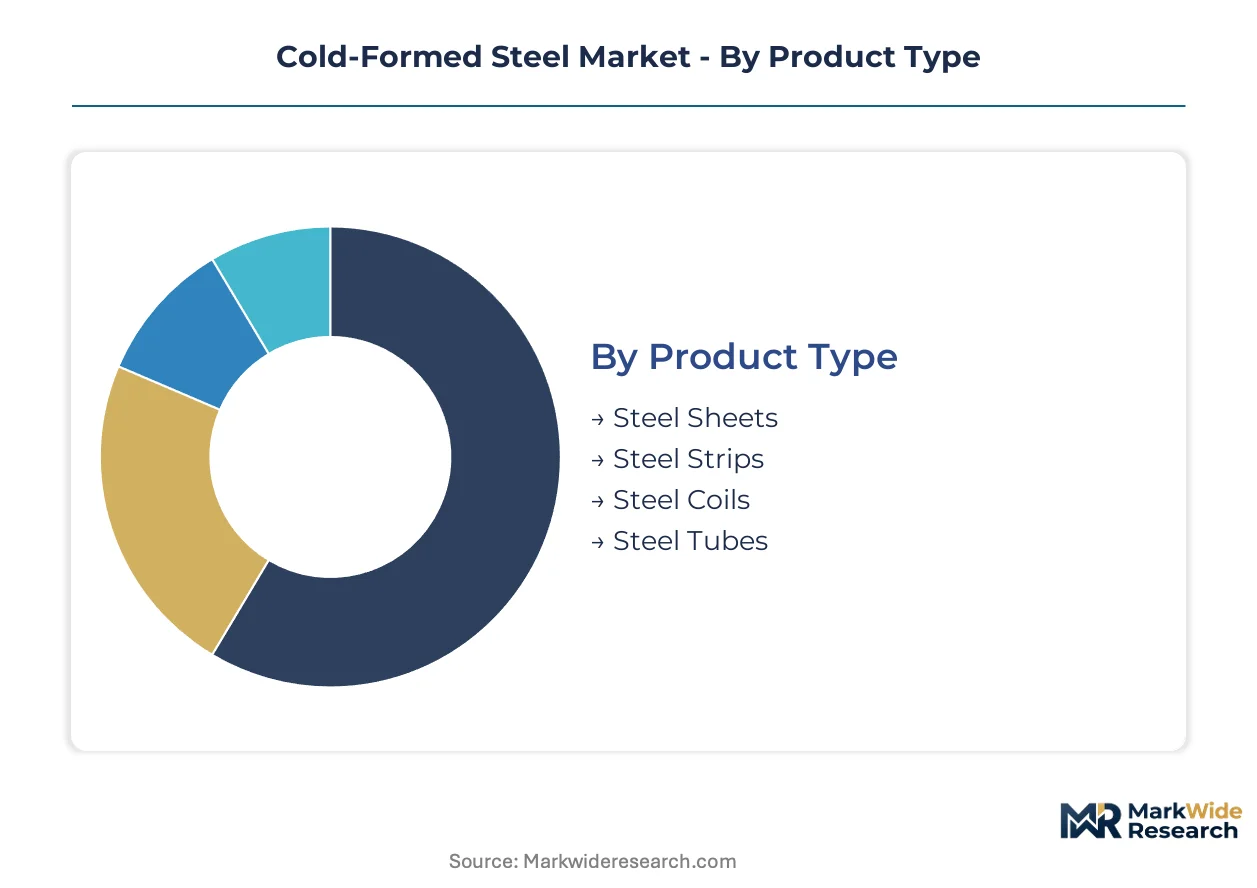
Segmentation in cold-formed steel reveals where substitution pressure from engineered timber and aluminum shapes concentrates most acutely. Manufacturers configure production lines differently depending on whether dimensional tolerance or corrosion resistance governs specification.
Product Type:
Steel tubes face the most acute substitution threat from structural aluminum hollow sections in long-span applications where weight reduction commands premium pricing.
- Steel Sheets:Thin-gauge flat products with yield strengths between 33 and 50 ksi dominate panelized wall systems for residential construction. Demand clusters in India and Southeast Asia where urban housing deficits accelerate modular assembly adoption.
- Steel Strips:Narrow-width coils processed through continuous rolling lines serve purlin and girt applications in metal building systems. Agricultural building automation in the US Midwest and Brazilian grain belt drives specification for pre-punched connection patterns.
- Steel Coils:Master coil formats feed downstream roll forming and slitting operations with zinc coating weights calibrated to humidity exposure.
- Steel Tubes:Structural hollow sections per ISO 10799 geometry standards command premium positioning in warehouse clear-span structures where torsional rigidity reduces diagonal bracing requirements.
Steel sheets retain volume leadership; steel tubes hold the steepest expansion curve.
Technology:
Cost tier differentiation separates high-capital continuous lines from batch-oriented fabrication equipment with lower throughput economics.
- Roll Forming:Continuous rotary bending through sequential die stations produces uniform cross-sections at line speeds exceeding 100 meters per minute. Warehouse and distribution center developers specify these sections for roof purlins above 50-ton steel quantities, cutting connection labor by half.
- Press Braking:Incremental bending between punch and die sets retains margin pools in custom architectural fabrications where batch sizes resist automation economics and geometric complexity exceeds roll forming capability.
- Roll Bending:Pyramid-style three-roll configurations curve structural sections for arched roof systems and circular grain bin construction.
- Stamping:Punch-and-die operations pierce connection holes and notching patterns with positional tolerances matching automated assembly robotics.
Roll forming commands the highest throughput volumes; press braking defends the widest margin percentages.
Application:
Customer type concentration shapes specification pathways differently across project scale and procurement authority structures.
- Warehouse Structures:Long-span clear heights between 9 and 15 meters require steel tube primary frames with bolted moment connections. US distribution center construction concentrates demand in Dallas-Fort Worth, Indianapolis, and Phoenix logistics corridors.
- Residential Frameworks:Load-bearing wall studs and floor joists in panelized systems serve national homebuilder procurement programs with compressed qualification cycles.
- Commercial Complexes:Mid-rise office and retail shells combine cold-formed curtain wall framing with hot-rolled structural cores for lateral force resistance.
- Agricultural Buildings:Equipment storage and livestock housing structures prioritize coated products engineered for humid climates with extended lifecycle requirements.
Warehouse structures retain volume leadership; residential frameworks gain share fastest.
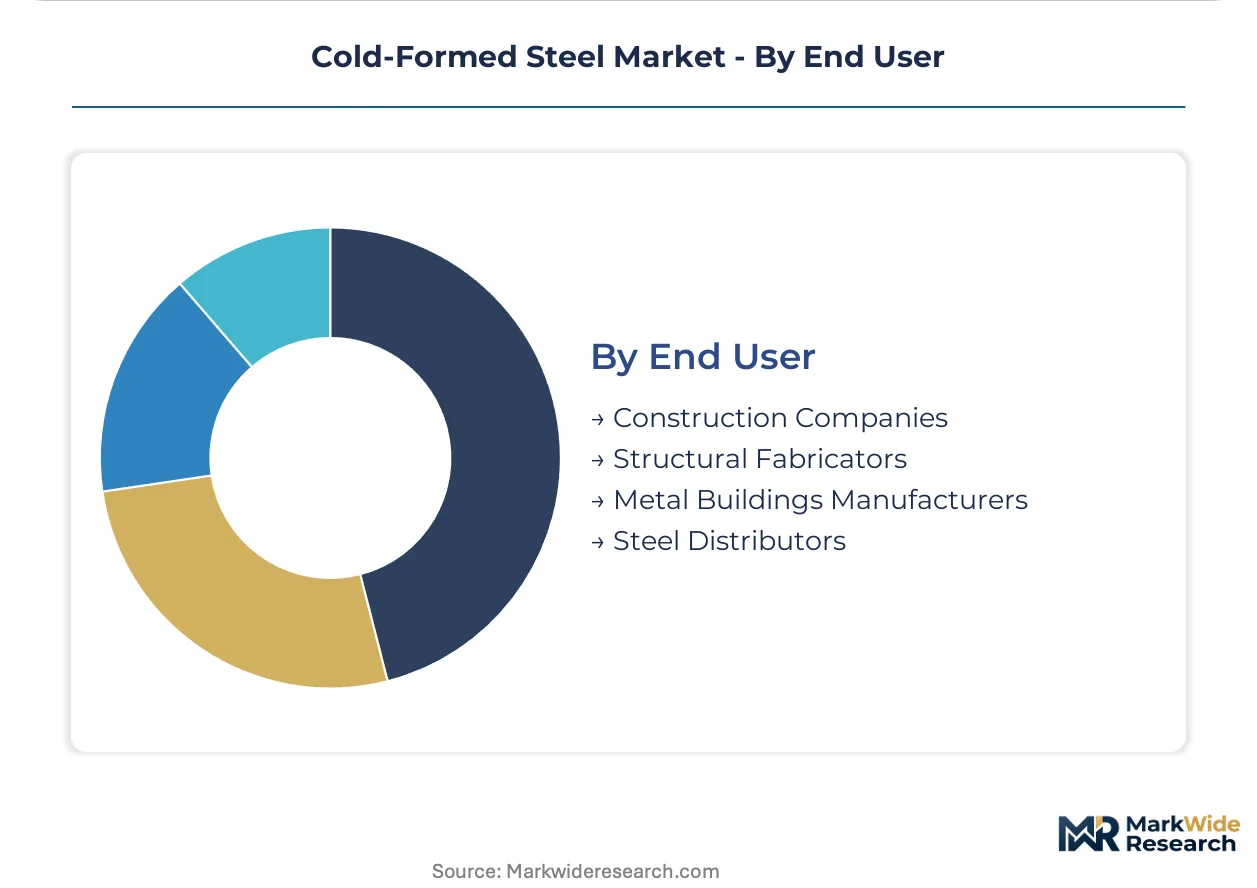
End User:
Supply concentration among integrated service centers reconfigures procurement leverage across decentralized contractor networks.
- Construction Companies:General contractors managing design-build delivery seek pre-engineered framing packages with certified installation documentation for ASTM A1003 compliance.
- Metal Buildings Manufacturers:Integrated producers of warehouse and agricultural structures source master coils for captive roll forming with tight dimensional tolerances.
- Structural Fabricators:Regional shops preprocess hollow sections and angle profiles for project-specific connection detailing.
- Steel Distributors:Stocking service centers buffer coil availability volatility for fabricators without direct mill relationships.
Metal buildings manufacturers retain volume leadership; construction companies represent the steepest procurement consolidation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's steel handling terminals anchor European coil distribution, while the Houston Ship Channel underwrites North American scrap-fed production networks. India's Jawaharlal Nehru Port Trust channels coated coil imports for Southeast Asian fabricators.
United States
EPA industrial emissions guidelines now mandate documented scrap-recycling ratios for mills supplying federally funded construction. The Dallas-Fort Worth logistics corridor concentrates warehouse demand for long-span steel tube primary frames. National homebuilders compress supplier qualification cycles, shifting procurement leverage toward integrated service centers.
Germany
EU Green Deal embodied-carbon benchmarks tighten mill-level disclosure requirements for structural hollow sections. The Ruhr industrial belt hosts preprocessing facilities that calibrate zinc coating weights to humidity exposure. Fabricators serving Dutch and Belgian markets validate cross-border ISO 10799 geometry protocols from German service centers.
India
Urban housing deficits in Maharashtra and Karnataka accelerate modular assembly adoption for panelized wall systems. BIS standards enforcement raises dimensional tolerance requirements for thin-gauge residential framing. The Mundra Port cluster channels master coil imports for captive roll forming operations serving Delhi-NCR construction markets.
China
Dual carbon goals under MIIT oversight compel electric arc furnace operators to verify energy intensity per ton. The Yangtze River Delta concentrates roll forming capacity for warehouse roof purlins above 50-ton steel quantities. Shandong Province fabricators preprocess coils for regional agricultural building automation in the grain belt.
Vietnam
Coastal manufacturing zones near Haiphong attract regional headquarters for Southeast Asian distribution. Humid climate specifications drive coated product validation for extended building lifecycle requirements. The Cai Lan Port steel terminal buffers coil availability for fabricators serving Ho Chi Minh City commercial construction.
Cold-Formed Steel Market Key Industry Players
Concentration sits with integrated steel producers operating electric arc furnace networks and captive service center footprints. Three archetypes dominate: scrap-recycling specialists with verified environmental product declarations, coil preprocessors controlling regional distribution chokepoints, and coated product engineers targeting humid climate markets. Competitive moves center on capacity expansion in Southeast Asian preprocessing hubs and strategic partnerships with national homebuilder procurement programs.
Among North American producers, Nucor Corporation and Steel Dynamics exemplify the scrap-recycling archetype with disclosed melt shop inputs. ArcelorMittal anchors the European preprocessor tier through integrated service center networks. Tata Steel Group occupies the coated product specialist position for corrosion-resistant specifications.
| Leading Market Players |
|---|
| Steel Dynamics |
| POSCO Holdings |
| Pinnacle Steel |
| ArcelorMittal |
| Tata Steel Group |
| Nucor Corporation |
| Nippon Steel Corporation |
| Jianlong Group |
| Cleveland-Cliffs |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between electric arc furnace mills and national homebuilders lock in both scrap supply access and price visibility, insulating procurement teams from ferrous scrap volatility while compressing qualification timelines for project compliance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified EPD-compliant coils from commodity-grade stock and import alternatives. Price differentiation hinges on zinc coating weight and dimensional tolerance certification, with ASTM A1003 compliance commanding measurable premiums. Cost compression in standard-grade residential framing is intensifying because national homebuilders unbundle after-sales technical support. Metal buildings manufacturers show the least price sensitivity due to captive roll forming economics, while regional structural fabricators face the steepest margin pressure from coil availability volatility.
Supply Chain Analysis
The Houston Ship Channel underwrites North American scrap-fed production networks, anchoring melt shop inputs for thin-gauge structural sections. Raw material flows draw from ferrous scrap yards, zinc ingot suppliers, and coating chemical providers. Single-source vulnerability concentrates in integrated service centers controlling preprocessing capacity for regional fabricators. Distribution runs through mill-direct coil programs and stocking service centers buffering availability for decentralized contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panelized wall system interoperability is reshaping procurement authority structures, as national homebuilder platforms consolidate specification pathways and compress supplier qualification cycles across modular construction ecosystems.
For Market Incumbents: Shield margin pools in custom architectural fabrications by deepening press braking capacity where batch sizes resist automation economics. Fortify ASTM A1003 and AISI S240 certification coverage against emerging engineered timber substitution threats in mid-rise residential cores. Prioritize captive service center expansion in Southeast Asian preprocessing hubs to anchor regional distribution chokepoints. For New Entrants and Emerging Players: Differentiate on coated product engineering for humid climate validation, targeting Maharashtra and Karnataka urban housing deficits where corrosion resistance extends building lifecycle. Penetrate agricultural building automation in the US Midwest and Brazilian grain belt through pre-punched connection pattern specialization. Deploy direct-roll forming with inline punching to displace batch fabrication economics in warehouse projects above 50-ton steel quantities. For Investors and Strategic Acquirers: Capital is best deployed toward scrap-recycling specialists with verified environmental product declarations and disclosed melt shop inputs, as EPA industrial emissions guidelines and EU Green Deal embodied-carbon benchmarks reshape material qualification pathways. Watch for EPD mandate expansion signals as inflection indicators for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recycling | Electric arc furnace operators secure ferrous scrap supply access against price volatility through captive yard networks. |
| Coated Product Line Expansion | Tata Steel Group validates corrosion-resistant specifications for Southeast Asian humid climate applications. |
| Service Center Preprocessing Capacity | ArcelorMittal anchors European distribution through integrated facilities calibrating zinc coatings to regional humidity. |
| EPD Certification Investment | Mills with verified lifecycle data capture first-mover advantage as EPA guidelines tighten disclosure requirements. |
| Modular Construction Partnership | Roll formers bundle engineering and panel fabrication for national homebuilder procurement consolidation. |
Research Approach
Initial hypotheses were tested against primary input from electric arc furnace operations managers, metal building manufacturer procurement leads, regional structural fabricators, and national homebuilder supply chain directors, and refined through secondary validation against SEC 10-K filings, customs and trade data, ASTM and ISO technical standards, and EPA industrial emissions disclosures. Bottom-up volume triangulation across product type, technology, and application segments was cross-checked with top-down macroeconomic indicators.
Variance decomposition separates volume growth from price-mix effects across the projection horizon, with segmentation modeled by product type, technology, application, end user, and regional production hub. CAGRs were derived from trend-line extrapolation of historical shipment data adjusted for capacity expansion announcements and regulatory phase-in schedules. Forecast inputs include scrap-recycling ratio disclosures, zinc coating weight specifications, and modular construction adoption curves in India and Southeast Asia.
Forecasts assume regulatory continuity in EPA industrial emissions guidelines and EU Green Deal embodied-carbon benchmarks; material policy shifts would require re-modeling of mill-level qualification pathways. Practitioners should keep alternative scenarios live as building code amendment timelines and EPD mandate expansion patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Structural Steel Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Europe Bridge Bearings Market