
 Tunnel and Metro Fans Market | 2026-2036
Tunnel and Metro Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel and Metro Fans Market Insights
Underground rail infrastructure is hardening as the dominant demand vertical for tunnel and metro fans, displacing traditional road-tunnel applications in procurement priority. Systemair leverages its Nordic engineering heritage to dominate European rail ventilation specifications. Jindun anchors domestic supply chains across China's expanding metro networks. TLT-Turbo GmbH differentiates through high-pressure axial fan designs purpose-built for deep-bore tunnel environments.
Tunnel and metro fans are electromechanical air-movement devices engineered to deliver controlled airflow volumes, pressure differentials, and smoke-extraction velocities in confined underground passages, typically constructed from corrosion-resistant alloys or coated steel with impeller diameters spanning 0.3 to 5 meters. Axial configurations lead installed base volumes due to their straight-through airflow efficiency in longitudinal tunnel ventilation schemes, while mixed flow designs capture expanding margin pools in space-constrained metro stations where footprint restrictions limit pure axial or centrifugal deployment. Fixed installations sustain the majority of revenue given their integration into permanent tunnel infrastructure, though portable units are gaining specification share in emergency response and construction-phase applications.
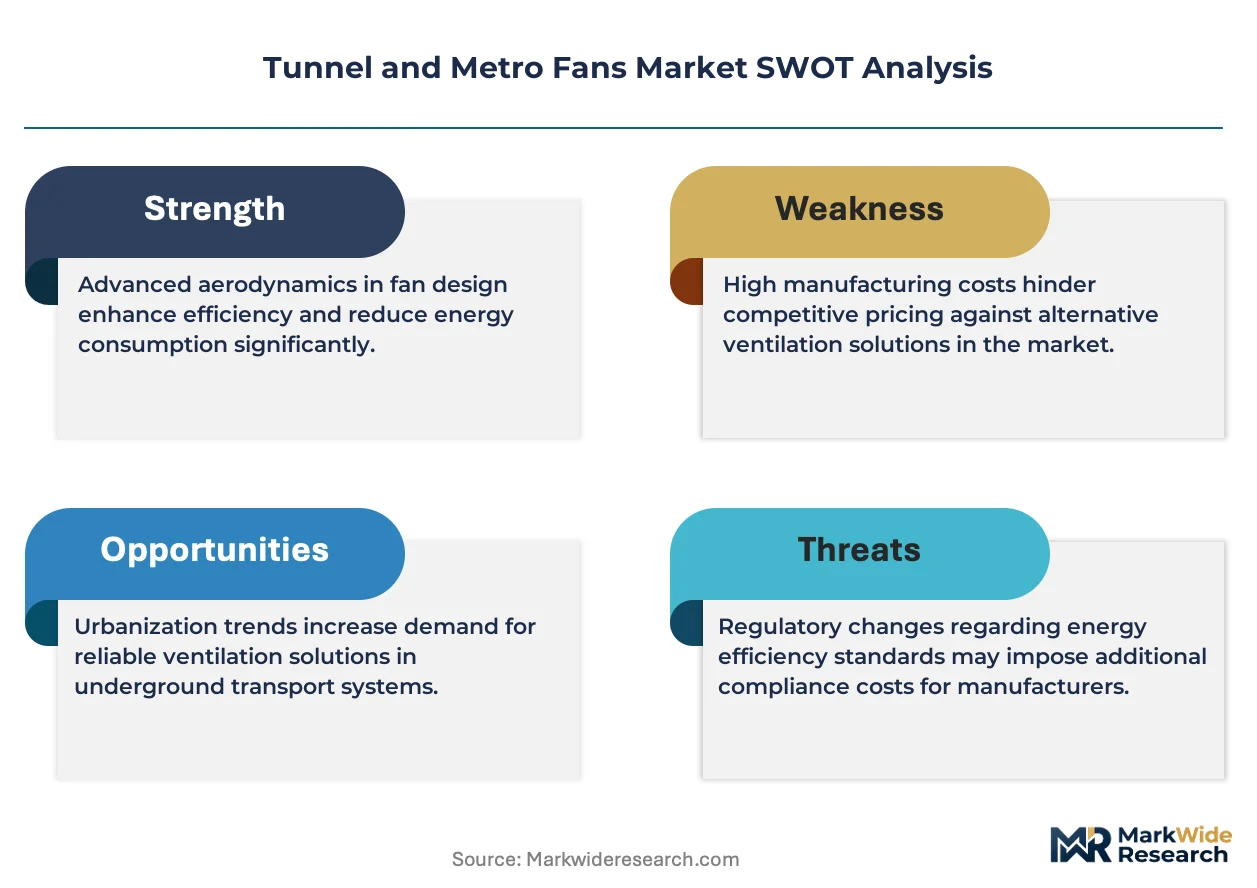
China's GB standards and the EU F-Gas Regulation are tightening energy-efficiency and refrigerant-emission thresholds that directly shape fan motor specifications and thermal management system integration in new tunnel projects. The US EPA and OSHA jointly influence underground construction air quality mandates that determine fan sizing, redundancy requirements, and filtration add-ons in American transit tunnels. Stakeholders must monitor evolving fire safety certification protocols across multiple jurisdictions, as harmonization gaps between national standards continue to fragment cross-border procurement and complicate manufacturer compliance roadmaps.
Market Dynamics
Deep-bore tunnel construction in Southeast Asia and China's high-speed metro corridors is compressing procurement cycles and forcing manufacturers to pre-certify equipment against divergent national fire safety standards before bid submission.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating specification of magnetically levitated bearing systems in tunnel climate control, expanding addressable equipment scope beyond pure ventilation.
- China's GB 50157 metro standard:Updated fire safety clauses mandate redundant smoke-extraction capacity in underground stations, doubling fan count per platform versus legacy designs.
- Variable frequency drive integration:Metro operators in Singapore and Bangkok are retrofitting existing tunnel networks with demand-responsive airflow control, extending equipment replacement cycles while adding control system revenue.
Market Restraints
- Copper and rare-earth magnet costs:Permanent magnet motor cores depend on neodymium supply concentrated in Chinese processing facilities, exposing European and North American manufacturers to input price volatility and export restriction risk.
- Fire certification fragmentation:EN 12101-3, UL 705, and China's CCC fire safety approvals lack mutual recognition, forcing manufacturers to maintain parallel testing programs and inventory SKUs.
- Deep-bore technical ceiling:Single-stage axial fans face pressure limitations beyond 3,000 Pascals in Himalayan and Alpine tunnel projects, requiring costly multi-stage configurations that compress margins.
Strategic Opportunities
- Indonesia's Trans-Sumatra rail corridor:The 1,700-kilometer underground and elevated network represents greenfield specification opportunity without incumbent vendor lock-in.
- Digital twin integration:Convergence of computational fluid dynamics with real-time sensor networks enables predictive maintenance contracts, shifting revenue from equipment sales to recurring service streams.
- India's PLI scheme for rail components:Domestic manufacturing incentives for metro subsystems are opening local assembly pathways for foreign fan manufacturers partnering with Indian engineering firms.
Industry Challenges
- Thermofluids simulation expertise:Deep-bore projects require computational modeling of fire smoke propagation that exceeds traditional HVAC engineering skill sets, creating talent bottlenecks in project execution teams.
- Legacy tunnel retrofit compatibility:1980s-era road tunnels in Japan and Western Europe lack structural clearance for modern jet fan diameters, forcing custom low-profile designs that extend engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel and Metro Fans Market |
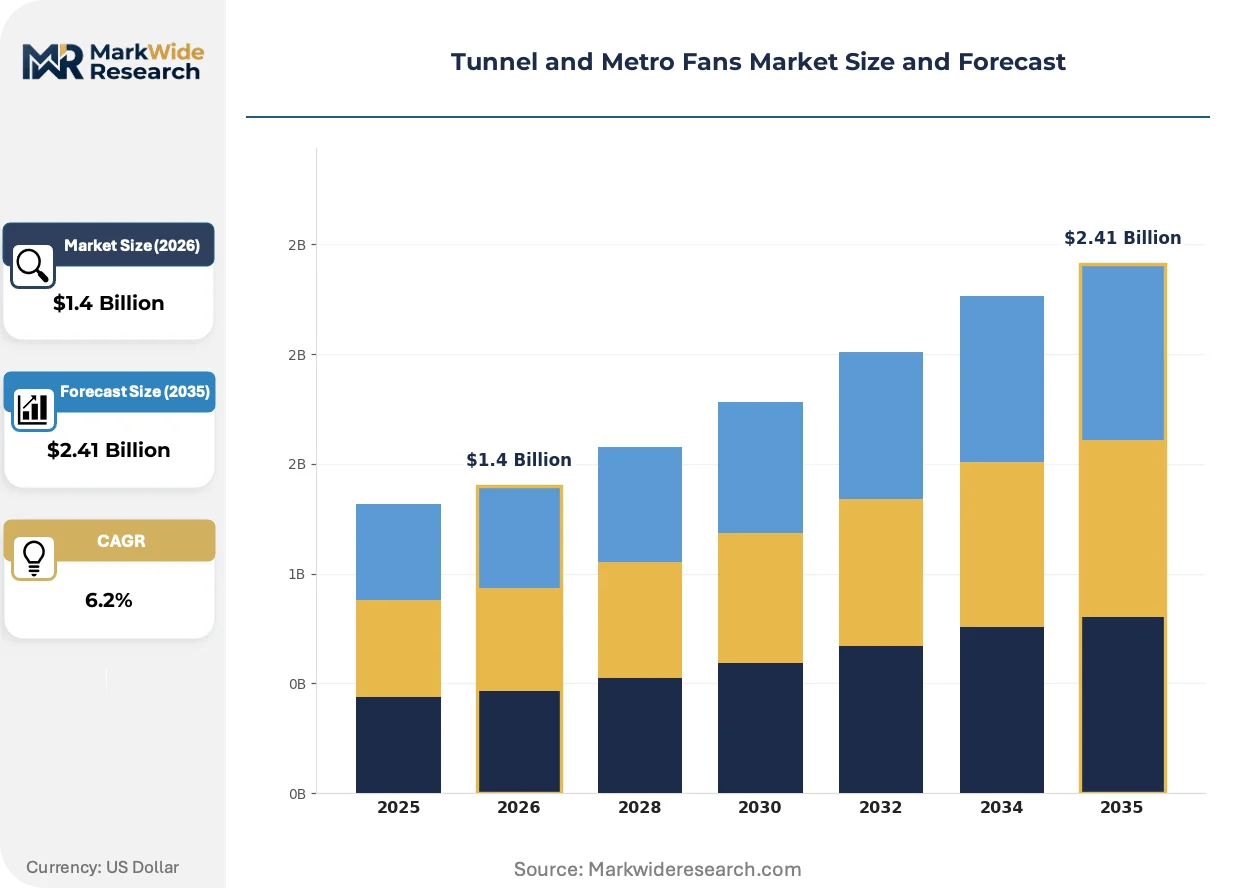
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Axial, Centrifugal, Mixed Flow, Cross Flow Application: Underground Construction, Public Transportation, Fire Safety, Ventilation End User: Municipalities, Construction Companies, Transport Authorities, Fire Departments Installation: Fixed, Portable, Wall-Mounted, Ceiling-Mounted |
| Companies Covered | Systemair, Jindun, ShangFeng, Kruger Ventilation, TLT-Turbo GmbH, Fläkt Woods, WITT & SOHN, NanFeng, Howden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel and Metro Fans Market Trends and Innovations
Permanent magnet synchronous motor technology is compressing energy consumption benchmarks while digital control architectures are unbundling hardware from optimization software. Equipment manufacturers are repositioning around airflow-as-a-service models.
Permanent magnet synchronous motor technology is electrifying tunnel ventilation efficiency benchmarks through integrated variable speed control and elimination of gearbox losses. Metro operators in Shenzhen and Kuala Lumpur are specifying these systems for all new deep-bore stations. The technology is electrifying competitive differentiation away from pure aerodynamic performance toward integrated power electronics and control software capability.
The EU F-Gas Regulation's refrigerant phase-down timeline is forcing tunnel climate system designers to specify air-cooled heat rejection in place of vapor compression cooling. This industrial consequence expands thermal management equipment scope to include larger airflow volumes and higher static pressure requirements. Deep-bore metro projects in Germany and Austria are most affected, with specifications now requiring fan manufacturers to certify combined ventilation-cooling integrated performance.
Lifecycle cost contracting is replacing capital expenditure procurement in Scandinavian and Dutch metro authorities. Engineering-procurement-construction firms are absorbing equipment selection risk and demanding guaranteed energy performance, displacing traditional lowest-first-cost bidding. This pattern is most visible in Copenhagen's City Circle Line extensions and Amsterdam's North-South metro expansion, where 15-year total cost of ownership models dominate vendor evaluation.
Tunnel and Metro Fans Market Segmentation
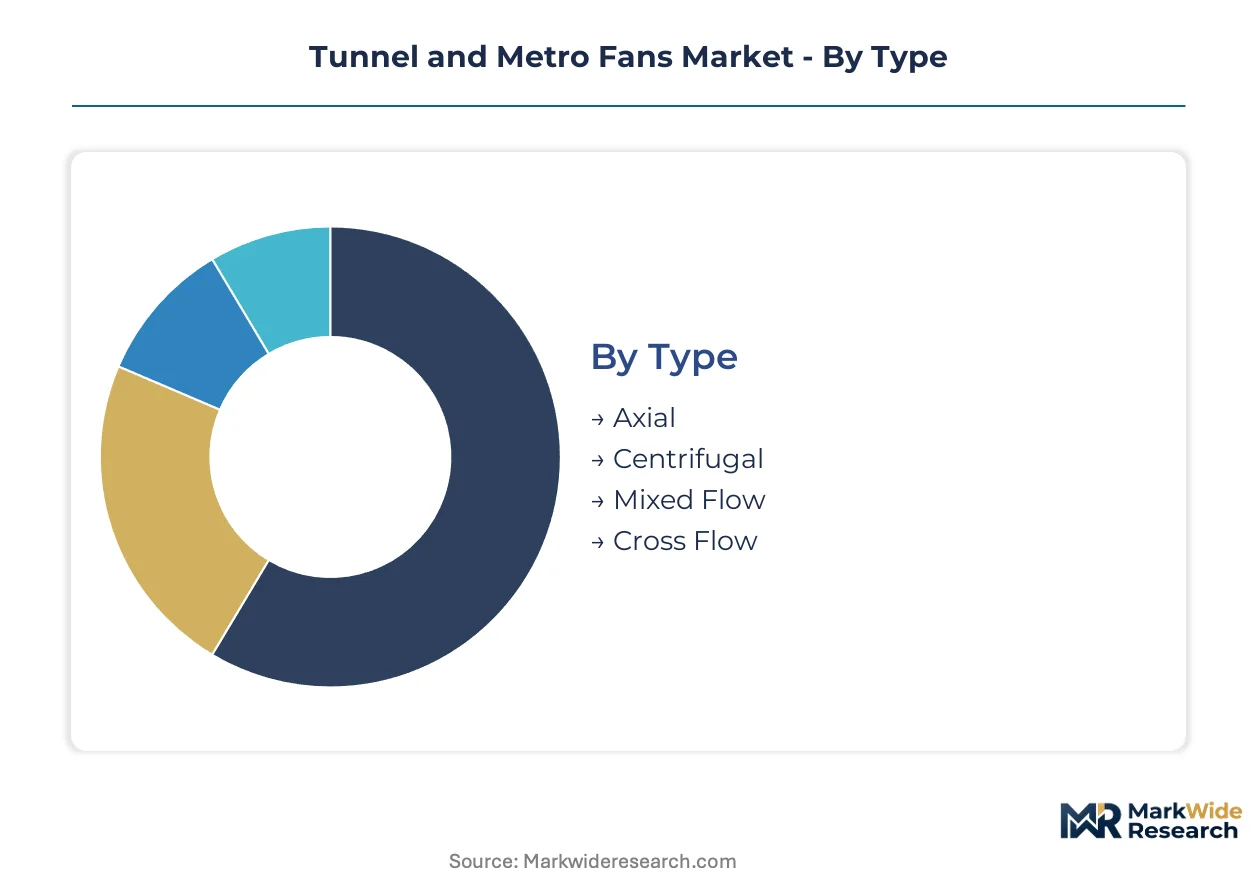
Tunnel and metro fan procurement splits across four intersecting dimensions that determine equipment specifications, contract structures, and margin profiles. Capital intensity varies dramatically by fan type and installation permanence, while application context dictates fire safety certification requirements and redundancy levels.
Type:
Capital intensity peaks with mixed flow configurations requiring precision-machined impellers and dual-curvature volutes, while axial designs dominate volume shipments through simpler manufacturing economics.
- Axial:Straight-through airflow path with impeller diameters from 0.3 to 5 meters delivers efficiency in longitudinal tunnel ventilation schemes. China's high-speed metro corridors specify these for platform-level smoke extraction, driven by GB 50157 redundant capacity mandates.
- Mixed Flow:Hybrid impeller geometry combining axial entry with radial discharge achieves higher pressure ratios in constrained footprints. Deep-bore stations in Germany and Austria under EU F-Gas Regulation pressure specify these for integrated ventilation-cooling duty where space limits pure axial deployment.
- Centrifugal:Radial blade configurations generate high static pressure for ducted distribution networks in complex station mezzanines.
- Cross Flow:Tangential impeller designs span narrow rectangular ducts in auxiliary equipment rooms and control spaces.
Most installed capacity flows through axial configurations. Expansion is steepest in mixed flow designs gaining specification share in space-constrained deep-bore environments.
Application:
Procurement cycle length varies by application, with fire safety systems requiring longest pre-certification timelines and underground construction demanding shortest equipment delivery windows.
- Underground Construction:Temporary ventilation during excavation and tunnel boring operations requires portable high-capacity units. Southeast Asian rail projects compress delivery schedules, forcing manufacturers to hold pre-certified inventory.
- Fire Safety:Smoke extraction systems must achieve velocity targets exceeding 2 meters per second under EN 12101-3 and UL 705 protocols. Updated Chinese metro standards double fan count per platform versus legacy designs, expanding specification volumes.
- Public Transportation:Passenger comfort and platform air quality systems integrate with building management architectures in Singapore and Bangkok retrofit programs.
- Ventilation:General air exchange and pollutant dilution in road tunnels and service corridors.
Fire safety commands premium pricing tiers. Underground construction exhibits the most volatile demand cyclicality tied to infrastructure stimulus timing.
End User:
Contracting sophistication separates end user segments, with transport authorities adopting lifecycle cost models while construction companies prioritize equipment rental flexibility.
- Transport Authorities:Scandinavian and Dutch metro operators specify 15-year total cost of ownership contracts with guaranteed energy performance, shifting vendor selection criteria from first cost to operational efficiency.
- Municipalities:City governments balance constituent visibility with budget constraints in road tunnel and transit upgrades.
- Construction Companies:Tunnel boring contractors source portable units on short-term lease arrangements with rapid deployment requirements.
- Fire Departments:Emergency response agencies specify mobile smoke extraction for incident command deployment.
Transport authorities deploy the most complex procurement frameworks. Construction companies generate the highest equipment turnover velocity.
Installation:
Mounting configuration determines structural integration requirements, with fixed installations demanding civil engineering coordination and portable units requiring modular power and control interfaces.
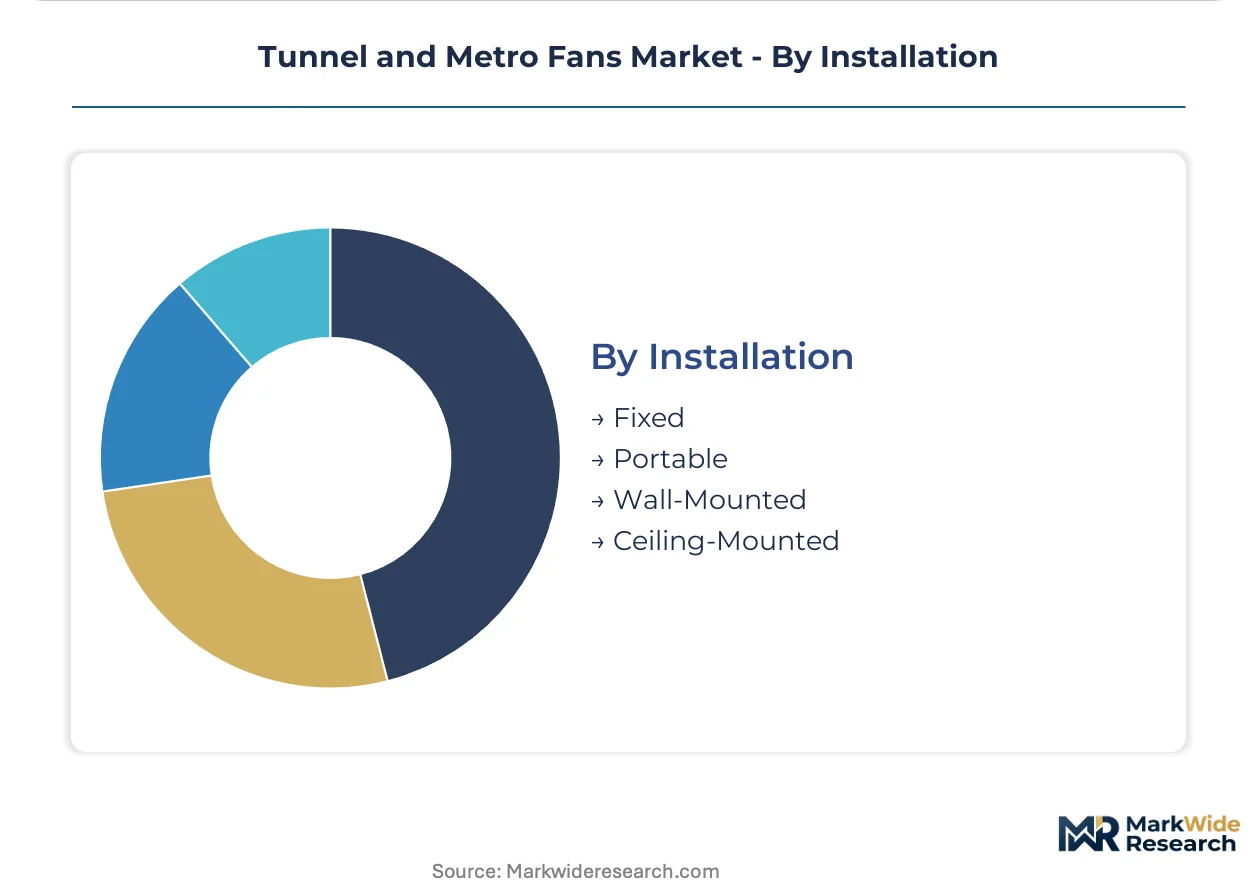
- Fixed:Permanent structural mounting in tunnel soffits and equipment galleries sustains majority revenue through integration with building management systems. Copenhagen's City Circle Line and Amsterdam's North-South expansion specify these with 15-year service contracts.
- Portable:Skid-mounted or trailer-based units serve construction phases and emergency response, gaining specification share in Southeast Asian procurement pipelines without incumbent vendor lock-in.
- Wall-Mounted:Compact axial or cross flow units in ancillary spaces and equipment rooms.
- Ceiling-Mounted:Space-saving configurations in low-clearance mezzanine and concourse areas.
Fixed installations anchor manufacturer revenue stability. Portable configurations are climbing the fastest as construction-phase and emergency applications expand specification scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly to jurisdictions with lower fire certification burdens, creating regulatory arbitrage between EU F-Gas compliance costs and Southeast Asian procurement timelines.
China
GB 50157 metro standard revisions mandate redundant smoke-extraction capacity, doubling fan specifications per platform. MIIT domestic content requirements strengthen local supply chains. Shenzhen and Guangzhou anchor high-speed corridor buildouts where deep-bore stations specify mixed-flow configurations.
Germany
Alpine tunnel projects face 3,000 Pascal pressure ceilings requiring multi-stage axial arrays. EU F-Gas Regulation refrigerant phase-down expands thermal management equipment scope. Munich and Stuttgart rail extensions specify integrated ventilation-cooling systems with 15-year lifecycle contracts.
United States
EPA and OSHA joint mandates on underground construction air quality determine fan sizing and filtration requirements. Infrastructure stimulus compresses delivery windows for tunnel boring operations. Los Angeles and New York transit authorities specify portable emergency response units alongside fixed installations.
Indonesia
Trans-Sumatra rail corridor represents 1,700 kilometers of greenfield specification without incumbent vendor lock-in. National infrastructure bank financing accelerates procurement cycles. Jakarta and Bandung underground segments anchor initial demand clusters for mixed-flow station ventilation.
India
PLI scheme for rail components opens local assembly pathways for foreign manufacturers partnering with domestic engineering firms. BIS certification requirements are harmonizing with EN standards. Delhi-Mumbai and Bengaluru metro expansions specify redundant fire safety systems per updated national building codes.
Tunnel and Metro Fans Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers pre-certify equipment against divergent national standards before bid submission. The vendor base concentrates around three tiers: Nordic engineering specialists, Chinese domestic champions, and German precision fabricators. Strategic archetypes include full-system integrators pursuing lifecycle service contracts and component specialists defending margin positions in high-pressure axial segments. M&A activity and geographic licensing partnerships represent the dominant competitive vectors.
Among Nordic engineering specialists, Systemair anchors European rail ventilation specifications through regional certification depth. Jindun occupies a position within the Chinese domestic champion tier, leveraging GB standards alignment across state-backed metro buildouts. TLT-Turbo GmbH exemplifies the precision fabricator archetype, with German GmbH structure signaling engineering-intensive positioning in deep-bore pressure applications.
| Leading Market Players |
|---|
| Systemair |
| Jindun |
| ShangFeng |
| Kruger Ventilation |
| TLT-Turbo GmbH |
| Fläkt Woods |
| WITT & SOHN |
| NanFeng |
| Howden |
| Others |
Pricing and Supply Chain Analysis
Transport authority procurement concentration in Scandinavia and the Netherlands anchors lifecycle cost contracting as the dominant pricing model, compressing margins for equipment-only vendors while rewarding integrated service providers. Pricing pressure feeds back into supplier consolidation decisions, as manufacturers absorb engineering-procurement-construction risk to secure 15-year total cost of ownership agreements.
Pricing Analysis
Distributor margins in European rail specifications compress under direct-to-OEM procurement frameworks favored by Systemair and TLT-Turbo GmbH. Three-tier pricing structure across premium, standard, and economy levels segments by fire certification grade and redundancy configuration, with EN 12101-3 certified systems commanding substantial premiums. Cost compression in standard axial configurations is intensifying because Chinese domestic champions leverage GB standards alignment to undercut import pricing. Construction companies exhibit highest price sensitivity due to short-term lease arrangements, while transport authorities prioritize operational efficiency over first cost.
Supply Chain Analysis
Workforce availability in precision machining and thermofluids simulation constrains final assembly scale-up in Germany and Austria, forcing manufacturers to relocate production to jurisdictions with lower certification burdens. Supply concentration centers on China for rare-earth magnet processing, Germany for high-pressure axial engineering, and Southeast Asia for portable unit fabrication. Raw material dependencies draw from copper windings, neodymium permanent magnets, and corrosion-resistant alloy steel. Single-source vulnerability in Chinese rare-earth processing exposes European manufacturers to export restriction risk. Distribution runs through engineering-procurement-construction firms absorbing equipment selection risk under lifecycle performance guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunnel and metro fans constitute a late-cycle quality story as deep-bore construction specifications displace commodity ventilation procurement. Demand is hardening toward redundant smoke-extraction systems and integrated ventilation-cooling performance under tightening fire safety mandates.
For Market Incumbents: Extend certification depth across divergent national standards to preempt bid disqualification in Southeast Asian procurement pipelines. Absorb thermofluids simulation talent bottlenecks through targeted acquisition of computational fluid dynamics specialists. Vertical integration into permanent magnet motor production mitigates neodymium price volatility exposure from Chinese processing concentration. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and Austria opens a window for magnetically levitated bearing system specialists to capture specification share in integrated ventilation-cooling duty. Indonesia's Trans-Sumatra rail corridor represents the most penetrable geography absent incumbent vendor lock-in. Partner with domestic engineering firms under India's PLI scheme to establish local assembly pathways without full greenfield investment. For Investors and Strategic Acquirers: Engineering-procurement-construction firms are the most active acquirer in this space as they consolidate equipment selection risk under lifecycle performance contracts. Long-term viability hinges on recurring service revenue displacement of capital equipment sales. Acquisition target archetype: precision fabricators with deep-bore pressure application expertise and existing EN 12101-3 certification. Monitor harmonization progress between EN, UL, and CCC fire safety protocols as inflection indicator for cross-border procurement efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Fire Certification Pre-Investment | Parallel EN 12101-3, UL 705, and CCC testing programs secure bid eligibility across Chinese, European, and North American procurement pipelines. |
| Permanent Magnet Motor Integration | In-house synchronous motor production eliminates gearbox losses and reduces neodymium supply chain exposure. |
| Computational Fluid Dynamics Acquisition | Thermofluids simulation capability addresses talent bottlenecks in deep-bore fire smoke propagation modeling. |
| Lifecycle Service Contract Expansion | Copenhagen and Amsterdam transport authority frameworks demonstrate revenue stability from 15-year performance guarantees. |
| Southeast Asian Local Assembly | Indonesia and India domestic content requirements favor partnered manufacturing over pure export positioning. |
Research Methodology
Bottom-up transport authority procurement modeling reconciled against top-down manufacturer order book tracking forms the analytical core of this study. Primary interviews with tunnel ventilation engineers, fire safety certification specialists, engineering-procurement-construction procurement directors, and metro authority maintenance heads combined with secondary validation from EU F-Gas Regulation filings, GB standards documentation, SEC equipment supplier disclosures, and national infrastructure bank financing announcements. Triangulation between demand-side project pipelines and supply-side capacity announcements ensures statistical integrity.
Historical trendline analysis of installed base replacement cycles and new-build specification rates informs the projection framework. Segmentation modeling spans fan type, application context, end user contracting sophistication, and installation permanence across the analysis window. CAGRs derive from equipment shipment trajectories correlated with tunnel boring machine deployment schedules and metro line opening timelines. Deep-bore technical ceiling constraints and refrigerant phase-down regulatory timelines constitute industry-specific forecast inputs.
Revisions become necessary when fire certification harmonization agreements materialize, rare-earth export restrictions disrupt motor supply chains, or infrastructure stimulus timing shifts compress procurement windows. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and project financing closure rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Roof Insulation Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
HVAC Blower and Fan Systems Market