
 Asia Pacific Power Tools & Hand Tools Market | 2026-2036
Asia Pacific Power Tools & Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Power Tools & Hand Tools Market Analytics
Brushless motor electrification is tilting the Asia Pacific power tools technology stack toward higher efficiency platforms with reduced maintenance intervals. Robert Bosch GmbH leverages its German-Asian R&D footprint to anchor premium cordless lines across industrial manufacturing accounts. Makita Corporation sustains manufacturing scale through captive motor production in Japan and Vietnam. Techtronic Industries Co., Ltd. competes aggressively through Milwaukee-brand battery platform consolidation across professional contractor segments.
Power tools and hand tools encompass electrically, pneumatically, or manually actuated implements designed for material cutting, fastening, shaping, or surface finishing, typically rated by torque output, no-load speed, or impact energy measured in joules. Their primary commercial purpose spans construction assembly, automotive repair, metal fabrication, and woodworking production where precision and repeatability govern output quality. Electric tools lead value generation due to battery platform investments, while pneumatic tools retain share in high-torque automotive and metalworking applications where compressed air infrastructure already exists. Accessories capture expanding margin pools as proprietary battery ecosystems lock users into branded consumable and attachment replacement cycles.
Japan's METI enforces JIS standards for power tool electromagnetic compatibility and mechanical safety, while China's SAMR administers GB standards governing tool insulation classes and noise emissions under national quality infrastructure programs. India's BIS operates mandatory certification schemes for power tool electrical safety that condition market access for imported equipment. Stakeholders must monitor how ASEAN harmonization of equipment safety protocols reshapes cross-border manufacturing location decisions and distributor compliance burdens.
Market Dynamics
Brushless motor electrification is collapsing the maintenance-cost advantage that corded tools held over cordless platforms, forcing fleet replacement cycles across Southeast Asian construction sites. Lithium-ion battery maturation now permits sustained torque output matching pneumatic alternatives, redrawing competitive boundaries between electric and compressed-air tool categories.
Growth Catalysts
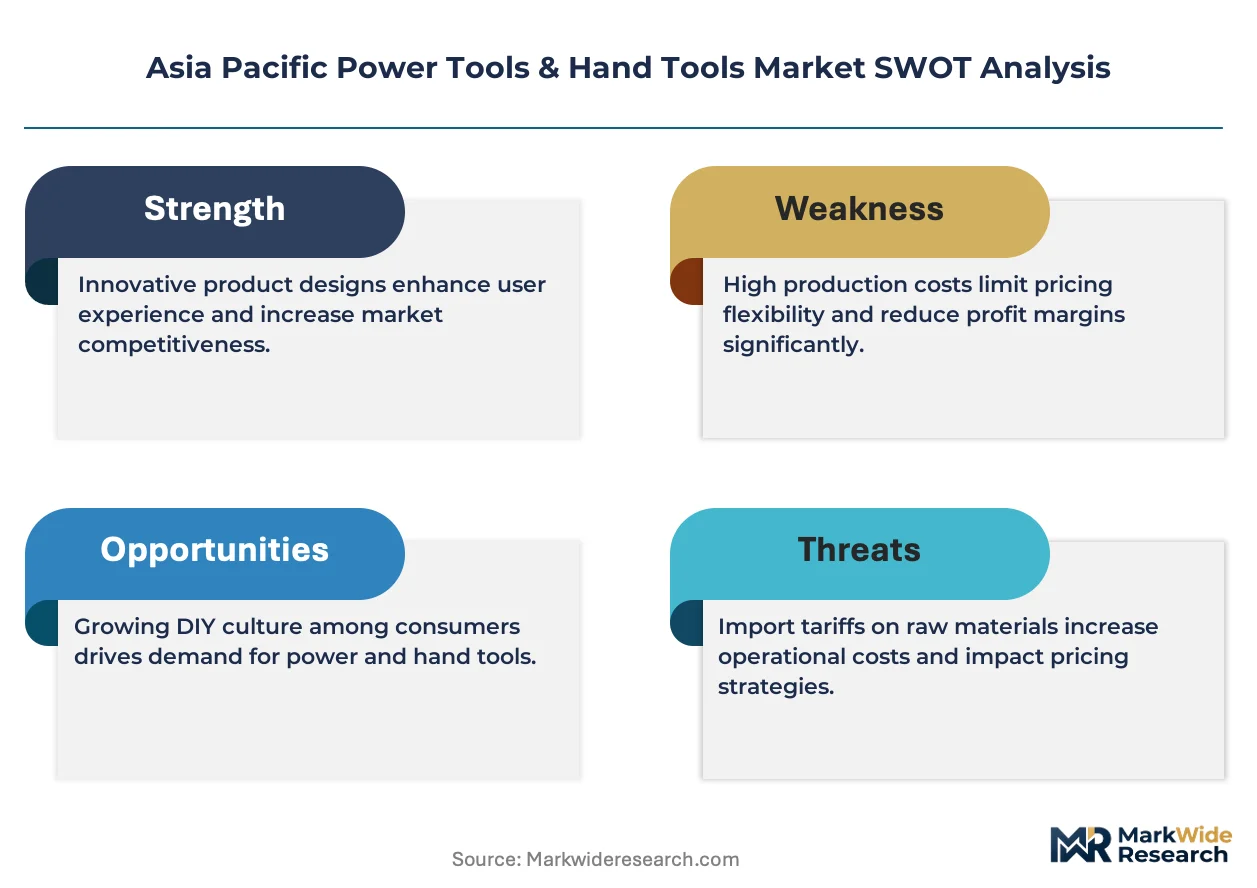
- India's BIS certification mandates:Tightened electrical safety standards for imported power tools are filtering out low-quality entrants and elevating certified domestic manufacturing capacity.
- Cordless platform consolidation:Interchangeable battery ecosystems across drill, impact driver, and grinder categories reduce contractor total cost of ownership and accelerate fleet standardization decisions.
- Pearl River Delta cluster concentration:Tool OEMs serving both domestic Chinese demand and export production lines achieve component sourcing efficiencies unavailable in fragmented supply bases.
Market Restraints
- Lithium and rare earth input volatility:Permanent magnet motor dependency on neodymium concentrates exposes margin compression when Chinese export quotas tighten.
- Japanese motor production concentration:Captive manufacturing of high-efficiency brushless motors in Japan and Vietnam creates supply vulnerability for non-integrated assemblers.
- Pneumatic infrastructure lock-in:Existing compressed air systems in Thai and Indonesian automotive plants delay electric tool conversion despite operating cost disadvantages.
Strategic Opportunities
- Vietnamese manufacturing expansion:Labor cost advantages and EU-ASEAN trade facilitation position the country for export-oriented tool assembly migration from China.
- Smart tool connectivity convergence:Integration of torque telemetry and usage analytics with inventory management systems opens premium pricing in industrial maintenance contracts.
- Australian mining maintenance demand:Remote site operations require durable cordless platforms where compressed air infrastructure is uneconomical to deploy.
Industry Challenges
- BIS certification timeline compression:India's mandatory testing protocols for power tool electrical safety extend product launch schedules by six to nine months for new entrants.
- Legacy pneumatic skill base displacement:Maintenance technicians trained on compressed air systems require reskilling for battery platform diagnostics and motor controller troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Power Tools & Hand Tools Market |
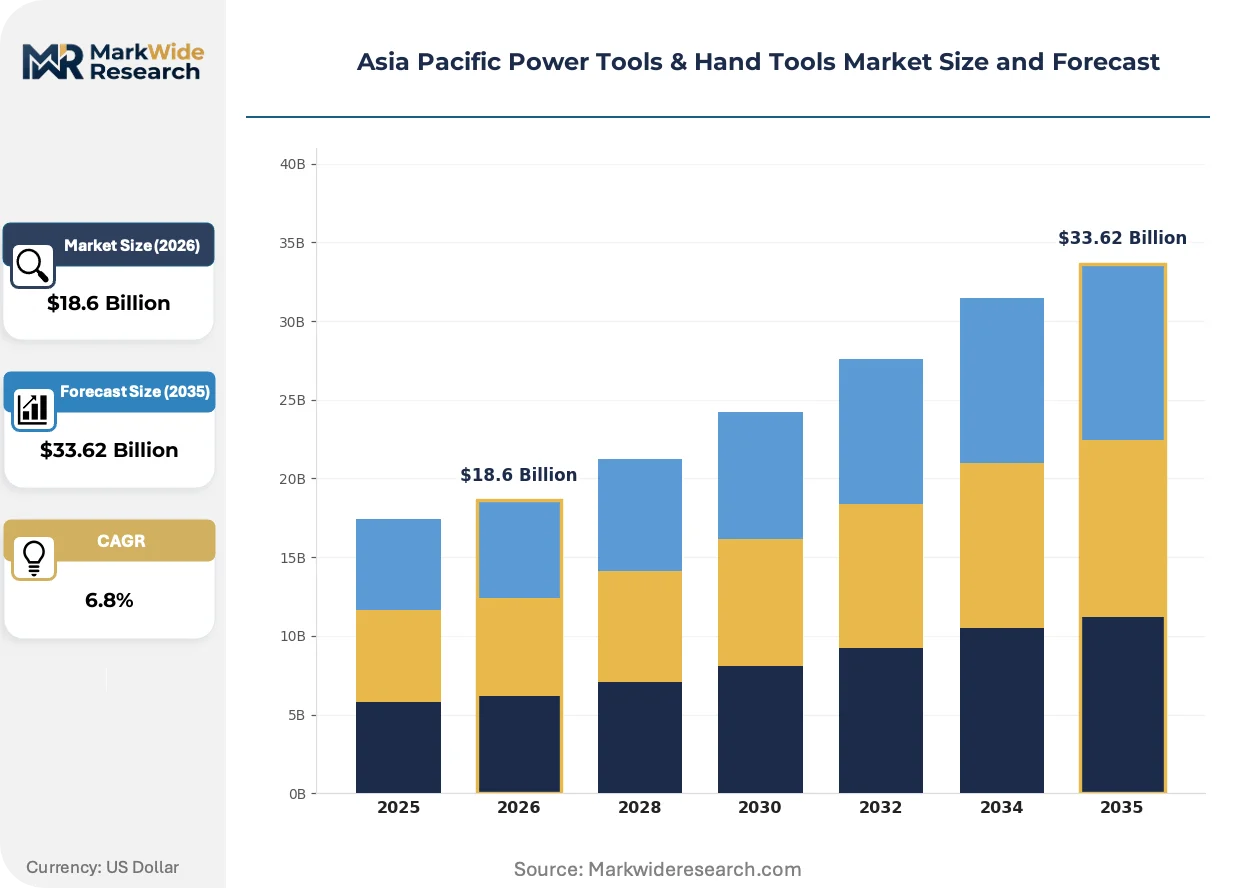
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tools, Hand Tools, Pneumatic Tools, Accessories End User: Contractors, DIY Enthusiasts, Industrial Manufacturers, Maintenance Services Sales Channel: Online Retail, Direct Sales, Wholesalers, Distributors Application: Construction, Automotive, Woodworking, Metalworking |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Makita Corporation, Techtronic Industries Co., Ltd., Hilti Corporation, Atlas Copco AB, Emerson Electric Co., Apex Tool Group, Ingersoll Rand, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Power Tools & Hand Tools Market Evolving Landscape
Electrification is collapsing category boundaries between professional and consumer tool tiers as battery performance parity enables feature migration downward. Three distinct vectors are compressing traditional market segmentation and reshaping value capture mechanisms.
Brushless DC motor architecture is collapsing the price-performance gap between industrial-grade and prosumer cordless tools. High-torque density magnets and silicon carbide inverters now deliver sustained output previously requiring AC mains or pneumatic supply. Japanese automotive suppliers are adopting these platforms for assembly line torque-critical fastening, compressing the premium that corded tools commanded for precision applications.
China's SAMR enforcement of GB standards for tool electromagnetic compatibility and noise emissions is accelerating design standardization across export-bound manufacturers. Compliance testing for insulation classes and harmonic distortion now conditions market access, forcing component supplier consolidation. Korean battery pack assemblers are absorbing additional certification costs to maintain Pearl River Delta OEM relationships, compressing margins for uncertified competitors.
Contractor procurement patterns are fragmenting as digital distributor platforms disintermediate traditional wholesale relationships. Professional trades in Australian metropolitan markets now specify tools through integrated project management software that links inventory to job costing. This behavior compresses brand loyalty cycles and elevates total-cost-of-ownership analytics over point-of-purchase specifications, favoring vendors with transparent lifecycle data.
Asia Pacific Power Tools & Hand Tools Market Segmentation
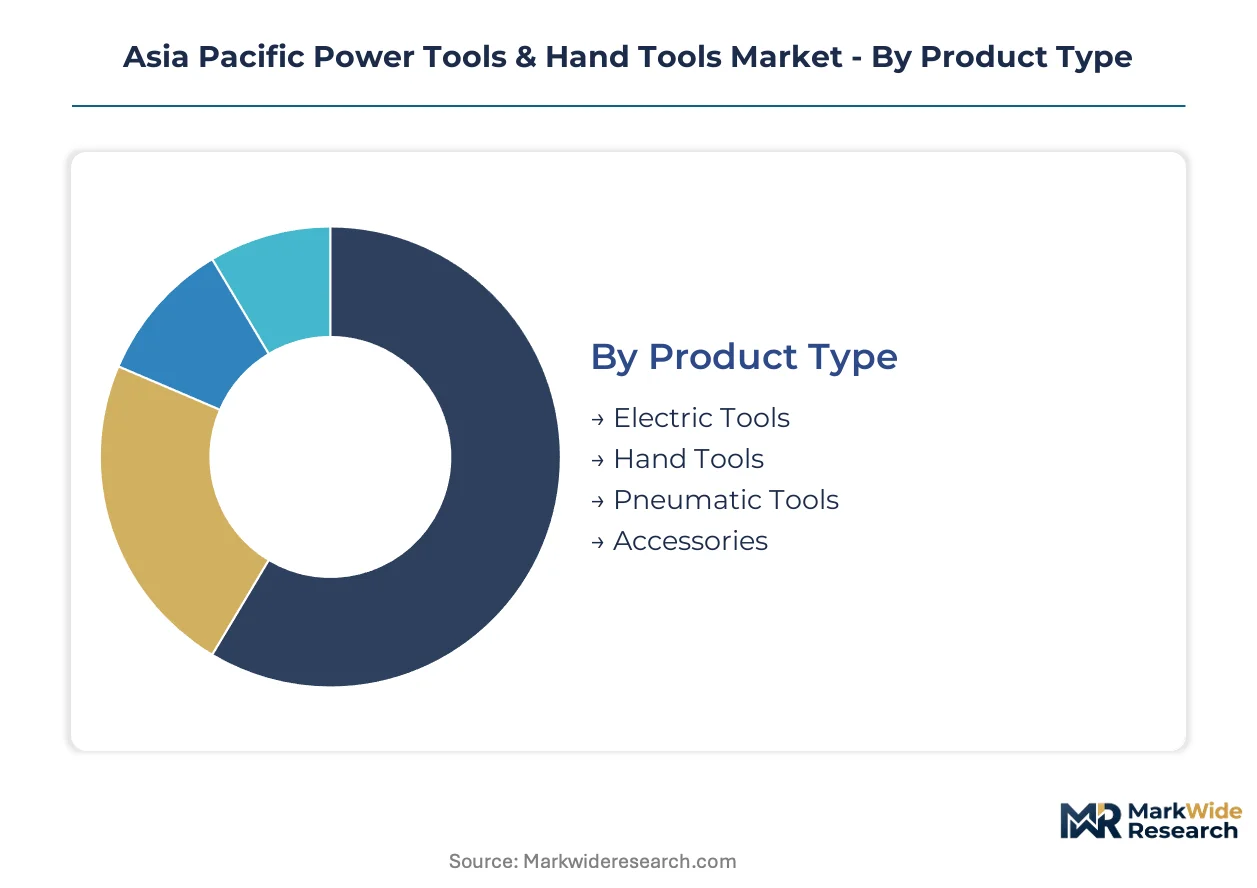
Tool replacement cycles vary dramatically across Asia Pacific power tools and hand tools segments, with cordless electric platforms turning over every three to four years while pneumatic infrastructure persists for decades. Segmentation discipline reveals where battery platform investments concentrate versus where legacy equipment retains stubborn installed bases.
Product Type:
Electric tools compress replacement timelines through lithium-ion degradation and motor controller obsolescence, while pneumatic systems endure through mechanical simplicity and sunk infrastructure costs.
- Electric Tools:Brushless DC motor architectures and interchangeable battery ecosystems dominate contractor fleet procurement across Southeast Asian construction sites. China's SAMR enforces GB standards for electromagnetic compatibility that accelerate design refresh cycles. Demand concentrates in cordless drill, impact driver, and angle grinder categories where torque density improvements displace corded alternatives.
- Hand Tools:Manual implements—wrenches, screwdrivers, hammers, and measuring instruments—retain indispensability in precision assembly and confined-space operations where power sources are impractical. Japanese automotive plants in Thailand and Indonesia specify JIS-certified hand tools for torque-critical fastening where electric tool bulk obstructs access.
- Pneumatic Tools:Compressed-air actuated impact wrenches and grinders persist in high-volume Thai and Indonesian automotive assembly where existing compressor infrastructure amortizes capital costs.
- Accessories:Proprietary battery packs, drill bits, and abrasive discs generate recurring revenue through vendor lock-in.
Hand tools anchor the volume base while electric tools gains share at the steepest rate.
End User:
Procurement authority and technical sophistication create sharp segmentation boundaries between price-sensitive amateurs and lifecycle-cost-focused professionals.
- Contractors:Professional construction trades across Australia's metropolitan markets and Southeast Asian infrastructure projects prioritize total cost of ownership analytics over point-of-purchase pricing. Fleet standardization on single battery platforms reduces downtime and inventory complexity. India's tightening BIS certification mandates filter supplier pools toward certified domestic and imported equipment.
- Industrial Manufacturers:Automotive and electronics assembly plants in Japan, South Korea, and China's Pearl River Delta specify tools for torque repeatability and traceability compliance. Smart tool connectivity with usage telemetry commands premium pricing in preventive maintenance contracts.
- DIY Enthusiasts:Home improvement consumers in Australian suburbs and Chinese tier-two cities purchase through digital retail platforms where brand loyalty cycles compress.
- Maintenance Services:Industrial repair contractors require durable cordless platforms for remote site operations where compressed air infrastructure is uneconomical.
Contractors generate the largest revenue pool while industrial manufacturers adopt premium features fastest.
Sales Channel:
Channel economics reflect inventory carrying costs, technical support requirements, and customer acquisition efficiency across distinct buyer segments.
- Wholesalers:Traditional two-step distribution through regional tool warehouses persists in Southeast Asian construction supply chains where contractor credit relationships and bulk purchasing dominate. Inventory depth and same-day availability protect this channel against digital disintermediation.
- Online Retail:E-commerce platforms capture DIY and small contractor segments through transparent pricing and delivery convenience. Australian metropolitan trades increasingly specify tools through integrated project management software that links procurement to job costing.
- Direct Sales:OEM field organizations serve automotive and electronics manufacturers with application engineering support and custom torque specification.
- Distributors:Authorized dealer networks provide warranty service and spare parts availability for professional contractor segments.
Wholesalers retain the largest transaction volume while online retail expands most quickly.
Application:
Application-specific torque, precision, and durability requirements segment the market by technical performance tier and replacement cycle intensity.
- Construction:Heavy-duty cordless platforms for concrete drilling, demolition, and steel fastening face the most severe duty cycles and shortest replacement intervals. Southeast Asian infrastructure investment drives fleet expansion among regional contractors.
- Automotive:Assembly plants and repair shops require torque-critical fastening tools with calibration traceability. Thailand's position as ASEAN automotive production hub concentrates demand for both electric and pneumatic assembly equipment.
- Woodworking:Precision cutting and finishing tools serve furniture manufacturing clusters in Vietnam and Indonesia where export-oriented production quality standards elevate equipment specifications.
- Metalworking:High-torque grinding and cutting applications in Chinese and Indian fabrication shops stress thermal management and abrasive consumption.
Construction commands the largest equipment spend while automotive applications adopt smart tool connectivity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters across the Asia Pacific power tools and hand tools market generate trade surpluses in finished equipment while importing precision components from Japan and South Korea. Import dependency concentrates in brushless motor controllers and lithium-ion battery cells. Domestic certification regimes increasingly condition market access for cross-border suppliers.
China
Construction equipment procurement in Guangdong and Jiangsu provinces drives cordless platform demand as contractors replace aging pneumatic fleets. SAMR enforces GB standards for electromagnetic compatibility and noise emissions that accelerate design refresh cycles. Tool OEMs in Shenzhen and Dongguan serve both domestic infrastructure projects and export production lines for Southeast Asian distributors.
Japan
Automotive assembly plants in Aichi and Shizuoka prefectures specify torque-critical fastening tools with calibration traceability for EV production lines. METI administers JIS standards for power tool electromagnetic compatibility and mechanical safety. Nagoya-based motor manufacturers supply high-efficiency brushless architectures to regional assemblers across ASEAN markets.
India
Infrastructure investment under the National Infrastructure Pipeline expands contractor equipment procurement in Maharashtra and Karnataka states. BIS operates mandatory certification schemes for power tool electrical safety that extend product launch timelines for imported equipment. Tool distributors in Mumbai and Bangalore consolidate inventory around certified domestic and imported brands.
Vietnam
Furniture manufacturing clusters in Binh Duong and Dong Nai provinces drive precision cutting and finishing tool demand for export-oriented production. The country's national quality infrastructure administration aligns equipment safety protocols with EU-ASEAN trade facilitation agreements. Assembly operations in Ho Chi Minh City periphery migrate from Chinese suppliers seeking labor cost advantages.
Australia
Remote mining maintenance operations in Western Australia and Queensland require durable cordless platforms where compressed air infrastructure deployment is uneconomical. The country's national equipment safety regulator enforces electrical safety standards for imported power tools. Contractor procurement in Sydney and Melbourne metropolitan markets increasingly flows through digital distributor platforms linking inventory to project management systems.
Asia Pacific Power Tools & Hand Tools Market Competitive Landscape
On the supply side, the industry is consolidating around battery platform ecosystems that lock users into proprietary consumable and attachment replacement cycles. Tiered competitive positioning separates integrated motor manufacturers from brand marketers dependent on outsourced component supply. Two strategic archetypes dominate: German-Japanese engineering houses with captive R&D footprints and Asian scale assemblers leveraging manufacturing cost advantages. Dominant competitive moves include cordless platform consolidation across tool categories and backward integration into lithium-ion battery cell assembly.
Among diversified industrial conglomerates, Robert Bosch GmbH and Emerson Electric Co. exemplify the integrated engineering archetype with cross-border R&D footprints spanning German and Asian technical centers. Stanley Black & Decker occupies a position representing the brand-aggregator model with broad portfolio coverage across professional and consumer segments. These three anchors illustrate how competitive positioning in the Asia Pacific power tools and hand tools market depends on control over core motor and battery technologies versus reliance on supplier networks for critical components.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Makita Corporation |
| Techtronic Industries Co., Ltd. |
| Hilti Corporation |
| Atlas Copco AB |
| Emerson Electric Co. |
| Apex Tool Group |
| Ingersoll Rand |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Pearl River Delta motor assembly plants compresses supplier pricing power while simultaneously accelerating consolidation toward integrated battery-motor platforms. Contractors and industrial OEMs exploit this utilization slack to negotiate favorable fleet-standardization terms that lock in multi-year consumable revenue streams.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Asia Pacific power tools and hand tools market. Premium cordless platforms command 40-60% markups over economy alternatives based on brushless motor efficiency ratings and BIS/JIS certification status. Cost compression in economy tiers intensifies because Vietnamese assemblers absorb margin erosion to maintain Pearl River Delta OEM relationships. Small contractors and DIY enthusiasts exhibit highest price sensitivity, while automotive manufacturers prioritize total cost of ownership over point-of-purchase pricing.
Supply Chain Analysis
Export controls on semiconductor manufacturing equipment constrain brushless motor controller fabrication, concentrating high-efficiency drive electronics production in Japan and South Korea. Neodymium permanent magnets and lithium-ion battery cells draw from Chinese rare earth processing and Korean cathode material supply. Single-source vulnerability haunts non-integrated tool assemblers dependent on Nagoya-based motor suppliers. Distribution runs through regional wholesaler networks in Southeast Asia and direct OEM field organizations serving Japanese automotive plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery platform economics now govern competitive outcomes as interoperable ecosystems displace standalone tool procurement across contractor and industrial segments.
For Market Incumbents: Entrench proprietary battery ecosystems through backward integration into lithium-ion cell assembly and aggressive certification investment under India's BIS mandates. Defend against emerging Vietnamese scale assemblers by deepening captive motor production in Japan and expanding application engineering presence in Australian mining maintenance accounts. For New Entrants and Emerging Players: Mid-market commercial contractors in Indonesia and the Philippines represent the most penetrable entry point where fleet standardization remains incomplete. Digital distributor platforms linking procurement to project management software offer channel access without wholesale relationship overhead. Target smart tool connectivity gaps in preventive maintenance contracts where telemetry integration commands premium positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across brushless motor and battery pack manufacturing as scale requirements for certification compliance escalate. Acquisition candidates include Vietnamese assembly operations with EU-ASEAN trade facilitation alignment and Korean battery pack assemblers absorbing SAMR electromagnetic compatibility testing costs. Monitor BIS certification timeline compression as early signal for import-dependent supplier distress.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Consolidation | Proprietary ecosystems lock contractors into recurring consumable revenue streams across tool categories. |
| Backward Integration into Cells | Captive lithium-ion supply insulates margins from Korean cathode material price volatility. |
| Smart Tool Connectivity Development | Torque telemetry integration with inventory management commands premium pricing in industrial contracts. |
| Vietnamese Manufacturing Expansion | Labor cost advantages and EU-ASEAN trade facilitation position export-oriented assembly migration. |
| BIS Certification Pre-Positioning | Early compliance investment filters competitor pools and accelerates product launch timelines. |
Research Methodology
Desk research of customs trade records, SAMR certification databases, and automotive production statistics preceded structured interviews with procurement directors at Thai automotive assembly plants, maintenance supervisors at Australian mining operations, and distribution managers at Southeast Asian tool wholesalers. Primary fieldwork with OEM product strategists and battery pack assemblers in Shenzhen and Ho Chi Minh City combined with secondary validation against JIS and BIS regulatory filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Assumptions held lithium-ion energy density improvements and brushless motor efficiency gains at historical rates while varying infrastructure investment scenarios across India's National Infrastructure Pipeline and ASEAN harmonization timelines. The modeling framework projected electric tool, hand tool, pneumatic tool, and accessories demand by contractor, industrial manufacturer, DIY enthusiast, and maintenance service end users. CAGRs derived from replacement cycle analysis and fleet penetration curves incorporated Pearl River Delta production capacity utilization and BIS certification adoption rates as industry-specific inputs.
Practitioners should monitor rare earth export quota announcements and ASEAN equipment safety protocol harmonization for early signals of supply constraint or regulatory acceleration. Forecasts reflect assumptions of continued lithium-ion platform maturation and stable trade facilitation between EU and ASEAN member states. Material shifts in Chinese permanent magnet export policy or Indian BIS testing protocol stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Electric Power Tools Market
Tools
Thread Milling Machine Market
Tools
Tool Pliers Market
Tools
Cold and Hot Tool Steel Market
Tools
Power Nibbler Market
Tools
Mortiser Market
Tools
Handheld Blower Market
Tools
Automatic Heat Press Machines Market
Tools
Power Tools Market
Tools
United States Machine Tools Market
Tools
Hacksaw Blades Market
Tools
Saw Blades Market
Tools
Metal Forming Tools Market
Tools
Mechanical Springs Market
Tools
Chainsaw Market
Tools
Flooring Tools Market