
 India Structural Steel Fabrication Market | 2026-2036
India Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
India Structural Steel Fabrication Market Foresight
Project finance availability for infrastructure buildouts is tilting competitive dynamics toward firms with balance-sheet capacity. Tata Steel leverages captive iron ore and downstream integration to secure margin visibility on long-delivery contracts. Larsen & Toubro anchors its fabrication dominance through EPC-led bundling that locks in steel offtake across metro rail, nuclear containment, and data center projects. Jindal Steel & Power competes on plate and structural section breadth, supplying specialized grades for bridge and power-plant applications.
Structural steel fabrication transforms hot-rolled sections, plates, and hollow sections into engineered assemblies through cutting, welding, bending, and surface treatment, with yield strengths typically ranging from 250 MPa to 550 MPa per BIS 2062 and IS 800 design codes. The process serves as the skeletal backbone for buildings, bridges, industrial plants, and transmission infrastructure where load-bearing performance governs safety margins. Infrastructure applications command the deepest fabrication value pools, driven by girders, trusses, and portal frames for railways and expressways. Carbon steel dominates material intake by tonnage, though coated steel is gaining share in coastal and chemical-exposure projects where corrosion resistance extends asset life.
BIS standards, the Indian Railways' RDSO specifications, and state-level RERA compliance frameworks collectively dictate weld quality, traceability, and fire-rating thresholds that fabricators must certify before contract eligibility. The Ministry of Steel's PLI scheme for specialty grades is redirecting capital toward high-strength and weathering steel capacities that reduce lifecycle costs for bridge and offshore structures. Stakeholders must track how National Steel Policy revisions and state-level mandi reforms alter raw material access economics for mid-scale fabrication units.
Market Dynamics
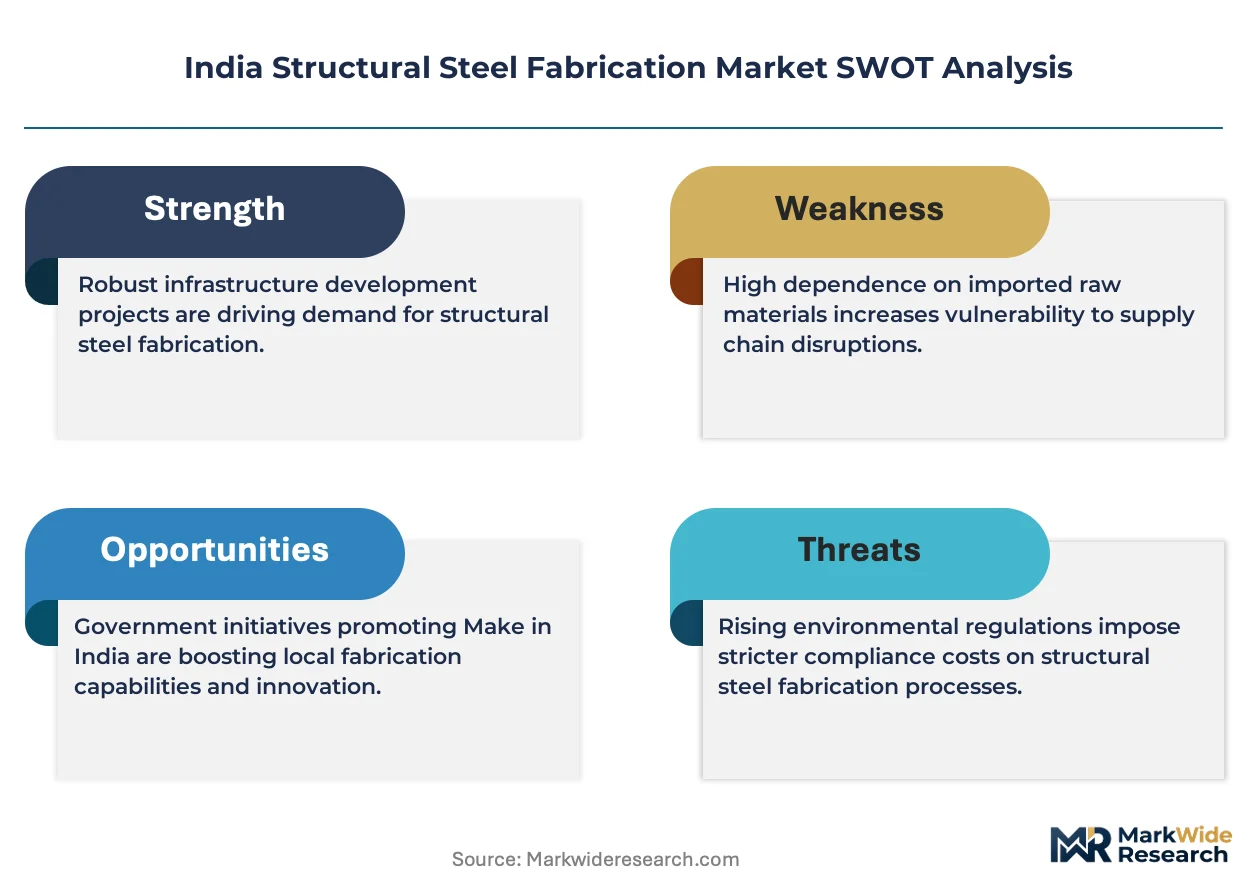
Project finance concentration and BIS certification mandates are compressing the vendor base, favoring fabricators with captive raw material access and multi-location weld qualification capacity.
Growth Catalysts
- National Infrastructure Pipeline:Megaprojects in metro rail, expressway corridors, and port modernization are absorbing record structural steel tonnage, locking in multi-year fabrication contracts.
- BIM-enabled workflows:Building Information Modeling integration is compressing design-to-fabrication cycles, reducing rework rates and enabling just-in-time delivery for complex truss assemblies.
- PLI scheme for specialty grades:Ministry of Steel incentives are redirecting capital toward high-strength and weathering steel capacities, expanding addressable markets for bridge and offshore structures.
Market Restraints
- Scrap and billet cost volatility:Input price swings compress margin visibility for mid-scale fabricators lacking long-term raw material hedging mechanisms.
- Odisha-Jharkhand supply concentration:Captive iron ore and primary steel capacity clusters in eastern India create logistics cost disadvantages for western and southern fabrication hubs.
- Welder certification bottlenecks:BIS and Indian Railways RDSO qualification timelines extend project onboarding, limiting surge capacity during peak construction windows.
Strategic Opportunities
- Data center structural frames:Hyperscale cloud infrastructure buildouts in Mumbai, Chennai, and Hyderabad corridors are creating demand for vibration-resistant steel assemblies with rapid deployment timelines.
- Coastal corrosion-resistant coatings:Chemical-exposure projects in Gujarat and Tamil Nadu are expanding specification for duplex coating systems that extend asset lifecycle.
- Modular prefabrication for affordable housing:State-level RERA compliance frameworks and PMAY-Urban mandates are opening standardized portal-frame contracts for volume fabrication players.
Industry Challenges
- CNC programming and robotic welding talent:Shortage of operators capable of integrating automated cutting and welding cells limits productivity gains from capital equipment investments.
- Multi-standard traceability systems:Simultaneous compliance with BIS 2062, IS 800, and project-specific client specifications fragments quality documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Structural Steel Fabrication Market |
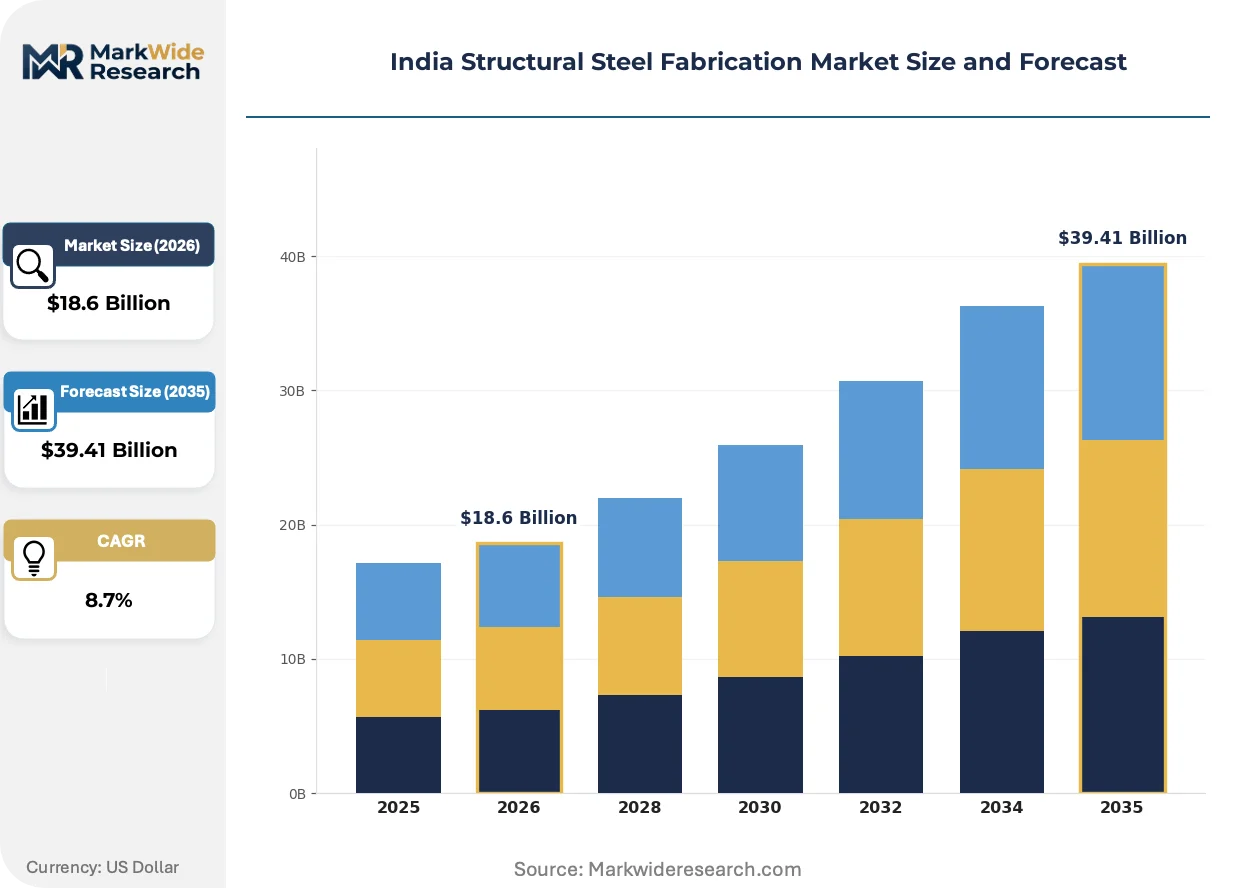
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential, Commercial, Industrial, Infrastructure Material Type: Carbon Steel, Alloy Steel, Stainless Steel, Coated Steel End User: Construction Firms, Engineering Companies, Fabricators, Contractors Fabrication Method: Welding, Cutting, Bending, Assembly |
| Companies Covered | Bharat Forge, Tata Steel, Larsen & Toubro, Steel Authority of India, Walchandnagar Industries, ISGEC Heavy Engineering, Jindal Steel & Power, Mukand, Bharat Heavy Electricals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Structural Steel Fabrication Market Shifts & Advancements
Digital thread integration from design through erection is compressing project timelines and redefining competitive advantage around data interoperability rather than standalone equipment scale.
BIM-to-fabrication data pipelines are digitizing shop floor operations by translating structural models directly into CNC cutting paths and robotic welding sequences. Infrastructure EPCs and industrial developers are mandating these handoffs on contracts above defined complexity thresholds. The technology is digitizing quality assurance by embedding weld mapping and material traceability into digital twins that persist through asset lifecycle.
BIS certification mandates for fire-rated structural assemblies are elevating documentation burdens while creating segmentation between qualified and unqualified vendors. The regulation is compressing tender eligibility for fabricators lacking in-house testing facilities or third-party laboratory partnerships. Bridge and metro rail segments are responding by consolidating supplier panels around pre-qualified fabrication yards with demonstrated RDSO and BIS track records.
Buyers are unbundling fabrication from turnkey EPC contracts to secure direct control over steel grade selection and weld quality verification. Large infrastructure developers are establishing preferred fabricator networks with pre-negotiated rates and dedicated capacity allocations. This pattern is most visible in Maharashtra and Gujarat, where port-linked industrial corridor projects require synchronized delivery schedules that generic EPC procurement cannot guarantee.
India Structural Steel Fabrication Market Segmentation
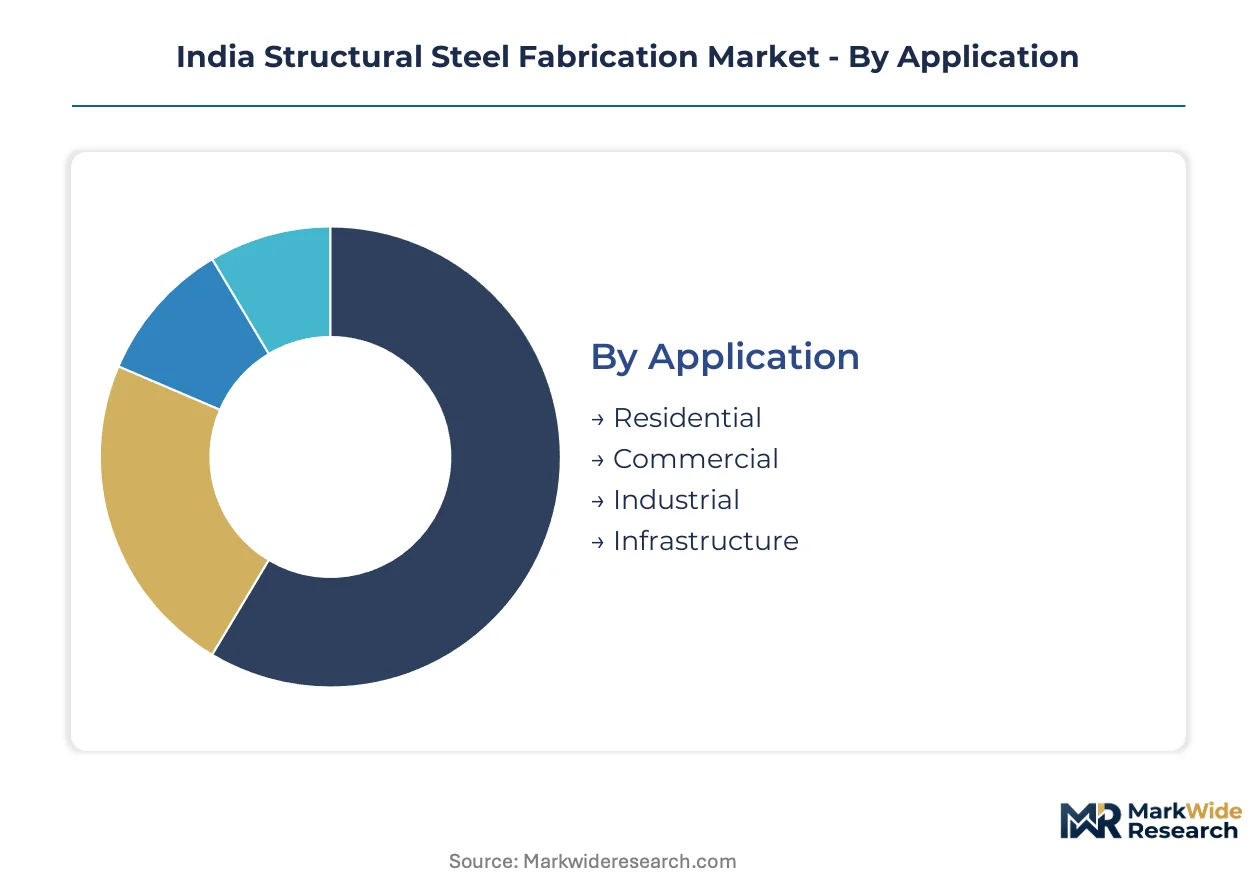
Structural steel fabrication in India serves radically different performance requirements across building types, material grades, and project delivery models. Segmentation reveals how BIS certification tiers, corrosion exposure levels, and EPC bundling strategies partition the vendor base into distinct competitive arenas.
Application:
Demand intensity spans from standardized portal frames to engineered seismic-resistant assemblies for mission-critical infrastructure.
- Infrastructure:Girders, trusses, and portal frames for metro rail corridors, expressway interchanges, and port modernization dominate tonnage absorption. Maharashtra and Gujarat industrial corridors lock in multi-year fabrication contracts with pre-qualified yards.
- Industrial:Power plant boiler structures, refinery pipe racks, and manufacturing facility frameworks require specialized weld procedures per BIS 2062 and IS 800 design codes. Heavy plate fabrication concentrates in eastern India near captive steel supply.
- Commercial:High-rise building frames and data center structural assemblies in Mumbai, Chennai, and Hyderabad corridors specify vibration-resistant connections with rapid deployment timelines.
- Residential:Affordable housing under PMAY-Urban mandates standardized light-gauge portal frames, though adoption remains constrained by masonry construction cost advantages in tier-2 and tier-3 cities.
Established volume favors Infrastructure; emerging adoption favors Commercial data center frames.
Material Type:
Raw material selection hinges on strength-to-weight ratios, corrosion exposure, and lifecycle cost calculations across coastal and chemical-process environments.
- Carbon Steel:Hot-rolled sections and plates with yield strengths of 250-350 MPa constitute the tonnage base for buildings and standard bridges. Eastern India's Odisha-Jharkhand cluster supplies billet and slab at logistics cost advantage to nearby fabrication hubs.
- Coated Steel:Duplex coating systems—zinc-aluminum base layers with epoxy topcoats—extend asset life in Gujarat and Tamil Nadu coastal projects where salt spray accelerates corrosion. Chemical-exposure specifications in refineries and ports are expanding addressable demand.
- Alloy Steel:Quenched and tempered grades deliver 420-550 MPa yield strengths for heavy crane girders and mining equipment frames. The Ministry of Steel's PLI scheme is redirecting capacity expansion toward these high-strength grades.
- Stainless Steel:Austenitic and duplex grades serve food processing, pharmaceutical clean rooms, and architectural facades where hygiene and aesthetic requirements override cost premiums.
Carbon Steel anchors current procurement volumes; Coated Steel is climbing the fastest on coastal infrastructure specifications.
End User:
Buyer sophistication and quality verification capabilities determine contract eligibility and pricing power in the vendor relationship.
- Engineering Companies:EPC-led bundling by Larsen & Toubro and comparable firms locks in steel offtake across metro rail, nuclear containment, and industrial projects. These buyers mandate BIM-to-fabrication data handoffs and pre-qualify yards on BIS and RDSO track records.
- Construction Firms:Large infrastructure developers in Maharashtra and Gujarat are unbundling fabrication from turnkey contracts to secure direct control over grade selection and weld verification. Preferred fabricator networks with dedicated capacity allocations are consolidating around synchronized delivery requirements.
- Fabricators:Mid-scale independent shops serve secondary steel demand for warehouses, commercial fit-outs, and residential extensions. These operators face margin compression from scrap and billet cost volatility without long-term hedging mechanisms.
- Contractors:Small-scale contractors procure standardized beam-column assemblies for low-rise construction, often sourcing from regional distributors rather than direct mill relationships.
Engineering Companies concentrate premium contract flow; Construction Firms are gaining procurement autonomy fastest.
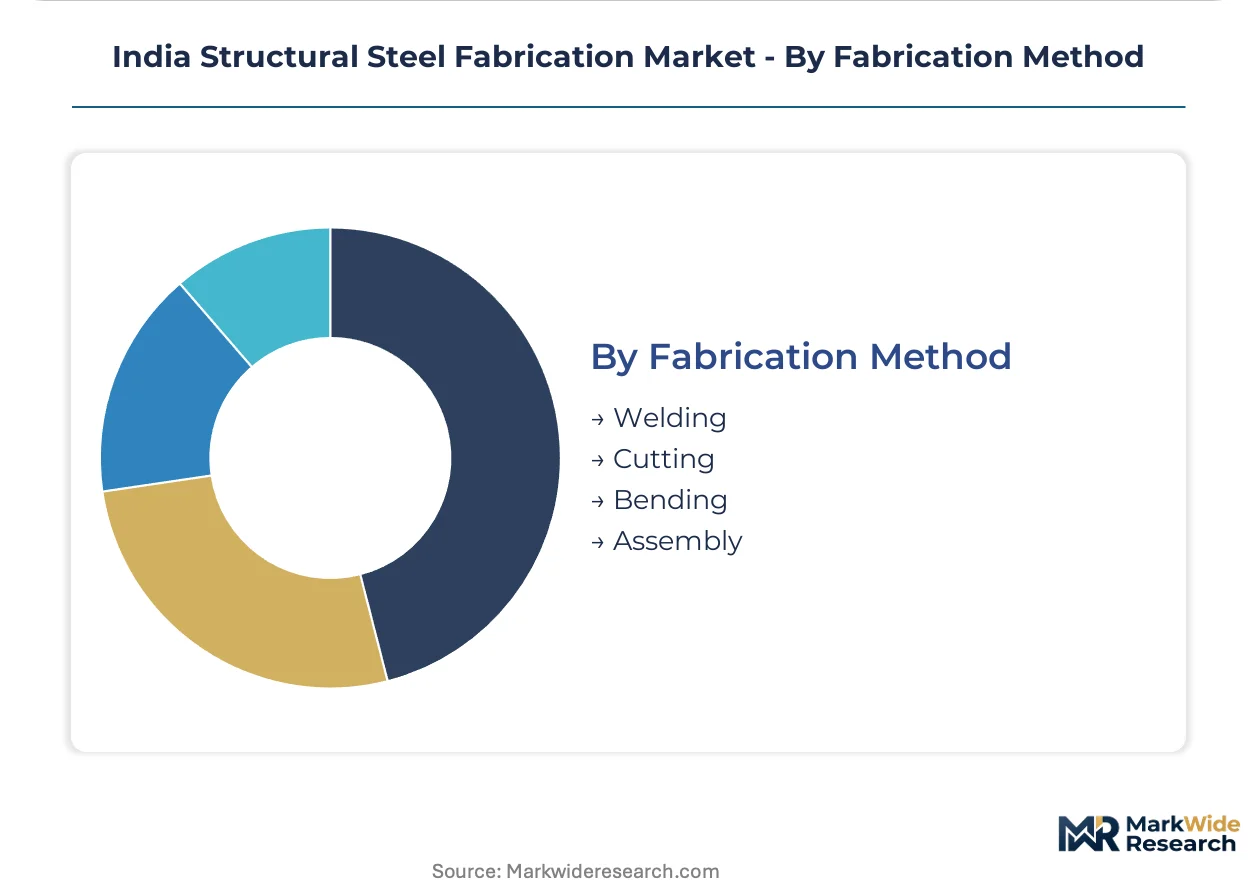
Fabrication Method:
Process automation and certification requirements fragment the competitive landscape between precision-engineered and commodity assembly operations.
- Welding:Shielded metal arc, submerged arc, and gas metal arc processes dominate structural joint fabrication. BIS and Indian Railways RDSO qualification timelines extend project onboarding, limiting surge capacity during peak construction windows.
- Cutting:CNC oxy-fuel and plasma cutting systems translate BIM models directly into plate and section profiles. Shortage of operators capable of programming automated cutting cells constrains productivity gains from capital equipment investments.
- Bending:Press brake and roll-forming operations shape plates into curved girders and architectural sections. Multi-standard traceability requirements fragment quality documentation workflows across BIS 2062, IS 800, and client-specific specifications.
- Assembly:Fit-up and bolting of sub-components into transportable modules enables just-in-time delivery for congested urban sites. Modular prefabrication is expanding under state-level RERA compliance frameworks for affordable housing.
Welding commands the deepest certification barriers; Cutting is gaining automation penetration fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Steel's PLI scheme for specialty grades and state-level infrastructure mandates are redirecting fabrication demand toward sub-regions with port-linked industrial corridors and metro rail buildouts.
Maharashtra
Mumbai Metro Line extensions and the Mumbai-Ahmedabad high-speed rail corridor absorb heavy structural tonnage for viaduct girders and station frameworks. BIS certification requirements for fire-rated assemblies compress tender eligibility to pre-qualified yards. The Mumbai-Pune industrial belt concentrates fabrication capacity serving data center and commercial high-rise projects.
Gujarat
Dholera Special Investment Region and port modernization at Mundra and Hazira drive demand for corrosion-resistant coated steel assemblies. State-level RERA compliance frameworks standardize documentation for affordable housing portal frames. The Ahmedabad-Surat corridor anchors fabrication hubs supplying chemical-process industries and coastal infrastructure.
Tamil Nadu
Chennai Metro Phase II and smart city deployments in Coimbatore and Madurai lock in multi-year contracts for seismic-resistant truss systems. Duplex coating specifications for salt-spray environments expand addressable demand for coastal bridge projects. The Sriperumbudur-Oragadam auto and electronics cluster sustains precision fabrication for industrial facility frameworks.
Telangana
Hyderabad's hyperscale data center corridor specifies vibration-resistant steel frames with rapid deployment timelines. The state's electronics manufacturing policy attracts fabrication capacity for clean-room and industrial infrastructure. The Hyderabad-Warangal industrial zone concentrates mid-scale shops serving warehouse and logistics park construction.
Karnataka
Bengaluru's metro rail extensions and aerospace manufacturing parks require specialized weld procedures per RDSO and BIS 2062 codes. The state's machine tool ecosystem supplies CNC cutting and bending equipment to regional fabrication yards. The Dharwad-Belagavi industrial corridor emerges as a secondary hub for bridge and highway structural components.
India Structural Steel Fabrication Market Competitive Landscape
On the supply side, the industry is consolidating around integrated steel producers and EPC-led bundlers that control raw material access and multi-location certification capacity. Three archetypes dominate: captive steel mills with downstream fabrication arms, infrastructure EPCs with in-house steel shops, and independent mid-scale fabricators serving secondary demand. Competitive moves center on backward integration into iron ore and plate supply, plus strategic partnerships to secure weld qualification capacity across multiple state jurisdictions.
Among integrated steel producers, Tata Steel and Jindal Steel & Power occupy positions that exemplify captive raw material advantage, while Larsen & Toubro anchors the EPC-led bundling archetype through project execution scale. These three entities represent the dominant competitive formations: mill-integrated fabricators leveraging ore access for margin visibility, and construction-led players locking in offtake through design-build contracts.
| Leading Market Players |
|---|
| Bharat Forge |
| Tata Steel |
| Larsen & Toubro |
| Steel Authority of India |
| Walchandnagar Industries |
| ISGEC Heavy Engineering |
| Jindal Steel & Power |
| Mukand |
| Bharat Heavy Electricals |
| Others |
Supply & Pricing Matrix
Odisha-Jharkhand's captive iron ore and primary steel clusters concentrate raw material leverage in eastern India, positioning integrated mills to capture margin pools that mid-scale western and southern fabricators cannot access. This geographic asymmetry compresses pricing power for non-integrated players while elevating contract premiums for yards with BIS-certified weld capacity and multi-location qualification.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with BIS 2062 and RDSO-qualified yards commanding project-based long-term offtake premiums against spot-market commodity assemblers. Price differentiation hinges on traceability documentation and fire-rating compliance, with western hubs facing cost compression from logistics disadvantages relative to eastern supply clusters. Margins are tightening for mid-scale independents lacking captive ore or plate hedging, while construction firms with preferred fabricator networks exhibit lowest price sensitivity due to synchronized delivery requirements.
Supply Chain Analysis
Export-control regimes on advanced CNC and robotic welding systems limit technology flows into Indian fabrication yards, constraining automation penetration. Supply concentrates in China, Germany, and Japan for precision cutting equipment and consumables, while billet and slab feedstock draws from domestic Odisha-Jharkhand clusters. Single-source vulnerability runs through specialized alloy import dependencies for high-strength grades. Distribution feeds through EPC-led bundling and direct mill relationships, with secondary channels serving contractor spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified welder scarcity and multi-standard traceability burdens fragment competitive capacity, creating acquisition opportunities around certified yards with demonstrated BIS and RDSO track records. The capability gap between automated and manual fabrication operations widens the performance spread that capital can exploit.
For Market Incumbents: Entrench fabrication dominance through backward integration into plate supply and captive coating facilities, securing margin visibility against scrap volatility. Expand multi-location weld qualification capacity across Maharashtra, Gujarat, and Tamil Nadu to capture National Infrastructure Pipeline contract flows. Lock in data center and metro rail segments through pre-negotiated preferred supplier networks with dedicated capacity allocations. For New Entrants and Emerging Players: Pursue modular prefabrication contracts under PMAY-Urban mandates and state-level RERA frameworks, where standardized portal-frame specifications lower certification barriers. Target Telangana's hyperscale data center corridor for vibration-resistant frame assemblies with rapid deployment timelines. Establish go-to-market partnerships with regional distributors serving warehouse and logistics park construction outside EPC-dominated infrastructure segments. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fabricators with existing BIS certification and underutilized automation equipment, where operational leverage meets acquisition multiple compression. Long-term viability favors yards with demonstrated RDSO track records and geographic positioning in western or southern industrial corridors. Watch for inflection in Ministry of Steel PLI scheme allocations toward high-strength and weathering steel capacities as signal for specialty grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plate Supply | Captive steel access insulates margin visibility from Odisha-Jharkhand logistics cost swings. |
| Multi-Location Weld Qualification | BIS and RDSO certification across states unlocks National Infrastructure Pipeline contract eligibility. |
| BIM-to-Fabrication Data Pipeline | Digital thread integration compresses design-to-delivery cycles for complex truss assemblies. |
| Coastal Corrosion-Resistant Coating Capacity | Duplex coating systems capture Gujarat and Tamil Nadu port modernization specifications. |
| Modular Prefabrication Scale-Up | Standardized portal-frame production aligns with PMAY-Urban affordable housing mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and industry association reports across the structural steel value chain. Primary inputs drew from EPC procurement directors, fabrication yard operations managers, Ministry of Steel policy leads, and Indian Railways RDSO certification officers. Secondary validation incorporated BIS standard documentation, Ministry of Steel PLI scheme disclosures, state-level RERA framework publications, and customs data on steel import flows. Bottom-up project pipeline assessments triangulated against top-down steel consumption forecasts.
Forecast inputs span application segments, material grade tiers, fabrication method automation levels, and regional infrastructure deployment patterns across the projection horizon. Modeled dimensions include infrastructure versus commercial versus residential end-use, carbon versus coated versus alloy steel specifications, and welding versus cutting versus assembly process intensity. CAGRs derived from trend extrapolation of National Infrastructure Pipeline project awards, steel sector capacity expansion timelines, and regulatory compliance cost trajectories. Industry-specific inputs incorporated BIS certification adoption curves and BIM penetration rates in EPC contracting.
Macroeconomic conditions sit as an overlay; deviation in infrastructure disbursement velocity, iron ore pricing, or rupee-denominated equipment import costs would shift the trajectory. Forecasts reflect documented assumptions on project finance availability and welder certification throughput capacity. Material shifts in National Steel Policy revisions or state-level mandi reform implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
UK Facade Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Civil Engineering Market