
 US Commercial Windows Market | 2026-2036
US Commercial Windows Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Windows Market Intelligence
Glazier and fenestration technician shortages across the Southeast and Southwest is reorganizing project timelines and pushing general contractors toward prefabricated window systems. Andersen Windows & Doors leverages its vertically integrated wood-composite supply chain to control lead times in premium segments. Pella Corp. competes through specialized commercial-grade aluminum framing systems designed for mid-rise office towers. Marvin Windows and Doors anchors its position in the replacement channel through dealer network density in legacy urban cores.
US Commercial Windows are factory-assembled fenestration units incorporating insulated glass, thermally broken frames, and weather-sealed operable or fixed sash configurations engineered to manage solar heat gain, daylighting, and structural wind loads in non-residential buildings. The primary commercial purpose centers on envelope performance, occupant comfort, and code-compliant energy efficiency in buildings over three stories. Aluminum frames dominate new construction specifications due to strength-to-weight ratios and curtain wall compatibility, while vinyl captures replacement volume through cost-positioning in retail and office renovation. Fiberglass represents the fastest-growing material category as architects specify it for coastal and high-thermal-performance healthcare projects.
NFRC certification requirements, ASHRAE standards, and the Inflation Reduction Act efficiency provisions collectively shape product specifications and procurement criteria across federal, state, and municipal commercial projects. The Department of Energy's ENERGY STAR Most Efficient designation increasingly gates access to institutional and government building portfolios. Stakeholders must monitor evolving state-level stretch codes in California, Washington, and New York that anticipate federal benchmarks and force early specification upgrades.
Market Dynamics
Glazier shortages across the Sun Belt are compressing project timelines and forcing general contractors toward prefabricated window systems, fundamentally restructuring how commercial fenestration reaches job sites.
Growth Catalysts
- IRA Efficiency Tax Incentives:The Inflation Reduction Act's provisions for high-performance glazing systems are accelerating hospital and university retrofit programs across the Southeast.
- Healthcare Facility Expansion:Hospital construction in Texas and Florida is driving specification upgrades for thermally broken aluminum curtain walls meeting ASHRAE standards.
- Fiberglass Material Adoption:Coastal healthcare projects are specifying pultruded fiberglass frames for salt-air corrosion resistance and superior thermal performance.
Market Restraints
- Aluminum Input Cost Volatility:Primary aluminum price swings tied to smelter energy costs in the Pacific Northwest are compressing fabricator margins on fixed-bid commercial projects.
- NFRC Certification Timelines:Extended third-party thermal performance testing queues are delaying product launches for mid-size regional window manufacturers.
- Float Glass Supply Concentration:Domestic flat glass production concentrates among three primary suppliers, creating vulnerability for large-scale curtain wall contracts.
Strategic Opportunities
- Stretch Code Anticipation:California's Title 24 and Washington's Clean Buildings Performance Standard are creating early-mover advantage for triple-glazed system suppliers.
- Retrofit Channel Penetration:Legacy urban cores in Chicago and Philadelphia present replacement volume as 1970s curtain walls reach end-of-service life.
- Integrated Facade Systems:Convergence of dynamic glazing with building management systems is opening specification pathways for technology-embedded window units.
Industry Challenges
- Fenestration Technician Shortage:Specialized curtain wall installation skills are scarce in Arizona and Nevada, extending project schedules and inflating labor rates.
- Curtain Wall Integration Complexity:Coordination between window fabricators and structural steel contractors on mid-rise towers generates field-adjustment costs and waterproofing liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Windows Market |
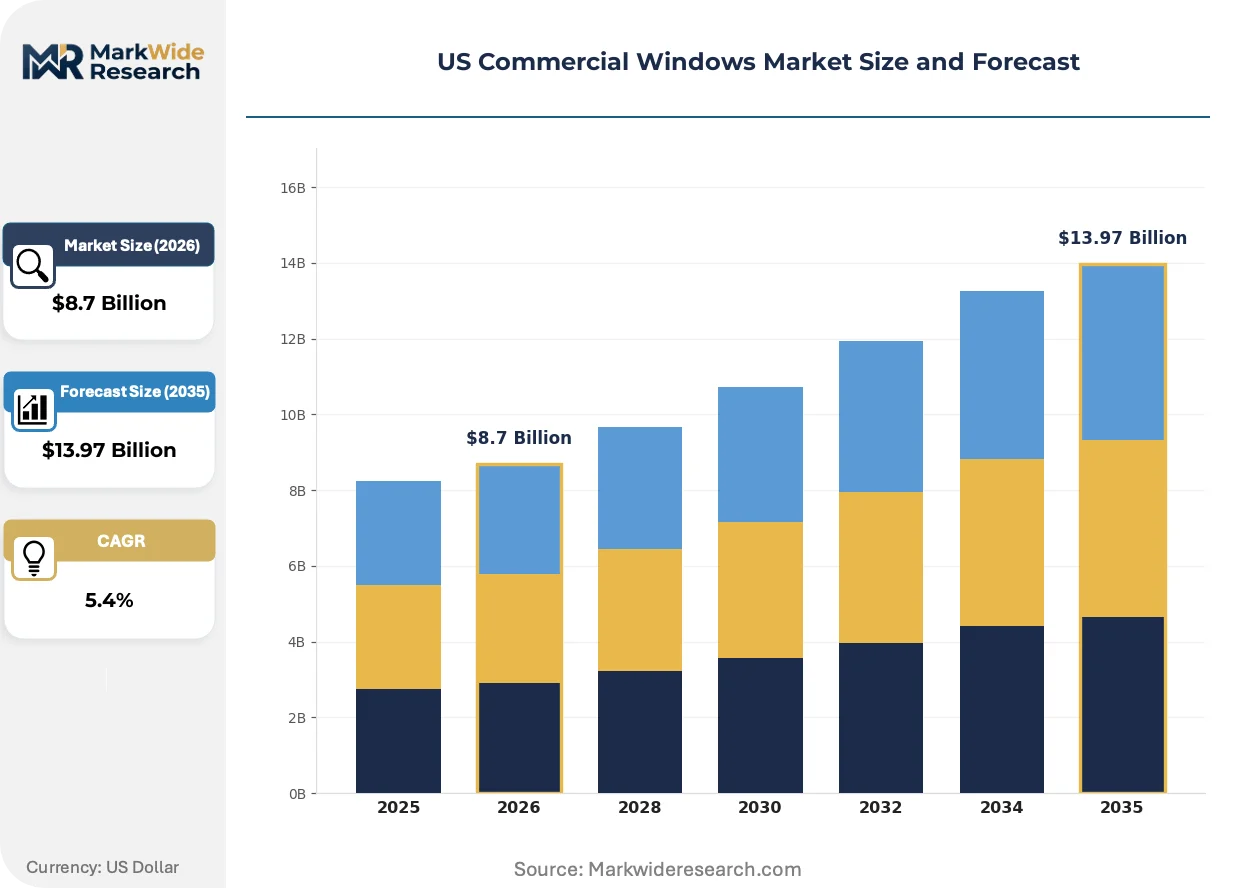
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Window Type: Casement, Sliding, Double-Hung, Awning Material: Vinyl, Aluminum, Wood, Fiberglass Installation Type: New Construction, Replacement, Renovation, Retrofit End User: Office Buildings, Retail Spaces, Educational Institutions, Healthcare Facilities |
| Companies Covered | Jeld-Wen, PGT Innovations, Andersen Windows & Doors, Winco Window, Ply Gem, Pella Corp., YKK AP America Inc., Velux USA, Marvin Windows and Doors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Windows Market Strategic Shifts & Innovations
Electrochromic glazing and vacuum-insulated glass are crossing cost thresholds that position them for mainstream commercial adoption, while procurement patterns favor turnkey facade contractors over discrete window suppliers.
Vacuum-insulated glass units utilizing edge-sealed evacuated cavities are achieving R-values comparable to insulated wall assemblies. Healthcare and laboratory developers in Boston and Seattle are specifying these systems for thermal bridge elimination. The technology is displacing conventional triple-glazed configurations in net-zero building portfolios where envelope performance targets are most aggressive.
The Department of Energy's ENERGY STAR Most Efficient designation is tightening qualification criteria for commercial fenestration products. Federal GSA procurement schedules now require this certification for new construction and major renovation contracts. Institutional buyers in the Mountain West are filtering specifications early to avoid downstream compliance risk on projects seeking IRA tax incentives.
General contractors are consolidating envelope procurement under single-source facade contractors rather than bidding windows separately from curtain wall and cladding. This bundling compresses supplier margins while shifting design-assist risk to integrated facade specialists. The pattern is most pronounced in speculative office development across Atlanta and Dallas-Fort Worth where speed-to-market prioritizes simplified procurement structures.
US Commercial Windows Market Segmentation
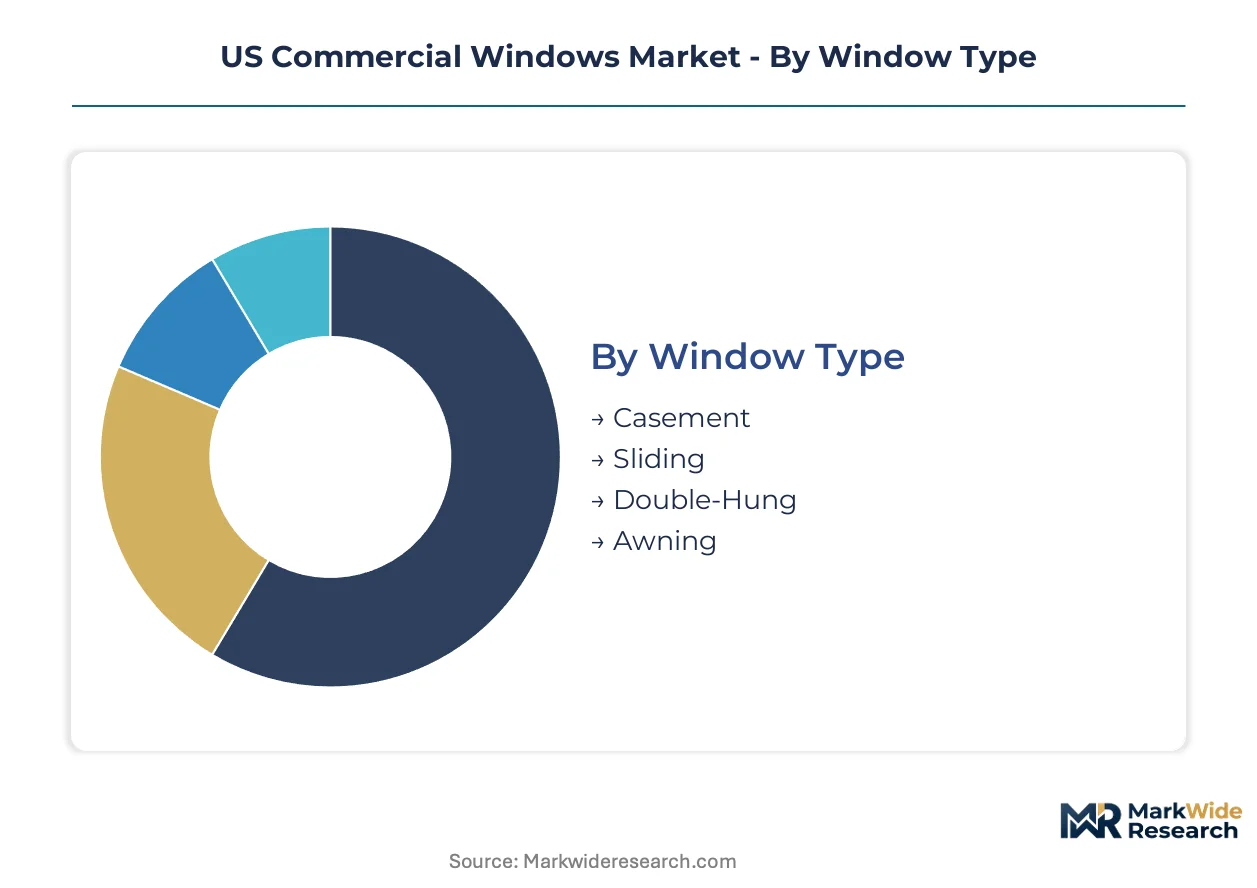
Commercial window procurement channels diverge sharply by project type, with new construction flowing through curtain wall contractors while replacement volume concentrates in dealer networks serving facility managers. Understanding these pathway distinctions enables suppliers to align inventory, certification, and service capabilities with actual purchase behavior.
Window Type:
Channel mix varies by operability requirements, with fixed and operable units following separate distribution paths to job sites.
- Casement:Hinged sash units projecting outward with multi-point locking hardware. Hospital patient towers in Florida and Texas specify these for controlled ventilation and pressure management. Demand concentrates through design-build healthcare contractors.
- Sliding:Horizontal sash travel on thermally broken tracks. Retail strip centers across Arizona and Nevada favor these for cost-efficient storefront configurations. Volume flows through regional glazing subcontractors serving speculative development.
- Double-Hung:Vertically operable sashes meeting historic preservation codes. Philadelphia and Baltimore school districts specify these for 1920s building renovations.
- Awning:Top-hinged units permitting ventilation during precipitation. Seattle and Portland office retrofits specify these for natural cooling strategies.
By volume, Sliding leads. By growth pace, Casement is ahead.
Material:
Cost tier alignment determines specification authority, with premium materials requiring architect engagement and economy materials flowing through contractor-directed procurement.
- Vinyl:PVC extrusions with multi-chamber thermal breaks. Suburban office parks in the Southeast specify these for renovation budgets under IRA incentive thresholds. Volume concentrates in replacement channel through stocking distributors.
- Aluminum:Thermally broken extrusions with polyamide struts. Mid-rise towers in Dallas-Fort Worth and Atlanta specify these for curtain wall integration. New construction specifications dominate this segment.
- Wood:Solid and engineered lumber with aluminum cladding. Historic district hotels in Boston and Charleston specify these for facade authenticity requirements.
- Fiberglass:Pultruded profiles with embedded glass fiber. Coastal healthcare projects in Florida specify these for salt-air corrosion resistance and thermal performance. This material is expanding most quickly.
By installed base, Aluminum dominates. By specification momentum, Fiberglass is gaining share fastest.
Installation Type:
Customer type dictates project structure, with institutional owners favoring performance contracts and speculative developers prioritizing speed-to-occupancy.
- New Construction:Factory-fabricated units integrated during structural steel erection. Speculative office towers in Sun Belt markets drive volume through design-assist procurement.
- Replacement:In-sash substitution preserving existing frames. Chicago and Philadelphia legacy cores generate volume as 1970s curtain walls reach end-of-service life.
- Renovation:Frame modification with envelope remediation. University housing authorities in California specify these for Title 24 compliance upgrades.
- Retrofit:Complete fenestration system replacement with structural adaptation. Hospital systems in Texas pursue these through IRA tax incentive programs.
By project count, Replacement leads. By contract value, New Construction is ahead.
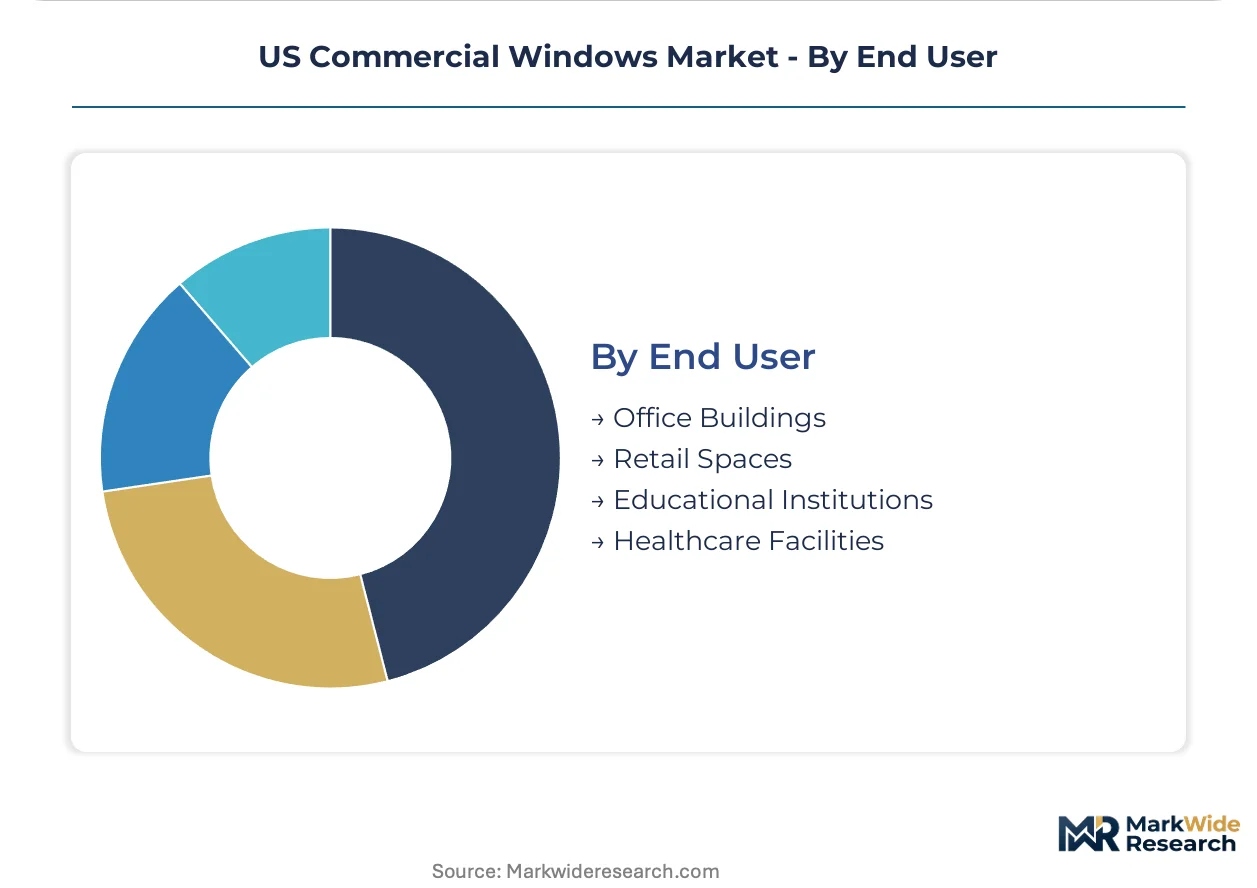
End User:
Application context shapes performance requirements, with healthcare and education imposing distinct thermal and acoustic specifications that filter supplier eligibility.
- Office Buildings:Speculative and owner-occupied towers requiring daylight optimization. Atlanta and Dallas-Fort Worth construction activity concentrates demand through integrated facade contractors.
- Retail Spaces:Big-box and strip center configurations prioritizing display visibility. Phoenix and Las Vegas development cycles drive volume through national retail construction managers.
- Educational Institutions:K-12 and university facilities with acoustic and security requirements. Texas and Florida school bond programs generate specification upgrades.
- Healthcare Facilities:Hospitals and clinics with pressure differential and infection control needs. ASHRAE compliance requirements filter procurement to certified fabricators.
By square footage, Office Buildings lead. By specification intensity, Healthcare Facilities is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across US sub-regions diverge sharply between Sun Belt new construction and legacy urban replacement, with Texas and Florida driving aluminum curtain wall specifications while the Northeast and Midwest concentrate renovation volume.
Texas
Hospital construction in Dallas-Fort Worth and Houston generates demand for thermally broken aluminum systems meeting ASHRAE standards. The Inflation Reduction Act's efficiency tax incentives accelerate healthcare retrofit programs across the state's medical center districts. Austin's speculative office towers channel procurement through integrated facade contractors prioritizing speed-to-market.
Florida
Coastal healthcare projects specify pultruded fiberglass frames for salt-air corrosion resistance and thermal performance. Miami-Dade and Tampa Bay construction activity concentrates demand for hurricane-rated glazing systems. The state's building code enforcement filters procurement to certified fabricators with NFRC documentation.
California
Title 24 stretch codes create early-mover advantage for triple-glazed system suppliers in Los Angeles and San Francisco Bay Area developments. University housing authorities specify renovation packages for compliance upgrades. The California Energy Commission's evolving benchmarks force specification upgrades ahead of federal adoption.
Illinois
Chicago's legacy urban core generates replacement volume as 1970s curtain walls reach end-of-service life. School districts specify double-hung units meeting historic preservation codes for 1920s building renovations. The city's commercial retrofit pipeline concentrates procurement through dealer networks serving facility managers.
Washington
Seattle and Portland office retrofits specify awning windows for natural cooling strategies. The Clean Buildings Performance Standard mandates performance upgrades across commercial portfolios. Healthcare and laboratory developers in the Puget Sound region specify vacuum-insulated glass for thermal bridge elimination in net-zero projects.
US Commercial Windows Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling captive supply chains for premium segments and the specialist tier competing on regional fabrication proximity. Three archetypes dominate: vertically integrated wood-composite specialists, aluminum curtain wall fabricators with design-assist capabilities, and fiberglass pultrusion specialists serving coastal healthcare. Competitive moves concentrate on backward integration into glass supply and consolidation of regional glazing subcontractor networks.
Among domestic fabricators, Andersen Windows & Doors, Pella Corp., and Marvin Windows and Doors exemplify distinct strategic positions within the tiered structure. Andersen occupies a position anchored in vertically integrated wood-composite supply chain control. Pella represents the aluminum framing specialist archetype targeting mid-rise commercial specifications. Marvin exemplifies dealer network density strategies concentrated in replacement channel penetration across legacy urban cores.
| Leading Market Players |
|---|
| Jeld-Wen |
| PGT Innovations |
| Andersen Windows & Doors |
| Winco Window |
| Ply Gem |
| Pella Corp. |
| YKK AP America Inc. |
| Velux USA |
| Marvin Windows and Doors |
| Others |
Cost & Logistics Intelligence
NFRC certification requirements gate both supply qualification and price differentiation simultaneously, filtering commercial window fabricators into certified premium tiers versus uncertified economy positions while the Inflation Reduction Act's efficiency tax incentives concentrate procurement authority among specification-grade suppliers commanding measurable premiums.
Pricing Analysis
Project-based contracts dominate commercial window procurement, with fixed-bid structures exposing fabricators to aluminum input cost volatility from Pacific Northwest smelter energy swings. Pricing stratifies across premium, standard, and economy tiers based on NFRC certification grade and thermal performance designation, with ENERGY STAR Most Efficient units commanding authority in federal GSA schedules. Cost compression in mid-rise aluminum curtain walls is intensifying because general contractors consolidate envelope procurement under single-source facade contractors. Speculative developers in Atlanta and Dallas-Fort Worth exhibit highest price sensitivity, while healthcare systems pursuing IRA tax incentives demonstrate lowest sensitivity to upfront premiums.
Supply Chain Analysis
Float glass supply concentration among three domestic primary suppliers creates single-source vulnerability for large-scale curtain wall contracts serving Texas hospital construction and Florida coastal healthcare projects. The US commercial window supply chain draws from primary aluminum smelters in the Pacific Northwest, pultruded fiberglass operations in the Southeast, and polyamide thermal break extrusions from specialized compounders. Tariff exposure on imported glass and aluminum components amplifies margin pressure for regional fabricators without captive supply arrangements. Distribution runs through integrated facade contractors consolidating window, curtain wall, and cladding procurement rather than discrete window suppliers bidding separately.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Commercial Windows Market fragmentation creates opportunity as procurement consolidation under integrated facade contractors splinters specification authority across project types, with healthcare retrofit programs and legacy urban replacement generating distinct supplier niches.
For Market Incumbents: Fortify backward integration into glass supply and regional glazing subcontractor networks to defend against margin compression from single-source facade procurement consolidation. Capture captive supply of float glass and thermally broken aluminum extrusions to offset input cost volatility. Deepen certification investment in NFRC and ENERGY STAR Most Efficient designations to maintain access to federal GSA schedules and IRA-incentivized healthcare retrofits. For New Entrants and Emerging Players: Anchor in pultruded fiberglass specialization for coastal healthcare projects where salt-air corrosion resistance and thermal performance command specification premiums. Target Chicago and Philadelphia legacy urban cores where 1970s curtain wall replacement volume concentrates through dealer networks underserved by national fabricators. Pursue design-assist partnerships with regional healthcare contractors in Texas and Florida as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum-insulated glass and electrochromic glazing sub-segments as net-zero building portfolios displace conventional triple-glazed configurations. Acquisition candidates include mid-cap fiberglass pultrusion specialists with coastal healthcare certification and regional glazing subcontractors with curtain wall installation capabilities in Arizona and Nevada. Monitor NFRC certification queue lengths as an inflection indicator for product launch delays that concentrate market share among certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass Supply | Captive glass production insulates fabricators from three-supplier concentration risk in large curtain wall contracts. |
| NFRC Certification Acceleration | Fast-tracked thermal performance testing unlocks federal GSA procurement schedules and IRA tax incentive eligibility. |
| Regional Glazing Subcontractor Acquisition | Controlled installation networks in Arizona and Nevada address fenestration technician shortages compressing project timelines. |
| Fiberglass Pultrusion Capacity Expansion | Coastal healthcare specification share gains from salt-air corrosion resistance and superior thermal performance metrics. |
| Integrated Facade Contractor Partnership | Design-assist relationships with consolidated envelope procurement channels secure position in speculative office development. |
Research Approach
The analysis maps window type, material, installation type, and end user segments, each validated through primary interviews with fenestration fabricators, glazing contractors, healthcare facility managers, and architectural specification consultants. Secondary validation draws from NFRC certification databases, ENERGY STAR product listings, Department of Energy efficiency program disclosures, and American Architectural Manufacturers Association technical standards. Bottom-up project pipeline tracking across Sun Belt construction markets triangulates against top-down spending flow analysis from federal IRA incentive allocation reports.
Outputs were validated against external benchmarks including regional construction spending indices, hospital capital expenditure disclosures, and curtain wall installation labor rate surveys. The analytical framework models volume and value across the projection horizon by window type, material tier, installation category, and end-use application, with additional dimensioning by state-level energy code adoption patterns. CAGRs were derived from regression analysis of historical specification trends and forward projection of IRA incentive uptake curves, with aluminum price elasticity and glazier wage inflation as key industry-specific forecast inputs.
Underlying assumptions cover sustained IRA efficiency tax incentive authorization, NFRC certification capacity expansion, and Sun Belt commercial construction activity levels, with deviation risk concentrated in aluminum smelter energy cost volatility and federal procurement policy shifts. Practitioners should keep alternative scenarios live as stretch code adoption timelines and integrated facade contractor consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Risers Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Oriented Strand Board (OSB) Market