
 Global Automated Mining Equipment Market | 2026-2036
Global Automated Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Mining Equipment Market Intelligence
The existing talent pool of experienced human mine equipment operators is collapsing under the pressure of retirements and a lack of new entrants. This skills gap creates a direct opening for automation. Caterpillar leverages its extensive installed base to deploy autonomous haulage systems. Sandvik AB specializes in advanced drilling and loading automation for underground environments, while Hexagon AB provides the critical software and sensor fusion platforms that enable fleet-wide autonomy.
Automated mining equipment refers to heavy machinery capable of performing tasks with reduced or no human intervention. These systems integrate guidance systems, such as LiDAR and high-precision GPS, with control systems to execute pre-programmed or dynamically calculated routes and functions. Within the equipment landscape, autonomous haulers represent the most mature and widely deployed segment, driven by clear productivity gains. The automation technology itself is a key battleground, with machine learning algorithms for predictive maintenance and real-time optimization becoming significant differentiators.
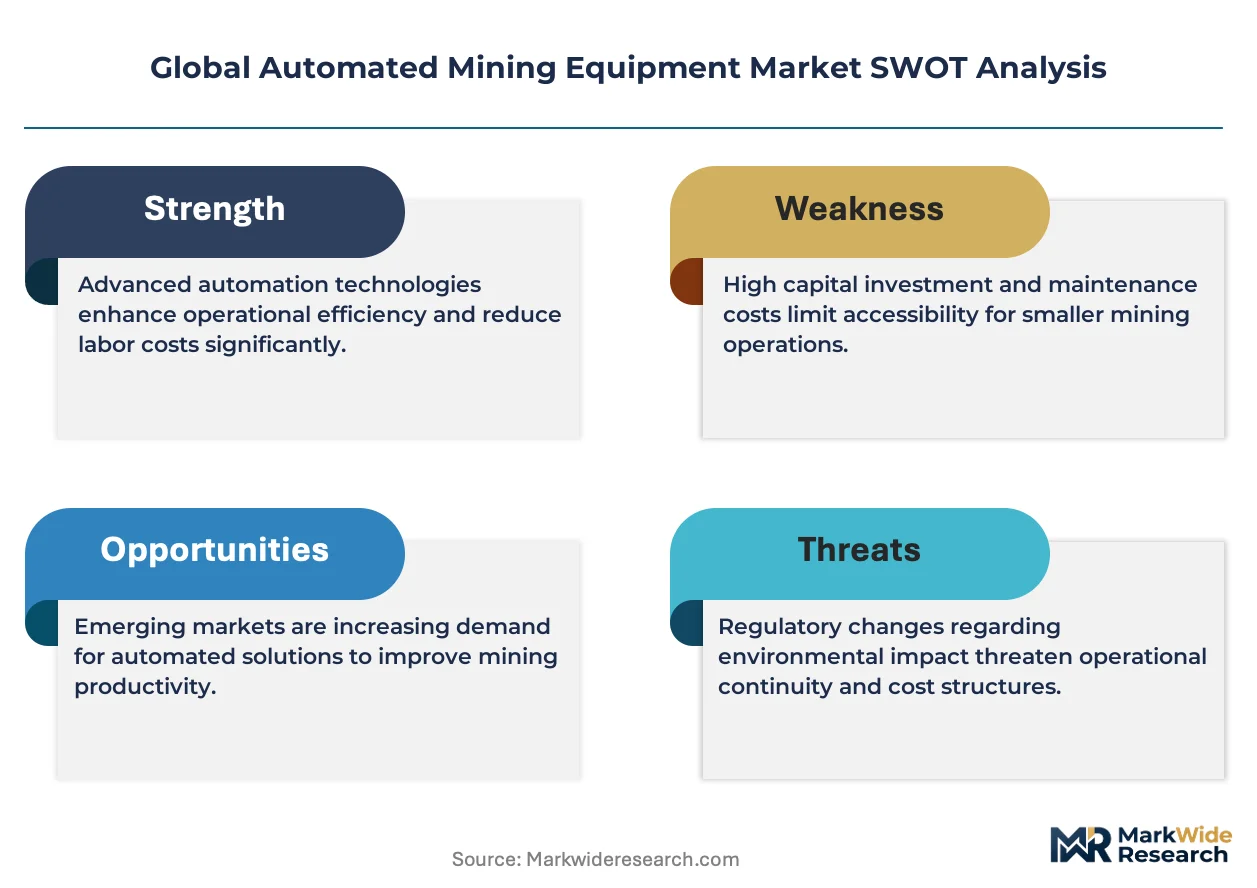
Safety mandates from bodies like the U.S. Occupational Safety and Health Administration (OSHA) and similar agencies in Australia and Canada create a strong incentive for removing humans from hazardous areas. Concurrently, ISO standards are emerging to ensure interoperability between equipment from different manufacturers, a critical factor for fleet-wide deployment. The central decision for mine operators now revolves around balancing the high initial capital outlay against the long-term operational efficiencies and safety improvements.
Market Dynamics
The acute shortage of skilled human operators, driven by retirements, collides with stringent safety regulations from agencies like the U.S. OSHA. This dual pressure creates a powerful, non-negotiable imperative for mining companies to adopt autonomous equipment technologies to maintain production and protect personnel.
Growth Catalysts
- Worker Safety Mandates:Regulations from bodies such as Australia's safety authorities and Canada's provincial mining regulators compel operators to remove personnel from high-risk environments like deep underground stopes and unstable open-pit faces.
- Critical Mineral Demand:The global energy transition requires vast quantities of minerals like lithium and cobalt, often found in deep or complex geologies, making automated deep-earth extraction a technical and economic necessity.
- Geographic Concentration:Major mining hubs, particularly for iron ore in Western Australia and copper in Chile's Atacama Desert, provide the scale necessary for large, cost-effective autonomous fleet deployments that justify the initial investment.
Market Restraints
- High Capital Outlay:The initial investment for a fleet of autonomous haulers and the requisite high-bandwidth wireless network infrastructure represents a significant financial barrier for junior and mid-tier mining operators.
- Interoperability Hurdles:A lack of universal communication standards, despite progress on ISO norms, complicates the integration of equipment from different manufacturers into a single, cohesive autonomous system, creating vendor lock-in risks.
- Sensor Supply Bottlenecks:The supply of high-performance LiDAR and specialized inertial measurement units is concentrated among a few suppliers, creating potential chokepoints and price volatility for equipment OEMs.
Strategic Opportunities
- Underground Automation:Beyond haulage, significant opportunity exists in automating the full drill-to-blast cycle in underground mines, a technically complex but high-value application with low current penetration.
- Predictive Maintenance AI:Integrating machine learning algorithms for predictive maintenance offers a new service-based revenue stream, shifting the model from equipment sales toward uptime-as-a-service contracts for OEMs.
- African Mining Corridors:Developing mining corridors in countries like Zambia and the DRC, rich in copper and cobalt, represent underpenetrated markets for initial deployments of modular autonomous systems tailored to local conditions.
Industry Challenges
- Automation Skill Gap:The industry faces a severe shortage of technicians, data scientists, and robotics engineers needed to install, maintain, and optimize autonomous mining fleets at remote mine sites.
- Legacy System Integration:Integrating advanced autonomous control platforms with existing, often decades-old, mine planning software and operational technology infrastructure is a major implementation hurdle causing delays and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Mining Equipment Market |
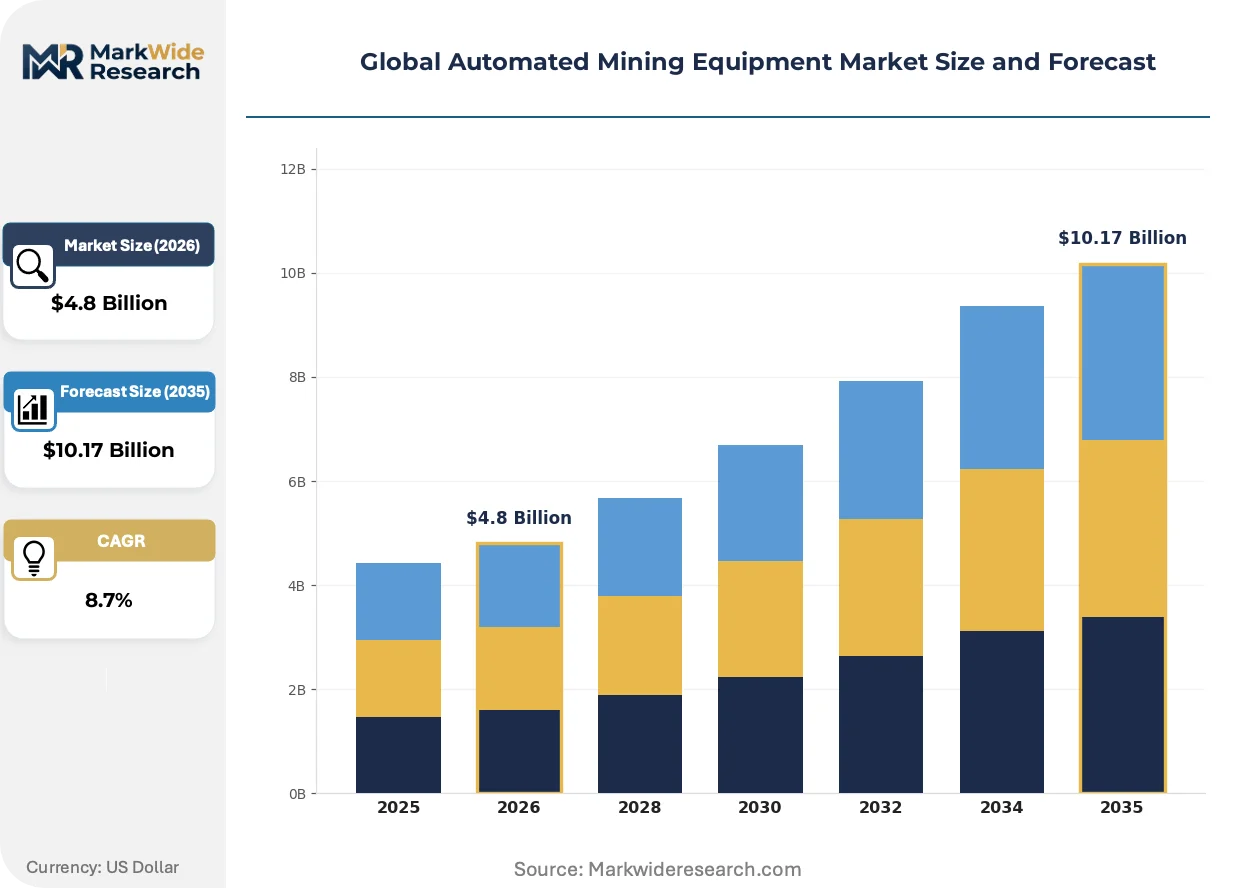
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Drills, Loaders, Haulers, Excavators, Crushers Automation Technology: Guidance Systems, Robotics, Control Systems, Sensors, Machine Learning Application: Surface Mining, Underground Mining, Quarrying, Ore Extraction, Mineral Processing End User: Mining Contractors, Mineral Producers, Equipment Manufacturers, Engineering Services |
| Companies Covered | Caterpillar, Komatsu Ltd., Sandvik AB, Epiroc AB, Hitachi Construction Machinery, Liebherr, Hexagon AB, Rockwell Automation, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Mining Equipment Market Strategic Shifts & Innovations
The competitive focus is shifting from the raw mechanical capability of equipment to the intelligence of the software platforms that control them. Data analytics and machine learning are becoming the primary levers for unlocking productivity and safety gains in mining operations.
Onboard sensor fusion technology integrates data from LiDAR, high-precision GPS, and radar to create a real-time environmental model for the equipment. Mine operators are adopting these systems primarily for large-scale haulage fleets in open-pit environments. This adoption is bifurcating the market into highly automated, large-scale mines and smaller, manually operated sites that cannot achieve the necessary scale for investment.
Development of ISO 17757 and related standards for autonomous machine interoperability is creating a framework for multi-vendor fleets. This standardization forces OEMs to open their proprietary control systems, moving value from locked-in hardware to software and support services. The underground mining segment, which often uses specialized equipment from multiple vendors, is most directly impacted by this push for common communication protocols.
A shift from outright capital equipment purchase to performance-based contracts is gaining traction among major mining houses. This model transfers the risk of equipment uptime and maintenance from the mine operator to the equipment manufacturer, paid on a per-ton-moved basis. This trend is most visible in major iron ore operations in Western Australia, where fleet productivity is the paramount economic driver.
Global Automated Mining Equipment Market Segmentation
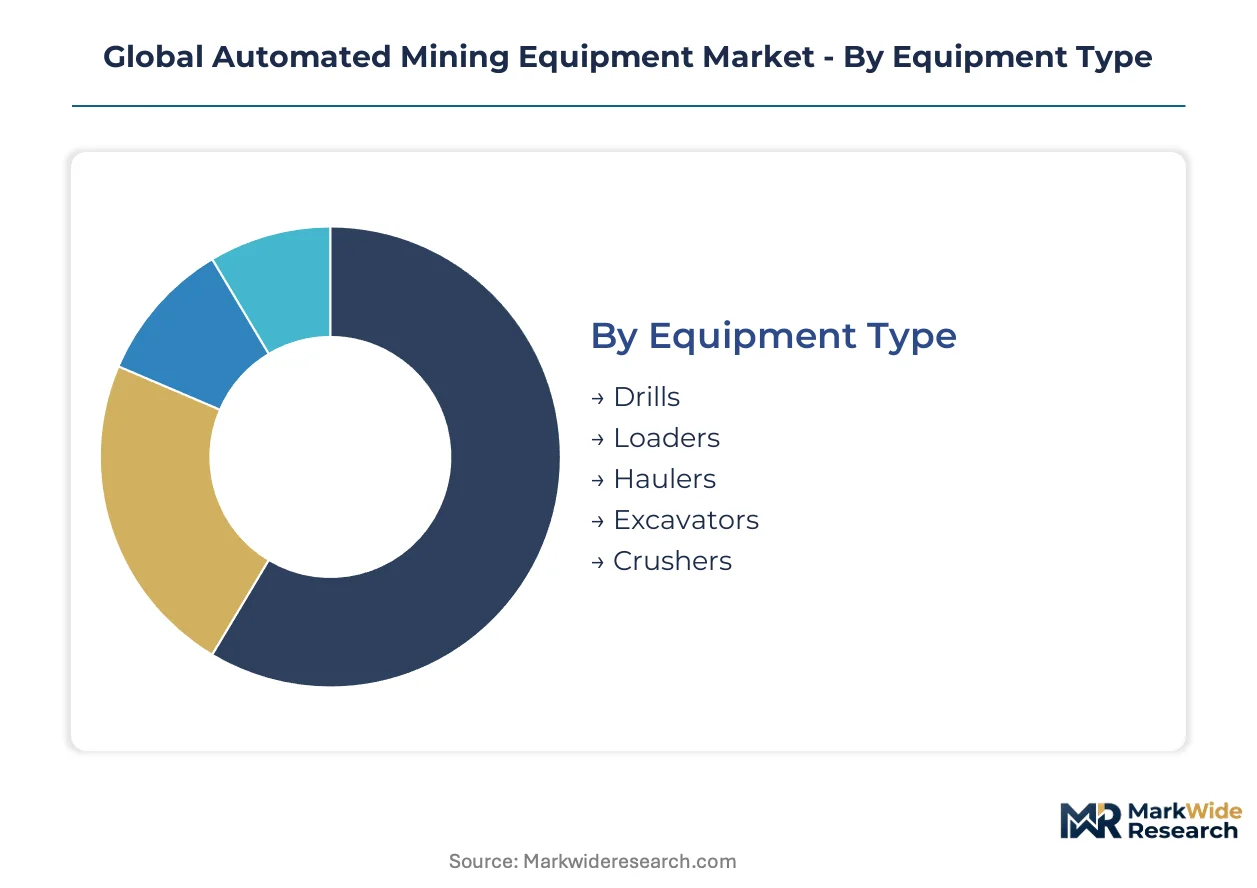
The segmentation of the automated mining equipment market provides a granular view of technology adoption and operational shifts across the industry. Understanding these distinct segments helps mine operators identify optimal investment areas and manufacturers align product development with specific industry needs. This detailed breakdown highlights where automation delivers the most significant impact.
Equipment Type:
The equipment type segment faces significant substitution pressure as manual operations rapidly convert to automated systems to enhance safety and efficiency.
- Haulers:These heavy-duty vehicles transport excavated material from the mine face to processing plants or stockpiles. Their automation is the most mature, driven by clear productivity gains in large-scale open-pit operations like those in Western Australia.
- Drills:Automated drills execute precise drilling patterns for blasting or exploration, often integrating with geological models. Demand concentrates in deep-earth and underground mining for critical minerals, where precision and safety are paramount.
- Loaders:Automated loaders manage the transfer of material onto haulers or into processing facilities, minimizing human exposure to hazardous environments.
- Excavators:These machines dig and move large volumes of earth and ore, with automation focusing on repetitive tasks and hazardous area operation.
- Crushers:Automated crushing equipment reduces ore to smaller sizes for processing, often integrated into a continuous material flow system at the mine site.
Haulers anchor the volume base while Drills gain share at the steepest rate.
Automation Technology:
The diverse automation technologies reflect varying levels of sophistication required for different mining tasks and operational environments.
- Machine Learning:Algorithms analyze vast datasets from equipment operations to predict maintenance needs, optimize routes, and improve operational efficiency. This technology is a key differentiator for OEMs seeking to offer uptime-as-a-service contracts.
- Sensors:Advanced sensors, including LiDAR, radar, and high-precision GPS, provide real-time environmental data and equipment positioning. These are foundational for creating accurate digital twins and enabling precise navigation in hazardous conditions.
- Guidance Systems:These systems enable automated equipment to follow pre-programmed paths and avoid obstacles, crucial for autonomous haulage and drilling.
- Robotics:Robotic systems are deployed for specialized tasks in dangerous or inaccessible areas, reducing human exposure to risk.
- Control Systems:These platforms integrate sensor data and machine learning outputs to execute commands and manage the autonomous operation of mining fleets.
Machine Learning algorithms are expanding most quickly, driven by the demand for real-time optimization.
Application:
The maturity of automation varies significantly across different mining applications, influencing investment patterns and technology deployment.
- Underground Mining:Automation addresses the inherent dangers and operational complexities of deep-earth extraction, particularly for critical minerals like lithium and cobalt. Regulations from agencies like Australia's safety authorities compel operators to remove personnel from high-risk stopes.
- Surface Mining:This application involves large-scale open-pit operations where autonomous haulage fleets are most mature and widely deployed. Major iron ore operations in Western Australia exemplify this segment's scale and productivity gains.
- Quarrying:Automation in quarrying focuses on improving efficiency and safety in extracting construction materials like aggregate and dimension stone.
- Ore Extraction:This segment includes the direct removal of mineral-bearing rock from the earth, leveraging automation for precision and continuous operation.
- Mineral Processing:Automation optimizes the crushing, grinding, and separation stages of mineral beneficiation, improving yield and reducing energy consumption.
Automation in underground mining is climbing the fastest, propelled by stringent safety regulations and critical mineral demand.
End User:
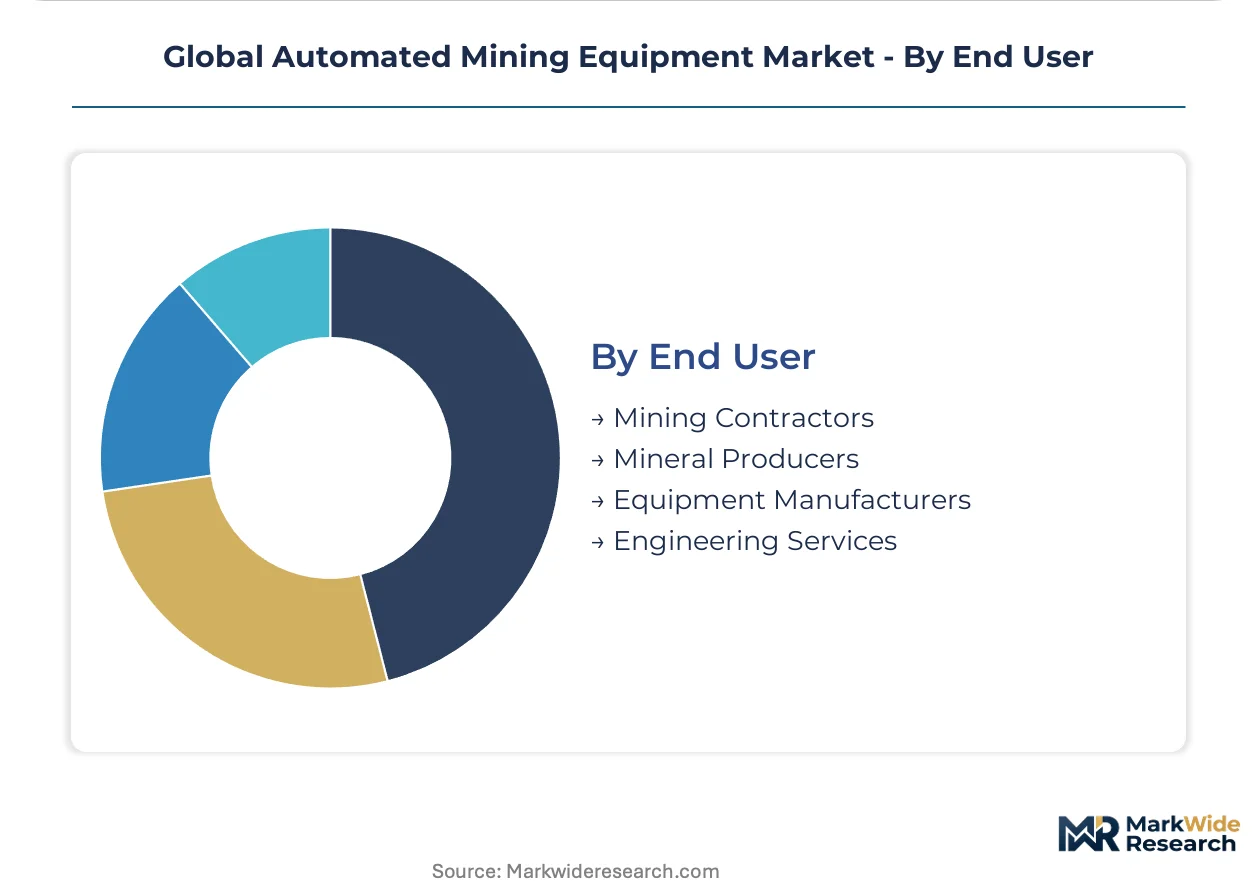
Different end-user types exhibit distinct purchasing behaviors and integration requirements for automated mining solutions.
- Mineral Producers:These are the primary buyers and operators of automated mining equipment, seeking to enhance productivity, safety, and cost efficiency in their operations. Large mineral producers in Chile's Atacama Desert are significant adopters.
- Mining Contractors:Contractors offer specialized mining services to mineral producers, often deploying their own automated fleets and expertise. They drive demand for flexible, scalable autonomous solutions.
- Equipment Manufacturers:OEMs develop and integrate automation technologies into their machinery, often partnering with software and sensor providers.
- Engineering Services:These firms provide consulting, integration, and optimization services for deploying and managing automated mining systems.
Mineral Producers represent the largest customer base, while Engineering Services show strong growth in integration and support roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for automated mining equipment varies significantly across key geographies, driven by distinct mineral endowments and regulatory environments. Some regions prioritize large-scale surface haulage automation, while others focus on precision deep-earth drilling and loading systems.
Australia
Australia's mining sector demands advanced automation for its vast iron ore and lithium extraction operations. Safety mandates from Australia's safety authorities compel operators to remove personnel from high-risk environments. Western Australia serves as a major hub, demonstrating significant scale for large, cost-effective autonomous fleet deployments.
Chile
Chilean mineral producers prioritize automation for large-scale copper extraction in challenging high-altitude and seismic conditions. The country's national mining safety regulations encourage remote operation and advanced monitoring systems. The Atacama Desert provides the geographic concentration necessary for extensive autonomous fleet deployments.
Canada
Canadian mining companies increasingly adopt automation for critical mineral extraction in remote, harsh environments, particularly in underground operations. Provincial mining regulators in Canada issue stringent safety guidelines, accelerating the shift to autonomous equipment. Ontario's Ring of Fire region is a focal point for new deep-earth automated mining projects.
South Africa
South Africa, with its deep-level gold and platinum group metals mines, requires automation to address inherent safety risks and operational complexities. The country's Department of Mineral Resources and Energy regulations push for enhanced worker protection. The historic Witwatersrand Basin sees renewed interest in automation for its remaining deep-earth resources.
Global Automated Mining Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the automated mining equipment market. This tiered structure reflects the capital intensity of heavy machinery manufacturing and the specialized nature of automation software. Equipment OEMs, specialized automation providers, and software integrators represent the primary strategic archetypes. Strategic partnerships between hardware manufacturers and software developers, alongside technology licensing agreements, drive innovation and market penetration.
Within the integrated solutions segment, Caterpillar and Sandvik AB exemplify companies offering end-to-end automation platforms for diverse mining applications. Hexagon AB occupies a position as a critical enabler, providing the software and sensor fusion platforms that underpin fleet-wide autonomy. These entities anchor the market by delivering comprehensive systems that enhance productivity and safety across mine sites globally.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu Ltd. |
| Sandvik AB |
| Epiroc AB |
| Hitachi Construction Machinery |
| Liebherr |
| Hexagon AB |
| Rockwell Automation |
| ABB |
| Others |
Cost & Logistics Intelligence
ISO standards for interoperability gate both equipment supply qualification and price differentiation across the automated mining equipment market. This framework influences which manufacturers can integrate into multi-vendor fleets and impacts the value proposition of compliant solutions.
Pricing Analysis
Performance-based contracts, often structured on a per-ton-moved basis, represent the dominant pricing model for large-scale autonomous fleet deployments. Price differentiation stems from the embedded software intelligence and the comprehensiveness of after-sales service packages. Pricing softness for basic equipment stems from the high initial capital outlay for junior and mid-tier mining operators. These smaller entities exhibit the highest price sensitivity, contrasting with major producers prioritizing long-term operational efficiency.
Supply Chain Analysis
Inventory accumulation and extended lead times pose challenges due to the concentrated supply of critical components. The supply chain for high-performance LiDAR and specialized inertial measurement units centers on a few key suppliers, primarily based in North America, Europe, and East Asia. This concentration introduces a structural risk of single-source vulnerability for equipment OEMs. Downstream distribution typically runs through direct sales channels from major equipment manufacturers to mine operators, supplemented by specialized systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated mining equipment market presents a significant service-attach opportunity, with uptime-as-a-service contracts for predictive maintenance expanding faster than hardware sales.
For Market Incumbents: Compound existing installed bases by integrating advanced AI for predictive maintenance and real-time optimization. Focus R&D on software platforms that enhance interoperability, countering the threat of specialized software-first entrants. Acquire niche technology firms specializing in sensor fusion or robotic applications to broaden product portfolios and deepen vertical integration into critical software layers. Expand service contracts to guarantee operational uptime for large fleet deployments in Western Australia.
For New Entrants and Emerging Players: Differentiate on niche applications like underground automation for the full drill-to-blast cycle, a segment with low current penetration. Target African mining corridors with modular, scalable autonomous systems tailored to local conditions and infrastructure limitations. Provide outcome-based service contracts to mid-tier operators, reducing their initial capital outlay and demonstrating clear productivity gains. Focus go-to-market strategies on specific critical mineral extraction projects requiring precision and safety.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular autonomous systems, presenting opportunities for specialized software and sensor providers. Focus acquisition strategies on companies with proven machine learning algorithms for real-time optimization or advanced guidance systems that enable multi-vendor fleet integration. The long-term viability of this market over the next decade is strong, driven by safety mandates and critical mineral demand. The signal to watch is the adoption rate of ISO standards for autonomous machine interoperability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embeds proprietary software deeper into mine operator workflows, enhancing stickiness for Caterpillar. |
| Strategic Partnership | Combines OEM hardware with specialized AI analytics from Hexagon AB, accelerating deployment. |
| Manufacturing Scale-Up | Addresses demand for autonomous haulers in Western Australia, improving delivery times. |
| Technology Licensing | Expands reach of sensor fusion capabilities to smaller equipment OEMs, fostering ecosystem growth. |
| Product Launch | Introduces new automated drill systems for deep-earth critical mineral extraction, capturing high-value segments. |
Research Approach
Initial hypotheses were tested against primary input from mine operators, equipment engineers, automation software developers, and safety regulators, then refined through iterative analysis. This approach combined in-depth interviews with secondary validation from industry association reports, OEM financial filings, government mining statistics, and academic research. Bottom-up and top-down triangulation ensured data consistency and accuracy across all market parameters.
Variance decomposition informed the analytical framework across the modeling period, segmenting the market by equipment type, automation technology, application, end user, and regional regulatory stringency. Compound annual growth rates were derived from historical trends and projected technology adoption rates, incorporating forecast inputs such as critical mineral demand and skilled operator availability. This comprehensive approach provides robust market projections.
The analysis sits within stated boundaries; outcomes outside rapid shifts in commodity prices or unexpected regulatory changes would require recalibration. Forecasts reflect a carefully considered set of assumptions regarding technology development and market adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Auger Drilling Machine Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
DTH Drill Market
Mining Equipment
Smart Mining Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Borehole Equipment Market