
 High Damping Rubber Bearing (HDRB) Market | 2026-2036
High Damping Rubber Bearing (HDRB) Market Size, Share, and Industry Trends Forecast 2026-2036
High Damping Rubber Bearing (HDRB) Market Insights
JIS B 8621 qualification for seismic isolation devices is reorganizing competitive access across the HDRB supply base. Bridgestone Corporation leverages decades of elastomer compounding expertise to sustain technical leadership in natural rubber formulations for high-strain applications. Nippon Chuzo K.K. anchors domestic project pipelines through integrated design-to-installation capabilities in Japanese civil infrastructure. Zhuzhou Times New Material Technology Co competes on manufacturing scale, operating one of Asia's largest dedicated production lines for laminated elastomeric bearings.
High damping rubber bearings are multi-layer elastomer-steel laminate devices engineered to dissipate seismic energy through hysteretic damping while supporting structural gravity loads, typically achieving equivalent damping ratios of 15-25% at shear strains exceeding 100%. Their primary purpose is to decouple superstructures from ground motion during earthquakes, protecting bridges, buildings, and industrial facilities from inertial damage. Elastomeric bearings dominate current procurement volumes due to proven performance in Japanese and Chinese seismic codes, while pot bearings command premium positioning in heavy-load bridge applications where vertical capacity exceeds 10,000 kN. Natural rubber technology leads the material mix for high-damping formulations, though neoprene compounds are displacing alternatives in coastal and chemically exposed environments where ozone resistance proves critical.
FAA seismic design guidelines for airport facilities, Japan's METI technical standards for base-isolation structures, and China's GB 50011 seismic design code collectively shape product certification pathways and procurement eligibility across the three largest national markets. These frameworks mandate third-party testing, traceable manufacturing records, and installation supervision that elevate barriers for unqualified suppliers. Stakeholders must monitor evolving code harmonization between national standards and ISO 22762 test protocols, as alignment will determine which manufacturers can cross-sell across jurisdictions without redundant qualification investments.
Market Dynamics
Japan's METI building code revisions are compressing supplier qualification timelines while elevating third-party testing requirements, forcing bearing manufacturers to restructure certification pipelines or forfeit eligibility for public infrastructure tenders.
Growth Catalysts
- Seismic code harmonization:China's GB 50011 and Japan's METI standards are converging toward ISO 22762 test protocols, reducing redundant qualification costs for manufacturers serving both markets.
- Urban renewal cycles:Bridge rehabilitation programs in the United States are specifying base-isolation retrofits for aging highway structures crossing active fault zones.
- Natural rubber formulation advances:Modified elastomer compounds achieving 20%+ equivalent damping ratios are expanding addressable shear strain ranges for high-rise applications.
Market Restraints
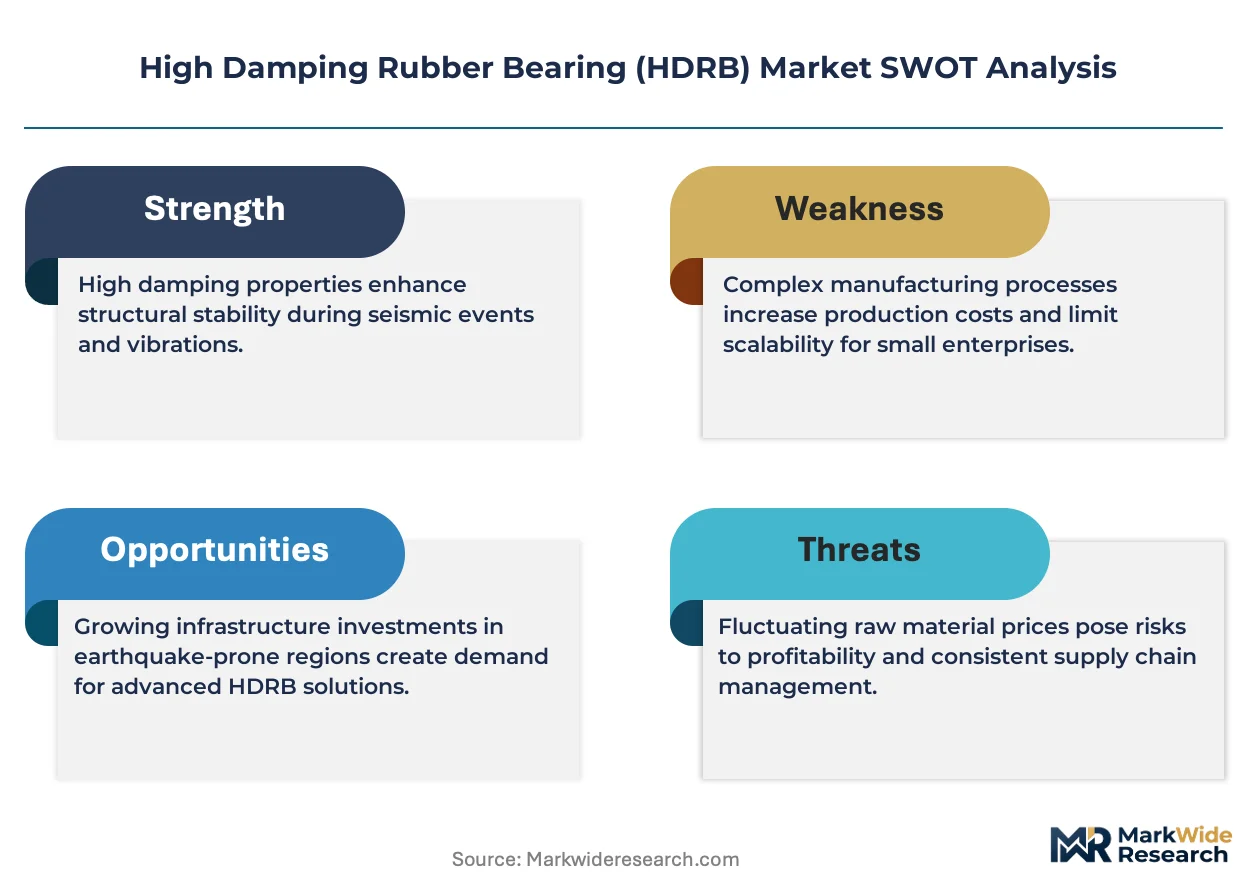
- Natural rubber price volatility:Raw material costs fluctuate with Southeast Asian harvest cycles and climate disruptions, compressing margin predictability for compounders.
- Supplier concentration:JIS B 8621 qualification requirements limit certified production to a handful of Japanese and Chinese facilities, creating bottleneck risk.
- Lead-rubber bearing substitution:Lower-cost seismic isolation devices with comparable vertical load capacity are capturing budget-constrained municipal procurement.
Strategic Opportunities
- India's infrastructure buildout:The country's national seismic code updates are creating first-mover advantage for qualified suppliers entering bridge and metro rail contracts.
- FAA airport facility mandates:Seismic design guidelines for critical airfield structures are opening specification pathways for HDRB systems in runway-adjacent buildings.
- Digital twin integration:Real-time structural health monitoring combined with predictive bearing degradation models is enabling performance-guaranteed service contracts.
Industry Challenges
- Specialized welding certification:Steel laminate fabrication requires ASME-qualified pressure vessel welders, creating recruitment bottlenecks in mature manufacturing regions.
- Multi-jurisdiction traceability:Harmonized ISO 22762 documentation demands conflict with legacy paper-based quality systems at smaller compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Damping Rubber Bearing (HDRB) Market |
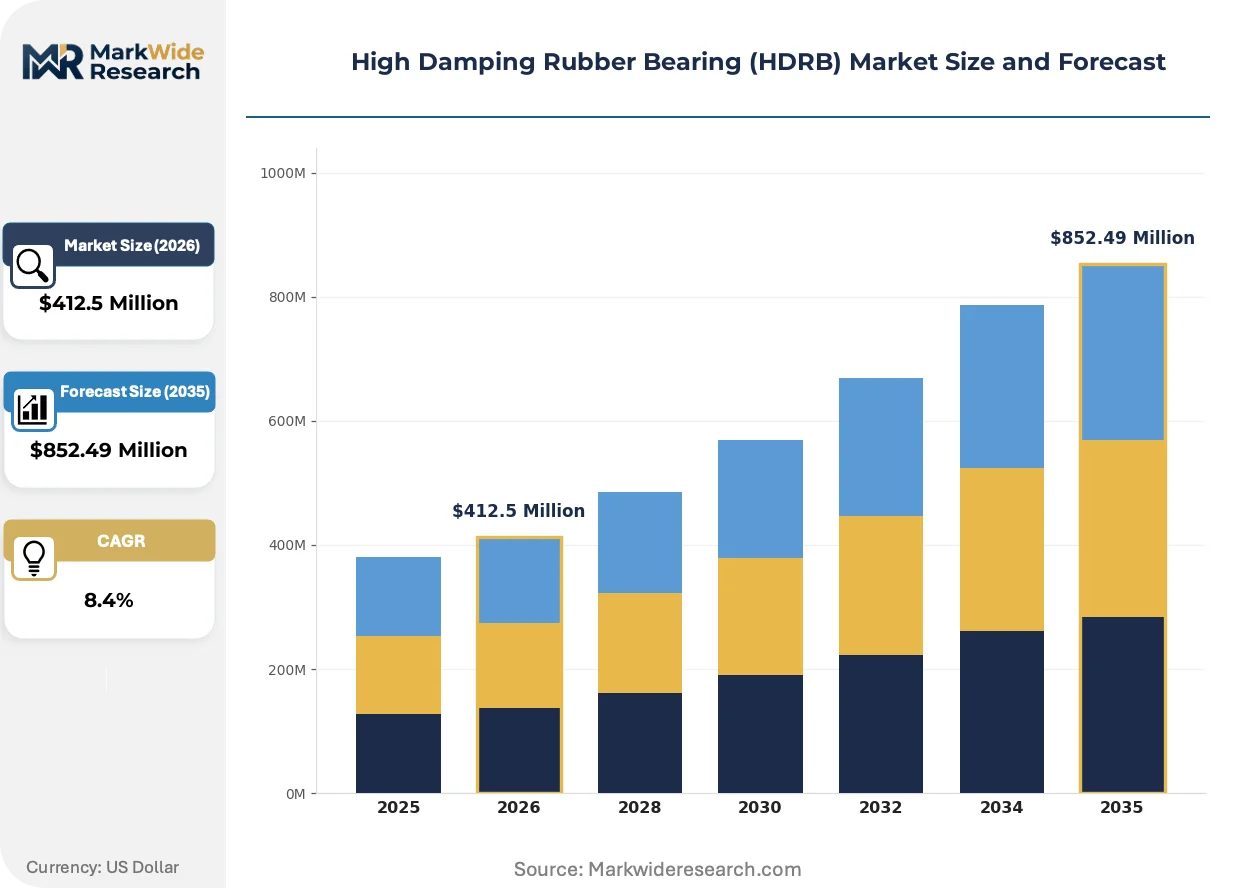
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
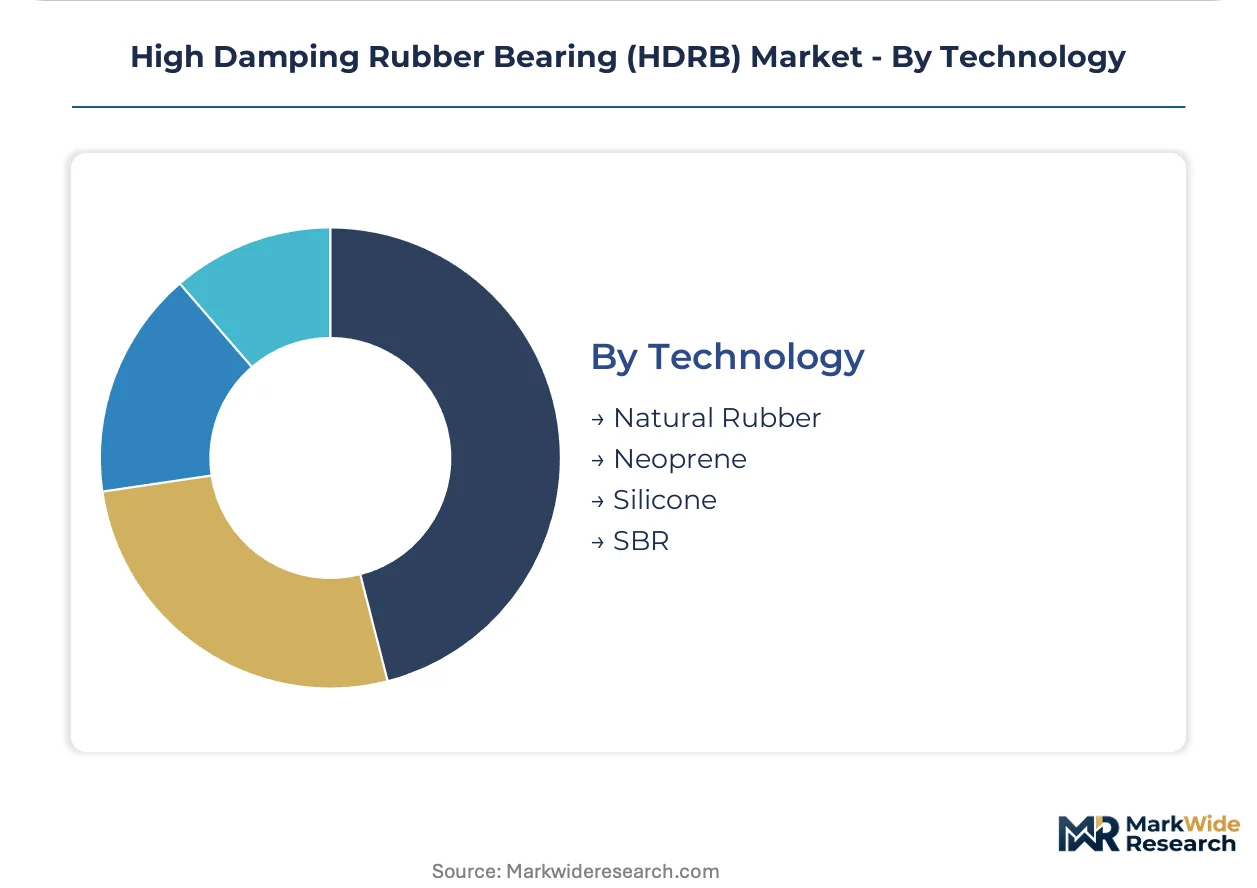
| Segmentation | Product Type: Elastomeric Bearings, Caster Bearings, Pot Bearings, Roller Bearings Application: Seismic Isolation, Bridge Expansion Joints, Building Foundations, Railway Tracks End User: Civil Construction, Transportation, Oil & Gas, Infrastructure Technology: Natural Rubber, Neoprene, Silicone, SBR |
| Companies Covered | Bridgestone Corporation, Nippon Chuzo K.K., UnisonHKR, Kawakin Holdings, Mageba, Zhuzhou Times New Material Technology Co, Hengshui JingTong Rubber Co, Doshin Rubber Product (M) Sdn Bhd, Sumitomo Rubber Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Damping Rubber Bearing (HDRB) Market Trends and Innovations
Material science breakthroughs and regulatory convergence are compressing product development cycles while expanding performance envelopes for elastomeric isolation systems.
Hybrid neoprene-natural rubber compounds are supplanting conventional high-damping formulations in coastal bridge applications. State transportation departments in California and Florida are specifying these blends for marine exposure zones where ozone degradation accelerates conventional elastomer aging. The shift is compressing qualification timelines for pure natural rubber suppliers while rewarding compounders with multi-polymer expertise.
Japan's METI technical standards for base-isolation structures now mandate installation supervision by certified seismic isolation engineers. The requirement is elevating project delivery costs while creating service revenue pools for qualified contractors. Domestic suppliers with integrated design-to-installation capabilities are capturing margin expansion unavailable to component-only manufacturers.
Performance-based procurement specifications are displacing prescriptive product catalogs in Japanese public works tenders. Municipal agencies now specify target isolation periods and maximum floor accelerations rather than bearing model numbers. The shift is compressing supplier differentiation around engineering services while commoditizing basic hardware manufacturing.
High Damping Rubber Bearing (HDRB) Market Segmentation
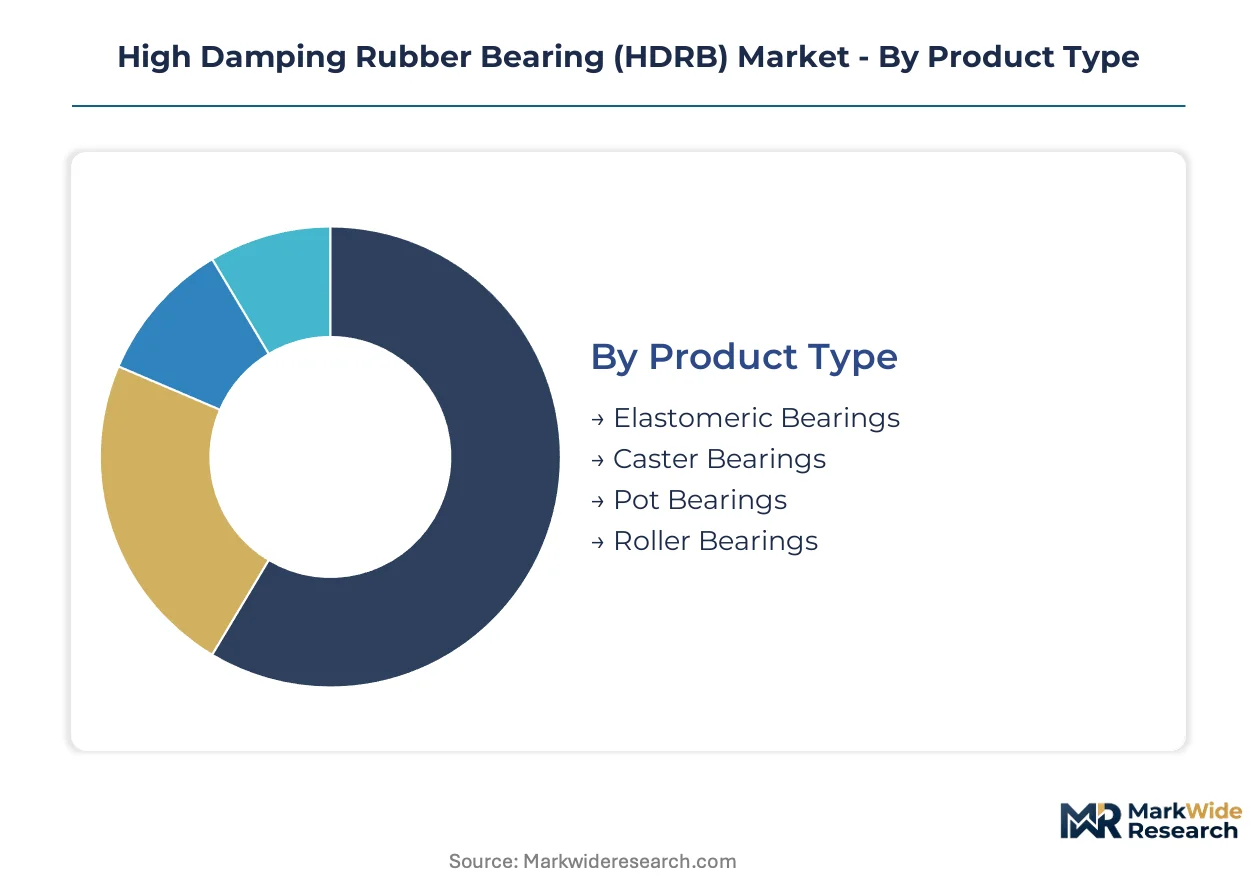
Seismic code divergence across Japan, China, and the United States forces HDRB manufacturers to maintain parallel product portfolios. Each segment carries distinct qualification burdens that reshape competitive access and margin structures.
Product Type:
JIS B 8621 and ISO 22762 test protocols impose divergent damping ratio thresholds that privilege certain bearing architectures over others.
- Elastomeric Bearings:Multi-layer elastomer-steel laminates achieve 15-25% equivalent damping at shear strains exceeding 100%. Japanese civil construction procurement concentrates here due to decades of METI-sanctioned performance data in high-rise base-isolation.
- Pot Bearings:Steel piston-in-cylinder designs accommodate vertical loads beyond 10,000 kN with minimal horizontal displacement. Bridge rehabilitation contracts in California and Florida specify these for heavy-load highway structures crossing active fault zones.
- Caster Bearings:Compact swivel-mounted units enable directional load distribution in industrial machinery isolation.
- Roller Bearings:Cylindrical steel rollers accommodate thermal expansion in long-span bridge decks.
Established volume favors elastomeric configurations; emerging adoption favors pot bearing specifications in heavy-load retrofit programs.
Application:
Cost tier stratification separates premium engineered solutions from commodity expansion joint hardware.
- Seismic Isolation:Base-isolation systems decouple superstructures from ground motion using hysteretic energy dissipation. China's GB 50011 code updates are accelerating municipal building retrofits in Chengdu and Kunming seismic zones.
- Bridge Expansion Joints:HDRB-integrated joints accommodate thermal cycling and seismic displacement simultaneously. State transportation departments in the United States are specifying these for aging interstate structures.
- Building Foundations:Direct foundation mounting for mid-rise commercial and residential structures in Japan's urban corridors.
- Railway Tracks:Vibration isolation for high-speed rail ballast systems requiring maintenance-accessible replacement cycles.
Seismic isolation commands premium pricing; bridge expansion joints scale through volume procurement.
End User:
Customer type determines specification complexity and installation supervision requirements.
- Civil Construction:Public infrastructure tenders dominate, requiring certified seismic isolation engineer oversight per Japan's revised METI standards. Integrated design-to-installation capabilities capture margin unavailable to component suppliers.
- Transportation:Bridge and highway authorities specify performance-based targets—isolation periods and maximum floor accelerations—rather than catalog model numbers.
- Oil & Gas:Petrochemical facility seismic protection with explosion-resistant installation protocols.
- Infrastructure:Airport and port facilities governed by FAA seismic design guidelines for critical airfield structures.
Civil construction anchors procurement volume; transportation authorities are expanding fastest.
Technology:
Material formulation dictates environmental durability and damping performance envelopes.
- Natural Rubber:Modified compounds achieving 20%+ equivalent damping ratios extend addressable shear strain ranges. Southeast Asian supply concentration exposes compounders to harvest cycle volatility.
- Neoprene:Chloroprene-based formulations displace alternatives in coastal exposure zones where ozone resistance proves critical. California and Florida marine bridge specifications are accelerating qualification demand.
- Silicone:Extreme temperature stability for cryogenic industrial applications.
- SBR:Cost-optimized styrene-butadiene blends for non-critical vibration isolation.
Natural rubber maintains volume leadership; neoprene compounds gain share fastest in coastal procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public infrastructure authorities in Japan, China, and the United States account for the dominant share of HDRB procurement, with municipal seismic retrofit programs and bridge rehabilitation cycles driving specification volumes across each market.
Japan
Japan's METI building code revisions mandate base-isolation technology for critical facilities including hospitals and emergency response centers. JIS B 8621 qualification requirements limit certified production to domestic and select Chinese facilities, tightening supplier access. Tokyo and Osaka metropolitan corridors concentrate retrofit demand for mid-rise commercial buildings.
China
China's GB 50011 seismic design code updates are accelerating municipal building retrofits in Chengdu and Kunming seismic zones. The country's dual carbon goals intersect with infrastructure renewal, favoring durable isolation systems with extended service life. Zhuzhou and Changsha manufacturing clusters host Asia's largest dedicated production lines for laminated elastomeric bearings.
United States
Bridge rehabilitation programs in California and Florida specify base-isolation retrofits for aging highway structures crossing active fault zones. FAA seismic design guidelines for airport facilities are opening specification pathways for runway-adjacent buildings. State transportation departments increasingly specify performance-based targets rather than catalog model numbers.
India
India's national seismic code updates are creating first-mover advantage for qualified suppliers entering bridge and metro rail contracts. The Bureau of Indian Standards is developing alignment with ISO 22762 test protocols to reduce redundant qualification barriers. Mumbai and Delhi infrastructure buildouts concentrate early procurement for elevated metro corridors.
Germany
German bridge engineering standards reference EN 1337 structural bearing specifications with emerging convergence toward seismic isolation for Rhine-Ruhr industrial corridor structures. Federal transport infrastructure programs prioritize durability in heavy-load highway applications. Bavaria and Baden-Württemberg engineering clusters supply design expertise for Central European retrofit projects.
High Damping Rubber Bearing (HDRB) Market Competitive Landscape
Player mix skews toward integrated elastomer compounders with captive steel fabrication capabilities and certified installation services. Supplier concentration reflects JIS B 8621 and ISO 22762 qualification barriers that exclude unqualified manufacturers from public tender eligibility. Two strategic archetypes dominate: vertically integrated Japanese suppliers combining material science with design-to-installation services, and scale-focused Chinese manufacturers operating dedicated production lines for laminated bearings. Competitive moves center on qualification pipeline restructuring to meet compressed certification timelines, and geographic expansion into India's emerging infrastructure market.
Among Japanese fabricators, Bridgestone Corporation and Nippon Chuzo K.K. exemplify the integrated service archetype, anchoring domestic project pipelines through capabilities spanning natural rubber formulation to certified installation supervision. Zhuzhou Times New Material Technology Co occupies a position within the scale-driven tier, representing Chinese manufacturing concentration in dedicated elastomeric bearing production. These three entities collectively illustrate how qualification access and production scale define competitive positioning across the three largest national markets.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Nippon Chuzo K.K. |
| UnisonHKR |
| Kawakin Holdings |
| Mageba |
| Zhuzhou Times New Material Technology Co |
| Hengshui JingTong Rubber Co |
| Doshin Rubber Product (M) Sdn Bhd |
| Sumitomo Rubber Industries |
| Others |
Pricing and Supply Chain Analysis
Neoprene displacement of natural rubber in coastal bridge specifications is simultaneously shifting compounder geography toward chloroprene-capable facilities and compressing margin structures for pure natural rubber suppliers locked into Southeast Asian harvest cycles. This substitution dynamic reconfigures procurement economics as state transportation departments in California and Florida rewrite specifications around ozone resistance.
Pricing Analysis
Cost-plus contracts with Singapore SICOM rubber indexation dominate municipal procurement in Japan and China. Price differentiation separates JIS B 8621-certified bearings from uncertified alternatives, with certification tier and installation supervision bundling as primary drivers. Pricing pressure stems from lead-rubber bearing substitution in budget-constrained bridge retrofits. Municipal transportation authorities exhibit highest price sensitivity; critical facility operators in hospital and airport segments show lowest.
Supply Chain Analysis
Thailand and Indonesia anchor natural rubber cultivation, while China and Japan concentrate elastomer compounding and steel laminate fabrication. Raw material sourcing draws from Southeast Asian latex harvests, Japanese specialty steel mills, and chloroprene feedstock from South Korean petrochemical complexes. Single-source vulnerability concentrates in JIS B 8621-certified welding capacity. Distribution runs through project-specific direct contracts with civil engineering contractors rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HDRB market functions as a regulatory-entrenchment defensive moat where JIS B 8621 and ISO 22762 qualification timelines create switching costs that lock qualified suppliers into multi-year public infrastructure pipelines.
For Market Incumbents: Compound qualification pipeline investments to compress JIS B 8621 recertification cycles before METI's revised third-party testing mandates take full effect. Defend against lead-rubber bearing substitution by bundling installation supervision services that budget competitors cannot replicate. Extend backward integration into captive natural rubber compounding to buffer Southeast Asian harvest volatility.
For New Entrants and Emerging Players: Lead with India's Bureau of Indian Standards alignment process as the most penetrable regulatory entry point before ISO 22762 harmonization completes. Target metro rail contracts in Mumbai and Delhi where first-mover advantage remains unclaimed. Pursue joint venture structures with established Japanese installation contractors to bypass certification experience requirements.
For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors compounders with multi-polymer formulation expertise over pure natural rubber specialists. Long-term viability hinges on neoprene-natural rubber hybrid capability as coastal specifications expand. Watch for FAA guideline expansion beyond airport facilities into adjacent critical infrastructure as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Rubber Compounding | Captive supply buffers SICOM index volatility for Japanese and Chinese manufacturers. |
| JIS B 8621 Recertification Acceleration | Compressed timelines under METI revisions lock in qualified supplier status ahead of competitors. |
| India Market Entry Partnership | BIS alignment with ISO 22762 creates first-mover positioning in Mumbai-Delhi infrastructure corridors. |
| Hybrid Neoprene-Natural Rubber Formulation | Multi-polymer expertise captures California and Florida coastal bridge specifications. |
| Installation Supervision Service Bundling | Certified seismic isolation engineer mandates in Japan create recurring revenue pools. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with seismic isolation engineers, civil infrastructure procurement officers, elastomer compounders, and bridge rehabilitation program managers; and secondary validation through JIS B 8621 certification registries, METI technical standard filings, GB 50011 code documentation, and customs trade records for laminated bearing imports. Bottom-up project pipeline tracking across Japanese prefectures and Chinese provincial transportation bureaus triangulated against top-down elastomer consumption estimates.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product architecture, application severity tier, material formulation technology, and end-user procurement complexity. CAGRs derived from elasticity-adjusted infrastructure spend correlations with seismic code adoption timelines. Forecast inputs incorporated natural rubber harvest cycle patterns, METI certification queue lengths, and state transportation department retrofit program announcements.
The analysis sits within stated boundaries; outcomes outside sustained seismic code enforcement, stable natural rubber supply, and continued infrastructure renewal funding would require recalibration. Forecasts reflect documented assumptions regarding qualification timeline compression and hybrid material adoption curves. Recalibration cycles align with material shifts in METI regulatory updates and Bureau of Indian Standards harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Europe Facade Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Europe Bridge Bearings Market