
 Self-Levelling Concrete Market | 2026-2036
Self-Levelling Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Levelling Concrete Market Analysis
Commercial flooring is consolidating as the dominant end-use vertical, displacing residential applications in volume share across major construction corridors. Sika AG leverages its polymer-modified technology leadership to anchor premium specification channels in European logistics hubs. Ardex Group competes through specialized distribution networks that control contractor-grade product access in North American metropolitan markets. Mapei S.p.A. sustains manufacturing scale advantages across Mediterranean and Middle Eastern project corridors.
Self-levelling concrete comprises a fluid, pumpable cementitious or calcium sulfate-based formulation designed to achieve flatness tolerances of FF 35 or higher without mechanical screeding, primarily serving as an underlayment for finished floor coverings. Polymer-modified systems dominate specification-driven commercial segments where adhesion and crack-resistance thresholds exceed standard cement-based performance, while calcium sulfate formulations occupy faster-track renovation timelines where moisture sensitivity constraints permit deployment. Cement-based products retain volume leadership in cost-sensitive residential and repair applications where substrate compatibility and material availability outweigh premium performance requirements.
EMA's Construction Products Regulation and EPA volatile organic compound standards shape formulation chemistry and market access conditions across European and North American supply chains. REACH compliance obligations and evolving ISO 16000 indoor air quality protocols are elevating testing and certification burdens for imported formulations. Stakeholders must monitor regulatory divergence between EU Green Deal embodied-carbon tracking requirements and emerging state-level building performance standards in the United States to anticipate specification preference shifts.
Market Dynamics
Polymer-modified formulation chemistry is restructuring competitive positioning across commercial specification channels, as logistics facility developers demand FF 50+ flatness tolerances that cement-based systems cannot reliably deliver. This technical threshold is concentrating procurement authority among specialized applicator networks capable of certifying installation quality.
Growth Catalysts
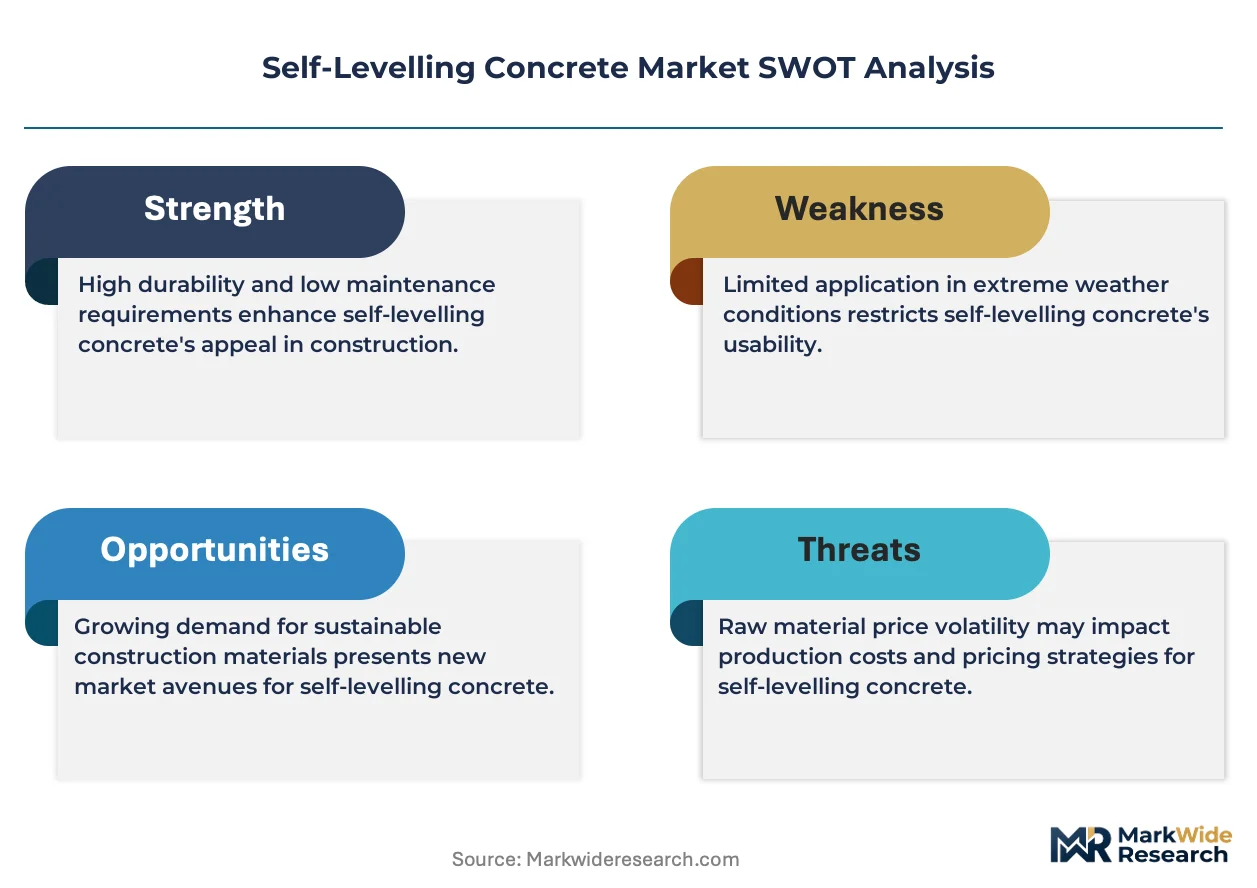
- EU Green Deal embodied-carbon tracking:Low-emission self-levelling systems gain specification preference in German and French warehouse construction as lifecycle assessment data becomes mandatory for public procurement.
- Calcium sulfate fast-track renovation:Retail and hospitality retrofit contractors in Italy and Spain specify rapid-setting formulations to compress project timelines where moisture sensitivity permits substrate deployment.
- Logistics automation flooring requirements:Automated storage and retrieval system installations in China and the United States require ultra-flat underlayments that only high-performance polymer systems can guarantee.
Market Restraints
- Petrochemical input volatility:Acrylic and vinyl acetate monomer costs fluctuate with crude oil indices, compressing margin stability for polymer-modified producers dependent on Asian petrochemical supply.
- Specialized applicator scarcity:Certified installation capacity concentrates in Germany, China, and the United States, creating bottleneck risk for specification growth in secondary construction corridors.
- Moisture sensitivity limitations:Calcium sulfate formulations face deployment restrictions in ground-floor and basement applications where hydrostatic pressure exceeds substrate tolerance thresholds.
Strategic Opportunities
- India logistics infrastructure buildout:Cold chain and e-commerce fulfillment center construction accelerates specification potential for cement-based economy formulations in cost-sensitive regional markets.
- ISO 16000 indoor air quality certification:Emission-tested product lines capture premium positioning in healthcare and educational facility procurement where occupant safety protocols dominate material selection.
- Digital moisture monitoring integration:Sensor-embedded underlayment systems enable predictive maintenance contracts, creating recurring revenue streams beyond material supply.
Industry Challenges
- Applicator certification bottlenecks:Manufacturer-backed training programs struggle to scale qualified installer networks fast enough to match specification velocity in high-growth logistics corridors.
- REACH compliance documentation:Extended substance testing timelines delay new formulation launches in European markets, compressing competitive response windows to regulatory shifts.
- Substrate compatibility verification:Project-specific moisture and alkalinity testing requirements fragment standard product offerings, forcing customization that strains production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Levelling Concrete Market |
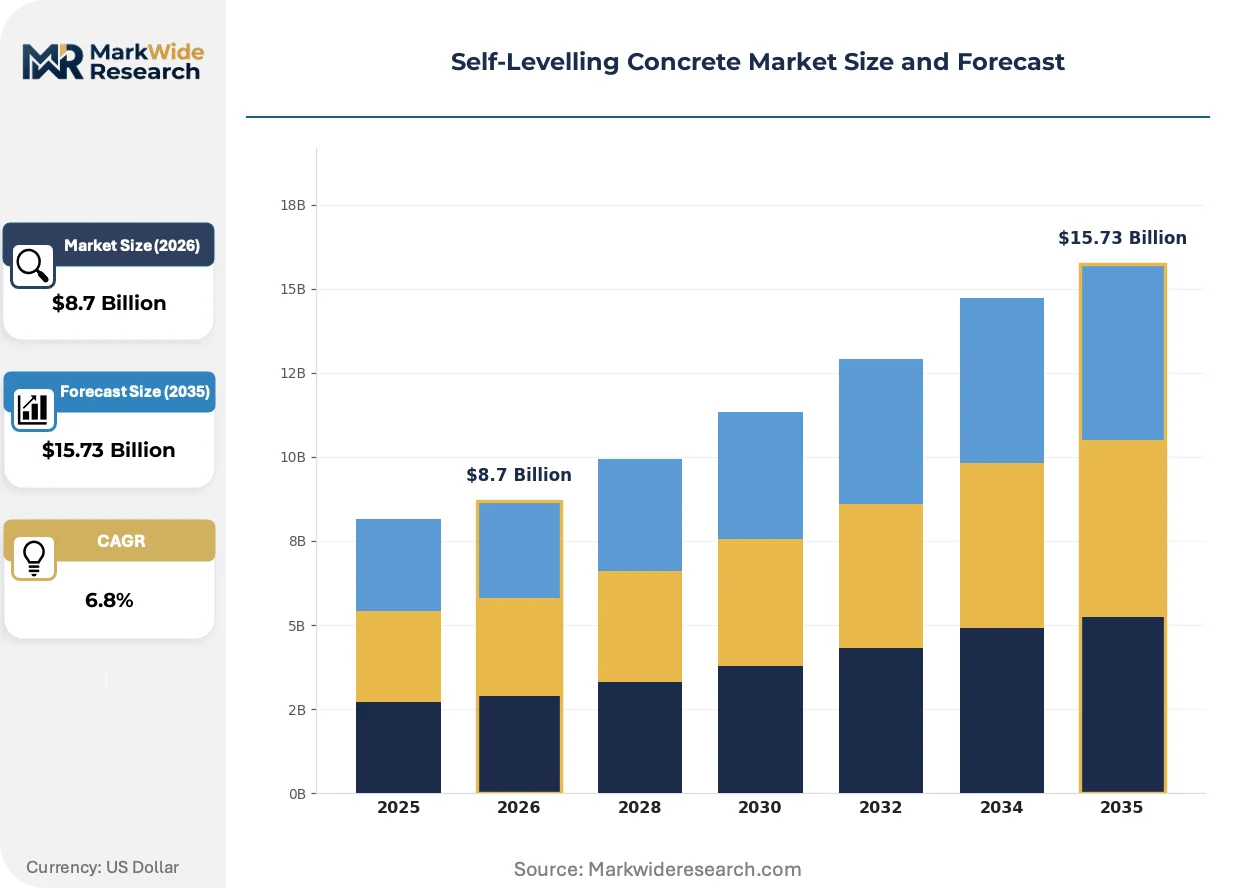
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Modified, Cement-Based, Calcium Sulfate, Others Application: Residential Flooring, Commercial Flooring, Industrial Flooring, Repair Work End User: Contractors, Homeowners, Building Companies, Retailers Distribution Channel: Direct Sales, Online Retail, Building Supply Stores, Distributors |
| Companies Covered | Sika AG, Ardex Group, Mapei S.p.A., Holcim, Saint-Gobain, BASF, USG Corporation, LafargeHolcim, Laticrete International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Levelling Concrete Market Emerging Trajectories
Formulation chemistry convergence with digital specification tools is restructuring how performance guarantees are contracted and verified across commercial flooring projects. This technical-service bundling is redrawing competitive boundaries between material suppliers and installation specialists.
Hybrid polymer-cement composite technology is overtaking conventional acrylic-modified systems in high-load commercial specifications. German logistics developers specify these formulations for automated warehouse floors requiring simultaneous crack resistance and point-load tolerance. The technology is overtaking standard offerings by compressing the trade-off between installation speed and long-term durability that previously segmented product tiers.
EPA volatile organic compound standards and REACH authorization procedures are tightening simultaneously, forcing reformulation of solvent-containing primers and sealers that historically anchored system warranties. North American and European manufacturers face divergent compliance timelines that fragment product portfolio rationalization. Cement-based producers with lower emission profiles capture specification share from polymer-dependent competitors in public sector procurement.
Specification authority is migrating from general contractors to specialized flooring consultants who control performance guarantee documentation. Large-scale warehouse developers in China and the United States now contract directly with applicator networks, disintermediating traditional distribution channels. This concentration of procurement decision-making favors manufacturers with captive certification programs and digital project tracking capabilities.
Self-Levelling Concrete Market Segmentation
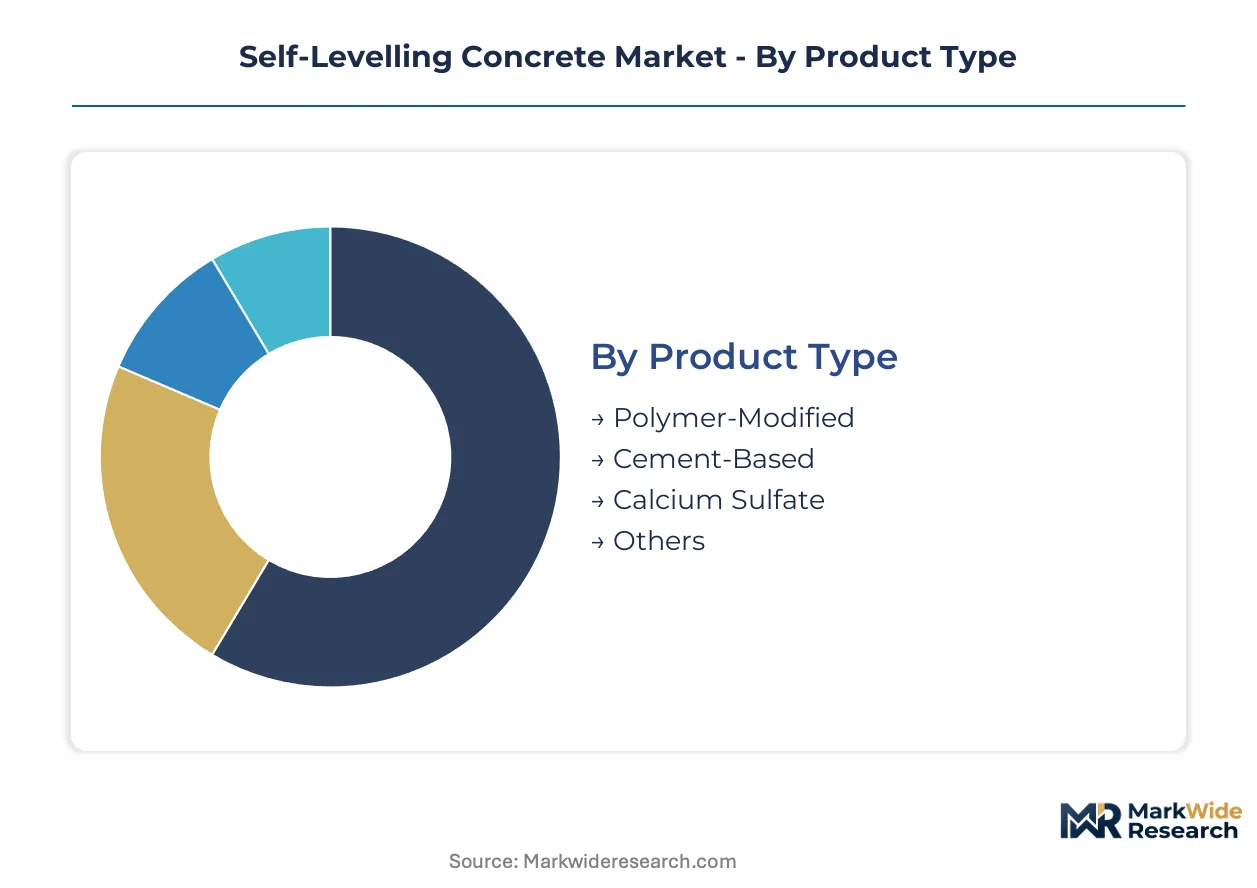
Self-levelling concrete procurement splits across technical performance tiers, project scale, and supply chain access models. Specification authority concentrates differently across each dimension, with polymer-modified systems commanding premium channels while cement-based products flow through volume retail networks.
Product Type:
Customization intensity spans from standardized commodity formulations to engineered polymer systems requiring substrate-specific application protocols.
- Polymer-Modified:Acrylic and vinyl acetate copolymer dispersions enhance adhesion, flexibility, and crack resistance for FF 50+ flatness specifications. German logistics developers and Chinese automated warehouse contractors specify these systems exclusively for high-load commercial floors where point-load tolerance exceeds standard cement performance.
- Cement-Based:Portland cement formulations with standard superplasticizers dominate cost-sensitive residential and repair applications. Indian cold chain construction and US residential renovation contractors favor these products where substrate compatibility and local material availability outweigh premium performance requirements.
- Calcium Sulfate:Rapid-setting gypsum-based systems enable 24-hour return-to-service timelines for retail and hospitality retrofits in Italy and Spain where moisture sensitivity permits substrate deployment.
- Others:Epoxy and polyurethane hybrid formulations serve niche chemical-resistant industrial specifications in pharmaceutical and food processing facilities.
Most installed capacity flows through Cement-Based. Expansion is steepest in Polymer-Modified.
Application:
Project scale and flatness tolerance requirements segment demand across residential renovation, commercial specification, and industrial performance tiers.
- Commercial Flooring:Warehouse, logistics, and retail space construction drives specification for FF 35+ underlayments. US e-commerce fulfillment centers and German distribution hubs anchor volume demand for polymer-modified systems with certified installation networks.
- Industrial Flooring:Manufacturing and automated storage facilities require simultaneous chemical resistance, point-load tolerance, and thermal cycling stability. Chinese automotive plants and US pharmaceutical manufacturing specify hybrid polymer-cement composites for these demanding environments.
- Residential Flooring:Single-family and multi-family renovation projects favor cement-based economy formulations applied by generalist contractors without specialized certification.
- Repair Work:Patch and overlay applications for damaged concrete substrates utilize fast-setting calcium sulfate or cement-based products depending on moisture conditions and timeline constraints.
Volume concentrates in Commercial Flooring. Industrial Flooring is gaining share fastest.
End User:
Technical capability and procurement authority determine whether specification flows through certified applicators, direct retail purchase, or institutional procurement departments.
- Contractors:Specialized flooring applicators control premium commercial and industrial specifications through manufacturer-backed certification programs. German and US applicator networks increasingly contract directly with warehouse developers, bypassing traditional distribution.
- Building Companies:Large construction firms with in-house flooring divisions standardize on specific product lines across multi-site logistics portfolios, creating volume procurement leverage.
- Homeowners:DIY renovation demand flows through retail building supply channels for pre-mixed cement-based products with simplified application instructions.
- Retailers:Commercial property managers specify rapid-setting formulations for tenant turnover minimization in shopping centers and hospitality properties.
Contractors capture the largest volume share. Building Companies are expanding procurement authority most quickly.
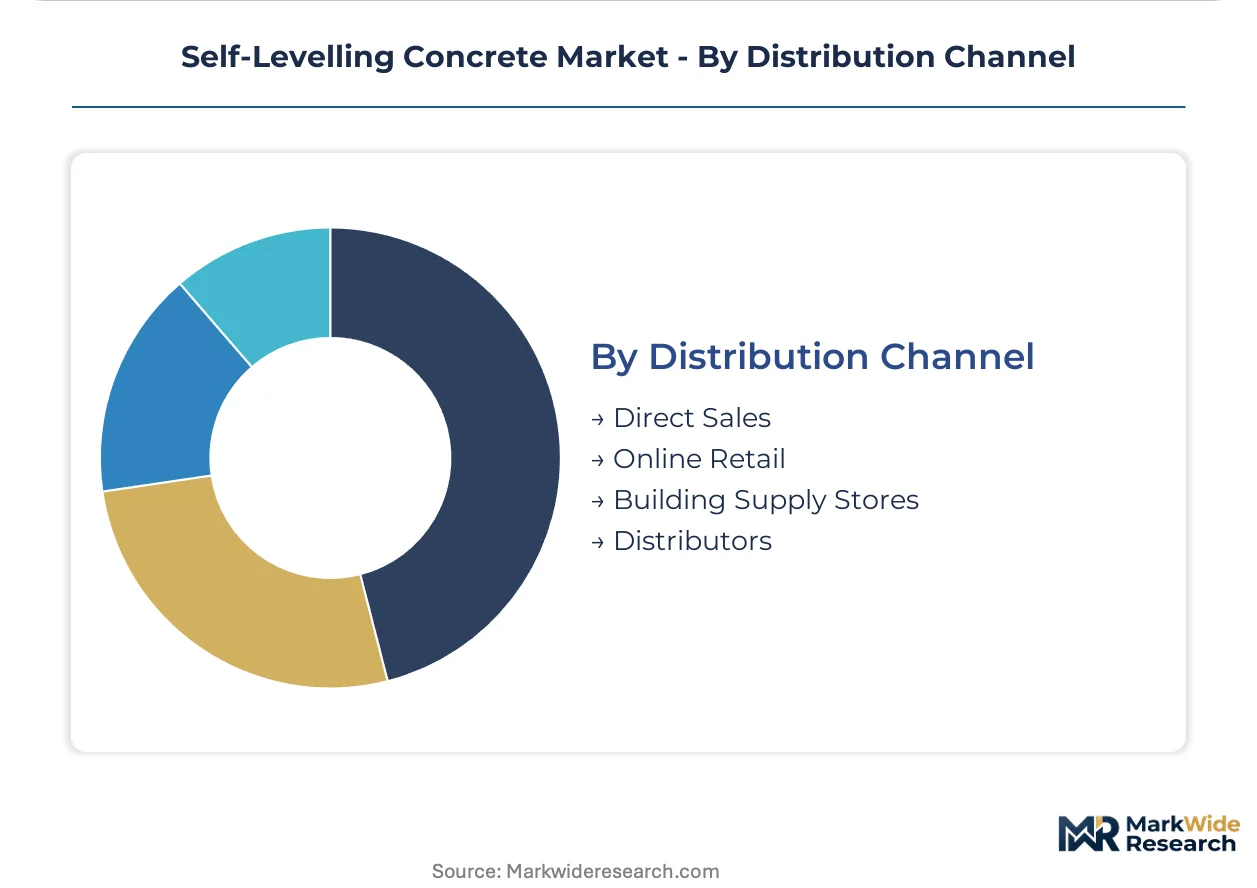
Distribution Channel:
Channel selection reflects specification complexity, with performance-guaranteed systems requiring technical service bundling that commodity products do not.
- Distributors:Regional building material distributors control contractor-grade product access in North American metropolitan markets, maintaining inventory positions for cement-based and standard polymer formulations.
- Direct Sales:Manufacturers engage warehouse developers and large construction firms directly for polymer-modified system specifications, embedding installation certification and project tracking services.
- Building Supply Stores:Retail chains serve residential renovation and small commercial repair demand with bagged cement-based products and limited technical support.
- Online Retail:E-commerce platforms capture DIY homeowner demand and small contractor replenishment orders for standardized formulations with established application protocols.
Distributors handle the greatest volume throughput. Direct Sales channels are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics corridors anchor specification velocity for polymer-modified self-levelling systems. Warehouse developers in Leipzig-Halle and Ruhr industrial clusters demand FF 50+ flatness tolerances for automated storage facilities. EU Green Deal embodied-carbon tracking mandates redirect procurement toward low-emission formulations in public infrastructure tenders.
United States
E-commerce fulfillment center construction in Dallas-Fort Worth and Chicago Metro drives polymer-modified specification rates. EPA volatile organic compound standards tighten formulation requirements for solvent-containing primers and sealers. Texas-based applicator networks now contract directly with warehouse developers, bypassing traditional distribution channels.
China
Automated storage and retrieval system installations in Yangtze River Delta logistics hubs require ultra-flat underlayments. National dual carbon goals elevate low-emission material preference in state-backed infrastructure procurement. Shanghai and Suzhou manufacturing clusters concentrate certified installation capacity for high-performance commercial specifications.
India
Cold chain and e-commerce fulfillment center construction accelerates cement-based economy formulation demand. Bureau of Indian Standards certification requirements shape product qualification timelines for imported polymer systems. Maharashtra and Gujarat industrial corridors concentrate regional distribution infrastructure for cost-sensitive project segments.
Italy
Retail and hospitality retrofit contractors in Milan and Rome specify rapid-setting calcium sulfate formulations. REACH authorization procedures delay new formulation launches, compressing competitive response windows. Northern Italian manufacturing clusters sustain specialized production capacity for Mediterranean market supply.
Self-Levelling Concrete Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers balance polymer-modified premium systems against cement-based volume products. The vendor base organizes around three strategic archetypes: integrated building materials conglomerates with captive distribution, specialized flooring chemical producers with certification-backed installation networks, and regional cement processors with cost-optimized commodity formulations. Technology licensing agreements and geographic expansion through distributor acquisition represent the primary competitive vectors reshaping market access.
Among Swiss-integrated building materials specialists, Sika AG exemplifies the polymer-modified technology leadership archetype. Italian chemical producers Mapei S.p.A. occupy positions anchored to Mediterranean and Middle Eastern manufacturing scale. German specialty flooring groups Ardex Group represent the certified applicator network control model in North American metropolitan markets.
| Leading Market Players |
|---|
| Sika AG |
| Ardex Group |
| Mapei S.p.A. |
| Holcim |
| Saint-Gobain |
| BASF |
| USG Corporation |
| LafargeHolcim |
| Laticrete International, Inc. |
| Others |
Supply Flow & Price Mechanics
Acrylic and vinyl acetate monomer costs transmit from Asian petrochemical feedstocks through polymer-modified formulation tiers, compressing margin stability for manufacturers serving German logistics hubs while cement-based producers in India absorb less volatile Portland cement input structures.
Pricing Analysis
Distributor margins in North American metropolitan markets stratify pricing across three performance tiers. Certification-backed polymer-modified systems command premium positioning through Sika AG and Ardex Group channel control, while cement-based economy formulations flow through retail building supply at compressed markups. Price differentiation hinges on FF flatness rating thresholds and ISO 16000 emission certification status. Pricing pressure intensifies in standard polymer tiers as Chinese imports displace European production in Middle Eastern project corridors. Residential renovation contractors exhibit highest price sensitivity, whereas German warehouse developers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's Bureau of Indian Standards certification reshape sourcing patterns for imported polymer systems, forcing European manufacturers to establish local blending capacity in Maharashtra and Gujarat industrial corridors. Manufacturing concentrates in Germany, China, and Italy for polymer-modified systems, while cement-based production feeds from dispersed regional grinding operations. Raw material dependencies center on petrochemical monomers, Portland cement clinker, and synthetic gypsum feedstocks. Single-source vulnerability runs through acrylic dispersion supply from Yangtze River Delta chemical clusters. Distribution runs through specialized applicator networks for premium specifications and regional building material distributors for volume products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal embodied-carbon compliance costs in German public procurement create specification premiums unattainable in Indian cost-sensitive cold chain construction.
For Market Incumbents: Deploy certification program scaling to defend polymer-modified share against emerging Chinese producers with lower emission profiles. Backward integration into synthetic gypsum sourcing mitigates calcium sulfate formulation cost volatility from power-plant flue-gas supply disruptions. Channel control through direct contractor relationships in Dallas-Fort Worth and Chicago Metro logistics corridors offsets distributor margin compression. For New Entrants and Emerging Players: Capture specification share in Indian cement-based economy tiers where Bureau of Indian Standards localization requirements disadvantage imported polymer systems. White-space concentration exists in sensor-embedded underlayment digital service layers where predictive maintenance contracts remain undeveloped. Partner with Maharashtra-based cold chain developers to establish reference installations before national logistics infrastructure buildout accelerates. For Investors and Strategic Acquirers: Consolidation pressure builds where certified applicator network scarcity constrains specification velocity in high-growth logistics corridors. Long-term viability favors manufacturers with hybrid polymer-cement composite technology and captive installation certification programs. Acquisition target archetype: regional cement processors with cost-optimized formulations and undeveloped polymer-modified upgrade pathways. Watch for divergence between EU Green Deal carbon tracking enforcement and state-level US building performance standards as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Certification Program Expansion | Scarce certified installer capacity in China and Germany creates bottleneck risk for specification growth. |
| Backward Integration into Synthetic Gypsum | Captive flue-gas desulfurization supply secures calcium sulfate formulation cost stability against power-plant output volatility. |
| Digital Moisture Monitoring Integration | Sensor-embedded underlayments enable recurring predictive maintenance revenue beyond one-time material supply. |
| REACH Compliance Documentation Investment | Accelerated substance testing timelines compress competitive response windows for European market access. |
| Hybrid Polymer-Cement Composite Development | German logistics developers specify these systems for automated warehouse floors requiring simultaneous crack resistance and point-load tolerance. |
Methodological Framework
Bottom-up commercial flooring specification modeling reconciled against top-down polymer-modified production capacity tracking forms the analytical core of this study. Primary interviews with specialized flooring applicators, logistics facility developers, cement plant operations managers, and building materials procurement directors supplied installation network constraints and specification trend validation. Secondary sources include customs and trade flow data, EU ECHA REACH registration databases, SEC 10-K filings from integrated building materials conglomerates, and national construction output statistics from Germany's Destatis and China's National Bureau of Statistics. Triangulation between demand-side project pipelines and supply-side manufacturing footprints validates volume estimates.
Input-output matrices map formulation chemistry inputs through regional production clusters to end-use application segments across the projection horizon. Segmentation dimensions encompass product type tier, flatness tolerance specification, project scale category, and procurement channel structure. CAGRs derive from regression analysis of historical specification rates against logistics facility construction permits and warehouse automation capital expenditure trends. Industry-specific forecast inputs include EU Green Deal embodied-carbon tracking adoption curves and Indian cold chain infrastructure investment flows.
Petrochemical input cost volatility, regulatory authorization timeline delays, and substrate compatibility testing fragmentation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding certification program scaling rates and logistics automation flooring specification thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Philippines Roofing Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
UK Facade Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Structural Steel Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Philippines Structural Insulated Panels Market