
 High Strength Concrete Market | 2026-2036
High Strength Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
High Strength Concrete Market Outlook
Buyer concentration among infrastructure developers and large construction companies is expanding as public procurement frameworks consolidate award volumes toward fewer qualified contractors. CEMEX S.A.B. de C.V. leverages its integrated quarry-to-project network across Latin America and the southern United States to secure long-term supply agreements. Heidelberg Materials anchors European demand through its specialized cement plants serving bridge and tunnel specifications. Sika AG differentiates via its additive and admixture portfolio that enables producers to hit compressive strength targets above 80 MPa without proportionate cost escalation.
High strength concrete refers to Portland cement-based formulations engineered to achieve compressive strengths exceeding 41 MPa, typically through reduced water-cement ratios, silica fume or fly ash incorporation, and precise aggregate grading. Its primary purpose is to enable slender structural sections, longer spans, and reduced material volumes in load-bearing elements where dead weight constraints govern design. Ready-mix concrete dominates volume flows but carries thinner margins due to commoditization and transport radius limitations; ultra-high performance concrete occupies a premium niche where project-specific engineering justifies substantially higher per-cubic-meter pricing. Self-compacting concrete is gaining share in densely reinforced high-rise cores where vibration access is impractical.
ASTM C94 governs ready-mix quality in the United States while EN 206 in the European Union sets performance classes and exposure categories that directly specify minimum strength grades for structural applications. The EPA and state-level air quality districts in California enforce emissions caps on cement kilns that elevate production costs for conventional high-strength binders and incentivize clinker substitution. Stakeholders must monitor how tightening embodied carbon regulations in multiple jurisdictions reshape material specifications and supplier qualification criteria.
Market Dynamics
Embodied carbon regulations across multiple jurisdictions are compressing clinker content in high-strength formulations while simultaneously demanding higher performance thresholds, forcing producers to reformulate binders without sacrificing compressive targets.
Growth Catalysts
- EU Green Deal compliance mandates:European infrastructure tenders now require Environmental Product Declarations with verified carbon footprints, accelerating adoption of low-clinker ultra-high performance concrete for bridge decks and tunnel linings.
- Yangtze River Delta megaproject clustering:State-backed transit and commercial tower developments in Shanghai, Nanjing, and Hangzhou concentrate demand for ready-mix grades exceeding 60 MPa.
- Silica fume densification technology:Advanced pozzolanic processing enables water-cement ratios below 0.30 without excessive superplasticizer dosages, unlocking slender column designs in seismic zones.
Market Restraints
- Petroleum-derived superplasticizer cost volatility:Polycarboxylate ether feedstock prices track naphtha and ethylene markets, compressing margins on high-performance mixes where admixture dosages triple standard formulations.
- Specialized silica fume supply concentration:Ferrosilicon smelter byproduct availability clusters in Norway, Iceland, and China's Sichuan province, exposing formulators to logistics disruptions and currency fluctuations.
- EN 206 exposure class XXC4 limitation:European marine splash zone specifications cap cement replacement rates, preventing full clinker substitution in coastal high-rise foundations.
Strategic Opportunities
- Calcined clay geopolymer convergence:Metakaolin-limestone calcined clay blends paired with alkali-activated binders open formulation space for sub-300 kg CO2 per cubic meter structural concrete.
- India's National Infrastructure Pipeline:Dedicated freight corridors and Mumbai-Delhi industrial corridors generate concentrated demand for precast high-strength segments with 28-day targets above 50 MPa.
- Performance-based contractor prequalification:Owner-operator frameworks in Germany and France reward documented durability modeling with multi-year framework agreements, displacing spot-market bidding.
Industry Challenges
- Thermal control modeling expertise gap:Mass pour specifications exceeding 80 MPa generate internal heat spikes that crack sections; few contractors possess in-house temperature-stress simulation capability.
- CE marking timeline compression:Factory Production Control audits for ultra-high performance concrete require 90-day initial assessment cycles that delay project mobilization.
- Legacy batching system integration:Automated moisture probes and real-time rheology sensors retrofit poorly into stationary plants built for conventional slump-based quality control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Strength Concrete Market |
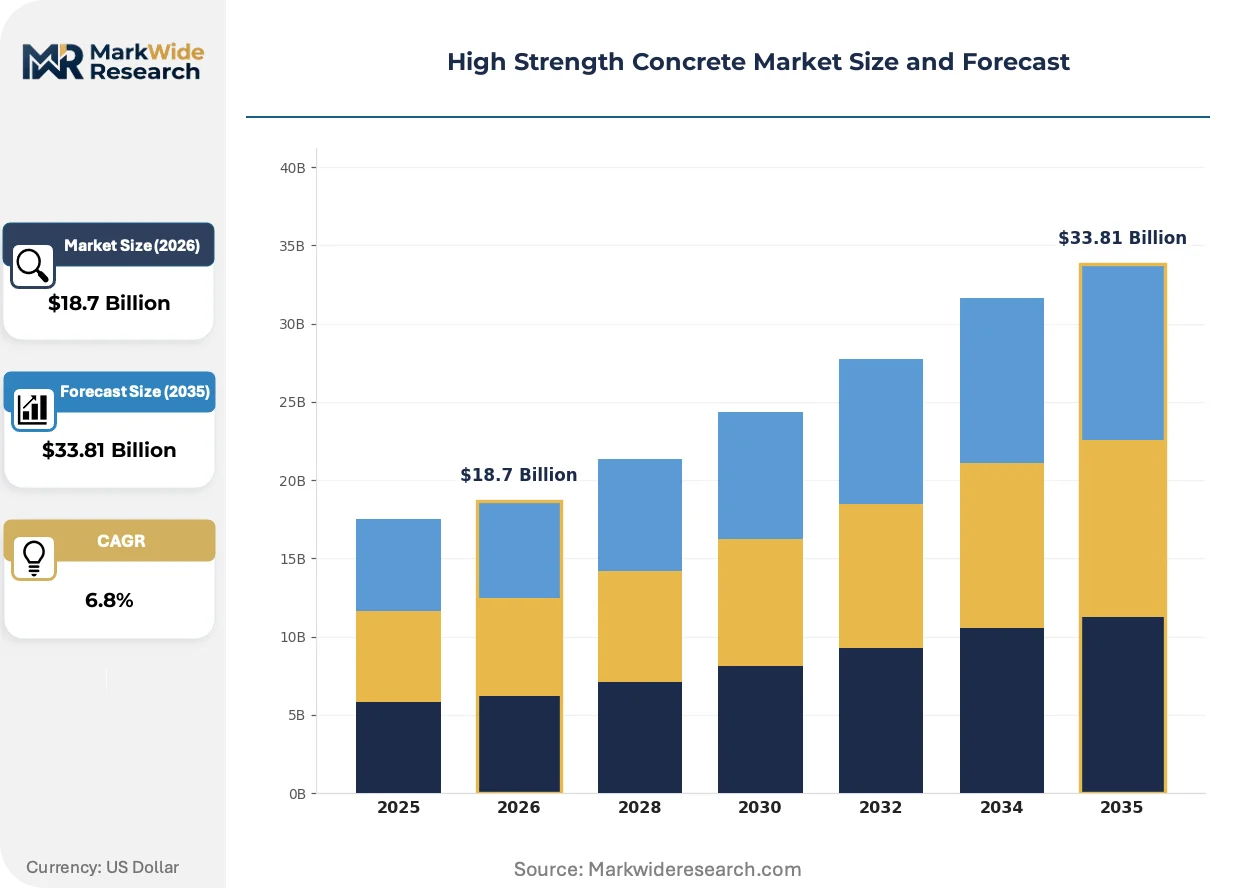
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-High Performance Concrete, Precast Concrete, Ready-Mix Concrete, Self-Compacting Concrete Application: Bridges, High-Rise Buildings, Parking Structures, Industrial Flooring End User: Construction Companies, Infrastructure Developers, Architects, Contractors Technology: 3D Printing, Traditional Casting, Shotcrete, Fiber Reinforcement |
| Companies Covered | CEMEX S.A.B. de C.V., Holcim Ltd, Heidelberg Materials, CRH plc, Sika AG, UltraTech Cement Ltd, BASF SE, LafargeHolcim, ACC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Strength Concrete Market Strategic Shifts
Carbon accounting transparency is rewiring material selection protocols across public infrastructure procurement, while digital fabrication and advanced admixture chemistry compress the performance-cost frontier for ultra-high strength grades.
Electrified curing systems using resistive heating embedded in formwork is electrifying production timelines for precast ultra-high performance elements. Bridge component fabricators in Germany and Japan are deploying this technology to achieve 150 MPa at 24 hours rather than 28 days. The compression of early-strength development cycles is electrifying just-in-time delivery models for segmental construction.
REACH Annex XIV authorization requirements for crystalline silica are forcing reformulation of conventional silica fume blends across European ready-mix operations. Producers are accelerating qualification of amorphous silica alternatives and engineered nanosilica dispersions to maintain EN 206 conformity. Precast specialists serving Dutch and Belgian tunnel markets face the steepest compliance timelines as 2025 sunset dates approach.
Integrated design-build contracts are consolidating concrete specification authority away from general contractors toward engineering firms with in-house materials science capability. Skanska and Strabag framework agreements in Nordic markets now embed durability performance guarantees rather than prescriptive mix designs. This concentration of formulation control is most visible in Denmark's Fehmarn Belt tunnel and Norway's coastal highway renewal programs.
High Strength Concrete Market Segmentation
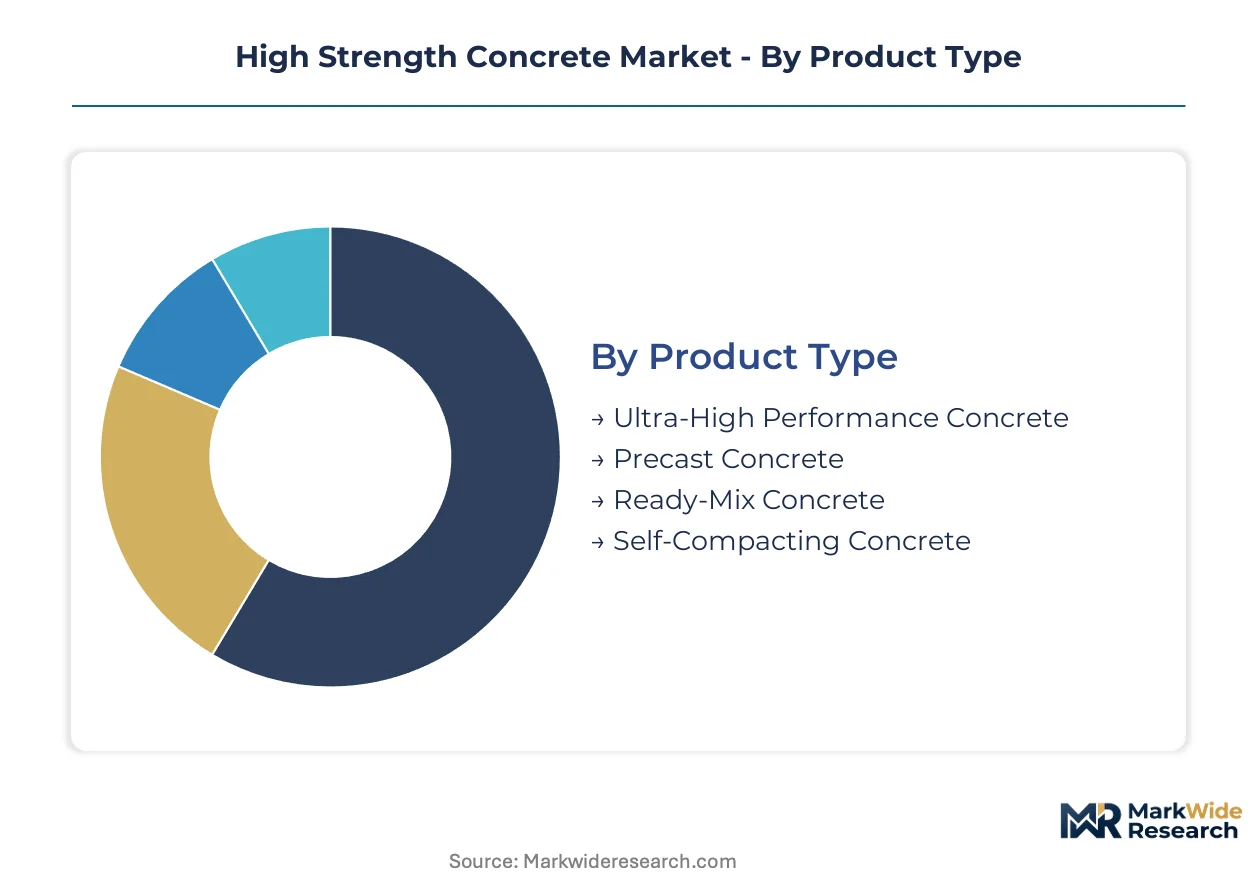
High strength concrete markets fragment across formulation chemistry, placement method, and structural application. Specification authority concentrates with engineering firms and public procurement frameworks that embed distinct certification requirements for each segment.
Product Type:
Ultra-High Performance Concrete and Self-Compacting Concrete carry the heaviest certification burdens under EN 206 exposure classes and ASTM C94 performance verification. Ready-Mix and Precast grades navigate lighter Factory Production Control requirements but face thinner margin pressure from commoditization.
- Ultra-High Performance Concrete:Fiber-reinforced cementitious composite achieving compressive strengths above 150 MPa through optimized particle packing and steel or polymer fiber inclusion. Bridge deck applications in Germany and Japan absorb premium volumes where 24-hour early strength development justifies electrified curing investments. EN 206 XXC4 marine exposure caps limit full clinker substitution in coastal deployments.
- Self-Compacting Concrete:Highly flowable formulation passing through congested reinforcement without mechanical vibration, stabilized by polycarboxylate ether superplasticizers and viscosity-modifying agents. High-rise core construction in Shanghai and Shenzhen drives demand where vibration access is structurally impractical. Thermal control modeling gaps among contractors constrain adoption for mass pours exceeding 80 MPa.
- Ready-Mix Concrete:Site-delivered high-strength grades batched at central plants and transported within 90-minute placement windows.
- Precast Concrete:Factory-cast structural elements cured under controlled conditions for segmental bridge and tunnel lining applications.
Leading the category by volume: Ready-Mix Concrete. Growing fastest: Ultra-High Performance Concrete.
Application:
Structural application segments diverge sharply on performance thresholds and durability modeling requirements. Bridge and high-rise specifications demand compressive targets above 80 MPa with verified carbon footprints under EU Green Deal procurement rules.
- Bridges:Segmental construction and cable-stayed decks requiring ultra-high performance grades for slender girder profiles and extended service life. Yangtze River Delta megaprojects in China concentrate procurement volumes for 60 MPa-plus ready-mix and precast segments. Electrified curing systems compress production timelines for just-in-time delivery models.
- High-Rise Buildings:Vertical load-bearing cores and columns where dead weight reduction enables taller structures with smaller footprints. Mumbai and Delhi industrial corridors in India generate concentrated demand for precast segments with 28-day targets above 50 MPa. Self-compacting formulations gain share in densely reinforced zones.
- Parking Structures:Multi-level decks exposed to chloride-bearing de-icing salts and carbonation cycles.
- Industrial Flooring:Heavy-vehicle load surfaces requiring abrasion resistance and flatness tolerances.
Bridges command the highest per-cubic-meter pricing. Industrial Flooring expands most quickly in logistics hub construction.
End User:
End-user segments stratify by technical capability and procurement authority. Infrastructure developers and large construction companies consolidate award volumes through performance-based prequalification frameworks.
- Infrastructure Developers:State-backed and private owner-operators specifying durability performance guarantees rather than prescriptive mix designs. Germany and France embed multi-year framework agreements rewarding documented service-life modeling. Skanska and Strabag Nordic agreements exemplify this concentration of formulation control.
- Construction Companies:General contractors executing design-build contracts with shifting specification authority toward engineering partners. Integrated design-build models in Denmark and Norway consolidate concrete authority with firms possessing in-house materials science capability.
- Architects:Design professionals influencing aesthetic and structural performance specifications.
- Contractors:Specialized placement firms with expertise in thermal control modeling and mass pour execution.
Infrastructure Developers dominate procurement value. Construction Companies are gaining specification influence fastest through design-build consolidation.
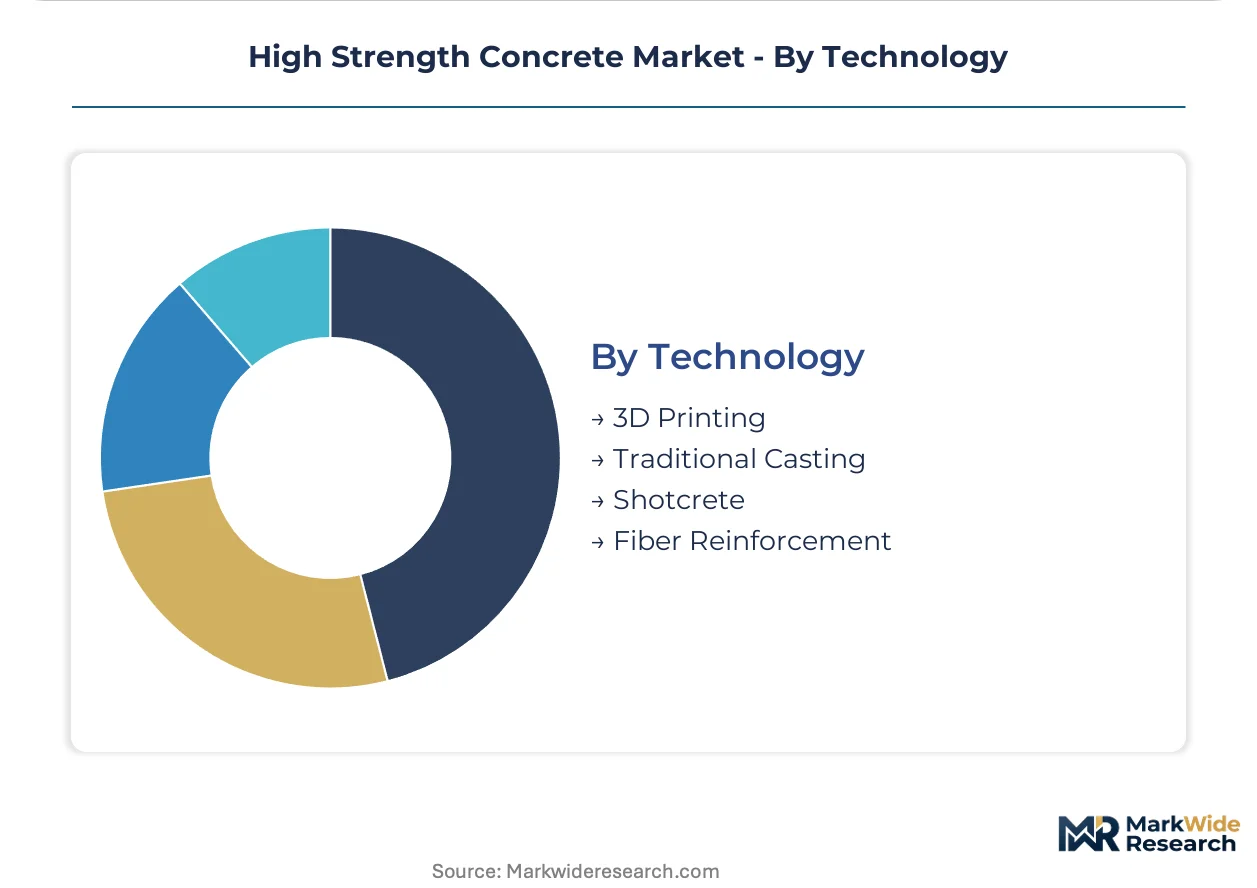
Technology:
Technology segments separate by capital intensity and intellectual property concentration. 3D printing and fiber reinforcement carry emerging patent landscapes while traditional casting and shotcrete rely on established equipment bases.
- 3D Printing:Layered extrusion of high-strength mortar formulations enabling geometrically complex structural elements without formwork. German and Japanese bridge fabricators pilot electrified curing integration with printed ultra-high performance elements. REACH Annex XIV crystalline silica restrictions force reformulation of printable binder systems.
- Fiber Reinforcement:Steel, synthetic, or glass fiber incorporation enhancing tensile capacity and crack control in ultra-high performance matrices. Advanced pozzolanic processing enables water-cement ratios below 0.30 without excessive superplasticizer dosages. Ferrosilicon smelter byproduct concentration in Norway, Iceland, and Sichuan exposes supply chain vulnerabilities.
- Traditional Casting:Conventional formwork-based placement of ready-mix and precast grades.
- Shotcrete:Pneumatically applied high-strength concrete for tunnel linings and slope stabilization.
Traditional Casting retains volume leadership. 3D Printing exhibits the steepest expansion trajectory in precast component fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China where state-backed megaprojects absorb substantial volumes, while EU Green Deal compliance and India's infrastructure pipeline reshape procurement patterns across multiple jurisdictions.
China
Yangtze River Delta megaprojects in Shanghai, Nanjing, and Hangzhou drive concentrated absorption of ready-mix grades exceeding 60 MPa. MEE dual carbon goals and GB standards enforce clinker reduction targets for public infrastructure tenders. Sichuan province anchors silica fume supply from ferrosilicon smelter byproducts, exposing formulators to logistics disruptions.
Germany
Bridge and tunnel specifications under EN 206 XXC4 exposure classes sustain premium demand for ultra-high performance concrete with verified carbon footprints. EU Green Deal procurement rules now mandate Environmental Product Declarations for federal infrastructure awards. Fehmarn Belt tunnel construction exemplifies integrated design-build consolidation of specification authority.
United States
EPA emissions caps on cement kilns elevate production costs for conventional high-strength binders across California and Texas markets. ASTM C94 governs ready-mix quality while state-level air quality districts enforce clinker substitution incentives. Southern state highway departments accelerate procurement of ultra-high performance concrete for bridge deck rehabilitation.
India
Mumbai-Delhi industrial corridors and dedicated freight corridors generate concentrated demand for precast segments with 28-day targets above 50 MPa. BIS standards and the National Infrastructure Pipeline embed performance-based contractor prequalification frameworks. Maharashtra and Gujarat industrial zones concentrate ready-mix batching capacity for high-rise core construction.
Japan
Bridge fabricators deploy electrified curing systems to achieve 150 MPa at 24 hours for segmental construction timelines. METI industrial standards and JIS specifications govern fiber-reinforced ultra-high performance matrices. Kanto and Kansai metropolitan clusters pilot 3D-printed structural elements with embedded resistive heating formwork.
High Strength Concrete Market Competitive Environment
European producers anchor one tier through specialized cement plants and additive portfolios; Latin American and Asian specialists hold supply network advantages in quarry-to-project integration. The market structures around three tiers: integrated multinationals with vertical quarry control, admixture specialists enabling performance thresholds above 80 MPa, and regional batching operators serving transport-constrained radii. Dominant competitive moves include long-term framework agreements displacing spot-market bidding and in-house materials science capability consolidation.
Among Mexico-based integrated producers, CEMEX S.A.B. de C.V. occupies a position exemplifying quarry-to-project network leverage across Latin American and southern United States markets. Heidelberg Materials AG represents the European archetype through specialized cement plant configurations serving bridge and tunnel specifications. Sika AG anchors the admixture specialist tier, enabling producers to achieve compressive strength targets without proportionate cost escalation through polycarboxylate ether and silica fume densification technology portfolios.
| Leading Market Players |
|---|
| CEMEX S.A.B. de C.V. |
| Holcim Ltd |
| Heidelberg Materials |
| CRH plc |
| Sika AG |
| UltraTech Cement Ltd |
| BASF SE |
| LafargeHolcim |
| ACC Limited |
| Others |
Value Chain & Pricing Dynamics
Ultra-high performance concrete's 5-8x premium over ready-mix grades creates a bifurcated market where certification burdens and silica fume supply concentration simultaneously inflate input costs and restrict formulation access to qualified producers. This divergence concentrates pricing power with admixture specialists and integrated quarry operators while commoditized ready-mix segments face margin compression from transport radius constraints and petroleum-derived superplasticizer volatility.
Pricing Analysis
Ready-mix concrete dominates volume flows but carries thinner margins due to transport radius limitations and spot-market bidding, while ultra-high performance concrete commands project-specific premiums where 150 MPa targets justify electrified curing investments. Price differentiation hinges on compressive strength certification tiers and clinker substitution rates under EU Green Deal procurement rules. Pricing pressure stems from polycarboxylate ether feedstock tracking naphtha and ethylene markets, compressing margins on high-performance mixes. Infrastructure developers show lowest price sensitivity where durability guarantees displace prescriptive specifications, while regional batching operators serving transport-constrained radii face acute cost consciousness.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for precast segment delivery to bridge and tunnel sites. Raw material sourcing draws from Norway, Iceland, and Sichuan province for ferrosilicon smelter byproduct silica fume, with petroleum-derived superplasticizers and calcined clay feedstocks as secondary dependencies. Single-source vulnerability in specialized silica fume supply exposes formulators to logistics disruptions and currency fluctuations. Distribution runs through quarry-to-project networks controlled by integrated multinationals and long-term framework agreements displacing spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silica fume supply concentration in three geographic clusters props pricing premiums for ultra-high performance grades, creating a supply-constrained structure where qualified producers capture disproportionate returns. Ferrosilicon smelter byproduct bottlenecks limit rapid capacity expansion regardless of demand signals from Yangtze River Delta megaprojects.
For Market Incumbents:Cement long-term supply agreements with state-backed infrastructure developers in China and India before performance-based prequalification frameworks consolidate award volumes further. Backward integration into ferrosilicon smelter partnerships or calcined clay mining assets mitigates silica fume supply disruption risks from Norwegian and Icelandic logistics chokepoints. Prioritize R&D investment in amorphous silica alternatives ahead of REACH Annex XIV crystalline silica sunset deadlines.
For New Entrants and Emerging Players:Launch via specialized admixture formulation services enabling regional batching operators to hit 80 MPa targets without in-house materials science capability. India's National Infrastructure Pipeline offers the most penetrable white space, where dedicated freight corridors generate concentrated demand for precast segments with 28-day targets above 50 MPa. Target performance-based contractor prequalification frameworks in Germany and France with documented durability modeling as the go-to-market wedge.
For Investors and Strategic Acquirers:Re-rating potential sits with admixture specialists possessing polycarboxylate ether and silica fume densification technology portfolios given accelerating clinker substitution mandates across multiple jurisdictions. Long-term viability favors vertically integrated producers with captive quarry networks and in-house thermal control modeling expertise for mass pour execution. Watch for electrified curing system adoption rates in German and Japanese bridge fabrication as the inflection signal for ultra-high performance concrete demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calcined Clay Mining | Secures low-clinker binder feedstock ahead of EU Green Deal embodied carbon enforcement. |
| Long-term Supply Agreement with Infrastructure Developers | Locks in Yangtze River Delta megaproject volumes before procurement framework consolidation. |
| Electrified Curing System Deployment | Compresses 150 MPa production timelines for German and Japanese segmental bridge construction. |
| Amorphous Silica Alternative Qualification | Maintains EN 206 conformity as REACH Annex XIV crystalline silica restrictions take effect. |
| Performance-Based Contractor Prequalification | Displaces spot-market bidding in Nordic markets through documented durability guarantees. |
Study Parameters
Trade flow databases, cement industry association publications, and regulatory filing repositories formed the secondary backbone, supplemented by primary interviews with ready-mix plant managers, infrastructure procurement officers, admixture R&D directors, and EPC contractors executing bridge and tunnel projects. Bottom-up and top-down triangulation validated volume estimates across formulation chemistry, placement method, and structural application segments.
Bottom-up modeling anchored demand projections while top-down macroeconomic cross-checks verified plausibility across the analysis window. Segmentation dimensions included compressive strength tier, placement technology, end-use application, and regional regulatory cluster. CAGRs were derived from production capacity utilization trends, megaproject pipeline tracking, and clinker substitution rate assumptions under evolving embodied carbon standards.
Petroleum feedstock volatility, ferrosilicon smelter output disruptions, and EN 206 exposure class revisions are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
North America Facade Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
UK Facade Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Structural Steel Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Civil Engineering Market
Structural Engineering
FRP Bridge Market