
 Europe Structural Health Monitoring Market | 2026-2036
Europe Structural Health Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Structural Health Monitoring Market Foresight
A capability gap in fiber optic sensing scale is rotating competitive dynamics across the Europe Structural Health Monitoring Market. HBM leverages its strain measurement heritage to anchor premium positioning in German bridge installations. Fugro N.V. sustains offshore and civil infrastructure dominance through integrated geotechnical and structural monitoring services. Siemens AG competes by extending industrial automation expertise into cloud-based diagnostics platforms for tunnel networks.
Structural health monitoring encompasses the continuous or periodic assessment of civil infrastructure integrity through deployed sensor networks, data acquisition systems, and analytical algorithms that detect anomalies in strain, vibration, displacement, or crack propagation. Fiber optic technology leads European deployments due to electromagnetic immunity and distributed sensing capability along kilometer-scale structures. The bridges application category occupies the largest revenue share as European member states prioritize deferred maintenance on aging motorway and rail crossings. Cloud-based deployment is accelerating fastest among engineering consulting end users seeking remote diagnostics and predictive maintenance dashboards across multi-site portfolios.
The EU Green Deal and F-Gas Regulation shape equipment specifications by restricting certain sensor cooling technologies while manduring lifecycle extension documentation for major infrastructure. ECHA's REACH framework governs material composition in sensor housings and cabling deployed across European construction sites. Germany's KBA and France's ANSN infrastructure guidelines influence national procurement standards for continuous monitoring systems on critical transport links. Stakeholders must weigh regulatory compliance timelines against the accelerating shift toward AI-driven anomaly detection in hybrid deployment architectures.
Market Dynamics
The EU Green Deal's lifecycle extension mandates are compressing procurement timelines for continuous monitoring systems across European transport infrastructure. Bridge operators now face binding documentation requirements that favor fiber optic and wireless sensor networks over periodic manual inspection regimes.
Growth Catalysts
- EU Green Deal infrastructure mandates:The regulation requires lifecycle extension documentation for major assets, forcing transport authorities to deploy continuous monitoring on critical spans.
- Germany's KBA protocols:Federal highway administration guidelines now mandate continuous structural assessment on critical bridge inventory, creating immediate procurement pull.
- Fiber optic immunity advantages:Electromagnetic immunity and distributed kilometer-scale sensing capability position this technology ahead of electrical alternatives for rail and motorway crossings.
Market Restraints
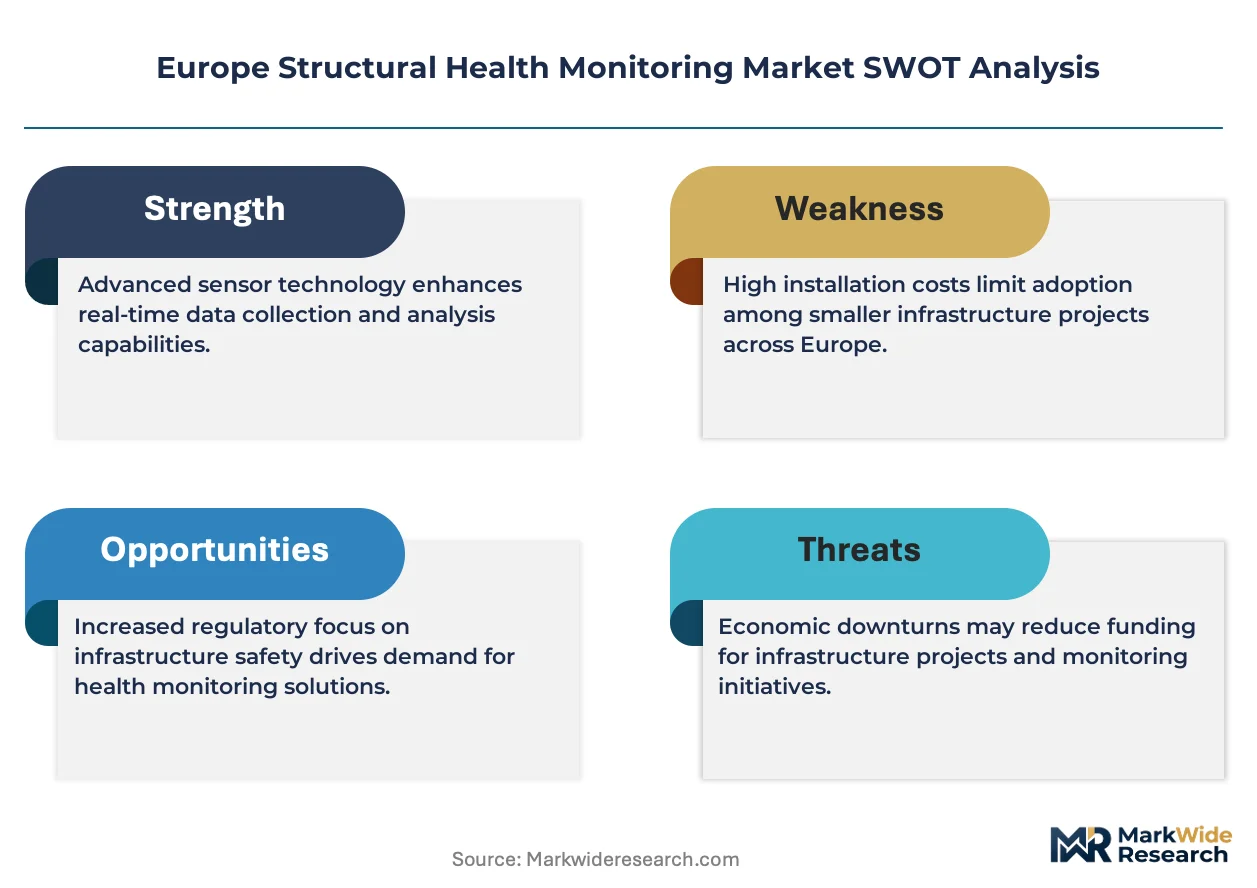
- ECHA REACH material compliance:Sensor housing and cabling composition restrictions add certification delays and limit supplier pools for European deployments.
- Specialized installation labor scarcity:Fiber optic splicing and calibration expertise concentrates in German and French engineering consultancies, constraining deployment velocity elsewhere.
- Capital intensity of cloud infrastructure:Real-time diagnostic platforms require sustained investment in edge computing and secure data architecture that mid-sized operators struggle to fund.
Strategic Opportunities
- Eastern European bridge inventory:Poland, Romania, and Czech Republic maintain extensive aging motorway crossings with minimal monitoring penetration, presenting greenfield deployment potential.
- AI-driven anomaly detection convergence:Machine learning algorithms fused with distributed fiber sensing enable predictive maintenance models that command premium pricing from rail operators.
- EU F-Gas Regulation sensor cooling restrictions:The policy accelerates demand for passive and thermoelectric cooling architectures in monitoring equipment, favoring suppliers with compliant thermal designs.
Industry Challenges
- Integration complexity with legacy SCADA:Bridge operators operate decades-old control systems that resist seamless data handoff to modern cloud-based diagnostic platforms.
- Certification timeline compression:CE marking and national transport authority approvals for new sensor form factors now lag procurement deadlines set by infrastructure maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Structural Health Monitoring Market |
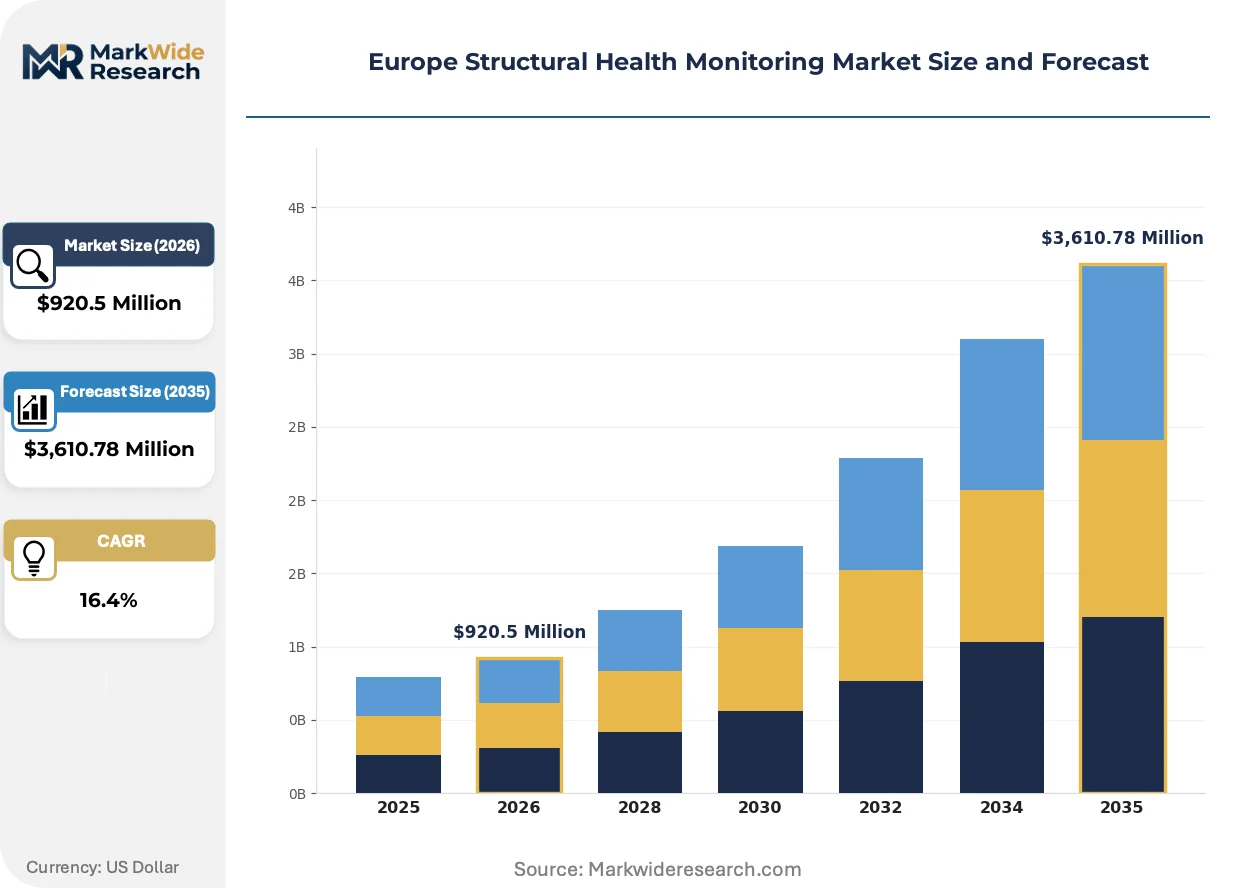
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $3,610.78 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vibration, Acoustic Emission, Thermography, Fiber Optic Application: Bridges, Buildings, Dams, Tunnels End User: Construction Firms, Government Agencies, Research Institutions, Engineering Consulting Deployment: On-premise, Cloud-based, Hybrid, Portable |
| Companies Covered | HBM (Hottinger Bruel and Kjaer), Fugro N.V., Campbell Scientific, GEOKON, SIXENSE Systems, Structural Monitoring Systems PLC, COWI A/S, OSMOS Group SA, Siemens AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Structural Health Monitoring Market Shifts & Advancements
Sensor fusion architectures are displacing single-technology deployments across European structural monitoring. The convergence of fiber optic strain sensing with wireless accelerometer networks enables redundant anomaly detection that reduces false-positive rates for critical infrastructure operators.
Distributed acoustic sensing using fiber optic cables is fragmenting the vibration monitoring segment. German rail operators now deploy kilometer-length fiber as both communication backbone and dynamic strain sensor. This convergence compresses revenue for standalone accelerometer suppliers while expanding addressable scope for integrated platform vendors.
The EU AI Act's risk classification framework is reshaping procurement specifications for automated diagnostic systems. Tunnel and bridge operators must now document algorithmic transparency and human oversight protocols for safety-critical anomaly detection. French infrastructure managers are revising tender documents to require AI system conformity assessments before deployment.
Engineering consultancies are unbundling hardware supply from diagnostic service contracts. Asset owners in the Netherlands and Belgium now lease sensor networks with bundled analytics subscriptions rather than capitalizing equipment purchases. This shift compresses upfront project values while extending revenue visibility for platform vendors with captive monitoring capabilities.
Europe Structural Health Monitoring Market Segmentation
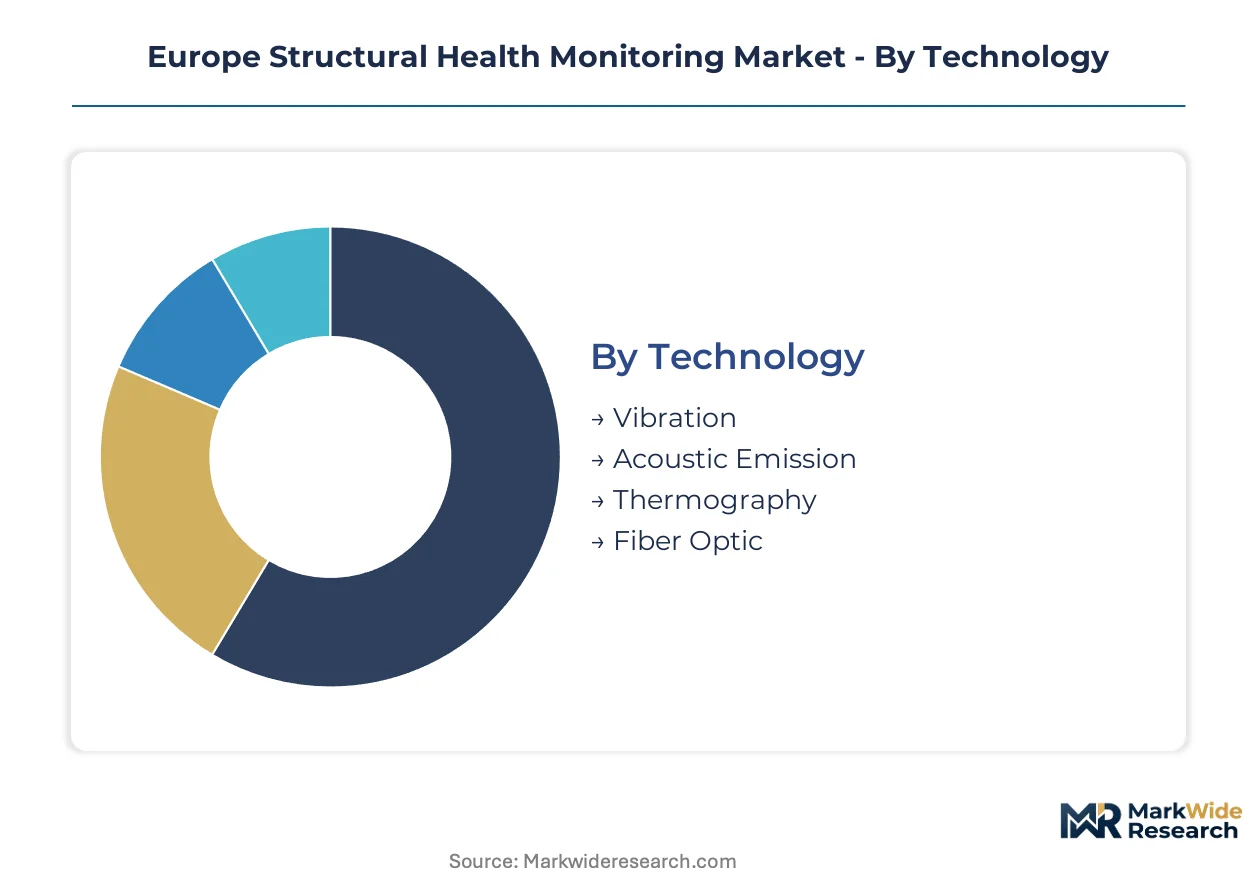
Structural health monitoring deployments vary sharply by infrastructure type and procurement authority. Technology selection, deployment architecture, and end-user sophistication create distinct margin pools across the European market.
Technology:
Fiber optic systems command premium pricing due to distributed sensing capability and electromagnetic immunity requirements on rail corridors. Vibration and acoustic emission sensors compete on installation simplicity for smaller-scale building applications.
- Fiber Optic:Distributed strain and temperature sensing along kilometer-scale structures enables continuous crack detection without electrical interference. German rail operators and French motorway authorities specify this technology for critical spans under EU Green Deal lifecycle documentation mandates.
- Vibration:Accelerometer networks measure dynamic response to traffic and environmental loading. Demand concentrates in Dutch and Belgian building monitoring where wireless retrofitting avoids structural modification costs.
- Acoustic Emission:Detects stress-wave emissions from crack propagation in concrete and steel. Italian dam operators deploy this for early-stage damage identification in alpine reservoir structures.
- Thermography:Infrared imaging identifies delamination and moisture ingress in bridge decks. Polish infrastructure agencies adopt this for periodic assessment of aging motorway crossings.
The dominant share belongs to Fiber Optic, while Vibration is closing the gap fastest through wireless retrofit adoption.
Application:
Bridge inventory scale and regulatory scrutiny create the deepest procurement budgets. Building and tunnel applications follow distinct funding mechanisms and technical specifications.
- Bridges:Continuous monitoring of strain, displacement, and cable tension addresses deferred maintenance on European motorway and rail networks. Germany's KBA protocols and France's ANSN guidelines mandate sensor deployment on critical inventory.
- Buildings:Historic structure preservation and seismic resilience drive demand in Italy and Romania. Monitoring focuses on settlement, crack propagation, and vibration transmission from adjacent construction.
- Dams:Hydroelectric operators in Austria and Switzerland monitor seepage, concrete swelling, and foundation stability. Regulatory pressure from national water authorities shapes procurement specifications.
- Tunnels:Fire safety integration and convergence zone monitoring predominate in Alpine corridor projects. Swiss and Austrian operators require redundant sensing for ventilation control system integration.
Bridges absorb the largest capital allocation, though Tunnels exhibit the steepest expansion trajectory from trans-European transport network investments.
End User:
Engineering consultancies and government agencies control procurement through distinct contract structures. Construction firms and research institutions occupy narrower, specialized roles.
- Engineering Consulting:Firms bundle sensor deployment with predictive analytics subscriptions. Dutch and Belgian asset owners increasingly lease monitoring capabilities rather than capitalizing equipment purchases.
- Government Agencies:National transport authorities in Germany, France, and Italy specify continuous monitoring for critical infrastructure under federal highway administration protocols.
- Construction Firms:Temporary monitoring during construction and handover documentation drives adoption. Eastern European contractors deploy portable systems for quality assurance on new motorway spans.
- Research Institutions:Universities and national laboratories validate novel sensing algorithms. Collaboration with fiber optic suppliers advances distributed acoustic sensing applications.
Government Agencies hold the established revenue base, yet Engineering Consulting is capturing share fastest through outcome-based service models.
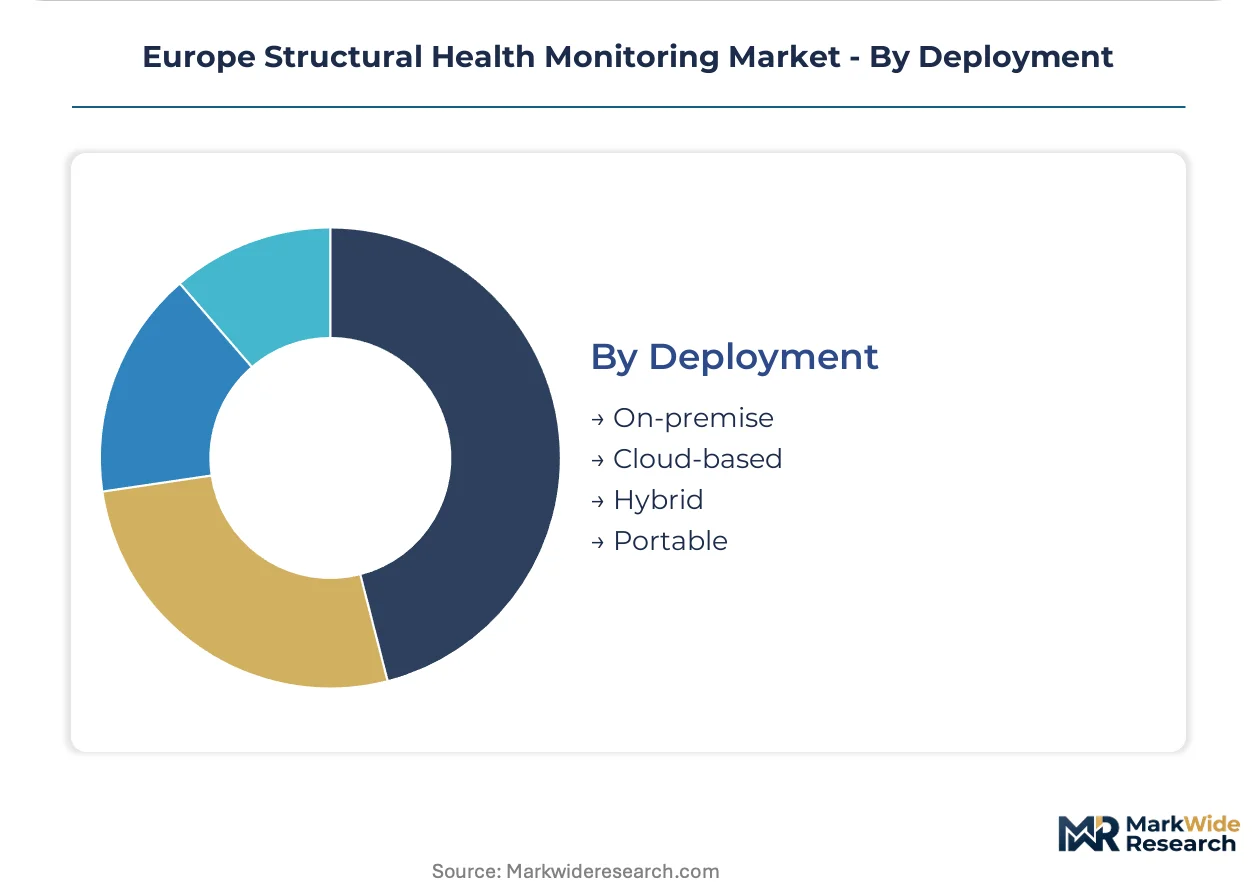
Deployment:
Cloud infrastructure investment separates large-scale operators from mid-sized asset owners. Hybrid architectures emerge where legacy SCADA integration constrains full migration.
- Cloud-based:Real-time dashboards and predictive maintenance algorithms require sustained edge computing investment. Large European rail operators favor this for multi-site portfolio management.
- Hybrid:Local data acquisition with cloud analytics balances latency requirements and remote access. German bridge operators adopt this to integrate decades-old control systems with modern diagnostics.
- On-premise:Air-gapped systems satisfy cybersecurity requirements for critical tunnel ventilation controls. Swiss infrastructure managers specify this for Alpine base tunnel segments.
- Portable:Rapid-deployment kits serve construction-phase monitoring and emergency structural assessment. Romanian and Czech contractors utilize this for aging inventory triage.
Cloud-based deployment leads new installations, though Hybrid configurations are expanding most quickly among operators with legacy system constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Eastern Europe remain acutely price-sensitive, while German and Swiss operators absorb premium sensor pricing for compliance-grade deployments. Western European procurement concentrates on lifecycle documentation mandates, creating divergent elasticity patterns across the continent.
Germany
The KBA mandates continuous structural assessment on critical bridge inventory, compressing procurement timelines for fiber optic networks. Federal highway administration protocols require electromagnetic-immune sensing on rail corridors spanning Bavaria and North Rhine-Westphalia. Stuttgart engineering clusters supply calibration expertise that constrains deployment velocity elsewhere.
France
ANSN infrastructure guidelines govern national procurement standards for motorway and rail crossings. The EU AI Act's risk classification framework forces French tunnel operators to document algorithmic transparency before automated diagnostic deployment. Lyon-based consultancies bundle sensor leasing with predictive analytics subscriptions.
Italy
Alpine dam operators deploy acoustic emission sensing for early-stage concrete damage identification under national water authority pressure. Historic structure preservation in Rome and Florence drives seismic resilience monitoring demand. Emilia-Romagna engineering firms specialize in settlement and crack propagation assessment.
Switzerland
Alpine base tunnel segments require redundant air-gapped sensing for ventilation control integration. Gotthard and Lötschberg corridor operators specify on-premise systems satisfying cybersecurity protocols. Zurich infrastructure managers lead trans-European transport network convergence zone monitoring.
Poland
Extensive aging motorway crossings present greenfield deployment potential with minimal existing monitoring penetration. Thermography adoption concentrates in Warsaw and Krakow for periodic bridge deck assessment. EU Green Deal lifecycle documentation mandates are accelerating procurement among national road administration authorities.
Europe Structural Health Monitoring Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European structural health monitoring landscape. The market exhibits moderate consolidation with tiered specialization between premium fiber optic suppliers and volume-focused wireless sensor vendors. Three archetypes dominate: heritage strain measurement specialists, integrated geotechnical service providers, and industrial automation platform extenders. Competitive moves center on strategic partnerships for AI algorithm development and geographic expansion into Eastern European greenfield infrastructure.
Among heritage measurement specialists, HBM (Hottinger Bruel and Kjaer) represents the premium-tier anchor in German bridge installations. Fugro N.V. exemplifies the integrated service archetype, occupying a position spanning offshore and civil infrastructure domains. Siemens AG sits within the industrial automation extension tier, leveraging cloud platform expertise for tunnel network diagnostics. These three players illustrate the capability segmentation that defines procurement selection criteria across European transport authorities.
| Leading Market Players |
|---|
| HBM (Hottinger Bruel and Kjaer) |
| Fugro N.V. |
| Campbell Scientific |
| GEOKON |
| SIXENSE Systems |
| Structural Monitoring Systems PLC |
| COWI A/S |
| OSMOS Group SA |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Long-term sensor leasing contracts with bundled analytics subscriptions lock in supply access and price visibility for Dutch and Belgian asset owners while compressing upfront capital requirements. This contract-structure pattern concentrates procurement power among engineering consultancies capable of sustaining edge computing infrastructure across multi-site portfolios.
Pricing Analysis
After-sales service revenue from calibration contracts and predictive maintenance subscriptions drives lifetime value for fiber optic system vendors. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked installations with full AI diagnostic suites from basic sensor hardware. Pricing pressure stems from mid-sized operators deferring cloud infrastructure investments. Government agencies in Germany and France exhibit lowest price sensitivity due to KBA and ANSN compliance mandates, while Polish road authorities remain acutely cost-conscious.
Supply Chain Analysis
Fiber optic splicing expertise concentrates in Stuttgart engineering clusters and Lyon-based consultancies, creating a chokepoint that constrains deployment velocity across Eastern Europe. Component sourcing draws from German precision sensor manufacturers, French optical cable producers, and Swiss data acquisition specialists. Single-source vulnerability runs through specialized calibration equipment suppliers. Distribution runs through engineering consultancies that bundle hardware procurement with installation and ongoing diagnostic services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU Green Deal lifecycle documentation mandates and national transport authority protocols create switching costs that protect incumbent positioning.
For Market Incumbents: Fortify market position by deepening captive calibration service capabilities and securing exclusive partnerships with Stuttgart and Lyon engineering clusters. Emerging AI-driven diagnostic platforms from industrial automation extenders threaten premium-tier fiber optic positioning. Vertical integration into edge computing infrastructure locks in multi-site portfolio contracts.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission offers the most viable entry path for sensor hardware vendors. Eastern European bridge inventory in Poland, Romania, and Czech Republic presents the most penetrable geography with minimal existing monitoring penetration. Outcome-based service contracts for aging motorway crossings bypass capital-intensive cloud infrastructure requirements.
For Investors and Strategic Acquirers: The market sits at an infrastructure-mandate acceleration phase that favors integrated platform vendors with captive diagnostic capabilities. Long-term viability hinges on regulatory compliance depth rather than hardware differentiation alone. Acquisition targets should demonstrate established relationships with German KBA or French ANSN procurement frameworks. Watch for EU AI Act conformity assessment bottlenecks as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development Partnership | French tunnel operators now require documented algorithmic transparency under EU AI Act risk classifications. |
| Eastern European Geographic Expansion | Polish and Romanian road authorities accelerate procurement under EU Green Deal lifecycle mandates. |
| Sensor Fusion Platform Integration | German rail operators specify redundant fiber optic and wireless accelerometer networks for kilometer-scale structures. |
| Calibration Service Capability Buildout | Fiber optic splicing expertise concentrates in Stuttgart and Lyon, constraining competitor deployment velocity. |
| CE Marking Fast-Track Investment | Certification timeline compression creates competitive advantage for notified body pre-submission relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU transport authority procurement databases, ECHA REACH compliance filings, and national infrastructure maintenance records. Primary interviews engaged bridge operators, fiber optic system procurement leads, engineering consultancy technical directors, and tunnel ventilation control specialists. Secondary validation drew from KBA protocol documentation, ANSN guideline publications, and EU Green Deal implementation reports. Bottom-up sensor deployment tallies triangulate against top-down infrastructure investment forecasts.
Segmentation dimensions modeled include technology type, application category, end-user archetype, and deployment architecture across the analysis window. CAGRs derive from infrastructure investment trajectories, regulatory compliance timeline compression, and technology substitution elasticities. Industry-specific forecast inputs incorporate EU F-Gas Regulation thermal design restrictions and AI Act risk classification implementation schedules.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable fiber optic component supply; material deviation in regulatory implementation pace or specialized labor availability would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act conformity assessment timelines and Eastern European procurement acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Europe Facade Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
UK Facade Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Philippines Roofing Market