
 North America Anchors and Grouts Market | 2026-2036
North America Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Anchors and Grouts Market Analytics
Buyer concentration across North American infrastructure agencies is rebalancing as state DOTs consolidate multi-year supply contracts while independent contractors fragment procurement through distributor networks. BASF SE leverages its epoxy formulation portfolio to anchor specification-driven highway projects. Sika AG competes through localized blending capacity near major construction corridors. Hilti Corporation dominates engineered fastening systems for seismic-rated commercial structures.
Anchors and grouts comprise load-transfer devices and void-filling compounds that bond structural elements to substrates, with epoxy grouts typically achieving compressive strengths exceeding 14,000 psi and chemical anchors relying on resin-cartridge systems for cracked-concrete performance. Their primary purpose is to secure structural integrity under dynamic, seismic, and heavy-load conditions across built infrastructure. Mechanical anchors lead the product type category in volume terms due to standardized installation protocols in commercial building foundations. Epoxy grouts capture premium margin pools in industrial machinery baseplate applications where precision alignment and chemical resistance justify higher material costs. Cement grouts remain mature across roadworks and mass concrete rehabilitation where cost efficiency dominates specification criteria.
ASTM International governs mechanical anchor performance testing through E488 and E1512 protocols, while ACI 355.2 shapes adhesive anchor qualification requirements that manufacturers must satisfy for DOT eligibility. OSHA fall-protection anchorage standards additionally drive specification-grade demand in vertical construction applications. State transportation departments increasingly mandate environmental product declarations and embodied-carbon thresholds for federally funded projects, tightening market access for uncertified suppliers. Stakeholders must monitor evolving MASH-compliant barrier anchor standards and the shift toward performance-based seismic qualification as determinants of long-term specification lock-in.
Market Dynamics
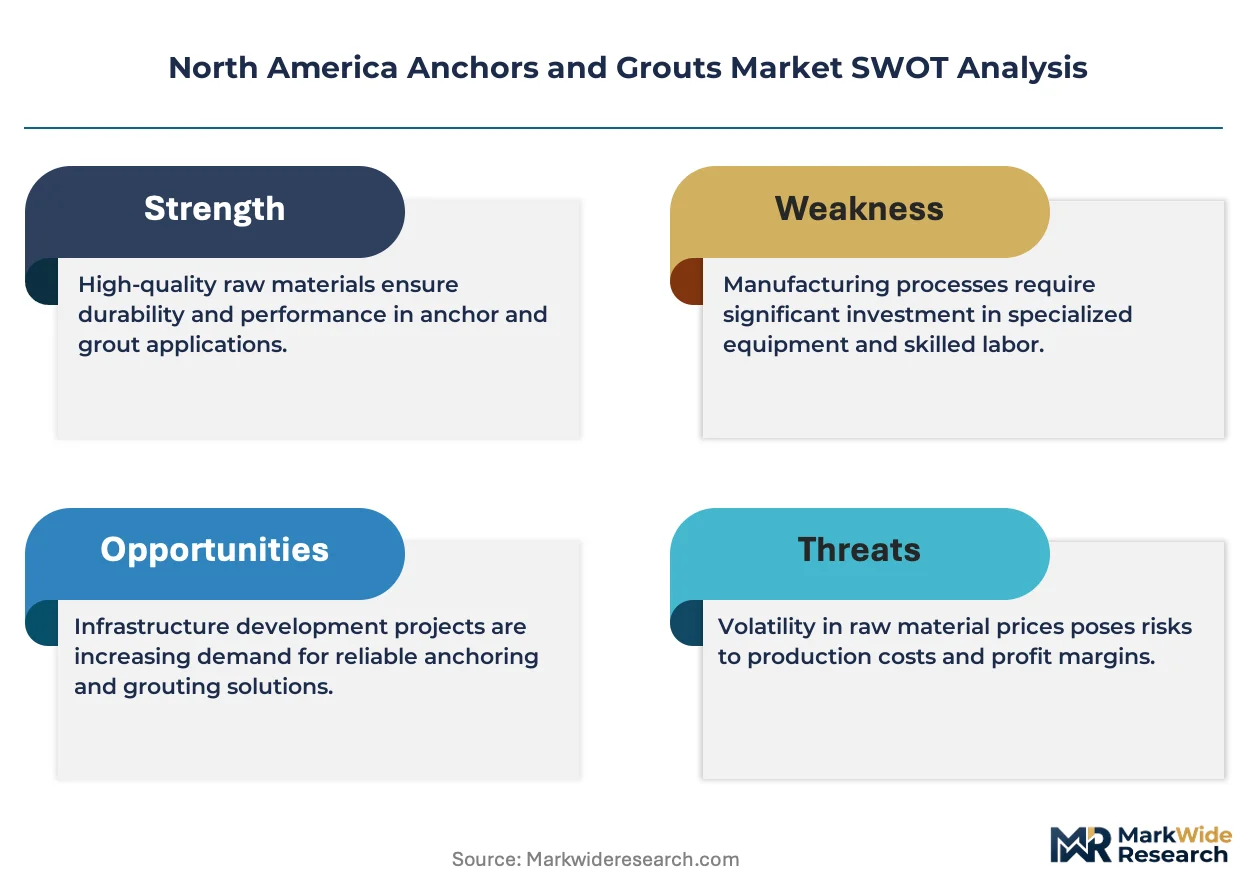
State DOT seismic design standards are tightening material certification requirements across the North America Anchors and Grouts Market, forcing manufacturers to requalify product portfolios for federally funded infrastructure contracts.
Growth Catalysts
- Infrastructure Rehabilitation:Aging highway and bridge networks across the United States and Canada are expanding procurement volumes for epoxy and cement grout systems as agencies prioritize structural reinforcement over new construction.
- Buy America Provisions:State-level domestic content mandates are reshaping supplier eligibility criteria, creating specification advantages for manufacturers with localized blending and testing facilities.
- Hurricane-Resilient Construction:Gulf Coast port modernization and petrochemical facility upgrades are driving demand for high-performance anchor systems rated for extreme wind and seismic loading conditions.
Market Restraints
- Raw Material Volatility:Epoxy resin and specialty cement feedstock costs fluctuate with petrochemical pricing cycles, compressing margins for formulation-dependent product lines.
- Supply Concentration:Domestic production of specification-grade chemical anchors concentrates among a limited number of DOT-prequalified facilities, creating bottleneck risks during peak construction seasons.
- Technical Limitations:Cement grouts exhibit inferior performance in dynamic load applications compared to epoxy alternatives, restricting their specification in seismic-rated commercial structures.
Strategic Opportunities
- Carbon-Embodied Procurement:State transportation departments are mandating environmental product declarations for federally funded projects, creating first-mover advantages for suppliers with verified lifecycle data.
- MASH-Compliant Barrier Systems:Updated roadside hardware anchor standards are opening specification windows for manufacturers capable of demonstrating crash-tested performance in high-tension applications.
- Seismic Retrofit Contracts:California and Pacific Northwest building stock upgrades are generating sustained demand for cracked-concrete-rated adhesive anchor systems in commercial and institutional structures.
Industry Challenges
- Certification Timeline Compression:ACI 355.2 qualification protocols for adhesive anchors require extended testing cycles, delaying product commercialization and locking out smaller formulation specialists.
- Skilled Installation Shortage:Proper torque-controlled tightening and hole-cleaning protocols for epoxy and mechanical anchors demand certified field technicians, creating workforce bottlenecks in high-growth corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Anchors and Grouts Market |
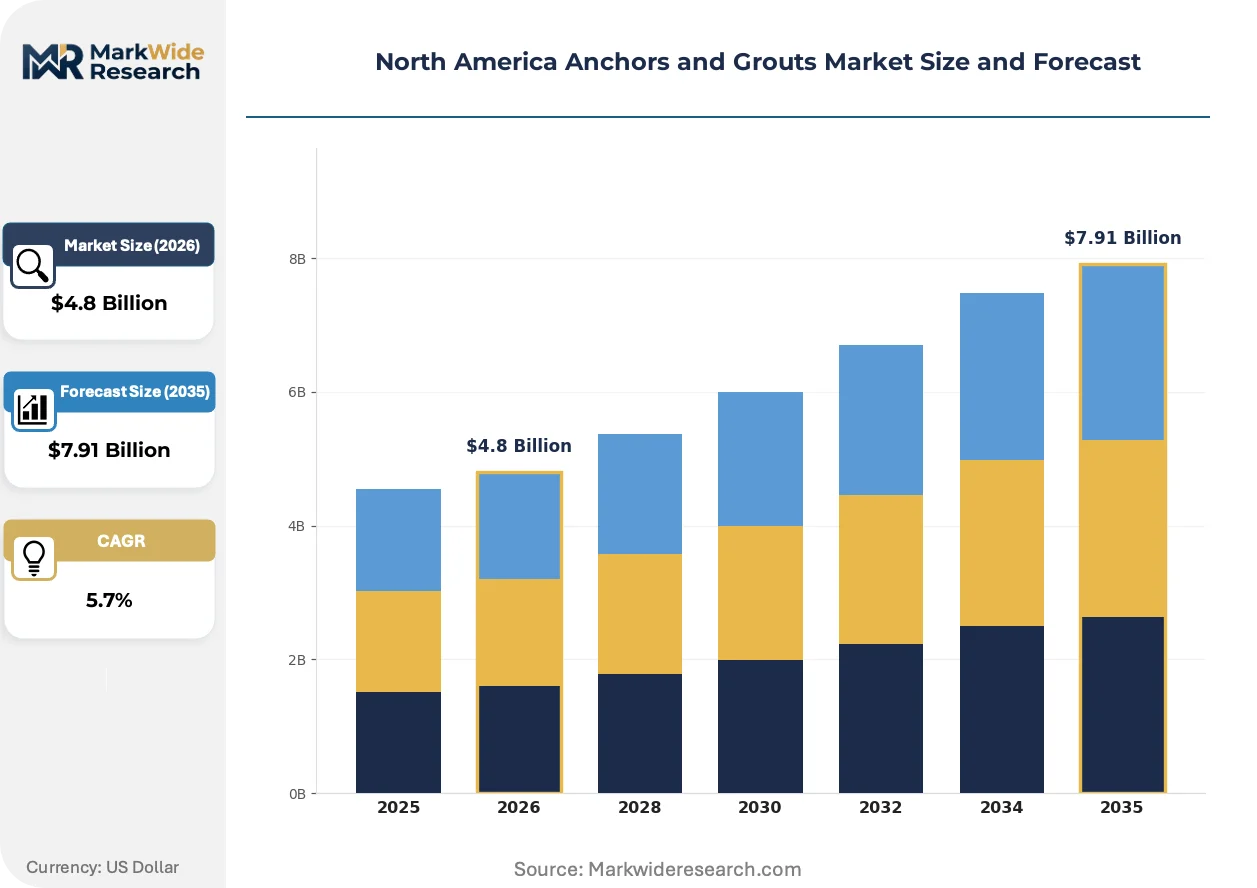
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Anchors, Chemical Anchors, Epoxy Grouts, Cement Grouts End User: Construction, Infrastructure, Marine, Industrial Application: Building Foundations, Roadworks, Renovation, Bridge Construction Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Saint-Gobain Weber, BASF SE, Sika AG, LATICRETE International Inc., Hilti Corporation, MAPEI SpA, MBCC Group, W. R. Grace & Co., Fosroc Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Anchors and Grouts Market Evolving Landscape
Material science advances and procurement digitization are restructuring competitive positioning across anchor and grout specification channels, with performance-based qualification protocols displacing legacy prescriptive standards.
Hybrid epoxy-cement grout formulations are consolidating specification-grade applications previously split between pure epoxy and traditional cement systems. Industrial machinery baseplate installers are adopting these intermediate-performance materials for precision alignment tasks where full epoxy cost is unjustified. The technology is consolidating mid-tier procurement decisions by offering compressive strength thresholds above 10,000 psi with reduced material expenditure.
OSHA fall-protection anchorage standards are driving specification-grade demand in vertical construction applications across the United States. Contractors must demonstrate engineered system capacity for worker tie-off points, shifting anchor selection from commodity hardware to tested and documented assemblies. Commercial high-rise developments in Texas and Florida are responding by embedding anchor qualification data directly into digital building information models.
Buyer concentration among state DOTs is fragmenting procurement through mandated distributor networks for smaller contractors. Independent installers in the southeastern United States are accessing specification-grade materials through regional supply houses rather than direct manufacturer relationships. This channel evolution is most visible in highway maintenance contracts where emergency repair timelines preclude traditional bidding cycles.
North America Anchors and Grouts Market Segmentation
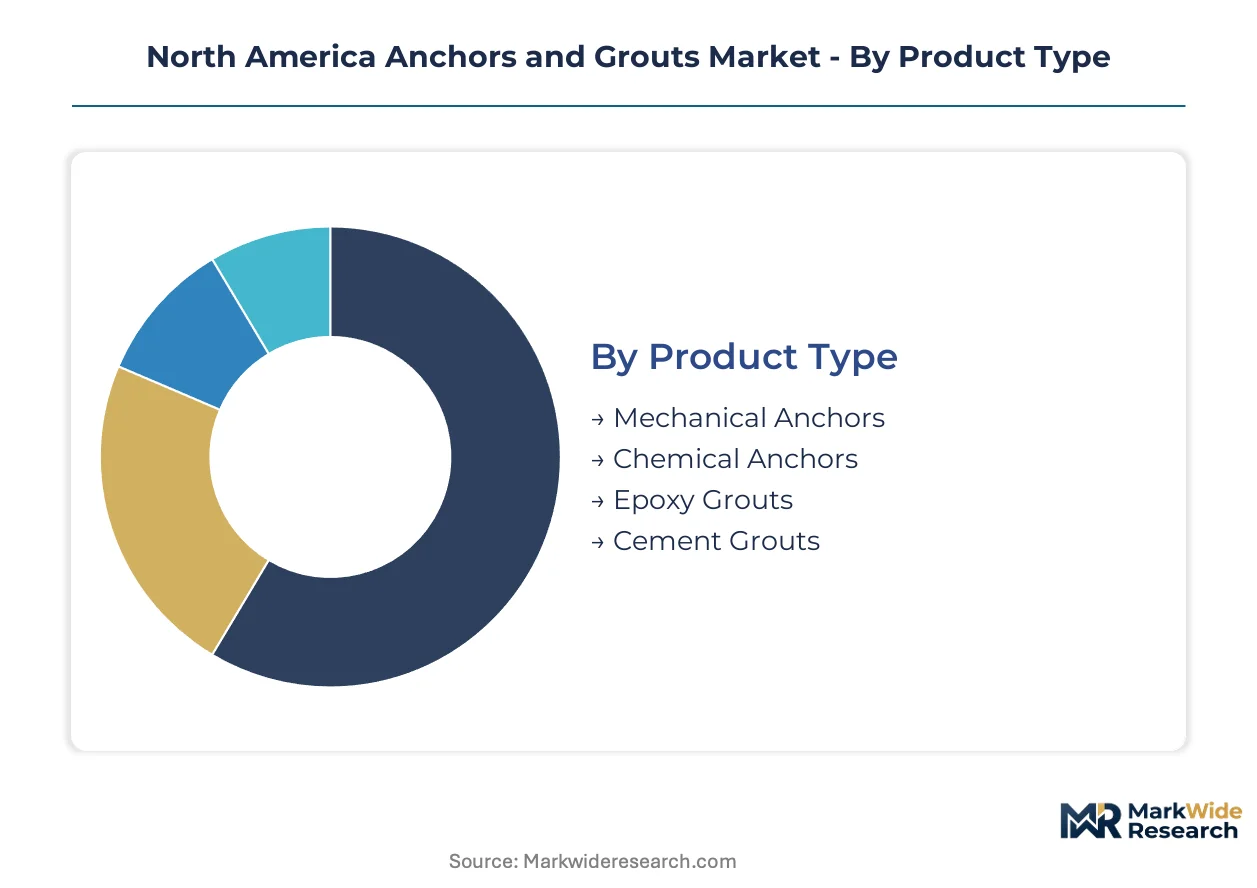
Segmentation across the North America Anchors and Grouts Market reveals how specification-grade materials flow through distinct procurement channels. Product chemistry, installation environment, and buyer sophistication determine margin capture and supplier relationships.
Product Type:
Integration depth varies sharply: mechanical and chemical anchors function as standalone fastening systems, while epoxy and cement grouts embed within larger structural assemblies requiring substrate bonding.
- Mechanical Anchors:Expansion and undercut designs achieve load transfer through physical interlock with concrete. Texas and Florida commercial high-rises specify these for non-cracked concrete applications where rapid installation and immediate loading dominate procurement criteria. State DOT highway maintenance crews favor standardized torque-controlled systems for barrier retrofits.
- Chemical Anchors:Injectable resin systems bond threaded rod to cracked and uncracked concrete through polymerization. California seismic retrofit contractors specify ACI 355.2-qualified adhesive anchors for hospital and school upgrades where dynamic load resistance is mandatory. Installation demands hole-cleaning protocols and cure-time management that elevate labor costs.
- Epoxy Grouts:High-performance formulations exceed 14,000 psi compressive strength for precision machinery baseplate alignment. Gulf Coast petrochemical facilities specify these for turbine and compressor installations where chemical resistance and vibration damping justify premium material expenditure.
- Cement Grouts:Portland cement-based systems dominate roadworks and mass concrete rehabilitation across state DOT portfolios. Cost efficiency and familiar placement protocols sustain specification despite inferior dynamic performance versus epoxy alternatives.
Mechanical anchors lead volumes today; chemical anchors are gaining share fastest.
End User:
Cost tier stratification separates specification-grade industrial buyers from price-sensitive construction segments, with procurement sophistication determining supplier access.
- Construction:Commercial building developers balance code compliance against material cost, driving volume through distributor networks. Multi-family residential projects in the southeastern United States favor mechanical anchors for speed of installation.
- Infrastructure:State DOTs and federal agencies mandate certified products with documented testing protocols. Buy America provisions restrict eligibility to domestic manufacturing facilities, consolidating procurement among prequalified suppliers.
- Marine:Port modernization along the Gulf and Atlantic coasts specifies corrosion-resistant anchoring for fender systems and mooring hardware. Saltwater exposure demands stainless steel or hot-dip galvanized finishes that elevate unit economics.
- Industrial:Petrochemical and power generation facilities impose precision alignment and chemical resistance requirements. Machinery baseplate installations specify epoxy grouts with documented compressive strength and shrinkage performance.
Infrastructure commands the largest procurement budgets; industrial applications deliver the steepest margin expansion.
Application:
Volume concentration clusters in new construction foundations, while renovation and bridge work drive specification-grade chemical anchor adoption.
- Building Foundations:Commercial and institutional structures anchor structural steel and precast elements to concrete footings. Seismic design categories determine whether mechanical or adhesive systems satisfy code requirements.
- Roadworks:Highway barrier installations, sign structures, and lighting foundations consume standardized mechanical anchors in high volumes. Emergency repair contracts favor distributor-channel procurement over direct manufacturer relationships.
- Renovation:Existing concrete rehabilitation demands cracked-concrete-rated adhesive anchors where substrate integrity is uncertain. Urban core commercial upgrades in California and the Pacific Northwest sustain demand for seismic-rated systems.
- Bridge Construction:Expansion joint anchors, bearing assemblies, and deck rehabilitation specify high-performance grouts and post-installed anchoring. Federal funding eligibility requires compliance with updated DOT seismic standards.
Building foundations anchor current volumes; renovation applications are expanding most quickly.
Distribution Channel:
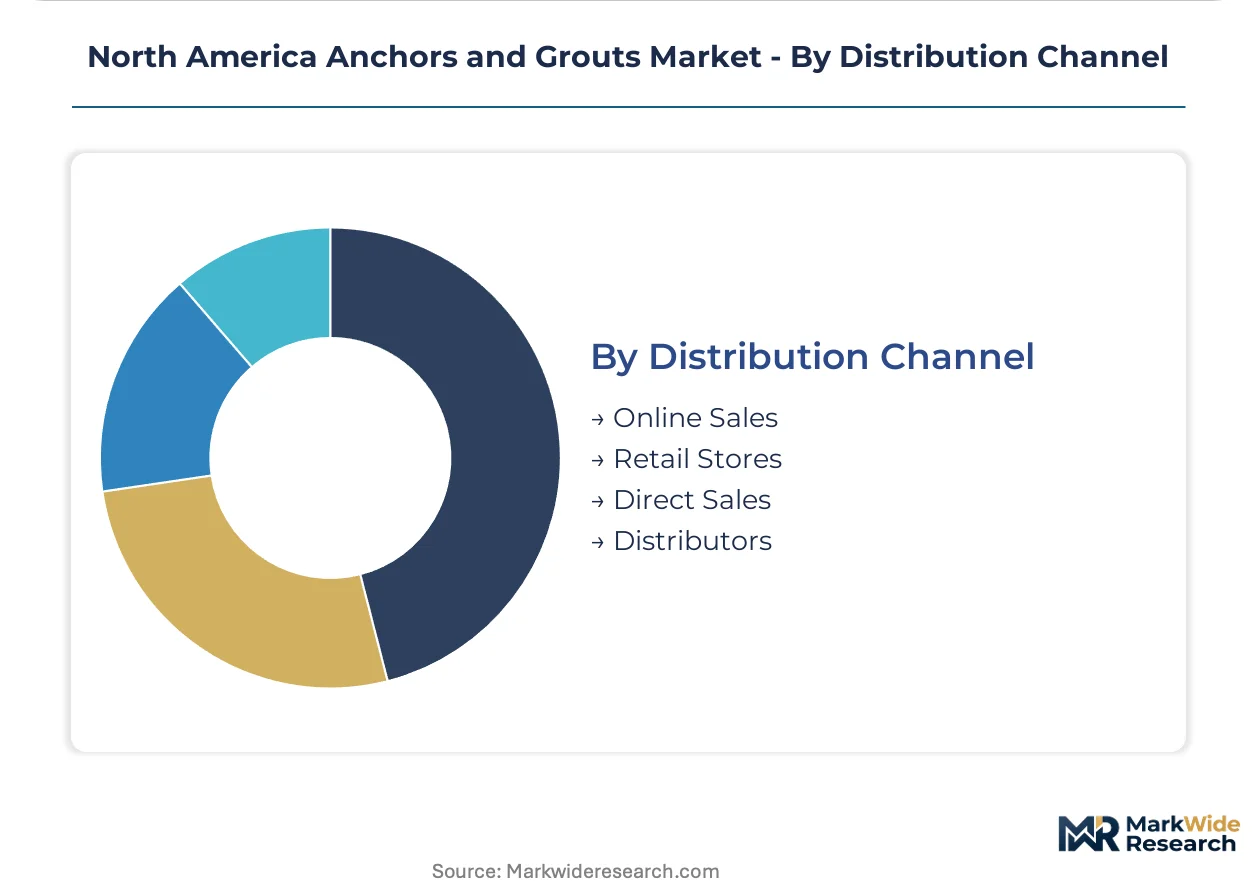
Customer type and project scale determine channel selection, with large contractors leveraging direct relationships and independent installers fragmenting through regional supply houses.
- Online Sales:Standardized mechanical anchors and commodity grout products move through digital procurement platforms. Small contractors and maintenance crews value specification lookup and rapid fulfillment.
- Retail Stores:Big-box construction supply outlets serve residential and light commercial segments. Product selection emphasizes mechanical anchors with visible load ratings and installation instructions.
- Direct Sales:Major infrastructure contractors and industrial end users negotiate multi-year supply agreements with manufacturers. Technical support, custom blending, and project-specific testing justify direct relationships.
- Distributors:Regional supply houses aggregate specification-grade products for independent contractors and smaller construction firms. Channel fragmentation accelerates as state DOTs mandate distributor access for disadvantaged business participation.
Direct sales capture the highest-value contracts; distributor networks are climbing the fastest as procurement decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's infrastructure procurement runs tighter certification protocols than Mexico's distributor-heavy construction channels, while the United States dominates absolute volume through federal highway rehabilitation programs.
United States
State DOTs across California, Texas, and Florida are consolidating multi-year supply contracts for seismic-rated anchor systems. OSHA fall-protection anchorage standards mandate engineered system capacity for commercial high-rise developments. The Gulf Coast corridor concentrates petrochemical facility upgrades where epoxy grout specifications exceed 14,000 psi compressive strength requirements.
Canada
Provincial transportation departments in Ontario and British Columbia are expanding bridge rehabilitation procurement for cracked-concrete-rated adhesive anchors. Health Canada environmental guidelines intersect with provincial infrastructure standards to tighten material certification for federally funded projects. The Toronto-Waterloo corridor anchors commercial high-rise construction demanding precision machinery baseplate alignment systems.
Mexico
Northern border states are absorbing cross-border infrastructure investment tied to nearshoring manufacturing expansion. The national construction regulator enforces evolving seismic design standards for commercial structures in Mexico City and Monterrey. The Bajío Region's automotive manufacturing clusters are specifying imported epoxy grout systems for precision equipment installation.
North America Anchors and Grouts Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification-grade and commodity product tiers. The vendor base stratifies between multinational chemical formulators with localized blending capacity and regional distributors aggregating certified products for independent contractors. Three archetypes dominate: integrated construction chemical conglomerates, engineered fastening system specialists, and regional blending facilities serving DOT-prequalified channels. M&A activity concentrates among mid-cap specialists seeking vertical integration into resin formulation, while capacity expansion targets Gulf Coast petrochemical corridor proximity.
Among European-anchored construction chemical conglomerates, BASF SE and Sika AG exemplify integrated formulation capabilities spanning epoxy and cement grout portfolios. Hilti Corporation occupies a distinct position as a Liechtenstein-based engineered fastening specialist. These three entities represent contrasting strategic postures: diversified chemical platforms versus focused precision-engineering operations, each anchoring different specification tiers within infrastructure and commercial construction procurement channels.
| Leading Market Players |
|---|
| Saint-Gobain Weber |
| BASF SE |
| Sika AG |
| LATICRETE International Inc. |
| Hilti Corporation |
| MAPEI SpA |
| MBCC Group |
| W. R. Grace & Co. |
| Fosroc Inc. |
| Others |
Value Network & Pricing Analysis
State DOT procurement concentration across California, Texas, and Florida sustains contract-based long-term offtake pricing for specification-grade anchor systems. Buy America compliance costs and DOT prequalification requirements embed premium tiers into multi-year supply agreements that smaller contractors cannot access through distributor channels.
Pricing Analysis
Capacity additions in the Gulf Coast petrochemical corridor are reshaping price floors for epoxy grout formulations as localized blending reduces freight absorption costs. Three-tier pricing structure across DOT-certified premium, state-approved standard, and distributor-grade economy levels separates infrastructure contractors from commercial builders and residential installers. Cost compression in cement grout segments is intensifying because Portland cement feedstock volatility transfers directly into spot-market quotations. Independent contractors operating through regional supply houses exhibit the highest price sensitivity, while industrial facility engineers specifying machinery baseplate systems demonstrate minimal elasticity.
Supply Chain Analysis
DOT prequalification protocols gate market access for adhesive anchor manufacturers, forcing extended ACI 355.2 testing cycles that lock out uncertified suppliers. Domestic production concentrates in the United States, Canada, and Mexico border zones where Buy America compliance can be demonstrated through localized formulation and testing. Epoxy resin and specialty cement feedstocks draw from petrochemical complexes along the Texas-Louisiana corridor, creating single-source vulnerability during hurricane-disrupted seasons. Distribution runs through manufacturer-direct relationships for infrastructure contractors and regional supply house networks for independent installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between California's seismic retrofit mandates and Texas's commercial construction surge creates margin capture opportunities for suppliers with dual-state certification portfolios. Cost differentials in DOT testing protocols versus private-label commercial standards reward manufacturers that segment qualification investments geographically.
For Market Incumbents: Cement specification lock-in through MASH-compliant barrier system prequalification before updated federal highway standards take full effect. Capacity addition in the Pacific Northwest addresses California spillover demand for cracked-concrete-rated adhesive anchors. Backward integration into epoxy resin formulation buffers margin pressure from petrochemical feedstock volatility. Channel control through exclusive distributor agreements in the southeastern United States defends against independent contractor fragmentation. For New Entrants and Emerging Players: Independent seismic retrofit contractors in California secondary metros represent the most penetrable buyer archetype for ACI 355.2-qualified adhesive anchor specialists. Emergency repair crews serving state DOT highway maintenance contracts offer white-space access through rapid-fulfillment distributor partnerships rather than traditional bidding cycles. Go-to-market execution should anchor in digital building information model integration for commercial high-rise developers in Texas and Florida. For Investors and Strategic Acquirers: Construction chemical conglomerates with North American blending infrastructure are the most active acquirer in this space, targeting DOT-prequalified regional specialists for vertical capability expansion. The five-to-ten-year viability window favors manufacturers with verified environmental product declaration databases as carbon-embodied procurement mandates expand. Acquisition target archetype: mid-cap adhesive anchor formulators with ACI 355.2 qualification and Gulf Coast geographic presence. Monitor MASH-compliant barrier anchor standard enforcement velocity as the inflection signal for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Formulation | Captive supply of petrochemical feedstock buffers margin compression from raw material volatility cycles. |
| DOT Prequalification Capacity Expansion | ACI 355.2 testing facility investment locks out competitor access to California seismic retrofit contracts. |
| Environmental Product Declaration Program | Verified lifecycle data positions suppliers for state transportation department carbon-embodied procurement mandates. |
| MASH-Compliant Barrier System Development | Crash-tested performance documentation opens federal highway rehabilitation specification windows. |
| Regional Distributor Network Consolidation | Channel control in the southeastern United States captures independent contractor procurement fragmentation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with state DOT procurement officers, commercial construction project managers, industrial facility engineers, and regional distributor principals with secondary validation. Trade data from U.S. Census construction spending reports, ACI committee documentation, state transportation department contract award databases, and SEC filings from construction chemical conglomerates anchored volume estimates. Bottom-up project pipeline analysis and top-down infrastructure budget allocation triangulation reconciled demand figures across the forecast horizon.
Segment-weighting applied product type, end user vertical, application environment, and distribution channel dimensions across the modeling period. Mechanical anchor, chemical anchor, epoxy grout, and cement grout categories carried distinct growth trajectories based on infrastructure rehabilitation intensity versus new construction velocity. CAGRs derived from historical procurement pattern analysis projected forward against DOT seismic standard implementation timelines and petrochemical facility upgrade cycles.
Underlying measurement precision varies by segment; infrastructure and industrial end-use categories carry tighter precision than residential construction estimates due to documented contract award transparency. Forecasts reflect assumptions about federal highway funding continuity, Buy America provision enforcement consistency, and epoxy resin price normalization. A model refresh is warranted upon material change in state DOT seismic design standard adoption velocity or MASH-compliant barrier hardware mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Global Concrete Restoration Market