
 Southeast Asia Anchors and Grouts Market | 2026-2036
Southeast Asia Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Anchors and Grouts Market Analytics
Market Context
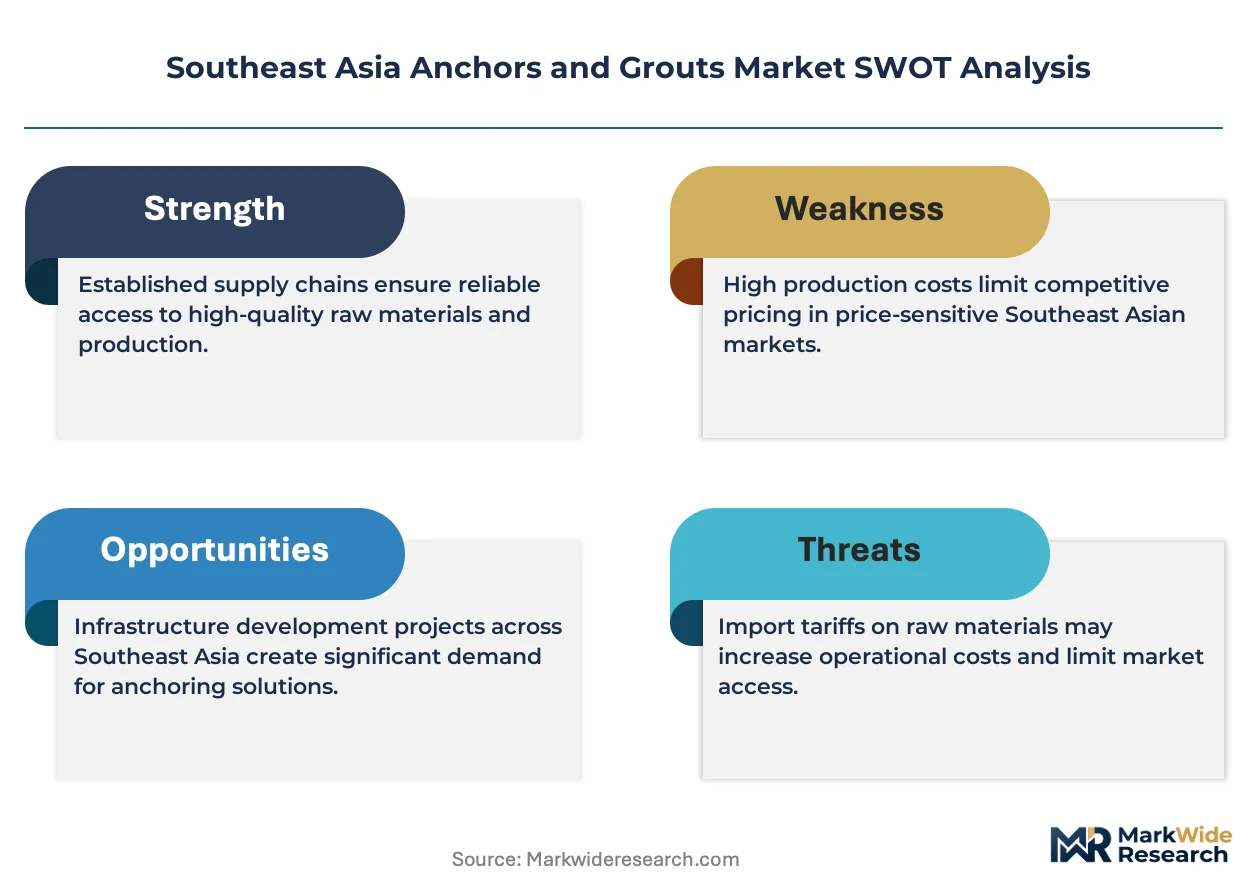
ISO 9001 quality management certification is collapsing as a baseline market-access filter across Southeast Asia, forcing suppliers to pursue more demanding national credentials. Sika AG leverages its Swiss-engineered product portfolio to dominate specification-driven infrastructure tenders across Thailand and Vietnam. Mapei SpA sustains regional manufacturing presence through localized blending facilities that reduce import duty exposure. Fosroc Inc competes on technical service intensity, embedding application engineers directly with contractor teams on major civil projects.
Technical Definition and Segment Structure
Southeast Asia anchors and grouts encompass load-transfer mechanical fasteners and void-filling binder systems, with epoxy grouts typically achieving compressive strengths exceeding 80 MPa for heavy machinery baseplates and structural column connections. These products primarily secure structural elements, stabilize rock faces, and seal water ingress pathways in tropical construction environments. Cementitious grouts occupy the volume base across residential and mid-rise commercial construction where cost sensitivity dominates procurement decisions. Chemical grouts represent the fastest-expanding category as tunneling projects in Vietnam and Indonesia accelerate demand for rapid-setting, low-viscosity injection systems. Epoxy grouts command premium positioning in mining and industrial applications where chemical resistance and dynamic load tolerance justify higher material outlays.
Regulatory Framework and Outlook
Indonesia's SNI standards, Thailand's TISI certification requirements, and Malaysia's CIDB product approval schemes collectively determine which formulations gain market access across ASEAN construction supply chains. These frameworks elevate testing documentation burdens, particularly for imported chemical grout systems seeking project-level specification. Stakeholders must monitor evolving national building code harmonization under the ASEAN Economic Community mutual recognition arrangements, as regulatory convergence would reshape competitive barriers and sourcing strategies for cross-border project contractors.
Market Dynamics
Malaysia's CIDB certification requirements are compressing supplier margins while elevating technical documentation burdens, forcing regional distributors to consolidate testing capabilities or exit specification-driven tenders entirely.
Growth Catalysts
- Indonesia's Dam and Tunnel Pipeline:Java corridor infrastructure projects require specialized chemical anchoring systems for water ingress control, pulling advanced epoxy formulations into specification sheets previously dominated by cementitious alternatives.
- Vietnam's Underground Construction Surge:Metro expansion in Ho Chi Minh City and Hanoi accelerates demand for rapid-setting, low-viscosity injection grouts that enable continuous tunneling operations without cure-time delays.
- REACH-Aligned Formulation Standards:ASEAN Economic Community harmonization discussions are elevating environmental compliance baselines, rewarding suppliers with pre-certified product portfolios across multiple national approval schemes.
Market Restraints
- Epoxy Resin Price Volatility:Petrochemical feedstock fluctuations compress margins for premium grout manufacturers serving mining and industrial baseplate applications where material costs dominate project bids.
- Import Dependency for Specialty Additives:Singapore and Thailand-based blenders rely on European and Japanese sources for amine hardeners and rheology modifiers, exposing supply chains to currency and shipping cost shocks.
- Cementitious Substitution Floor:Mid-rise residential construction across Philippines and Myanmar maintains fierce cost sensitivity, preventing chemical grout penetration regardless of performance advantages in seismic or moisture-prone conditions.
Strategic Opportunities
- Cambodia and Laos Infrastructure Buildout:Mekong hydropower and road tunnel projects lack established local supply chains, creating first-mover advantages for contractors bundling technical service with material provision.
- Polyurethane Slope Stabilization:Malaysia's mountainous highway expansion and Indonesia's volcanic terrain generate demand for flexible, expansion-tolerant anchoring systems that accommodate tropical thermal cycling.
- E-Procurement Platform Integration:Thailand's government construction portal and Vietnam's state investor digital tender systems enable direct supplier-contractor relationships that bypass traditional distributor markups.
Industry Challenges
- Application Engineer Scarcity:Specialist crews capable of executing high-pressure injection grouting in confined tunnel environments command premium wages across Vietnam and Indonesia, constraining project scaling.
- Multi-Jurisdictional Certification Timelines:Suppliers seeking simultaneous approval under Indonesia's SNI, Thailand's TISI, and Malaysia's CIDB face redundant testing protocols that extend market entry by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Anchors and Grouts Market |
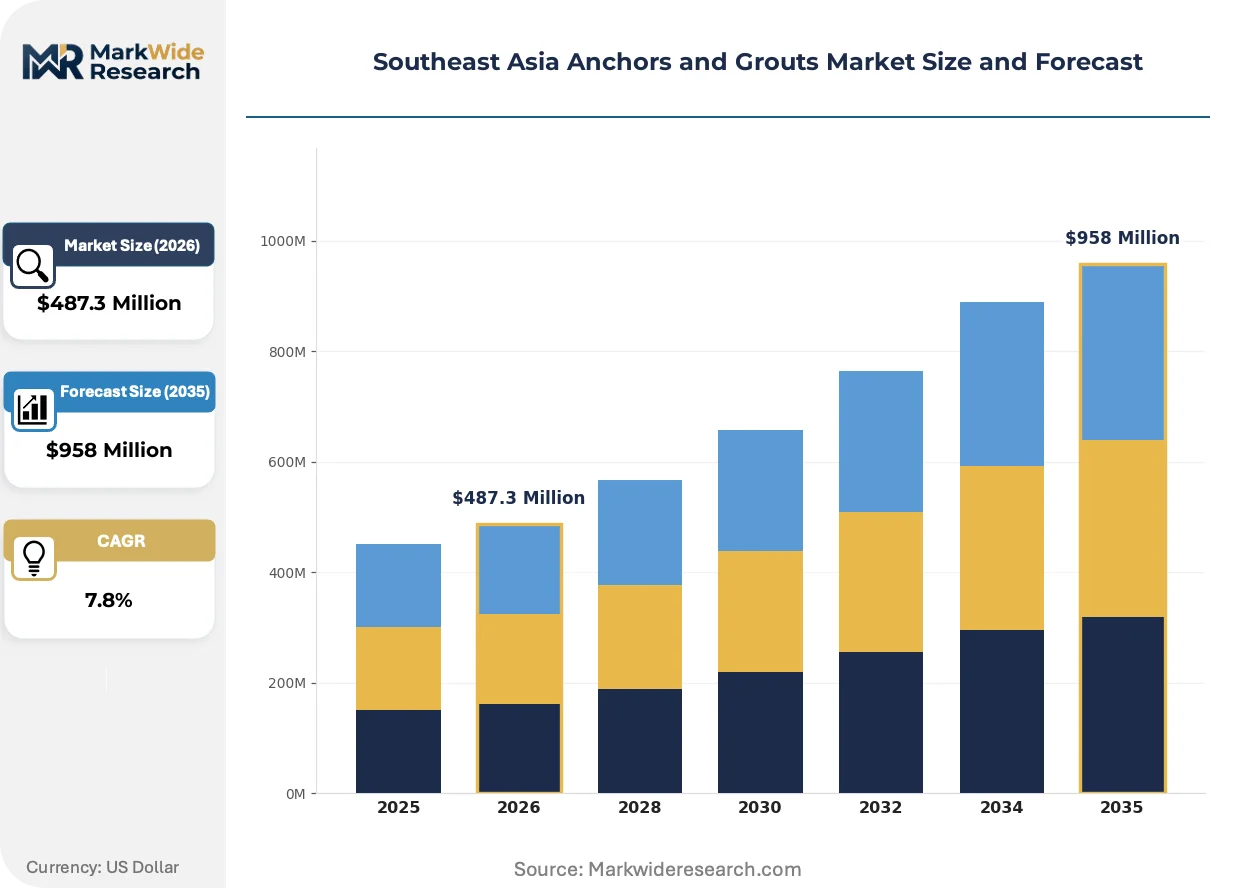
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $958 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Grouts, Epoxy Grouts, Polyurethane Grouts, Cementitious Grouts Application: Construction, Slope Stabilization, Soil Stabilization, Underwater Applications End User: Commercial Construction, Residential Construction, Infrastructure Projects, Mining Distribution Channel: Direct Sales, Online Sales, Wholesale Distributors, Retail Stores |
| Companies Covered | Sika AG, Mapei SpA, Bostik, Fosroc Inc, Saint-Gobain Weber, MBCC Group, Henkel AG & Co KGaA, Laticrete International Inc, GCP Applied Technologies Inc, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Anchors and Grouts Market Evolving Landscape
Formulation chemistry and procurement digitization are converging to reshape competitive positioning, with specification authority shifting from distributors to contractors capable of demonstrating field-proven application expertise.
Hybrid polyurethane-epoxy grout systems are supplanting pure epoxy formulations in mining machinery baseplate installations across Thailand and Indonesia. Site engineers favor these materials for their superior vibration damping and thermal expansion tolerance in tropical climates. Equipment OEMs are compressing warranty coverage for installations using legacy cementitious grouts, accelerating specification migration toward polymer-modified alternatives.
Malaysia's CIDB product approval scheme now mandates independent third-party testing for all imported chemical anchoring systems, rejecting manufacturer-declared performance data. This regulatory friction disproportionately burdens smaller European and Japanese suppliers lacking local laboratory partnerships. Major infrastructure tender documents increasingly specify CIDB-preapproved product lists, effectively creating procurement walled gardens.
Contractor procurement teams are unbundling material supply from technical supervision, sourcing grouts through digital platforms while retaining specialized application crews on retainer. This behavioral shift concentrates volume with price-transparent suppliers while fragmenting service revenue to independent field engineering consultancies. Indonesia's state-owned construction holding companies are piloting this model on Java corridor tunnel projects, with adoption spreading to Vietnamese metro consortia.
Southeast Asia Anchors and Grouts Market Segmentation
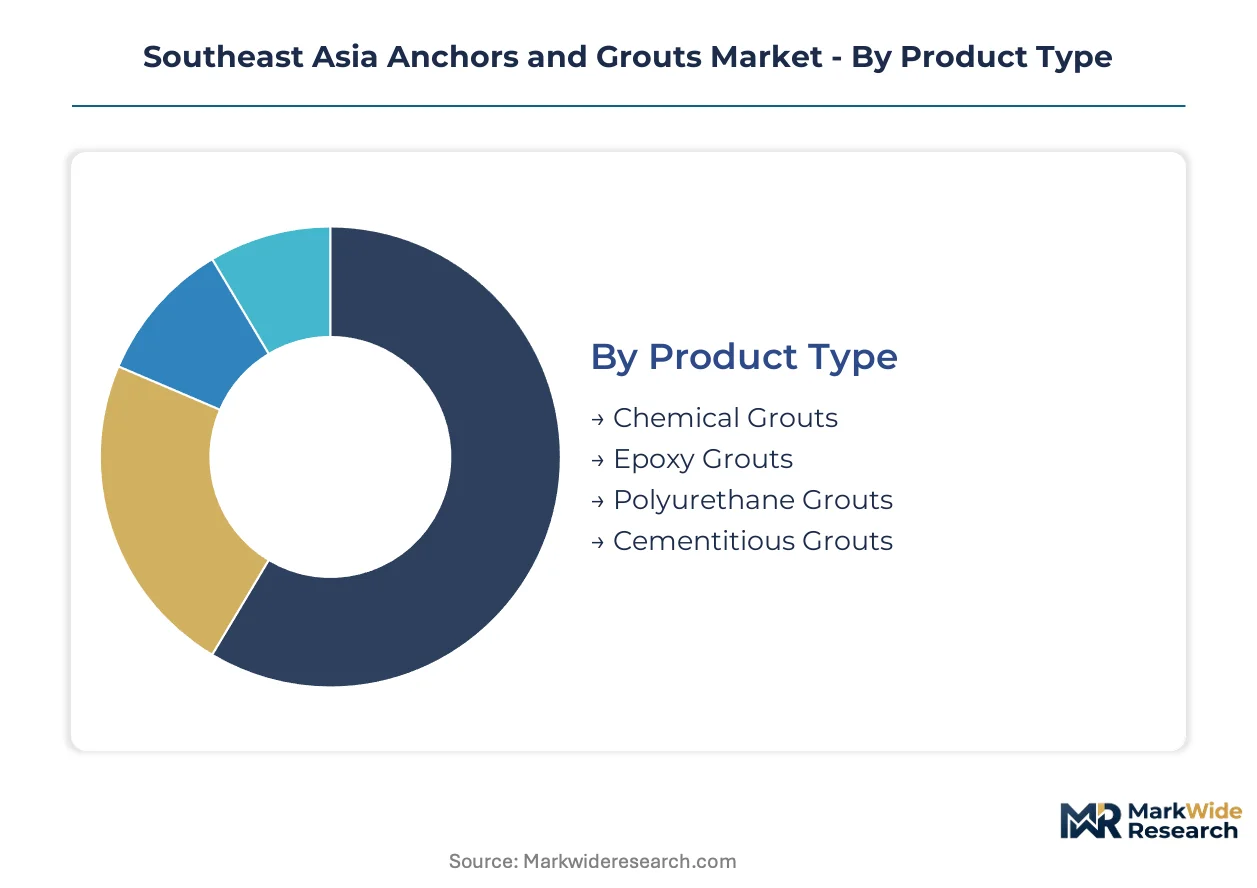
Segmentation in Southeast Asia anchors and grouts reveals how regulatory regimes, project scale, and application complexity fragment procurement patterns. Understanding these divides exposes where specification authority concentrates and which channels capture margin.
Product Type:
Indonesia's SNI standards, Thailand's TISI certification, and Malaysia's CIDB approval schemes create divergent compliance burdens that reshape competitive positioning across formulation categories.
- Chemical Grouts:Low-viscosity injection systems formulated with polyurethane or acrylate resins enable rapid water ingress control in confined underground environments. Demand concentrates in Vietnam's metro expansion and Indonesia's Java corridor tunneling, where continuous pour operations eliminate cure-time delays. These formulations face the steepest regulatory documentation requirements under ASEAN harmonization discussions.
- Epoxy Grouts:Two-component systems achieving compressive strengths exceeding 80 MPa through amine-cured epoxy chemistry. Mining machinery baseplate installations across Thailand and Indonesia specify these for dynamic load tolerance and chemical resistance, though petrochemical feedstock volatility compresses manufacturer margins.
- Polyurethane Grouts:Flexible, expansion-tolerant systems penetrating Malaysia's mountainous highway expansion and Indonesia's volcanic terrain slope stabilization. Tropical thermal cycling performance differentiates these from rigid alternatives.
- Cementitious Grouts:Portland cement-based systems with standard compressive strengths of 30-50 MPa. Cost sensitivity in Philippines and Myanmar residential construction preserves volume dominance despite performance limitations in seismic zones.
Established volume favors cementitious formulations; emerging adoption favors chemical systems.
Application:
Project scale and technical risk determine whether procurement flows through distributor networks or direct manufacturer-contractor relationships.
- Construction:Structural column connections, machinery baseplates, and precast element joining across commercial and industrial builds. Indonesia's dam construction pipeline and Vietnam's high-rise development concentrate specification authority for high-performance systems.
- Slope Stabilization:Rock face anchoring and soil nail applications in Malaysia's highway expansion and Indonesia's volcanic regions. Polyurethane flexibility commands premium positioning where thermal cycling exceeds 30°C diurnal variation.
- Soil Stabilization:Ground improvement and liquefaction mitigation for foundation support. Mekong delta soft-soil conditions in Vietnam and Cambodia drive demand for specialized injection techniques.
- Underwater Applications:Marine structure repair and submerged foundation sealing. Singapore port expansion and Indonesia's archipelago bridge programs require hydrophobic formulation chemistry.
Construction commands the largest absolute spend; slope stabilization exhibits the steepest specification upgrade trajectory.
End User:
Buyer sophistication and warranty exposure create tiered procurement behaviors that fragment supplier access.
- Infrastructure Projects:State-owned construction holding companies and multilateral-financed civil works with mandatory third-party testing. Indonesia's state investor model and Vietnam's metro consortia pilot unbundled procurement separating material supply from technical supervision.
- Commercial Construction:High-rise and industrial facility developers with specification-driven tender processes. Equipment OEM warranty requirements are compressing cementitious grout acceptance in machinery baseplate applications.
- Mining:Extractive operations with extreme chemical exposure and dynamic load conditions. Thailand and Indonesia mining corridors specify epoxy systems for 20-year design life guarantees.
- Residential Construction:Cost-sensitive mid-rise development across Philippines and Myanmar. Procurement favors volume distributors with minimal technical service attachment.
Infrastructure projects concentrate premium formulation demand; residential construction preserves commodity volume.
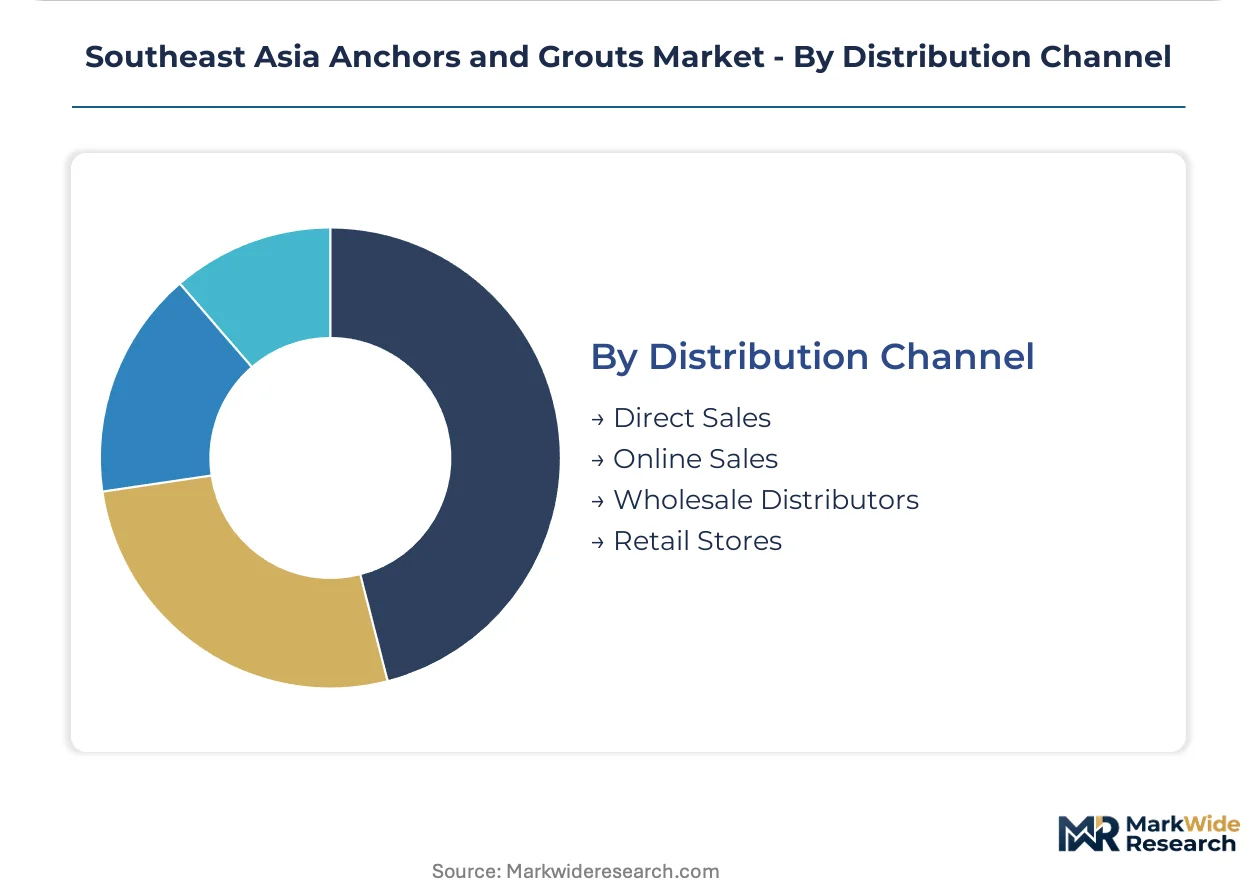
Distribution Channel:
Digital platform integration and certification complexity are compressing traditional distributor markups while fragmenting technical service revenue.
- Direct Sales:Manufacturer-contractor relationships bypassing distributor networks. Thailand's government construction portal and Vietnam's state investor digital tender systems enable this channel for CIDB-preapproved products.
- Wholesale Distributors:Regional stockists with testing capabilities and technical documentation support. Malaysia's CIDB mandates are forcing consolidation among distributors capable of maintaining certification libraries.
- Online Sales:E-procurement platforms for standardized cementitious products with defined specifications. Adoption concentrates in residential construction where application complexity remains low.
- Retail Stores:Local hardware channels for small-scale repair and maintenance applications. Limited penetration beyond residential DIY segments.
Wholesale distributors retain infrastructure project access; direct sales channels are gaining share fastest in government digital tender systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure contractors and state-owned construction holding companies concentrate procurement authority across Southeast Asia, with specification decisions increasingly migrating from distributors to project-level engineering teams capable of validating field performance.
Indonesia
Java corridor dam construction and tunneling projects drive demand for specialized chemical anchoring systems capable of water ingress control. Indonesia's SNI standards mandate independent testing documentation for imported formulations, elevating compliance burdens for foreign suppliers. Jakarta and Bandung industrial zones anchor procurement volume for epoxy grout systems in mining machinery baseplate applications.
Vietnam
Metro expansion in Ho Chi Minh City and Hanoi accelerates adoption of rapid-setting, low-viscosity injection grouts for continuous tunneling operations. The country's state investor digital tender systems enable direct manufacturer-contractor relationships that bypass traditional distributor networks. Mekong delta soft-soil conditions in southern provinces generate specialized ground improvement demand.
Thailand
Mining corridor machinery installations and industrial facility development specify epoxy systems for dynamic load tolerance under equipment OEM warranty requirements. Thailand's TISI certification requirements and government construction portal digitization reshape procurement channels. Eastern Economic Corridor industrial zones concentrate premium formulation demand from Japanese and Korean manufacturing investors.
Malaysia
Mountainous highway expansion and slope stabilization projects favor flexible polyurethane anchoring systems accommodating tropical thermal cycling. CIDB product approval schemes now mandate third-party testing for all imported chemical anchoring systems, creating procurement walled gardens around preapproved product lists. Kuala Lumpur and Penang infrastructure tenders drive specification migration toward polymer-modified alternatives.
Philippines
Cost-sensitive mid-rise residential construction preserves cementitious grout dominance despite seismic performance limitations. The country's national building code enforcement varies across local government units, fragmenting standardization efforts. Metro Manila and Cebu development corridors concentrate volume procurement through distributor networks with minimal technical service attachment.
Southeast Asia Anchors and Grouts Market Competitive Landscape
Player mix skews toward European-headquartered specialty chemical conglomerates with regional manufacturing presence, creating a tiered structure where specification authority concentrates among suppliers capable of embedding application engineers with contractor teams. Three strategic archetypes dominate: Swiss-engineered product portfolio specialists, localized blending facility operators, and technical service-intensive field engineering providers. Competitive moves center on certification library consolidation and digital platform integration to bypass distributor markups.
Within the European-headquartered tier, Sika AG, Mapei SpA, and Fosroc Inc occupy distinct positioning vectors. Sika AG exemplifies the specification-driven infrastructure specialist leveraging Swiss-engineered portfolios to dominate tenders across Thailand and Vietnam. Mapei SpA represents the localized manufacturing archetype, sustaining regional presence through blending facilities that reduce import duty exposure. Fosroc Inc anchors the technical service-intensive position, competing through embedded application engineers deployed directly with contractor teams on major civil projects.
| Leading Market Players |
|---|
| Sika AG |
| Mapei SpA |
| Bostik |
| Fosroc Inc |
| Saint-Gobain Weber |
| MBCC Group |
| Henkel AG & Co KGaA |
| Laticrete International Inc |
| GCP Applied Technologies Inc |
| Others |
Value Network & Pricing Analysis
Project-based procurement contracts with epoxy resin indexation lock in supply access for Indonesian dam contractors while exposing margins to petrochemical feedstock swings. These arrangements tie material costs to regional naphtha benchmarks, forcing blenders to hedge or absorb volatility on Java corridor tunnel projects.
Pricing Analysis
Cost-plus contracts with naphtha-indexed adjustments dominate epoxy grout procurement for Thai mining machinery installations. Three-tier pricing structure across CIDB-certified premium, TISI-compliant standard, and uncertified economy levels reflects documentation burden differentiation. Price erosion runs through cementitious tiers as Philippine residential developers squeeze distributor margins. Infrastructure projects show lowest price sensitivity; mid-rise Myanmar construction exhibits highest.
Supply Chain Analysis
Singapore Port congestion periodically chokes amine hardener deliveries to Vietnamese metro contractors, extending lead times for rapid-setting injection systems. European and Japanese sources feed specialty additives to Thailand and Indonesia blending facilities, creating single-source vulnerability for rheology modifiers. Distribution runs through CIDB-certified wholesale distributors in Malaysia and direct digital tender platforms in Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist application engineers capable of high-pressure injection in confined tunnel environments represent the scarcest capability layer, constraining project scaling across Vietnam and Indonesia regardless of material availability.
For Market Incumbents: Secure CIDB certification libraries across multiple ASEAN jurisdictions to defend specification-driven tenders from emerging technical service providers. Backward integration into amine hardener sourcing mitigates petrochemical volatility exposure on Thai mining contracts. Capacity addition in Vietnam's Eastern Economic Corridor captures Japanese manufacturing investor demand. For New Entrants and Emerging Players: Technical supervision unbundling from material supply creates white-space for independent field engineering consultancies serving Indonesian state-owned construction holding companies. Cambodia and Laos hydropower projects offer most penetrable geography given absent local supply chains. Go-to-market through e-procurement platform integration bypasses established distributor markups. For Investors and Strategic Acquirers: Regional blending facilities with SNI-TISI-CIDB preapproval status represent the most defensible acquisition archetype as regulatory documentation burdens intensify. Long-term viability hinges on certification library depth rather than formulation differentiation alone. Watch ASEAN Economic Community mutual recognition progress as inflection signal for cross-border sourcing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Library Expansion | CIDB preapproval unlocks Malaysian infrastructure tender participation against unqualified rivals. |
| Backward Integration into Additives | Captive amine hardener production insulates Thai blenders from Japanese supply shocks. |
| Digital Platform Integration | Direct supplier-contractor relationships through Vietnam's state investor portal eliminate distributor markups. |
| Technical Service Unbundling | Independent field engineering retainers capture fragmented service revenue from material suppliers. |
| Hybrid Formulation Development | Polyurethane-epoxy systems displace pure epoxy in Indonesian mining baseplate specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at Indonesian dam contractors, technical R&D directors at regional blending facilities, and channel partners in Malaysia's CIDB certification ecosystem; and secondary validation through customs and trade data, ASEAN construction tender databases, SNI-TISI-CIDB regulatory filings, and SEC disclosures from listed specialty chemical conglomerates. Bottom-up project pipeline enumeration triangulated against top-down formulation demand estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, application complexity, end-user sophistication tier, and distribution channel digitization maturity. CAGRs derived from regression against historical infrastructure investment cycles and petrochemical feedstock correlation patterns. Industry-specific inputs included tunneling project completion rates in Vietnam's metro expansion and CIDB approval timeline distributions.
Underlying assumptions cover sustained ASEAN infrastructure investment commitment and stable naphtha pricing correlation, with deviation risk concentrated in regulatory harmonization delays and application engineer wage inflation. Practitioners should keep alternative scenarios live as ASEAN Economic Community mutual recognition arrangements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Europe Facade Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Structural Lightweight Concrete Market