
 Prestressed High Strength Concrete Pipe Pile Market | 2026-2036
Prestressed High Strength Concrete Pipe Pile Market Size, Share, and Industry Trends Forecast 2026-2036
Prestressed High Strength Concrete Pipe Pile Market Insights
Asian prestressed concrete manufacturers is broadening production capacity to serve marine foundation contracts across the Pacific Rim. Taiheiyo Cement Corporation leverages its integrated cement-to-pile supply chain to control raw material costs for offshore projects. Oldcastle Infrastructure Inc. anchors its competitive stance through specialized spun pipe production for North American bridge supports. PT Wijaya Karya Beton Tbk dominates Southeast Asian procurement channels for port authority contracts in Indonesia.
Prestressed high strength concrete pipe piles are cylindrical structural elements manufactured with high-tensile steel tendons tensioned before concrete curing, typically achieving compressive strengths exceeding 80 MPa to withstand axial and lateral loads in aggressive soil or marine environments. Their primary purpose is to transfer structural loads from buildings, bridges, and offshore platforms through weak surface soils into deeper, stable bearing strata. Spun pipes command the largest share of product type revenue due to mature centrifugal casting infrastructure and proven performance in saltwater immersion. Marine foundations represent the fastest-expanding application segment as offshore wind installations multiply. Driving remains the dominant installation method, though hydraulic pushing gains share in urban environments where vibration restrictions apply.
China's MEE enforces GB standards for marine concrete durability that mandate sulfate-resistant cement blends and chloride permeability thresholds for pipe piles in tidal zones. Japan's METI coordinates JIS standards with coastal resilience codes requiring enhanced flexural capacity for earthquake-prone subduction zones. The EU F-Gas Regulation indirectly shapes demand by accelerating offshore wind targets that rely on prestressed pile foundations. Stakeholders must monitor how carbon border adjustments and embodied-carbon disclosure rules reshape sourcing decisions for cement and steel reinforcement inputs.
Market Dynamics
Offshore wind farm developers are consolidating foundation procurement around prestressed pipe piles, compressing supplier qualification timelines and reshaping manufacturing capacity allocation across coastal Asia.
Growth Catalysts
- Offshore wind targets:China's dual carbon goals mandate gigawatt-scale turbine installations requiring prestressed pile foundations in Bohai Bay and Guangdong coastal zones.
- GB standards enforcement:China's MEE mandates sulfate-resistant cement blends and chloride permeability thresholds for marine concrete durability in tidal construction.
- Bridge megaproject pipelines:Port expansion and cross-sea link projects in Fujian and Zhejiang provinces sustain volume demand for spun pipe production.
Market Restraints
- Steel tendon volatility:High-tensile prestressing steel prices fluctuate with scrap metal and energy input costs, compressing margin visibility for manufacturers.
- Supply concentration:Coastal China hosts over 70% of spun pipe centrifugal casting infrastructure, creating geographic risk for Pacific Rim project timelines.
- Cast-in-place substitution:Bored pile techniques with post-tensioned segments threaten prestressed pipe share in onshore building foundations where vibration limits are absent.
Strategic Opportunities
- Southeast Asian port authorities:Indonesia's Trans-Java toll road and new container terminal projects in Batam and Makassar lack domestic spun pipe capacity.
- Hydraulic pushing adoption:Urban metro and rail projects in Tokyo and Osaka are specifying vibration-free installation methods for dense commercial districts.
- EU F-Gas Regulation acceleration:Offshore wind targets in the North Sea and Baltic are pulling Asian pile manufacturers into European foundation supply chains.
Industry Challenges
- Marine concrete certification timelines:GB standard compliance for chloride diffusion coefficients requires 90-day testing cycles that delay project mobilization.
- Spun pipe transport logistics:Cylindrical pile dimensions exceed standard flatbed capacity, requiring specialized vessel chartering for island and offshore deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prestressed High Strength Concrete Pipe Pile Market |
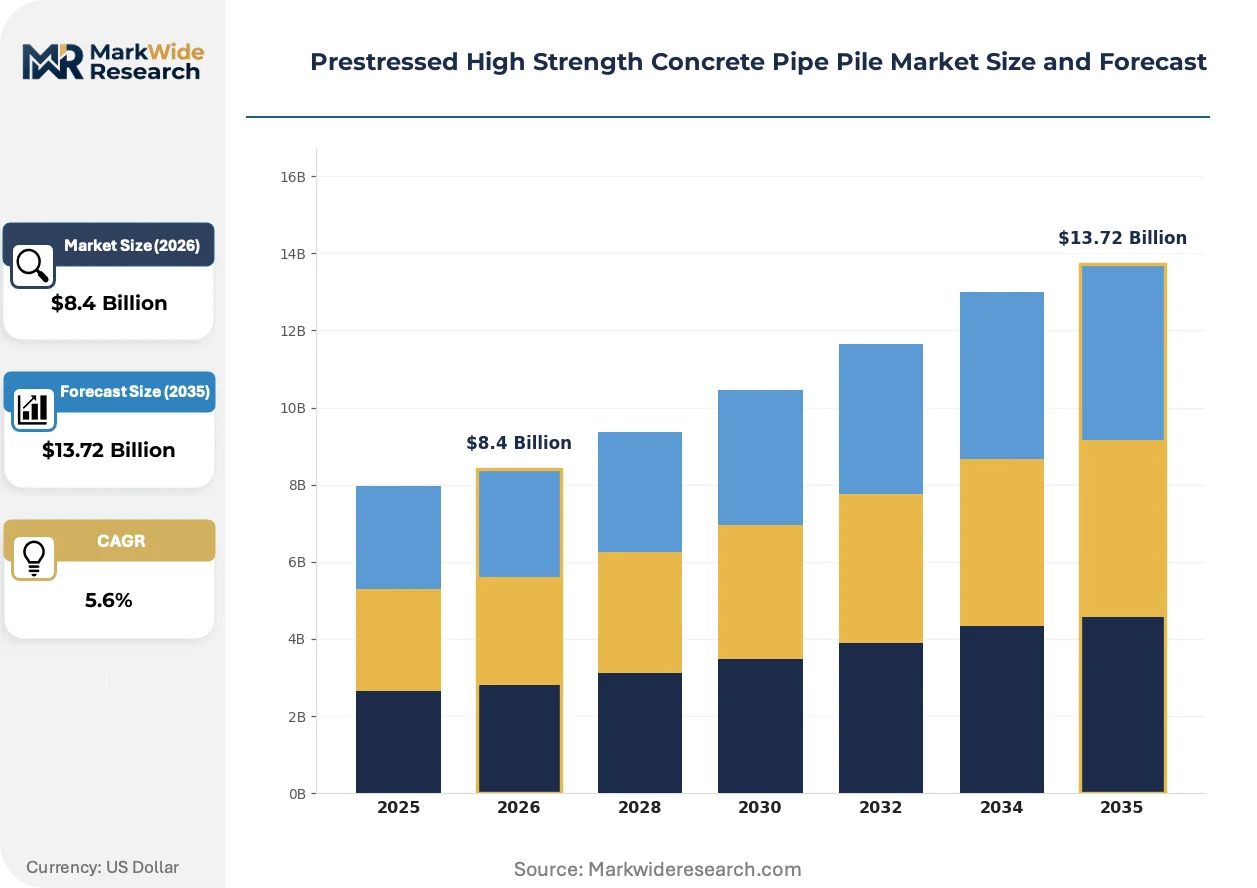
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spun Pipes, Segmental Pipes, Other Pipelines, Monolithic Pipes, Jacked Pipes Application: Marine Foundations, Bridge Supports, Building Footings, Offshore Platforms, Retaining Walls Installation Method: Driving, Boring, Pressing, Jetting, Vibratory, Hydraulic Pushing End User Industry: Construction Contractors, Infrastructure Developers, Energy Extractors, Port Authorities, Heavy Engineering Firms |
| Companies Covered | Taiheiyo Cement Corporation, Oldcastle Infrastructure Inc., PT Wijaya Karya Beton Tbk, Industrial Concrete Products Sdn Bhd, Ningxia Qinglong Pipes Industry Co. Ltd., AMACCAO Concrete Joint Stock Company, VCON Thai Company Limited, Jianhua Construction Materials Group Limited, PCM Construction Materials Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prestressed High Strength Concrete Pipe Pile Market Trends and Innovations
Material science advances and installation method evolution are compressing foundation project schedules while raising performance specifications for aggressive marine exposure.
Ultra-high performance concrete (UHPC) jacketing is rewriting durability expectations for prestressed pipe piles in splash zones. Offshore wind EPC contractors in the Yellow Sea and East China Sea are specifying UHPC overlays for turbine monopile transition pieces. This material convergence is compressing maintenance intervals and extending design life assumptions for substructure assets.
Japan's METI has coordinated revised JIS standards with coastal resilience codes requiring enhanced flexural capacity for earthquake-prone subduction zones. The updated frameworks mandate performance-based design verification for lateral load resistance. Foundation engineers in Kansai and Tohoku regions are recalculating pile section properties to meet the new seismic ductility thresholds.
Buyers are consolidating annual pile procurement into multi-year framework agreements with volume guarantees and fixed-price escalators. Port authority clients in China and Indonesia are displacing spot-market purchasing with integrated supply contracts that bundle manufacturing, transport, and installation supervision. This contractual shift is most visible in Bohai Rim port clusters where project pipelines extend through 2030.
Prestressed High Strength Concrete Pipe Pile Market Segmentation
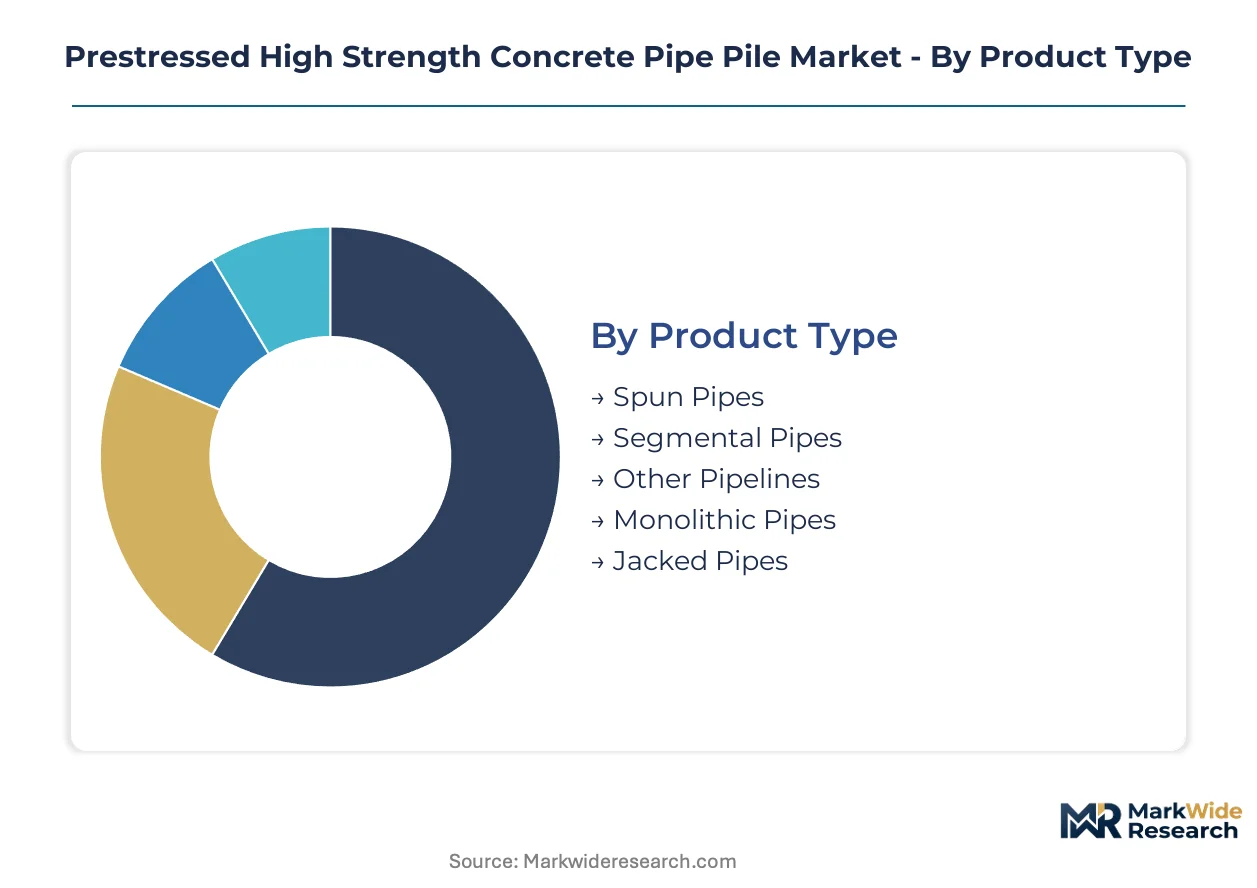
Prestressed pipe pile procurement patterns diverge sharply across product specifications, installation constraints, and end-user risk profiles. Understanding these segment boundaries clarifies where capital deployment yields highest returns for manufacturers and where project delays concentrate for contractors.
Product Type:
Centrifugal casting infrastructure demands the heaviest upfront capital outlay among manufacturing configurations, locking in competitive moats for incumbent producers.
- Spun Pipes:Manufactured through high-speed centrifugal casting that densifies concrete matrix and aligns steel tendons circumferentially. Bohai Rim port clusters and Guangdong coastal zones absorb the majority of output for offshore wind monopile foundations where saltwater immersion resistance is mandatory.
- Segmental Pipes:Assembled from precast cylindrical sections with post-tensioned joints, enabling transport of oversized diameters in modular components. Bridge megaprojects in Fujian and Zhejiang provinces specify these for cross-sea viaducts where monolithic casting logistics fail.
- Other Pipelines:Encompasses hybrid configurations and specialty geometries for non-standard load cases in industrial facility foundations.
- Monolithic Pipes:Cast as single continuous units for maximum structural integrity in deep-water applications.
- Jacked Pipes:Engineered for microtunneling installations beneath existing infrastructure without surface disruption.
Most installed capacity flows through Spun Pipes. Expansion is steepest in Segmental Pipes.
Application:
Load-bearing requirements and environmental exposure severity determine specification tiers across project types.
- Marine Foundations:Offshore wind EPC contractors in the Yellow Sea and East China Sea specify prestressed piles for turbine substructures. METI-coordinated JIS standards and China's MEE GB durability mandates are compressing supplier qualification timelines for this segment.
- Bridge Supports:Cross-sea link projects demand high flexural capacity for ship impact and seismic lateral loads. Japan's coastal resilience codes are recalibrating pile section properties in Kansai and Tohoku regions.
- Building Footings:Urban high-rise foundations in dense commercial districts where vibration limits constrain installation methods.
- Offshore Platforms:Oil and gas extraction infrastructure requiring corrosion-resistant specifications for decades-long service life.
- Retaining Walls:Coastal and waterfront stabilization projects with combined axial and earth pressure loading.
Marine Foundations command premium pricing tiers. Building Footings face the strongest substitution pressure from cast-in-place alternatives.
Installation Method:
Equipment specialization and site access constraints fragment contractor capabilities across techniques.
- Driving:Conventional impact hammer installation dominates open-water and rural construction where vibration restrictions are absent.
- Boring:Auger and rotary techniques for soil conditions where pile refusal risks damage driven elements.
- Pressing:Static load application for sensitive urban environments with strict noise ordinances.
- Jetting:High-pressure water assistance in dense sands where penetration resistance exceeds hammer capacity.
- Vibratory:Oscillatory insertion for granular soils with reduced ground disturbance compared to impact driving.
- Hydraulic Pushing:Metro and rail projects in Tokyo and Osaka are specifying this vibration-free method for dense commercial districts where structural damage liability is acute.
Driving retains the largest equipment fleet base. Hydraulic Pushing is gaining specification share fastest in urban contracts.
End User Industry:
Procurement sophistication and contract duration vary systematically across buyer categories.
- Construction Contractors:Project-specific purchasing with spot-market pricing sensitivity and tight mobilization schedules.
- Infrastructure Developers:Long-horizon pipeline owners consolidating annual pile procurement into multi-year framework agreements with volume guarantees.
- Energy Extractors:Offshore wind and oil and gas operators with stringent certification requirements and extended design life specifications.
- Port Authorities:Bohai Rim and Indonesian terminal operators displacing spot purchasing with integrated supply contracts bundling manufacturing, transport, and installation supervision.
- Heavy Engineering Firms:Specialized foundation contractors with captive installation fleets and direct manufacturing relationships.
Port Authorities anchor volume demand through 2030. Energy Extractors are compressing supplier qualification timelines most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is pulling manufacturing capacity toward jurisdictions with streamlined marine concrete certification timelines, even as end-use demand clusters in coastal megaproject zones with stricter durability mandates. Producers face a compliance-cost gap between markets that reward rapid project mobilization and those that enforce extended testing protocols.
China
Offshore wind foundations in Bohai Bay and Guangdong coastal zones absorb the majority of regional spun pipe output. The Ministry of Ecology and Environment enforces GB standards mandating sulfate-resistant cement blends and chloride permeability thresholds for tidal zone construction. Ningxia Qinglong Pipes Industry anchors northwestern supply chains serving port expansion projects along the Yellow Sea rim.
Japan
Earthquake-prone subduction zones in Kansai and Tohoku regions drive specification upgrades for enhanced flexural capacity in bridge supports. METI coordinates revised JIS standards with coastal resilience codes requiring performance-based design verification for lateral load resistance. Taiheiyo Cement Corporation leverages integrated cement-to-pile supply chains to control raw material costs for offshore wind monopile contracts in the East China Sea.
Indonesia
Trans-Java toll road development and container terminal projects in Batam and Makassar outstrip domestic spun pipe manufacturing capacity. Port authority procurement is consolidating into multi-year framework agreements with volume guarantees displacing spot-market purchasing. PT Wijaya Karya Beton Tbk dominates procurement channels for terminal operator contracts across the archipelago.
Vietnam
Coastal infrastructure expansion in Hai Phong and Da Nang is accelerating demand for prestressed pile foundations in port deepening and bridge construction. AMACCAO Concrete Joint Stock Company exemplifies regional fabricators expanding centrifugal casting capacity to capture marine foundation contracts. The country's national construction regulator is aligning local standards with ASEAN harmonization protocols for marine concrete durability.
United States
Bridge rehabilitation and hurricane-resistant coastal construction in Florida and Gulf Coast states is specifying prestressed pipe piles for enhanced lateral load performance. Oldcastle Infrastructure Inc. anchors North American competitive positioning through specialized spun pipe production for transportation authority contracts. EPA stormwater management guidelines are indirectly shaping foundation specifications for resilient infrastructure design.
Prestressed High Strength Concrete Pipe Pile Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue marine foundation specialization and vibration-free installation method integration. The vendor base stratifies across three maturity levels: integrated cement-pile conglomerates with captive raw material supply, regional specialists with coastal casting infrastructure, and project-specific fabricators serving spot-market construction demand. Dominant competitive moves include backward integration into cement production and strategic partnerships with offshore wind EPC contractors for qualification acceleration.
Among Asia-Pacific fabricators, Taiheiyo Cement Corporation and PT Wijaya Karya Beton Tbk represent contrasting archetypes of integrated supply chain control versus regional procurement channel dominance. Oldcastle Infrastructure Inc. occupies a position exemplifying North American specialization in transportation infrastructure applications. These three anchors illustrate how geographic production clustering and end-use segment focus shape competitive positioning without requiring uniform scale or technology profiles.
| Leading Market Players |
|---|
| Taiheiyo Cement Corporation |
| Oldcastle Infrastructure Inc. |
| PT Wijaya Karya Beton Tbk |
| Industrial Concrete Products Sdn Bhd |
| Ningxia Qinglong Pipes Industry Co. Ltd. |
| AMACCAO Concrete Joint Stock Company |
| VCON Thai Company Limited |
| Jianhua Construction Materials Group Limited |
| PCM Construction Materials Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Centrifugal casting technicians concentrated in coastal Jiangsu and Zhejiang provinces command wage premiums that compress margin spreads between standard and premium pile tiers. Labor-cost differentials between these specialized manufacturing clusters and inland fabrication zones drive pricing-tier spreads that favor integrated producers with captive workforce development programs.
Pricing Analysis
Distributor markups on project-specific marine foundation contracts absorb margin layers that direct-to-port-authority agreements bypass entirely. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified marine durability piles from general infrastructure grades and spot-market construction lots. Pricing pressure stems from high-tensile prestressing steel volatility feeding into raw material cost escalators. Port authorities exhibit lowest price sensitivity due to multi-year framework guarantees, while construction contractors face acute spot-market pressure.
Supply Chain Analysis
Workforce availability for certified welders and centrifugal casting operators tightens most acutely in Bohai Rim manufacturing zones, constraining capacity expansion timelines. Supply concentrates in China, Japan, and Indonesia, with over seventy percent of spun pipe centrifugal casting infrastructure anchored in coastal Chinese provinces. Raw material dependencies center on high-grade Portland cement, high-tensile steel tendons, and sulfate-resistant admixtures. Single-source vulnerability from scrap metal price volatility threatens margin stability. Distribution runs through specialized heavy-lift vessel chartering for island and offshore deliveries, bypassing standard flatbed logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with China's MEE GB durability mandates for marine concrete creating irreversible specification upgrades that lock in premium-tier demand.
For Market Incumbents: Acquire captive cement production capacity to insulate margin structures from energy-input volatility in clinker manufacturing. Secure long-term offtake agreements with Bohai Rim offshore wind EPC contractors before qualification timelines compress further. Cast-in-place bored pile substitution in onshore building foundations threatens volume share; counter through certification investment in vibration-free hydraulic pushing installation methods.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium marine-certified piles and economy-grade construction lots offers white-space entry for regional fabricators with coastal casting infrastructure. Target Indonesia's Trans-Java toll road and Batam container terminal projects where domestic spun pipe capacity falls short of port authority procurement timelines. Penetrate through multi-year framework bidding that bundles manufacturing with installation supervision, displacing spot-market purchasing patterns.
For Investors and Strategic Acquirers: Offshore wind developers are the most active acquirer in this space, consolidating foundation supply chains through equity stakes in pile manufacturers to accelerate project mobilization. Long-term viability rests on exposure to marine foundation segments where GB and JIS certification barriers sustain margin premiums. Monitor chloride diffusion coefficient testing cycle delays as the inflection signal for supply-constraint pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cement Production | Captive clinker supply shields Taiheiyo Cement Corporation from energy-input cost spikes. |
| Multi-Year Framework Agreement | Port authority contracts in Bohai Rim displace spot purchasing with volume-guaranteed pricing. |
| Marine Concrete Certification Investment | GB standard compliance for chloride permeability accelerates supplier qualification for MEE tidal zone mandates. |
| Hydraulic Pushing Installation Method | Tokyo metro projects specify vibration-free pile insertion for dense commercial district liability control. |
| Geographic Capacity Expansion | Indonesian fabricators capture Trans-Java toll road demand exceeding domestic spun pipe output. |
Research Methodology
Direct dialogue with offshore wind EPC procurement directors, port authority engineering managers, centrifugal casting plant operators, and marine foundation design consultants grounded qualitative assessment in operational reality. Secondary validation drew from customs trade databases for prestressed concrete pile exports, MEE GB standard enforcement bulletins, METI JIS revision notices, and SEC filings of integrated cement-pile conglomerates. Bottom-up project pipeline enumeration triangulated against top-down regional infrastructure budget allocations.
Segment-level value outputs calibrated product type splits across spun pipe, segmental pipe, and monolithic configurations against installation method adoption curves for driving, hydraulic pushing, and vibratory techniques. Modeled dimensions spanned application segments from marine foundations through bridge supports to building footings, crossed with end-user industry procurement sophistication tiers. CAGRs derived from regression of historical project award volumes against regulatory milestone implementation schedules, with offshore wind capacity targets and port expansion pipelines as primary demand drivers.
Caveats apply where steel tendon price volatility, 90-day marine concrete certification delays, or cast-in-place substitution acceleration could materially shift the outlook. Forecasts embed assumptions on GB standard enforcement continuity and dual carbon goal persistence. Material deviation in scrap metal input costs or MEE testing protocol revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Europe Facade Market