
 Concrete Slabs Market | 2026-2036
Concrete Slabs Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Slabs Market Outlook
REACH compliance is broadening the cost-of-entry calculus for concrete slab producers serving European projects. Holcim leverages its vertically integrated cement-to-precast chain to manage embodied carbon reporting across multiple jurisdictions. CEMEX anchors its position through R&D intensity in ultra-high performance concrete formulations. Heidelberg Materials specializes in hollow core slab production with optimized thermal mass properties for commercial building specifications.
Concrete slabs are flat, horizontal structural elements cast from cementitious binders, aggregates, and reinforcement, typically spanning 100-400 mm in thickness depending on load requirements and spanning distance. They function as primary floor and roof systems that transfer live and dead loads to supporting beams, columns, and walls. Precast slabs capture dominant share in infrastructure and commercial verticals due to accelerated construction schedules and controlled factory curing conditions. Hollow core slabs represent the fastest-expanding product category as voided cross-sections reduce material volume while maintaining structural capacity. Composite slabs combining steel decking with cast-in-place concrete command premium positioning in multi-story commercial buildings where fire ratings and long spans are specified.
The US EPA and OSHA frameworks govern emissions and workplace exposure in precast manufacturing facilities, while the EU Green Deal's embodied carbon thresholds are redirecting specification decisions toward low-clinker concrete mixes. China's MIIT enforces GB standards for structural concrete performance that directly constrain slab design parameters in building codes. Stakeholders must monitor regulatory divergence between carbon accounting methodologies as this will determine which material technologies achieve cross-border project eligibility.
Market Dynamics
Embodied carbon compliance is compressing specification windows across commercial construction, forcing producers to requalify mixes for EU Green Deal thresholds and diverting R&D budgets from mechanical performance to environmental accounting.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Commercial developers in Germany and France now mandate Environmental Product Declarations for slab procurement, pulling low-clinker precast systems into specification pipelines.
- Hollow core voiding technology:Automated extrusion lines in India and Brazil are cutting material volumes by 30-40% while maintaining span ratings, accelerating factory-to-site logistics in high-rise residential towers.
- China's MIIT dual carbon enforcement:Provincial building codes in Jiangsu and Guangdong now penalize high-carbon slab specifications, redirecting public infrastructure budgets toward certified precast suppliers.
Market Restraints
- Portland cement price volatility:Energy costs and clinker import restrictions in Turkey and Egypt are compressing precast margins, with some producers shifting to blended binder systems that require costly re-certification.
- Specialized prestressing strand supply:Three European wire rod mills control 70% of high-tensile strand capacity for hollow core production, creating bottleneck risk during infrastructure stimulus cycles.
- Cross-laminated timber substitution:Mid-rise commercial developers in Scandinavia and the Pacific Northwest are specifying mass timber floor systems for sub-12 meter spans, displacing composite concrete slabs in sustainability-marketed projects.
Strategic Opportunities
- Carbon capture curing integration:Precast producers in Alberta and Texas are piloting CO2 mineralization chambers that lock emissions into slab surfaces, creating differentiated products for LEED v4.1 and BREEAM-NC procurement.
- Modular data center construction:Hyperscale cloud operators in Northern Virginia and Frankfurt are specifying precast slab mezzanines with integrated cable management voids, opening a specification channel outside traditional building verticals.
- India's Smart Cities Mission infrastructure:Metro rail depots and bus rapid transit terminals in Pune and Hyderabad are deploying precast platform slabs with embedded RFID for lifecycle tracking, creating anchor demand for digitized production lines.
Industry Challenges
- EPD verification timeline compression:Third-party carbon accounting for slab product categories now requires 12-18 month dataset collection, delaying market entry for reformulated low-emission mixes.
- Prestressing tendon placement automation:Hollow core production lines lack standardized robotic tendon threading systems, constraining throughput scaling and creating quality variance across shift patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Slabs Market |
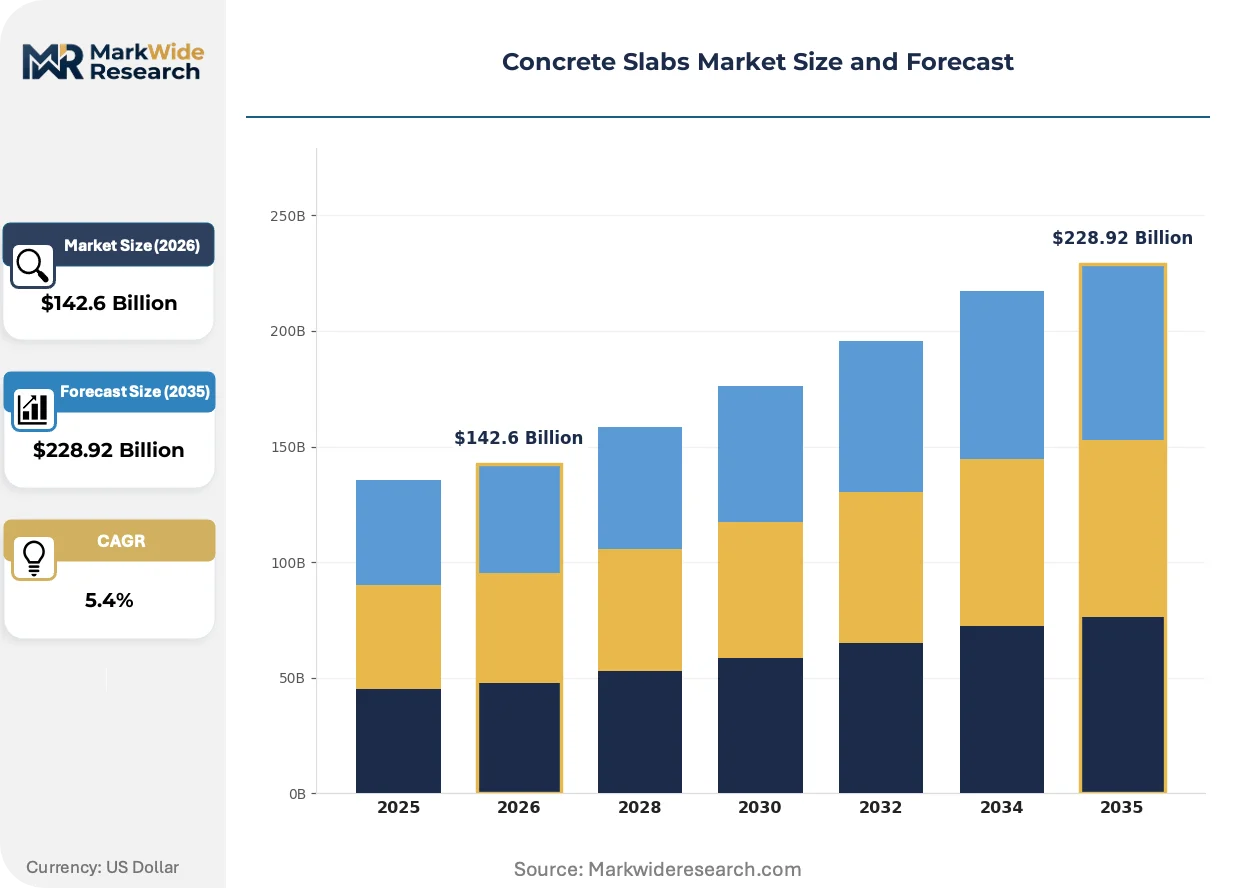
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $228.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precast Slabs, Hollow Core Slabs, Solid Slabs, Composite Slabs End User: Residential Construction, Commercial Buildings, Infrastructure Development, Industrial Facilities Material: Reinforced Concrete, Lightweight Concrete, Ultra-High Performance Concrete, Normal Strength Concrete Thickness: Thin Slabs, Medium Slabs, Thick Slabs, Custom Thickness |
| Companies Covered | Holcim, CEMEX, CRH, Oldcastle Infrastructure, Heidelberg Materials, Keegan Precast Ltd, Leesburg Concrete Co., Precast New Zealand Inc., U.S. Concrete Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Slabs Market Strategic Shifts
Carbon accounting digitization is rewiring how slab producers compete, with environmental data transparency becoming as decisive as structural performance in specification battles across institutional and commercial verticals.
Electrified curing systems using resistive heating elements embedded in casting beds are electrifying production energy profiles at precast facilities in Denmark and the Netherlands. Industrial developers with Science Based Targets initiative commitments are prioritizing slab suppliers with verified renewable electricity inputs. This technology is compressing the payback period for factory decarbonization investments from seven years to under four.
REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing reformulation of release agents and surface retarders used in exposed aggregate finishes. German and Dutch precasters are qualifying bio-based alternatives through ECHA-registered safety data sheets. The commercial facade segment is absorbing these compliance costs through specification premiums for certified clean chemistry.
Integrated project delivery contracts are consolidating slab procurement decisions under general contractor risk pools, displacing traditional architect-specified product selection. Multi-story residential developers in Sydney and Melbourne are bundling structural frame and MEP rough-in through design-build entities. This concentration is visible most acutely in Australia, where tier-one contractors now control 60% of precast slab specification authority on projects above 10,000 square meters.
Concrete Slabs Market Segmentation
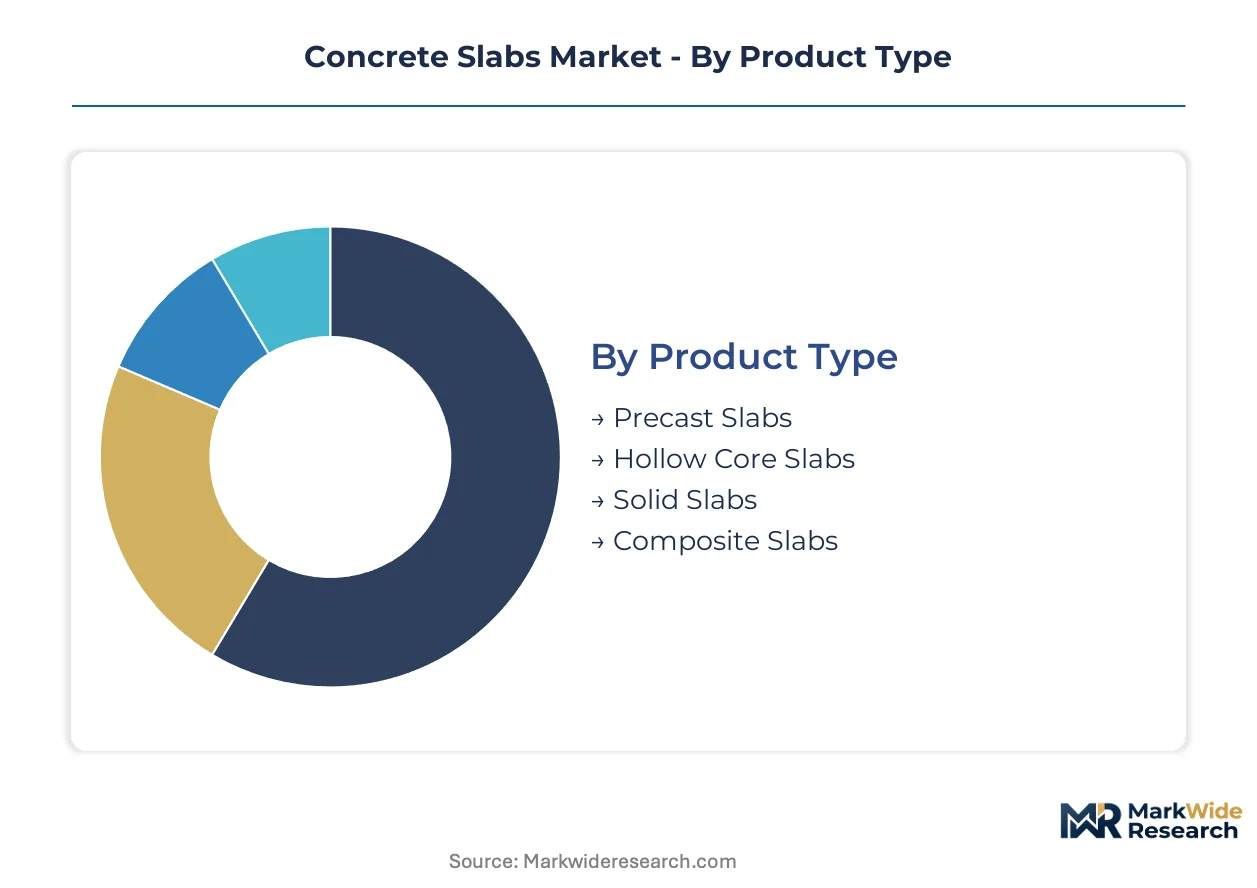
Segmentation in concrete slabs reveals how specification authority flows through distinct procurement channels. Product type determines factory capital requirements and logistics radius. End-user verticals impose divergent performance certifications and carbon accounting standards. Material and thickness selections increasingly trace back to embodied carbon thresholds rather than pure structural engineering.
Product Type:
Contractors select slab systems based on span requirements, crane availability, and schedule compression needs.
- Precast Slabs:Factory-cast elements with controlled curing deliver consistent strength ratings and accelerate site installation timelines. Demand concentrates in German and French commercial developments where EU Green Deal procurement rules favor Environmental Product Declaration documentation from centralized production facilities.
- Hollow Core Slabs:Longitudinal voids reduce self-weight by 30-40% while maintaining load-bearing capacity through prestressed strand integration. Indian and Brazilian high-rise residential towers specify these systems for floor plates above 15 stories where material efficiency directly impacts structural steel tonnage.
- Solid Slabs:Monolithic cross-sections provide maximum fire resistance and acoustic dampening for healthcare and educational facilities.
- Composite Slabs:Steel decking bonded to cast-in-place concrete enables long-span commercial floors without temporary propping.
Volume sits with precast systems; growth tilts toward hollow core technology.
End User:
Vertical-specific certification requirements and carbon disclosure obligations steer procurement toward qualified supplier pools.
- Residential Construction:Multi-family developers in São Paulo and Mumbai specify hollow core floor systems for repetitive tower typologies where speed-to-market determines financing costs. India's Smart Cities Mission infrastructure anchors demand for standardized slab dimensions across mass housing schemes.
- Commercial Buildings:Office and retail developers in Frankfurt and Northern Virginia prioritize composite slabs with integrated MEP routing for flexible lease configurations. Hyperscale data center operators are emerging as a distinct specification channel for precast mezzanine systems.
- Infrastructure Development:Metro rail platforms and airport terminals demand high-durability surfaces with embedded asset tracking.
- Industrial Facilities:Manufacturing floors require impact-resistant surfaces with load ratings exceeding standard commercial specifications.
Residential captures the largest project count; commercial buildings generate the highest value per square meter.
Material:
Binder chemistry and aggregate selection now dominate prequalification conversations as embodied carbon thresholds harden across procurement frameworks.
- Reinforced Concrete:Conventional steel-bar reinforcement within Portland cement matrices remains the default for cost-sensitive infrastructure tenders. Chinese provincial building codes in Jiangsu and Guangdong now penalize high-clinker mixes, redirecting public budgets toward certified low-carbon suppliers.
- Ultra-High Performance Concrete:Dense microstructures with fiber reinforcement achieve slender cross-sections and extended durability for aggressive environments. Danish and Dutch bridge specifications are adopting UHPC deck panels where lifecycle cost analysis overrides first-cost premiums.
- Lightweight Concrete:Expanded clay or shale aggregates reduce structural dead load for seismic zones and long-span applications.
- Normal Strength Concrete:Standard-grade mixes serve non-structural applications and temporary works where performance margins exceed demand.
Reinforced concrete maintains volume dominance; ultra-high performance formulations are climbing the fastest.
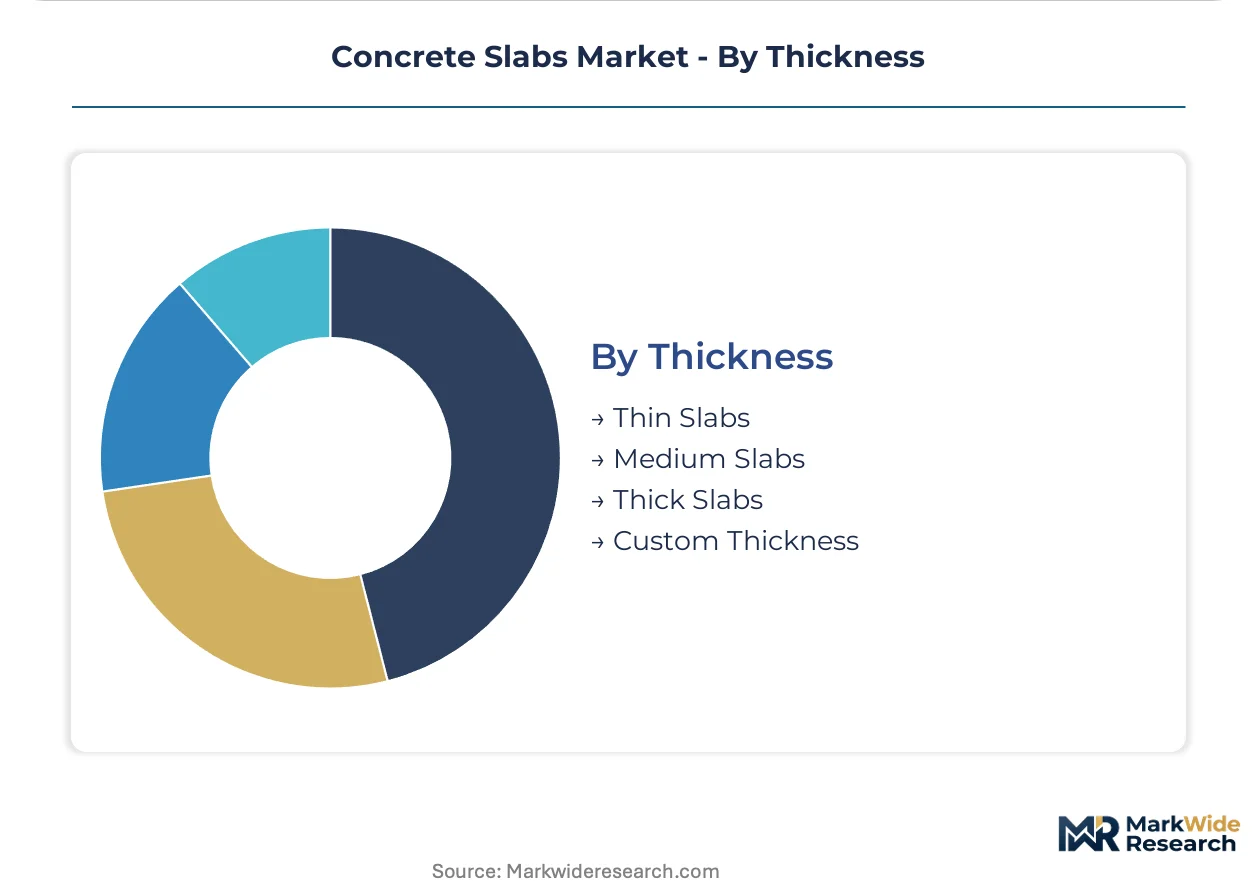
Thickness:
Span-to-depth ratios and imposed load calculations determine slab selection within structural engineering workflows.
- Medium Slabs:150-250mm sections balance material economy with acoustic and fire performance for standard office and residential floors. Australian design-build contractors specify medium-thickness precast elements for projects above 10,000 square meters where procurement authority has consolidated under tier-one builders.
- Thick Slabs:Sections exceeding 300mm accommodate heavy industrial loads and parking garage wear surfaces with minimal maintenance. German automotive manufacturing facilities specify thick post-tensioned slabs for assembly line foundations with precise level tolerances.
- Thin Slabs:100-150mm systems serve residential renovations and light commercial fit-outs with restricted floor-to-floor heights.
- Custom Thickness:Project-specific dimensions address unique span conditions or integration requirements for specialized MEP configurations.
Medium thickness commands the highest shipment volumes; thick slabs generate premium pricing in industrial verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for concrete slabs concentrates in China, India, Germany, Brazil, and the United States, where urbanization and infrastructure renewal are redirecting procurement toward precast and hollow core systems. National building codes and carbon disclosure frameworks are fragmenting specification standards across these markets.
China
Provincial infrastructure budgets in Jiangsu and Guangdong are prioritizing certified low-carbon precast suppliers as MIIT dual carbon enforcement tightens embodied carbon thresholds. GB standards for structural concrete performance now directly constrain slab design parameters in building codes. Factory clusters in the Yangtze River Delta are scaling automated hollow core extrusion lines to serve high-rise residential towers in Shanghai and Nanjing.
Germany
Commercial developers in Frankfurt and Munich now mandate Environmental Product Declarations for slab procurement, pulling low-clinker precast systems into specification pipelines. EU Green Deal embodied carbon thresholds are compressing specification windows and forcing producers to requalify mixes. The Ruhr industrial corridor anchors hollow core production capacity serving Benelux and Northern French construction markets.
India
Metro rail depots and bus rapid transit terminals in Pune and Hyderabad are deploying precast platform slabs with embedded RFID for lifecycle tracking. The Smart Cities Mission infrastructure is creating anchor demand for digitized production lines across Maharashtra and Telangana. Hollow core floor systems dominate multi-family towers in Mumbai and Bangalore where speed-to-market determines financing costs.
Brazil
High-rise residential developers in São Paulo specify hollow core systems for repetitive tower typologies above 15 stories where material efficiency reduces structural steel tonnage. Automated extrusion lines are cutting concrete volumes by 30-40% while maintaining span ratings. Precast clusters in the São Paulo metropolitan area are expanding factory-to-site logistics capacity for accelerated construction schedules.
United States
Hyperscale cloud operators in Northern Virginia are specifying precast slab mezzanines with integrated cable management voids for modular data center construction. EPA and OSHA frameworks govern emissions and workplace exposure in precast manufacturing facilities across the Southeast and Texas. Carbon capture curing pilots in Alberta-connected supply chains are creating differentiated products for LEED v4.1 procurement in institutional verticals.
Concrete Slabs Market Competitive Environment
European producers anchor the premium-tier specification channel; North American specialists hold project-scale bundling advantages through design-build consolidation. The vendor base organizes around three archetypes: vertically integrated cement-to-precast conglomerates, regional hollow core specialists with optimized thermal mass offerings, and project-scale fabricators serving contractor-controlled procurement. Competitive moves concentrate on carbon accounting transparency and factory automation rather than capacity expansion.
Among Switzerland-based conglomerates, Holcim occupies a position exemplifying vertical integration from cement production through precast fabrication. CEMEX represents the R&D-intensive archetype with formulation capabilities spanning conventional and ultra-high performance concrete matrices. Heidelberg Materials anchors the hollow core specialization vector with production systems optimized for commercial building thermal mass specifications. These three entities collectively illustrate how environmental data transparency is becoming as decisive as structural performance in specification battles.
| Leading Market Players |
|---|
| Holcim |
| CEMEX |
| CRH |
| Oldcastle Infrastructure |
| Heidelberg Materials |
| Keegan Precast Ltd |
| Leesburg Concrete Co. |
| Precast New Zealand Inc. |
| U.S. Concrete Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned precast specialists across Germany and Northern Italy anchor supply-side discipline through conservative balance sheets and multi-generational customer relationships, insulating pricing power from volatile cement input costs while constraining aggressive expansion financing.
Pricing Analysis
Lead-time premiums command significant price separation in project-based procurement, with contractors paying substantial markups for sub-48-hour hollow core delivery to congested urban sites in Mumbai and São Paulo. Three-tier pricing structure across premium EPD-certified, standard precast, and economy spot-inventory tiers differentiates slab suppliers in EU Green Deal jurisdictions. Cost compression in standard-grade reinforced concrete intensifies as Turkish clinker import restrictions feed raw material volatility. Public infrastructure tenders in China exhibit the highest price sensitivity, while German commercial developers with Science Based Targets commitments absorb certification premiums with minimal negotiation.
Supply Chain Analysis
Workforce availability constraints in Poland and Romania limit hollow core production scaling despite strong order backlogs from German and Benelux construction markets. Manufacturing gravity centers on China, Germany, and India, with automated extrusion lines in Jiangsu and Maharashtra feeding regional high-rise residential demand. Supply chains draw from high-tensile prestressing strand, low-clinker cement blends, and automated release agent systems. Single-source vulnerability concentrates in European wire rod mills controlling prestressing strand capacity. Distribution runs through project-scale general contractor bundling and direct-to-developer specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete slabs market functions as a vertical-integration race where control over cement-to-precast value chains determines carbon accounting credibility and specification access in EU Green Deal procurement.
For Market Incumbents: Extend EPD verification capabilities across multiple product categories to defend specification share against emerging low-carbon entrants. Anchor backward integration into alternative binder supply through partnerships with calcined clay and slag processors in France and the Netherlands. Cement-to-precast conglomerates must consolidate fragmented regional hollow core specialists before carbon disclosure mandates harden procurement barriers.
For New Entrants and Emerging Players: Launch via carbon capture curing technology partnerships with Alberta and Texas industrial clusters, targeting LEED v4.1 institutional verticals underserved by legacy producers. India's Smart Cities Mission infrastructure presents the most penetrable white-space, with digitized precast platform slabs for metro rail depots offering specification entry without entrenched incumbent relationships. Prioritize design-build contractor direct sales over architect-specified channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hollow core specialists with thermal mass optimization capabilities in German and Dutch commercial building markets. Long-term viability hinges on Environmental Product Declaration infrastructure and automated tendon placement technology across the analysis window. Watch for MIIT dual carbon enforcement intensity in Jiangsu and Guangdong as the signal for Chinese precast consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Curing Integration | CO2 mineralization chambers in Alberta and Texas supply LEED v4.1 procurement channels with differentiated low-emission slab products. |
| EPD Verification Infrastructure Buildout | Third-party carbon accounting capabilities unlock EU Green Deal commercial specifications in Frankfurt and Munich. |
| Automated Tendon Placement Technology | Robotic threading systems address hollow core quality variance and throughput constraints across shift patterns. |
| Backward Integration into Alternative Binders | Calcined clay and slag partnerships in France and the Netherlands secure low-clinker mix supply for embodied carbon compliance. |
| Design-Build Channel Direct Sales | Australian tier-one contractor relationships capture specification authority on projects above 10,000 square meters. |
Study Parameters
Trade association filings, customs and trade flow databases, and SEC 10-K disclosures from cement-to-precast conglomerates formed the secondary backbone of this analysis. Primary interviews with plant managers at hollow core production facilities, procurement leads at German commercial developers, EPC contractors on Indian Smart Cities Mission infrastructure, and technical R&D directors at UHPC formulation specialists combined with secondary validation. Bottom-up shipment data triangulation against top-down construction spend estimates anchored volume and value outputs.
Bottom-up modeling tracked product type, end-user vertical, material formulation, and thickness segmentation across the projection horizon. CAGRs derived from construction activity indices, embodied carbon regulatory trajectory, and precast penetration rate assumptions. Hollow core voiding technology adoption curves and carbon capture curing pilot scalability served as industry-specific forecast sensitivity inputs.
Portland cement price volatility, prestressing strand supply disruptions, and cross-laminated timber substitution acceleration are the dominant revision risks to these projections. Forecasts reflect documented assumptions on regulatory enforcement timing and technology cost curves. Material deviation in clinker import restrictions or EU Green Deal threshold stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
North America Facade Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Fabricated Structural Steel Market