
 Search and Rescue Helicopter Market | 2026-2036
Search and Rescue Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Search and Rescue Helicopter Market Intelligence
All-weather operational certification is reorganizing competitive priorities across the search and rescue helicopter landscape. Airbus Helicopters leverages its H225 Super Puma platform to dominate North Sea oil-and-gas recovery contracts. Leonardo S.p.A. sustains Mediterranean market presence through specialized naval variants with integrated dipping sonar. Lockheed Martin Corp. anchors its position via military SAR configurations derived from the Black Hawk family.
Search and rescue helicopters are rotary-wing aircraft engineered for life-saving missions in adverse conditions, typically featuring hoist systems, medical interiors, and power reserves for hovering at altitude. Their primary purpose spans medical evacuation, disaster relief, and maritime recovery where fixed-wing assets cannot operate. Medium helicopters command the largest procurement volumes due to their balance of range, payload, and deck compatibility. Infrared sensor technology represents the fastest-expanding capability segment as operators prioritize night and low-visibility search effectiveness. Military end users maintain the deepest installed base, though civil defense budgets are closing the gap in several jurisdictions.
FAA Part 29 airworthiness standards and EASA CS-29 certification frameworks govern structural integrity and crashworthiness for new SAR platforms. These requirements extend development timelines but create barriers that favor established manufacturers with dedicated flight-test resources. ISO 9001 quality management and ICAO SARPs additionally shape cross-border equipment interoperability for multinational relief operations. Stakeholders must monitor evolving unmanned systems integration rules, as hybrid manned-unmanned SAR architectures reshape fleet planning assumptions.
Market Dynamics
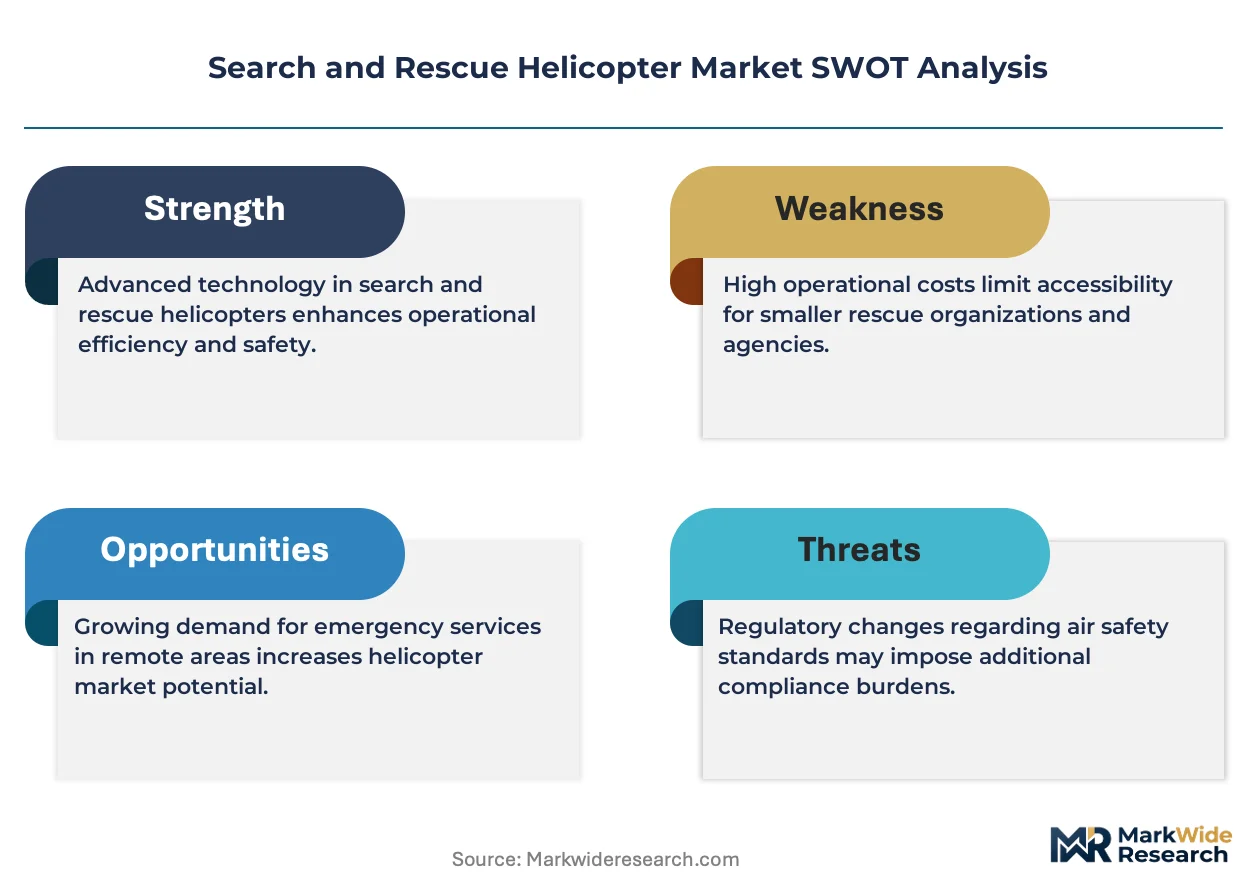
All-weather operational certification requirements from EASA and FAA are compressing development timelines while simultaneously elevating barriers to entry for new SAR platform manufacturers. This structural force is reorganizing competitive priorities toward avionics modernization and integrated sensor suites.
Growth Catalysts
- Climate-driven disaster frequency:Coastal patrol agencies across Australia and Southeast Asian civil defense bodies are accelerating rotary-wing fleet procurement for bushfire response and maritime recovery missions.
- EASA CS-29 certification standards:Stricter crashworthiness mandates are forcing avionics upgrades across existing fleets, creating sustained retrofit demand for established manufacturers with dedicated flight-test resources.
- Infrared sensor integration:Night and low-visibility search effectiveness requirements are driving sensor technology adoption across military and civil SAR operators alike.
Market Restraints
- Specialized airframe input concentration:Titanium and composite material supply for crash-resistant structures concentrates among a limited supplier base, exposing procurement to price volatility.
- Flight-test resource scarcity:Dedicated certification infrastructure for rotary-wing platforms remains concentrated in France, Germany, and the United States, limiting new entrant viability.
- Hybrid unmanned system substitution:Long-endurance fixed-wing drones and rotary UAVs are displacing manned helicopters for certain surveillance and initial search phases.
Strategic Opportunities
- Underpenetrated Southeast Asian civil defense:Indonesia, Philippines, and Vietnam lack all-weather SAR helicopter coverage for archipelagic disaster response, creating fleet expansion white space.
- ICAO SARPs alignment:Cross-border equipment interoperability standards for multinational relief operations are creating specification harmonization opportunities for modular interior systems.
- Manned-unmanned teaming architectures:Hybrid fleet configurations combining traditional helicopters with UAV coordination systems represent an emerging procurement category without established vendor lock-in.
Industry Challenges
- Airworthiness certification timeline compression:FAA Part 29 and EASA CS-29 validation cycles for new SAR configurations now extend 18-24 months beyond baseline commercial helicopter programs, straining R&D capital allocation.
- Hoist operator skill scarcity:Qualified rescue winch technicians and night-vision goggle pilots remain concentrated among military-trained personnel, limiting civil operator expansion capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Search and Rescue Helicopter Market |
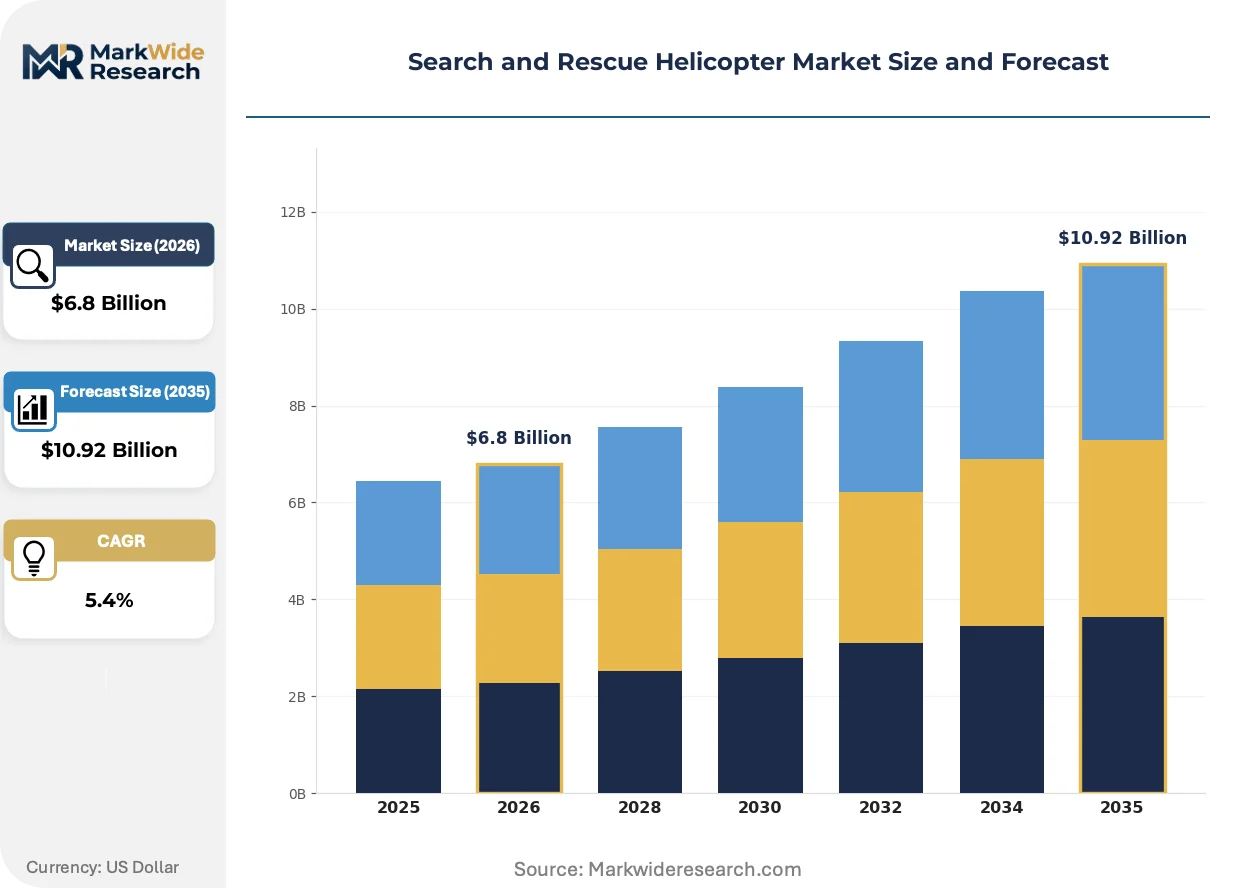
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Super Heavy Helicopters Technology: GPS Navigation, Infrared Sensors, Communication Systems, Stabilization Systems End User: Military, Civil Defense, Emergency Services, Oil & Gas Application: Disaster Response, Medical Evacuation, Firefighting, Coastal Patrol |
| Companies Covered | Airbus Helicopters, Leonardo S.p.A., Lockheed Martin Corp., Bell Textron Inc., Hindustan Aeronautics Ltd., Korea Aerospace Industries Ltd., Russian Helicopters JSC, MD Helicopters Inc., Enstrom Helicopter Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Search and Rescue Helicopter Market Strategic Shifts & Innovations
Sensor fusion architectures and autonomous flight systems are actively reorganizing capability hierarchies in SAR helicopter procurement. Platform differentiation now hinges on integrated mission systems rather than airframe performance alone.
Synthetic aperture radar and electro-optical/infrared sensor fusion is bifurcating the SAR helicopter market into premium all-weather platforms and daylight-limited utility configurations. Military operators in NATO member states are adopting fused-sensor suites for contested environment operations, while civil agencies defer upgrades due to budget constraints. This technology divide is compressing residual values for non-all-weather fleets and concentrating upgrade demand among specialized integrators.
REACH chemical safety regulations and the EU F-Gas Regulation are mandating refrigerant transitions in environmental control systems for European-registered SAR platforms. These requirements are forcing cabin system redesigns and supplier qualification changes for helicopter completion centers. Mediterranean naval SAR operators are responding by consolidating procurement specifications to minimize configuration fragmentation across mixed fleets.
Performance-based logistics contracts are displacing traditional time-and-material maintenance arrangements for military SAR operators. Australia's coastal patrol programs and United Kingdom military aviation units now specify availability guarantees rather than parts provisioning, shifting risk to OEM service networks. This contracting evolution is most visible in Anglo-sphere defense procurement, where through-life cost accountability has displaced upfront acquisition price as the primary selection criterion.
Search and Rescue Helicopter Market Segmentation
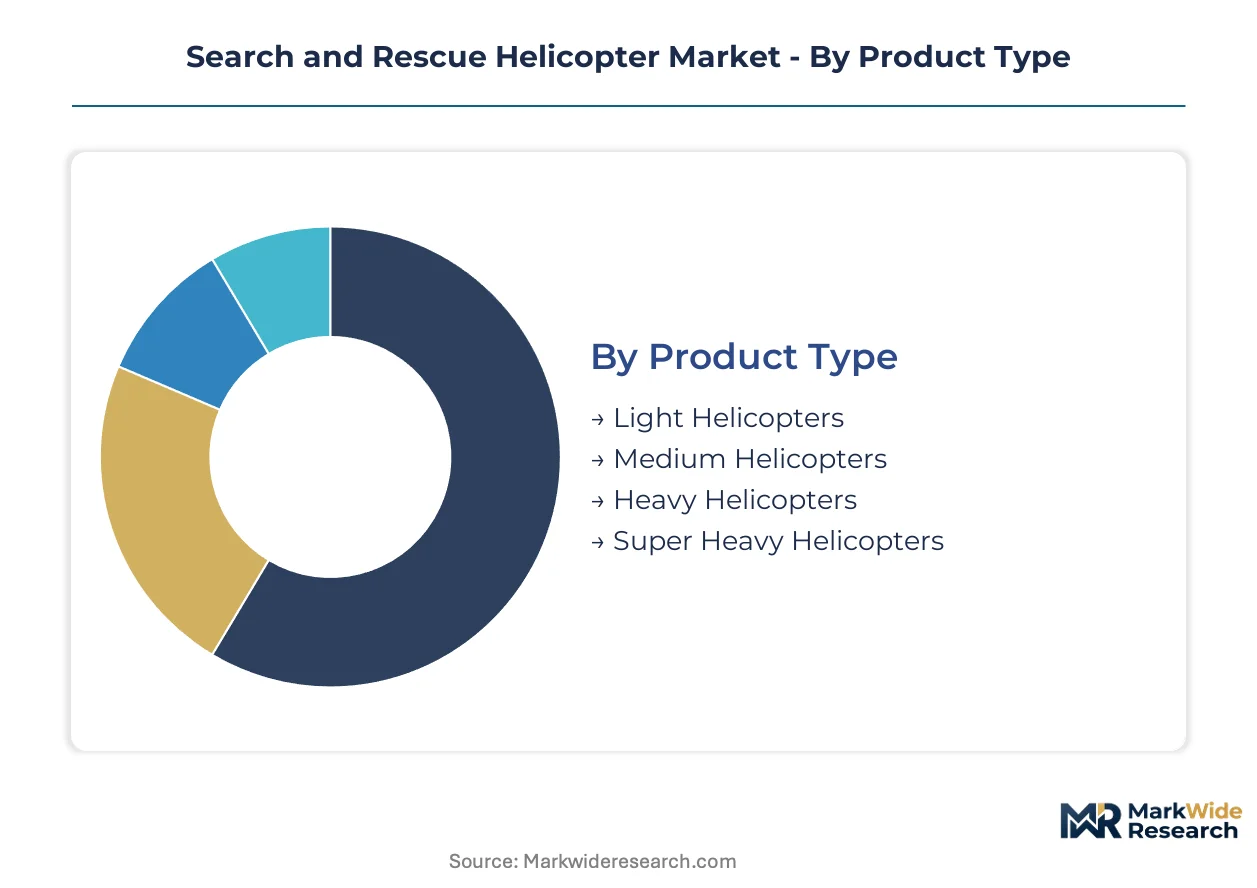
Search and rescue helicopter procurement channels vary sharply by segment, with military tenders favoring integrated platform-sensor bundles while civil operators source airframes and mission systems separately. Understanding these channel dynamics illuminates where pricing power concentrates and where modular suppliers can wedge into value chains.
Product Type:
Light and medium helicopters flow predominantly through civil defense procurement channels, while heavy and super heavy platforms concentrate in military and oil-and-gas fleet tenders with through-life service commitments.
- Medium Helicopters:These platforms balance range, payload capacity, and deck compatibility for maritime and alpine operations. Australia's coastal patrol agencies and Southeast Asian civil defense bodies drive fleet renewal demand here, constrained by EASA CS-29 certification timelines that extend delivery schedules.
- Light Helicopters:Compact rotorcraft with reduced fuel consumption for rapid deployment in confined terrain. Emergency services in mountainous regions and urban medical evacuation operators prioritize these for rooftop landing clearance, though payload limits restrict multi-patient transport.
- Heavy Helicopters:Extended-range platforms with dual-engine redundancy for long-duration offshore missions.
- Super Heavy Helicopters:Maximum-lift configurations for mass casualty evacuation and heavy equipment transport in disaster zones.
Medium helicopters dominate installed base. Light helicopters are where expansion concentrates for urban air mobility integration.
Technology:
Technology adoption stratifies by operator sophistication, with NATO military programs specifying fused-sensor architectures while budget-constrained civil agencies defer to standalone GPS and communication upgrades.
- Infrared Sensors:Electro-optical systems enabling thermal signature detection through obscurants and darkness. Night-vision effectiveness requirements from Australian bushfire response coordinators and Mediterranean naval SAR units are accelerating procurement, though qualified sensor operator scarcity constrains deployment velocity.
- GPS Navigation:Satellite-based positioning with terrain-following augmentation for degraded visual environment operations. Civil defense agencies across archipelagic Southeast Asia rely on these systems where ground-based navigation infrastructure remains sparse, creating specification divergence from military-grade INS alternatives.
- Communication Systems:Multi-band radios and satellite links for beyond-line-of-contact coordination.
- Stabilization Systems:Active rotor and autopilot damping for precision hover in turbulent conditions.
Infrared sensors command premium pricing tiers. GPS navigation represents the broadest installed footprint.
End User:
End-user procurement patterns diverge fundamentally, with military operators accepting 15-20 year platform lifecycles while oil-and-gas contractors demand 7-year depreciation schedules that reshape residual value calculations.
- Military:Defense ministries with contested-environment mission requirements and established pilot training pipelines. The United Kingdom and Australian defense procurement frameworks now specify availability-based logistics contracts rather than traditional spares provisioning, shifting operational risk to OEM service networks.
- Civil Defense:Government agencies responsible for multi-jurisdictional disaster response without dedicated aviation infrastructure. Indonesia, Philippines, and Vietnam exhibit acute coverage gaps for all-weather archipelagic operations, creating fleet expansion white space where hybrid manned-unmanned architectures are gaining traction.
- Emergency Services:Municipal and regional medical evacuation operators with fragmented fleet scales.
- Oil & Gas:Offshore platform contractors with weather-limited launch windows and passenger evacuation mandates.
Military end users maintain deepest installed base. Civil defense is climbing the fastest as climate-driven disaster frequency reshapes government spending priorities.
Application:
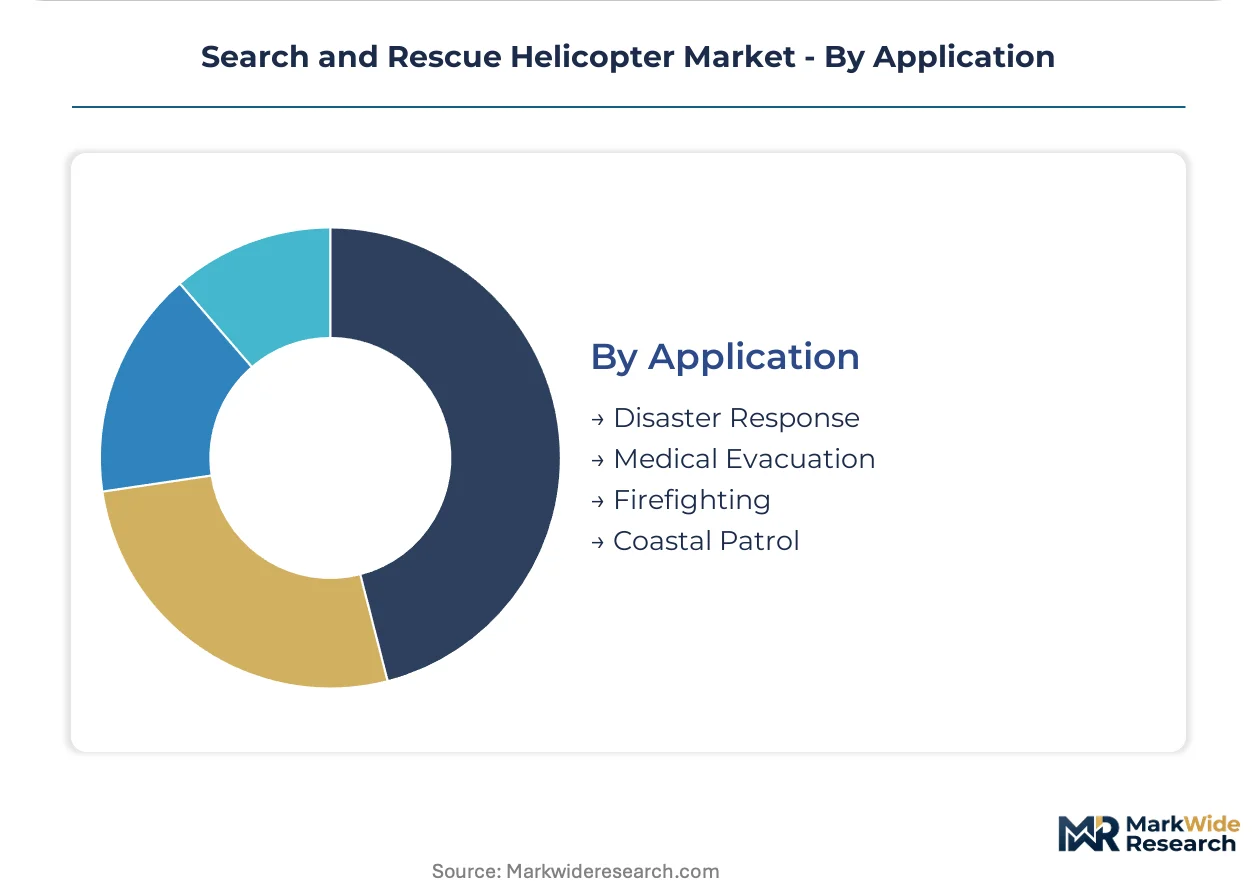
Application-specific configurations determine interior modularity requirements, with medical evacuation demanding rapid reconfiguration capability while coastal patrol prioritizes sensor persistence and fuel endurance.
- Medical Evacuation:Helicopters equipped with intensive-care interiors, patient loading systems, and pressurized cabins for high-altitude physiology management. Australian rural health networks and alpine European emergency services are consolidating specifications around ISO 9001-quality modular systems that enable cross-border interoperability under ICAO SARPs.
- Coastal Patrol:Maritime surveillance platforms with dipping sonar and extended-range fuel systems. Mediterranean naval operators and Australian border protection agencies drive demand here, with Leonardo S.p.A. and Airbus Helicopters competing on integrated mission system performance rather than airframe metrics alone.
- Disaster Response:Multi-role configurations for search, rescue, and supply distribution in degraded infrastructure environments.
- Firefighting:Bambi bucket and tank-equipped rotorcraft for aerial suppression with high-cycle structural loading.
Medical evacuation commands highest unit economics. Coastal patrol is where sensor fusion architectures are reorganizing competitive hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy European OEMs supply rotary-wing platforms to import-dependent Asia-Pacific operators, creating a trade flow that concentrates manufacturing certification resources in France and Germany while fleet expansion concentrates in archipelagic civil defense markets.
United States
FAA Part 29 certification infrastructure anchors North American SAR helicopter development, with military availability-based logistics contracts shifting procurement risk to OEM service networks. The Pentagon's contested-environment mission requirements drive fused-sensor architecture adoption. Texas and Connecticut host concentrated flight-test and final assembly operations for heavy-lift military configurations.
Australia
Coastal patrol agencies and bushfire response coordinators drive medium-helicopter fleet renewal, with TGA-aligned medical evacuation specifications creating cross-border interoperability requirements. The country's national aviation regulator enforces strict crashworthiness mandates for alpine and maritime operations. Queensland and New South Wales concentrate civil defense rotary-wing deployment for archipelagic search coverage.
Indonesia
Archipelagic disaster response gaps create fleet expansion white space where hybrid manned-unmanned architectures gain traction among civil defense procurement planners. The country's national aviation authority lacks dedicated SAR certification infrastructure, forcing reliance on EASA-validated imports. Java and Sulawesi concentrate emergency services demand for volcanic and tsunami response capabilities.
United Kingdom
Ministry of Defence availability guarantees now displace upfront acquisition price as the primary selection criterion for military SAR programs. EASA CS-29 alignment post-Brexit creates transitional certification complexity for fleet modernization. Scotland and the North Sea basin concentrate offshore oil-and-gas recovery helicopter operations with integrated dipping sonar requirements.
Japan
METI industrial policy supports domestic aerospace supply chain participation in international SAR platform programs, though final assembly remains import-dependent. The country's national defense ministry prioritizes all-weather naval variants for contested maritime environment operations. Nagoya and the Kanto region concentrate avionics subsystem manufacturing for regional export markets.
Search and Rescue Helicopter Market Key Industry Players
Concentration sits with diversified aerospace conglomerates and state-backed defense contractors. Five manufacturers control platform development, with tiered competition separating integrated mission system providers from airframe specialists. Strategic archetypes include European full-service OEMs with completion center networks, US defense primes with military SAR derivatives, and Asian state enterprises serving protected domestic markets. Competitive moves center on avionics modernization partnerships and performance-based logistics contracting.
Within the European full-service tier, Airbus Helicopters and Leonardo S.p.A. exemplify divergent regional specialization strategies, with the former anchoring North Sea oil-and-gas recovery and the latter dominating Mediterranean naval configurations. Lockheed Martin Corp. occupies a position as the US defense prime archetype, deriving SAR platforms from established military rotorcraft families. These three represent the dominant certification-resource holders whose flight-test infrastructure creates structural barriers for new entrants.
| Leading Market Players |
|---|
| Airbus Helicopters |
| Leonardo S.p.A. |
| Lockheed Martin Corp. |
| Bell Textron Inc. |
| Hindustan Aeronautics Ltd. |
| Korea Aerospace Industries Ltd. |
| Russian Helicopters JSC |
| MD Helicopters Inc. |
| Enstrom Helicopter Corp. |
| Others |
Cost & Logistics Intelligence
EASA CS-29 certification requirements gate both supplier qualification timelines and price differentiation tiers across SAR helicopter procurement channels. Manufacturers with dedicated flight-test resources in France and Germany extract premium positioning for all-weather platforms, while non-certified suppliers compete on price for daylight-limited utility configurations.
Pricing Analysis
Military OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in SAR helicopter procurement. Premium tiers attach to integrated sensor-fusion platforms with through-life service commitments, while economy tiers cover standalone airframes without mission system bundling. Price differentiation hinges on certification grade and after-sales service depth. Cost compression in economy tiers is intensifying because qualified sensor operator scarcity constrains deployment velocity for mid-tier offerings. Civil defense agencies exhibit highest price sensitivity due to fragmented budget cycles, whereas oil-and-gas contractors prioritize availability guarantees over upfront acquisition cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for titanium and composite material shipments to European completion centers. Manufacturing gravity centers on France, Germany, and the United States for final assembly and flight-test validation. Raw material dependencies rest on titanium forgings for crash-resistant structures, carbon fiber prepregs for rotor blades, and avionics subsystems from Japanese suppliers. Single-source vulnerability concentrates in qualified dipping sonar and infrared sensor integrators. Distribution runs through military tender channels with integrated platform-sensor bundles and civil operator direct procurement for modular mission systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous flight system integration is disrupting capability hierarchies faster than certification timelines can absorb, creating compressed windows for strategic repositioning across all market tiers.
For Market Incumbents: Fortify certification-resource moats by expanding flight-test infrastructure in Germany and the United States before hybrid unmanned architectures erode platform-differentiation value. Lock in performance-based logistics contracts with Australian and UK defense procurement frameworks to shift operational risk onto OEM service networks and forestall price competition from modular integrators. For New Entrants and Emerging Players: Anchor in Southeast Asian civil defense white space where Indonesia, Philippines, and Vietnam lack all-weather SAR coverage for archipelagic operations. Target hybrid manned-unmanned coordination systems as the most penetrable procurement category without established vendor lock-in, pursuing sensor-operator training partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: FAA Part 29 and EASA CS-29 timeline extensions reshape the acquisition landscape toward specialized avionics integrators with existing certification relationships rather than airframe developers. Five-to-ten year viability favors tier-one completion centers with modular interior system portfolios. Watch for manned-unmanned teaming architecture adoption rates in Australian coastal patrol programs as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Avionics Modernization Partnership | Airbus Helicopters and Leonardo S.p.A. compete on fused-sensor suite performance rather than airframe metrics alone. |
| Performance-Based Logistics Contract | UK Ministry of Defence and Australian defense procurement frameworks now specify availability guarantees displacing traditional spares provisioning. |
| Modular Interior System Certification | ISO 9001-quality cabin systems enable cross-border interoperability under ICAO SARPs for multinational relief operations. |
| Hybrid Manned-Unmanned Architecture | Indonesian civil defense procurement planners evaluate UAV coordination systems without established vendor lock-in constraints. |
| Sensor Fusion Integration | NATO military programs specify synthetic aperture radar and electro-optical/infrared fusion for contested environment operations. |
Research Approach
A spread of perspectives from fleet procurement directors at civil defense agencies, military aviation program managers, helicopter completion center engineers, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EASA certification databases, FAA type certificate records, defense procurement disclosure filings, and customs trade data for titanium and composite material flows. Bottom-up unit economics triangulated against top-down budget allocation analysis across the analysis window.
Segmentation dimensions modeled include platform weight class, sensor technology tier, end-user procurement channel, and application-specific configuration requirements. CAGRs were derived from installed base retirement schedules and replacement demand curves across military, civil defense, and oil-and-gas operator segments. Forecast inputs incorporated climate-driven disaster frequency projections for Southeast Asian archipelagic coverage gaps and EASA CS-29 retrofit compliance timelines for European-registered fleets.
Material uncertainties — regulatory timeline slippage, titanium supply price volatility, and hybrid unmanned substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification infrastructure capacity and qualified rescue winch technician pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Regional Jet Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Fighter Aircraft Market
Aircraft
Europe Aviation Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Aircraft Elevator Market
Aircraft
Turboprop Aircraft Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Military Transport Aircraft Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Aircraft Cables Market
Aircraft
Aircraft Oxygen System Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market