
 Aircraft Cables Market | 2026-2036
Aircraft Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cables Market Analysis
Carbon fiber-reinforced polymer sheathing is decoupling aircraft cable weight from electrical performance benchmarks, enabling single-digit percentage mass reductions on long-haul platforms. TE Connectivity leverages backward integration into specialty copper alloys to secure conductor purity for high-frequency avionics harnesses. Collins Aerospace sustains manufacturing scale across multiple FAA-certified production lines, while Amphenol Corporation differentiates through connector-cable integration for military fighter programs.
Aircraft cables are engineered electrical and data transmission assemblies consisting of stranded conductors, insulating jackets, and shielding layers designed to operate across temperature extremes from minus 65 to 200 degrees Celsius while resisting electromagnetic interference and mechanical fatigue during pressurization cycles. Their primary purpose is to distribute power, transmit control signals, and enable data networking across airframe systems while meeting strict weight and fire-resistance thresholds. Power cables occupy the largest revenue pool given engine and auxiliary power unit electrification trends, though fiber optic data cables represent the fastest-expanding segment as fly-by-light architectures displace copper in next-generation flight control networks. Control cables within the application dimension retain mature demand profiles tied to hydraulic actuator interfaces, while OEM end users command premium pricing through long-term platform-specific qualification requirements.
FAA airworthiness directives and EPA restrictions on halogenated flame retardants are jointly reshaping jacket material formulations, compelling suppliers to validate alternative chemistries through costly recertification protocols. EASA's CS-25 certification standards for large aeroplanes create parallel compliance obligations for European-registered platforms and their component suppliers. ISO 7137 environmental test methods provide common reference frameworks that reduce technical barriers between regulatory jurisdictions. Stakeholders must weigh qualification timeline risks against material substitution rewards as platform OEMs consolidate supplier bases around dual-certified cable architectures.
Market Dynamics
Fleet electrification and fly-by-wire architecture proliferation are compressing qualification timelines while expanding performance requirements for next-generation harness systems across commercial and defense platforms.
Growth Catalysts
- FAA Fire-Resistance Mandates:Tightened airworthiness directives for flame-retardant jacket materials are forcing platform-wide cable replacements on aging narrowbody fleets, creating sustained aftermarket pull.
- Carbon Fiber Sheathing:Advanced polymer composites are decoupling weight from conductivity metrics, enabling mass reduction targets on long-haul widebody programs without sacrificing ampacity.
- APU Electrification:Auxiliary power unit subsystem upgrades across Boeing and Airbus next-generation platforms are expanding high-temperature power cable procurement volumes.
Market Restraints
- Specialty Copper Alloy Volatility:Conductor-grade oxygen-free copper and silver-plated variants face price instability tied to mining concentration in Chile and Peru, compressing margin predictability for harness assemblers.
- Dual Certification Burden:EASA CS-25 and FAA parallel validation requirements extend qualification timelines by 18-24 months, freezing supplier selection decisions until both jurisdictions approve material substitutions.
- Halogen-Free Formulation Costs:EPA restrictions on brominated flame retardants compel jacket material reformulation, with alternative phosphorus-nitrogen chemistries commanding 15-20% raw material premiums.
Strategic Opportunities
- Urban Air Mobility:Electric vertical takeoff and landing aircraft manufacturers in the United States and Germany represent uncaptured demand for miniaturized, high-flexure harness systems with simplified certification pathways.
- ISO 7137 Harmonization:Standardized environmental test methods across jurisdictions reduce technical barriers for suppliers seeking dual FAA-EASA approval, compressing market entry costs.
- Fiber-Optic Convergence:Fly-by-light architectures merging photonic data transmission with traditional power distribution create integrated cable-connector opportunities in next-generation flight control networks.
Industry Challenges
- EMI Shielding Expertise Scarcity:Electromagnetic interference mitigation for high-frequency avionics harnesses requires specialized engineering talent concentrated at legacy defense contractors, limiting supplier pool expansion.
- Platform-Specific Qualification Lock-In:OEM long-term agreements tether cable architectures to individual airframe programs, creating switching friction when incumbent suppliers fail to meet cost reduction targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cables Market |
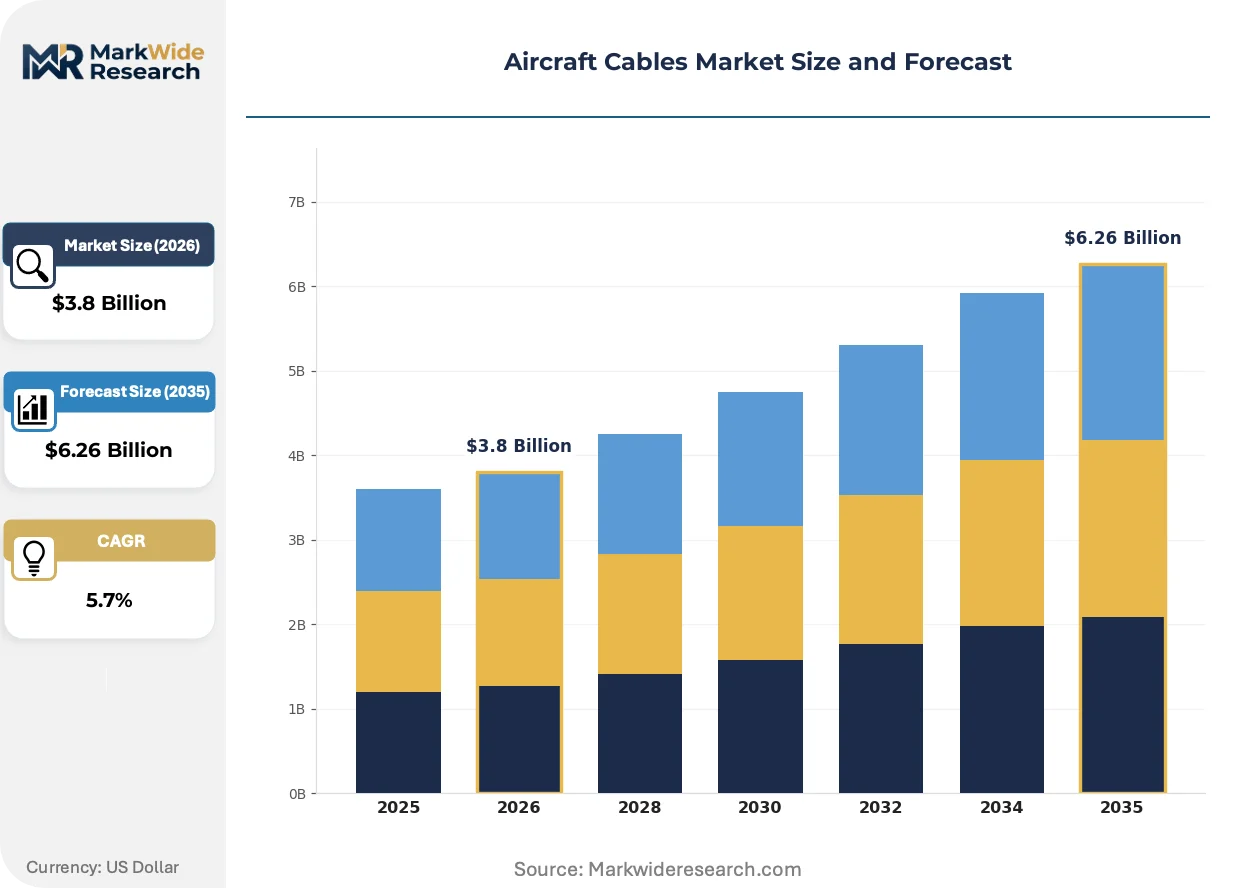
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Control Cables, Data Cables, Signal Cables Material: Copper, Aluminum, Fiber Optic, Composite Application: Aerospace, Avionics, Propulsion, Control Systems End User: OEMs, MROs, Military, Commercial Airlines |
| Companies Covered | Collins Aerospace, Radiall, TE Connectivity, Glenair Inc., Loos and Co. Inc., Amphenol Corporation, Nexans, A.E. Petsche, Carlisle Interconnect Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cables Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are jointly restructuring how cable systems achieve fire resistance, weight reduction, and signal integrity across temperature extremes from minus 65 to 200 degrees Celsius.
Silicon dioxide-based fiber optic cores are absorbing copper's historical dominance in flight control data transmission. Military fighter programs and next-generation commercial platforms are adopting photonic harnesses for immunity to electromagnetic pulse interference. This absorption is compressing demand for shielded twisted-pair copper in safety-critical avionics networks while expanding connector-cable integration complexity.
EPA halogenated flame retardant restrictions are compelling jacket material suppliers to validate phosphorus-nitrogen and metal hydroxide alternative chemistries through full-scale burn-test protocols. The industrial consequence is extended qualification timelines and elevated R&D recovery costs passed through to OEM pricing. European-registered platforms under EASA jurisdiction face parallel compliance obligations, with dual-certified suppliers capturing consolidated procurement volumes.
Platform OEMs are unbundling cable harness sourcing from airframe final assembly, establishing direct supplier relationships with specialty cable manufacturers for qualified component supply. This disintermediation compresses tier-one system integrator margins while rewarding harness specialists with captive metallurgy and in-house extrusion capabilities. The United States exhibits the most visible procurement restructuring, with Boeing's supplier base consolidation favoring dual-certified production lines.
Aircraft Cables Market Segmentation
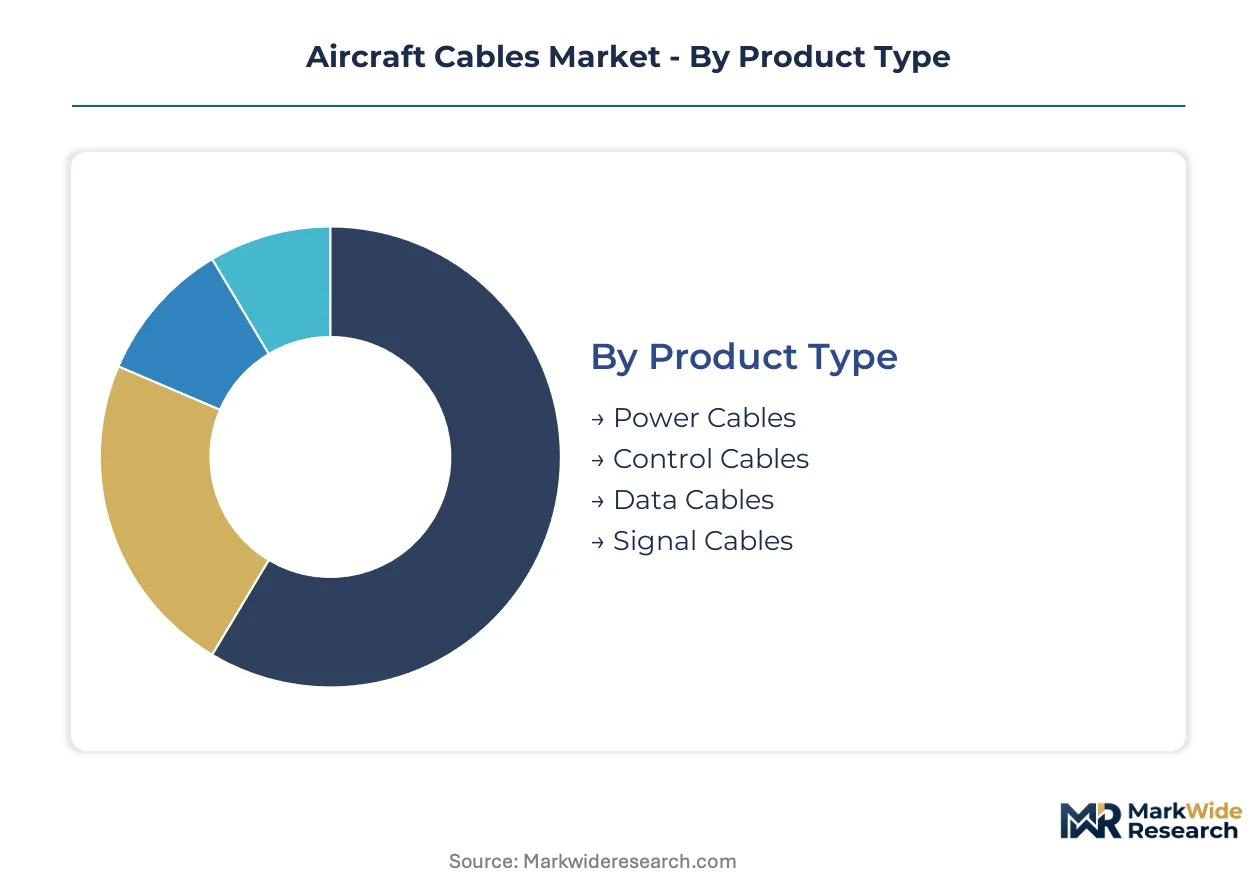
Aircraft cable procurement patterns diverge sharply between platform development cycles and aftermarket replacement schedules. Each segmentation dimension captures distinct buyer priorities: electrical load specifications, material certification burdens, subsystem integration complexity, and contractual relationships with airframe manufacturers.
Product Type:
Buyers in this category differentiate by ampacity requirements and signal integrity thresholds across propulsion, avionics, and flight control networks.
- Power Cables:Engineered with high-temperature insulation jackets rated for auxiliary power unit electrification and engine nacelle environments. Boeing and Airbus next-generation narrowbody programs in the United States anchor procurement volumes as fleet electrification expands conductor gauge requirements.
- Data Cables:Shielded twisted-pair and fiber optic assemblies enabling fly-by-wire and fly-by-light architectures. Military fighter programs and commercial widebody platforms in Germany are adopting photonic harnesses for electromagnetic pulse immunity, compressing copper's historical dominance in safety-critical networks.
- Control Cables:Mechanical-electrical hybrid assemblies interfacing with hydraulic actuators and flight surface mechanisms. Demand concentrates in mature narrowbody retrofit programs where FAA airworthiness directives mandate replacement cycles.
- Signal Cables:Low-voltage transmission lines for sensor networks and cabin management systems. Commercial airlines specify these for in-flight entertainment and environmental control subsystem upgrades.
Power cables lead volumes today; data cables are expanding most quickly.
Material:
Specification engineers weigh conductivity purity against weight targets and regulatory chemistry restrictions when selecting conductor and jacket compositions.
- Copper:Oxygen-free and silver-plated variants remain the baseline for high-frequency avionics harnesses. TE Connectivity's backward integration into specialty copper alloys secures conductor purity for military and commercial platforms in the United States.
- Fiber Optic:Silicon dioxide cores with polymer cladding deliver immunity to electromagnetic interference across temperature extremes. Next-generation flight control networks in France and Germany are displacing copper shielded pairs at accelerating rates.
- Aluminum:Lightweight conductor alternatives for non-critical power distribution where ampacity requirements permit reduced conductivity. Regional jet manufacturers specify aluminum for secondary electrical buses.
- Composite:Carbon fiber-reinforced polymer sheathing decouples weight from electrical performance, enabling single-digit percentage mass reductions on long-haul platforms without sacrificing fire-resistance ratings.
Copper dominates installed base; fiber optic is climbing the fastest.
Application:
Subsystem integration complexity and certification pathway duration separate procurement strategies across airframe functional domains.
- Avionics:High-density harness assemblies for flight management computers, navigation systems, and communication radios. Collins Aerospace sustains manufacturing scale across multiple FAA-certified production lines serving this specification-intensive segment.
- Propulsion:Fire-resistant power distribution for engines, auxiliary power units, and fuel system interfaces. EPA restrictions on halogenated flame retardants compel jacket reformulation with phosphorus-nitrogen chemistries commanding raw material premiums.
- Aerospace:General airframe wiring for lighting, heating, and auxiliary electrical services. MRO providers in the United States generate sustained aftermarket demand from aging narrowbody fleet refurbishment.
- Control Systems:Redundant signal paths for fly-by-wire flight surface actuation. Dual FAA-EASA certification requirements extend qualification timelines, freezing supplier selection until both jurisdictions approve material substitutions.
Avionics commands premium pricing; propulsion is gaining share fastest.
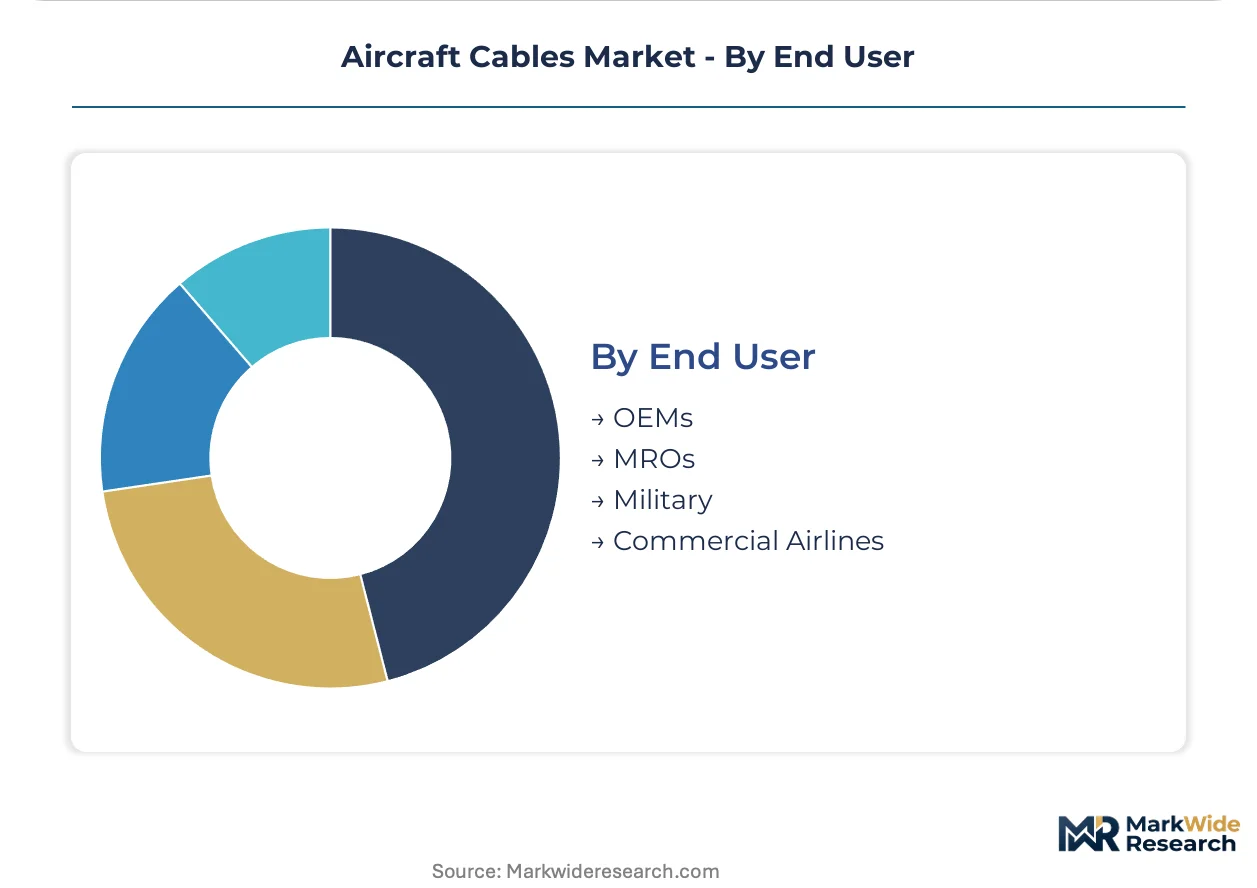
End User:
Contractual structures and qualification lock-in duration create divergent margin profiles across buyer categories.
- OEMs:Boeing and Airbus platform-specific long-term agreements tether cable architectures to individual airframe programs, creating switching friction when incumbent suppliers fail to meet cost reduction targets.
- MROs:Aftermarket service providers generate replacement demand from FAA-mandated fire-resistance upgrades and aging fleet electrical system refurbishment in the United States.
- Military:Defense contractors specify connector-cable integration for fighter programs with electromagnetic interference shielding requirements. Amphenol Corporation differentiates through captive manufacturing for this segment.
- Commercial Airlines:Fleet operators procure directly from qualified cable manufacturers as platform OEMs unbundle harness sourcing from airframe final assembly.
OEMs anchor revenue concentration; MROs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boeing's supplier network in the United States anchors procurement volumes for next-generation narrowbody and widebody platforms. Fleet modernization programs and FAA certification requirements are tightening material specifications across multiple jurisdictions.
United States
Boeing's 737 MAX and 777X programs drive concentrated demand for fire-resistant power cables and fiber optic harnesses. FAA airworthiness directives mandate platform-wide cable replacements on aging narrowbody fleets, sustaining aftermarket pull through MRO providers. The Pacific Northwest manufacturing cluster around Seattle anchors final assembly integration with specialty cable qualification facilities.
Germany
Airbus operations in Hamburg and Bremen generate procurement volumes for next-generation flight control networks adopting fly-by-light architectures. EASA CS-25 certification standards create parallel compliance obligations for European-registered platforms and their component suppliers. The Bavarian aerospace corridor around Munich hosts specialized harness assemblers serving military fighter programs.
France
Airbus final assembly lines in Toulouse drive specification requirements for high-temperature power distribution systems. The country's national aerospace regulator enforces EASA harmonized standards for large aeroplane electrical installations. The Occitanie region clusters cable component suppliers around ATR and Dassault Aviation manufacturing sites.
United Kingdom
Rolls-Royce engine programs in Derby generate demand for auxiliary power unit electrification cabling. The Civil Aviation Authority implements FAA-aligned fire-resistance mandates for flame-retardant jacket materials. The Southwest England aerospace cluster around Bristol maintains specialty copper alloy processing capabilities for avionics harnesses.
Japan
Mitsubishi Heavy Industries regional jet development creates procurement opportunities for miniaturized harness systems. METI industrial policy supports domestic qualification of alternative phosphorus-nitrogen flame retardant chemistries. The Nagoya aerospace manufacturing zone integrates cable suppliers into Boeing and Airbus subcontractor networks.
Aircraft Cables Market Vendor Landscape
Global majors compete with regional champions across qualification timelines and certification breadth. The vendor base concentrates around dual-certified production lines capable of satisfying both FAA and EASA jurisdictions simultaneously. Three archetypes dominate: integrated airframe system suppliers with captive cable divisions, specialty harness manufacturers with backward metallurgy control, and connector-focused integrators serving military programs. Consolidation pressures favor acquisition of regional qualification specialists, while greenfield capacity expansion concentrates in low-cost manufacturing zones with streamlined environmental permitting.
Within the integrated system supplier tier, Collins Aerospace and TE Connectivity exemplify scale-driven positioning through multiple FAA-certified production lines. Among connector-cable integrators, Amphenol Corporation occupies a specialist position tied to electromagnetic interference shielding requirements for defense platforms. The specialty harness segment includes Carlisle Interconnect Technologies, which represents the archetype of component-focused manufacturers serving both commercial and military end users.
| Leading Market Players |
|---|
| Collins Aerospace |
| Radiall |
| TE Connectivity |
| Glenair Inc. |
| Loos and Co. Inc. |
| Amphenol Corporation |
| Nexans |
| A.E. Petsche |
| Carlisle Interconnect Technologies |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange copper price volatility cascades through conductor-grade oxygen-free copper procurement into three-tier pricing stratification across premium FAA-EASA dual-certified harnesses, standard single-jurisdiction cables, and economy-grade aftermarket replacements. Boeing and Airbus platform-specific long-term agreements compress margin predictability for harness assemblers when mining concentration in Chile and Peru triggers raw material premiums.
Pricing Analysis
Input-cost pass-through from specialty copper alloys and phosphorus-nitrogen flame retardant chemistries shapes contract negotiations between tier-one system integrators and platform OEMs. Price differentiation hinges on dual-certification breadth and captive metallurgy capabilities, with dual-certified suppliers commanding premiums over single-jurisdiction competitors. Cost compression in standard-grade segments is intensifying because EPA halogen restrictions force jacket reformulation R&D recovery. Commercial airlines exhibit highest price sensitivity due to unbundled harness sourcing from airframe final assembly, while military contractors prioritize electromagnetic interference shielding performance over unit economics.
Supply Chain Analysis
Specialized harness engineering talent availability in the United States, Germany, and Japan constrains capacity expansion for fly-by-light and high-frequency avionics programs. Conductor-grade oxygen-free copper draws from Chilean and Peruvian mining concentration, while silicon dioxide fiber optic cores rest on Japanese and German specialty glass manufacturing. Single-source vulnerability around FAA-certified production line qualification creates switching friction when incumbent suppliers fail cost reduction targets. Distribution runs through direct supplier relationships with platform OEMs and MRO refurbishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fleet electrification and fly-by-wire proliferation shift procurement toward fire-resistant, lightweight premium specifications. OEM consolidation of supplier bases around dual-certified architectures rewards qualification depth over pure scale.
For Market Incumbents: Cement dual-certification lock-in across Boeing 737 MAX and 777X programs while deepening backward integration into specialty copper alloys to offset conductor-grade price volatility. Threat of fiber optic substitution in flight control networks demands accelerated photonic harness R&D investment. Certification investment in EASA CS-25 parallel validation remains the critical lever for capturing consolidated procurement volumes. For New Entrants and Emerging Players: Capture urban air mobility white space in United States and Germany electric vertical takeoff and landing programs where simplified certification pathways reduce barrier to entry. Miniaturized high-flexure harness systems for regional jet manufacturers represent the most penetrable segment given lower qualification timeline requirements. Go-to-market execution should emphasize ISO 7137 harmonization credentials to compress dual FAA-EASA approval costs. For Investors and Strategic Acquirers: Consolidation pressure builds where regional qualification specialists hold captive FAA-certified production lines without scale to serve consolidated OEM supplier bases. Long-term viability favors component-focused harness manufacturers with in-house extrusion and metallurgy control over pure assembly operations. Watch fiber optic penetration rates in next-generation flight control networks as inflection indicator for copper displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel FAA-EASA validation compresses supplier selection timelines for Boeing and Airbus platforms. |
| Backward Integration into Specialty Alloys | Captive copper purity control secures conductor supply for high-frequency avionics harness specifications. |
| Photonic Harness Development | Silicon dioxide core manufacturing capability positions suppliers for fly-by-light architecture displacement of copper. |
| Urban Air Mobility Partnership | Simplified certification pathways with eVTOL manufacturers in United States and Germany unlock uncaptured demand. |
| Halogen-Free Formulation Scale-Up | Phosphorus-nitrogen chemistry production capacity addresses EPA restrictions and EASA parallel compliance obligations. |
Methodological Framework
Bottom-up platform-level modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with harness engineering directors, OEM procurement leads, MRO refurbishment specialists, and FAA certification officers combined with secondary validation against FAA airworthiness directive filings, EASA CS-25 regulatory updates, and specialty copper trade flow data. This approach triangulates demand signals from fleet electrification programs and supply-side capacity constraints across dual-certified production networks.
Historical trendline analysis of narrowbody and widebody platform delivery schedules, coupled with aftermarket replacement cycle data from aging fleet refurbishment programs, informs the projection framework. Segmentation dimensions span product type, material composition, application subsystem, and end-user contractual structure across the analysis window. CAGRs derive from platform-specific content-per-aircraft assumptions for power, data, control, and signal cable categories, with fiber optic penetration rates and APU electrification trends as key forecast inputs.
Underlying measurement precision varies by segment; OEM platform-specific qualification data carries tighter precision than aftermarket MRO replacement estimates. Forecasts reflect assumptions about regulatory chemistry restriction timelines and mining concentration stability. Material deviation in FAA-EASA harmonization pace or halogenated flame retardant ban enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Air Starter Market
Aircraft
North America Business Jet Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
India Winglets Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
North America General Aviation Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Freighter Aircraft Market