
 Aircraft Autopilot System Market | 2026-2036
Aircraft Autopilot System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Autopilot System Market Analysis
The EU Green Deal aviation emissions framework is repositioning autopilot system requirements toward trajectory optimization and fuel-efficient flight profiles. Honeywell International Inc. leverages its integrated flight deck portfolio to dominate the commercial retrofit segment. Garmin Ltd. anchors the general aviation autopilot market with certified retrofit solutions for light aircraft. Collins Aerospace competes through its sensor fusion architectures that support single-pilot operations.
An aircraft autopilot system is an automated flight control mechanism that uses gyroscopic sensors, accelerometers, GPS receivers, and servo actuators to maintain attitude, heading, and altitude without continuous human input, typically operating within precision parameters of less than 0.1 degree deviation for commercial certification. Its primary purpose is to reduce pilot workload, enhance flight safety, and enable fuel-optimal routing across all phases of flight. Fly-by-wire systems command the highest value per unit as they integrate full authority digital engine control with flight management computers. Unmanned Aerial Vehicles represent the fastest-expanding application segment as military and commercial drone operators mandate autonomous navigation for beyond-visual-line-of-sight missions. Conventional autopilot installations remain the largest installed base but face replacement pressure from digital architectures.
The FAA mandates TCAS and autopilot redundancy standards under Part 25 airworthiness certification, while EASA enforces CS-25 requirements for automatic landing minima and fail-operational performance. China's CAAC aligns with ICAO standards but imposes additional cybersecurity protocols for foreign-sourced flight control software. Stakeholders must monitor evolving single-pilot cockpit regulations and corresponding autopilot reliability thresholds as certification authorities reassess minimum equipment requirements.
Market Dynamics
The transition toward reduced-crew and single-pilot operations is compressing reliability requirements for flight control architectures, forcing autopilot manufacturers to engineer fail-operational systems that exceed current certification thresholds.
Growth Catalysts
- FAA NextGen mandates:Trajectory-based operations require precision autopilot capabilities for required navigation performance, compelling commercial carriers to upgrade aging analog systems.
- EU Green Deal aviation emissions framework:Fuel-efficient flight profiles depend on advanced autopilot trajectory optimization, repositioning system specifications toward continuous descent approaches and optimized cruise routing.
- Unmanned Aerial Vehicles:Military and commercial drone operators mandate autonomous navigation for beyond-visual-line-of-sight missions, expanding addressable demand beyond crewed aircraft.
Market Restraints
- Semiconductor supply concentration:Specialized flight control processors source from limited foundry capacity in East Asia, creating vulnerability in servo actuator digital controller availability.
- Certification timeline friction:EASA CS-25 amendments for automatic landing minima impose extended validation periods, stretching development-to-revenue cycles for new architectures.
- Retrofit cost structure:Wiring harness replacement and flight deck integration for aging Boeing 737 NG and Airbus A320ceo fleets demands labor-intensive installation exceeding narrowbody residual values.
Strategic Opportunities
- Urban Air Mobility:Electric vertical take-off and landing aircraft require certifiable autonomous flight systems, opening greenfield demand from Joby Aviation, Archer, and Lilium development programs.
- India defense procurement:Indigenous combat aircraft and unmanned platforms under the Ministry of Defence's Make in India initiative create localized autopilot sourcing requirements.
- Artificial intelligence sensor fusion:Machine learning-based turbulence prediction converging with traditional inertial reference units enables predictive flight control adjustments before atmospheric disturbance encounter.
Industry Challenges
- Embedded software engineering scarcity:DO-178C certified developers command premium compensation, constraining expansion velocity for autopilot system houses.
- Legacy analog interface integration:Hybrid digital-analog architectures in retrofitted aircraft create signal compatibility failures between modern flight management computers and existing servo mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Autopilot System Market |
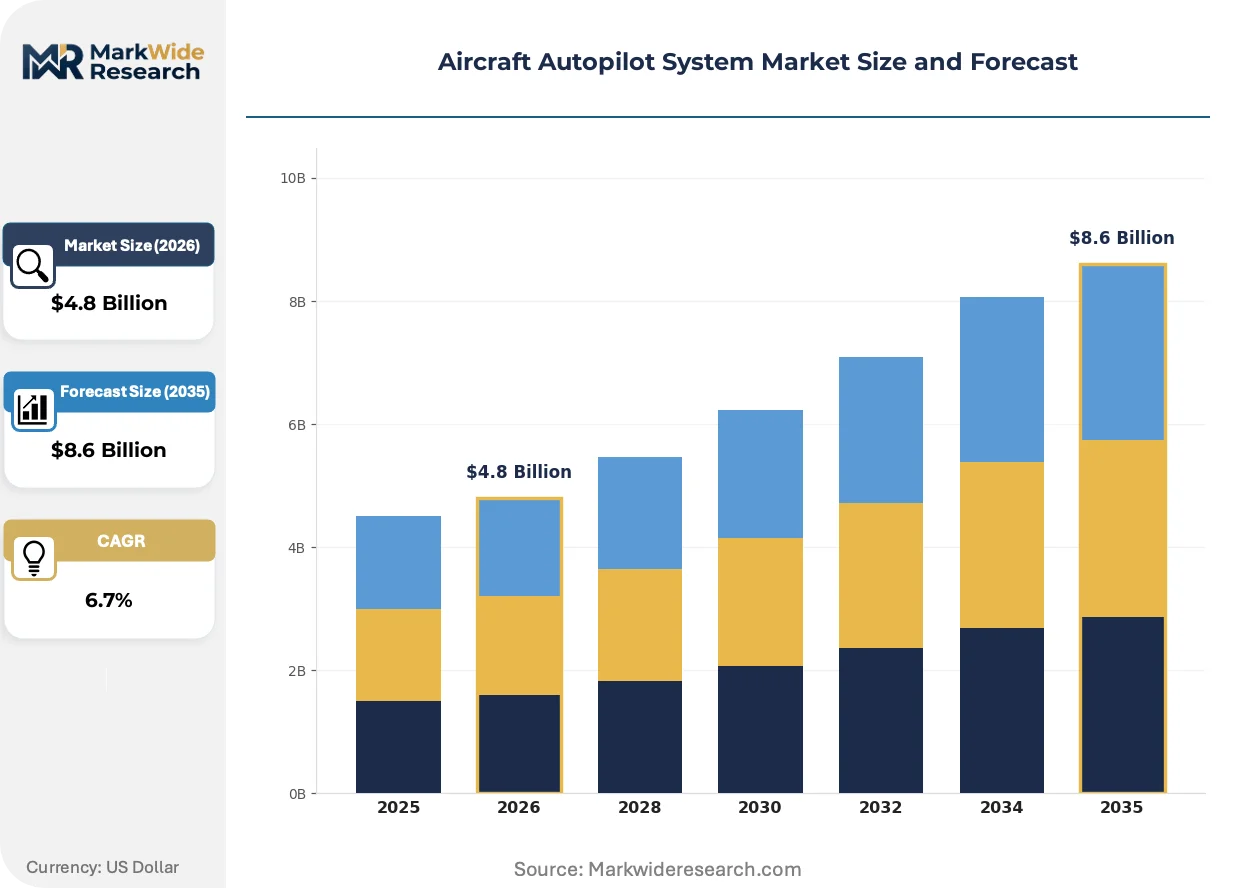
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Digital, Fly-by-Wire, Autoland Application: Commercial Aviation, Military Aviation, General Aviation, Unmanned Aerial Vehicles Technology: Autonomous Navigation, Sensor Fusion, Real-Time Data Processing, Artificial Intelligence End User: Airlines, Defense Contractors, Aerospace Manufacturers, Flight Training Organizations |
| Companies Covered | Thales Group, Rockwell Collins, Honeywell International Inc., Dynon Avionics, Avidyne Corporation, Collins Aerospace, Genesys Aerosystems, Moog Inc., Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Autopilot System Market Emerging Trajectories
Digital flight control architectures are displacing electromechanical systems across all aircraft categories, compressing hardware content while expanding software-defined functionality and over-the-air update capabilities.
Artificial intelligence-based predictive flight control is automating real-time trajectory adjustments based on meteorological data fusion and aerodynamic modeling. Business jet operators and fractional ownership fleets are adopting these systems fastest, prioritizing passenger comfort and fuel efficiency over acquisition cost. This capability is automating the displacement of reactive autopilot modes that respond only after deviation detection.
EASA's regulatory framework for single-pilot commercial operations under CS-25 is mandating redundant autopilot channels with independent power and computation architectures. European carriers preparing for 2030 implementation targets are pre-certifying enhanced flight control systems. The narrowbody retrofit segment faces the steepest compliance burden as aging platforms require complete avionics stack replacement.
Airline technical procurement departments are consolidating vendor relationships, preferring integrated flight deck suppliers over discrete autopilot specialists. Full-service contracts covering installation, training, and long-term support are displacing component-only transactions. This consolidation is most pronounced among United States legacy carriers managing mixed Boeing and Airbus fleets under unified technical standards.
Aircraft Autopilot System Market Segmentation
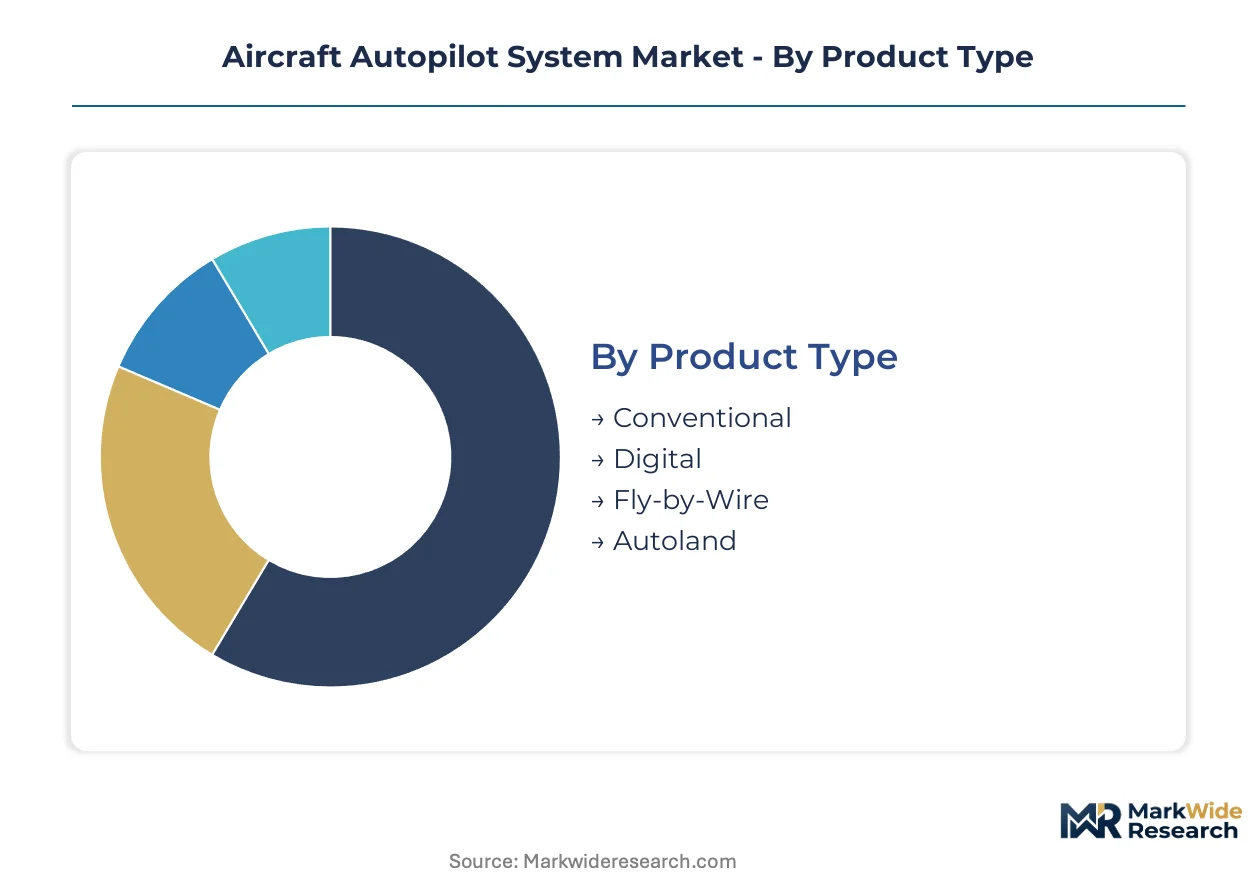
Autopilot system procurement varies sharply across aircraft categories, with certification thresholds and integration complexity creating distinct buyer profiles. Technology maturity and fleet replacement cycles further differentiate segment economics, particularly as analog architectures face obsolescence pressure from digital mandates.
Product Type:
Buyers in this category separate by aircraft generation and regulatory pathway — new-build programs demand integrated digital architectures while retrofit operators balance residual value against compliance deadlines.
- Fly-by-Wire:Full authority digital flight control eliminates mechanical linkages between cockpit controls and control surfaces. Commercial narrowbody and widebody production lines in the United States and France specify these systems for all new deliveries, with EASA CS-25 amendments for reduced-crew operations accelerating specification upgrades.
- Digital:Microprocessor-based architectures replace analog computation with software-defined functionality and over-the-air update capability. General aviation retrofit demand concentrates in Germany and Australia as owner-operators seek ADS-B Out compliance and precision approach certification without complete panel replacement.
- Conventional:Electromechanical autopilots using gyroscopic sensors and analog servo amplifiers retain the largest installed base. Aging Boeing 737 NG and Airbus A320ceo fleets face replacement pressure as wiring harness degradation exceeds narrowbody residual values.
- Autoland:Fail-operational triple-redundant systems enabling zero-visibility landings. CAT IIIb certification requirements at London Heathrow and Frankfurt Main drive retrofit demand among European flag carriers.
Conventional systems retain volume leadership from installed base; fly-by-wire is gaining share fastest as new-build programs dominate procurement.
Application:
Operational environment dictates reliability architecture — crewed platforms prioritize pilot workload reduction while unmanned systems mandate deterministic autonomy for beyond-visual-line-of-sight missions.
- Commercial Aviation:Scheduled passenger and cargo operations requiring continuous autopilot engagement across oceanic and continental routes. United States legacy carriers and Chinese state-owned airlines drive specification upgrades as FAA NextGen and CAAC trajectory-based operation mandates take effect.
- Unmanned Aerial Vehicles:Military reconnaissance platforms and commercial delivery drones requiring autonomous navigation without ground station contact. Defense procurement in India and logistics pilot programs in the United Arab Emirates expand addressable demand beyond crewed aircraft.
- Military Aviation:Combat and transport aircraft with jam-resistant navigation and terrain-following requirements. Indigenous platform development under India's Make in India initiative creates localized sourcing mandates.
- General Aviation:Private and business aircraft with owner-operator maintenance economics. Fractional ownership fleets in the United States adopt AI-based turbulence prediction faster than full-ownership operators.
Commercial aviation dominates current procurement volumes; unmanned aerial vehicles are expanding most quickly as regulatory frameworks mature.
Technology:
Development investment splits between proven sensor integration and emerging predictive capabilities, with certification timeline risk determining buyer technology appetite.
- Sensor Fusion:Integration of inertial reference units, GPS, and air data computers into unified navigation solutions. Collins Aerospace and Honeywell architectures in the United States and France support single-pilot operation pre-certification for EASA's 2030 implementation target.
- Artificial Intelligence:Machine learning models predicting atmospheric disturbance and optimizing trajectory in real time. Business jet operators prioritize passenger comfort and fuel efficiency over acquisition cost.
- Autonomous Navigation:Deterministic algorithms for waypoint following and obstacle avoidance without human intervention. Urban air mobility developers in the United States and Germany require certifiable systems for electric vertical take-off and landing aircraft.
- Real-Time Data Processing:Edge computing architectures enabling sub-100-millisecond control loop latency. Military applications in Israel and South Korea demand hardened processing against electromagnetic interference.
Sensor fusion leads installed volumes; artificial intelligence is climbing the fastest as predictive capabilities displace reactive autopilot modes.
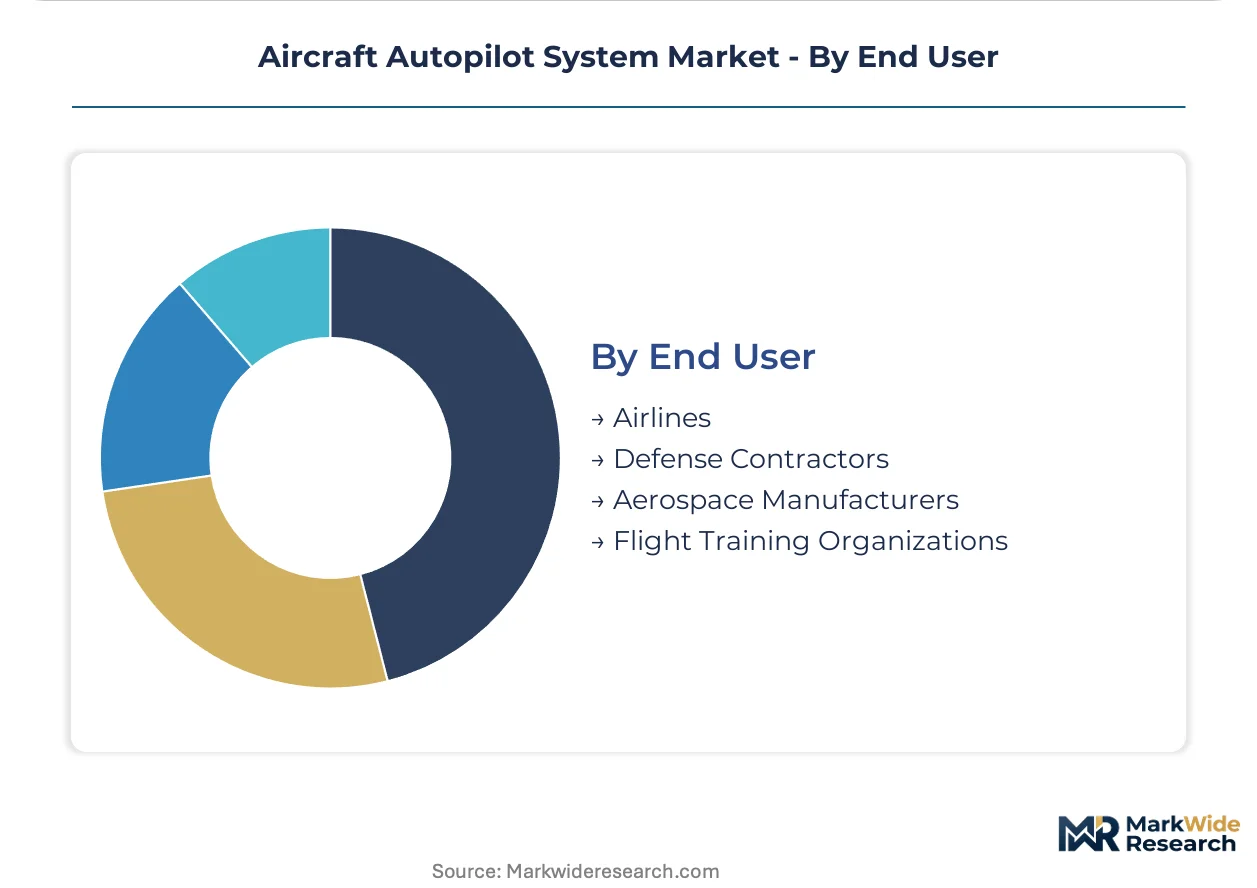
End User:
Procurement authority and technical integration capability vary — fleet operators prioritize long-term support contracts while manufacturers seek modular architectures for platform flexibility.
- Airlines:Technical procurement departments consolidating vendor relationships toward integrated flight deck suppliers. United States legacy carriers managing mixed Boeing and Airbus fleets under unified technical standards.
- Aerospace Manufacturers:Original equipment suppliers embedding autopilot systems during airframe assembly. Airbus in France and COMAC in China specify fly-by-wire architectures at design phase.
- Defense Contractors:System integrators requiring export-controlled software and sovereign data processing. India's Ministry of Defence mandates indigenous content for combat aircraft programs.
- Flight Training Organizations:Schools certifying pilots on autopilot-dependent operation profiles. Australian and Canadian training fleets upgrade to digital architectures for instrument rating curricula.
Airlines represent the largest procurement volume; aerospace manufacturers are gaining share fastest as new-build programs dominate over retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in aerospace hubs anchor regional demand, with certification authorities and fleet operators co-locating near technical universities and defense procurement centers.
United States
FAA NextGen mandates for trajectory-based operations drive commercial carrier upgrades, while defense procurement sustains military autopilot development. The FAA's Part 25 airworthiness standards enforce TCAS and autopilot redundancy requirements. Seattle and Wichita concentrate Boeing supplier networks and general aviation manufacturing, with retrofit programs accelerating at Dallas-Fort Worth maintenance hubs.
Germany
EASA CS-25 amendments for reduced-crew operations compress development timelines for fail-operational architectures. The EU Green Deal aviation emissions framework mandates fuel-efficient flight profiles through trajectory optimization. Hamburg and Munich host Airbus final assembly and avionics integration centers, with Frankfurt Main airport demanding CAT IIIb autoland capability.
China
CAAC alignment with ICAO standards plus indigenous cybersecurity protocols for foreign-sourced flight control software shape procurement patterns. State-owned airline fleet modernization programs dominate volume demand. Shanghai and Xi'an concentrate COMAC manufacturing and military aircraft production, with Tianjin hosting Airbus final assembly lines requiring localized autopilot sourcing.
India
The Ministry of Defence's Make in India initiative creates localized autopilot sourcing mandates for indigenous combat aircraft and unmanned platforms. Defense procurement budgets expand addressable demand beyond commercial aviation. Bangalore and Hyderabad concentrate aerospace engineering talent and unmanned systems development, with Hindustan Aeronautics Limited integrating foreign partnerships.
France
EASA single-pilot commercial operation frameworks under CS-25 mandate redundant autopilot channels with independent power architectures. Airbus design-phase specification of fly-by-wire systems locks in supplier relationships. Toulouse anchors global narrowbody and widebody final assembly, with Paris-Le Bourget maintaining business jet avionics integration clusters.
Aircraft Autopilot System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the autopilot system value chain, with integrated flight deck suppliers consolidating procurement relationships against discrete component specialists. The vendor base stratifies between full-service platform providers and narrow technology licensors. Three archetypes dominate: aerospace conglomerates with sensor fusion portfolios, avionics specialists targeting retrofit segments, and defense contractors with sovereign data processing capabilities. Competitive moves center on long-term support contract consolidation and pre-certification investments for reduced-crew operation mandates.
Within the integrated systems tier, Honeywell International Inc. and Collins Aerospace exemplify full-authority flight control platform providers, while Garmin Ltd. occupies a position anchoring the general aviation retrofit segment. Thales Group represents the European defense-aerospace conglomerate archetype with sovereign processing requirements.
| Leading Market Players |
|---|
| Thales Group |
| Rockwell Collins |
| Honeywell International Inc. |
| Dynon Avionics |
| Avidyne Corporation |
| Collins Aerospace |
| Genesys Aerosystems |
| Moog Inc. |
| Garmin Ltd. |
| Others |
Supply Flow & Price Mechanics
DO-178C certified software engineers concentrated in Seattle and Toulouse command compensation premiums that widen pricing spreads between premium-tier integrated flight deck suppliers and economy retrofit specialists. Labor-cost differentials between these certification-holding talent pools and general embedded systems developers in lower-cost engineering hubs directly translate into three-tier pricing stratification across commercial, military, and general aviation buyer segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs autopilot system procurement, with fail-operational CAT IIIb autoland architectures commanding substantial premiums over conventional electromechanical retrofits. Price differentiation rests on certification grade — EASA CS-25 amendments for reduced-crew operations versus legacy analog approvals — and after-sales service bundling spanning installation through long-term technical support. Cost compression in the conventional retrofit tier is intensifying because wiring harness replacement labor exceeds narrowbody residual values, squeezing margins for aging fleet upgrades. Defense contractors exhibit lowest price sensitivity due to sovereign data processing mandates, while general aviation owner-operators demonstrate highest elasticity as they weigh ADS-B compliance costs against aircraft market values.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth, Hamburg, and Shanghai anchor hub-and-spoke patterns for flight control hardware, with specialized servo actuator digital controllers flowing through aerospace logistics networks. Manufacturing concentrates in the United States, France, and Germany where EASA and FAA certification authorities co-locate with final assembly operations. The supply chain draws from gallium arsenide semiconductors, precision gyroscopic sensors, and rare-earth magnet materials for actuator motors. Single-source vulnerability in East Asian foundry capacity for radiation-hardened flight processors creates procurement risk during geopolitical disruptions. Distribution runs through OEM direct channels for new-build programs and certified repair stations for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft autopilot system market functions as a stable compounder, with regulatory mandates for reduced-crew operations and trajectory-based navigation driving steady fleet upgrade cycles regardless of macroeconomic volatility.
For Market Incumbents: Acquire AI sensor fusion startups to preempt displacement of reactive autopilot architectures by predictive flight control systems. Consolidate channel relationships with United States legacy carriers managing mixed Boeing and Airbus fleets under unified technical standards, while investing in DO-178C certification capacity to defend against embedded software engineering scarcity threatening expansion velocity. For New Entrants and Emerging Players: EASA CS-25 amendments for single-pilot commercial operations in Europe open a window for pre-certification partnerships with narrowbody retrofit specialists facing 2030 compliance deadlines. Target the urban air mobility segment in Germany and the United States where electric vertical take-off and landing aircraft developers require certifiable autonomous flight systems without incumbent legacy baggage. Pursue white-label sensor fusion modules for defense contractors under India's Make in India initiative. For Investors and Strategic Acquirers: Valuations sit cheapest among conventional autopilot retrofit specialists with established FAA Part 25 repair station networks but limited digital architecture roadmaps. Long-term viability hinges on regulatory tailwinds for reduced-crew operations extending across the next decade. Watch EASA implementation timelines for single-pilot commercial certification as the inflection signal determining which pre-certified platforms capture fleet upgrade budgets.| Strategic Initiative | Industry Significance |
|---|---|
| Fail-Operational Architecture Development | EASA CS-25 amendments for reduced-crew operations mandate triple-redundant autopilot channels with independent power architectures. |
| AI Sensor Fusion Integration | Machine learning-based turbulence prediction converging with Honeywell and Collins inertial reference units enables predictive flight control adjustments. |
| Urban Air Mobility Partnership | Joby Aviation and Archer development programs in the United States require certifiable autonomous flight systems for electric vertical take-off and landing aircraft. |
| India Defense Localization | The Ministry of Defence's Make in India initiative creates captive demand for indigenous autopilot sourcing in combat aircraft and unmanned platforms. |
| Long-Term Support Contract Consolidation | United States legacy carriers prefer full-service contracts covering installation, training, and technical support over discrete component transactions. |
Methodological Framework
Multiple input streams — technical interviews with avionics procurement directors at United States legacy carriers, regulatory affairs specialists at EASA and FAA certification centers, and flight control engineering leads at Airbus and COMAC — were reconciled against secondary validation from FAA NextGen implementation documentation, EASA CS-25 amendment filings, and CAAC cybersecurity protocol releases. Bottom-up triangulation across fleet operator upgrade schedules and top-down reconciliation against OEM production forecasts anchored market sizing.
Data-stream reconciliation across product type, application, technology, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, new-build program ramp rates, and regulatory compliance deadline clustering. Forecast inputs incorporated trajectory-based operation mandate timelines, semiconductor foundry capacity constraints, and DO-178C certified developer availability.
Revisions become necessary when EASA single-pilot certification timelines shift, East Asian foundry capacity experiences disruption, or FAA NextGen implementation accelerates beyond baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
General Aviation Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Air Deflector Market
Aircraft
Military Transport Aircraft Market
Aircraft
Middle-East Aviation Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Military Fixed-Wing Aircraft Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Aircraft Window Frame Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Aircraft Fairings Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Commercial Aircraft Leasing Market