
 Autonomous Pods Market | 2026-2036
Autonomous Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Pods Market Outlook
Campus transportation is expanding as universities replace diesel shuttles with electric autonomous pods. Waymo leverages its LiDAR heritage to dominate highway-adjacent logistics trials. Einride anchors European freight-pod deployments through its cabless design specialization. Navya sustains a manufacturing footprint in France while competing on low-speed urban shuttle contracts.
Autonomous pods are self-driving, enclosed vehicles operating at SAE Level 4 or above, typically restricted to geofenced routes below 25 mph and powered by battery-electric drivetrains with redundant sensor arrays; they move passengers or goods without human operators in controlled environments. Shuttle deployments lead absolute unit volume as cities prioritize first-mile transit gaps, while last-mile delivery pods capture accelerating interest from logistics providers seeking to eliminate driver costs in dense districts. LiDAR-based navigation still occupies the premium tier, though computer vision systems are narrowing the performance gap in fair-weather corridors.
The FAA governs airspace integration for future aerial pod concepts, while the NHTSA oversees ground-based autonomous vehicle safety standards and crash-test protocols that determine market access. California's DMV operates the most permissive real-world testing framework in the United States, drawing fleet operators to its public-road pilot zones. Stakeholders must monitor how municipal liability rules evolve before committing capital to multi-city pod networks.
Market Dynamics
LiDAR cost deflation below $500 per unit is compressing sensor economics and enabling fleet-scale deployments across university campuses and logistics corridors previously priced out of autonomous navigation.
Growth Catalysts
- California DMV frameworks:The state's permissive real-world testing protocols draw fleet operators to public-road pilot zones, accelerating validation cycles for geofenced shuttle networks.
- First-mile transit gaps:Municipalities prioritize autonomous shuttles to bridge connectivity deserts between residential clusters and mass transit nodes, driving unit demand in dense urban districts.
- Battery-electric drivetrain maturation:Energy density gains in solid-state cell architectures extend operational range for low-speed pods operating 18-hour service windows.
Market Restraints
- LiDAR supply concentration:High-fidelity sensor production clusters in East Asian manufacturing zones create vulnerability to component allocation disruptions.
- NHTSA crash-test protocols:Extended validation timelines for occupant protection in non-traditional vehicle geometries delay market access for novel form factors.
- Computer vision performance ceilings:Fair-weather dependency of camera-dominant systems limits deployment latitude in precipitation-prone corridors.
Strategic Opportunities
- FAA low-altitude corridor clarification:Emerging airspace integration rules for aerial pod concepts open vertical mobility layers beyond ground-based geofencing.
- Last-mile logistics densification:E-commerce fulfillment networks seek driverless delivery pods to eliminate labor costs in urban core distribution.
- France manufacturing anchoring:European production footprints near established automotive supplier ecosystems reduce logistics friction for continental fleet deployments.
Industry Challenges
- Systems integration complexity:Retrofitting legacy campus shuttle infrastructure with V2X communication hardware demands specialized engineering talent scarce in mid-sized operators.
- Municipal liability fragmentation:Inconsistent tort frameworks across city jurisdictions complicate insurance underwriting for multi-node pod networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Pods Market |
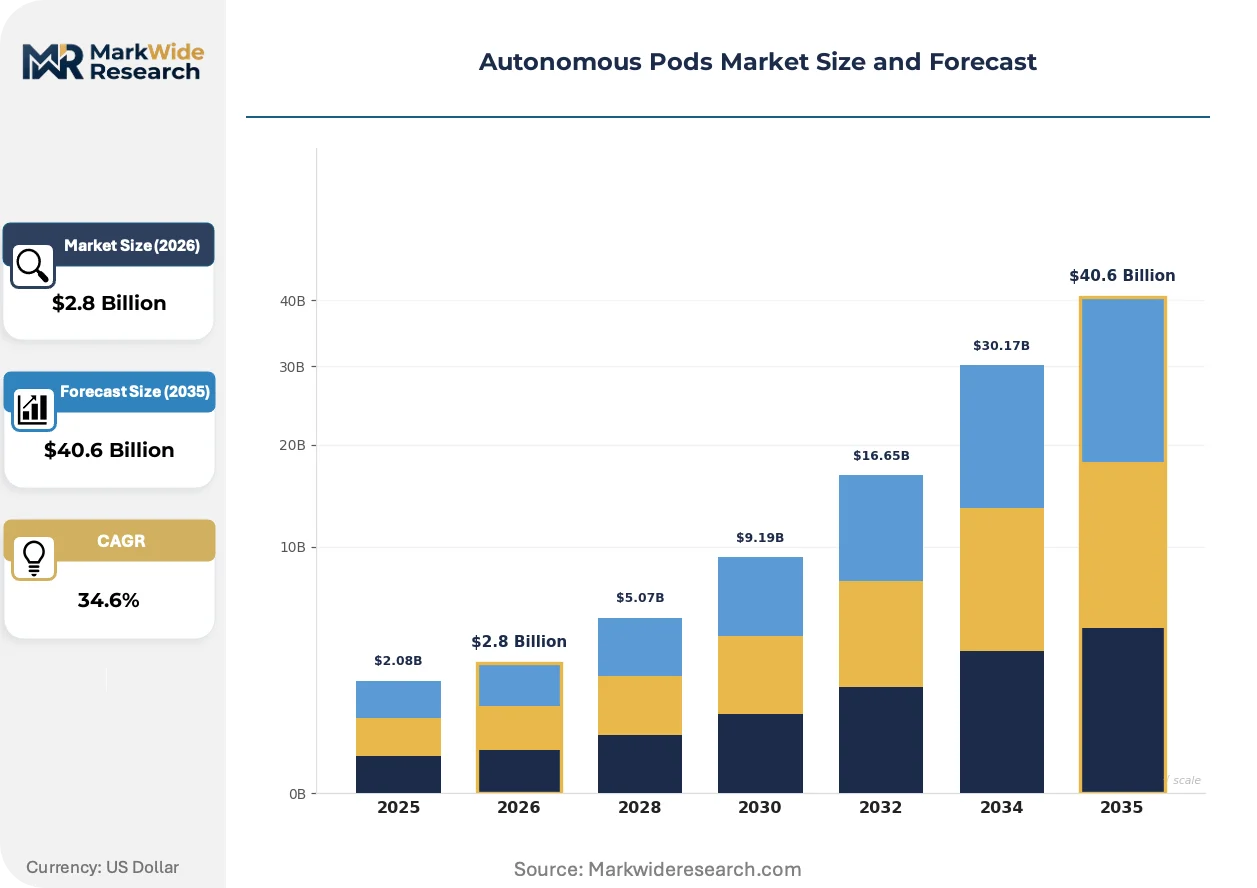
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $40.6 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Shuttle, Delivery, Passenger, Cargo Application: Campus Transportation, Urban Mobility, Last-Mile Delivery, Logistics Technology: LiDAR, Computer Vision, AI Navigation, V2X Communication End User: Government, Enterprises, Educational Institutions, Logistics Providers |
| Companies Covered | Waymo, Einride, MILLA POD, Nuro, Easymile, Navya, Aurrigo, Westfield AV, EVIE Autonomous, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Pods Market Strategic Shifts
Sensor fusion architectures and edge computing deployment are compressing the gap between premium LiDAR navigation and cost-optimized computer vision systems across controlled-environment fleets.
Multi-modal sensor stacks is unifying camera, radar, and low-cost LiDAR inputs into single perception pipelines. Campus transportation operators in California's university clusters adopt these integrated arrays to reduce per-unit sensor spend. The convergence is unifying hardware cost structures across premium and standard pod tiers.
EU AI Act risk classification rules are imposing conformity assessment burdens on autonomous decision systems in passenger-moving applications. Pod manufacturers face expanded documentation requirements for algorithmic transparency in geofenced shuttle deployments. French and German operators accelerate compliance investments ahead of 2025 enforcement windows.
Universities now specify performance-based service contracts rather than asset ownership for campus mobility. Fleet management platforms displace direct procurement as the dominant acquisition channel. This shift concentrates most visibly in California and Texas public university systems seeking operational expenditure treatment for sustainability reporting.
Autonomous Pods Market Segmentation
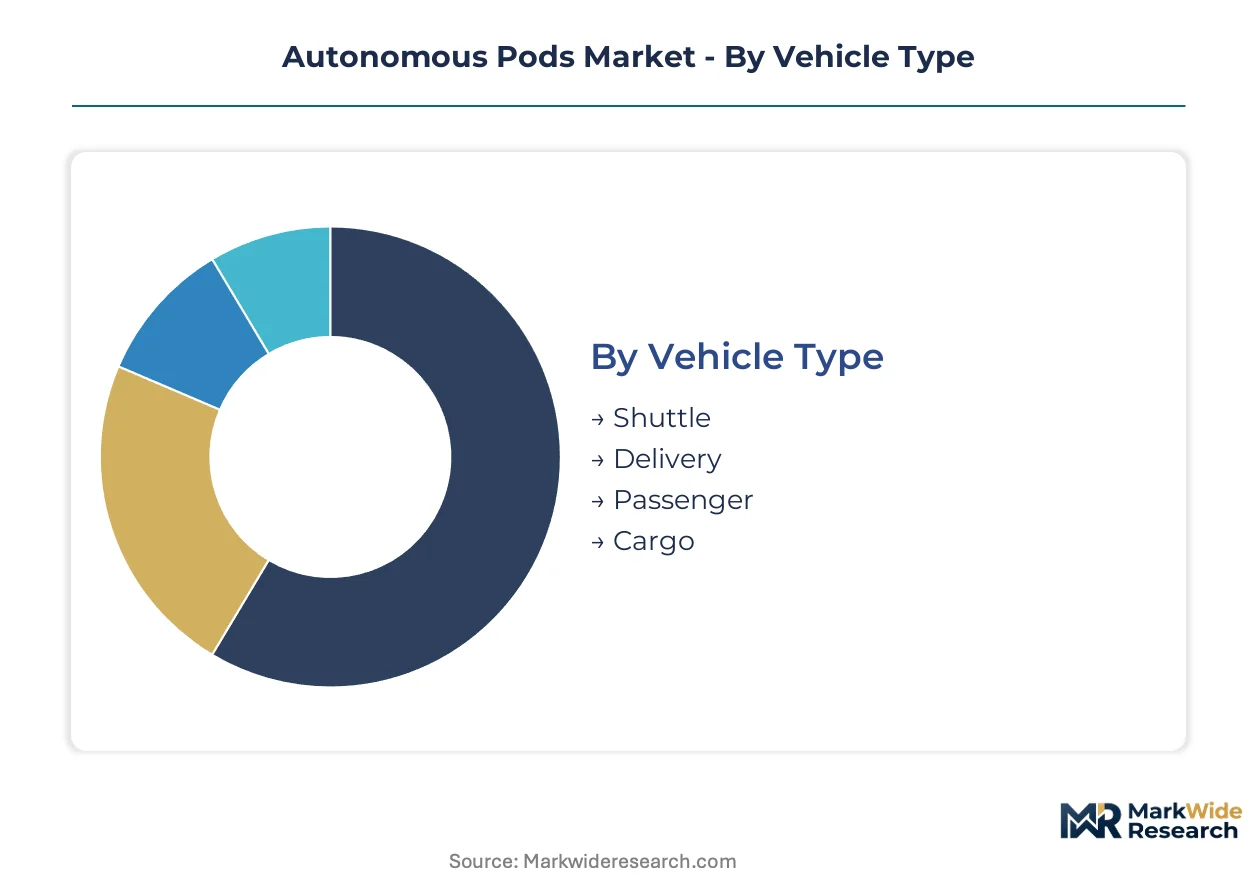
Segmentation in autonomous pods reveals how deployment economics fragment across operational envelopes. Buyers select vehicle configurations based on geofence complexity, payload requirements, and regulatory exposure rather than unit cost alone.
Vehicle Type:
Buyers differentiate by duty cycle intensity and passenger versus cargo orientation, with fleet operators prioritizing form factors that minimize sensor redundancy costs.
- Shuttle:Enclosed multi-passenger platforms operating at 15-25 mph with redundant LiDAR arrays dominate university campus contracts. California's public university systems specify these for 18-hour service windows between dormitory clusters and transit nodes, with procurement shifting to performance-based service contracts rather than asset ownership.
- Delivery:Compact cargo compartments on low-speed chassis eliminate driver costs in dense urban districts. E-commerce fulfillment networks in Texas and Florida pilot these for last-mile densification where sidewalk width permits mixed-traffic operation.
- Passenger:Single-occupant or dual-occupant pods prioritize comfort specifications for executive transport and healthcare campus applications.
- Cargo:Larger-volume variants serve industrial park logistics with palletized freight capacity and weatherized compartments.
Volume sits with Shuttle deployments; growth tilts toward Delivery as logistics providers eliminate labor costs in urban core distribution.
Application:
Application selection tracks infrastructure maturity and municipal risk tolerance, with early adopters clustering where liability frameworks clarify fastest.
- Campus Transportation:Geofenced university and corporate environments offer controlled deployment corridors with minimal mixed-traffic exposure. California DMV permissive testing protocols accelerate validation cycles here, while Texas public university systems follow with operational expenditure treatment for sustainability reporting.
- Urban Mobility:First-mile transit gaps between residential clusters and mass transit nodes drive municipal procurement in dense districts. Cities prioritize these shuttles where bus route economics fail.
- Last-Mile Delivery:Dense urban cores with predictable delivery windows attract logistics provider investment.
- Logistics:Industrial corridor freight movement leverages dedicated lanes and private road access.
Campus Transportation captures current fleet scale; Urban Mobility expands most quickly as municipalities bridge connectivity deserts.
Technology:
Technology selection divides buyers by weather exposure tolerance and sensor budget allocation, with cost deflation compressing historical tier boundaries.
- LiDAR:High-fidelity point-cloud generation enables operation in precipitation and low-light conditions. Premium campus shuttle fleets in California and Arizona specify these arrays despite supply concentration risks in East Asian manufacturing zones.
- Computer Vision:Camera-dominant systems narrow the performance gap in fair-weather corridors at sub-$500 per-unit economics. Texas and Florida logistics pilots adopt these where precipitation dependency poses acceptable operational constraints.
- AI Navigation:End-to-end learned driving policies reduce hand-coded rule dependency.
- V2X Communication:Vehicle-to-infrastructure integration enables coordinated fleet movement at intersections.
LiDAR retains premium positioning; Computer Vision gains share fastest as multi-modal sensor fusion compresses cost-performance gaps.
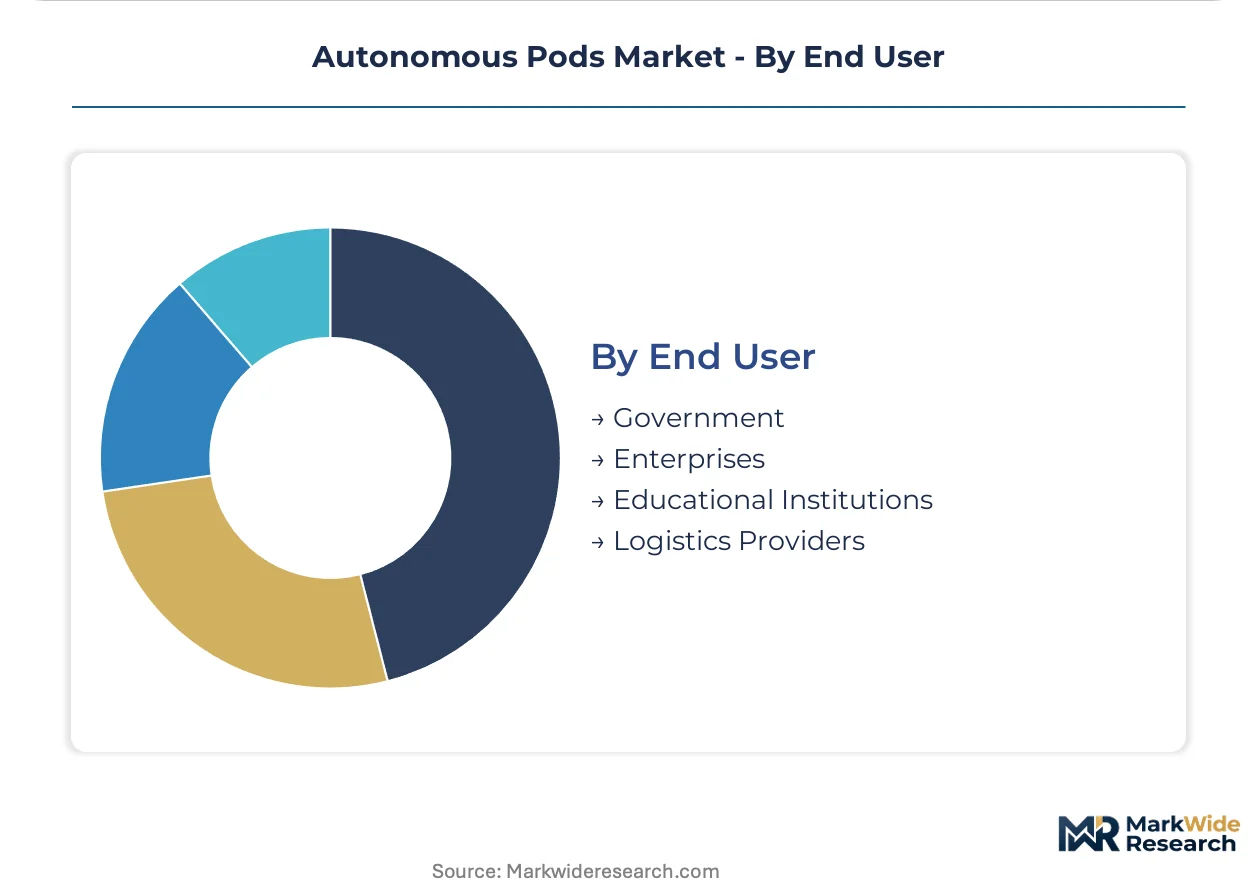
End User:
End user category determines procurement mechanism and contract structure, with institutional buyers shifting from capital expenditure to service-based acquisition.
- Government:Municipal transit authorities specify performance metrics for first-mile connectivity contracts. California and Texas municipalities lead in public-road pilot zone establishment.
- Enterprises:Corporate campus operators prioritize employee shuttle services with brand-aligned vehicle aesthetics.
- Educational Institutions:Universities specify sustainability reporting compliance and 18-hour operational windows. California's university clusters concentrate demand as diesel shuttle replacement accelerates.
- Logistics Providers:E-commerce and parcel networks seek driverless delivery to densify urban core distribution.
Educational Institutions anchor near-term volume; Logistics Providers drive steepest expansion trajectory as labor cost elimination motivates fleet conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in France and the United States while consumption clusters in California's university corridors and European logistics hubs. Production capacity expansion tracks regulatory clarity rather than demand signals alone.
United States
California's DMV permissive testing protocols draw fleet operators to public-road pilot zones between dormitory clusters and transit nodes. The FAA governs emerging low-altitude corridor rules for aerial pod concepts. Texas public university systems accelerate diesel shuttle replacement with operational expenditure treatment for sustainability reporting.
France
Navya sustains manufacturing operations near established automotive supplier ecosystems while competing on low-speed urban shuttle contracts. The EU AI Act risk classification rules impose conformity assessment burdens on autonomous decision systems in passenger-moving applications. The Auvergne-Rhône-Alpes region anchors continental production footprints for fleet deployments.
Germany
Industrial corridor freight movement leverages dedicated lanes and private road access for cargo-pod validation. The KBA oversees ground-based autonomous vehicle safety standards and crash-test protocols. Bavaria's automotive supplier density reduces logistics friction for continental fleet procurement.
United Kingdom
Aurrigo anchors deployment activity through manufacturing specialization in low-speed shuttle form factors. The country's national automotive regulator validates occupant protection in non-traditional vehicle geometries. Greater London municipalities prioritize first-mile transit gaps between residential clusters and mass transit nodes.
Sweden
Einride anchors European freight-pod deployments through cabless design specialization for industrial logistics corridors. The country's national transport authority coordinates with EU frameworks on autonomous vehicle safety validation. Gothenburg's port and logistics infrastructure supports pilot programs for palletized freight movement.
Autonomous Pods Market Competitive Environment
Top-tier vendors anchor highway-adjacent logistics and premium campus shuttle tiers, while mid-cap specialists compete on low-speed urban contracts and regional manufacturing proximity. The vendor base separates into LiDAR-heritage operators, cabless freight specialists, and integrated fleet management platforms. Three archetypes dominate: technology licensors with sensor-stack advantages, manufacturing-anchored European producers, and software-centric fleet operators. Competitive moves concentrate on strategic partnerships with university systems and capacity expansion near automotive supplier clusters.
Within the LiDAR-heritage tier, Waymo occupies a position exemplifying premium navigation-stack advantages. Among European manufacturing-anchored specialists, Navya and Einride represent contrasting approaches to regional production proximity versus cabless freight specialization. These three anchors illustrate how competitive positioning splits between sensor technology depth, manufacturing geography, and form-factor specialization.
| Leading Market Players |
|---|
| Waymo |
| Einride |
| MILLA POD |
| Nuro |
| Easymile |
| Navya |
| Aurrigo |
| Westfield AV |
| EVIE Autonomous |
| Others |
Value Chain & Pricing Dynamics
LiDAR sensor costs cascading below $500 per unit compress premium-tier pricing while amplifying procurement leverage for fleet-scale buyers across California university clusters and Texas logistics corridors. This cost deflation redraws tier boundaries between high-fidelity navigation stacks and multi-modal sensor fusion alternatives.
Pricing Analysis
Cost-down pressure on shuttle-tier pods accelerates because computer vision systems narrow performance gaps at sub-$500 sensor economics. Three-tier pricing structure across premium LiDAR, standard sensor-fusion, and economy vision-dominant configurations tracks certification level and weather-operability specifications. California educational institutions exhibit lowest price sensitivity where sustainability reporting mandates override unit economics, while Texas logistics providers drive hardest bargain negotiations for last-mile delivery fleets. Price differentiation hinges on SAE validation tier and after-sales telemetry bundling.
Supply Chain Analysis
Direct-to-fleet-operator channels handle hyperscale university procurement, while distributor-mediated pathways serve mid-sized municipal transit authorities. Component manufacturing concentrates in Taiwan, South Korea, and Japan for solid-state LiDAR emitters and edge-computing processors. Raw material dependencies span rare-earth magnet supply for electric drivetrains, lithium-ion cell cathode chemistry, and precision optical glass for sensor housings. Single-source vulnerability in East Asian LiDAR fabrication creates allocation risk during demand surges. Distribution runs through integrated fleet management platforms displacing traditional asset vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous pods occupy a technology-transition phase where battery-electric drivetrains and solid-state sensor architectures displace legacy diesel shuttles and mechanical steering systems. Stakeholder positioning must account for this hardware-software convergence reshaping procurement patterns.
For Market Incumbents: Cement LiDAR-heritage advantages through backward integration into solid-state emitter production, securing supply priority during allocation crunches. Anchor manufacturing capacity near automotive supplier clusters in France and Germany to reduce logistics friction for European fleet deployments. Defend against camera-dominant entrants by accelerating SAE Level 4 certification timelines for precipitation-capable navigation stacks. For New Entrants and Emerging Players: Enter via last-mile delivery segments in Florida and Texas where fair-weather corridors minimize sensor performance requirements and municipal liability frameworks remain permissive. Target mid-sized university systems outside California seeking operational expenditure treatment without premium-tier procurement budgets. Pursue white-label fleet management partnerships with established campus infrastructure providers rather than direct asset sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor cabless freight specialists with validated industrial corridor deployments in Sweden and Germany. Long-term viability hinges on regulatory clarity for multi-city pod networks across the analysis window. Monitor FAA low-altitude corridor rulemaking as inflection signal for aerial pod concept commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| LiDAR Supply Agreement | Secures emitter allocation priority from Taiwan and South Korean fabs during demand spikes. |
| Campus Service Contract Conversion | Shifts California universities from asset ownership to performance-based fleet management platforms. |
| EU AI Act Compliance Investment | Accelerates algorithmic documentation for French and German passenger shuttle deployments ahead of enforcement. |
| Solid-State Battery Integration | Extends operational range for 18-hour service windows in Texas public university systems. |
| V2X Infrastructure Partnership | Enables coordinated intersection movement for urban mobility deployments in Greater London municipalities. |
Study Parameters
Multi-period observation of LiDAR cost trajectories, DMV permit issuance rates, and university fleet conversion timelines anchored the trend analysis, supplemented by interviews with autonomous vehicle engineering directors, campus transportation procurement managers, municipal transit authority planners, and logistics fleet operators. Secondary validation drew from NHTSA safety filings, California DMV testing databases, FAA airspace integration notices, EU AI Act implementation guidance, and SEC disclosures from publicly traded sensor manufacturers. Bottom-up unit deployment estimates triangulated against top-down addressable market sizing across vehicle type and application segments.
Input-output matrices modeled sensor cost elasticity, regulatory pathway duration, and fleet operator procurement cycle phasing throughout the forecast period. Segmentation dimensions spanned vehicle configuration, application environment, navigation technology tier, and end-user institutional category. CAGRs derived from logistic diffusion curves fitted to historical technology adoption patterns in controlled-environment mobility, adjusted for battery-electric drivetrain maturation curves and solid-state sensor commercialization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NHTSA rulemaking delays or LiDAR supply chain disruptions. Projections reflect assumptions regarding FAA low-altitude corridor clarification velocity and municipal liability framework convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
North America AUV Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market