
 Europe Turboprop Aircraft Market | 2026-2036
Europe Turboprop Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Turboprop Aircraft Market Foresight
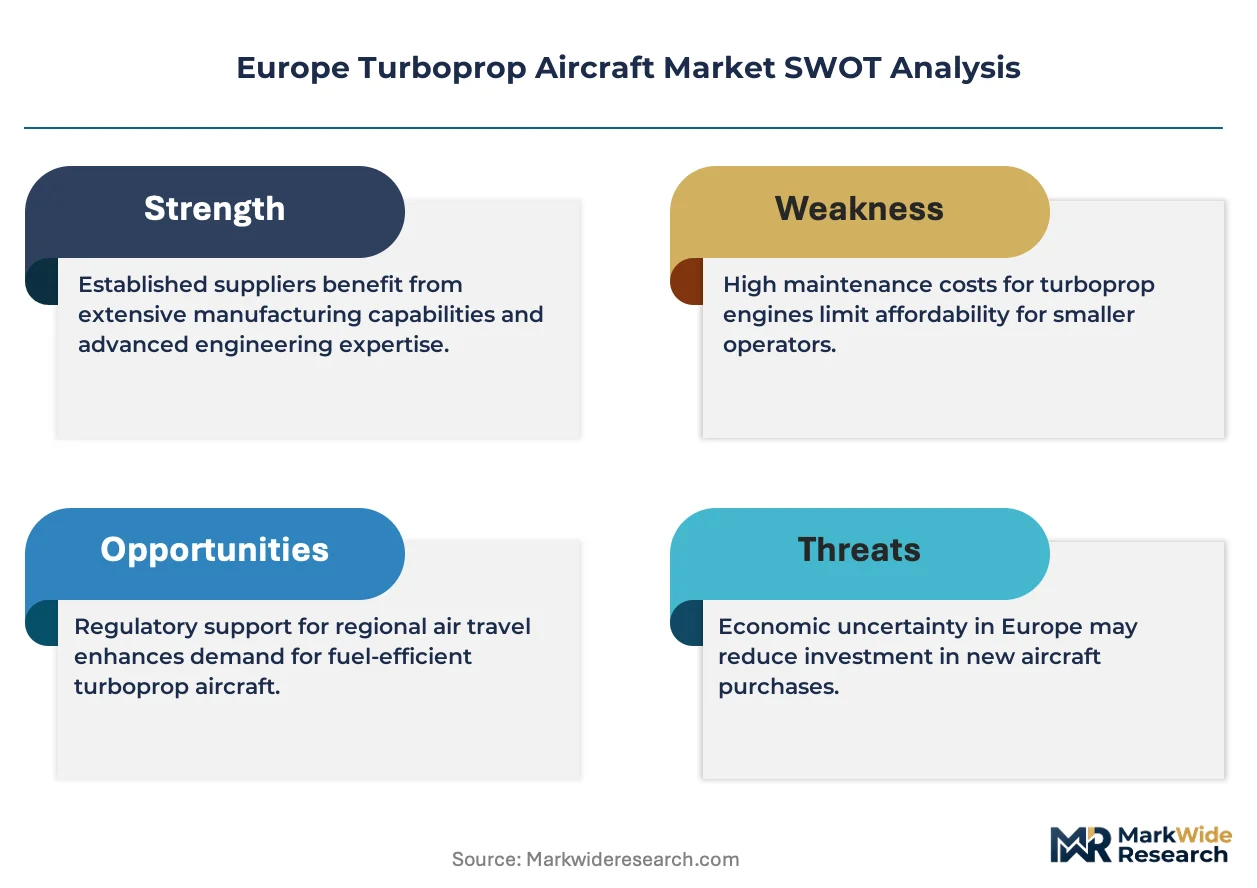
Regional connectivity carriers is reorganizing European turboprop demand away from legacy flag carriers toward independent short-haul operators. Deutsche Aircraft sustains development momentum through its D328eco program targeting zero-emission-compatible architecture. ATR dominates the continental order book with proven fuel efficiency metrics on thin routes. Textron Aviation Inc. leverages its King Air lineage to occupy the executive turboprop tier against jet alternatives.
A turboprop aircraft employs gas turbine engines driving constant-speed propellers, typically operating at altitudes below 25,000 feet with cruise speeds of 300-400 knots for missions spanning 500-1,500 nautical miles. The configuration delivers superior fuel burn per seat-mile versus regional jets, making it indispensable for low-density European routes and special-mission applications. Regional turboprops command the largest installed base across the continent, while utility turboprops capture disproportionate margin pools in maritime patrol and multi-role government configurations. Executive turboprops represent the fastest-growing product category as fractional ownership platforms expand Nordic and Alpine access.
EASA certification requirements and the EU Green Deal's sustainable aviation fuel mandates are reshaping manufacturer R&D priorities toward hybrid-electric propulsion compatibility. REACH compliance on composite materials and the F-Gas Regulation on onboard cooling systems add compliance layers to new platform development. Stakeholders must monitor ETS carbon pricing trajectories and national PSO contract terms to anticipate fleet replacement cycles and financing structures.
Market Dynamics
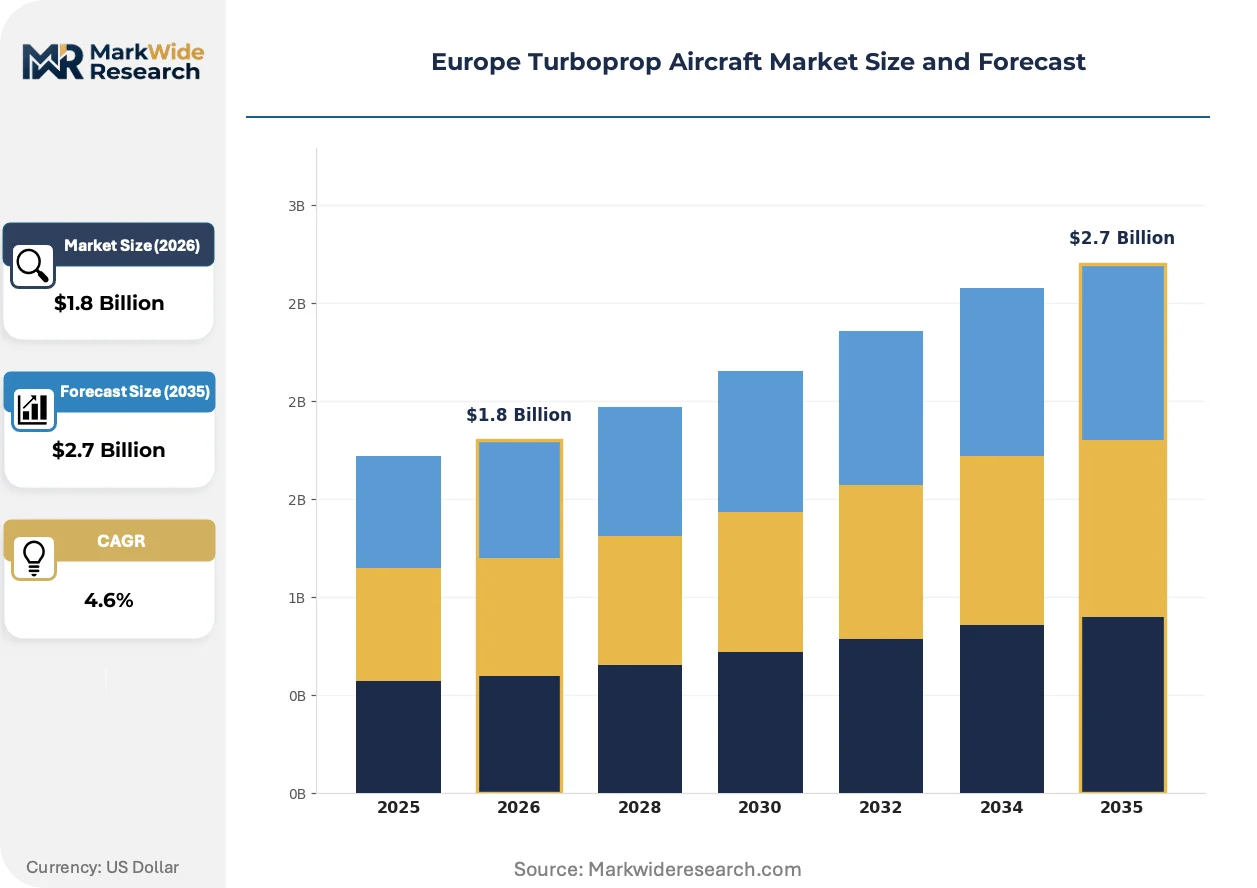
EU Green Deal mandates on sustainable aviation fuel are compressing replacement cycles for aging regional fleets, forcing operators to prioritize fuel-efficient platforms over legacy jet configurations on thin European routes.
Growth Catalysts
- PSO Contract Expansion:National governments across France, Germany, and Italy are expanding public service obligation routes, mandating connectivity to remote airports that only turboprops serve economically.
- SAF Mandate Alignment:The EU Green Deal's sustainable aviation fuel requirements favor turboprop burn rates, positioning the segment ahead of regional jets for compliance pathway simplicity.
- Scandinavian Fleet Renewal:Nordic operators are accelerating retirement schedules for 30-year-old regional jets, creating concentrated demand for modern turboprop replacements with 40% better seat-mile economics.
Market Restraints
- Engine Supply Concentration:Pratt & Whitney Canada and GE Aerospace dominate turboprop powerplant supply, creating single-source vulnerability for European airframers during production ramps.
- Reach Compliance Costs:ECHA restrictions on composite material chemistry add certification delays and material substitution expenses to new platform development timelines.
- Regional Jet Residual Value:Depressed secondary markets for aging 50-seat jets delay retirement decisions, extending competitive pressure on turboprop route assignments.
Strategic Opportunities
- Hybrid-Electric Architecture:Battery-hybrid propulsion convergence offers zero-emission-compatible platforms for sub-500 nautical mile missions, with Deutsche Aircraft positioning the D328eco for this transition window.
- Maritime Patrol Expansion:Coastal surveillance requirements across Mediterranean and North Sea borders are opening multi-role government configurations with higher margin profiles than passenger variants.
- Alpine Fractional Ownership:Executive turboprop demand from Swiss and Austrian private aviation platforms is creating premium-tier volume independent of airline cyclicality.
Industry Challenges
- EASA Certification Bottlenecks:Novel propulsion architectures face extended validation timelines at the EU's aviation safety agency, compressing first-mover advantage windows for hybrid platforms.
- Specialized Maintenance Labor:Turboprop-specific airframe and powerplant technicians concentrate at legacy regional carriers, creating recruitment friction for new entrants and expanding operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Turboprop Aircraft Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regional Turboprops, Utility Turboprops, Agricultural Turboprops, Executive Turboprops End User: Commercial Airlines, Government Agencies, Private Owners, Charter Operators Application: Passenger Transport, Cargo Transport, Surveillance, Training Technology: Digital Cockpits, Advanced Avionics, Fuel-Efficient Engines, Enhanced Safety Systems |
| Companies Covered | Textron Aviation Inc., Deutsche Aircraft, ATR, Airbus SE, Grob Aircraft SE, PILATUS AIRCRAFT LTD, Lockheed Martin Corporation, Embraer S.A., DAHER, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Turboprop Aircraft Market Shifts & Advancements
Propulsion electrification and sustainable fuel compatibility are reshaping manufacturer R&D allocation, while procurement patterns shift toward lifecycle operating cost guarantees rather than upfront acquisition pricing.
Hybrid-electric distributed propulsion is supplanting conventional twin-turbine layouts in next-generation development programs. Scandinavian regional operators are piloting retrofit assessments for battery-assist configurations. This architecture is supplanting pure turboprop economics on routes under 300 nautical miles by enabling 15-20% fuel burn reductions.
REACH and the F-Gas Regulation are tightening material and cooling system specifications for new type certifications. EASA is integrating these chemical compliance layers into concurrent airworthiness reviews. Thin-route regional aircraft face disproportionate cost impacts as refrigerant and composite substitution requirements compound.
Power-by-the-hour contracts with guaranteed availability metrics are displacing traditional maintenance reserve structures. Independent regional carriers in Italy and Spain are demanding consolidated service packages from airframers. This consolidation is most visible in Alpine connectivity markets where operational reliability directly determines PSO contract renewals.
Europe Turboprop Aircraft Market Segmentation
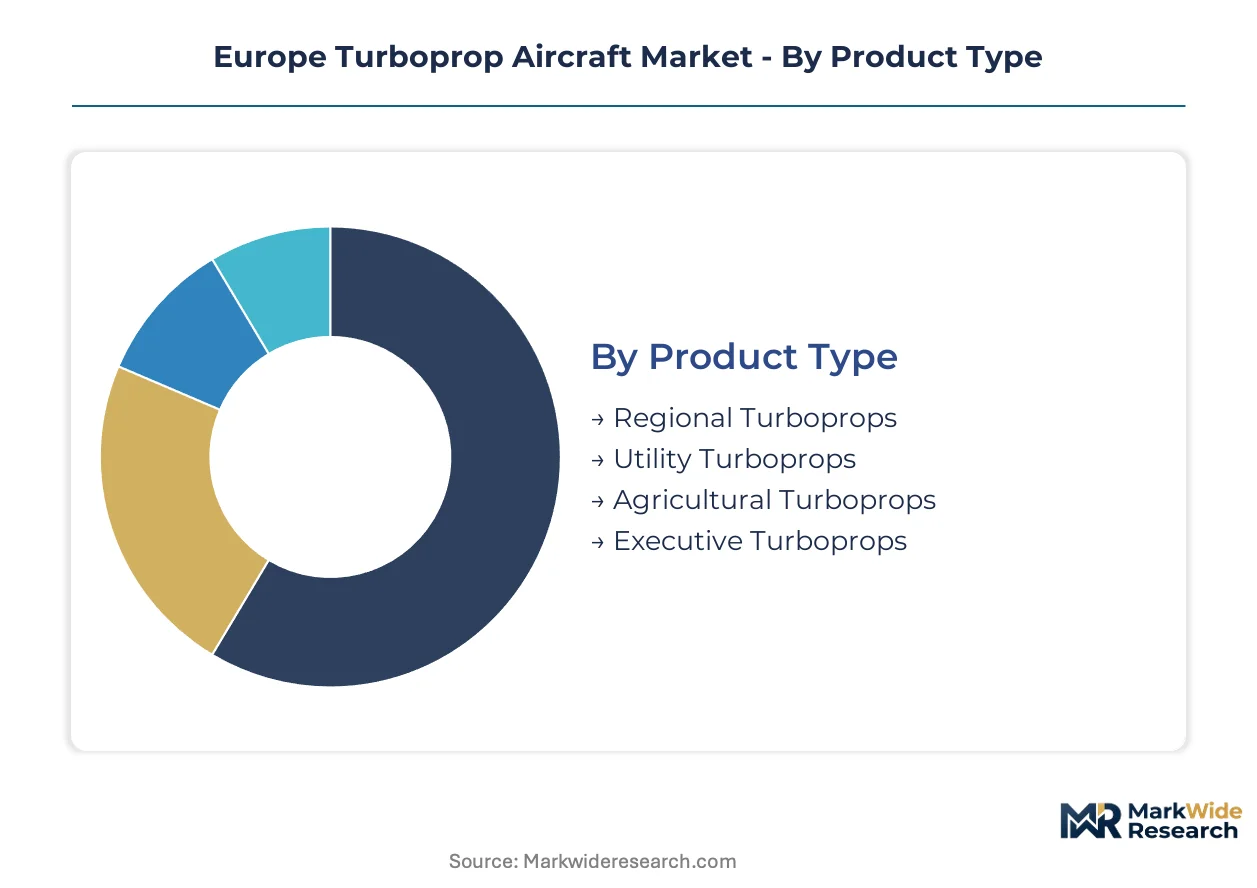
Segmentation reveals how EU Green Deal pressures and PSO contract structures concentrate procurement across distinct operational profiles. Understanding these divides clarifies where fuel efficiency mandates and certification requirements reshape fleet planning priorities.
Product Type:
Regional turboprops dominate procurement within France, Germany, and Italy, while utility and executive variants draw stronger export-linked demand from Nordic and Alpine operators.
- Regional Turboprops:These 30-70 seat platforms serve thin-density routes under 500 nautical miles with seat-mile economics 40% superior to regional jets. French and Italian PSO contracts concentrate demand for 50-seat configurations connecting secondary cities to hub airports.
- Executive Turboprops:Pressurized cabins and 300-400 knot cruise speeds target fractional ownership platforms across Switzerland and Austria. Alpine access requirements and short-runway performance specifications drive specification premiums above airline variants.
- Utility Turboprops:Unpressurized, high-wing designs with reinforced landing gear serve multi-role government contracts.
- Agricultural Turboprops:Specialized dispensing systems and low-altitude maneuverability profiles address seasonal crop protection demand.
Regional turboprops command the established base. The steepest expansion runs through executive turboprops.
End User:
Cost tier stratification separates price-sensitive commercial operators from premium-tier private and government buyers with divergent specification requirements.
- Commercial Airlines:Independent regional carriers in Italy and Spain prioritize lifecycle operating cost guarantees over acquisition price. Fleet standardization pressures drive consolidation toward ATR and Embraer platforms with established maintenance networks.
- Government Agencies:Maritime patrol and surveillance configurations across Mediterranean and North Sea borders command higher margins than passenger variants. Multi-role adaptability requirements extend procurement cycles but reduce per-mission operating costs.
- Private Owners:Individual acquisition volumes concentrate in Swiss and Austrian Alpine corridors.
- Charter Operators:Seasonal demand fluctuation requires flexible lease structures and rapid reconfiguration capability.
Commercial airlines absorb the highest unit volumes. Government agencies generate the strongest margin contribution per airframe.
Application:
Volume concentration in passenger transport contrasts with surveillance applications where technology integration creates pricing power.
- Passenger Transport:Scheduled service on sub-500 nautical mile routes constitutes the core revenue base. PSO contract renewals across France and Germany hinge on reliability metrics and emissions compliance trajectories.
- Surveillance:Sensor integration and extended loiter requirements transform basic airframes into specialized platforms. Coastal enforcement agencies in Italy and Greece specify maritime radar and electro-optical payload compatibility.
- Cargo Transport:Quick-change interior configurations serve overnight parcel networks.
- Training:Dual-control cockpits and forgiving stall characteristics address flight school procurement.
Passenger transport anchors installed fleet numbers. Surveillance applications are climbing the fastest on defense spending alignment.
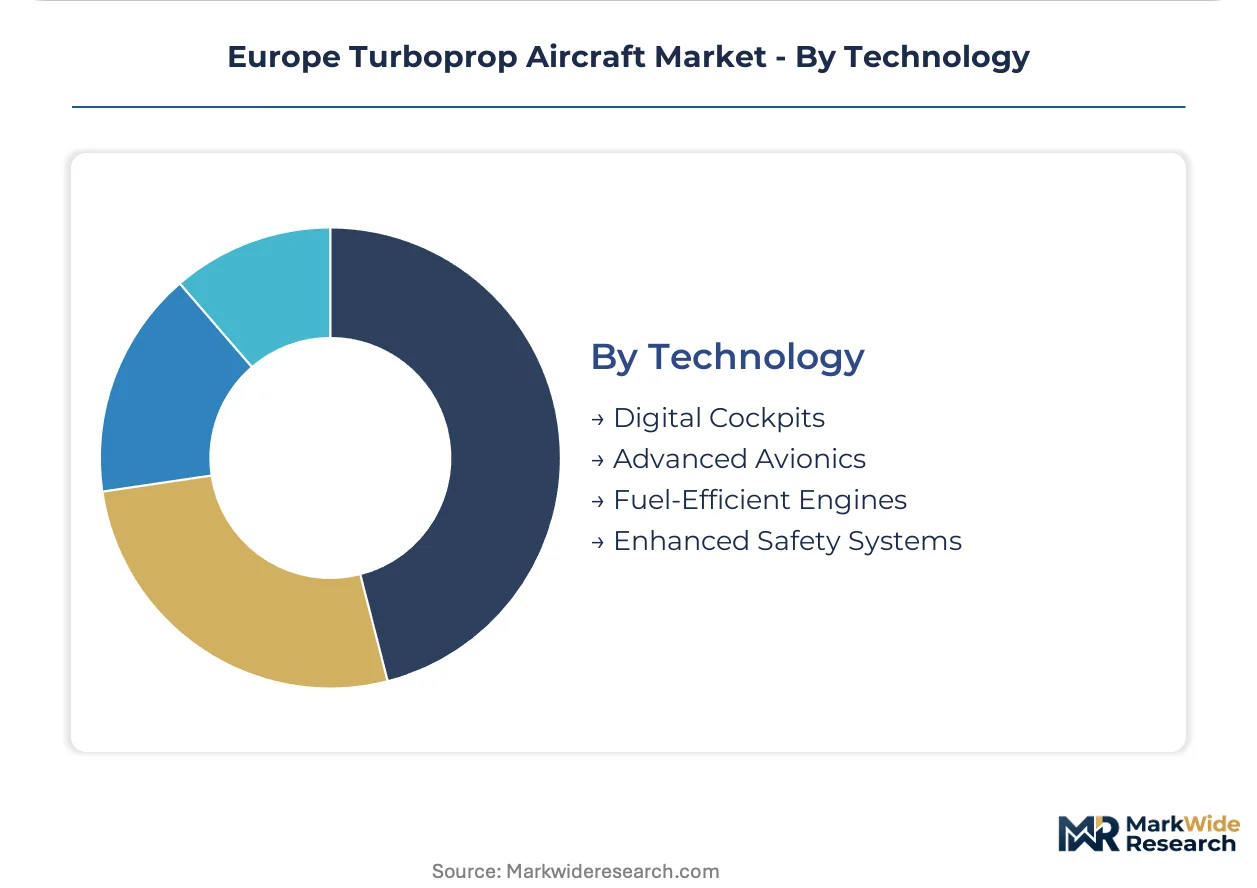
Technology:
Maturity gradients separate certified legacy systems from developmental architectures facing EASA timeline uncertainty.
- Fuel-Efficient Engines:Pratt & Whitney Canada and GE Aerospace powerplants deliver 15% burn reductions over prior generation turboprops. Scandinavian operators prioritize these platforms for EU ETS compliance pathway simplicity.
- Digital Cockpits:Integrated flight management and terrain awareness systems reduce crew workload on complex European airspace routes. Garmin and Collins Aerospace avionics suites dominate retrofit and new-build specifications.
- Advanced Avionics:Required navigation performance and satellite-based landing systems enable all-weather operations at minimally equipped airports.
- Enhanced Safety Systems:Stall protection and automated emergency descent functions address EASA certification mandates.
Fuel-efficient engines dominate current procurement. Digital cockpits are gaining share fastest on retrofit demand and new type certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports turboprop technology and subsystems to Scandinavian connectivity carriers, while Germany channels engineering services into Alpine fractional ownership platforms across Austria and Switzerland.
France
PSO contract renewals drive fleet standardization toward fuel-efficient 50-seat configurations. The EU Green Deal's SAF mandates accelerate retirement timelines for aging regional equipment. Toulouse and Occitanie host ATR's manufacturing and engineering clusters where hybrid-electric R&D programs concentrate.
Germany
Deutsche Aircraft's D328eco development anchors demand for zero-emission-compatible architectures. REACH compliance on composite materials shapes certification timelines for new platforms. Bavaria's aerospace corridor around Munich supplies propulsion integration and avionics systems to European airframers.
Italy
Independent regional carriers in Sicily and Sardinia prioritize lifecycle cost guarantees over acquisition pricing. F-Gas Regulation compliance adds refrigerant substitution requirements to new type certifications. Rome-Fiumicino and Milan-Linate connectivity routes concentrate turboprop deployment under expanded public service obligations.
United Kingdom
Maritime patrol configurations for North Sea surveillance generate multi-role government demand. EASA certification alignment post-Brexit creates dual-track regulatory compliance for UK-registered operators. Northern England and Scottish Highlands maintain essential air links where turboprops serve thin-density routes uneconomical for jet equipment.
Sweden
Nordic operators accelerate retirement of 30-year-old regional jets, creating concentrated replacement demand. EU ETS carbon pricing trajectories favor turboprop seat-mile economics on sub-500 nautical mile sectors. Stockholm-Arlanda and Gothenburg connectivity hubs anchor Scandinavian fleet renewal decisions.
Europe Turboprop Aircraft Market Competitive Landscape
Player mix skews toward established airframers with certified platforms and emerging specialists developing next-generation architectures. Consolidation pressures concentrate around fuel efficiency metrics and EASA certification timelines. Two strategic archetypes dominate: legacy manufacturers with installed base advantages, and development-stage entrants positioning for hybrid-electric transitions. Competitive moves center on strategic partnerships for propulsion integration and geographic expansion into PSO contract markets.
Within the legacy airframer tier, Textron Aviation Inc., ATR, and Deutsche Aircraft occupy positions defined by product lineage and development trajectory. Textron Aviation Inc. exemplifies the executive turboprop specialist with King Air heritage. ATR anchors the regional turboprop segment through proven fuel efficiency metrics on thin European routes. Deutsche Aircraft represents the development-stage archetype targeting zero-emission-compatible architecture through its D328eco program.
| Leading Market Players |
|---|
| Textron Aviation Inc. |
| Deutsche Aircraft |
| ATR |
| Airbus SE |
| Grob Aircraft SE |
| PILATUS AIRCRAFT LTD |
| Lockheed Martin Corporation |
| Embraer S.A. |
| DAHER |
| Others |
Supply & Pricing Matrix
Power-by-the-hour contracts with guaranteed availability metrics lock in supply access for regional carriers while anchoring price visibility across multi-year fleet commitments. These structures concentrate procurement leverage among Italian and Spanish operators demanding consolidated service packages from airframers.
Pricing Analysis
Current-generation fuel-efficient platforms command 15-20% acquisition premiums over prior-generation turboprops, while next-generation hybrid-electric architectures face pricing uncertainty pending EASA certification timelines. Three-tier pricing structure across premium executive, standard regional, and economy utility configurations differentiates by certification grade and after-sales bundling. Cost compression in the regional tier is intensifying because PSO contract terms cap allowable operating expenses. Commercial airlines exhibit highest price sensitivity, while government maritime patrol buyers absorb specification premiums for multi-role adaptability.
Supply Chain Analysis
Strategic stockpiling of critical powerplant components contrasts with just-in-time avionics delivery preferences among European airframers managing REACH compliance lead times. Manufacturing gravity centers on France, Germany, and Italy, with propulsion integration drawing from Canadian and US engine specialists. Supply chains rest on titanium alloy forgings, composite prepregs, and specialized refrigerants for F-Gas Regulation compliance. Single-source vulnerability concentrates at Pratt & Whitney Canada and GE Aerospace for turboprop powerplants. Distribution runs through airframer-direct channels for large fleet orders and specialized distributors for executive variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among independent regional carriers in Italy and Spain as fleet standardization pressures reduce supplier fragmentation. Consolidation among these operators amplifies negotiating leverage for lifecycle cost guarantees.
For Market Incumbents: Shield installed base advantages by deepening aftermarket service capture through power-by-the-hour contract extensions. Accelerate hybrid-electric certification investment to preempt Deutsche Aircraft's D328eco threat. Lock in exclusive propulsion integration partnerships with Pratt & Whitney Canada before next-generation engine allocation tightens.
For New Entrants and Emerging Players: Lead with Alpine fractional ownership platforms in Switzerland and Austria where specification premiums exceed airline cyclicality exposure. Target maritime patrol configurations for Mediterranean coastal agencies where multi-role adaptability commands margin pools unavailable in passenger variants. Pursue direct airframer partnerships rather than distributor channels to control specification dialogue.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among airframers with captive aftermarket networks and long-term PSO contract visibility. Five-to-ten year viability favors platforms with hybrid-electric architecture compatibility and EASA certification momentum. Monitor Deutsche Aircraft's D328eco EASA timeline as the critical inflection signal for next-generation competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Architecture Certification | EASA validation of battery-assist propulsion enables 15-20% fuel burn reductions on sub-300 nautical mile routes. |
| Power-by-the-Hour Contract Expansion | Consolidated service packages displace traditional maintenance reserves among Italian and Spanish regional carriers. |
| Maritime Patrol Configuration Development | Multi-role government contracts across Mediterranean borders generate higher margins than passenger variants. |
| Propulsion Integration Partnership | Exclusive arrangements with Pratt & Whitney Canada or GE Aerospace secure engine allocation during production ramps. |
| Alpine Fractional Ownership Platform | Swiss and Austrian executive demand creates premium-tier volume independent of airline procurement cycles. |
Research Methodology
A standing panel of fleet planning directors, EASA certification specialists, PSO contract administrators, and regional airline procurement managers provided ongoing calibration across the research window. Primary interviews with these stakeholders combined with secondary validation against EASA type certificate databases, EU Green Deal regulatory filings, and aircraft production records. Bottom-up fleet deployment analysis triangulated against top-down market sizing from OEM delivery disclosures.
Consistency checks validated volume and value outputs against external benchmarks including powerplant manufacturer delivery schedules and PSO contract award announcements. The analytical framework modeled segmentation across product type, end user, application, and technology dimensions throughout the forecast period. CAGRs derived from fitted growth curves incorporating EU ETS carbon price trajectories and SAF mandate compliance timelines as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or stable EASA certification timelines would require recalibration. Forecasts reflect documented assumptions regarding PSO contract renewal rates and hybrid-electric technology maturation. Revision becomes warranted when EASA validation timelines for novel propulsion architectures cross material delay thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Online in-Flight Shopping Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Japan Aviation Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Airplane Landing Gear Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Military Aircraft Market
Aircraft
Glider Aircraft Market
Aircraft
Supersonic Jet Market
Aircraft
Europe Aviation Market
Aircraft
Aeronautic Propeller Market
Aircraft
Aircraft Control Surface Market