
 Regional Jet Market | 2026-2036
Regional Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Regional Jet Market Analysis
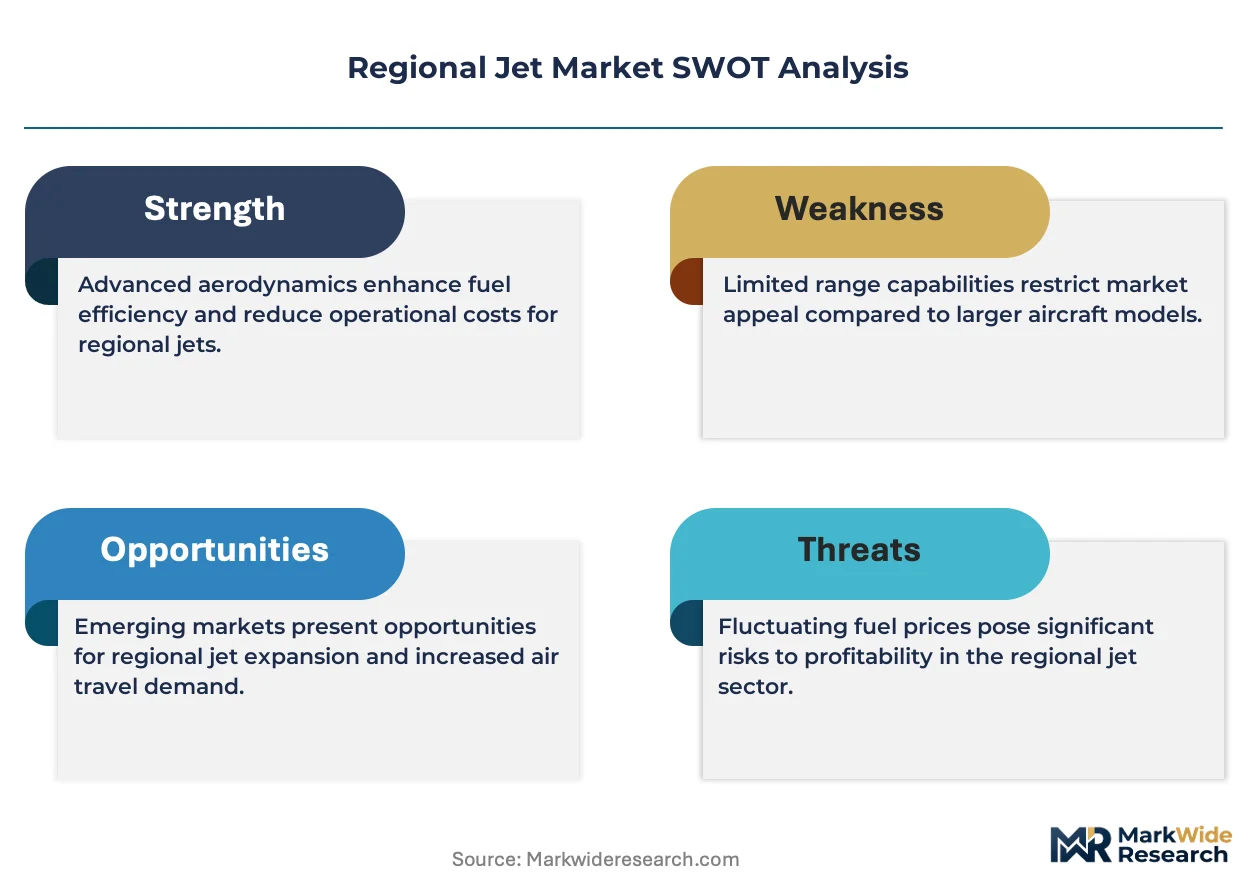
The EU Green Deal's aviation decarbonization targets is rebalancing procurement criteria toward fuel-efficient turbofans. Embraer leverages its E2 family platform to dominate the 76-seat segment with advanced Pratt & Whitney geared turbofan integration. ATR anchors the turboprop-regional boundary with continued investment in hybrid-electric propulsion research. Mitsubishi Aircraft Corporation navigates the SpaceJet program suspension while sustaining engineering partnerships for future platform revival.
A regional jet is a short-haul aircraft typically seating 30 to 100 passengers, powered by turbofan or turbojet engines mounted at the rear fuselage or under the wing, designed for operations at smaller airports with shorter runways and lower passenger volumes than mainline narrowbody service. The turbofan segment leads order books as airlines prioritize fuel burn reduction over pure speed, while the 70-seat and 90-seat capacity tiers capture the fastest fleet renewal cycles as scope clause economics shift. Commercial operators concentrate demand through capacity purchase agreements with major network carriers, whereas charter services and cargo conversion programs occupy emerging secondary value pools.
FAA Part 25 airworthiness standards, EASA CS-25 certification requirements, and ICAO CORSIA emissions monitoring frameworks collectively shape airframe design priorities, engine selection, and market access timelines for new platform introductions. EPA aircraft engine emission standards under CFR Part 87 further constrain NOx and particulate thresholds for US-registered fleets. Stakeholders must monitor scope clause renegotiations between US pilot unions and major carriers, as these labor agreements directly gate the addressable market for new aircraft in the highest-volume geography.
Market Dynamics
Scope clause negotiations between US pilot unions and network carriers are compressing the addressable market for 76-seat aircraft while simultaneously accelerating turbofan replacement cycles across regional fleets.
Growth Catalysts
- ICAO CORSIA Framework:Carbon offsetting mandates are forcing fleet-wide engine upgrades toward fuel-efficient turbofan architectures, particularly across North American and European operators.
- Capacity Purchase Agreements:Major network carriers are consolidating regional feed through long-term CPA structures, locking in demand for 70-to-90-seat platforms with standardized specifications.
- Airport Infrastructure Constraints:Runway limitations at secondary US airports sustain demand for short-field performance aircraft, protecting the regional jet category from narrowbody encroachment.
Market Restraints
- Turbofan Engine Supply Concentration:Pratt & Whitney and GE Aviation dominate geared turbofan supply, creating single-source vulnerability for new platform introductions.
- Pilot Labor Agreements:US scope clauses cap regional carrier aircraft size and block hours, structurally limiting fleet expansion regardless of underlying route economics.
- Feedstock Cost Volatility:Titanium and nickel-based superalloy prices fluctuate with aerospace demand cycles, pressuring airframe and engine manufacturer margins.
Strategic Opportunities
- Hybrid-Electric Propulsion:ATR's continued research investment signals a pathway to turboprop-regional boundary disruption, potentially capturing sub-50-seat routes currently served by aging jet fleets.
- Cargo Conversion Programs:Retired 70-seat regional jets are entering secondary value pools as dedicated freighters, extending asset economic life beyond passenger service.
- EU Green Deal Aviation Targets:Decarbonization procurement criteria are rebalancing European regional carrier RFPs toward fuel-burn performance metrics that favor next-generation turbofan platforms.
Industry Challenges
- Type Rating Pipeline Constraints:Flight training organizations face capacity bottlenecks for new-generation flight deck certifications, delaying crew availability for E2-family deliveries.
- Certification Timeline Compression:FAA Part 25 and EASA CS-25 validation processes for modified engine integrations are extending new variant entry-into-service schedules by 18 to 24 months.
- Legacy Avionics Integration:Regional operators maintaining mixed fleets face interoperability costs between Pro Line Fusion and Collins Apex architectures during phased renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regional Jet Market |
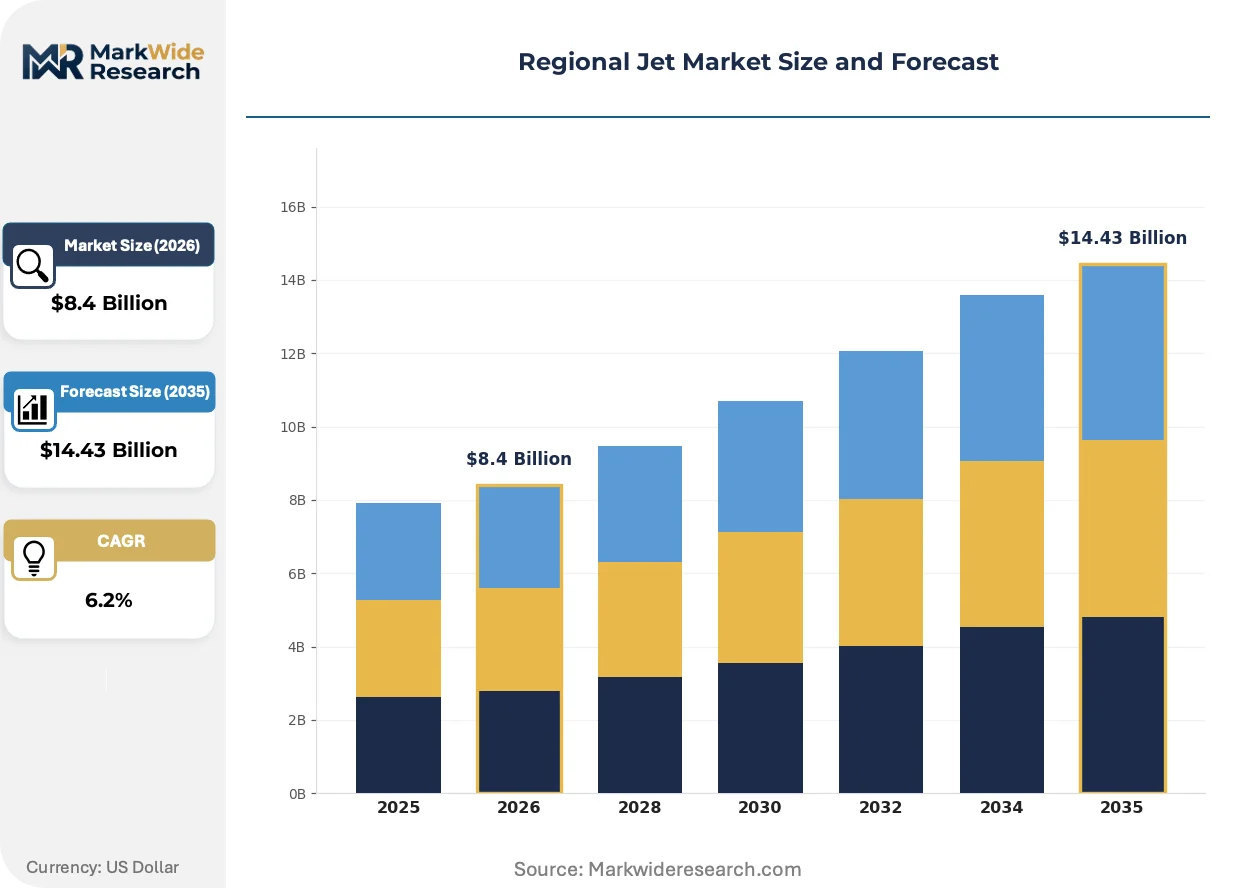
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Turbojet, Turbofan, Regional Airliner, Business Jet End User: Commercial Operators, Charter Services, Cargo Carriers, Government Agencies Capacity: 50 Seats, 70 Seats, 90 Seats, 100 Seats Component: Airframe, Engine, Avionics, Control Systems |
| Companies Covered | Mitsubishi Aircraft Corporation, China Aviation Industry Corporation, Embraer, Leonardo, United Aircraft Corporation, Airbus, Sukhoi Civil Aircraft, ATR, Bombardier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regional Jet Market Emerging Trajectories
Propulsion architecture convergence and regulatory emissions frameworks are compressing development cycles while fragmenting procurement specifications across operator segments.
Geared turbofan technology is unifying regional jet engine design priorities around fuel efficiency rather than thrust-to-weight ratios. US regional carriers adopting Pratt & Whitney PW1700G and PW1900G powerplants are achieving double-digit fuel burn reductions against legacy CF34 installations. This unifying technical standard is collapsing the competitive window for non-geared alternatives and forcing incumbent engine suppliers to accelerate next-generation thermal efficiency programs.
EPA aircraft engine emission standards under CFR Part 87 are tightening NOx and particulate thresholds for US-registered fleets. The industrial consequence is a certification burden shift toward engine manufacturers, who must now validate compliance across multiple thrust ratings and operating conditions. Regional aircraft in the 70-to-90-seat segment face the most acute compliance cost pressure, as their thinner margins absorb less R&D amortization than mainline platforms.
Service contract unbundling is separating power-by-the-hour agreements from line maintenance provisions. US regional operators are negotiating direct engine OEM support while retaining airframe maintenance in-house or through third-party MRO networks. This behavioral shift is most visible among capacity purchase agreement carriers, where major network sponsors are pushing risk allocation downstream to regional partners without corresponding rate adjustments.
Regional Jet Market Segmentation

Regional jet procurement decisions fragment across four distinct classification axes, each carrying separate certification burdens and operational economics. FAA Part 25 and EASA CS-25 requirements vary materially by aircraft type and capacity tier, while end-use applications dictate divergent reliability specifications and aftermarket support structures.
Aircraft Type:
FAA Part 25 certification intensity escalates from turbojet through turbofan architectures, with regional airliners facing the most stringent CS-25 validation cycles for passenger-carrying configurations.
- Turbojet:Legacy rear-fuselage mounting configurations dominate 50-seat fleet renewals where acquisition cost outweighs fuel efficiency metrics. Scope clause constraints in the United States compress residual demand to secondary markets with less stringent emissions frameworks.
- Turbofan:Geared turbofan integration requires supplemental type certification for each thrust rating variant, extending entry-into-service timelines. Pratt & Whitney PW1700G and PW1900G powerplants command the dominant procurement share as US regional carriers prioritize fuel burn reduction over speed.
- Regional Airliner:76-seat configurations anchor capacity purchase agreement specifications between major network carriers and regional operators.
- Business Jet:Corporate shuttle derivatives of regional platforms require reduced cabin density certifications under specialized operational rules.
Turbofan sits at the top of the volume ranking, with regional airliner climbing the fastest.
End User:
Customer type determines warranty structures, with commercial operators extracting fleet-wide power-by-the-hour terms unavailable to fragmented charter or government buyers.
- Commercial Operators:Capacity purchase agreement carriers concentrate order volumes through standardized 70-to-90-seat specifications. Major US network sponsors dictate engine selection and cabin configuration, compressing regional partner procurement autonomy.
- Charter Services:Ad-hoc demand patterns favor flexible lease structures over direct ownership, with operators prioritizing quick-change interior certifications for mixed passenger-cargo missions.
- Cargo Carriers:Retired 70-seat regional jets entering freighter conversion programs require supplemental type certificates for main deck cargo door installations.
- Government Agencies:Military and state aviation units impose specialized communications and defensive system integrations beyond commercial baselines.
Commercial operators command the dominant procurement volume, while cargo carriers gain share fastest as conversion programs accelerate.
Capacity:
Seat-count tiers align directly with US pilot union scope clause thresholds, with 76-seat variants requiring specific major carrier sponsorship for regional operator deployment.
- 50 Seats:Aging fleet replacement cycles lag as scope clause economics favor larger gauges. Turboprop alternatives capture remaining demand on thin routes below jet threshold economics.
- 70 Seats:Pratt & Whitney geared turbofan integration achieves optimal unit cost performance for US regional feed operations. Embraer E175-E2 certification delays have extended incumbent platform production windows.
- 90 Seats:Expanding scope clause negotiations threaten to reclassify this tier as mainline-operated, freezing regional carrier procurement.
- 100 Seats:Narrowbody competitive pressure limits addressable market to specialized short-field performance requirements.
70 Seats leads absolute delivery volumes, with 90 Seats facing the steepest expansion trajectory contingent on labor agreement evolution.
Component:
Supplier concentration varies sharply across subsystems, with engine OEMs extracting pricing premiums unavailable to fragmented avionics vendors.
- Airframe:Embraer and Mitsubishi (suspended) anchor composite wing and fuselage supply, with tier-one aerostructures concentrated in Brazil and Japan.
- Engine:Pratt & Whitney and GE Aviation dominate geared turbofan output, with single-source vulnerability forcing airframers into exclusive supplier arrangements.
- Avionics:Pro Line Fusion and Collins Apex architectures compete for flight deck retrofit and new-build contracts.
- Control Systems:Fly-by-wire integration requirements escalate with E2-family certification standards, pressuring legacy hydraulic system suppliers.
Engine captures the highest value concentration per airframe, with avionics expanding most quickly through mandated NextGen and SESAR compliance retrofits.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional jet manufacturing originated in North America and Europe during the 1980s turbofan revolution, with Brazil and Canada later emerging as production centers through state-supported aerospace programs.
United States
Capacity purchase agreements between network carriers and regional operators concentrate demand for 76-seat configurations. FAA Part 25 certification requirements and EPA CFR Part 87 emissions standards govern new platform introductions. Wichita, Kansas anchors airframe engineering clusters while Pratt & Whitney's geared turbofan production facilities in Connecticut supply dominant engine architectures.
Brazil
Embraer's E2 family platform drives turbofan adoption across Latin American and export markets. ANAC certification alignment with FAA standards accelerates US market access timelines. São José dos Campos hosts composite wing manufacturing and final assembly operations for the 70-to-90-seat segment leader.
Canada
Bombardier's historical regional jet production established Montreal as a turbofan engineering center before program divestitures shifted focus. Transport Canada certification reciprocity with FAA maintains cross-border market fluidity. Toronto-Waterloo corridor retains avionics integration expertise and flight test infrastructure.
France
ATR's turboprop-regional boundary research receives French government aerospace funding aligned with EU Green Deal decarbonization targets. EASA CS-25 validation processes for hybrid-electric propulsion concepts operate from Toulouse headquarters. Occitanie region concentrates aerostructures supply chains serving both ATR and Airbus operations.
Japan
Mitsubishi Aircraft Corporation's SpaceJet program suspension redirected engineering partnerships toward future platform revival efforts. METI industrial policy supports composite materials research for next-generation airframe applications. Nagoya aerospace cluster maintains tier-one supplier relationships with Pratt & Whitney and other engine OEMs.
Regional Jet Market Vendor Landscape
Capital-heavy airframe producers compete with asset-light engineering houses across divergent certification and production strategies. Market structure consolidates around three integrated platform developers with full FAA/EASA validation capabilities, supplemented by state-sponsored challengers and specialty turboprop manufacturers. Strategic archetypes include: full-stack OEMs controlling airframe-engine integration, government-backed national champions prioritizing industrial policy over commercial returns, and cooperative ventures pooling engineering resources across borders. Dominant competitive moves encompass exclusive engine supply arrangements and geographic diversification of final assembly to capture local content requirements.
Among the full-stack OEM tier, Embraer and Airbus occupy positions representing commercial turbofan leadership and turboprop-regional diversification respectively. Mitsubishi Aircraft Corporation exemplifies the state-sponsored archetype navigating program suspension while sustaining engineering capabilities for potential revival. ATR anchors the cooperative venture model through Franco-Italian ownership structures optimized for sub-50-seat market segments.
| Leading Market Players |
|---|
| Mitsubishi Aircraft Corporation |
| China Aviation Industry Corporation |
| Embraer |
| Leonardo |
| United Aircraft Corporation |
| Airbus |
| Sukhoi Civil Aircraft |
| ATR |
| Bombardier |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in Brazil and Canada anchor airframe manufacturing, while Pratt & Whitney's geared turbofan exclusivity in Connecticut concentrates engine pricing power. This ownership pattern links supply discipline to long-term capacity purchase agreement structures, compressing margin negotiation space for regional operators locked into standardized fleet specifications.
Pricing Analysis
Power-by-the-hour contracting dominates procurement, bundling engine maintenance with flight-hour fees across 70-to-90-seat platforms. Price differentiation separates FAA Part 25-certified new-builds from supplemental type certificate retrofits, with EASA CS-25 dual-validation commanding premiums for European deployment rights. Cost compression in the 50-seat segment intensifies as turboprop alternatives capture scope-constrained routes, while major network carriers exhibit lowest price sensitivity through consolidated CPA volumes.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from capacity purchase agreement carriers, bypassing distributor markups for fleet-wide orders. Supply concentrates in Brazil for Embraer composite fuselages, Connecticut for Pratt & Whitney geared turbofan output, and Japan for Mitsubishi tier-one aerostructures. Titanium and nickel-based superalloy dependencies draw from aerospace-grade foundries in the United States and France. Single-source vulnerability in geared turbofan supply creates structural risk for airframers without dual-engine certification paths.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through ICAO CORSIA carbon offsetting mandates, which force fleet-wide engine upgrades and sustain replacement demand regardless of underlying traffic growth.
For Market Incumbents: Anticipate scope clause renegotiations between US pilot unions and network carriers by securing exclusive engine supply arrangements before labor agreements crystallize. Embraer should deepen backward integration into composite wing manufacturing in São José dos Campos to defend margin position against emerging turboprop-regional boundary disruption from ATR hybrid-electric research. For New Entrants and Emerging Players: Launch via cargo conversion programs targeting retired 70-seat regional jets entering secondary value pools, where supplemental type certificate barriers are lower than new platform development. The most penetrable white-space sits in ad-hoc charter services requiring quick-change interior certifications, with government agency contracts offering specialized communications integration premiums unavailable to commercial operators. For Investors and Strategic Acquirers: Valuations sit cheapest among engineering houses sustaining capabilities through program suspension rather than production, exemplified by Mitsubishi Aircraft Corporation's partnership-dependent model. Long-term viability favors acquisition targets with dual FAA-EASA validation capabilities and established tier-one supplier relationships in Nagoya or Montreal. The signal to watch is scope clause threshold expansion beyond 76 seats, which would reclassify addressable market size and strand regional carrier-focused production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Geared Turbofan Integration | Pratt & Whitney PW1700G adoption locks in fuel efficiency premiums for E2-family deliveries against legacy CF34 installations. |
| Hybrid-Electric Propulsion Research | ATR's continued investment signals pathway to capture sub-50-seat routes currently served by aging jet fleets. |
| Cargo Conversion Program Expansion | Retired 70-seat platforms entering freighter service extend asset economic life beyond passenger retirement cycles. |
| Dual Certification Investment | Simultaneous FAA Part 25 and EASA CS-25 validation accelerates market access timelines for new variant introductions. |
| Power-by-the-Hour Unbundling | Separating engine OEM support from airframe maintenance reallocates risk to regional operators under CPA structures. |
Methodological Framework
Multiple input streams — fleet operator interviews, engine OEM procurement disclosures, and regulatory filing analysis — were reconciled against trade flow data and certification timeline records. Primary engagement captured regional carrier fleet directors, Pratt & Whitney program managers, ANAC validation specialists, and major network carrier CPA negotiators. Secondary validation drew from FAA type certificate databases, EASA CS-25 amendment trackers, ICAO CORSIA implementation reports, and EPA CFR Part 87 emission compliance filings. Bottom-up airframe delivery tallies and top-down market value estimates were cross-referenced to anchor projections.
Data-stream reconciliation applied across the projection horizon segmented volume and value by aircraft type, capacity tier, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical delivery cycles and announced backlog conversions. Forecast inputs incorporated scope clause negotiation probabilities, engine certification timeline compression factors, and hybrid-electric technology readiness thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pilot labor agreement disruptions or titanium superalloy price volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Search and Rescue Helicopter Market
Aircraft
Australia Aviation Market
Aircraft
Water Bomber Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
US Business Jet Market
Aircraft
Active Air Deflector Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Light Electric Aircraft Market
Aircraft
Winglets Market
Aircraft
Air Speed Indicator Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Anti Rolling Gyro (ARG) Market