
 Europe Commercial Aircraft Market | 2026-2036
Europe Commercial Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Aircraft Market Foresight
Power-by-the-hour maintenance contracts is expanding as the dominant commercial model for European operators seeking to offload balance-sheet risk. Airbus SE leverages its Toulouse and Hamburg production footprint to sustain delivery commitments across single-aisle and widebody programs. Embraer SA specializes in regional jet configurations that occupy the sub-150-seat niche where runway-constrained airports dominate route planning. Leonardo competes in the tiltrotor and helicopter segments that extend air mobility options beyond traditional fixed-wing infrastructure.
Europe commercial aircraft encompass fixed-wing and rotary-wing platforms certified for passenger transport, cargo carriage, and specialized aerial operations under EASA type certificates, with maximum takeoff weights ranging from below 5.7 tonnes for light business jets to over 550 tonnes for twin-aisle long-haul aircraft. These platforms integrate composite wing structures, fly-by-wire flight control architectures, and high-bypass turbofan propulsion systems to achieve specific fuel consumption targets and noise certification levels required for European airport slot allocations. Single-aisle aircraft dominate order backlogs as fleet planners prioritize route density on intra-European and North Atlantic corridors where slot constraints favor higher frequency over gauge growth. Turbofan engine types command the largest installed base while hybrid-electric propulsion systems attract development funding as airlines face escalating EU ETS compliance costs and national departure tax regimes in France, Germany, and the Netherlands.
EASA airworthiness standards, EU ETS aviation inclusion, and the ReFuelEU Aviation mandate collectively determine product viability and operating economics for new aircraft deliveries across European Union member states. CSRD disclosure requirements now extend to aviation supply chains, forcing OEMs and tier-one suppliers to document Scope 3 emissions associated with aircraft manufacturing and aftermarket support. Stakeholders must monitor how national implementation of EU-wide SAF blending mandates affects engine compatibility specifications and residual value forecasting for current-generation fleets.
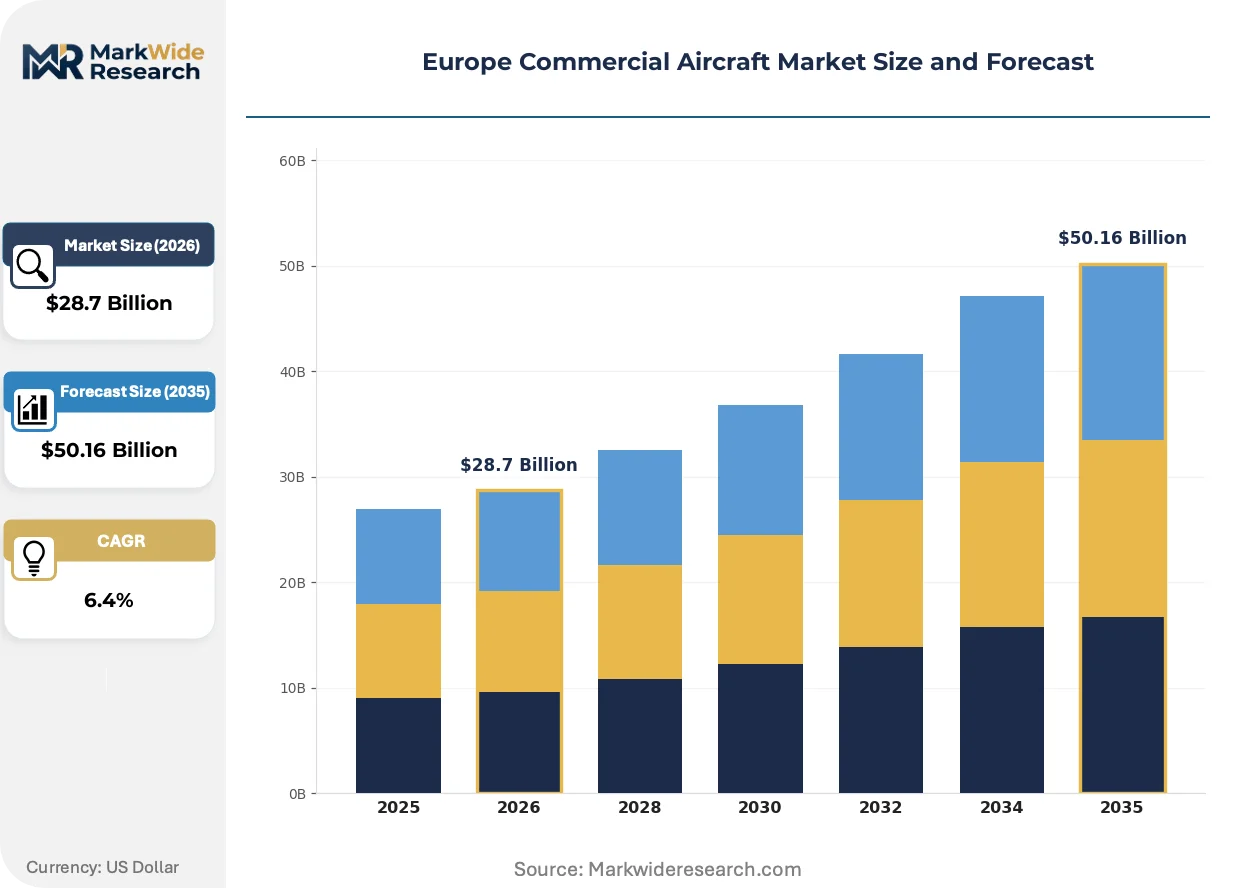
Market Dynamics
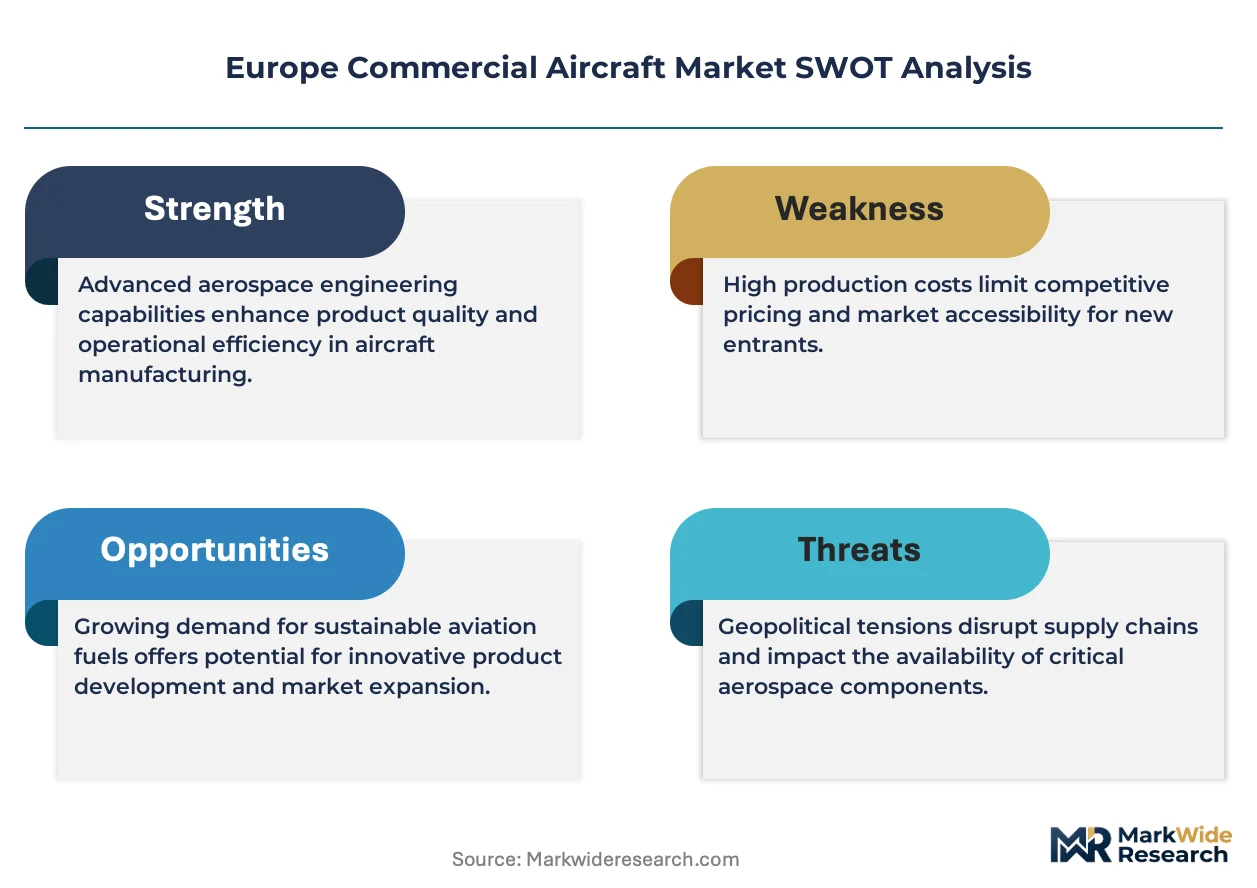
ReFuelEU Aviation mandates are forcing fleet planners to accelerate narrowbody replacement cycles as sustainable aviation fuel compatibility becomes a procurement gate for new deliveries. The EU Green Deal's binding SAF blending targets have shifted capital allocation toward power-by-the-hour contracts that transfer residual value risk to lessors and OEMs.
Growth Catalysts
- EASA SAF Certification Pathways:The regulator's streamlined approval process for synthetic fuel blends is compressing type certificate amendment timelines for next-generation turbofan architectures.
- Slot-Constrained Hub Expansion:Runway-limited airports in France and Germany are driving demand for sub-150-seat configurations that maximize frequency over gauge on thin routes.
- Composite Wing Manufacturing:Automated fiber placement advances at Hamburg and Toulouse supplier clusters are reducing airframe weight fractions and extending range-payload envelopes for single-aisle platforms.
Market Restraints
- Titanium Supply Concentration:Russian-origin sponge exclusions have concentrated feedstock sourcing on Japanese and Kazakh suppliers, inflating mill product lead times for engine forgings.
- EU ETS Compliance Cost Escalation:Carbon allowance price trajectories are eroding operating margins for wet-leased regional aircraft on intra-European sectors.
- Runway Performance Physics:Hot-and-high airport constraints in Southern Europe limit maximum takeoff weights for current-generation narrowbodies, restricting payload on summer Mediterranean operations.
Strategic Opportunities
- Polish and Romanian LCC Bases:Underpenetrated Eastern European point-to-point networks offer white-space deployment for high-density single-aisle configurations with 200-plus seat counts.
- Hybrid-Electric Distributed Propulsion:Convergence of solid-state battery chemistries with megawatt-class electric motors is opening sub-50-seat regional segments previously abandoned as uneconomical.
- CSRD Supply Chain Disclosure:Mandatory Scope 3 reporting is creating aftermarket revenue streams for carbon accounting software integrated with maintenance planning systems.
Industry Challenges
- Certification Workforce Bottlenecks:EASA's type certification division faces staffing shortfalls that extend validation timelines for supplemental type certificates on cabin reconfigurations.
- Legacy Avionics Integration:Retrofitting fly-by-wire architectures into first-generation digital cockpits requires hardware-software recertification that blocks quick-turn lease transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Aircraft Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Aisle, Twin-Aisle, Regional, Business Jets Engine Type: Turbofan, Turboprop, Electric, Hybrid Manufacturer: Boeing, Airbus, Bombardier, Embraer End User: Commercial Airlines, Charter Services, Cargo Operators, Military |
| Companies Covered | Embraer SA, Textron Inc, Airbus SE, Airbus Helicopters, Leonardo, ATR, Bombardier Inc, Piaggio Aerospace, Dassault Aviation SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Aircraft Market Shifts & Advancements
Propulsion architecture decisions now precede airframe selection as airlines hedge against multiple fuel pathways. The convergence of hydrogen combustion research with drop-in SAF compatibility requirements is splitting engineering resources across parallel development tracks.
Geared turbofan architectures with ultra-high bypass ratios are electrifying propulsion efficiency benchmarks for narrowbody platforms. Lufthansa Group and Air France-KLM are specifying these powerplants for 2027-2030 delivery slots. The technology is electrifying competitive positioning on transatlantic routes where fuel burn differentials determine slot allocation priority.
ReFuelEU Aviation's 2030 blending mandate is forcing engine OEMs to publish fuel-flexibility roadmaps that commit to 100% SAF compatibility by 2035. Industrial consequence includes accelerated high-pressure turbine material testing to validate thermal barrier coating durability under aromatic-free fuel chemistries. Widebody programs with 2040 entry-into-service targets are most affected, with design teams now locking combustor geometries earlier in development cycles.
Power-by-the-hour contracts are displacing traditional time-and-material maintenance arrangements across European flag carriers. Lessors like AerCap and SMBC Aviation Capital are capturing aftermarket value previously retained by MRO providers. This shift is most visible in Ireland and the UK, where leasing company concentration has created captive maintenance networks that bypass airline technical departments.
Europe Commercial Aircraft Market Segmentation
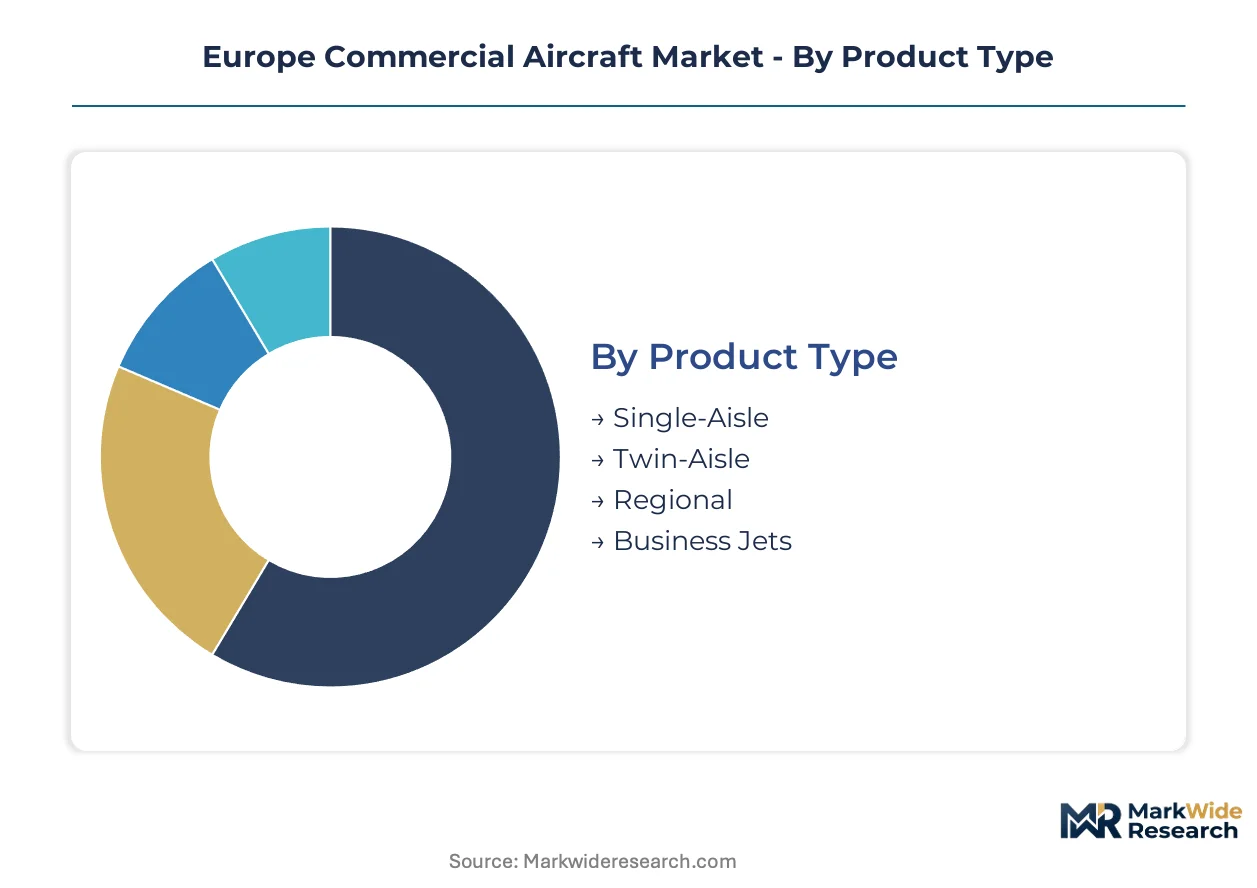
Segmentation in the Europe commercial aircraft market reflects how procurement criteria have fragmented across operational requirements, regulatory compliance pathways, and fleet financing structures. Airlines now select platforms based on fuel flexibility specifications and residual value guarantees rather than traditional capacity metrics alone.
Product Type:
Airframe architecture determines route economics and slot compatibility across Europe's constrained hub infrastructure.
- Single-Aisle:Narrowbody configurations with composite wing structures and high-bypass turbofans dominate intra-European and North Atlantic corridors. Demand concentrates at Toulouse and Hamburg final assembly lines where Airbus sustains delivery commitments for Lufthansa Group and Air France-KLM fleet renewals.
- Twin-Aisle:Widebody platforms exceeding 300 tonnes maximum takeoff weight serve long-haul trunk routes from Frankfurt and Paris-Charles de Gaulle. Procurement delays persist as airlines defer gauge growth in favor of frequency on slot-constrained runways.
- Regional:Sub-150-seat configurations access runway-limited airports in Southern Europe where hot-and-high performance constraints restrict larger aircraft.
- Business Jets:Light and mid-size platforms certified under EASA Part-25 standards serve point-to-point corporate travel from Geneva and London City.
Mature deployment sits with Single-Aisle platforms. Newer deployment is concentrated in Regional reconfigurations for Eastern European LCC bases.
Engine Type:
Propulsion selection now precedes airframe commitment as operators hedge against ReFuelEU Aviation's escalating blending mandates.
- Turbofan:High-bypass architectures with ultra-high pressure ratios power the installed base across European flag carriers. Geared turbofan variants from Pratt & Whitney and Rolls-Royce are climbing the fastest as airlines specify these powerplants for 2027-2030 delivery slots to secure transatlantic slot priority.
- Turboprop:Constant-speed propeller systems maintain relevance for sub-600 nautical mile sectors from regional bases in Poland and Romania where fuel burn differentials outweigh speed penalties.
- Electric:Battery-electric propulsion remains developmental, constrained by energy density limitations that restrict commercial payload-range envelopes.
- Hybrid:Turboelectric architectures combining gas turbines with distributed electric motors are gaining share fastest in sub-50-seat segments previously abandoned as uneconomical.
Procurement concentration favors Turbofan for mainline operations. Technology investment is redirecting toward Hybrid configurations for regional connectivity restoration.
Manufacturer:
Production footprint proximity to European MRO networks and financing centers shapes sourcing decisions for lessors and flag carriers.
- Boeing:US-based OEM with final assembly in Washington state supplies widebody platforms for British Airways and TUI Group long-haul fleets.
- Airbus:Toulouse and Hamburg production sites anchor the dominant European supply position across single-aisle and widebody programs.
- Bombardier:Canadian manufacturer with Belfast wing production specializes in business jet and regional platforms for corporate and charter operators.
- Embraer:Brazilian OEM captures the sub-150-seat niche with E-Jet configurations optimized for runway-constrained airports in France and Germany.
Market share leadership rests with Airbus. Competitive pressure is intensifying from Embraer in thin-route regional deployment.
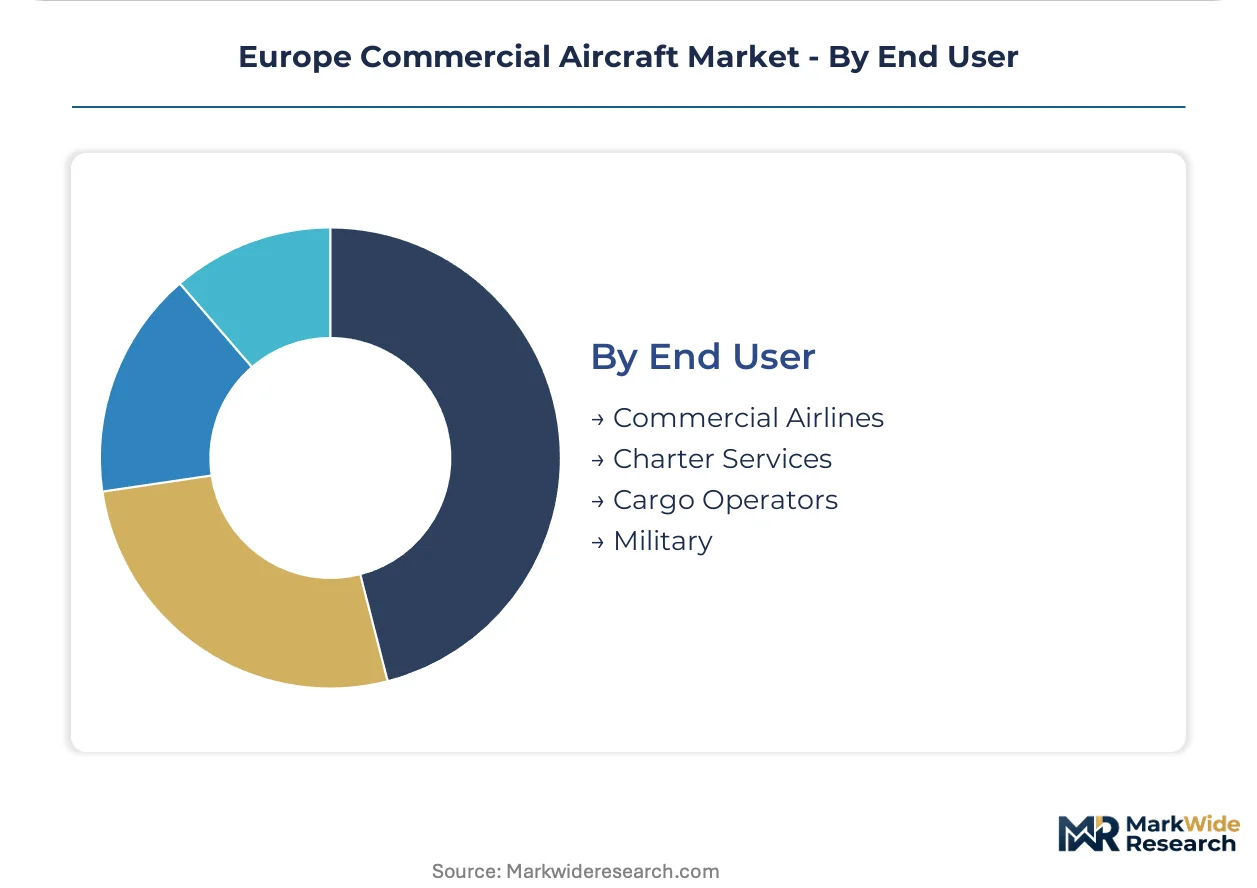
End User:
Customer type determines financing structure, maintenance contract terms, and residual value risk allocation across the European fleet.
- Commercial Airlines:Scheduled carriers including Lufthansa, Air France-KLM, and IAG Group drive narrowbody replacement cycles under power-by-the-hour contracts that transfer technical risk to lessors.
- Charter Services:Ad-hoc passenger operators and ACMI providers deploy mixed fleets across seasonal Mediterranean and Alpine leisure corridors.
- Cargo Operators:Dedicated freighter carriers and express integrators convert retired passenger widebodies for e-commerce trunk routes from Leipzig and Liège hubs.
- Military:Government transport and multi-role tanker requirements from NATO member states sustain limited procurement of certified commercial derivatives.
Contract volume concentrates with Commercial Airlines. Fleet expansion is accelerating fastest among Cargo Operators responding to e-commerce logistics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's commercial aircraft production concentrates in France and Germany while demand spreads across Eastern European low-cost carrier bases. The EU Green Deal's SAF mandates create divergent procurement pressures between manufacturing clusters and operating airlines.
France
Air France-KLM fleet renewal programs drive narrowbody demand from Toulouse final assembly lines. ReFuelEU Aviation mandates accelerate replacement cycles for aging A320ceo family aircraft. The Île-de-France aerospace cluster anchors composite wing manufacturing and EASA certification pathways.
Germany
Lufthansa Group's power-by-the-hour contracts reshape Hamburg and Munich procurement patterns. CSRD disclosure requirements force tier-one suppliers to document Scope 3 emissions from manufacturing operations. Bavaria's supplier networks specialize in high-pressure turbine components for geared turbofan architectures.
United Kingdom
British Airways and TUI Group long-haul fleets sustain widebody demand despite slot constraints at Heathrow. National departure tax regimes erode operating margins on short-haul regional sectors. Northern Ireland's Belfast facilities concentrate on business jet wing production for corporate operators.
Poland
Eastern European low-cost carriers deploy high-density single-aisle configurations from Warsaw and Krakow bases. Underpenetrated point-to-point networks offer white-space expansion for 200-plus seat count aircraft. Polish MRO providers capture aftermarket value from power-by-the-hour contract structures.
Netherlands
KLM's transatlantic slot priority depends on fuel burn differentials from next-generation turbofan specifications. Amsterdam Schiphol runway constraints favor frequency over gauge on North Atlantic corridors. Dutch leasing company concentration in Ireland creates captive maintenance networks bypassing airline technical departments.
Europe Commercial Aircraft Market Competitive Landscape
Top-tier vendors anchor final assembly and certification authority, while mid-tier specialists capture sub-150-seat niches and regional connectivity segments. The market structure consolidates around Toulouse and Hamburg production footprints with Brazilian and Canadian manufacturers occupying thin-route positions. Strategic archetypes include full-range platform OEMs, regional jet specialists, and business jet configurators. Dominant competitive moves center on power-by-the-hour contract expansion and SAF compatibility roadmapping.
Within the full-range OEM tier, Airbus SE exemplifies European production consolidation through Toulouse and Hamburg final assembly lines. Embraer SA occupies the regional specialist position with sub-150-seat configurations optimized for runway-constrained airports. Leonardo represents the diversified aerospace archetype extending into tiltrotor and helicopter segments beyond traditional fixed-wing infrastructure.
| Leading Market Players |
|---|
| Embraer SA |
| Textron Inc |
| Airbus SE |
| Airbus Helicopters |
| Leonardo |
| ATR |
| Bombardier Inc |
| Piaggio Aerospace |
| Dassault Aviation SA |
| Others |
Supply & Pricing Matrix
Leasing-company concentration in Ireland and the UK anchors pricing discipline across European commercial aviation, with AerCap and SMBC Aviation Capital leveraging captive maintenance networks to compress aftermarket margins while transferring residual value risk from airline balance sheets to lessor portfolios under power-by-the-hour contract structures.
Pricing Analysis
Margin tightening in aftermarket services reflects lessor capture of maintenance value previously retained by MRO providers. Three-tier pricing structure across premium, standard, and economy levels stratifies by engine generation and SAF compatibility certification, with Air France-KLM and Lufthansa Group showing lowest price sensitivity on next-generation turbofan specifications due to transatlantic slot priority dependencies. Cost-down pressure on regional jet configurations accelerates because Polish and Romanian LCCs prioritize acquisition cost over performance reserves on thin Eastern European routes.
Supply Chain Analysis
Regional distribution centers at Hamburg and Toulouse anchor hub-and-spoke patterns for composite wing components and engine forgings. Supply draws from France, Germany, and Japan for titanium mill products, with Kazakh sponge feedstock replacing excluded Russian origins. Single-source vulnerability concentrates on high-pressure turbine castings from Bavarian supplier networks. Distribution runs through final assembly lines at Airbus SE facilities with just-in-time sequencing to EASA certification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid-electric distributed propulsion is displacing conventional turbofan architectures in sub-50-seat segments, forcing stakeholders to reposition across a technology-transition phase where solid-state battery convergence with megawatt-class motors reopens regional connectivity markets previously abandoned as uneconomical.
For Market Incumbents: Deepen backward integration into titanium forging supply through Japanese and Kazakh mill product partnerships to mitigate Russian-origin exclusion risks. Expand power-by-the-hour contract coverage to capture aftermarket value from Irish and UK lessor concentration. Priority lever: EASA type certification workforce investment to compress supplemental type certificate timelines for cabin reconfigurations. For New Entrants and Emerging Players: Launch via ACMI wet-lease arrangements targeting underpenetrated Polish and Romanian point-to-point networks with high-density single-aisle configurations. White-space deployment favors 200-plus seat count aircraft on Eastern European LCC bases where slot constraints favor frequency over gauge. Go-to-market angle: CSRD-compliant carbon accounting software integration with maintenance planning systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional MRO specialists in Poland with captive power-by-the-hour contract structures. Long-term viability across the analysis window hinges on SAF compatibility roadmapping and ReFuelEU Aviation mandate compliance infrastructure. Signal to watch: EASA staffing allocations for type certification division expansion as validation bottleneck indicator.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Compatibility Roadmapping | Engine OEMs must commit to 100% synthetic fuel compatibility under ReFuelEU Aviation mandates. |
| Power-by-the-Hour Contract Expansion | Lessors like AerCap capture aftermarket value previously retained by airline technical departments. |
| Composite Wing Manufacturing Scale-Up | Automated fiber placement at Hamburg and Toulouse reduces airframe weight fractions for single-aisle platforms. |
| Geared Turbofan Specification Lock-In | Lufthansa Group and Air France-KLM prioritize Pratt & Whitney and Rolls-Royce architectures for transatlantic slot priority. |
| Eastern European LCC Base Establishment | Polish and Romanian point-to-point networks offer white-space deployment for high-density configurations. |
Research Methodology
EASA certification databases, EU ETS aviation registry filings, and ReFuelEU Aviation mandate documentation formed the secondary backbone, cross-referenced with primary interviews involving fleet planning executives at Lufthansa Group and Air France-KLM, procurement leads at tier-one engine OEMs, MRO operations directors in Poland and Germany, and lessor technical asset managers at Irish and UK leasing companies. Bottom-up and top-down triangulation validated order backlog data against production rate disclosures from Toulouse and Hamburg final assembly lines.
Bottom-up modeling aggregated individual program delivery schedules and operator fleet plans across single-aisle, twin-aisle, and regional configurations, while top-down analysis cross-checked against EU Green Deal policy implementation timelines and CSRD disclosure requirements. Segmentation dimensions included airframe architecture, propulsion type, manufacturer production footprint, and end-user financing structure. CAGR derivation incorporated ReFuelEU Aviation blending mandate escalation curves and ETS carbon allowance price trajectories across the projection horizon.
Supply chain disruption, EASA certification staffing shortfalls, and ReFuelEU Aviation mandate acceleration are the dominant revision risks that could compress or extend replacement cycle timelines. Forecasts reflect documented assumptions regarding SAF infrastructure buildout and titanium feedstock sourcing diversification. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Anchoring System Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Autopilot System Market
Aircraft
North America Business Jet Market
Aircraft
Afterburner Market
Aircraft
North America Military Helicopters Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Military Rotorcraft Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Global Business Aircraft Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Aircraft Hangar Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Aircraft Inspection Covers Market