
 South Korea Satellite Imagery Services Market | 2026-2036
South Korea Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Satellite Imagery Services Market Insights
Subscription-based analytics layers is repositioning how satellite imagery value gets captured in South Korea. SI Imaging Services leverages its KOMPSAT archive control to dominate domestic defense and civil government channels. Maxar Technologies sustains competitive positioning through high-resolution tasking capacity over the Korean peninsula. Dabeeo Inc. differentiates via AI-powered change-detection APIs that compress delivery timelines for urban planning clients.
South Korea satellite imagery services encompass the acquisition, processing, and analytic distribution of Earth observation data captured by orbital platforms, with spatial resolutions ranging from sub-meter panchromatic to 20-meter multispectral swaths, primarily serving cadastral verification, infrastructure monitoring, and environmental compliance functions. Orthophotography and 3D mapping command the largest revenue share due to persistent government demand for national spatial data infrastructure updates. Remote sensing applications in vegetation analysis represent the fastest-expanding segment as precision agriculture adoption spreads across Jeolla and Gyeongsang farming belts. Multispectral technology leads volume deployment while hyperspectral capabilities attract premium pricing from mineral exploration and defense intelligence end users.
MFDS geospatial data protocols, KARI satellite operation licenses, and National Geographic Information Institute accuracy standards collectively shape product certification requirements and procurement eligibility for domestic providers. Government Agencies anchor end-user demand through multi-year framework contracts tied to national land management mandates. Stakeholders must monitor K-SAT constellation launch schedules and evolving public-private data sharing agreements to anticipate capacity inflection points and pricing power shifts.
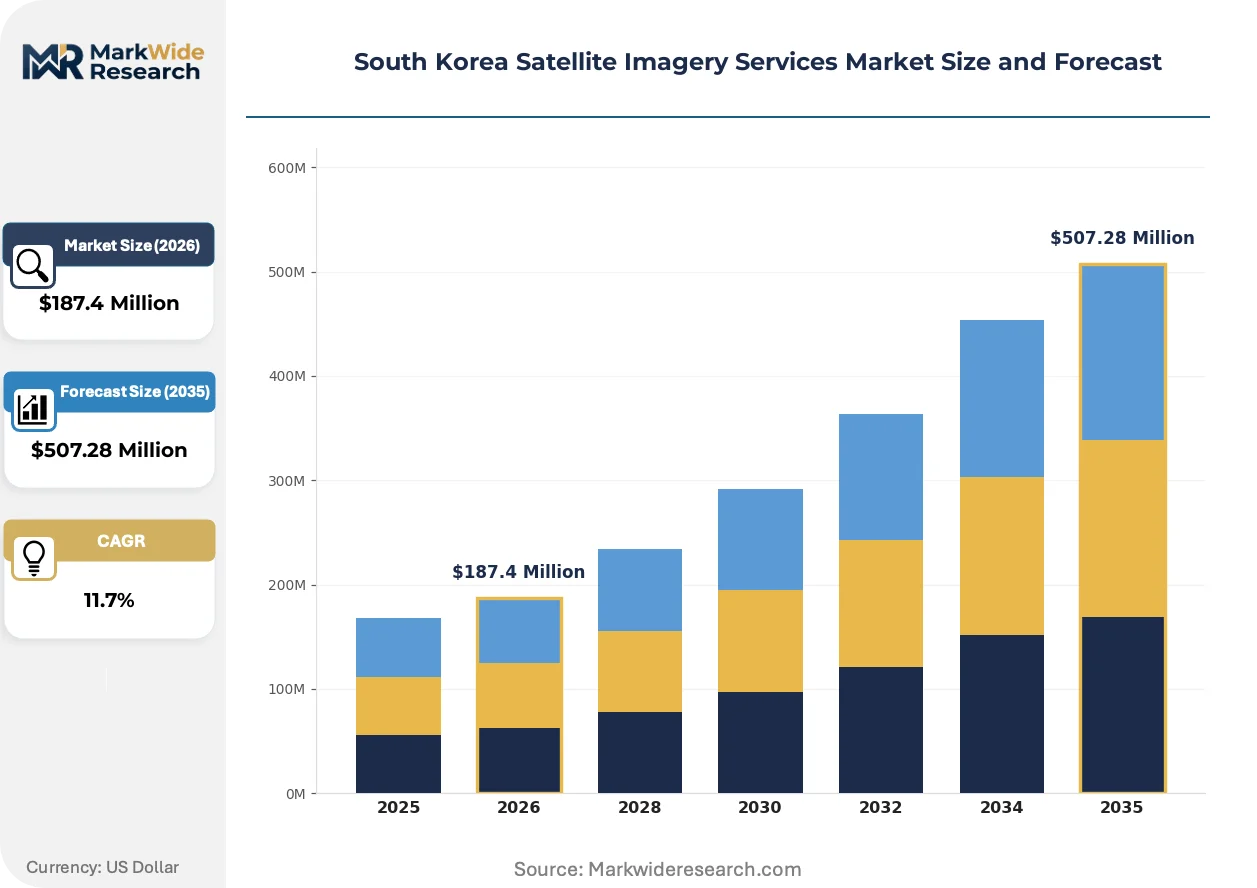
Market Dynamics
K-SAT constellation deployment schedules and MFDS geospatial certification mandates are compressing procurement timelines while tightening domestic supply availability across South Korea's national spatial data infrastructure programs.
Growth Catalysts
- MFDS Data Governance Alignment:The Ministry of Food and Drug Safety's geospatial protocols mandate certified orthophotography for cadastral surveys, creating guaranteed procurement channels for domestic providers meeting National Geographic Information Institute accuracy standards.
- Precision Agriculture Expansion:Jeolla and Gyeongsang farming belts are adopting vegetation analysis services for crop health monitoring, pulling multispectral imagery demand from cooperatives and agricultural extension services.
- Seoul Metropolitan Development:Urban planning corridors across the capital region require 3D mapping and change-detection analytics for infrastructure monitoring, sustaining multi-year framework contracts.
Market Restraints
- Domestic Launch Capacity Bottlenecks:KARI satellite operation licenses limit orbital platform deployment to government-coordinated schedules, constraining commercial imagery supply expansion regardless of demand signals.
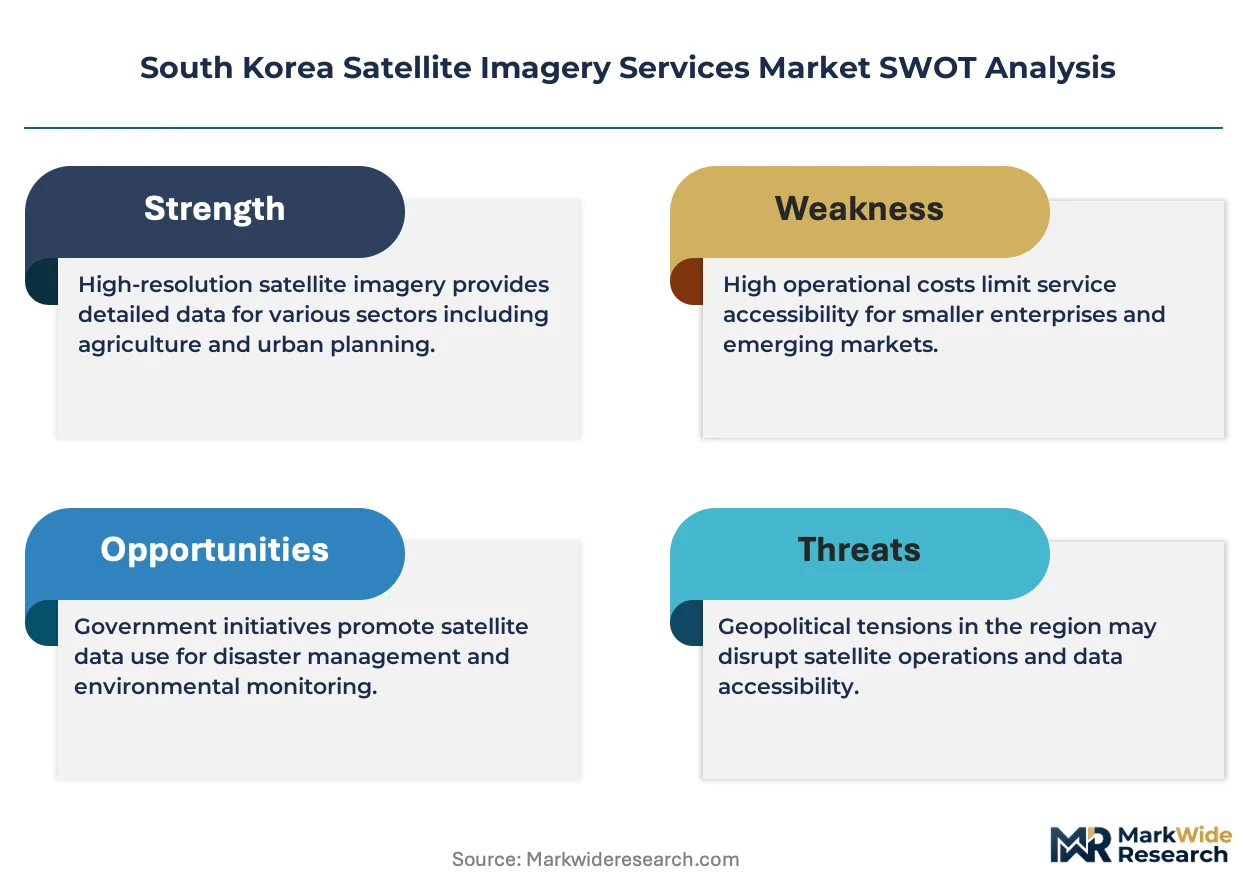
- High-Resolution Tasking Costs:Sub-meter panchromatic capture requires specialized sensor arrays and dedicated ground station access, pricing out mid-tier civil engineering consultancies from premium analytics tiers.
- Defense Channel Concentration:SI Imaging Services controls KOMPSAT archive distribution for military applications, creating single-source dependency for sensitive geospatial intelligence procurement.
Strategic Opportunities
- Busan-Ulsan Industrial Corridor:Port logistics and shipyard monitoring applications remain underpenetrated relative to Seoul-centric demand, offering whitespace for maritime infrastructure analytics providers.
- AI-API Distribution Models:Cloud-based change-detection interfaces are compressing delivery timelines for urban planning clients, enabling subscription revenue capture beyond traditional project-based orthophotography sales.
- Public-Private Data Sharing Expansion:Evolving agreements between KARI and commercial operators could unlock K-SAT constellation capacity for civilian mineral exploration and environmental compliance monitoring.
Industry Challenges
- Hyperspectral Analytics Talent Scarcity:Mineral exploration and defense intelligence applications require specialized spectral interpretation expertise that domestic universities are not producing at sufficient scale.
- Legacy System Integration Friction:Government agencies maintaining decades-old spatial data infrastructure face technical debt when migrating to API-driven analytics platforms, delaying procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Satellite Imagery Services Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orthophotography, 3D Mapping, Remote Sensing, Vegetation Analysis Application: Agriculture, Urban Planning, Disaster Management, Environmental Monitoring Technology: Multispectral, Hyperspectral, Thermal Imaging, LiDAR End User: Government Agencies, Real Estate Developers, Research Institutions, Environmental NGOs |
| Companies Covered | SI Imaging Services, GBS Korea, Dabeeo Inc., Dtonic Corporation, Soletop InSpace Co., Ltd., Maxar Technologies, L3Harris Corporation Inc., Bentley Systems, Inc., ESRI Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Satellite Imagery Services Market Trends and Innovations
Subscription-based service layers are displacing project-based orthophotography sales across South Korea's satellite imagery market, compressing revenue recognition timelines while expanding addressable user bases beyond traditional government clients.
Synthetic aperture radar technology is integrating with optical multispectral platforms to deliver all-weather surface deformation monitoring. Mining operators in Gangwon province are adopting these fused datasets for tailings dam surveillance, compressing risk assessment cycles from quarterly site visits to continuous automated alerts.
MFDS geospatial data protocols are tightening certification requirements for commercial providers seeking national land survey contracts. The regulation mandates specific radiometric calibration standards and metadata traceability, forcing domestic operators to upgrade ground processing infrastructure. Small and mid-size analytics firms are responding by pooling certification costs through industry consortium arrangements.
Framework contracting is consolidating buyer power among national land management agencies while fragmenting vendor access. Seoul metropolitan planners now procure imagery through multi-year consolidated tenders rather than discrete project orders, compressing supplier margins while locking in volume commitments. This pattern is most visible in cadastral verification workflows where NGII accuracy standards create procurement pre-qualification barriers.
South Korea Satellite Imagery Services Market Segmentation
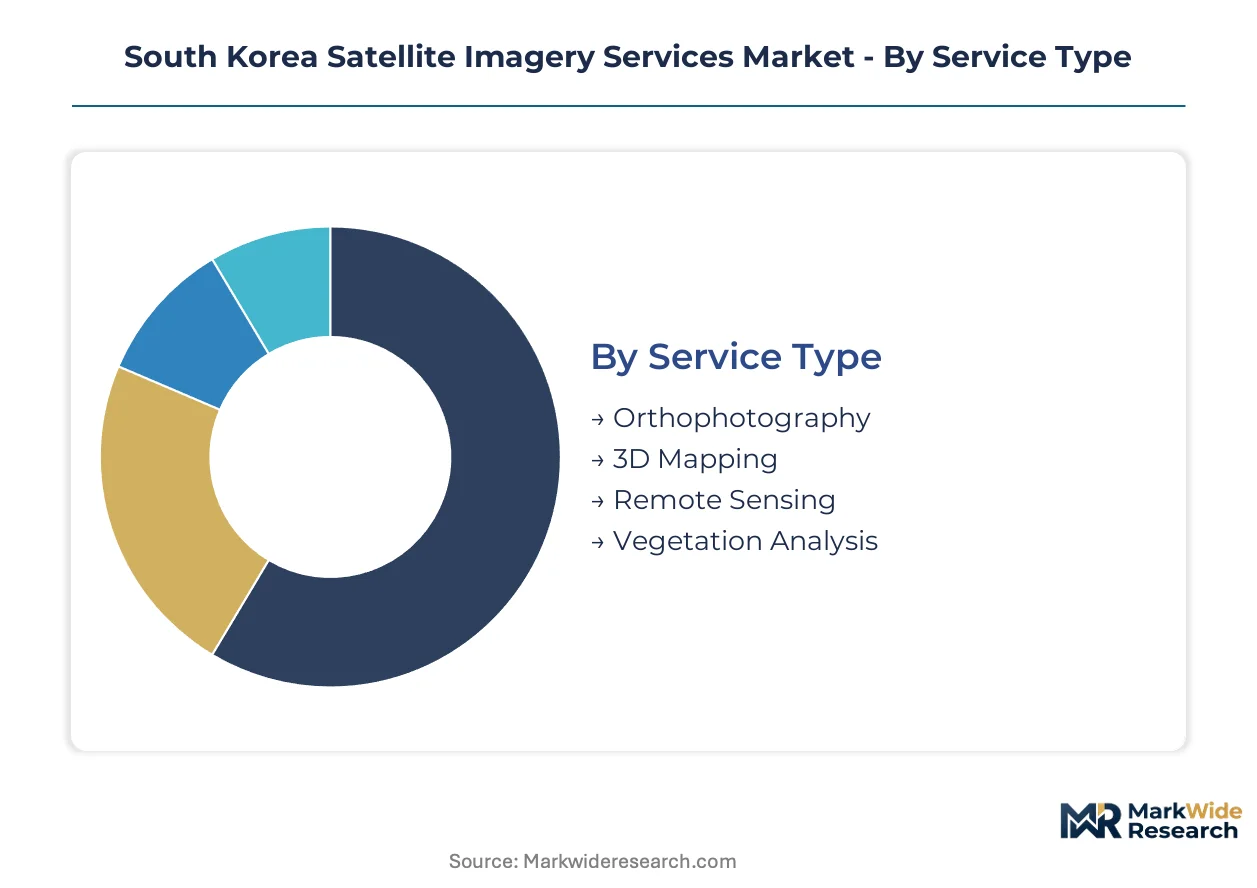
Segmentation in South Korea's satellite imagery market reveals how procurement authority concentrates among state bodies while technology choices diverge between operational reliability and analytical depth. Understanding these splits exposes where pricing power accrues and where vendor margins compress.
Service Type:
Spatial resolution and geometric correction standards define competitive positioning across service tiers, with certification requirements from the National Geographic Information Institute creating procurement gatekeeping.
- Orthophotography:Geometrically corrected aerial imagery with sub-meter ground sampling distance serves cadastral verification and national land survey mandates. Government agencies in Seoul and Sejong City anchor procurement through multi-year framework contracts tied to spatial data infrastructure updates. MFDS-aligned accuracy standards force domestic providers to maintain dedicated ground control point networks.
- 3D Mapping:Stereo pair-derived elevation models and textured mesh reconstructions support urban planning corridors across the capital region. Seoul metropolitan development authorities require continuous refresh cycles for infrastructure monitoring, compressing delivery timelines from quarterly to monthly for critical construction zones.
- Remote Sensing:Automated feature extraction and surface classification algorithms process raw satellite captures into actionable intelligence layers.
- Vegetation Analysis:NDVI and advanced spectral indices monitor crop health across Jeolla and Gyeongsang agricultural belts, pulling demand from farming cooperatives and regional extension services.
Mature deployment sits with Orthophotography. Newer deployment is concentrated in Vegetation Analysis.
Application:
Budget authority and procurement timelines separate applications where public funds dominate from those attracting private capital.
- Agriculture:Precision farming adoption spreads multispectral monitoring across South Korea's southwestern farming regions. Jeolla province cooperatives contract vegetation health services for rice and greenhouse crop management, with K-SAT constellation capacity increasingly directed toward seasonal monitoring windows.
- Urban Planning:Seoul metropolitan development corridors and Busan regeneration zones drive 3D mapping and change-detection demand. Municipal planners require sub-weekly refresh rates for construction compliance verification, pushing vendors toward API-driven subscription models.
- Disaster Management:Flood and landslide response protocols activate rapid tasking agreements with KOMPSAT operators for damage assessment.
- Environmental Monitoring:Coastal erosion tracking and air quality correlation studies utilize medium-resolution multispectral swaths for longitudinal trend analysis.
Revenue concentration favors Urban Planning. Volume expansion is climbing fastest in Agriculture.
Technology:
Sensor sophistication and data processing overhead create tiered pricing structures that filter customer access by analytical sophistication and budget scale.
- Multispectral:Four-to-eight band optical captures at 10-30 meter native resolution constitute the volume base. Government land management agencies and agricultural extension services deploy these datasets for vegetation classification and surface change detection across national territory.
- Hyperspectral:Hundreds of narrow spectral bands enable mineral composition identification and defense intelligence applications. Domestic supply constraints and specialized interpretation requirements restrict deployment to KARI-coordinated research programs and premium defense contracts.
- Thermal Imaging:Long-wave infrared detection supports industrial facility monitoring and urban heat island analysis for municipal climate adaptation planning.
- LiDAR:Active laser ranging generates high-fidelity elevation models for infrastructure engineering and forestry inventory applications.
Procurement volume concentrates in Multispectral. Technical differentiation and premium pricing accrue to Hyperspectral.
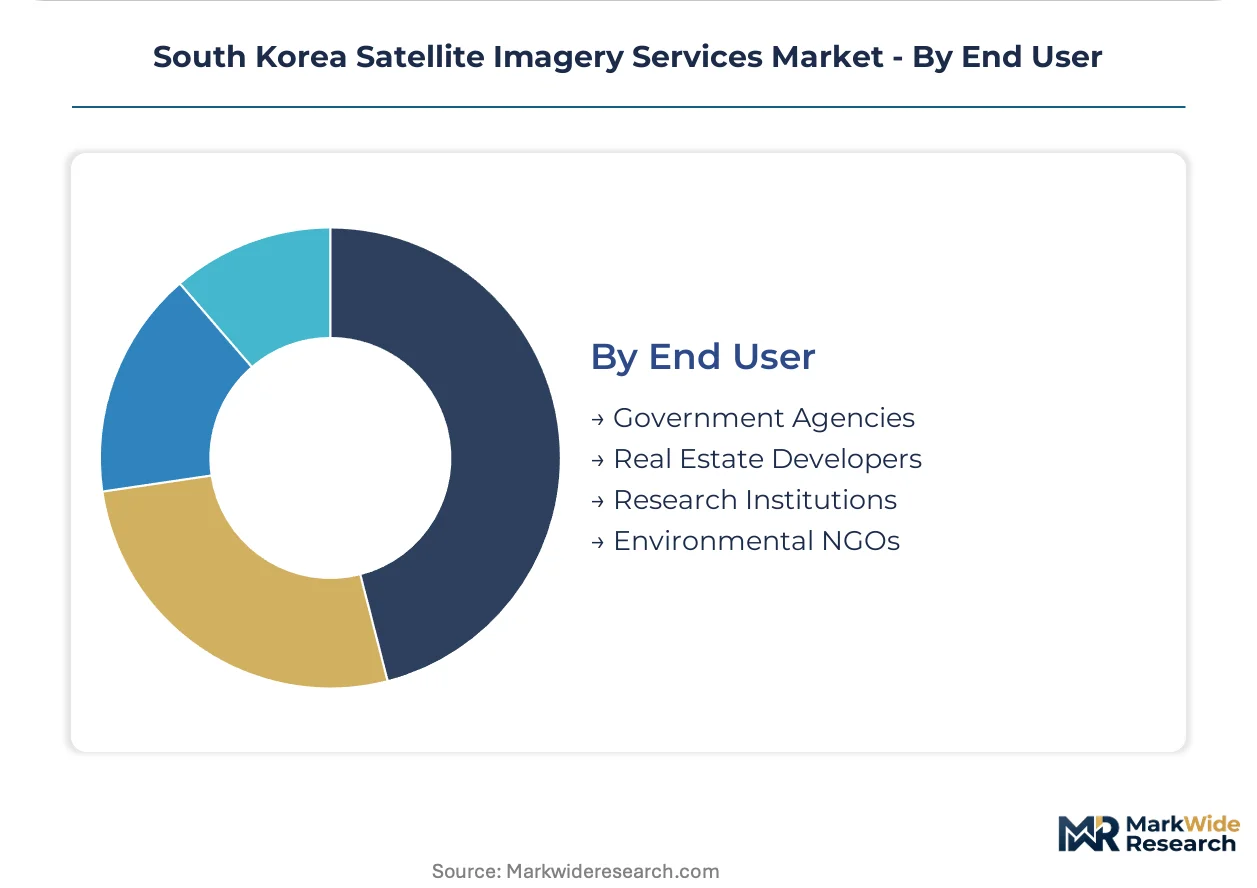
End User:
Contracting authority and data security clearance requirements segment customers by procurement channel access and price sensitivity.
- Government Agencies:National Geographic Information Institute and Ministry of Land, Infrastructure and Transport anchor demand through consolidated tenders. Multi-year framework agreements specify radiometric calibration standards and metadata traceability that exclude uncertified vendors from national land survey contracts.
- Real Estate Developers:Seoul and Busan property firms utilize 3D visualization and site analysis for pre-construction planning. Commercial tasking costs and delivery timeline constraints limit penetration to large-scale developers with dedicated geospatial budgets.
- Research Institutions:KARI-affiliated universities and technical colleges access subsidized K-SAT constellation capacity for climate and geological studies.
- Environmental NGOs:Coastal conservation and reforestation monitoring groups leverage medium-resolution archives for advocacy and project evaluation.
Budget authority and procurement volume sit with Government Agencies. Emerging demand with growth trajectory is concentrated in Real Estate Developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors South Korea's satellite imagery services demand through metropolitan development corridors and national spatial data infrastructure mandates. Provincial industrial zones and agricultural belts generate specialized requirements that reshape procurement patterns across the peninsula.
Seoul Capital Area
Urban planning authorities in Seoul and Sejong City drive orthophotography demand for cadastral verification and construction compliance monitoring. MFDS geospatial protocols mandate certified accuracy standards for national land survey contracts, filtering vendor eligibility. The Gyeonggi-do development corridor surrounding Seoul sustains multi-year framework agreements for 3D mapping refresh cycles.
Busan-Ulsan
Port logistics operators and shipyard facilities generate maritime infrastructure monitoring requirements distinct from Seoul-centric demand. The country's national geographic information institute directs satellite tasking capacity toward coastal erosion tracking and industrial facility surveillance. Hyundai Heavy Industries concentration in Ulsan pulls specialized elevation modeling for shipyard expansion planning.
Daegu-Gyeongbuk
Defense and aerospace manufacturing clusters in this southeastern region access KOMPSAT archive data for facility security and supply chain monitoring. KARI satellite operation licenses prioritize government-coordinated tasking schedules over commercial demand signals. Daegu's technology parks host geospatial analytics startups serving regional manufacturing clients.
Daejeon-Sejong
KARI headquarters and government administrative functions concentrate procurement authority for K-SAT constellation capacity allocation. The National Geographic Information Institute in Sejong consolidates tender specifications that shape vendor certification requirements across all domestic providers. Research institutions in Daejeon access subsidized imagery for climate and geological studies.
Gwangju-Honam
Agricultural cooperatives across Jeolla province contract vegetation analysis services for rice and greenhouse crop management. Precision farming adoption spreads multispectral monitoring demand through farming extension services. The region's relatively lower satellite imagery penetration compared to Seoul creates whitespace for API-driven subscription models targeting mid-size agricultural operators.
South Korea Satellite Imagery Services Market Competitive Landscape
Capital-heavy satellite operators compete with asset-light analytics platforms for value capture across South Korea's imagery services stack. The market structure concentrates archive control among government-affiliated entities while fragmenting downstream processing and application development. Three archetypes dominate: constellation operators with exclusive domestic licensing, international high-resolution tasking providers, and AI-native analytics specialists. Competitive positioning hinges on KARI data access agreements and MFDS certification attainment rather than pure technical capability.
Within the government-affiliated operator tier, SI Imaging Services exemplifies archive-dependent positioning through KOMPSAT constellation control. Among international tasking specialists, Maxar Technologies occupies a position defined by sub-meter panchromatic capacity over the Korean peninsula. On the AI-native analytics vector, Dabeeo Inc. represents cloud-based API distribution models that compress delivery timelines for urban planning clients. These three anchors illustrate how competitive advantage in South Korea's market flows from data access rights, regulatory certification, and processing speed rather than sensor hardware ownership alone.
| Leading Market Players |
|---|
| SI Imaging Services |
| GBS Korea |
| Dabeeo Inc. |
| Dtonic Corporation |
| Soletop InSpace Co., Ltd. |
| Maxar Technologies |
| L3Harris Corporation Inc. |
| Bentley Systems, Inc. |
| ESRI Inc. |
| Others |
Pricing and Supply Chain Analysis
Ground station network infrastructure costs cascade through South Korea's satellite imagery value chain, with KARI-coordinated orbital platform access fees compressing margins at the processing tier while MFDS certification investments stratify final delivery pricing across government and commercial channels.
Pricing Analysis
Outcome-based pricing anchored to cadastral survey accuracy certification commands premium positioning in South Korea's satellite imagery market. Three-tier pricing structure across certified orthophotography, standard multispectral analytics, and economy archive access segments buyer budgets by compliance requirements. Pricing pressure stems from framework contracting consolidation among Seoul metropolitan agencies, which compresses supplier margins through volume-commitment tenders. Government agencies exhibit lowest price sensitivity due to mandated accuracy standards, while mid-tier civil engineering consultancies face exclusion from premium analytics tiers.
Supply Chain Analysis
Single-source vulnerability sits with KARI-controlled K-SAT constellation launch schedules and KOMPSAT archive distribution rights. Domestic supply draws from government-coordinated orbital platforms, with international tasking capacity resting on Maxar Technologies and other foreign operators for sub-meter panchromatic coverage. Raw material dependencies include specialized sensor arrays, radiometric calibration equipment, and ground control point networks. Tariff exposure on foreign high-resolution tasking services creates procurement risk for uncertified domestic providers. Distribution runs through direct government framework contracts, API-driven subscription platforms, and consortium-pooled certification arrangements for smaller analytics firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's satellite imagery market operates as a cost-of-compliance story where MFDS geospatial data protocols and NGII accuracy standards erect barrier-to-entry moats that reward certified incumbents while filtering speculative entrants.
For Market Incumbents: To counter framework contracting margin compression, deepen backward integration into ground processing infrastructure to capture certification-tier premiums. Prioritize K-SAT constellation data access agreements that lock in orbital platform allocation ahead of civilian capacity expansion. For New Entrants and Emerging Players: Enter via API-driven subscription models targeting Busan-Ulsan maritime infrastructure monitoring and Gwangju-Honam agricultural cooperatives, where Seoul-centric vendor penetration remains limited. Lead with AI-powered change-detection interfaces that compress delivery timelines below incumbent project-based workflows. For Investors and Strategic Acquirers: K-SAT constellation civilian capacity allocation announcements are the leading indicator that public-private data sharing agreements are unlocking new addressable demand. Long-term viability favors analytics platforms with MFDS certification attainment and cloud-native delivery architectures over hardware-dependent operators. Target acquisition profiles should emphasize firms with established KARI data access and recurring government framework contract revenue.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Investment | NGII accuracy standards filter vendor eligibility for national land survey contracts. |
| API Platform Development | Cloud-based change-detection interfaces compress delivery timelines for urban planning clients. |
| K-SAT Data Access Agreement | Orbital platform allocation locks in supply security ahead of civilian capacity expansion. |
| AI Analytics Capability Buildout | Automated feature extraction commands premium positioning in vegetation analysis segments. |
| Consortium Certification Pooling | Shared compliance costs enable mid-tier firms to access framework contracting channels. |
Research Methodology
KARI technical publications, MFDS regulatory filings, and National Geographic Information Institute procurement records formed the secondary backbone, supplemented by customs data on satellite equipment imports and K-SAT constellation deployment disclosures. Primary interviews with geospatial data procurement officers at Seoul metropolitan agencies, defense channel distributors, agricultural extension service managers, and commercial analytics platform executives validated demand assumptions. Bottom-up triangulation across service type, application, and end-user segments reconciled with top-down market sizing from orbital platform capacity and tasking rate analysis.
Bottom-up modeling anchored volume projections to government framework contract award patterns and precision agriculture adoption curves across Jeolla and Gyeongsang farming belts. Segmentation dimensions included service type, application, technology tier, and end-user procurement authority. CAGRs were derived from satellite launch schedules, KARI capacity allocation announcements, and MFDS regulatory implementation timelines. Industry-specific forecast inputs incorporated K-SAT constellation civilian channel expansion and AI-API subscription model penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under KARI launch delays or accelerated public-private data sharing liberalization. Projections reflect assumptions about MFDS certification enforcement consistency and foreign high-resolution tasking cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Japan Satellite Communication Market
Satellite
Japan Satellite Connectivity Market
Satellite
Europe Satellite IoT Market
Satellite
Satellite Gateway Market
Satellite
Satellite Imaging Market
Satellite
Global Dish Antennas Market
Satellite
Global Satellite Modem Market
Satellite
Europe Small Satellite Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Electric Propulsion Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Satellite Bus Market