
 Military Transport Aircraft Market | 2026-2036
Military Transport Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Military Transport Aircraft Market Intelligence
The EU Green Deal is repositioning European defense procurement toward lower-emission transport platforms and sustainable aviation fuel compatibility. Lockheed Martin leverages its C-130J Super Hercules production line to sustain market presence across NATO operators. Airbus Defense and Space anchors European strategic airlift demand through A400M deliveries and aftermarket support networks. Boeing Defense, Space & Security competes on the KC-46 Pegasus tanker-transport hybrid, extending its reach into multi-mission contracts.
Military transport aircraft are fixed-wing platforms engineered for payload capacities spanning lightweight tactical loads to super heavy outsized cargo, typically operating from semi-prepared runways with defensive systems integration. Their primary purpose is the rapid projection of personnel, equipment, and supplies into contested or austere environments where commercial aviation infrastructure is unavailable or denied. Strategic operation types dominate value pools due to long-range heavy-lift requirements and platform longevity, while humanitarian and medical evacuation missions represent the fastest-growing operation type as militaries expand dual-use mandates. Payload capacity segmentation shows heavy platforms commanding premium pricing, though medium payload systems see accelerated procurement cycles from middle-power air forces seeking fleet flexibility.
The U.S. Department of Defense and NATO's Airlift Management Programme Board shape platform interoperability standards, while EASA and national military certification authorities govern airworthiness for European-registered defense aircraft. FAA regulations on civil derivative components create compliance bridges for platforms with dual military-civil applications. Stakeholders must monitor how sustainable aviation fuel mandates from Brussels and Washington alter engine specification requirements and retrofit economics for in-service fleets.
Market Dynamics
Defense procurement offices across NATO are consolidating tactical and strategic airlift requirements into multi-mission platform specifications, compressing supplier margins while extending contract durations.
Growth Catalysts
- EU Green Deal mandates:Sustainable aviation fuel compatibility requirements are accelerating engine retrofit programs and new propulsion research investments across European air forces.
- Indo-Pacific territorial defense postures:Australia, Japan, and South Korea are expanding medium and heavy payload fleets to address contested logistics corridors and disaster relief contingencies.
- Semi-prepared runway engineering advances:Improved landing gear and surface assessment systems are opening austere basing options previously inaccessible to heavy transport categories.
Market Restraints
- Titanium and specialty alloy supply concentration:Russian and Chinese dominance in aerospace-grade raw materials creates input cost volatility and sanctions exposure for Western manufacturers.
- Platform development timelines:Clean-sheet military transport programs require 15-20 year development cycles, locking procurement offices into aging fleet extensions.
- Civil aviation labor competition:Maintenance and flight crew talent migrates toward commercial carriers offering superior compensation, draining military operator readiness.
Strategic Opportunities
- Modular mission package architectures:Tanker, medical evacuation, and surveillance modules are converting single-role platforms into revenue-generating multi-mission assets.
- Unmanned aerial logistics convergence:Autonomous cargo drones and optionally manned transport concepts are merging with traditional fixed-wing programs.
- Indonesia and Philippines archipelagic requirements:Distributed island chains lacking road infrastructure create sustained demand for short-field tactical lift capabilities.
Industry Challenges
- Military type certification complexity:FAA and EASA civil-military harmonization efforts are extending airworthiness approval timelines for platforms with dual-use applications.
- Legacy system integration friction:Digital avionics upgrades on Cold War-era airframes encounter incompatible data bus architectures and obsolete software documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Transport Aircraft Market |
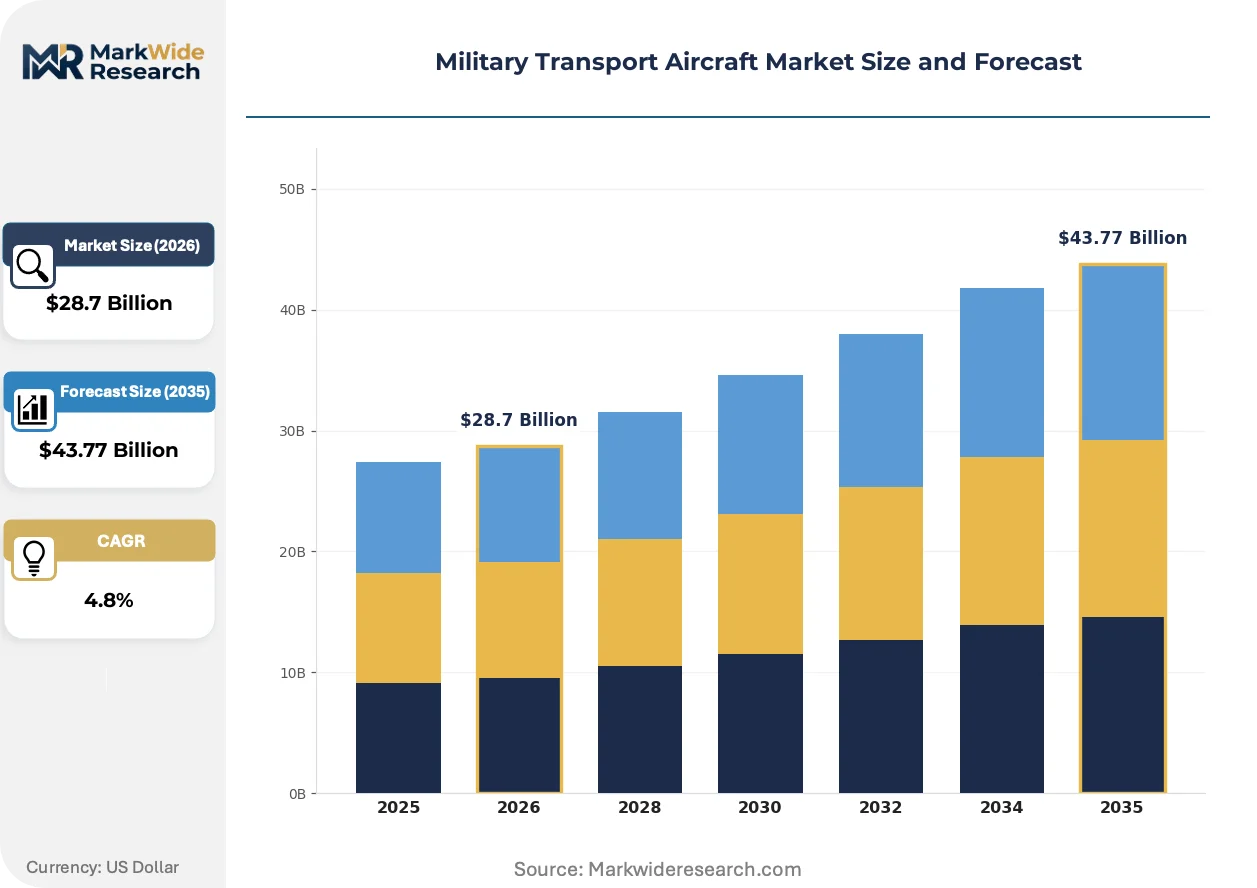
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Model: C-130, C-17, A400M, KC-46 Operation Type: Strategic, Tactical, Humanitarian, Medical Evacuation Payload Capacity: Medium, Heavy, Super Heavy, Lightweight End User: Military, Government, Private Contractors, NGOs |
| Companies Covered | Embraer Defense & Security, Kawasaki Heavy Industries, Lockheed Martin, Hindustan Aeronautics Limited, Antonov Company, Boeing Defense, Space & Security, United Aircraft Corporation/Ilyushin, AVIC/Xi'an Aircraft Industrial Corporation, Airbus Defense and Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Transport Aircraft Market Strategic Shifts & Innovations
Propulsion electrification and hybrid architectures are redefining range-payload tradeoffs, while open systems architectures are collapsing traditional avionics supplier monopolies.
Hybrid-electric distributed propulsion is electrifying subsonic cargo operations by replacing centralized turbine shafts with wing-embedded electric motors. Air forces in Norway and New Zealand are evaluating demonstrators for reduced-signature tactical insertions. This architecture is electrifying conventional assumptions about runway length requirements and acoustic detectability.
REACH chemical registration and EU F-Gas Regulation are phasing out legacy fire suppression and cooling chemistries in European-registered defense aircraft. Manufacturers must reformulate systems or face fleet grounding risks. German and French certification authorities are prioritizing platforms with closed-loop thermal management.
Performance-based logistics contracts are replacing traditional spares-and-maintenance agreements, transferring availability risk from air forces to original equipment manufacturers. Royal Australian Air Force C-130J sustainment contracts now specify mission-capable rates rather than parts delivery schedules. This model concentrates most visibly in Anglo-Pacific operator communities seeking reduced uniformed maintenance footprints.
Military Transport Aircraft Market Segmentation
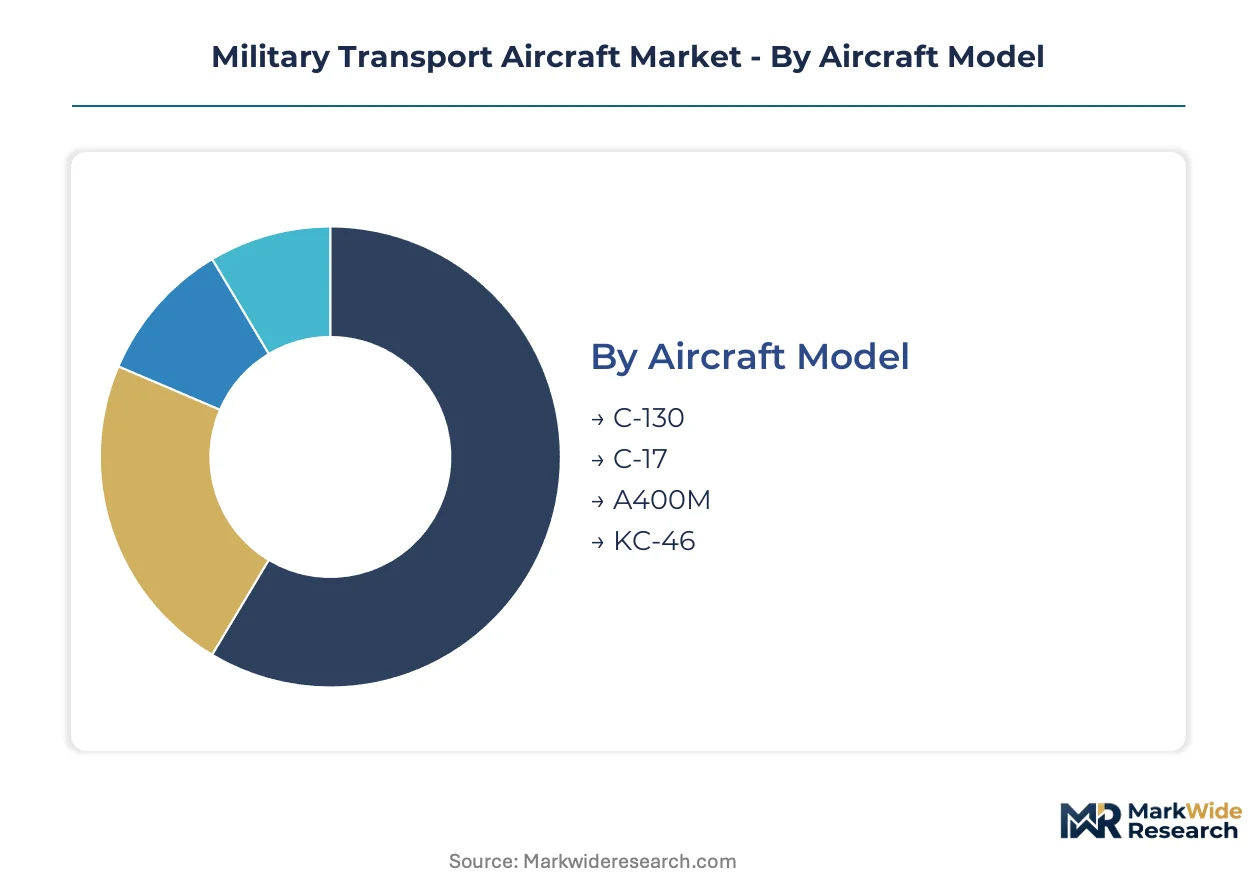
Segmentation reveals how procurement offices balance fleet modernization against budget constraints. Upgrade cycles and platform longevity drive purchasing patterns across operator categories. Understanding these divisions exposes where retrofit investments concentrate versus clean-sheet acquisitions.
Aircraft Model:
Replacement timelines for Cold War-era airframes dominate procurement planning, with operators weighing commonality benefits against performance step-changes.
- C-130:The tactical airlift workhorse features turboprop propulsion and short-field landing gear for austere runway operations. NATO members in Poland and Norway prioritize C-130J variants for intra-theater logistics and special operations support, driven by interoperability requirements with US expeditionary forces.
- C-17:Strategic heavy-lift platforms enable direct delivery of outsized combat equipment from continental bases to theater entry points. The Royal Australian Air Force and Royal Air Force sustain C-17 fleets for humanitarian relief surge capacity, constrained by Boeing's closed production line and finite airframe hours.
- A400M:European turboprop alternative bridges tactical responsiveness with strategic range for continental defense scenarios.
- KC-46:Tanker-transport hybrid architectures reduce fleet counts through multi-mission flexibility for Pacific theater operations.
C-130 sits at the top of the volume ranking, with KC-46 climbing the fastest as tanker recapitalization accelerates.
Operation Type:
Cost tier differentiation separates capital-intensive strategic assets from rapidly deployable tactical systems with lower per-mission overhead.
- Strategic:Long-range heavy-lift missions spanning intercontinental distances with maximum payload configurations. The US Transportation Command and NATO's Airlift Management Programme Board prioritize strategic capacity for rapid global force projection, constrained by airfield infrastructure requirements at destination theaters.
- Tactical:Short-to-medium range insertions into semi-prepared surfaces near contested zones. Air forces in Indonesia and the Philippines drive tactical procurement for archipelagic resupply, responding to distributed basing concepts and limited road connectivity.
- Humanitarian:Disaster relief and emergency response missions with rapid configuration changes for irregular cargo profiles.
- Medical Evacuation:Aeromedical transport with intensive care capabilities for casualty evacuation chains.
Strategic operations command the premium pricing tier, while medical evacuation gains share fastest as dual-use mandates expand.
Payload Capacity:
Volume concentration in heavy platforms reflects their irreplaceable role in outsized cargo movement, though procurement velocity favors flexibility.
- Medium:Payload ranges between 20-50 tons enable multi-mission flexibility without strategic airfield dependencies. Japan Air Self-Defense Force and Republic of Korea Air Force procurement emphasizes medium platforms for regional contingency response, driven by territorial defense postures and alliance burden-sharing requirements.
- Heavy:50-100 ton capacity supports main battle tank delivery and engineering equipment transport. The Indian Air Force and Brazilian Air Force pursue heavy-lift acquisitions for expeditionary force sustainment, constrained by runway pavement strength and ground handling equipment availability.
- Super Heavy:Specialized outsized cargo capacity exceeding 100 tons for aerospace components and infrastructure modules.
- Lightweight:Sub-20 ton platforms for special operations and austere insertion missions.
Heavy platforms dominate fleet investment value, with medium capacity expanding most quickly among middle-power air forces.
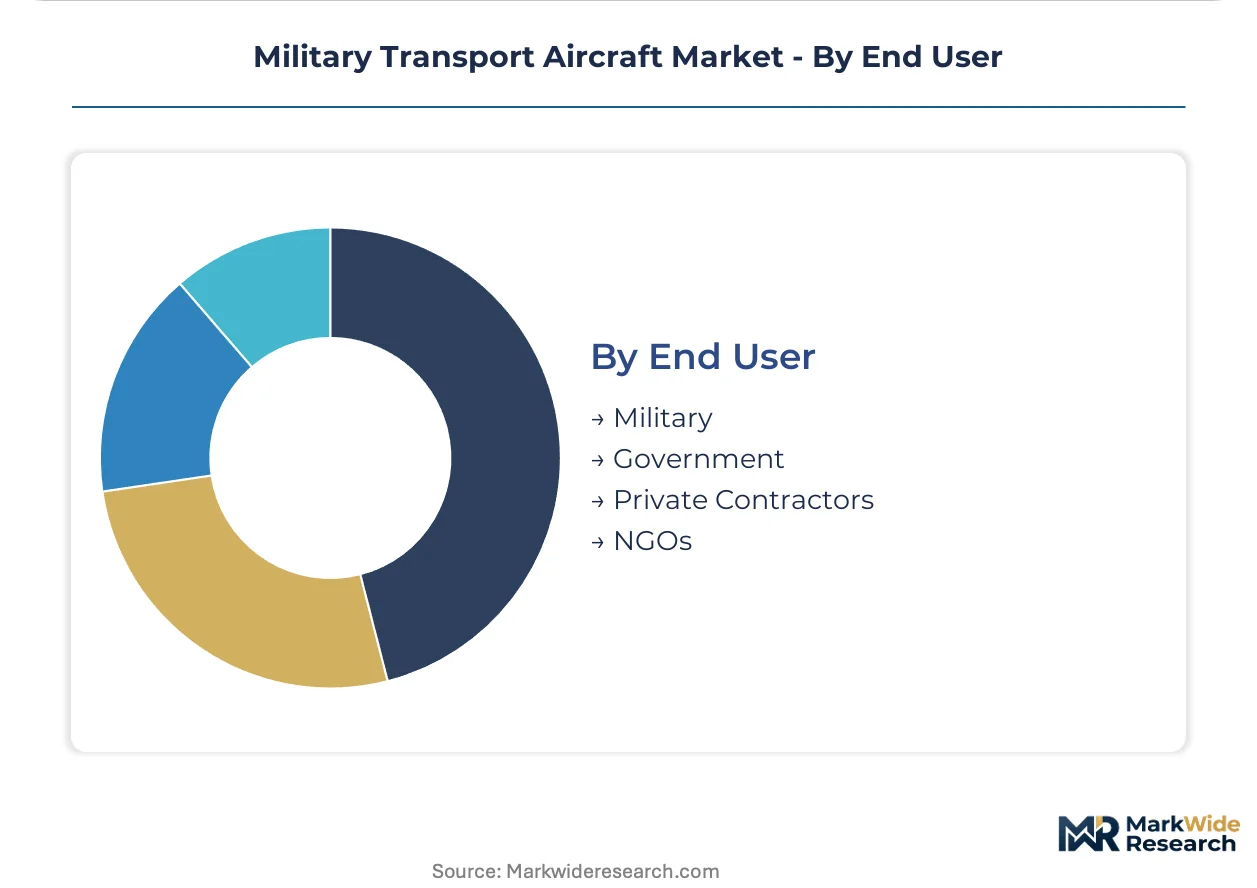
End User:
Customer type determines specification rigor, with military operators driving certification standards that cascade to government and contractor fleets.
- Military:National air forces with full-spectrum defensive systems integration and electronic warfare suites. The US Air Force, Royal Air Force, and Luftwaffe define platform requirements through NATO standardization agreements, prioritizing interoperability and coalition operability over unit cost optimization.
- Government:Civil protection agencies and border security services with reduced threat environment specifications. Federal Emergency Management Agency and analogous European civil defense organizations acquire transport capacity for domestic disaster response, driven by surge requirements beyond commercial charter availability.
- Private Contractors:Commercial operators with modified military platforms for logistics support contracts.
- NGOs:Humanitarian organizations with civil-registered aircraft for relief operations in permissive environments.
Military end users anchor platform development roadmaps, with private contractors representing the fastest-climbing customer category as outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled aerospace workforces in Toulouse, Seattle, and São José dos Campos anchor regional production networks. Defense procurement offices in Canberra, Warsaw, and Seoul concentrate platform specifications. Industrial clusters around Hamburg, Nagoya, and Bengaluru shape subsystem supply chains.
United States
The US Air Force drives strategic airlift recapitalization through tanker-transport hybrid acquisitions. FAA regulations on civil-derivative components create compliance bridges for dual-use platforms. Boeing's Everett facility and Lockheed Martin's Marietta complex concentrate final assembly and systems integration for NATO interoperable fleets.
Germany
The Luftwaffe prioritizes A400M deliveries for continental defense scenarios and alliance burden-sharing. EU Green Deal sustainable aviation fuel mandates accelerate engine retrofit programs across European-registered defense aircraft. Airbus Defense and Space's Hamburg-Bremen industrial corridor anchors turboprop final assembly and aftermarket support networks.
Australia
The Royal Australian Air Force expands C-130J and C-17 fleets for Indo-Pacific contested logistics and humanitarian surge capacity. Performance-based logistics contracts specify mission-capable rates rather than parts delivery schedules. RAAF Base Richmond in New South Wales concentrates tactical airlift operations and regional maintenance infrastructure.
Japan
The Japan Air Self-Defense Force procures medium payload platforms for territorial defense and regional contingency response. METI industrial policy supports domestic aerospace supply chain development for defense applications. Kawasaki Heavy Industries' Gifu and Kakamigahara facilities specialize in tactical transport engineering and subsystem manufacturing.
Brazil
The Brazilian Air Force pursues heavy-lift acquisitions for expeditionary force sustainment and Amazon basin logistics. ANVISA and national military certification authorities govern airworthiness for defense aircraft with dual civil-military applications. Embraer's São José dos Campos complex anchors regional transport platform development and Latin American operator support.
Military Transport Aircraft Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent risk-return profiles. The market structure consolidates around full-spectrum system integrators with captive airframe and propulsion capabilities, while specialized subsystem suppliers occupy niche tier positions. Strategic archetypes separate platform prime contractors from engine manufacturers and avionics integrators. Competitive moves concentrate on multi-mission contract bundling and performance-based logistics partnerships.
Among American system integrators, Lockheed Martin and Boeing Defense, Space & Security exemplify the platform prime archetype with sustained NATO operator relationships. Airbus Defense and Space occupies a comparable position in the European tier through A400M production continuity. Kawasaki Heavy Industries represents the Asia-Pacific specialist model with domestic market anchoring and selective export positioning.
| Leading Market Players |
|---|
| Embraer Defense & Security |
| Kawasaki Heavy Industries |
| Lockheed Martin |
| Hindustan Aeronautics Limited |
| Antonov Company |
| Boeing Defense, Space & Security |
| United Aircraft Corporation/Ilyushin |
| AVIC/Xi'an Aircraft Industrial Corporation |
| Airbus Defense and Space |
| Others |
Cost & Logistics Intelligence
Platform tier divergence between heavy strategic lifters and medium tactical workhorses manifests in divergent pricing architectures and supplier network configurations. Heavy platforms command long-term fixed-price development contracts with cost-plus escalation clauses, while medium payload systems trade on competitive tender pricing with compressed margins. This bifurcation concentrates titanium and specialty alloy sourcing through aerospace-grade suppliers in Russia and China, creating sanctions exposure that OEMs mitigate via strategic stockpiling and alternative metallurgy research.
Pricing Analysis
Bundled performance-based logistics contracts now dominate heavy platform sustainment, unbundling traditional spares-and-maintenance into availability-guarantee pricing. Price differentiation rests on mission-capable rate commitments and multi-mission module integration depth. Cost compression in medium payload segments intensifies as NATO procurement offices consolidate tactical requirements into fewer platform types. Government civil defense agencies exhibit highest price sensitivity due to fixed appropriation ceilings, while expeditionary air forces prioritize operational availability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense procurement from the US Air Force and NATO's Airlift Management Programme Board, bypassing distributor intermediaries for platform acquisitions. Manufacturing concentration centers on final assembly in the United States, Germany, and Brazil, with subsystem sourcing from Japan and France. Supply chains draw from titanium sponge producers in Russia, precision forgings from China, and avionics from Israeli and British specialists. Single-source vulnerability in aerospace-grade raw materials creates tariff and sanctions exposure. Distribution runs through military logistics commands and authorized depot maintenance partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Military Transport Aircraft Market functions as a stable compounder, underpinned by irreplaceable strategic airlift requirements for expeditionary force projection that resist demand cyclicality.
For Market Incumbents: To counter titanium supply concentration and sanctions exposure, Lockheed Martin and Airbus Defense and Space should deepen backward integration into specialty alloy recycling and alternative metallurgy R&D. Certification investment in sustainable aviation fuel compatibility across in-service C-130J and A400M fleets preserves NATO operator relationships against emerging hybrid-electric challengers. For New Entrants and Emerging Players: Launch via performance-based logistics partnerships with middle-power air forces in Indonesia and the Philippines seeking reduced uniformed maintenance footprints. Archipelagic resupply requirements create the most penetrable white space, with autonomous cargo drone integration offering a distinct go-to-market angle against established fixed-wing primes. For Investors and Strategic Acquirers: Consolidation pressure builds where subsystem suppliers face open systems architecture mandates that collapse traditional avionics monopolies. Long-term viability favors platform primes with captive engine and airframe integration. Acquisition targets include specialized landing gear and austere runway assessment technology providers. Watch for EU Green Deal enforcement timelines as inflection indicators for retrofit program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | Royal Australian Air Force C-130J sustainment transfers availability risk from operators to Lockheed Martin. |
| Sustainable Aviation Fuel Retrofit Programs | EU Green Deal mandates accelerate engine modification investments across Luftwaffe and NATO European fleets. |
| Multi-Mission Module Architecture Development | KC-46 Pegasus tanker-transport hybrid reduces fleet counts for US Indo-Pacific posture requirements. |
| Autonomous Cargo Drone Integration | Norwegian and New Zealand air forces evaluate electric distributed propulsion for reduced-signature tactical insertions. |
| Semi-Prepared Runway Engineering Advancement | Improved landing gear systems open austere basing options for Indian and Brazilian heavy-lift acquisitions. |
Research Approach
Coverage spans the United States, Germany, Australia, Japan, and Brazil, with primary inputs from each territory combined with secondary validation. Interviews with air force procurement officers, platform program managers at Lockheed Martin and Airbus Defense and Space, aftermarket service directors, and NATO standardization officials informed demand-side assessments. Secondary sources include FAA and EASA certification filings, EU Green Deal regulatory texts, US Transportation Command budget justifications, and national defense white papers from Australia and Japan. Bottom-up fleet inventory analysis triangulates against top-down defense expenditure projections.
Granularity-level modeling disaggregates volume and value across payload capacity tiers, operation type categories, and end-user segments, with additional dimensioning by propulsion architecture and mission system configuration. CAGRs derive from regression analysis of historical procurement cycles and projected replacement timelines for Cold War-era airframes. Industry-specific forecast inputs incorporate NATO burden-sharing agreements and Indo-Pacific territorial defense posture shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained titanium supply disruption or accelerated EU sustainable aviation fuel mandates. Periodic stress-testing of base assumptions is recommended, particularly regarding sanctions exposure on Russian and Chinese aerospace material suppliers and civil aviation labor competition effects on military operator readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
US Business Jet Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
Aircraft Sequencing System Market
Aircraft
Global Business Aircraft Market
Aircraft
Europe General Aviation Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Winglets Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Global Helicopter Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Aircraft Mounts Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Electric Aircraft Market