
 Aircraft Ice Protection System Market | 2026-2036
Aircraft Ice Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Ice Protection System Market Analysis
Certification-grade thermal performance is unwinding across the aircraft ice protection landscape. Collins Aerospace leverages its integrated avionics-to-thermal architecture to dominate line-fit contracts for narrowbody platforms. Honeywell International Inc. sustains R&D intensity in electrothermal actuator designs that reduce bleed-air dependency. Meggitt PLC anchors European aftermarket demand through its maintenance network across British and French airfields.
An aircraft ice protection system comprises integrated thermal, electrical, pneumatic, or chemical subsystems engineered to detect atmospheric icing conditions and dissipate accreted ice from critical flight surfaces, typically operating at power densities exceeding 5 kW per square meter on wing leading edges and engine nacelles. Electrothermal technology leads product development cycles due to its precision control and reduced aircraft power draw compared to legacy bleed-air architectures. Commercial aviation commands the largest installation base, while military aviation represents the fastest-growing end-user segment as unmanned platforms expand cold-weather operational envelopes. Retrofit installations concentrate margin pools in aging regional jet fleets requiring FAA-mandated ice detection upgrades.
FAA Part 25 Appendix C icing envelopes and EASA CS-25 certification standards shape minimum performance thresholds for supercooled large droplet conditions, directly determining product development roadmaps and market access eligibility. The EU Green Deal's decarbonization targets are forcing electrothermal system prioritization over pneumatic bleed-air methods that reduce engine thermodynamic efficiency. Stakeholders must monitor evolving certification requirements for hybrid-electric propulsion architectures where thermal management budgets compete directly with ice protection energy allocation.
Market Dynamics
Electrothermal architecture is displacing bleed-air systems as the dominant thermal management paradigm, driven by FAA and EASA mandates for reduced engine bleed dependency and the EU Green Deal's thermodynamic efficiency requirements.
Growth Catalysts
- FAA Part 25 Appendix C:Certification standards for supercooled large droplet conditions compel fleet-wide ice detection upgrades across commercial aviation platforms.
- Unmanned military platforms:Cold-weather operational envelope expansion for autonomous systems generates demand for lightweight electrothermal actuators.
- Regional jet retrofit cycles:Aging narrowbody fleets in the United States trigger mandated ice protection system replacements.
Market Restraints
- High-purity nickel-chromium alloy supply:Heating element raw material concentration in Russian and Chinese smelters creates input cost volatility.
- Bleed-air incumbent lock-in:Boeing and Airbus pneumatic system commonality across existing fleets slows electrothermal conversion timelines.
- Supercooled large droplet test infrastructure:Limited FAA-certified icing wind tunnel capacity in the United States extends product validation cycles.
Strategic Opportunities
- Hybrid-electric propulsion architectures:Thermal management budget competition between ice protection and battery cooling creates integrated system design white space.
- Aftermarket service unbundling:Airlines are separating ice protection maintenance from OEM bundled contracts, opening independent MRO channels.
- EU Green Deal decarbonization incentives:Electrothermal system prioritization over pneumatic methods unlocks green financing for fleet retrofits.
Industry Challenges
- Multiphysics simulation talent scarcity:CFD-thermal-electrical coupled modeling expertise required for electrothermal actuator design concentrates at a handful of aerospace engineering programs.
- Legacy pneumatic integration complexity:Bleed-air system removal during retrofit triggers engine nacelle structural recertification with FAA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Ice Protection System Market |
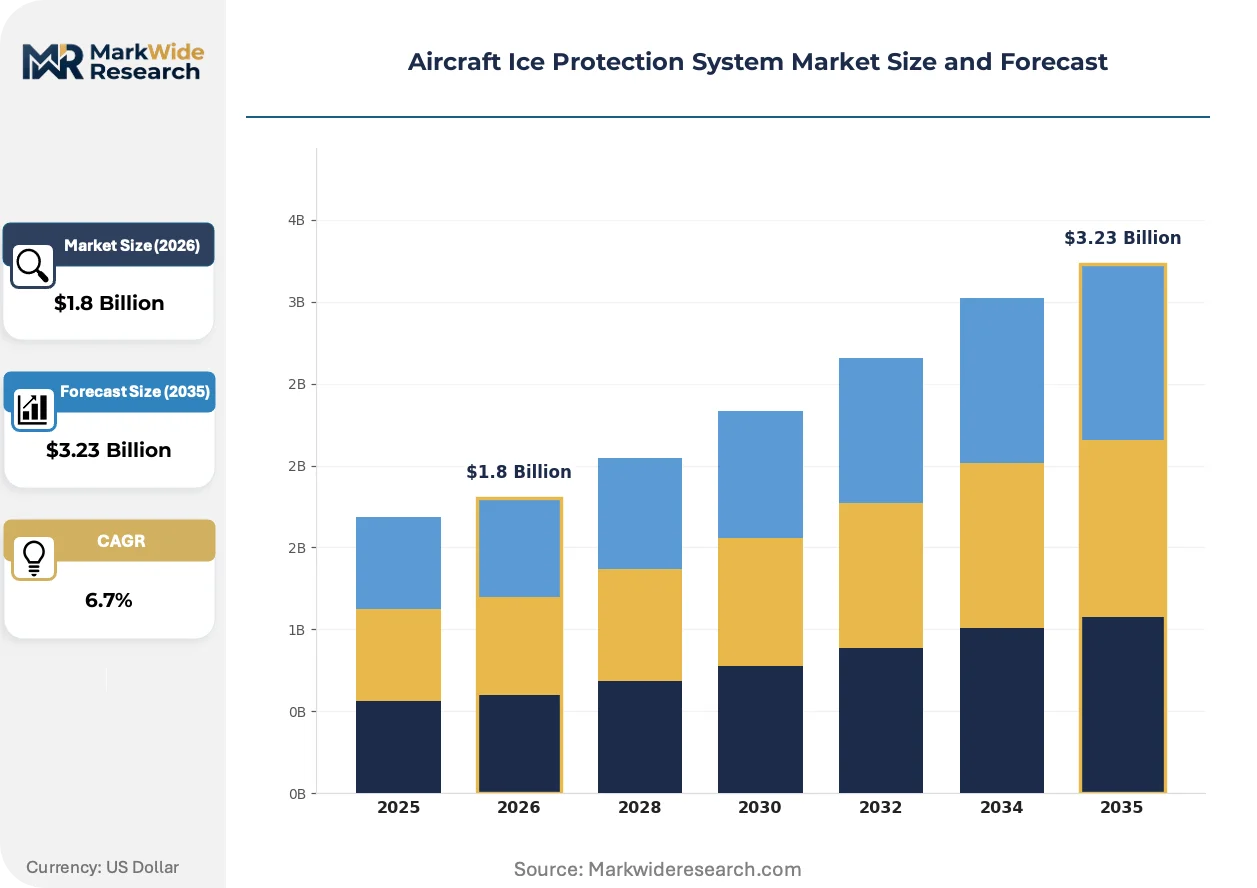
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Systems, Electrical Systems, Pneumatic Systems, Chemical Systems Technology: Electrothermal, Autothrottle Control, Supercooled Liquid, Heated Surfaces End User: Commercial Aviation, Military Aviation, Business Aviation, General Aviation Installation Type: Retrofit, Line Fit, Upgrade, Maintenance |
| Companies Covered | Collins Aerospace, Honeywell International Inc., Meggitt PLC, CAV Ice Protection, Safran, Curtiss-Wright Corporation, Cox & Company, Ultra Electronics, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Ice Protection System Market Emerging Trajectories
Active sensor fusion and predictive ice accretion algorithms are compressing system response latency from detection to dissipation. Three convergent developments are redefining competitive capability requirements.
Carbon nanotube heating element film is miniaturizing wing leading edge thermal management packaging. Business jet OEMs are adopting this technology for reduced power draw and weight penalties. The structural consequence is miniaturizing actuator footprint while maintaining FAA Part 25 thermal density thresholds.
EASA CS-25 amendments for hybrid-electric aircraft are forcing ice protection energy allocation into propulsion thermal budgets. Manufacturers must now demonstrate system performance under battery thermal load competition. Narrowbody platforms with partial electric propulsion are experiencing the most acute certification timeline pressure.
Airline procurement departments are consolidating ice protection maintenance under power-by-the-hour contracts with independent MRO networks. Legacy OEM service agreements are losing exclusivity as carriers seek cost transparency. This shift is most visible among United States-based low-cost carriers operating aging regional jet fleets.
Aircraft Ice Protection System Market Segmentation
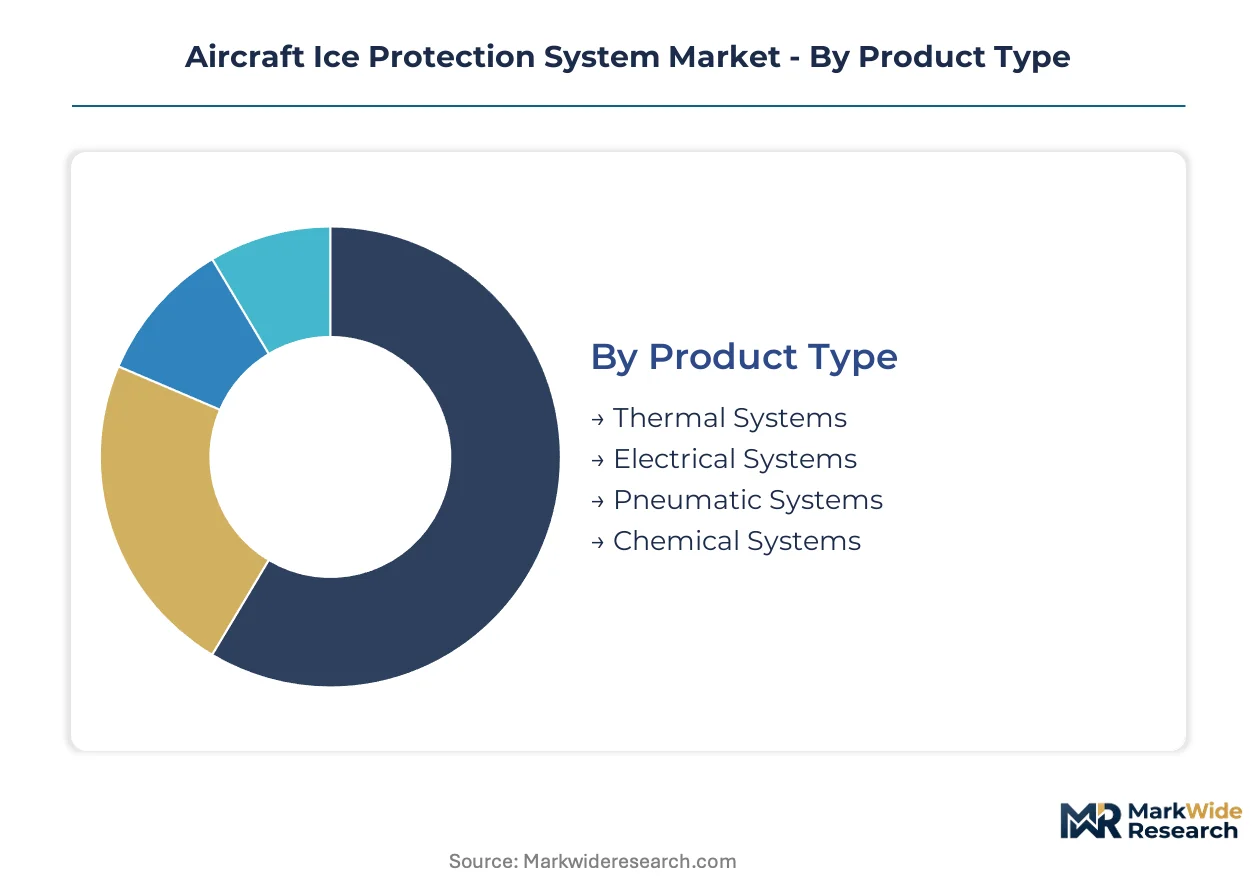
Segmentation in aircraft ice protection systems reveals divergent procurement channels and certification pathways. Product type and technology choices determine whether systems flow through OEM line-fit contracts or aftermarket retrofit channels, while end-user classification shapes regulatory scrutiny intensity and service bundling preferences.
Product Type:
Thermal and electrical systems dominate OEM line-fit procurement for new narrowbody platforms, while pneumatic and chemical alternatives concentrate in aftermarket retrofit channels for aging regional fleets.
- Thermal Systems:Bleed-air architectures utilizing engine compressor stage air deliver high heat flux for wing leading edges and engine nacelles. Boeing 737 MAX and Airbus A320neo families in the United States anchor line-fit demand as FAA Part 25 Appendix C certification tightens thermal density requirements.
- Electrical Systems:Electrothermal actuators with nickel-chromium heating elements achieve precision zone control at power densities exceeding 5 kW per square meter. European narrowbody assembly lines in France and Germany prioritize these systems under EU Green Deal thermodynamic efficiency mandates.
- Pneumatic Systems:Legacy rubber boot de-icers persist in regional jet aftermarket channels.
- Chemical Systems:Glycol-based weeping wing technologies serve limited general aviation applications.
By volume, thermal systems lead. By growth pace, electrical systems are expanding most quickly.
Technology:
Technology segmentation maps directly to development cost tiers, with electrothermal and heated surfaces commanding premium R&D investment while autothrottle control and supercooled liquid approaches occupy mid-tier and economy positions respectively.
- Electrothermal:Carbon nanotube film heating elements miniaturize actuator packaging for business jet leading edges. United States-based OEMs adopt this technology to reduce power draw and weight penalties while maintaining FAA thermal density thresholds.
- Heated Surfaces:Integrated metallic heating matrices embedded in composite wing structures serve hybrid-electric propulsion architectures. Battery thermal load competition in narrowbody platforms drives integration with propulsion thermal budgets.
- Autothrottle Control:Ice detection-to-throttle modulation links dominate military unmanned platforms.
- Supercooled Liquid:Runway de-icing fluid recovery systems serve ground-based infrastructure.
Electrothermal technology captures the steepest expansion trajectory as EASA CS-25 amendments force energy allocation trade-offs.
End User:
End-user segmentation concentrates margin pools differently, with commercial aviation generating volume throughput while military and business aviation yield higher per-unit technology premiums.
- Commercial Aviation:Narrowbody and widebody fleet renewal programs across United States, France, and Germany drive line-fit electrothermal adoption. FAA and EASA certification synchronization for supercooled large droplet conditions compels ice detection upgrades.
- Military Aviation:Unmanned platforms expanding cold-weather operational envelopes generate demand for lightweight electrothermal actuators. Autonomous system thermal budgets prioritize reduced power draw over legacy bleed-air dependency.
- Business Aviation:Carbon nanotube heating films penetrate jet OEM specifications for reduced packaging footprint.
- General Aviation:Cost-constrained piston aircraft operators defer to chemical and pneumatic alternatives.
Commercial aviation leads by installation base. Military aviation is gaining share fastest.
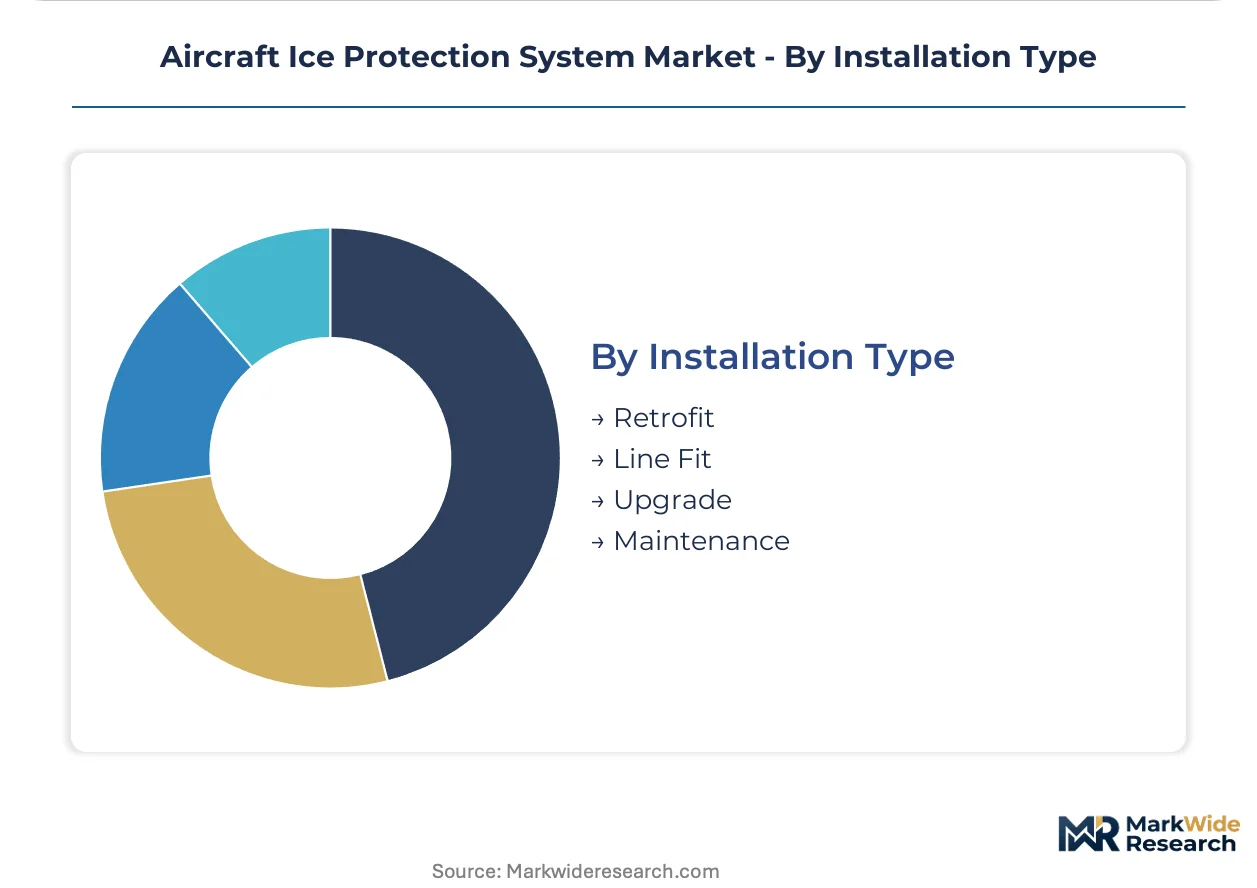
Installation Type:
Installation segmentation separates OEM-captive revenue from independent aftermarket opportunity, with line-fit and retrofit representing opposing channel strategies.
- Line Fit:OEM-integrated electrothermal systems ship with new aircraft from Boeing's Everett and Charleston facilities and Airbus assembly lines in Toulouse and Hamburg. Power-by-the-hour contracts increasingly bundle ice protection into airframe service agreements.
- Retrofit:Aging regional jet fleets in the United States trigger FAA-mandated ice detection system replacements. Independent MRO networks unbundle maintenance from OEM contracts as low-cost carriers seek cost transparency.
- Upgrade:Bleed-air-to-electrothermal conversions require engine nacelle structural recertification.
- Maintenance:Scheduled heating element replacement concentrates in British and French airfield networks.
Line fit dominates revenue concentration. Retrofit channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collins Aerospace and Honeywell anchor supply-side concentration in the United States, while Meggitt PLC sustains European aftermarket networks. France and Germany drive OEM line-fit demand through Airbus assembly clusters. Military unmanned platforms expand operational envelopes across Israel and Japan.
United States
Boeing's Everett and Charleston production hubs concentrate line-fit electrothermal contracts for narrowbody platforms. FAA Part 25 Appendix C certification standards for supercooled large droplet conditions compel fleet-wide ice detection upgrades. The Pacific Northwest aerospace corridor hosts Collins Aerospace integrated avionics-to-thermal development facilities.
France
Airbus Toulouse assembly lines prioritize electrothermal systems under EU Green Deal thermodynamic efficiency mandates. EASA CS-25 amendments for hybrid-electric propulsion force energy allocation trade-offs between ice protection and battery thermal management. Safran anchors French supplier networks across the Occitanie aerospace cluster.
Germany
Airbus Hamburg facilities drive electrical system adoption for A320neo family platforms. EU Green Deal decarbonization targets accelerate bleed-air-to-electrothermal conversion timelines. Bavarian engineering centers concentrate multiphysics simulation talent for CFD-thermal-electrical coupled modeling.
United Kingdom
Meggitt PLC maintains aftermarket service networks across British airfields for regional jet heating element replacement. EASA certification synchronization with FAA standards shapes product validation requirements. Southwest England manufacturing clusters specialize in nickel-chromium alloy heating element fabrication.
Israel
Unmanned military platforms expanding cold-weather operational envelopes generate demand for lightweight electrothermal actuators. Autonomous system thermal budgets prioritize reduced power draw over legacy bleed-air dependency. Tel Aviv-area defense technology clusters develop active sensor fusion for predictive ice accretion algorithms.
Aircraft Ice Protection System Market Vendor Landscape
Concentration sits with diversified aerospace conglomerates possessing integrated thermal management portfolios. Three to five vertically integrated suppliers dominate OEM line-fit contracts for narrowbody and widebody platforms. Two strategic archetypes prevail: avionics-integrated system architects and specialized heating element fabricators. Competitive moves center on M&A for electrothermal actuator capabilities and strategic partnerships for hybrid-electric propulsion thermal budget integration.
Among diversified aerospace conglomerates, Collins Aerospace and Honeywell International Inc. represent the avionics-integrated system architect archetype, while Meggitt PLC exemplifies the specialized heating element and aftermarket service tier. CAV Ice Protection and Cox & Company occupy positions within the independent specialist fabricator segment. Safran and Curtiss-Wright Corporation sit within the European and North American defense-aerospace crossover tier respectively.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell International Inc. |
| Meggitt PLC |
| CAV Ice Protection |
| Safran |
| Curtiss-Wright Corporation |
| Cox & Company |
| Ultra Electronics |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Electrothermal heating element substitution for pneumatic bleed-air systems redraws supplier geography from Russian and Chinese nickel-chromium smelters toward United States and European carbon nanotube film fabricators, compressing input cost structures while elevating certification-grade thermal performance premiums.
Pricing Analysis
FAA Part 25 Appendix C dictates the pricing tier structure across the aircraft ice protection landscape. Three-tier pricing structure across certification-grade, line-fit standard, and aftermarket economy levels separates OEM-integrated electrothermal systems from retrofit pneumatic alternatives. Cost compression in the aftermarket tier intensifies because low-cost carriers unbundle maintenance from OEM contracts. Regional jet operators exhibit the highest price sensitivity, while narrowbody fleet procurement departments prioritize thermal density compliance over unit cost.
Supply Chain Analysis
Inventory lead times for high-purity nickel-chromium alloys now extend eighteen to twenty-four months due to smelter concentration in Russian and Chinese supply zones. Raw material sourcing draws from nickel ore processing in Indonesia, chromium refining in Kazakhstan, and carbon nanotube synthesis in United States nanotechnology clusters. Single-source vulnerability concentrates in heating element substrate supply. Distribution runs through OEM-captive line-fit channels and independent MRO networks serving retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat where FAA and EASA certification entrenchment creates switching costs that lock airframe OEMs into established supplier relationships.
For Market Incumbents: Secure electrothermal actuator capacity additions in United States and German manufacturing clusters to preempt emerging entrant capacity plays. Deepen backward integration into carbon nanotube film substrate production to offset nickel-chromium alloy price volatility from Russian supply disruption. Certification investment in hybrid-electric propulsion thermal budget integration represents the priority defensive lever against aerospace conglomerate diversification. For New Entrants and Emerging Players: Anchor in Israeli and Japanese unmanned military platform supply chains where lightweight electrothermal actuator demand outpaces incumbent capacity allocation. Independent MRO networks serving United States regional jet retrofit cycles present the most penetrable channel. Pursue FAA-certified icing wind tunnel partnerships as the specific go-to-market angle to compress product validation timelines. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors specialized heating element fabricators with carbon nanotube film capabilities. Long-term viability over the next decade hinges on electrothermal architecture displacement of bleed-air incumbent lock-in. Acquisition targets should exhibit multiphysics simulation talent concentration and existing EASA CS-25 amendment compliance. Watch EASA hybrid-electric certification timeline acceleration as the inflection signal warranting portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Electrothermal Actuator Certification Investment | FAA Part 25 Appendix C compliance unlocks narrowbody line-fit contracts at Boeing and Airbus facilities. |
| Carbon Nanotube Film Backward Integration | Upstream control over heating element substrates insulates margins from nickel-chromium alloy price volatility. |
| Hybrid-Electric Thermal Budget Partnership | Joint development agreements with battery system architects secure positioning in next-generation propulsion architectures. |
| Independent MRO Network Channel Expansion | Power-by-the-hour contracts with low-cost carriers capture unbundled aftermarket service revenue pools. |
| Multiphysics Simulation Talent Acquisition | CFD-thermal-electrical coupled modeling expertise concentrates competitive capability in electrothermal design. |
Methodological Framework
Cross-validation between OEM procurement officer interviews and FAA certification database analysis anchors the qualitative findings in this study. Primary fieldwork engaged avionics integration architects, thermal management engineers, airline fleet planning directors, and independent MRO network operators across United States, France, Germany, and United Kingdom facilities. Secondary validation drew from FAA Part 25 certification filings, EASA CS-25 amendment documentation, EU Green Deal implementation reports, and aerospace supplier SEC disclosures. Bottom-up segment sizing triangulated against top-down fleet renewal program analysis.
Sensitivity analysis across electrothermal adoption rate scenarios and nickel-chromium alloy price volatility bands stress-tested projection robustness. Segmentation dimensions modeled include product type, technology architecture, end-user classification, and installation channel across the projection horizon. CAGRs derived from fleet delivery schedules and retrofit cycle timing. Industry-specific forecast inputs incorporated hybrid-electric propulsion development timelines and supercooled large droplet test infrastructure capacity constraints.
Material uncertainties — regulatory amendment acceleration, raw material supply disruption, hybrid-electric certification timeline compression — sit outside the modeled envelope. Forecasts reflect assumptions documented in fleet renewal program announcements and OEM supplier selection patterns. Revision becomes warranted when EASA hybrid-electric thermal budget allocation thresholds cross predetermined sensitivity bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aircraft Braking System Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Rescue Hoist System Market