
 Global Helicopter Market | 2026-2036
Global Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Helicopter Market Analysis
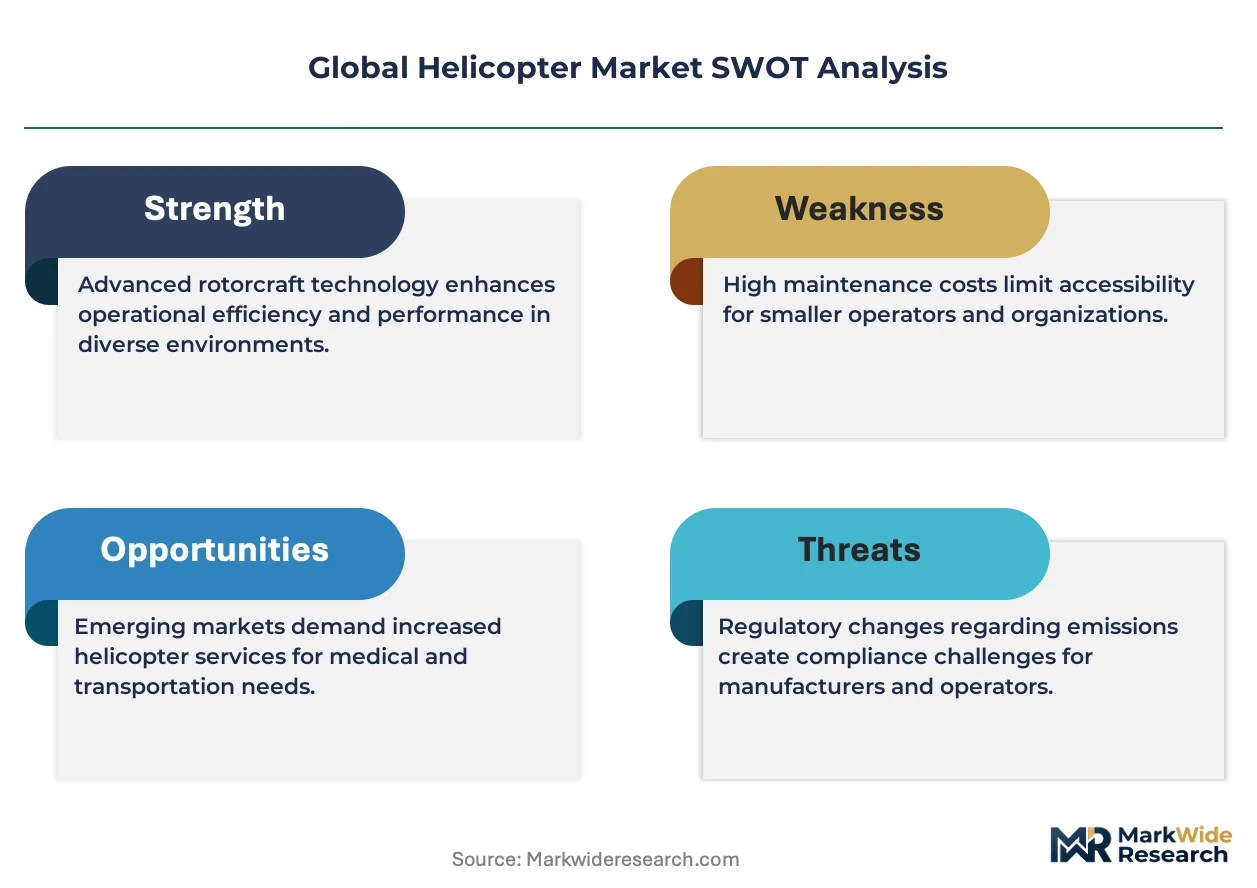
Multi-source avionics procurement is recalibrating how OEMs manage supplier risk across turboshaft and flight-control programs. Airbus Helicopters leverages its European manufacturing footprint to sustain competitive lead times on medium-lift platforms. Sikorsky anchors its position through in-house production of critical transmission systems for heavy-lift military contracts. Leonardo Helicopters differentiates via specialized tiltrotor and naval-optimized configurations that dominate Mediterranean and Asia-Pacific defense tenders.
A helicopter is a powered rotorcraft generating lift and thrust through one or more engine-driven horizontal rotors, with typical turbine powerplants ranging from 500 to 3,000 shaft horsepower and main rotor diameters spanning 8 to 30 meters depending on gross weight class. Its primary industrial purpose spans vertical-lift logistics, personnel transport, and mission-critical operations inaccessible to fixed-wing aircraft. Light helicopters occupy the highest unit-volume tier globally, driven by flight-training economics and private-owner accessibility, while heavy-lift platforms concentrate margin pools in military and offshore energy contracts. Civil end users represent the fastest-expanding demand channel as emergency medical services and corporate shuttle fleets replace aging piston-era fleets with turbine-powered alternatives.
The FAA enforces airworthiness standards under Part 27 and Part 29 certification pathways that dictate structural integrity, crashworthiness, and system redundancy requirements for civil and military rotorcraft entering US airspace. EASA's CS-29 harmonized standards shape European market access, while China's CAAC adopts convergent technical criteria that foreign OEMs must satisfy for domestic delivery eligibility. Military procurement across NATO and Indo-Pacific defense ministries increasingly mandates open-architecture avionics and cybersecurity-hardened data buses, tightening supplier qualification thresholds. Stakeholders must monitor how electric and hybrid propulsion certification frameworks evolve alongside traditional turbine regulations, as airworthiness authorities grapple with battery thermal management and distributed thrust architectures lacking decades of operational precedent.
Market Dynamics
Multi-source avionics procurement is fragmenting supplier relationships across turboshaft and flight-control programs, forcing OEMs to rebuild risk-management frameworks around distributed manufacturing footprints rather than concentrated sourcing.
Growth Catalysts
- Offshore fleet renewal:Oil and gas operators in the North Sea and Gulf of Mexico are replacing aging medium-lift platforms with next-generation rotorcraft featuring enhanced payload-range profiles and reduced fuel consumption.
- FAA Part 135 modernization:Updated operational rules for on-demand air carriers are compressing airworthiness certification timelines and lowering barriers for new entrants in urban air mobility testbeds.
- Turbine substitution:Emergency medical services and corporate shuttle operators are retiring piston-era fleets en masse, channeling replacement demand toward turbine-powered alternatives with improved reliability and dispatch rates.
Market Restraints
- Titanium and nickel alloy volatility:Turboshaft engine castings and transmission housings depend on aerospace-grade alloys whose spot prices swing with mining output from Russia and China, squeezing margin predictability for component suppliers.
- Transmission system concentration:Critical gearbox and drivetrain manufacturing clusters in Germany and Japan create single-point vulnerability for heavy-lift platform deliveries when regional logistics disrupt.
- Battery thermal management gaps:Electric and hybrid propulsion architectures lack decades of operational precedent, leaving airworthiness authorities without validated certification pathways for energy-dense lithium-ion installations.
Strategic Opportunities
- India defense modernization:The country's armed forces are issuing tenders for naval-optimized and medium-lift configurations, creating entry points for foreign OEMs willing to establish local assembly partnerships under offset requirements.
- Urban air mobility infrastructure:Vertiport construction in Dubai, Singapore, and São Paulo is generating demand for electric vertical-lift platforms that bridge traditional helicopter and fixed-wing operational models.
- EU Green Deal aviation incentives:Sustainable aviation fuel mandates and carbon border adjustments are tilting procurement criteria toward rotorcraft with hybrid-electric propulsion and optimized aerodynamic efficiency.
Industry Challenges
- Certification timeline compression:EASA's CS-29 and FAA's Part 29 pathways for new heavy-lift entrants now average 48-60 months, straining R&D amortization schedules and freezing platform development capital for extended periods.
- Avionics cybersecurity hardening:NATO and Indo-Pacific defense ministries now mandate open-architecture data buses with military-grade encryption, forcing suppliers to requalify legacy flight-control software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Helicopter Market |
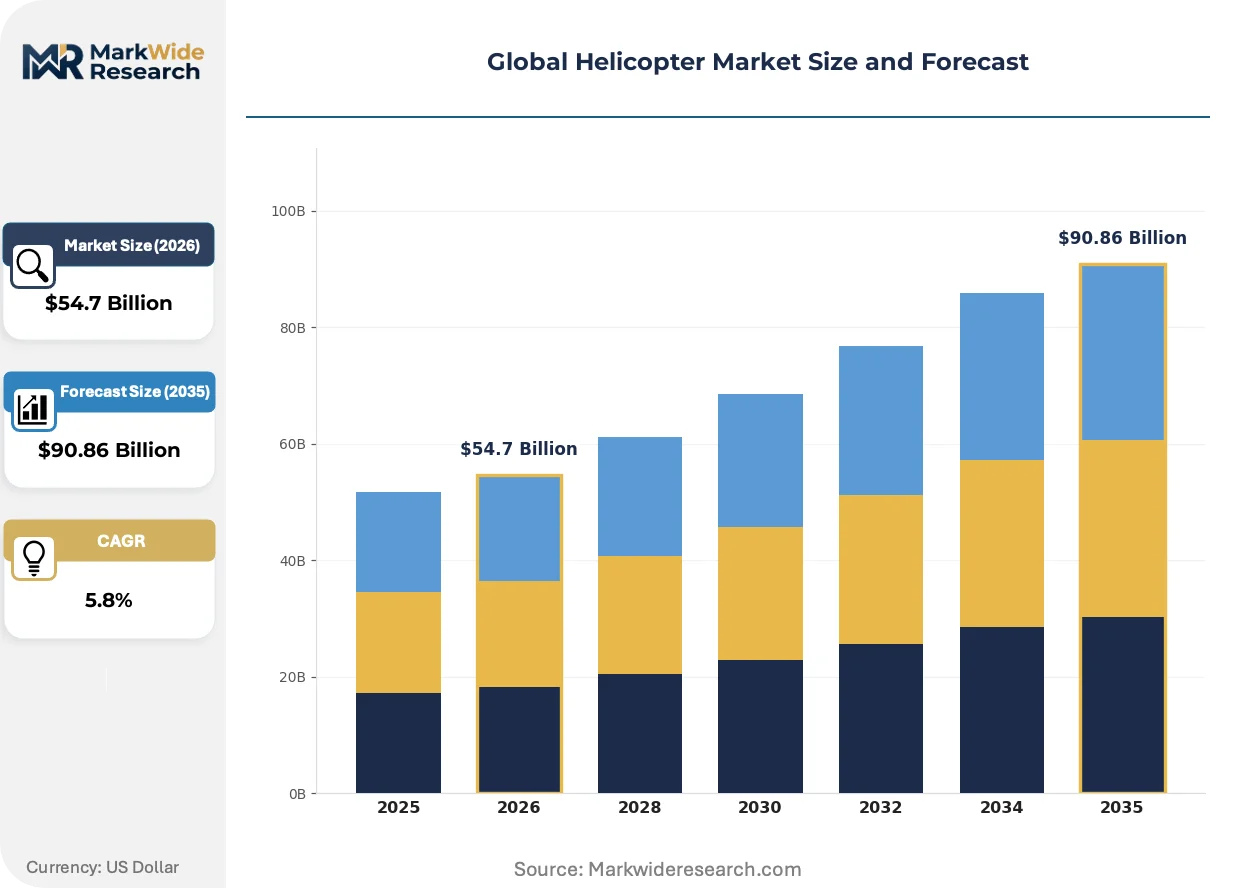
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $90.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Super Heavy Helicopters End User: Military, Civil, Emergency Services, Corporate Application: Transport, Surveillance, Medical Evacuation, Search and Rescue Technology: Electric, Hybrid, Turbine, Rotorcraft |
| Companies Covered | Sikorsky, MD Helicopters, Airbus Helicopters, Lockheed Martin, Robinson Helicopter Company, Bell Flight, Boeing, Enstrom Helicopter Corporation, Leonardo Helicopters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Helicopter Market Emerging Trajectories
Helicopter propulsion and mission systems are undergoing fundamental rearchitecture as battery energy density improvements and distributed thrust concepts challenge the century-old dominance of centralized turboshaft designs.
Hybrid-electric propulsion architectures are rewriting the payload-range economics of light and medium-lift categories. Emergency medical services fleets in Germany and Japan are piloting battery-assisted turbine configurations that reduce fuel burn during hover-intensive phases. This convergence is compressing the total-cost-of-ownership gap between conventional and next-generation platforms.
EASA's evolving CS-29 electric propulsion certification framework is forcing OEMs to submit battery thermal runaway containment protocols alongside traditional structural integrity documentation. The regulatory burden falls heaviest on tiltrotor and heavy-lift segments where energy storage mass competes directly with payload capacity. Manufacturers are responding by front-loading safety-case development and pre-negotiating special conditions with national authorities.
Corporate and government fleet operators are unbundling airframe procurement from long-term maintenance contracts, treating availability-based service agreements as distinct competitive variables. This split is displacing the traditional bundled-sales model in North Sea offshore transport and Mediterranean search-and-rescue tenders. Saudi Arabia's state aviation entities have pioneered this separation, forcing OEMs to price lifecycle support independently of initial platform delivery.
Global Helicopter Market Segmentation
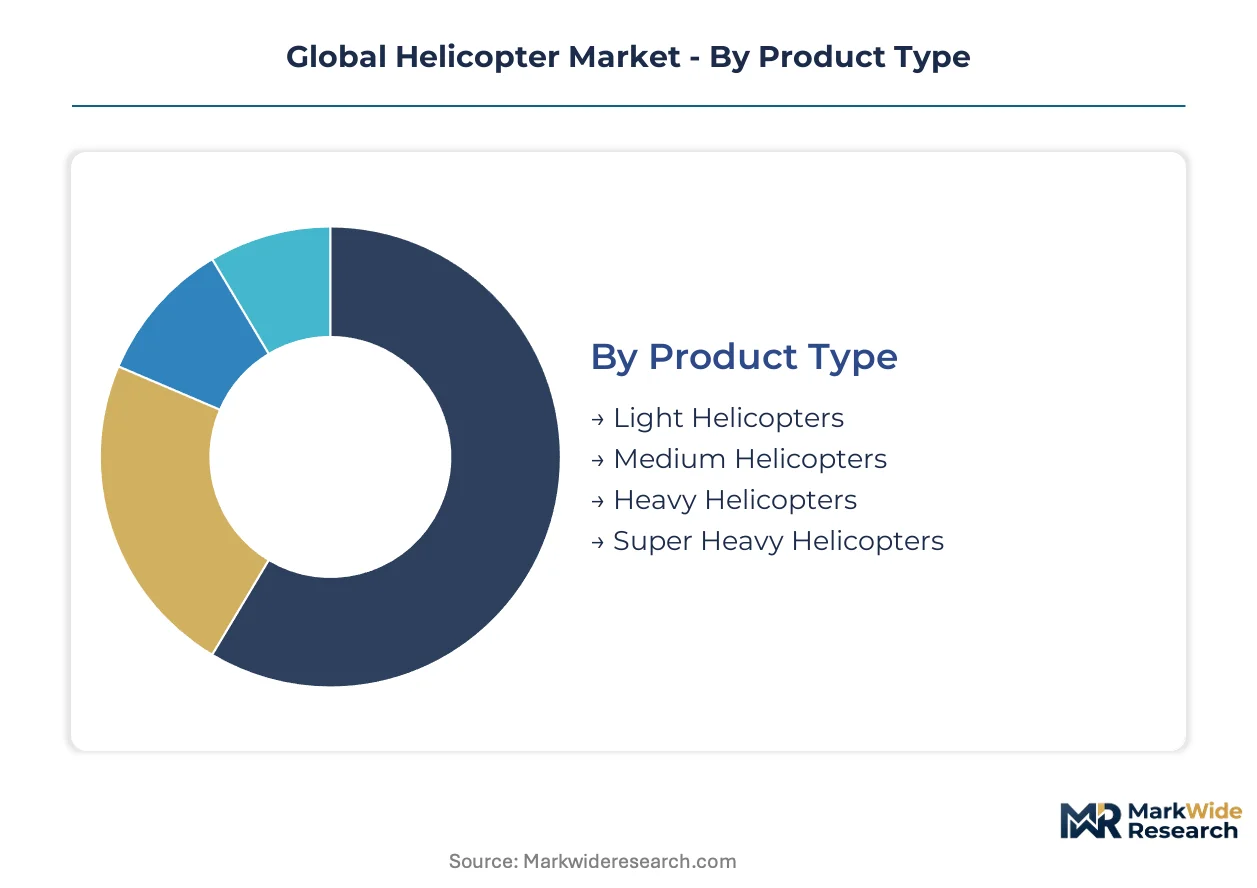
Helicopter market segmentation reveals how payload capacity, mission profile, and propulsion architecture create distinct competitive arenas with divergent margin structures and supplier qualification thresholds. Understanding these boundaries clarifies where capital deployment concentrates and which technology transitions threaten incumbent positions.
Product Type:
Payload capacity and rotor system complexity define four tiers with radically different manufacturing economics and customer procurement patterns.
- Light Helicopters:Single or twin-engine platforms under 3,175 kg maximum takeoff weight dominate flight-training economics and private-owner accessibility. Demand concentrates in the United States and Australia where Part 141 flight schools and agricultural spraying operators replace aging piston-era fleets with turbine-powered alternatives.
- Medium Helicopters:Multi-engine configurations between 3,175 kg and 5,700 kg MTOW anchor offshore oil and gas logistics and corporate shuttle services. North Sea and Gulf of Mexico operators are renewing aging fleets with next-generation rotorcraft featuring enhanced payload-range profiles and reduced fuel consumption.
- Heavy Helicopters:Platforms exceeding 5,700 kg MTOW with three or more engines concentrate in military assault and external-lift construction missions. Germany and Japan maintain critical gearbox and drivetrain manufacturing clusters that create single-point vulnerability for platform deliveries.
- Super Heavy Helicopters:Specialized configurations above 9,000 kg MTOW including tandem rotor and coaxial designs serve military heavy-lift and firefighting tanker roles. Russian and Chinese mining output volatility for titanium and nickel alloys squeezes margin predictability for transmission housing suppliers.
Light Helicopters leads on scale; Medium Helicopters leads on momentum.
End User:
Procurement authority and funding source create four customer classes with divergent contract structures and lifecycle service expectations.
- Military:Defense ministry tenders mandate open-architecture avionics and cybersecurity-hardened data buses with extended operational readiness requirements. NATO and Indo-Pacific procurement offices increasingly require local assembly partnerships under offset requirements.
- Civil:Commercial operators including tourism, agriculture, and private aviation represent the fastest-expanding demand channel as turbine substitution accelerates. Emergency medical services and corporate shuttle fleets in Germany and Japan are piloting battery-assisted configurations.
- Emergency Services:Government-funded search-and-rescue and medical evacuation operations require IFR-certified platforms with specialized mission equipment. Mediterranean and Asia-Pacific defense tenders increasingly specify naval-optimized configurations.
- Corporate:High-net-worth individuals and executive transport departments prioritize cabin configuration flexibility and dispatch reliability over absolute payload performance. Saudi Arabia's state aviation entities have pioneered availability-based service agreements that displace traditional bundled-sales models.
Military dominates contract value; Civil climbs the fastest.
Application:
Mission-criticality and regulatory exposure shape four operational domains with distinct airworthiness certification pathways and insurance cost structures.
- Transport:Personnel and cargo movement across vertical-lift logistics networks including offshore energy platforms and urban air mobility corridors. Vertiport construction in Dubai, Singapore, and São Paulo is generating demand for electric vertical-lift platforms.
- Surveillance:Law enforcement, border patrol, and military reconnaissance missions requiring stabilized sensor payloads and extended loiter endurance. FAA Part 135 modernization is compressing airworthiness certification timelines for new entrants in urban air mobility testbeds.
- Medical Evacuation:Time-critical patient transport with specialized life-support equipment and rapid loading configurations. EASA's CS-29 and FAA's Part 29 pathways for new heavy-lift entrants now average 48-60 months, straining R&D amortization schedules.
- Search and Rescue:All-weather extraction operations demanding autorotation capability, rescue hoists, and maritime survival equipment. EU Green Deal aviation incentives are tilting procurement criteria toward hybrid-electric propulsion and optimized aerodynamic efficiency.
Transport anchors volume; Medical Evacuation shows steepest expansion trajectory.
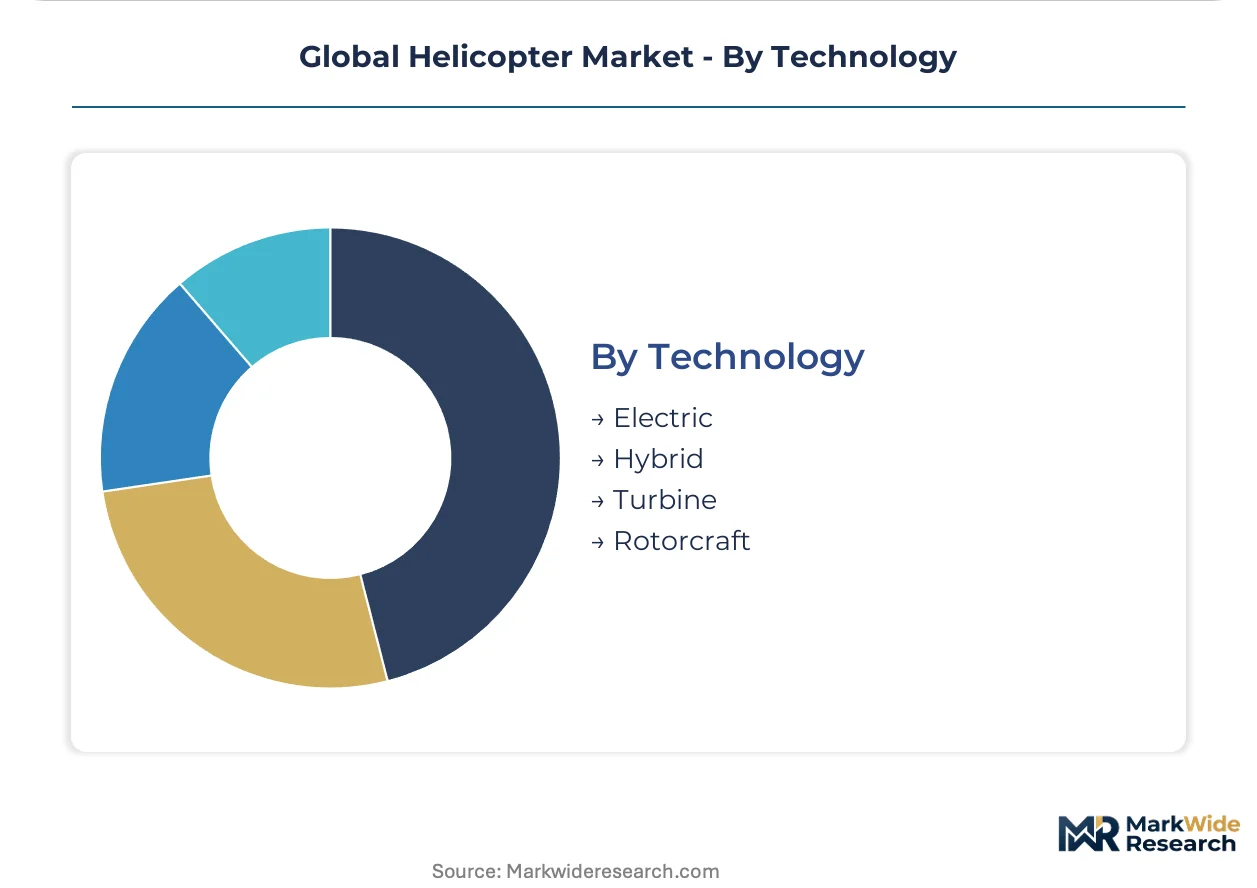
Technology:
Propulsion architecture and energy storage define four technological trajectories with divergent certification maturity and supply chain concentration.
- Electric:Battery-powered distributed thrust systems with zero direct emissions and reduced acoustic signature. EASA's evolving CS-29 electric propulsion certification framework forces OEMs to submit battery thermal runaway containment protocols alongside traditional structural integrity documentation.
- Hybrid:Battery-assisted turbine configurations that reduce fuel burn during hover-intensive phases and enable emergency landing capability. Emergency medical services fleets in Germany and Japan are piloting these architectures to compress total-cost-of-ownership gaps.
- Turbine:Conventional turboshaft powerplants with decades of operational precedent and established maintenance infrastructure. Oil and gas operators in the North Sea and Gulf of Mexico are replacing aging medium-lift platforms with next-generation rotorcraft featuring enhanced payload-range profiles.
- Rotorcraft:Traditional mechanical rotor systems including articulated, semi-rigid, and rigid hub configurations with proven autorotation safety margins. Tiltrotor and heavy-lift segments face regulatory burden heaviest where energy storage mass competes directly with payload capacity.
Turbine maintains installed base dominance; Hybrid gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American rotorcraft manufacturing with concentrated final assembly lines and specialized transmission component fabrication serving both military and civil demand channels.
United States
Military modernization programs and urban air mobility testbeds absorb disproportionate unit volume across Army, Navy, and commercial operator fleets. FAA Part 135 operational rule updates compress airworthiness certification timelines for new on-demand air carriers. The Gulf Coast corridor from Houston to New Orleans concentrates offshore oil and gas fleet renewal activity with next-generation medium-lift platform deliveries.
Germany
Critical gearbox and drivetrain manufacturing clusters create single-point vulnerability for heavy-lift platform deliveries across European defense tenders. EASA CS-29 harmonized standards shape market access requirements for civil and military rotorcraft entering European airspace. Bavaria hosts specialized transmission housing suppliers dependent on aerospace-grade titanium and nickel alloy supply chains.
India
Armed forces tenders for naval-optimized and medium-lift configurations create entry points for foreign OEMs establishing local assembly partnerships. Ministry of Defence offset requirements mandate indigenous component sourcing and technology transfer for contract eligibility. Bengaluru and Hyderabad clusters concentrate aerospace manufacturing infrastructure with growing rotorcraft subsystem capabilities.
Japan
Emergency medical services fleets pilot battery-assisted turbine configurations to reduce fuel burn during hover-intensive phases. METI industrial policy supports hybrid-electric propulsion development through targeted R&D subsidies and certification facilitation. Nagoya aerospace corridor maintains precision manufacturing capabilities for flight-control systems and avionics integration.
Saudi Arabia
State aviation entities pioneer availability-based service agreements that displace traditional bundled-sales models for corporate and government fleet operators. General Authority of Civil Aviation regulations align with EASA technical criteria for foreign OEM delivery eligibility. Riyadh and Eastern Province clusters concentrate vertiport infrastructure investment for urban air mobility corridor development.
Global Helicopter Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electric propulsion and urban air mobility specializations outside traditional turboshaft dominance. The vendor base stratifies across integrated platform manufacturers, subsystem specialists, and regional assembly partners. Three archetypes predominate: legacy defense contractors with captive military pipelines, European civil-specialist OEMs leveraging manufacturing footprint advantages, and diversified aerospace conglomerates with cross-program technology leverage. Competitive intensity concentrates in M&A activity for transmission and avionics capabilities, alongside strategic partnerships for electric propulsion certification.
Among legacy defense-anchored producers, Sikorsky and Lockheed Martin exemplify integrated military platform development with in-house critical system production. Leonardo Helicopters represents the European specialist archetype with tiltrotor and naval-optimized configuration focus. Airbus Helicopters anchors the diversified conglomerate tier with cross-continental manufacturing footprint and medium-lift platform breadth.
| Leading Market Players |
|---|
| Sikorsky |
| MD Helicopters |
| Airbus Helicopters |
| Lockheed Martin |
| Robinson Helicopter Company |
| Bell Flight |
| Boeing |
| Enstrom Helicopter Corporation |
| Leonardo Helicopters |
| Others |
Supply Flow & Price Mechanics
Aerospace-grade titanium and nickel alloy spot price indices cascade through transmission housing and turboshaft casting supply chains, compressing margins for German and Japanese component suppliers while forcing OEMs to renegotiate long-term offtake terms with North Sea and Gulf of Mexico operators.
Pricing Analysis
Input-cost pass-through from volatile alloy markets is intensifying margin pressure across heavy-lift and super-heavy platform tiers. Three-tier pricing structure across premium, standard, and economy levels separates FAA Part 29-certified military configurations from civil utility models and flight-training piston replacements. Cost compression in medium-lift offshore segments reflects fleet renewal volume concentration and bundled availability-based service agreements. Corporate shuttle operators exhibit lowest price sensitivity due to dispatch reliability premiums; agricultural spraying contractors face acute pressure from fuel burn economics and turbine substitution capex cycles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale military and offshore energy buyer demand, while specialized distributors serve fragmented civil and training fleet operators. Manufacturing gravity centers on Germany, Japan, and the United States for critical gearbox, drivetrain, and flight-control fabrication. Component sourcing draws from Russian and Chinese mining output for titanium and nickel alloys, alongside precision forging capabilities in Bavaria and Nagoya. Single-source vulnerability in transmission system clusters creates delivery risk when regional logistics disrupt. Distribution runs through captive OEM service networks for heavy-lift platforms and independent MRO channels for light helicopter aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Helicopter Market compounds steadily as military modernization programs and urban air mobility infrastructure buildouts sustain replacement demand across multiple decades.
For Market Incumbents: Extend platform lifecycle value through in-house production of critical transmission systems and battery thermal management certification pre-negotiation with EASA. Sikorsky anchors heavy-lift positioning via captive gearbox manufacturing; Airbus Helicopters leverages cross-continental footprint to compress medium-lift lead times. Electric propulsion entrants threaten turbine aftermarket revenue pools.
For New Entrants and Emerging Players: Enter via urban air mobility corridor development in Dubai, Singapore, and São Paulo where vertiport infrastructure precedes fleet procurement decisions. Battery-assisted turbine configurations for emergency medical services in Germany and Japan represent the most penetrable white space. Pursue availability-based service agreements that displace traditional bundled-sales models.
For Investors and Strategic Acquirers: Asymmetric upside sits with subsystem specialists holding certification-qualified transmission or open-architecture avionics capabilities. Long-term viability favors suppliers with military-grade cybersecurity hardening and hybrid-electric propulsion R&D pipelines. Watch battery energy density improvements as the inflection signal for electric platform economic viability against conventional turboshaft benchmarks.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | India's Ministry of Defence offset requirements mandate indigenous sourcing for contract eligibility. |
| Battery Thermal Management Certification | EASA CS-29 electric propulsion frameworks demand pre-submitted containment protocols for platform approval. |
| Availability-Based Service Agreement | Saudi Arabia's state aviation entities pioneered this model, separating airframe procurement from lifecycle support. |
| Hybrid-Electric Propulsion Development | EU Green Deal aviation incentives tilt procurement toward optimized aerodynamic efficiency and SAF compatibility. |
| Open-Architecture Avionics Integration | NATO and Indo-Pacific defense ministries mandate military-grade encryption and cybersecurity-hardened data buses. |
Methodological Framework
Direct dialogue with helicopter OEM program managers, turboshaft engine procurement leads, offshore energy fleet operators, FAA certification specialists, and EASA airworthiness authorities grounded qualitative assessments in operational reality. Secondary validation drew from FAA Part 27 and Part 29 certification databases, EASA CS-29 regulatory filings, customs trade records for aerospace alloy imports, and defense ministry tender documentation across NATO and Indo-Pacific jurisdictions. Bottom-up platform delivery forecasts triangulated against top-down military budget appropriations and civil operator fleet renewal schedules.
Bottom-up unit economics modeled payload capacity tiers, propulsion architecture transitions, and regional regulatory clusters across the projection horizon. Segmentation dimensions included product type, end user procurement authority, mission application, and technology maturity. CAGRs derived from installed base age profiles, replacement cycle timing, and emerging demand channel penetration rates. Forecast inputs incorporated battery energy density improvement curves, sustainable aviation fuel mandate compliance costs, and vertiport infrastructure buildout timelines.
Inputs from defense ministry procurement databases and civil operator fleet registries were available through the study window; gaps in electric propulsion operational precedent introduce uncertainty bands around certification timeline assumptions. Periodic stress-testing of base assumptions against alloy price volatility, regulatory framework evolution, and battery safety case validation progress is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
North America General Aviation Market
Aircraft
Military Rotorcraft Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Aircraft Jack Market
Aircraft
Aircraft Door Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
America Attack Helicopter Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Aircraft Sequencing System Market
Aircraft
GCC General Aviation Market
Aircraft
Europe Aviation Market