
 Aircraft Oxygen System Market | 2026-2036
Aircraft Oxygen System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Oxygen System Market Analysis
North American manufacturing capacity for aviation safety equipment is reshaping competitive dynamics in the aircraft oxygen system supply base. Collins Aerospace leverages in-house production of compressed gas regulators to sustain its position across commercial and military programs. Cobham Limited anchors European supply chains through specialized cryogenic system fabrication for fighter and transport platforms. Technodinamika competes on state-backed scale in chemical oxygen generator output for Russian and export military fleets.
An aircraft oxygen system encompasses the generators, storage vessels, regulators, masks, and distribution plumbing that deliver breathable gas to crew and passengers during decompression events or smoke-filled cabin conditions. These systems operate at altitudes up to 45,000 feet using compressed gas, chemical reaction, or cryogenic liquid sources, with flow controlled by demand regulators that conserve supply while maintaining physiologically adequate partial pressure. Compressed gas systems dominate commercial retrofit activity due to their serviceability and predictable lifecycle costs, while chemical oxygen generators retain share in narrowbody forward galley and lavatory installations where weight minimization governs specification. Electronic oxygen delivery represents the fastest-growing technology segment as digital pulse-dosing algorithms reduce onboard oxygen inventory requirements and extend mission endurance for military platforms.
FAA Technical Standard Orders and EASA Certification Specifications define minimum performance benchmarks for oxygen equipment installed on civil aircraft registered in the United States and European Union member states. Military standards including MIL-PRF and DEF STAN frameworks govern combat platform survivability requirements, creating parallel procurement channels with distinct qualification protocols. ISO 7317 and related material specifications further harmonize component-level testing across global supplier bases. Stakeholders must monitor evolving CS-25 amendments addressing post-crash fire toxicity limits for chemical generator formulations, as regulatory shifts in this domain could force accelerated replacement timelines and redirect R&D investment toward solid-fuel alternatives or advanced compressed gas architectures.
Market Dynamics
Fleet renewal cycles across Southeast Asian commercial aviation are compressing replacement timelines for chemical oxygen generators, while FAA and EASA mandates for enhanced passenger safety systems tighten certification requirements for fixed installations.
Growth Catalysts
- FAA Technical Standard Orders:Mandates for enhanced passenger safety systems drive retrofit demand across legacy narrowbody fleets in the United States.
- Chemical oxygen generator replacement:Southeast Asian commercial aviation expansion accelerates decommissioning cycles for aging forward galley installations.
- Cryogenic liquid systems:Military transport and fighter platforms in Europe require specialized fabrication capacity for extended mission endurance.
Market Restraints
- Helium supply concentration:Cryogenic system production depends on concentrated rare gas sourcing from limited geographic suppliers.
- CS-25 amendment uncertainty:Pending toxicity limit revisions for chemical generator formulations create certification timeline friction for manufacturers.
- Solid-fuel substitution gap:Advanced compressed gas architectures face weight penalties against legacy chemical systems in lavatory applications.
Strategic Opportunities
- Electronic pulse-dosing convergence:Digital algorithms combined with demand regulators reduce inventory requirements for military mission planning.
- Indian narrowbody deliveries:Expanding commercial fleet procurement creates specification windows for portable oxygen system suppliers.
- ISO 7317 harmonization:Global material testing standards enable component-level supplier qualification across multiple airworthiness jurisdictions.
Industry Challenges
- Cryogenic welder certification scarcity:Specialized fabrication skills for liquid oxygen vessels concentrate in European defense supply chains.
- Dual MIL-PRF and DEF STAN qualification:Military platforms require parallel certification protocols that extend development timelines.
- Legacy 45,000-foot system integration:New electronic delivery architectures must interface with existing distribution plumbing without full airframe modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Oxygen System Market |
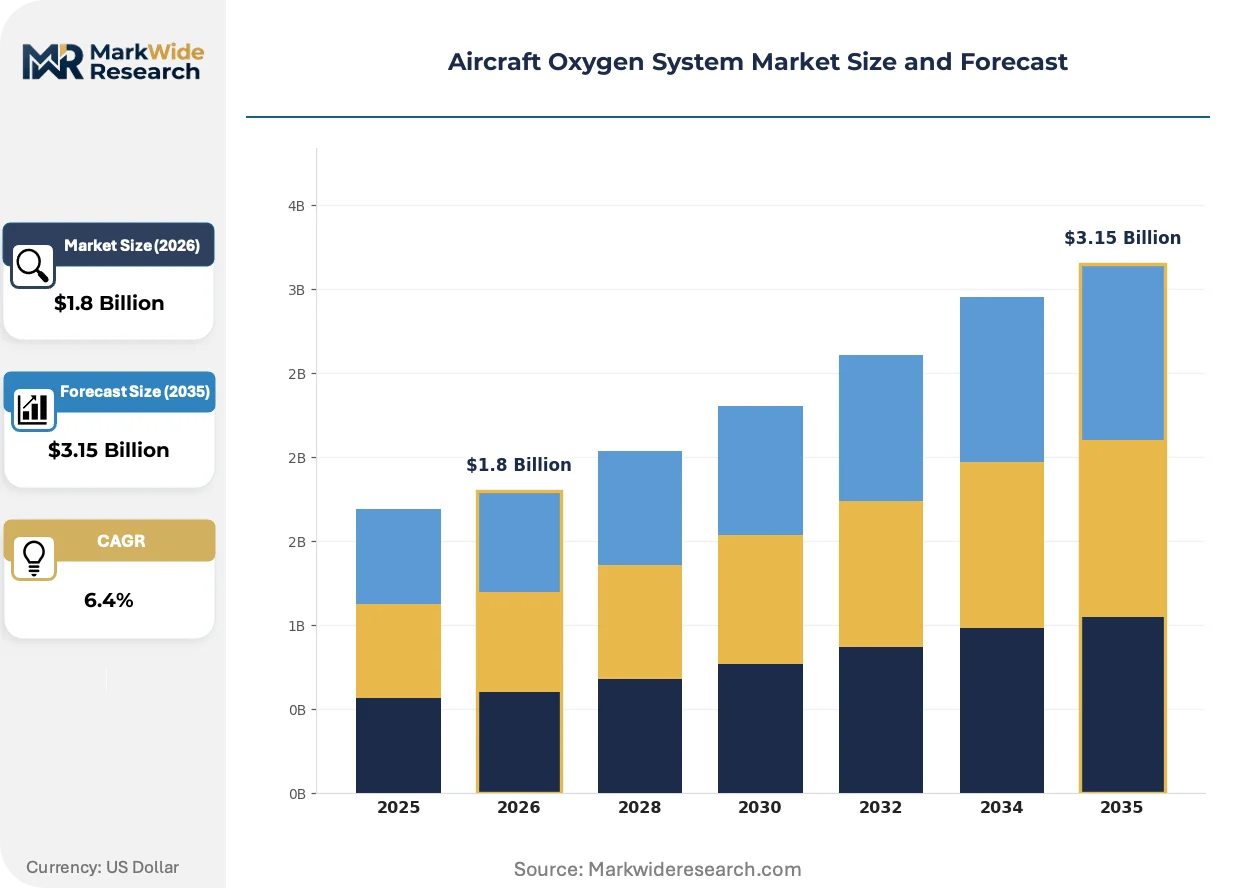
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Flow, Demand Oxygen, Portable Systems, Fixed Systems End User: Commercial Aviation, Military Aviation, Private Aviation, Maintenance Providers Technology: Cryogenic Systems, Chemical Oxygen Generators, Compressed Gas Systems, Electronic Oxygen Delivery Certification: FAA Approved, EASA Certified, ISO Compliant, Military Standards |
| Companies Covered | Collins Aerospace, Cobham Limited, Adams Rite Aerospace Inc., Essex Industries, Inc., East/West Industries, Inc., Zodiac Aerospace, Technodinamika, BAE Systems, Aerox Aviation Oxygen Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Oxygen System Market Emerging Trajectories
Digital oxygen delivery architectures are compressing inventory requirements while regulatory pressure on chemical generator toxicity reshapes formulation R&D priorities across civil and military procurement channels.
Pulse-dosing electronic regulators are virtualizing traditional continuous-flow architectures by algorithmically metering oxygen delivery to match physiological demand rather than maintaining constant output. Military platform integrators in the United States and Europe are specifying these systems for new transport and fighter programs where mission endurance extension outweighs acquisition cost premiums. This virtualization is compressing onboard storage requirements and enabling platform designers to reallocate weight budgets toward fuel or payload.
EASA Certification Specification amendments addressing post-crash fire toxicity limits are forcing accelerated evaluation of solid-fuel alternatives to traditional chlorate-based chemical generators. Manufacturers serving European-registered commercial fleets must reformulate or redesign forward galley and lavatory installations before compliance deadlines take effect. The segment most affected is narrowbody retrofit programs, where operators are delaying specification decisions until regulatory clarity emerges.
Airline procurement departments are unbundling aftermarket service contracts from initial system purchases, separating mask replacement and regulator overhaul from original equipment awards. Maintenance, repair, and overhaul providers in Singapore and Dubai are capturing these disaggregated service streams through localized stocking and faster turnaround commitments. This pattern is most visible in Southeast Asian low-cost carrier fleets where operational uptime metrics dominate vendor selection criteria.
Aircraft Oxygen System Market Segmentation
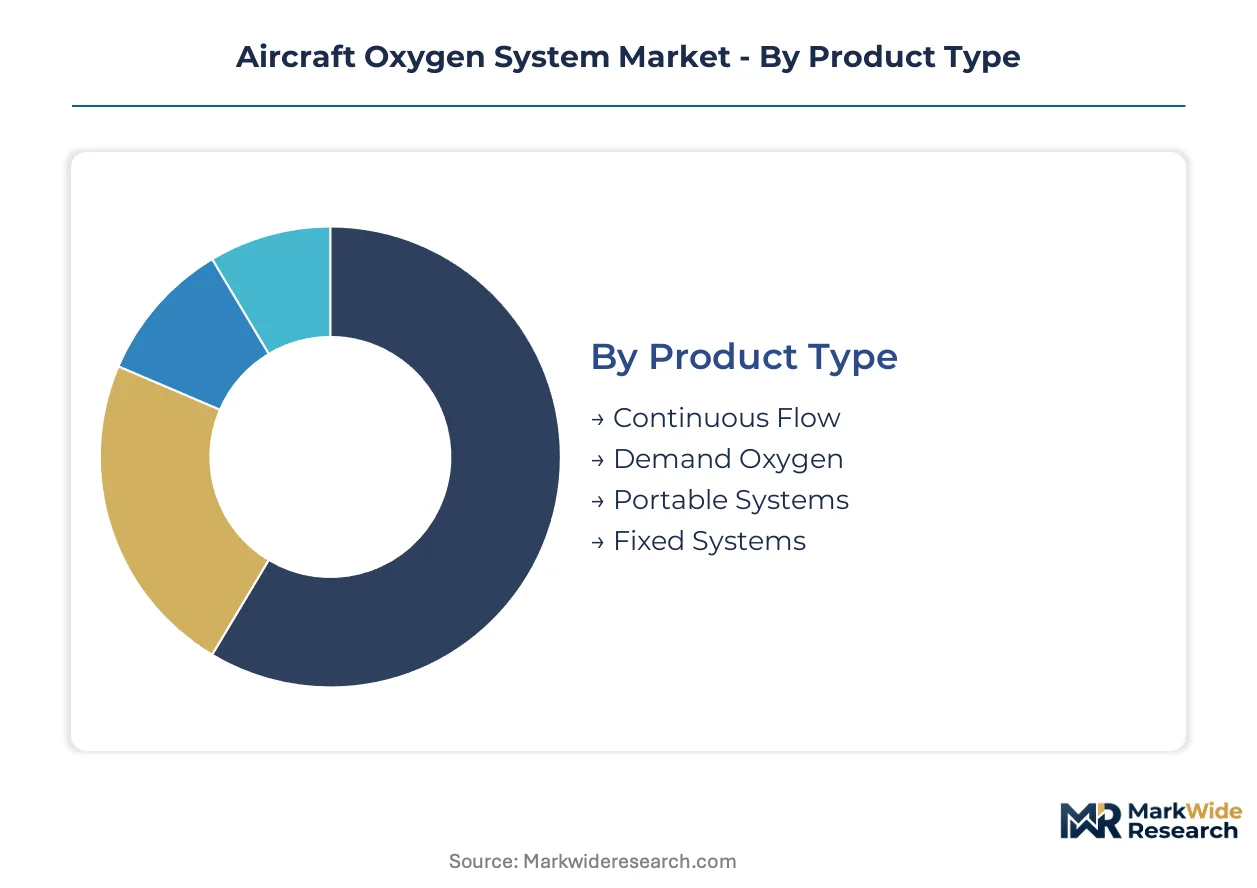
Oxygen system architectures vary sharply in lifecycle cost profiles and aftermarket attachment rates. Segmentation reveals which configurations generate recurring revenue through mask replacement and regulator overhaul versus one-time equipment sales.
Product Type:
Aftermarket service intensity diverges dramatically across flow architectures, with continuous-flow systems requiring scheduled component replacement while portable units concentrate wear-item demand in inspection intervals.
- Continuous Flow:These systems deliver uninterrupted oxygen streams through fixed plumbing networks at calibrated pressure rates. Commercial narrowbody retrofits in the United States drive replacement demand as FAA Technical Standard Orders tighten flow-rate tolerances for aging installations.
- Demand Oxygen:Demand regulators meter oxygen delivery through inhalation-triggered valves that conserve supply during decompression events. Military transport platforms in Europe specify these systems for extended mission endurance where inventory weight reduction outweighs acquisition premiums.
- Portable Systems:Self-contained units deploy for cabin crew mobility and emergency medical response.
- Fixed Systems:Permanent installations integrate with aircraft distribution plumbing and passenger service units.
Fixed systems hold the largest share; momentum sits with demand oxygen as pulse-dosing algorithms gain specification.
End User:
Procurement patterns split between fleet operators seeking total cost of ownership reductions and military integrators prioritizing mission performance over lifecycle economics.
- Commercial Aviation:Airlines specify oxygen systems during new narrowbody deliveries and mid-life cabin reconfigurations. Southeast Asian low-cost carriers compress replacement cycles for chemical generators as fleet expansion accelerates decommissioning timelines.
- Military Aviation:Combat platforms require cryogenic and electronic delivery systems certified to MIL-PRF and DEF STAN frameworks. Fighter programs in Europe demand specialized fabrication capacity for liquid oxygen vessels that extend operational endurance.
- Private Aviation:Business jet operators favor portable and compressed gas configurations for flexibility.
- Maintenance Providers:MRO facilities in Singapore and Dubai capture disaggregated service contracts through localized stocking and faster turnaround commitments.
Commercial aviation dominates procurement volume; military aviation climbs fastest as electronic delivery architectures displace legacy chemical systems.
Technology:
Weight-performance tradeoffs govern technology selection, with cryogenic systems offering density advantages against compressed gas serviceability and chemical generator simplicity.
- Cryogenic Systems:Liquid oxygen storage achieves the highest mass efficiency for extended-duration missions. European fighter and transport platforms require specialized welder certification that concentrates fabrication capacity in defense supply chains.
- Chemical Oxygen Generators:Solid-fuel reactions produce oxygen through thermal decomposition without pressurized storage. Narrowbody forward galley and lavatory installations retain these systems where weight minimization governs specification, though EASA toxicity amendments threaten formulation compliance.
- Compressed Gas Systems:Cylindrical storage with demand regulators dominates commercial retrofit activity.
- Electronic Oxygen Delivery:Digital pulse-dosing algorithms meter delivery to physiological demand.
Chemical generators retain installed base dominance; electronic oxygen delivery represents the fastest-growing technology segment as inventory reduction drives military specification.
Certification:
Regulatory jurisdiction determines qualification protocols, with civil and military channels operating parallel certification frameworks that extend development timelines for dual-use suppliers.
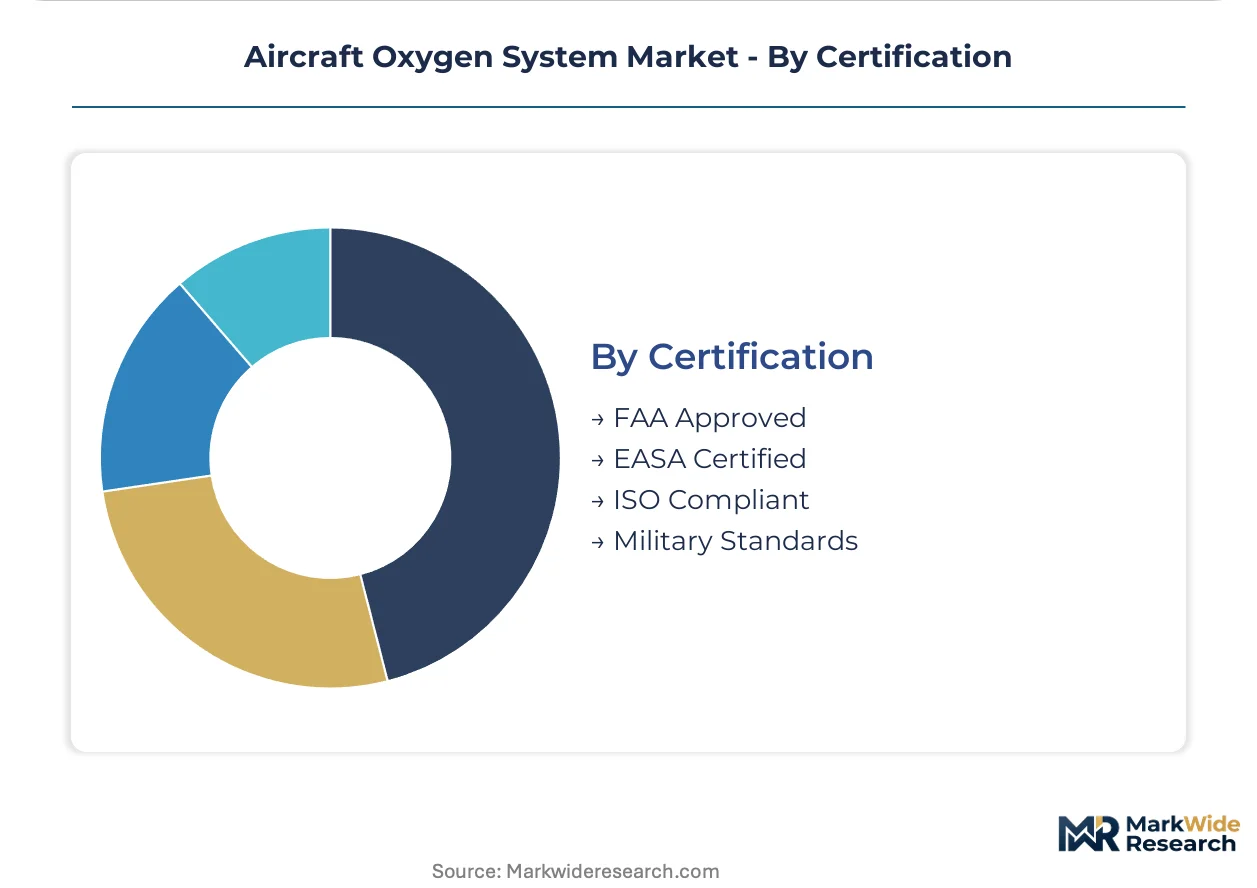
- FAA Approved:Technical Standard Orders define minimum performance benchmarks for oxygen equipment installed on United States-registered civil aircraft. Legacy fleet retrofit programs sustain procurement volumes as mandates for enhanced passenger safety systems tighten flow-rate and mask-performance requirements.
- EASA Certified:Certification Specifications govern European Union member state registrations. Pending CS-25 amendments addressing post-crash fire toxicity limits create certification timeline friction for chemical generator manufacturers serving European-registered fleets.
- ISO Compliant:ISO 7317 and related material specifications harmonize component-level testing across global supplier bases.
- Military Standards:MIL-PRF and DEF STAN frameworks establish combat platform survivability requirements.
FAA approval covers the broadest installed base; EASA certification faces the steepest regulatory revision uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Technical Standard Orders anchor procurement volumes in the United States, where legacy fleet retrofit programs and new narrowbody deliveries sustain demand for portable and fixed oxygen systems across commercial and military channels.
United States
Commercial narrowbody retrofits and military transport programs drive specification demand. FAA mandates for enhanced passenger safety systems tighten flow-rate tolerances for aging installations. Wichita's aviation cluster concentrates fabrication capacity for compressed gas regulators serving both civil and defense supply chains.
France
Fighter platform upgrades and commercial aftermarket services sustain procurement activity. EASA Certification Specifications govern equipment performance benchmarks for European-registered fleets. Toulouse's aerospace corridor hosts specialized suppliers addressing narrowbody forward galley installation requirements.
Germany
Cryogenic liquid system fabrication for military transport platforms anchors defense procurement. DEF STAN frameworks establish parallel qualification protocols alongside civil certification. Bavaria's precision engineering base concentrates welder certification capacity for liquid oxygen vessel production.
United Kingdom
Combat aircraft modernization programs and legacy fleet sustainment drive electronic delivery system adoption. Military standards including DEF STAN govern survivability requirements distinct from civil frameworks. Southwest England's defense supply chain clusters fabrication expertise for extended-mission endurance systems.
Singapore
Low-cost carrier fleet expansion accelerates chemical oxygen generator replacement cycles. The Civil Aviation Authority of Singapore enforces airworthiness standards aligned with FAA and EASA benchmarks. Changi's MRO hub captures disaggregated aftermarket service contracts through localized stocking and faster turnaround commitments.
Aircraft Oxygen System Market Vendor Landscape
Diversified aerospace conglomerates and specialized safety equipment fabricators split the market across distinct capability tiers. Consolidation concentrates around vertically integrated suppliers controlling regulator design and compressed gas storage fabrication. Three archetypes dominate: full-system integrators with in-house component production, specialized cryogenic fabricators serving defense platforms, and regional suppliers competing on aftermarket service proximity. Competitive moves center on backward integration into critical component manufacturing and geographic expansion toward Southeast Asian MRO clusters.
Among diversified system integrators, Collins Aerospace exemplifies the full-capability archetype through its integrated regulator and distribution portfolio. Cobham Limited occupies a position within the specialized defense tier, anchoring European cryogenic supply chains through liquid oxygen vessel fabrication. Technodinamika represents state-backed scale production, sitting within the regional champion archetype serving military export markets.
| Leading Market Players |
|---|
| Collins Aerospace |
| Cobham Limited |
| Adams Rite Aerospace Inc. |
| Essex Industries, Inc. |
| East/West Industries, Inc. |
| Zodiac Aerospace |
| Technodinamika |
| BAE Systems |
| Aerox Aviation Oxygen Systems |
| Others |
Supply Flow & Price Mechanics
Wichita's aviation manufacturing cluster concentrates compressed gas regulator fabrication capacity, translating into downstream pricing leverage for full-system integrators serving FAA-mandated retrofit programs. This geographic concentration of specialized welding and precision machining capabilities creates cost asymmetries between integrated suppliers and component-dependent competitors bidding on narrowbody replacement contracts.
Pricing Analysis
North American-European price spreads of 15-25% persist for cryogenic liquid oxygen vessels, reflecting Bavaria's concentrated welder certification capacity and associated skill premiums. Three-tier pricing structure across FAA-certified, EASA-certified, and dual-qualified equipment levels captures certification investment differentials. Cost compression in portable system segments is intensifying because Singapore-based MRO providers are unbundling aftermarket service contracts from initial equipment sales. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while European defense integrators prioritize mission endurance over acquisition cost.
Supply Chain Analysis
Extended payment terms of 90-120 days from major OEMs strain working capital for specialized component suppliers, particularly those serving dual MIL-PRF and DEF STAN qualification requirements. Fabrication capacity concentrates in the United States, Germany, and France, with raw material dependencies on aerospace-grade aluminum alloys, chlorate-based chemical formulations, and rare gas helium sourcing. Single-source vulnerability runs through concentrated helium supply from Qatar and Algeria. Distribution runs through authorized distributor networks for civil aviation and direct military procurement channels for defense platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as electronic pulse-dosing architectures displace legacy chemical systems across military transport and fighter programs. FAA and EASA regulatory tailwinds for enhanced passenger safety systems are accelerating replacement timelines that extend procurement visibility.
For Market Incumbents: Insulate installed base positions through backward integration into demand regulator production and captive supply of compressed gas cylinder fabrication. Collins Aerospace exemplifies this model through in-house regulator manufacturing. EASA CS-25 toxicity amendments threaten chemical generator formulations; incumbents should accelerate solid-fuel R&D investment to preempt compliance-driven specification losses. Channel control through localized MRO stocking agreements in Singapore and Dubai reinforces aftermarket attachment rates. For New Entrants and Emerging Players: Pursue white-space opportunities in electronic oxygen delivery system component supply, specifically digital pulse-dosing algorithm modules and lightweight storage vessel fabrication for unmanned platforms. Indian narrowbody delivery schedules create specification windows for portable system suppliers without legacy installed base conflicts. Go-to-market positioning through ISO 7317 component-level qualification enables multi-jurisdiction supplier approval without full airframe certification burden. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cryogenic fabricators with DEF STAN qualification and European defense platform relationships. Long-term viability hinges on military mission endurance requirements and civil aviation fleet renewal cycles. Acquisition targets should demonstrate welder certification depth and liquid oxygen vessel production capacity. The inflection signal to watch is EASA regulatory clarity on chemical generator toxicity limits, which would force accelerated replacement timelines and redirect R&D capital toward electronic delivery architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regulator Manufacturing | Captures margin from precision machining and reduces dependency on Wichita-cluster suppliers for FAA-certified flow control. |
| EASA Pre-Certification Investment | Positions suppliers ahead of CS-25 toxicity amendments for European narrowbody retrofit specification windows. |
| MRO Hub Localization | Singapore and Dubai stocking commitments capture disaggregated aftermarket service contracts from low-cost carriers. |
| Electronic Delivery System Development | Pulse-dosing algorithms reduce onboard inventory requirements for military transport mission endurance extension. |
| Dual MIL-PRF and DEF STAN Qualification | Opens parallel procurement channels for fighter and transport platforms across United States and European defense budgets. |
Methodological Framework
The analysis maps compressed gas, chemical generator, cryogenic liquid, and electronic oxygen delivery architectures, each validated through platform engineering directors, MRO procurement managers, and regulatory affairs specialists at FAA and EASA certification bodies. Primary fieldwork combined structured interviews with aftermarket service heads at Singapore and Dubai MRO facilities and defense procurement officers at European military airworthiness agencies. Secondary validation drew from FAA Technical Standard Order filings, EASA Certification Specification amendment notices, SEC 10-K disclosures from diversified aerospace conglomerates, and customs trade data for aerospace-grade aluminum and chlorate chemical imports. Bottom-up equipment shipment analysis triangulated against top-down fleet projection models.
Assumption sets held fixed regulatory timelines for EASA CS-25 amendments and FAA Technical Standard Order revisions, while varying military platform delivery schedules and commercial narrowbody retrofit penetration rates across the analysis window. Segmentation modeling incorporated product type, end user, technology, and certification jurisdiction dimensions. CAGRs were derived from equipment replacement cycle analysis and fleet expansion projections. Industry-specific forecast inputs included chemical oxygen generator decommissioning timelines and electronic pulse-dosing adoption curves in military transport specifications.
Macroeconomic conditions sit as an overlay; deviation in jet fuel pricing, commercial aviation passenger recovery trajectories, or defense budget allocation priorities would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and fleet renewal cadence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Cargo Systems Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Europe General Aviation Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Strategic Bomber Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Sailplane Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Aircraft Window Frame Market
Aircraft
Aircraft Control Surface Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market