
 Asia-Pacific Aircraft Windshield Wiper and Washer System Market | 2026-2036
Asia-Pacific Aircraft Windshield Wiper and Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Windshield Wiper and Washer System Market Analytics
CSRD-aligned supply chain transparency mandates are recalibrating the cost-of-entry calculus for component suppliers serving European-registered carriers operating Asia-Pacific routes. Safran S.A. leverages its integrated actuator portfolio to dominate electric wiper system deliveries for single-aisle platforms. Raytheon Technologies Corporation sustains dual-source agreements across multiple Asian MRO networks through Collins Aerospace. Honeywell International Inc. differentiates via proprietary ice-detection-linked washer control logic for high-altitude operations.
Asia-Pacific aircraft windshield wiper and washer systems integrate electric motor-driven pantograph or linear-blade assemblies with glycol-based fluid distribution circuits, engineered to maintain optical clarity across temperature ranges from minus 40 to plus 70 degrees Celsius during precipitation and icing events. Electric product types are displacing pneumatic alternatives as airlines prioritize weight reduction and variable-speed control on next-generation narrow-bodies. Military aircraft type demand anchors replacement volumes in Australia and South Korea amid fleet modernization cycles, while commercial line-fit installations capture the dominant margin pool as OEM delivery backlogs extend through the decade.
Japan's METI certifies de-icing fluid compatibility standards that directly shape product qualification timelines for washer system suppliers. India's DGFT import substitution frameworks and China's GB standards on aircraft electrical systems jointly constrain market access for non-domestic component manufacturers. Stakeholders must monitor evolving EASA-ICAO harmonization pressures on visibility system redundancy as these cascade into Asian regulator adoption timelines.
Market Dynamics
Electric actuation platforms are compressing the installed base of pneumatic wiper systems across Asia-Pacific narrow-body fleets, driven by China's MIIT airworthiness directives on enhanced visibility standards and weight-reduction mandates from regional carriers.
Growth Catalysts
- MIIT Enhanced Visibility Directives:China's Ministry of Industry and Information Technology mandates force OEMs toward electric wiper architectures, accelerating replacement cycles for legacy pneumatic units in domestic and export-configured aircraft.
- Southeast Asian MRO Contract Expansion:Commercial aviation fleets across Thailand, Indonesia, and Vietnam are scaling scheduled maintenance agreements to cover wiper system upgrades alongside airframe heavy checks.
- De-icing Fluid Compatibility Certification:Japan's METI standards for glycol-based washer fluids create qualified supplier pipelines that lock in recurring aftermarket revenue for certified system integrators.
Market Restraints
- Import Substitution Frameworks:India's DGFT local-content requirements and China's GB electrical standards erect non-tariff barriers that fragment supplier access across the region's two largest addressable markets.
- Specialized Aerospace Polymer Supply:Concentration of fluoroelastomer seal production in limited supplier bases exposes actuator manufacturers to input cost volatility and extended qualification timelines.
- Pneumatic System Longevity:Extended service intervals on legacy Boeing 737NG and A320ceo fleets delay electric conversion decisions as operators maximize remaining useful life on installed pneumatic units.
Strategic Opportunities
- Vietnam and Philippines Greenfield MRO:Emerging maintenance hubs in Da Nang and Clark Freeport Zone lack established wiper system specialists, creating first-mover positioning for electric platform providers with local partnership structures.
- EASA-ICAO Harmonization Cascade:Visibility system redundancy standards under discussion in European-Asian regulatory forums will likely transplant into CAAC and DGCA adoption timelines, pre-positioning dual-redundant architecture suppliers.
- Sensor-Wiper Convergence:Integration of ice-detection sensors with washer control logic enables predictive activation systems that differentiate offerings for high-altitude operators across the Himalaya corridor.
Industry Challenges
- Cross-Certification Timeline Compression:Simultaneous qualification demands from CAAC, DGCA, and CAAS stretch engineering validation resources as each regulator applies marginally divergent test protocols for electrical actuator safety.
- Legacy Fleet Integration Complexity:Electric wiper retrofits on older narrow-bodies require structural modifications to windshield frames and electrical bus architecture that exceed original equipment modification cost estimates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Windshield Wiper and Washer System Market |
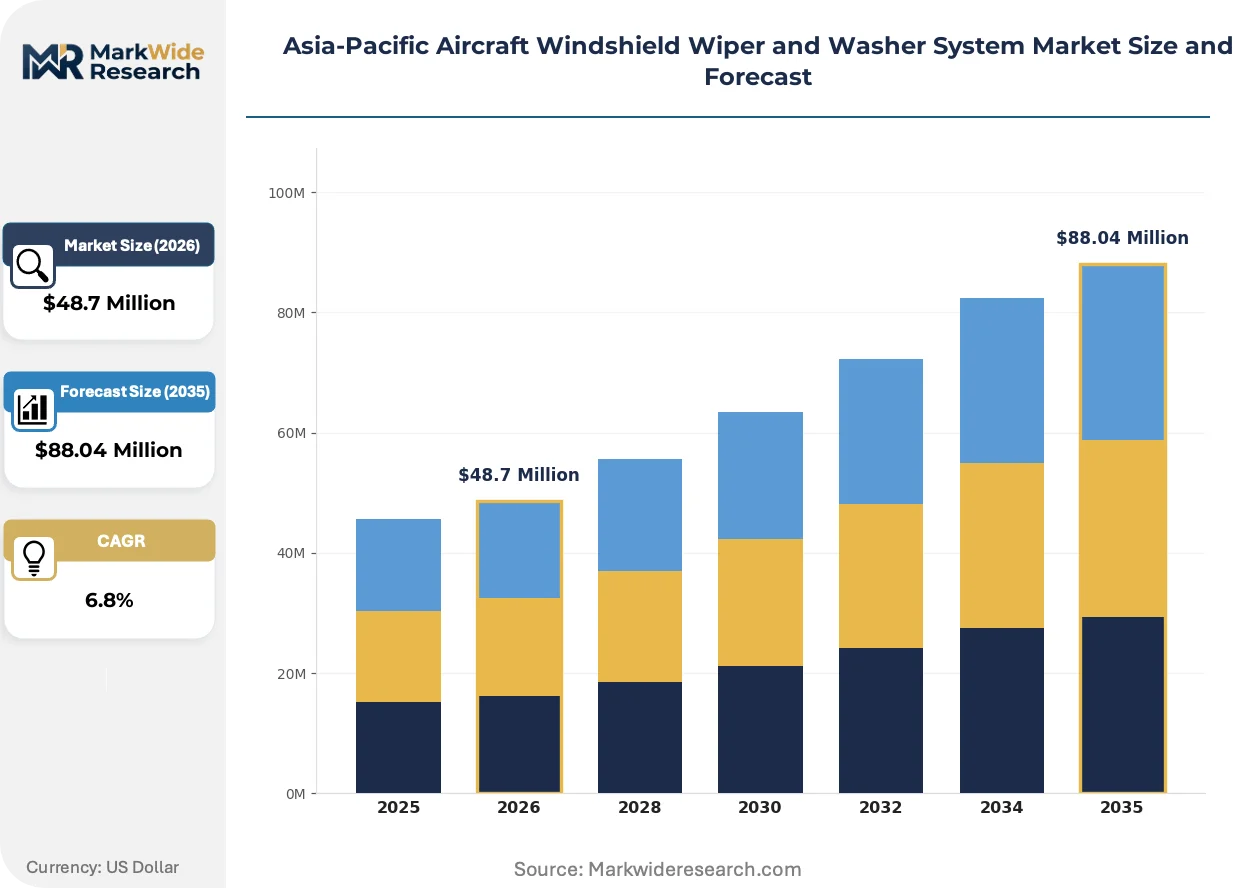
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electric, Hydraulic, Pneumatic Aircraft Type: Commercial, Military, General Aviation, Cargo End User: OEMs, MROs, Airlines, Government Agencies Installation Type: Retrofit, Line Fit, Aftermarket, Replacement |
| Companies Covered | Safran S.A., Raytheon Technologies Corporation, Collins Aerospace, Honeywell International Inc., Parker Hannifin Corporation, GKN Aerospace, Liebherr-Aerospace, Eaton Corporation, Meggitt PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Windshield Wiper and Washer System Market Evolving Landscape
Actuator miniaturization and smart-fluid distribution are compressing system weight profiles while embedding diagnostic capability, reshaping how regional carriers specify visibility equipment for next-generation single-aisle deliveries.
Brushless DC motor architectures with integrated motor-control electronics are absorbing the functional roles previously distributed across separate relay boxes and mechanical linkages in traditional wiper drive systems. Airlines operating high-cycle narrow-body routes from Bengaluru and Hyderabad are specifying these integrated units for new deliveries at accelerating rates. The technology is absorbing margin from aftermarket relay and linkage suppliers as line-fit configurations increasingly dominate procurement.
EASA-ICAO harmonization pressures on visibility system redundancy are cascading into Asian regulator adoption timelines, with China's CAAC and India's DGCA both reviewing draft amendments to aircraft equipment requirements. The industrial consequence is a qualification bottleneck for single-channel wiper systems that lack failover capability. Military operators in Australia and South Korea are absorbing these standards earliest, creating a bifurcation between defense and commercial certification pathways.
Aftermarket procurement for wiper blade consumables is unbundling from airframe heavy maintenance contracts as low-cost carriers establish direct relationships with component specialists. MRO networks in Southeast Asia are responding by developing dedicated visibility system service lines separate from general airframe workscopes. This pattern is most visible in Indonesia and Malaysia, where Lion Air Group and AirAsia operating subsidiaries have centralized wiper blade inventory management at hub locations.
Asia-Pacific Aircraft Windshield Wiper and Washer System Market Segmentation
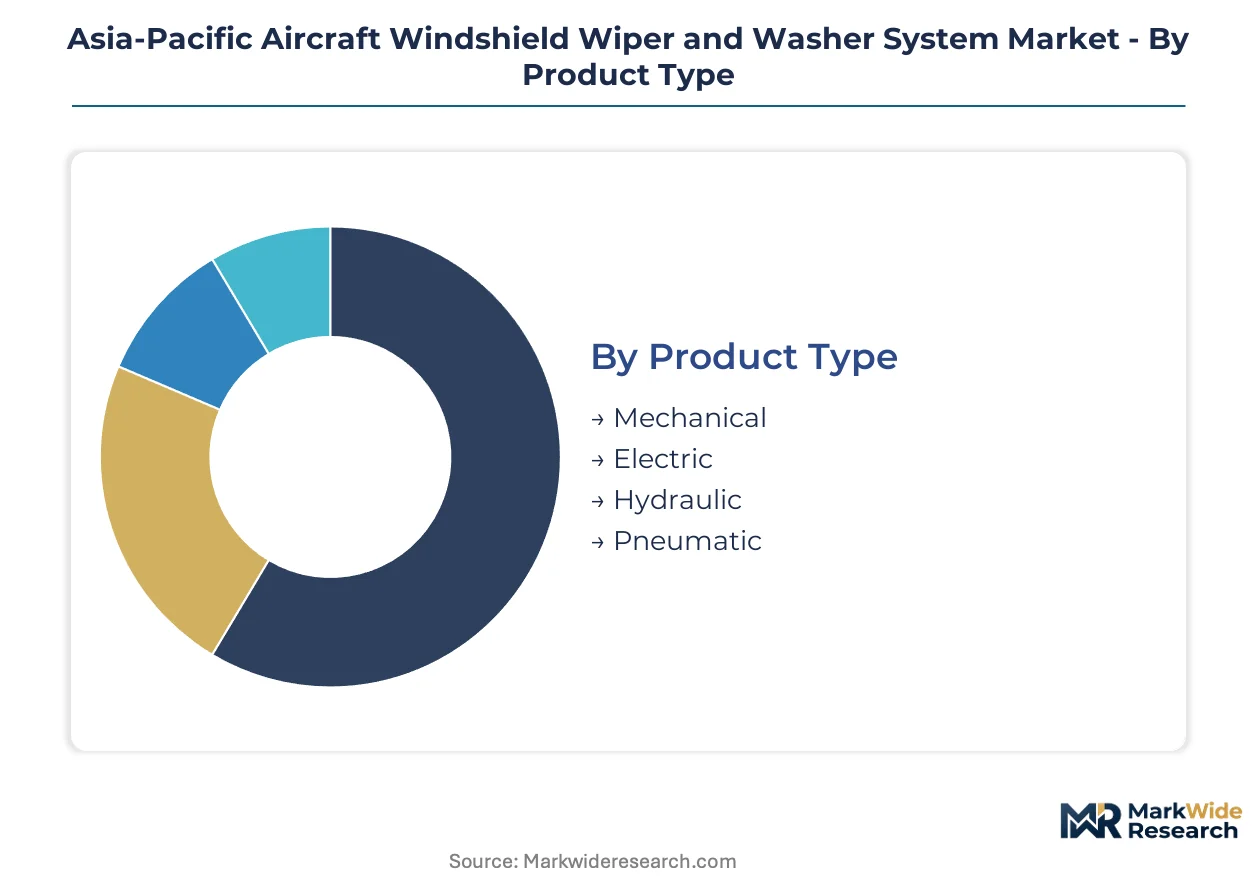
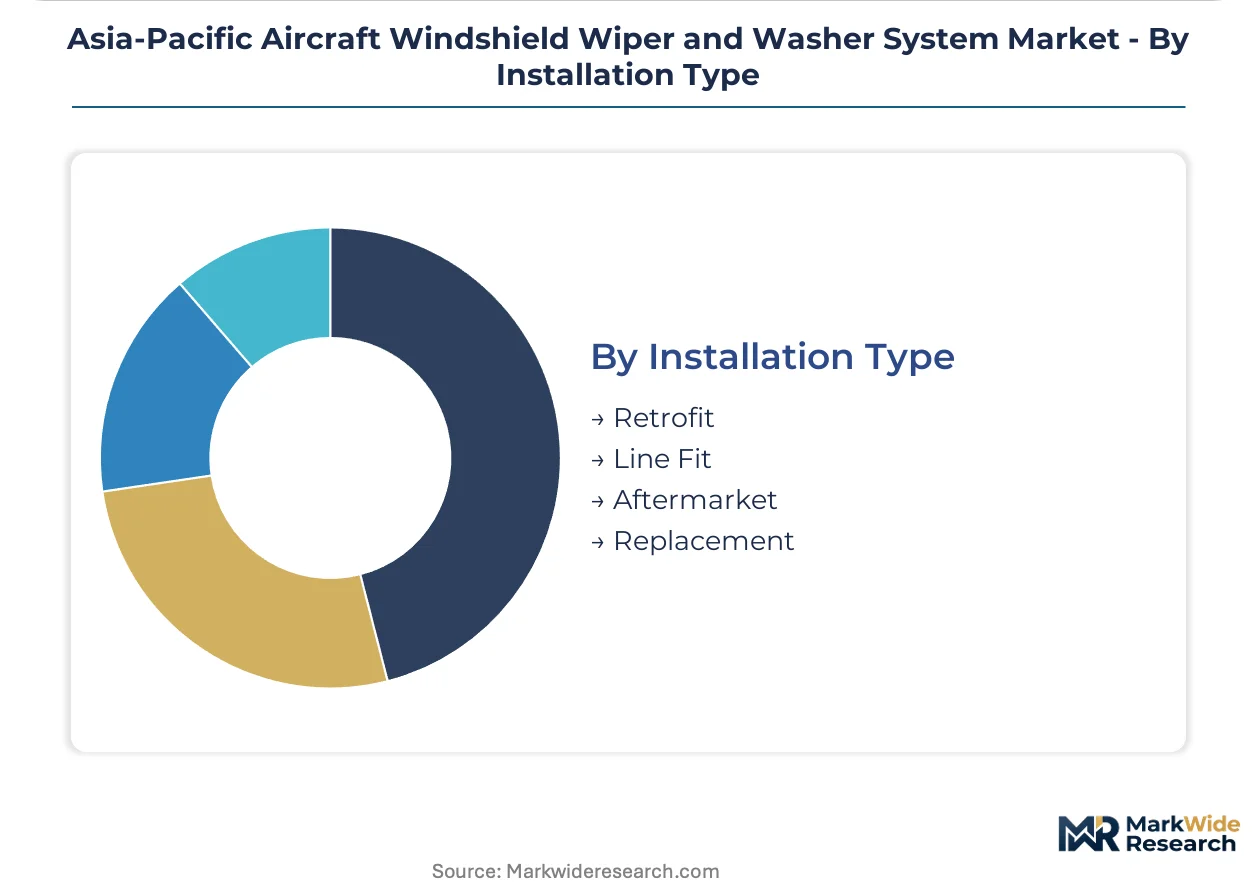
Segmentation across product architecture, aircraft application, and procurement channel reveals divergent margin structures and qualification barriers. Suppliers must align R&D allocation with the electric transition in narrow-body platforms while maintaining pneumatic aftermarket support for legacy fleets.
Product Type:
Electric systems command premium positioning against legacy pneumatic units, though volume concentration still favors established mechanical architectures in cost-sensitive retrofit scenarios.
- Electric:Brushless DC motor platforms with integrated control electronics absorb relay and linkage functions previously distributed across separate assemblies. China's MIIT airworthiness directives on enhanced visibility standards are accelerating airline specifications for variable-speed electric actuation on new narrow-body deliveries from COMAC and Airbus Tianjin.
- Pneumatic:Compressed-air drive systems retain installed base dominance on Boeing 737NG and A320ceo fleets across Southeast Asian low-cost carriers. Extended service intervals and minimal electrical bus modification requirements delay conversion decisions as operators maximize remaining useful life.
- Mechanical:Direct-drive linkages persist in general aviation and select cargo conversions where weight and complexity trade-offs favor simplicity.
- Hydraulic:High-torque hydraulic actuation remains confined to wide-body platforms and specialized military applications requiring extreme ice-shedding force.
Mature deployment sits with Pneumatic systems across legacy narrow-body fleets. Newer deployment is concentrated in Electric architectures for next-generation single-aisle platforms.
Aircraft Type:
Application-driven specification splits the market between high-cycle commercial line-fit programs and sporadic but high-value military modernization cycles.
- Commercial:Narrow-body platforms from Bengaluru and Hyderabad maintenance hubs generate concentrated demand for electric wiper retrofits and line-fit specifications. Airlines prioritize weight reduction and ice-detection integration on high-utilization routes across the Himalaya corridor.
- Military:Fleet modernization programs in Australia and South Korea anchor replacement volumes for dual-redundant visibility systems. Defense procurement timelines absorb harmonized EASA-ICAO redundancy standards earlier than commercial pathways.
- General Aviation:Light aircraft and business jets specify compact mechanical or basic electric units with minimal integration complexity.
- Cargo:Freighter conversions of passenger narrow-bodies retain original pneumatic configurations to minimize modification scope and certification burden.
Volume concentration clusters in Commercial narrow-body platforms. Procurement value intensity peaks in Military applications.
End User:
Channel structure determines qualification depth and pricing leverage, with OEM line-fit contracts locking in multi-year supply commitments against fragmented MRO procurement.
- OEMs:Original equipment manufacturers specify integrated electric platforms during airframe assembly, embedding wiper systems within broader visibility and ice-protection workscopes. COMAC and Airbus Asian final assembly lines are consolidating supplier pools around certified electric actuator integrators.
- MROs:Maintenance networks across Thailand, Indonesia, and Vietnam are unbundling wiper blade and actuator services from heavy check contracts. Lion Air Group and AirAsia subsidiaries have centralized visibility system inventory management at hub locations.
- Airlines:Direct procurement relationships with component specialists are expanding as low-cost carriers seek aftermarket cost control outside traditional MRO channels.
- Government Agencies:Defense and coast guard operators in Australia and South Korea drive dual-source requirements and localized technical support mandates.
Contract duration extends longest with OEMs. Procurement flexibility concentrates with Airlines establishing direct supplier relationships.
Installation Type:
Timing of system deployment relative to airframe lifecycle creates divergent engineering and margin requirements.
- Line Fit:Factory-installed electric systems capture dominant margin pools as OEM delivery backlogs extend. Integration with ice-detection sensors and predictive control logic differentiates specifications for high-altitude operators.
- Retrofit:Electric conversion of legacy pneumatic systems requires structural modifications to windshield frames and electrical bus architecture. India's DGFT import substitution frameworks constrain access for non-domestic component manufacturers pursuing retrofit certification.
- Aftermarket:Blade and seal consumables generate recurring revenue streams through unbundled procurement relationships. METI-certified glycol compatibility standards in Japan create qualified supplier pipelines.
- Replacement:Like-for-like pneumatic unit exchanges dominate near-term demand as operators defer electric conversion decisions.
Margin concentration aligns with Line Fit configurations. Volume expansion is climbing fastest in Aftermarket consumables as direct airline procurement patterns mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clark Freeport Zone in the Philippines and Vietnam's Da Nang Hi-Tech Park concentrate new MRO infrastructure investment, drawing electric wiper system specialists toward tax-advantaged maintenance corridors. These zones anchor regional distribution networks serving narrow-body fleets across Southeast Asia.
China
COMAC's Tianjin final assembly line and Airbus Tianjin operations drive electric wiper specifications for C919 and A320neo deliveries. MIIT airworthiness directives on enhanced visibility standards compress qualification timelines for domestic actuator suppliers. Xiamen and Chengdu maintenance clusters absorb conversion demand from legacy pneumatic systems on aging narrow-body fleets.
India
Bengaluru and Hyderabad maintenance hubs generate concentrated narrow-body wiper retrofit volumes for IndiGo and Air India Express fleets. DGFT import substitution frameworks constrain non-domestic component manufacturers pursuing certification for electric platform retrofits. The PLI scheme for aerospace components incentivizes local actuator assembly operations.
Japan
METI-certified glycol compatibility standards shape washer fluid system qualification pipelines, locking in recurring aftermarket revenue for certified integrators. Tokyo and Nagoya aerospace clusters host specialized seal and polymer suppliers serving regional actuator manufacturers. ANA and JAL fleet specifications prioritize ice-detection integration for high-altitude Himalayan routes.
Australia
RAAF fleet modernization programs in Williamtown and Amberley anchor replacement demand for dual-redundant military wiper systems. Defense procurement absorbs harmonized EASA-ICAO redundancy standards earlier than commercial pathways. Brisbane and Melbourne MRO networks support regional carrier retrofit decisions on legacy 737NG fleets.
South Korea
KF-21 fighter and maritime patrol programs drive specialized high-torque wiper specifications for extreme ice-shedding applications. Busan and Sacheon aerospace clusters concentrate military subsystem integration capabilities. Korean Air and Asiana maintenance divisions evaluate electric platform conversions amid fleet renewal cycles.
Asia-Pacific Aircraft Windshield Wiper and Washer System Market Competitive Landscape
European and North American producers anchor the premium-tier supply base; Japanese and South Korean specialists hold qualified positions in seal and polymer subsystems. The market exhibits moderate consolidation around integrated actuator portfolios, with tier-one aerospace conglomerates commanding OEM line-fit contracts. Three archetypes dominate: full-system integrators with airframe partnerships, component specialists with METI-certified fluid compatibility, and emerging Asian fabricators targeting MRO retrofit channels. Competitive moves center on local partnership structures for greenfield MRO access and dual-certification engineering for CAAC-DGCA convergence.
Among France-based conglomerates, Safran S.A. occupies a position exemplifying integrated electric actuator supply for single-aisle platforms. Raytheon Technologies Corporation and its Collins Aerospace division represent the multi-source agreement archetype sustaining presence across Asian MRO networks. Honeywell International Inc. anchors the sensor-integration tier, with proprietary control logic differentiation for high-altitude operations. These three entities collectively illustrate the geographic and technological span of incumbent positioning.
| Leading Market Players |
|---|
| Safran S.A. |
| Raytheon Technologies Corporation |
| Collins Aerospace |
| Honeywell International Inc. |
| Parker Hannifin Corporation |
| GKN Aerospace |
| Liebherr-Aerospace |
| Eaton Corporation |
| Meggitt PLC |
| Others |
Value Network & Pricing Analysis
Family-owned Japanese seal and polymer specialists anchor tier-two supply tiers, translating concentrated fluoroelastomer expertise into pricing discipline for actuator manufacturers while resisting margin compression from integrated European conglomerates.
Pricing Analysis
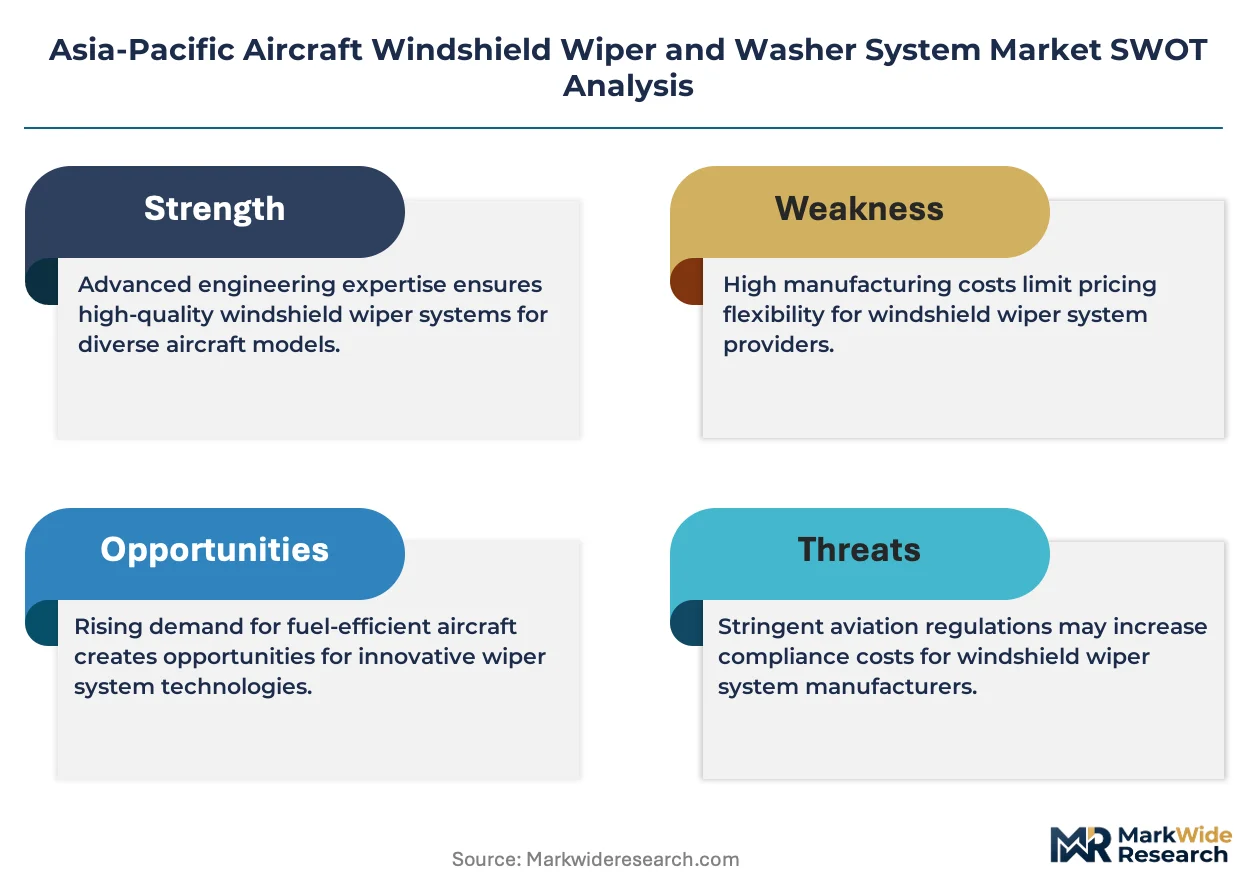
Short lead-time premiums separate urgent retrofit orders from standard line-fit procurement cycles, with electric actuator platforms commanding 15-20% markups over pneumatic equivalents due to CAAC-DGCA dual-certification engineering. Price differentiation rests on METI-certified glycol compatibility tiers and EASA-ICAO harmonization readiness, not raw material grades. Cost compression in aftermarket blade consumables intensifies as Lion Air Group and AirAsia subsidiaries centralize inventory management and disintermediate traditional MRO channels. Low-cost carriers exhibit highest price sensitivity, while RAAF and Korean defense programs absorb premium positioning for dual-redundant architectures.
Supply Chain Analysis
CAAC airworthiness qualification gates concentrate certified electric actuator production in China, Japan, and South Korea, with non-domestic manufacturers facing 18-24 month validation timelines for GB standard compliance. Fluoroelastomer seals, brushless DC motor windings, and glycol distribution manifolds constitute critical input dependencies. Single-source vulnerability concentrates in specialized aerospace polymer supply, where three Japanese producers control qualified seal formulations. Distribution runs through COMAC and Airbus final assembly lines for line-fit volumes, while MRO networks in Thailand, Indonesia, and Vietnam absorb unbundled aftermarket procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning, with actuator manufacturers pursuing backward control over fluoroelastomer seal production to deflect input cost volatility and compress CAAC qualification timelines.
For Market Incumbents: Hedge pneumatic aftermarket erosion by locking multi-year blade and seal supply contracts with Southeast Asian MRO networks before electric conversion decisions accelerate. Secure captive fluoroelastomer capacity through Japanese polymer specialist partnerships, as raw material concentration poses margin pressure points that integrated competitors will exploit. For New Entrants and Emerging Players: Sensor-wiper convergence technology offers a technology-first wedge into high-altitude operator specifications across the Himalaya corridor, where ice-detection-linked control logic remains underdeveloped. Target Vietnam's Da Nang and Philippines' Clark Freeport Zone greenfield MRO infrastructure, where established electric platform specialists lack local partnership structures and first-mover positioning remains available. For Investors and Strategic Acquirers: Distressed-cycle entries favor component specialists with METI-certified washer system qualifications in Japan, where recurring aftermarket revenue streams lock in defensive cash flow characteristics. Monitor EASA-ICAO redundancy standard adoption timelines across CAAC and DGCA as the inflection signal; dual-channel architecture qualification will bifurcate supplier viability within the forecast window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoroelastomer Production | Captive seal supply insulates margin structure from Japanese polymer concentration risk. |
| Dual-Certification Engineering Investment | CAAC-DGCA convergence readiness accelerates market access across China's MIIT directive environment. |
| Local Partnership Structuring in Vietnam | Da Nang MRO hub positioning captures unbundled visibility system service line expansion. |
| Sensor-Wiper Control Logic Development | Ice-detection integration differentiates specifications for ANA and JAL Himalayan route operations. |
| Aftermarket Inventory Centralization | Hub-based blade management mirrors Lion Air Group and AirAsia procurement pattern shifts. |
Research Methodology
Document review covered CAAC airworthiness directives, METI certification standards, and DGFT import substitution frameworks, complemented by interviews with electric actuator engineering directors, MRO procurement leads at Thai and Indonesian maintenance networks, COMAC supply chain managers, and airline fleet technical directors. Secondary validation drew from MIIT regulatory filings, EASA-ICAO harmonization committee minutes, and customs data on aerospace polymer trade flows. Bottom-up triangulation across component-level bill-of-materials analysis converged with top-down market sizing from OEM delivery schedules and MRO contract disclosure patterns.
Cross-referencing historical electric-pneumatic transition rates in narrow-body fleets against expert panel inputs on CAAC adoption timelines shaped the projection framework. Segmentation dimensions modeled include product architecture, aircraft application, procurement channel, and installation timing relative to airframe lifecycle. CAGRs were derived from installed base turnover analysis and line-fit specification trend extrapolation. Forecast inputs incorporated MIIT directive implementation phasing and PLI scheme incentive structures for Indian aerospace component assembly.
Several conditions sit outside the modeled scope, including unforeseen delays in EASA-ICAO redundancy standard finalization, abrupt shifts in China's GB electrical standard revision timelines, and geopolitical disruptions to fluoroelastomer supply chains. Forecasts reflect assumptions regarding continued narrow-body fleet expansion across Southeast Asia and sustained defense modernization budgets in Australia and South Korea. A model refresh is warranted upon material change in CAAC-DGCA harmonization adoption rates or COMAC C919 production ramp schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Fighter Aircraft Market
Aircraft
Aeronautic Propeller Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Aircraft Window Frame Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
America Attack Helicopter Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Aviation Market
Aircraft
Europe General Aviation Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Aerobatic Aircraft Market