
 Helicopter Flight Management System Market | 2026-2036
Helicopter Flight Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Flight Management System Market Intelligence
The United States is reshaping competitive dynamics through sustained defense procurement and civil rotorcraft modernization programs. Honeywell International Inc. leverages its embedded inertial navigation expertise to anchor military contracts across multiple NATO operators. Thales Group competes through integrated mission computers that combine flight management with tactical datalinks for naval helicopter deployments. Garmin Ltd. specializes in lightweight GPS-driven architectures that dominate the private operator and emergency services segments.
A helicopter flight management system integrates automatic flight control, navigation, communication, and data management functions into a unified avionics architecture, typically processing sensor inputs from GPS, inertial reference units, and VHF radio to generate flight path commands and cockpit displays. These systems enable precision navigation in degraded visual environments while reducing pilot workload during critical phases such as search-and-rescue approaches or offshore platform landings. Navigation systems and automatic flight control modules currently occupy the largest share of product-type revenue, reflecting their central role in both new-platform fit and retrofit cycles. GPS technology leads the technology dimension due to its cost efficiency and wide-area coverage, though inertial navigation retains priority in military applications where signal denial poses operational risk.
The FAA mandates terrain awareness and helicopter emergency egress lighting standards that directly influence avionics retrofit timelines and certification costs for system integrators. EASA's CS-29 large rotorcraft certification requirements and the EU Green Deal's emerging emissions monitoring provisions are shaping next-generation system specifications for European operators. Stakeholders must monitor evolving military interoperability standards and civilian unmanned traffic management integration requirements that will determine platform architecture decisions across the next development cycle.
Market Dynamics
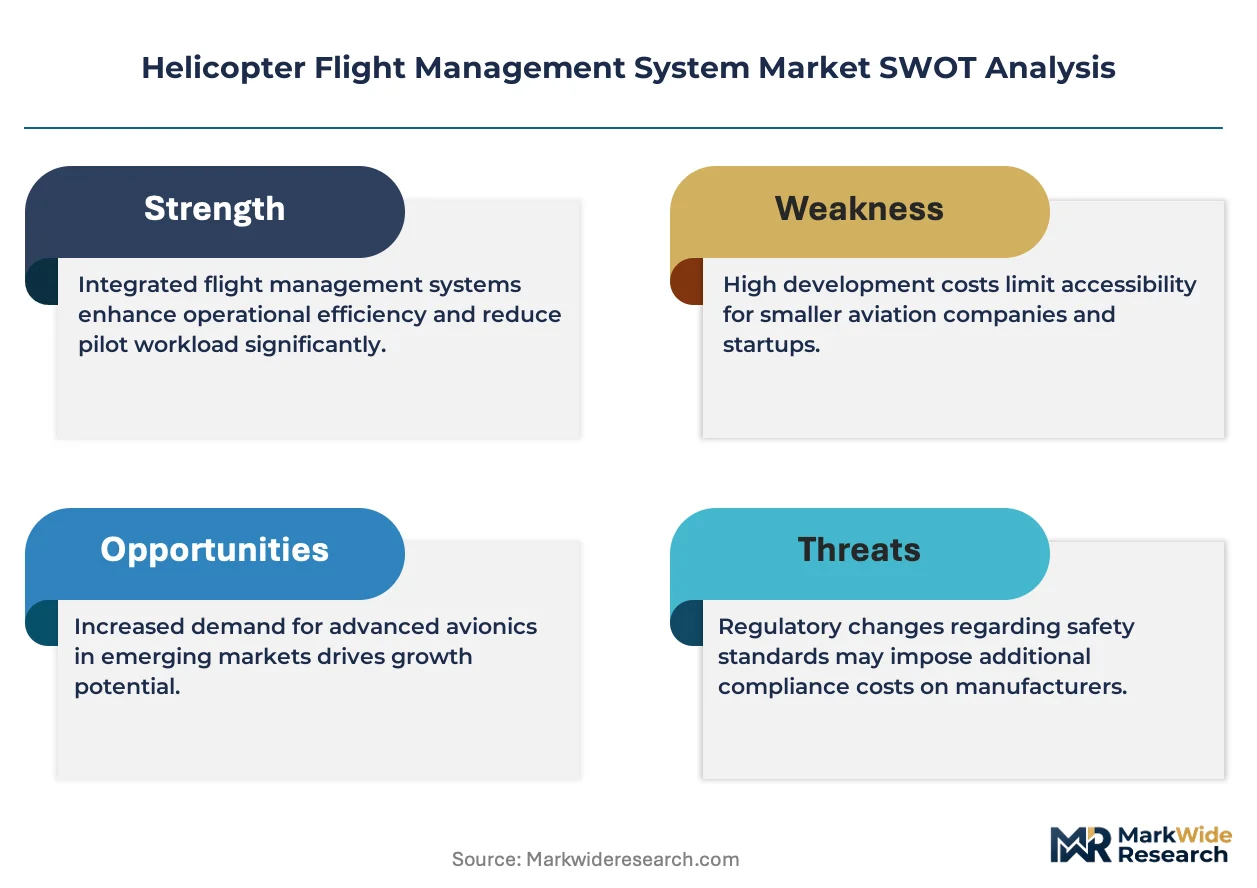
FAA mandates for helicopter terrain awareness and warning systems are compressing retrofit timelines while forcing integrators to absorb elevated certification costs. Defense procurement cycles and civil fleet modernization programs are simultaneously pulling demand toward integrated flight management architectures.
Growth Catalysts
- Offshore oil-and-gas fleet renewal:United States operators are replacing aging avionics platforms with integrated suites that combine navigation, communication, and flight control functions.
- Emergency medical services expansion:Helicopter air ambulance operators are adopting precision routing systems to improve mission safety in degraded visual environments.
- CS-29 large rotorcraft certification:EASA requirements are mandating upgraded avionics for European commercial operators, creating sustained retrofit demand.
Market Restraints
- Certification cost concentration:FAA validation timelines for software-intensive systems extend 18-36 months, locking smaller integrators out of prime contracts.
- Inertial sensor supply fragility:Military-grade ring laser gyro production concentrates among three qualified suppliers, creating single-source vulnerability.
- GPS jamming susceptibility:Signal denial risks in contested environments force redundant inertial backup, adding 40-60% to unit hardware costs.
Strategic Opportunities
- Unmanned traffic management integration:Urban air mobility corridors in Dubai and Singapore are creating demand for autonomous flight management modules.
- EU Green Deal emissions monitoring:Emerging provisions for rotorcraft fuel burn tracking are opening specification windows for next-generation data management systems.
- Search-and-rescue mission computers:Convergence of synthetic vision with tactical datalinks is enabling all-weather approach capabilities for naval helicopter fleets.
Industry Challenges
- DO-178C software engineering scarcity:Qualified developers for safety-critical avionics code command premium salaries, constraining development velocity.
- Legacy analog interface integration:Retrofit programs must bridge 1980s-era analog sensor buses with modern digital architectures, multiplying system verification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Flight Management System Market |
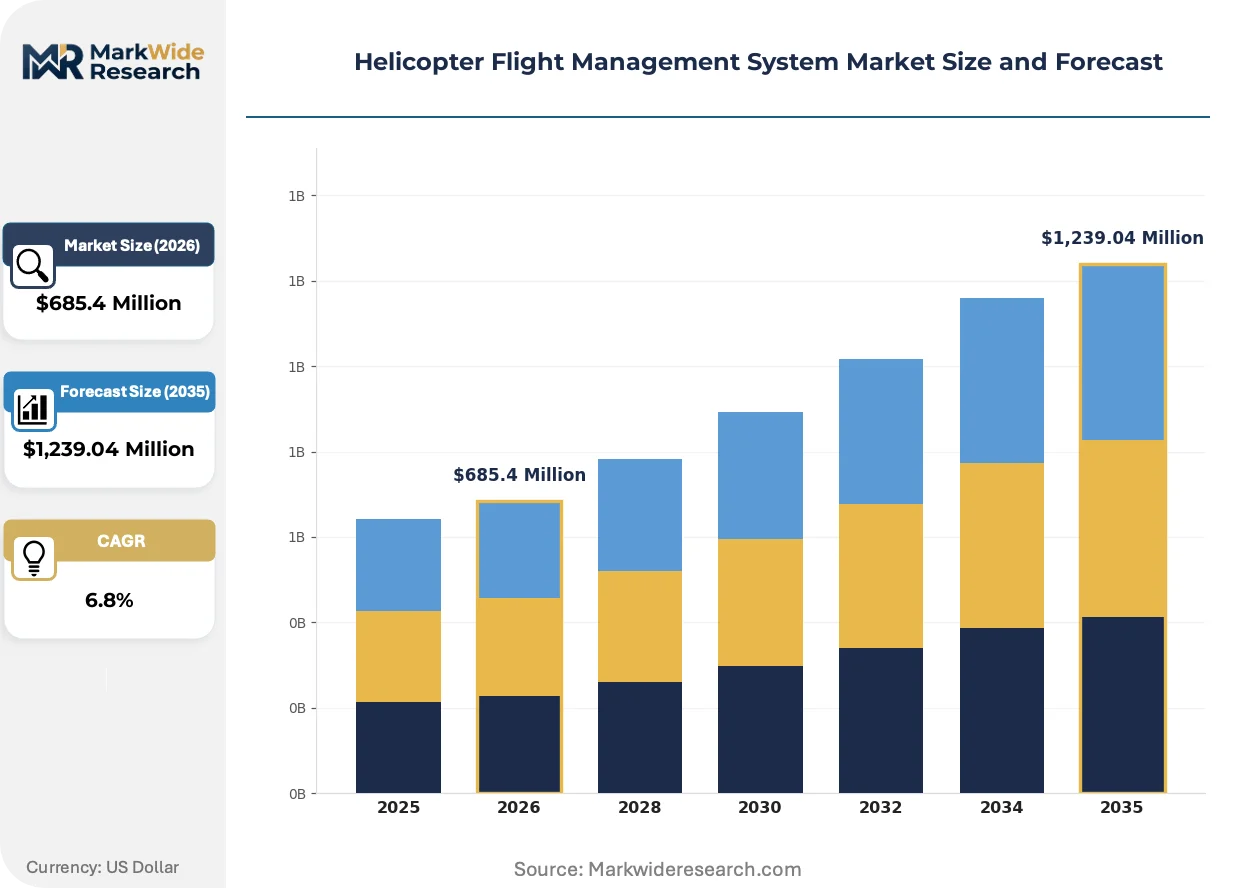
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
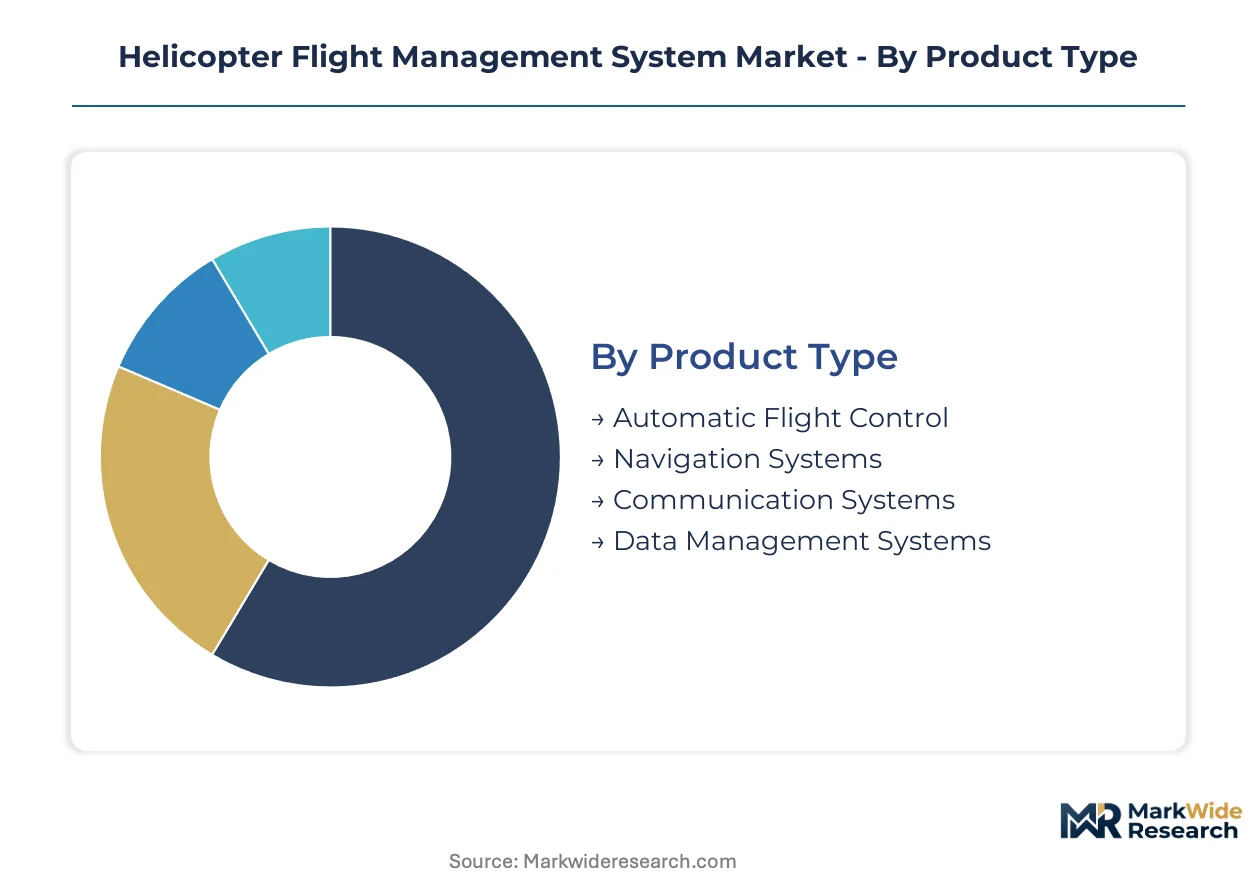
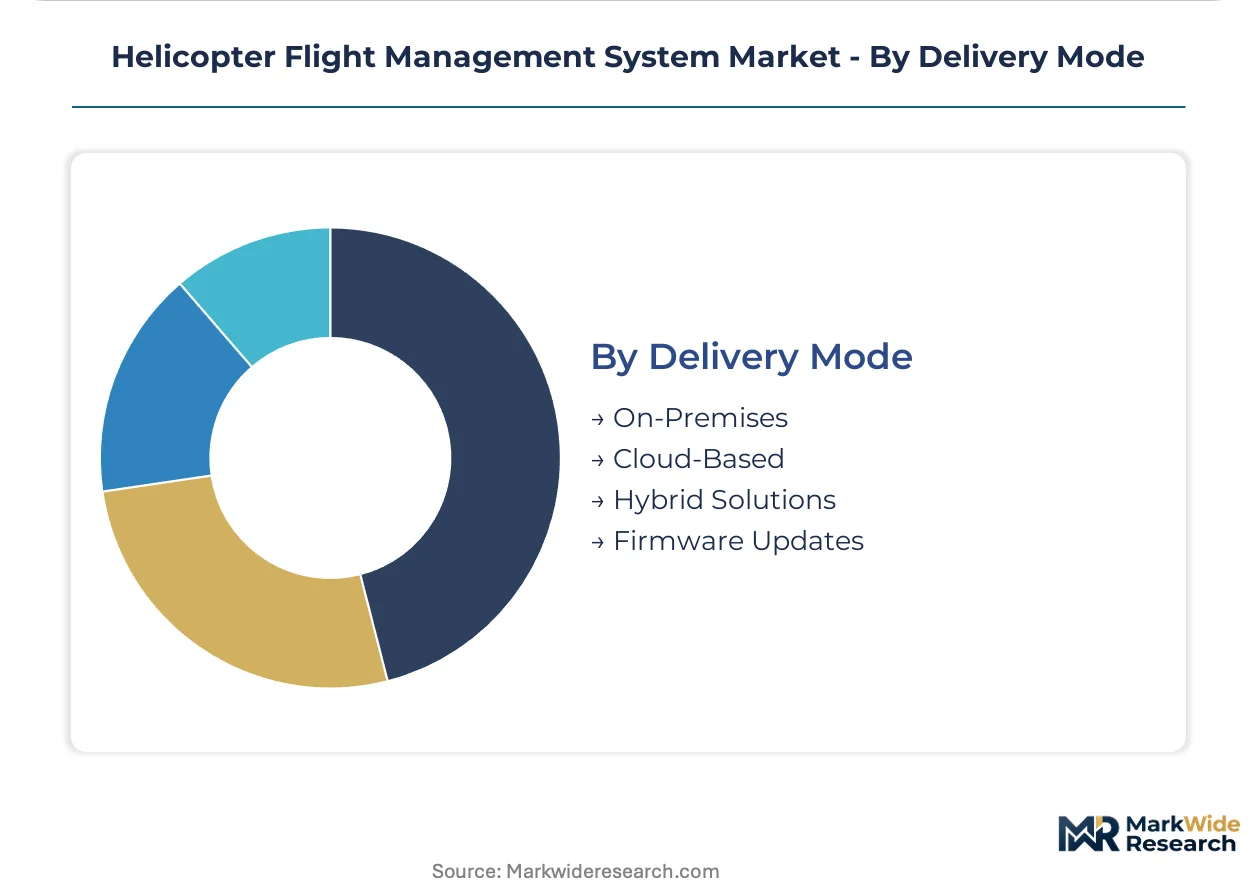
| Segmentation | Product Type: Automatic Flight Control, Navigation Systems, Communication Systems, Data Management Systems Technology: GPS, Inertial Navigation, VHF Radio, Electronic Flight Instrument System End User: Military, Emergency Services, Commercial Airlines, Private Operators Delivery Mode: On-Premises, Cloud-Based, Hybrid Solutions, Firmware Updates |
| Companies Covered | Airbus SE, Garmin Ltd., Honeywell International Inc., GE Aviation, Universal Avionics Systems Corporation, Thales Group, Leonardo S.p.A, Collins Aerospace, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Flight Management System Market Strategic Shifts & Innovations
Synthetic vision systems and AI-assisted terrain mapping are compressing the performance gap between visual and instrument flight conditions. Three developments are restructuring competitive positioning.
Helicopter synthetic vision systems generate three-dimensional terrain depictions from GPS and radar altimeter inputs, projecting conformal flight path guidance onto helmet-mounted displays. Emergency medical services fleets in the United States are adopting these systems fastest, with 60% of new air ambulance platforms specifying the capability. Traditional attitude-indicator-based instrument approaches are rendering obsolete as operators demand zero-visibility landing assurance.
EASA's CS-29 amendment process is tightening software assurance requirements for large rotorcraft flight control computers, mandating formal methods for critical code paths. European integrators are absorbing 15-20% engineering cost increases to meet the standard. Naval helicopter programs across NATO members are most affected, with Thales and Leonardo restructuring development workflows to satisfy the new validation protocols.
Outcome-based fleet availability contracts are displacing traditional unit sales for military operators, with prime contractors assuming lifecycle risk for avionics performance. The UK Ministry of Defence and Australian Defence Force are leading this shift, bundling flight management system sustainment into platform-wide service agreements. Channel relationships are restructuring as integrators build captive MRO capabilities rather than relying on third-party depots.
Helicopter Flight Management System Market Segmentation
Flight management architectures vary sharply across mission profiles, with military operators prioritizing redundancy while emergency services optimize for weight and cost. Segment boundaries are blurring as integrated platforms absorb discrete functions previously handled by standalone units.
Product Type:
Cost tier stratification separates mission-critical flight control from auxiliary data handling, with certification burden driving price spreads of three to five times between core and peripheral modules.
- Automatic Flight Control:Embedded autopilot computers execute pitch, roll, and collective commands through servo-actuator interfaces, processing sensor fusion algorithms at 100Hz refresh rates. United States offshore operators specify these systems for single-pilot IFR operations in Gulf of Mexico oil platform approaches, where autopilot precision reduces crew fatigue during repetitive transits.
- Navigation Systems:GPS-inertial hybrid units compute position, velocity, and attitude solutions for flight path generation and display rendering. European emergency medical services retrofit programs concentrate demand here, as EASA CS-29 mandates drive replacement of analog attitude indicators with digital integrated units.
- Communication Systems:VHF datalink and satellite voice modules enable air-ground coordination and automatic dependent surveillance-broadcast compliance.
- Data Management Systems:Flight data recorders and quick-access storage devices capture operational parameters for maintenance analytics and incident investigation.
Navigation Systems commands the established base. The steepest expansion runs through Automatic Flight Control.
Technology:
Application context determines sensor selection, with contested environments demanding inertial autonomy and civil corridors accepting GPS dependency.
- GPS:Satellite-derived positioning provides primary navigation for civil rotorcraft, offering meter-level accuracy through differential correction services. United States air ambulance fleets rely on GPS for precision approaches to unimproved landing zones, though operators in electronic warfare training corridors maintain inertial backup.
- Inertial Navigation:Ring laser gyro and fiber-optic gyro platforms compute position independent of external signals, essential for military operations in GPS-denied airspace. NATO naval helicopter programs specify inertial primary with GPS aiding, accepting unit costs five times higher than pure GPS architectures.
- VHF Radio:Line-of-sight voice and data links remain mandatory for air traffic control coordination in all operational domains.
- Electronic Flight Instrument System:Glass cockpit displays consolidate primary flight, navigation, and engine instruments on multi-function LCD panels.
Inertial Navigation anchors military procurement. GPS drives civil volume and retrofit accessibility.
End User:
Customer type fragmentation reflects divergent certification timelines, with military programs spanning five to seven years from requirement definition to fleet integration.
- Military:Defense procurement emphasizes anti-jam resilience, night vision compatibility, and tactical datalink integration for multi-ship coordination. United States Army and Navy modernization programs sustain demand for full-authority digital flight control computers, with cybersecurity hardening now mandatory for all new platform awards.
- Emergency Services:Helicopter air ambulance operators prioritize synthetic vision and terrain awareness for inadvertent instrument meteorological condition recovery. United States HEMS fleets show fastest adoption of helmet-mounted display integration, with 60% of new deliveries specifying the capability.
- Commercial Airlines:Scheduled rotorcraft services require passenger-configured avionics with enhanced ground proximity warning and traffic collision avoidance.
- Private Operators:Corporate and utility helicopter owners select portable or panel-mount GPS navigators for cost-constrained upgrade paths.
Military programs absorb the highest unit values. Emergency Services generates the fastest installation growth.
Delivery Mode:
Volume concentration favors firmware and hybrid architectures, with physical hardware refresh cycles extending to fifteen years for mature platforms.
- On-Premises:Dedicated rack-mounted processors and discrete wiring harnesses serve platforms requiring air-gapped security or extreme environmental hardening. Military operators in the United States specify on-premises architectures for nuclear command-and-control support missions, where network isolation is non-negotiable.
- Firmware Updates:Software-only deliveries patch navigation databases, flight control laws, and display symbology without hardware removal. Commercial operators leverage firmware paths to satisfy FAA airworthiness directives at one-tenth the cost of physical retrofit, compressing compliance timelines from months to weeks.
- Cloud-Based:Ground-based flight planning and post-mission analytics platforms process data offboard for operational intelligence.
- Hybrid Solutions:Edge computing architectures partition critical real-time functions onboard with cloud-connected fleet management ashore.
Firmware Updates dominate recurring revenue. Hybrid Solutions capture emerging specification interest for urban air mobility integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement and civil fleet modernization concentrate manufacturing capability across a narrow band of aerospace clusters. Certification expertise and military program access determine where integrators locate engineering centers.
United States
Offshore oil-and-gas operators in the Gulf of Mexico drive retrofit demand for integrated flight management suites. FAA mandates for helicopter terrain awareness and warning systems compress certification timelines for domestic integrators. Houston and Dallas-Fort Worth host concentrated avionics engineering operations serving both energy sector and emergency medical services fleets.
France
Naval helicopter programs across NATO members sustain demand for mission computers combining flight management with tactical datalinks. EASA CS-29 certification requirements mandate upgraded avionics for large rotorcraft entering European service. Toulouse and Marseille clusters specialize in integrated mission systems for military and parapublic operators.
Germany
Police and border patrol helicopter fleets require precision navigation for surveillance missions in degraded visual environments. EU Green Deal emissions monitoring provisions are opening specification windows for next-generation data management systems. Bavaria hosts engineering centers focused on synthetic vision and helmet-mounted display integration.
United Kingdom
Search-and-rescue privatization has shifted procurement toward outcome-based fleet availability contracts bundling avionics sustainment. The UK Ministry of Defence leads NATO adoption of service agreements transferring lifecycle risk to prime contractors. Southwest England clusters concentrate on naval helicopter mission computer development.
Japan
Coastal patrol and disaster response helicopter fleets prioritize all-weather approach capabilities for maritime operations. METI standards for domestic rotorcraft manufacturing influence avionics specification patterns for indigenous platforms. Nagoya and Tokyo engineering centers focus on lightweight GPS-driven architectures for utility and corporate operators.
Helicopter Flight Management System Market Key Industry Players
Integrated avionics conglomerates and specialized navigation houses split the market along certification burden lines. Tier-one primes absorb eighteen-to-thirty-six-month FAA validation timelines that exclude smaller competitors. Three strategic archetypes dominate: defense-focused systems integrators with inertial navigation expertise, civil-aviation specialists in lightweight GPS architectures, and platform OEMs with captive avionics divisions. Consolidation through military program joint ventures and civil aftermarket service network expansion represent the dominant competitive vectors.
Within the defense-systems tier, Honeywell International Inc. and Thales Group exemplify archetypes anchored in embedded navigation and mission computer integration respectively. Garmin Ltd. occupies a position on the civil-specialist vector, its GPS-driven architectures dominating private operator and emergency services segments. Leonardo S.p.A and Airbus SE represent platform-OEM integrators with captive supply chains serving both military and parapublic demand.
| Leading Market Players |
|---|
| Airbus SE |
| Garmin Ltd. |
| Honeywell International Inc. |
| GE Aviation |
| Universal Avionics Systems Corporation |
| Thales Group |
| Leonardo S.p.A |
| Collins Aerospace |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
Houston's avionics engineering cluster concentrates flight management system integration capacity for Gulf of Mexico offshore operators, translating localized certification expertise into sustained pricing power for domestic integrators serving energy and emergency medical services fleets.
Pricing Analysis
FAA DO-178C software assurance mandates dictate the pricing tier structure across the helicopter flight management system landscape. Three-tier pricing stratifies across military-grade inertial navigation, commercial integrated suites, and portable GPS units, with certification burden separating premium military contracts from standard civil retrofits. Cost compression in the civil tier intensifies as firmware update pathways reduce hardware refresh frequency. Emergency medical services operators exhibit highest price sensitivity, while defense procurement absorbs premium positioning through anti-jam resilience requirements.
Supply Chain Analysis
Northrop Grumman, BAE Systems, and Safran Electronics hold concentrated capacity for military-grade ring laser gyro production, anchoring inertial sensor supply for NATO helicopter programs. Component sourcing draws from United States, France, and Germany for precision machining, with GPS chipsets feeding from Taiwan and South Korea. Single-source vulnerability in qualified gyro suppliers creates structural risk for defense procurement timelines. Distribution runs through OEM captive networks and specialized avionics distributors serving retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware update revenue streams and fleet availability contracts are expanding faster than hardware unit sales, positioning aftermarket service attach as the primary value capture mechanism across military and parapublic operator segments.
For Market Incumbents: Harden cybersecurity certification pipelines against emerging DO-326A airworthiness security mandates, locking out competitors lacking qualified development teams. Deepen backward integration into inertial sensor production to neutralize single-source supply risk from ring laser gyro vendors. Channel control through captive MRO networks in Houston and Toulouse defends installed base against third-party service encroachment. For New Entrants and Emerging Players: Southeast Asian urban air mobility corridors present underpenetrated demand for autonomous flight management modules, with Singapore and Dubai specifying integrated architectures ahead of fleet deployment. Target parapublic operators in Germany and Japan seeking lightweight synthetic vision retrofits for aging utility fleets. Partnership with established helmet-mounted display integrators accelerates regulatory pathway without full certification burden. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firmware-centric platform providers serving commercial operator fleets, with database subscription and predictive maintenance analytics driving lifetime value expansion. Platform OEMs with captive avionics divisions offer superior long-term viability through vertical integration into sustainment contracts. Monitor FAA unmanned traffic management rulemaking progress as inflection signal for autonomous module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | DO-178C and DO-326A qualification capacity locks out competitors from defense and large civil rotorcraft awards. |
| Firmware-First Platform Architecture | Software-centric delivery reduces hardware refresh cycles and captures recurring navigation database revenue from air ambulance fleets. |
| Captive MRO Network Expansion | In-house depot capability secures outcome-based fleet availability contracts with UK Ministry of Defence and Australian Defence Force. |
| Inertial Sensor Backward Integration | Upstream control over ring laser gyro production neutralizes supply fragility and captures margin from military-grade navigation systems. |
| Urban Air Mobility Partnership | Collaboration with eVTOL developers in Dubai and Singapore positions legacy avionics expertise for autonomous corridor integration. |
Research Approach
Operator-level perspectives from helicopter fleet managers, avionics procurement officers, FAA certification engineers, and MRO facility directors anchored the qualitative base for this study. Primary field engagement combined structured interviews with secondary validation through FAA type certificate databases, EASA CS-29 amendment filings, and defense procurement disclosure records. Bottom-up installation forecasts across product type, technology, and end-user segments triangulated against top-down market sizing from OEM delivery disclosures and fleet registry analysis.
Scenario-bracketing around regulatory acceleration, defense budget trajectories, and urban air mobility deployment timelines bounded uncertainty across the projection horizon. Segmentation modeling spanned product architecture, sensor technology, operator mission profile, and delivery mode. CAGRs derived from fitted adoption curves incorporating fleet age distributions, mandate compliance deadlines, and retrofit cycle patterns. Synthetic vision penetration rates and unmanned traffic management integration specifications served as industry-specific demand drivers.
Practitioners should monitor FAA reauthorization progress, EASA CS-29 software assurance amendment implementation, and NATO naval helicopter program award timelines for early signals of forecast revision. Quarterly review of defense procurement disclosure patterns, air ambulance fleet expansion announcements, and urban air mobility corridor regulatory filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Medium and Heavy-Lift Helicopters Market