
 Fighter Aircraft Market | 2026-2036
Fighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Fighter Aircraft Market Intelligence
Aftermarket service revenue is reconfiguring margin distribution across the fighter aircraft value chain. Lockheed Martin Corporation leverages its sustainment infrastructure for the F-35 platform to capture recurring lifecycle value. Boeing sustains dominance in the fighter-bomber segment through Super Hornet upgrade programs and international offset agreements. Saab AB competes in the mid-tier export market with Gripen E variants optimized for nations with constrained procurement budgets.
A fighter aircraft is a fixed-wing military platform engineered for air-to-air combat, ground attack, and multi-mission operations, typically achieving supersonic speeds exceeding Mach 1.5 through afterburning turbofan propulsion and incorporating composite material airframes to reduce radar cross-section. Its primary purpose is to establish and maintain air superiority while delivering precision strike capability against terrestrial and maritime targets. Multirole fighters now command the largest procurement volume as militaries prioritize platform versatility over specialized interceptors, while stealth fighters absorb the steepest R&D investment despite constrained production rates. Avionics represents the fastest-evolving technology segment, with integrated sensor fusion architectures displacing federated systems and redistributing supplier influence toward software-intensive subsystem providers.
The US Department of Defense's Joint Capabilities Integration and Development System, the EU's Permanent Structured Cooperation framework, and NATO's airworthiness certification standards collectively shape platform requirements, interoperability mandates, and cross-border industrial participation rules. FAA airspace integration protocols for unmanned loyal wingman concepts and national export control regimes under ITAR further constrain market access and technology transfer pathways. Stakeholders must monitor how sixth-generation program commitments in Washington, Brussels, and Tokyo will redistribute development risk and production workload across transatlantic and Indo-Pacific industrial bases.
Market Dynamics
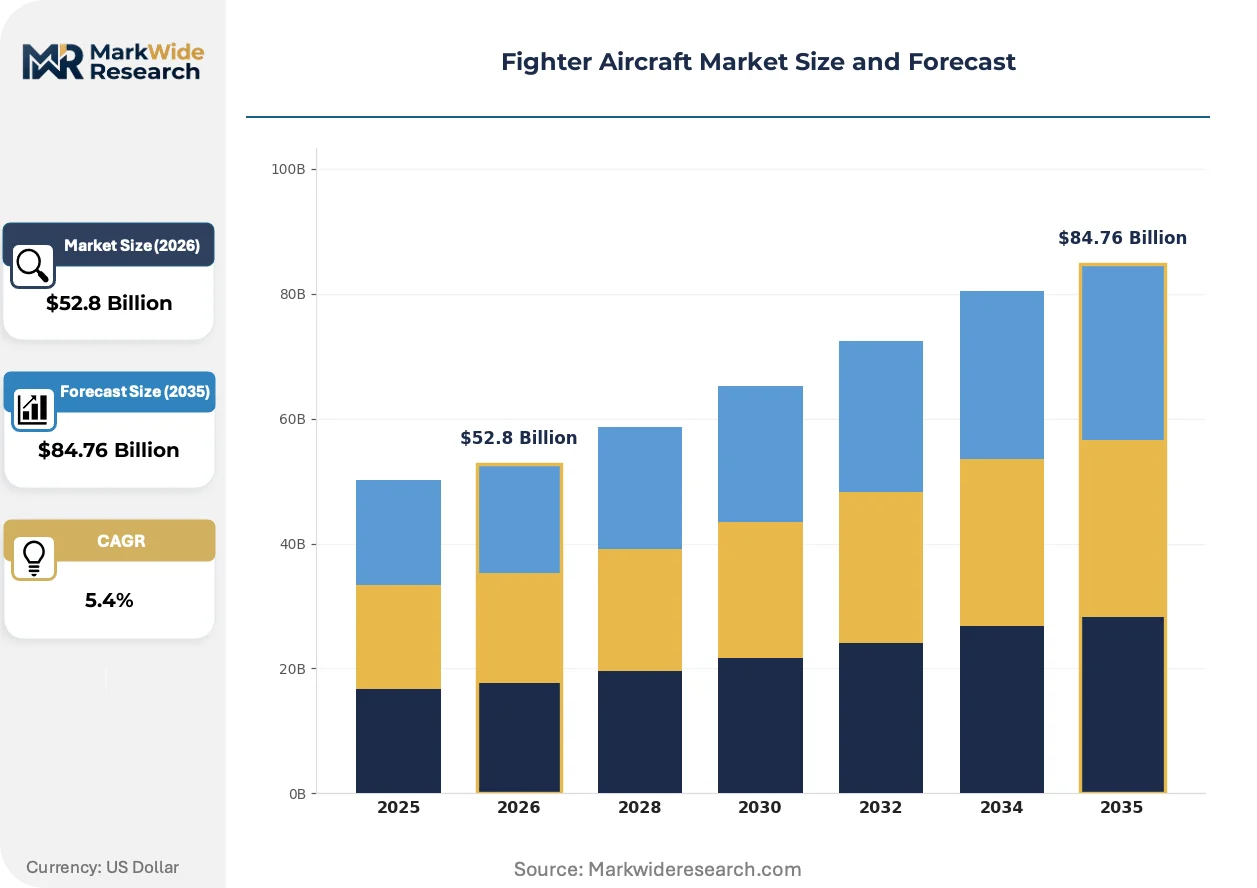
Fleet modernization mandates across NATO air forces are compressing procurement cycles while redirecting R&D investment toward sixth-generation architectures. The transition from federated avionics to integrated sensor fusion is redistributing supplier power toward software-intensive subsystem providers.
Growth Catalysts
- NGAD Program Acceleration:The US Department of Defense's Next Generation Air Dominance initiative is channeling development funding toward manned-unmanned teaming architectures, creating demand for loyal wingman platforms and advanced datalink infrastructure.
- Permanent Structured Cooperation:The EU's PESCO framework is pooling member state resources for collaborative fighter development, reducing per-unit R&D burden and standardizing interoperability protocols across continental air forces.
- Composite Airframe Adoption:Carbon-fiber reinforced polymer manufacturing processes are reducing radar cross-section while extending structural service life, enabling platforms to meet stealth requirements without titanium-intensive construction.
Market Restraints
- Turbofan Engine Supply Concentration:Production of low-observable afterburning propulsion systems concentrates among a handful of US and UK suppliers, creating single-source vulnerability for European and Asian platform integrators.
- ITAR Compliance Burden:US International Traffic in Arms Regulations impose licensing delays on technology transfer for stealth coatings and advanced avionics, constraining joint development programs with non-NATO partners.
- Specialized Titanium Forging Bottlenecks:High-temperature airframe components require inputs from a shrinking base of qualified forging facilities, with capacity concentrated in Russia and Ukraine prior to supply chain reconfiguration.
Strategic Opportunities
- Indo-Pacific Offset Agreements:Australia's AUKUS commitment and Japan's F-X program are creating pathways for technology co-development with US primes, bypassing traditional export control barriers through sovereign production clauses.
- Digital Thread Integration:Convergence of model-based systems engineering with predictive maintenance analytics is enabling condition-based sustainment contracts that capture recurring revenue across multi-decade platform lifecycles.
- Poland's Harpia Procurement:Warsaw's accelerated F-35 acquisition and future fighter studies represent a near-term demand concentration for multirole platforms with NATO interoperability certification.
Industry Challenges
- Flight Software Certification Timeline:FAA and military airworthiness authorities require exhaustive verification of autonomous decision-making algorithms, extending development schedules for unmanned collaborative combat aircraft by 18-24 months.
- Secure Supply Chain Reconfiguration:Platform integrators must duplicate qualified supplier bases for critical semiconductors and rare earth magnets, doubling qualification costs while maintaining production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fighter Aircraft Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirole Fighters, Stealth Fighters, Trainer Aircraft, Fighter Bombers Technology: Avionics, Propulsion Systems, Radar Systems, Weapon Systems End User: Military Forces, Defense Contractors, Government Agencies, Private Security Firms Deployment: Airborne Interception, Ground Attack, Reconnaissance, Maritime Strike |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, Northrop Grumman Corporation, Airbus SE, Dassault Aviation, BAE Systems, Saab AB, Mitsubishi Heavy Industries Ltd., Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fighter Aircraft Market Strategic Shifts & Innovations
Directed energy weapons and adaptive cycle propulsion are converging with open mission systems architectures to redefine platform design priorities. These advances are compressing the gap between technology demonstration and fielded capability.
Adaptive cycle engine technology is hybridizing traditional turbofan performance with variable bypass ratios that optimize fuel efficiency across subsonic cruise and supersonic dash regimes. The US Air Force Research Laboratory and Pratt & Whitney are flight-testing these configurations for sixth-generation platforms. This propulsion shift is hybridizing thermal management requirements with airframe design, forcing integrators to co-develop inlet geometry and cooling infrastructure rather than treating engines as line-replaceable units.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on autonomous targeting systems deployed by member state air forces. European defense ministries must now document decision logic for lethal autonomous weapon recommendations, adding documentation burden to software development. Combat aircraft with NATO-standard interoperability certification face the steepest compliance adjustment, as allied datalink protocols must demonstrate auditability without compromising operational security.
Air forces are consolidating fleet diversity around multirole platforms capable of substituting for specialized interceptors and strike aircraft. Denmark and Belgium have retired single-mission types entirely, concentrating pilot training and logistics around F-35 variants. This platform rationalization is most visible among smaller NATO members with constrained procurement budgets, where squadron-level flexibility outweighs mission-optimized performance margins.
Fighter Aircraft Market Segmentation
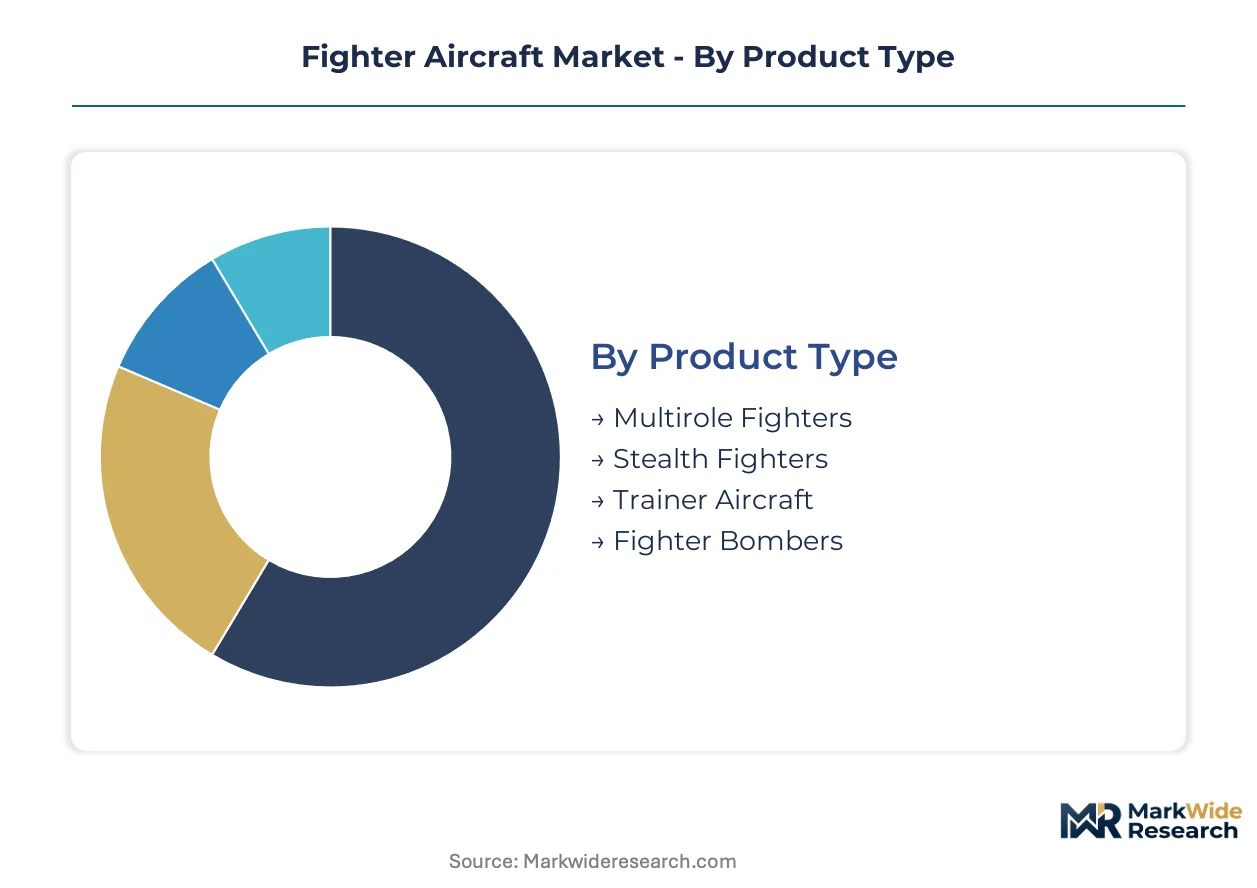
Platform specialization and subsystem integration define competitive positioning across fighter aircraft procurement cycles. Segment boundaries blur as multirole architectures absorb mission profiles once reserved for dedicated interceptors and strike platforms.
Product Type:
Mature combat airframes coexist with emerging stealth architectures, creating tiered procurement strategies across defense budgets.
- Multirole Fighters:These platforms integrate air-to-air and air-to-ground capabilities through modular weapon stations and software-defined mission systems. NATO members including Denmark and Belgium have consolidated entire fleets around single multirole types, eliminating logistics duplication. Demand concentrates in mid-tier export markets where squadron flexibility outweighs specialized performance margins.
- Stealth Fighters:Low-observable designs employ angled surfaces, radar-absorbent materials, and internal weapons bays to reduce electromagnetic signature. The F-35 program absorbs the largest development and sustainment investment in Western combat aviation, with production rates constrained by titanium forging bottlenecks and software certification timelines.
- Trainer Aircraft:Advanced jet trainers incorporate digital cockpits and sensor simulations to reduce pilot transition time to frontline fighters.
- Fighter Bombers:These platforms prioritize payload capacity and range over dogfight maneuverability, serving strike missions in contested airspace.
Multirole fighters retain volume leadership; stealth fighters hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy subsystem upgrades from integrated architecture replacements.
- Avionics:Integrated sensor fusion architectures displace federated systems, consolidating radar, electronic warfare, and communications processing through open mission systems standards. The EU AI Act imposes algorithmic transparency requirements on autonomous targeting functions, adding documentation burden to software development for European platform integrators.
- Propulsion Systems:Adaptive cycle engines optimize bypass ratios across subsonic cruise and supersonic dash regimes, co-developed with inlet geometry and thermal management infrastructure rather than treated as line-replaceable units.
- Radar Systems:Active electronically scanned arrays enable simultaneous air-to-air tracking and ground mapping modes.
- Weapon Systems:Internal carriage requirements for stealth compatibility drive compact munition development.
Avionics commands the premium tier; propulsion systems anchor platform performance differentiation.
End User:
Customer type determines procurement authority, funding mechanisms, and offset negotiation leverage.
- Military Forces:Service branches define technical requirements through operational concepts and threat assessments, with NATO airworthiness standards shaping interoperability mandates. Fleet modernization programs compress procurement cycles while redirecting investment toward sixth-generation architectures and loyal wingman concepts.
- Defense Contractors:Prime integrators manage subsystem supplier bases and government contract execution, capturing recurring lifecycle value through sustainment infrastructure.
- Government Agencies:Research laboratories and test organizations fund technology maturation prior to platform integration.
- Private Security Firms:Limited procurement authority concentrates on surveillance and training support rather than combat platforms.
Military forces dominate procurement volume; defense contractors capture the aftermarket value concentration.
Deployment:
Application scope shapes platform specifications and basing requirements across operational theaters.
- Airborne Interception:Beyond-visual-range missile engagement and sensor networking prioritize radar cross-section reduction and datalink bandwidth. Poland's accelerated F-35 acquisition reflects NATO's emphasis on contested airspace denial.
- Ground Attack:Precision strike missions require targeting pod integration and weapon delivery accuracy in GPS-denied environments.
- Reconnaissance:Sensor payload flexibility and endurance drive unmanned platform adoption for intelligence collection.
- Maritime Strike:Anti-ship missile carriage and sea-skimming targeting algorithms address naval surface action group threats.
Airborne interception retains mission priority; maritime strike shows the fastest capability investment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across NATO members. Poland and Baltic states accept premium pricing for rapid interoperability gains. Germany and France prioritize industrial participation over unit cost minimization.
United States
Congressional defense appropriations prioritize tactical air superiority through the Next Generation Air Dominance initiative. The FAA coordinates unmanned loyal wingman airspace integration protocols with the Pentagon. Lockheed Martin's F-35 final assembly line in Fort Worth, Texas, drives composite airframe manufacturing clusters across the Dallas-Fort Worth metroplex.
United Kingdom
Royal Air Force Tempest program commitments absorb sixth-generation R&D investment alongside Japan's F-X collaboration. UK export control regimes under the Strategic Export Licensing Criteria constrain technology transfer timelines for stealth coatings. BAE Systems' Warton facility in Lancashire anchors unmanned collaborative combat aircraft prototyping.
Germany
Luftwaffe fleet consolidation around Eurofighter and future FCAS platforms compresses procurement cycles for multirole replacements. The EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems deployed by Bundeswehr air forces. Airbus Defence and Space headquarters in Munich coordinates trilateral development with France and Spain.
Japan
Air Self-Defense Force F-X indigenous fighter development creates sovereign production pathways bypassing traditional ITAR barriers. METI defense production committee approvals govern technology co-development clauses with US primes. Mitsubishi Heavy Industries' Komaki South plant in Aichi Prefecture hosts stealth airframe fabrication for domestic and export programs.
Poland
Harpia program acceleration concentrates near-term F-35 demand for NATO interoperability certification. Ministry of National Defence offset negotiations prioritize local component manufacturing for sustainment infrastructure. Warsaw's Okęcie aerospace cluster attracts avionics subsystem suppliers serving Baltic air policing rotations.
Fighter Aircraft Market Key Industry Players
Capability concentration sits with primes holding stealth integration expertise; scale advantage sits with platforms with established sustainment networks. The vendor base stratifies across three tiers: sixth-generation system architects, mature multirole producers, and mid-tier export specialists. Consolidation pressure intensifies as development costs for manned-unmanned teaming architectures exceed single-nation funding capacity. Dominant competitive moves include cross-border joint ventures for risk-sharing and sovereign production agreements securing market access.
Within the sixth-generation system architect tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify capability concentration around low-observable platforms and advanced mission systems. Saab AB occupies a position representing mid-tier export competitiveness through Gripen variants optimized for constrained procurement budgets. These three anchors illustrate how geographic origin and platform specialization stratify competitive positioning across NATO and aligned defense markets.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| Northrop Grumman Corporation |
| Airbus SE |
| Dassault Aviation |
| BAE Systems |
| Saab AB |
| Mitsubishi Heavy Industries Ltd. |
| Leonardo S.p.A. |
| Others |
Cost & Logistics Intelligence
Dallas-Fort Worth's composite airframe manufacturing cluster concentrates titanium forging capacity and radar-absorbent material processing, translating upstream scarcity into sustained pricing power for low-observable platforms. This geographic chokepoint amplifies procurement premiums for stealth fighters while compressing margins on legacy multirole alternatives.
Pricing Analysis
Aftermarket sustainment contracts anchor lifetime value capture across the fighter aircraft value chain. Three-tier pricing structure across premium stealth platforms, standard multirole configurations, and economy trainer variants reflects certification grade and interoperability tier. Pricing pressure stems from congressional defense appropriation cycles compressing unit procurement budgets. Mid-tier export markets exhibit highest price sensitivity; NATO member states with fleet modernization mandates show lowest.
Supply Chain Analysis
Single-source vulnerability in low-observable afterburning propulsion systems concentrates among US and UK suppliers, exposing European and Asian platform integrators to delivery disruption. Titanium forging inputs draw from qualified facilities concentrated in the United States and Japan; rare earth magnet supply for avionics subsystems sources from China and Australia. Tariff exposure between the United States and China compounds ITAR licensing delays for stealth coating technology. Distribution runs through prime integrator final assembly lines with government contract execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery driven by NATO fleet modernization mandates compressing procurement cycles. Defense appropriation cycles and sixth-generation program commitments create predictable demand waves.
For Market Incumbents: Pre-empt emerging mid-tier export competitors by accelerating sovereign production agreements in Poland and Japan. Lockheed Martin's sustainment infrastructure for the F-35 platform exemplifies lifecycle value capture. Vertical integration into radar-absorbent material processing defends margin position against titanium forging bottlenecks.
For New Entrants and Emerging Players: Build out digital thread integration capabilities serving condition-based sustainment contracts for legacy multirole fleets. Poland's Harpia program and Baltic air policing rotations represent penetrable demand concentration. Partner with avionics subsystem suppliers in Warsaw's Okęcie aerospace cluster for NATO interoperability certification.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-industrial consolidation play because sixth-generation development costs exceed single-nation funding capacity. Target software-intensive subsystem providers with integrated sensor fusion expertise. Monitor Permanent Structured Cooperation framework commitments as inflection indicator for European collaborative procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Production Agreement | Japan's F-X program bypasses ITAR barriers through Mitsubishi Heavy Industries domestic fabrication. |
| Adaptive Cycle Engine Development | Pratt & Whitney flight-testing with US Air Force Research Laboratory redefines thermal management requirements. |
| Digital Thread Integration | Model-based systems engineering convergence enables predictive maintenance analytics for multi-decade sustainment. |
| Unmanned Collaborative Combat Aircraft Prototyping | BAE Systems' Warton facility anchors UK-Japan sixth-generation manned-unmanned teaming architectures. |
| EU AI Act Compliance Investment | Algorithmic transparency requirements for autonomous targeting systems reshape European software development burden. |
Research Approach
A spread of perspectives from program managers at prime integrators, procurement officers at NATO air forces, subsystem engineering leads, and congressional defense appropriations staff converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Department of Defense budget justification materials, EU Permanent Structured Cooperation framework documents, and FAA airworthiness certification databases. Bottom-up platform production estimates triangulated with top-down defense expenditure projections across the analysis window.
Demand-supply balance modeling anchored volume and value outputs across the projection horizon. Segmentation dimensions included platform type, technology tier, end-user category, and deployment mission profile. CAGRs derived from historical procurement cycle analysis and sixth-generation program commitment timelines. Forecast inputs incorporated titanium forging capacity utilization and adaptive cycle engine technology maturation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed aerospace conglomerates or accelerated AUKUS technology transfer would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Aircraft Sequencing System Market
Aircraft
India Aviation Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
US Military Aviation Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Middle-East Aviation Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Winglets Market
Aircraft
Aircraft Fairings Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Aircraft Hangar Market