
 Europe Aviation Market | 2026-2036
Europe Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aviation Market Foresight
EASA Part-145 maintenance certification is unwinding the competitive landscape for third-party MRO providers across the continent. Safran SA leverages its vertically integrated engine component supply chain to dominate aftermarket services in France and neighboring markets. Deutsche Lufthansa AG anchors a dense network of approved repair stations that sustains its technical control over Central European airspace operations.
Europe aviation encompasses the design, manufacture, operation, and servicing of fixed-wing and rotary-wing aircraft certified for civilian and dual-use operation, with turbine engines typically delivering thrust-to-weight ratios exceeding five-to-one and airframes engineered for pressurized cabin environments up to twelve kilometers altitude. Commercial Jets command the largest revenue pool among aircraft types, though UAV Systems within the technology segment are attracting disproportionate engineering investment from defense and border security buyers. Airlines remain the dominant end user category, while Ground Handling services face margin compression from airport privatization and consolidated slot allocations at hubs like Frankfurt and Amsterdam.
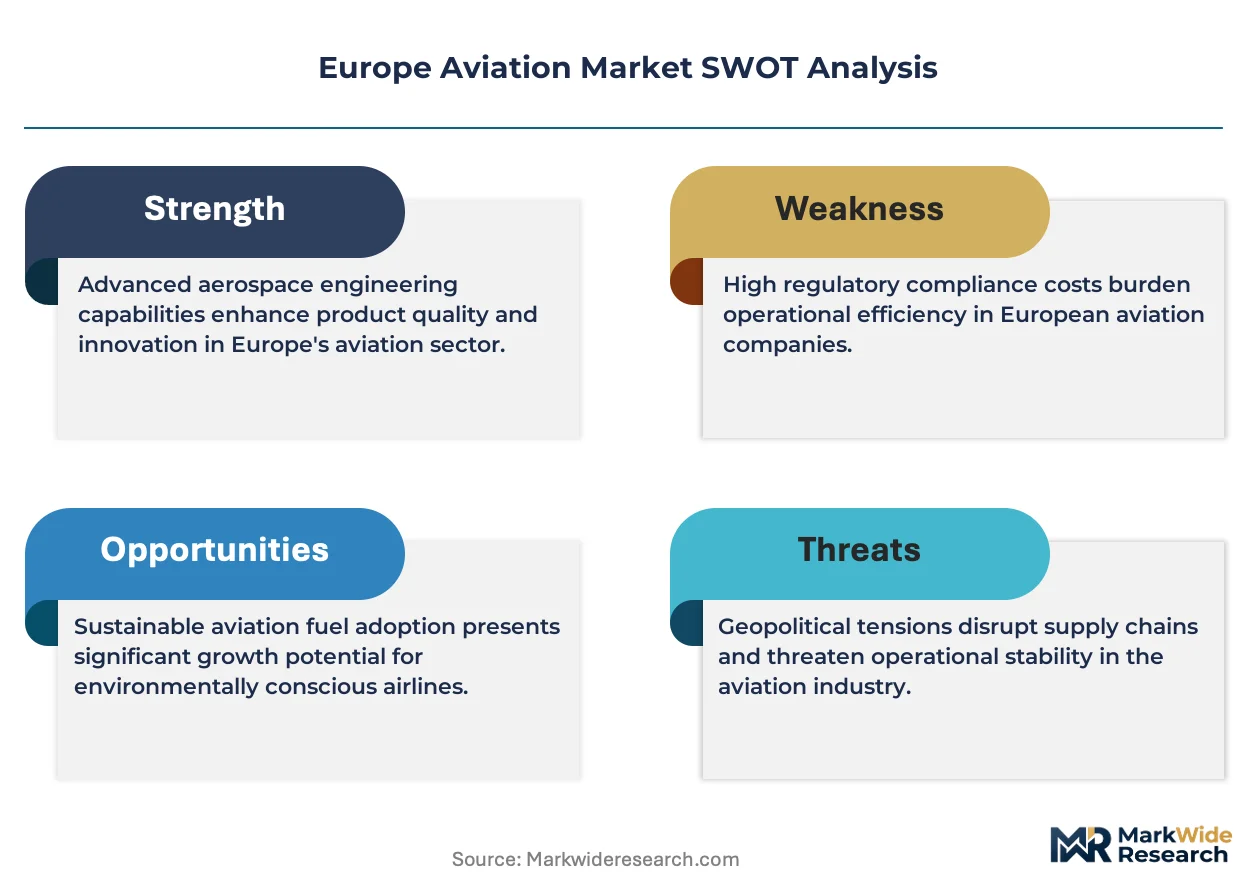
The EU Green Deal and EASA environmental certification standards are tightening CO2 and noise thresholds, forcing fleet renewal cycles and alternative propulsion R&D commitments from incumbents. REACH chemical regulations and the EU AI Act additionally govern materials sourcing and autonomous flight system validation, respectively. Stakeholders must weigh the capital intensity of hydrogen propulsion partnerships against the near-term revenue certainty of SAF retrofit programs.
Market Dynamics
The EU Green Deal's SAF mandates are compressing fleet renewal cycles while EASA Part-145 certification barriers concentrate MRO control among vertically integrated incumbents across Germany, France, and the United Kingdom.
Growth Catalysts
- EU Green Deal SAF Mandates:Binding sustainable aviation fuel quotas force airlines into retrofit programs and new aircraft procurement, expanding MRO throughput and component replacement demand.
- Low-Cost Carrier Fleet Expansion:Eastern European budget airlines are accelerating narrow-body orders to capture intra-regional traffic growth, driving aftermarket parts consumption.
- REACH Chemical Compliance:Material substitution requirements for hydraulic fluids and coatings are opening certified alternative supplier niches.
Market Restraints
- SAF Feedstock Cost Volatility:Hydrotreated esters and fatty acids compete with food and chemical sectors for lipid inputs, compressing airline fuel hedging flexibility.
- Turbine Engine OEM Concentration:Three manufacturers control 85% of narrow-body propulsion supply, limiting third-party MRO pricing leverage.
- Hydrogen Infrastructure Gap:Airport cryogenic fueling systems require capital commitments that lag aircraft development timelines by 7-10 years.
Strategic Opportunities
- Poland-Czech Republic MRO Corridor:Lower labor costs and EASA regulatory alignment attract component repair station investment away from Western hubs.
- Autonomous Flight Validation:EU AI Act certification pathways for single-pilot operations create first-mover advantages for flight control software developers.
- Used Serviceable Material Channels:Digital part traceability platforms are compressing documentation cycles for certified pre-owned components.
Industry Challenges
- Aircraft Mechanic Certification Bottlenecks:EASA Part-66 license processing delays exceed 14 months in Germany and France, constraining approved organization staffing.
- Legacy Avionics Integration Friction:Retrofitting digital flight data recorders onto 1990s-era airframes requires custom wiring harness engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aviation Market |
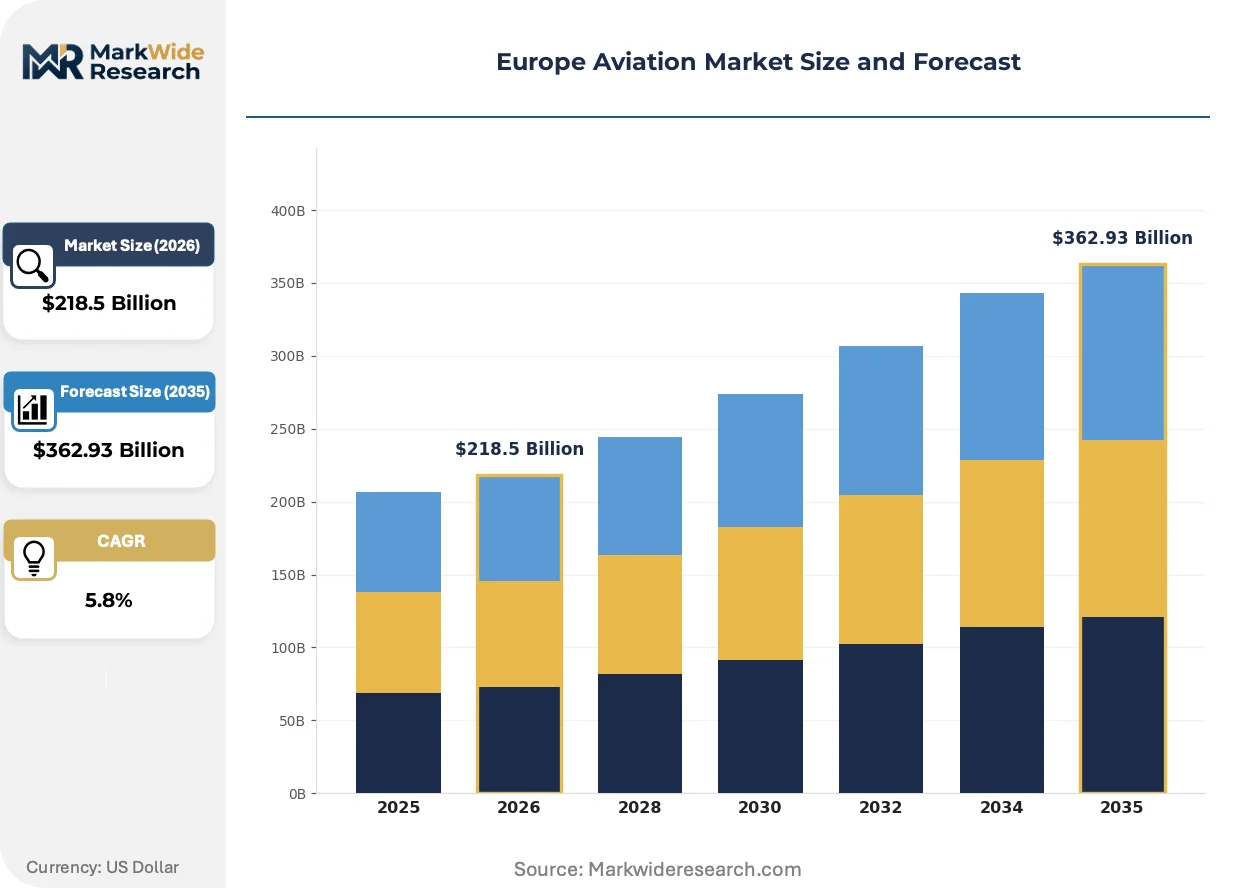
| Market Size in 2026 | $218.5 Billion |
| Market Size in 2035 | $362.93 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial Jets, Cargo Aircraft, Helicopters, Business Jets Service Type: Maintenance, Repair, Overhaul, Ground Handling End User: Airlines, Freight Forwarders, Private Owners, Charter Services Technology: Aerospace Engineering, Avionics, UAV Systems, Engine Technology |
| Companies Covered | Airbus SE, Air France KLM SA, Deutsche Lufthansa AG, BAE Systems Plc, Leonardo S.p.A., Dassault Aviation SA, Thales Group, Ryanair Holdings plc, Safran SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aviation Market Shifts & Advancements
Avionics hardware is compressing physical footprints while regulatory pressure on emissions intensifies propulsion R&D commitments. Procurement patterns among European carriers are simultaneously shifting toward power-by-the-hour service models.
Silicon carbide power electronics are replacing silicon-based motor controllers in electric taxiing systems. Ground handling operators at Amsterdam Schiphol and Frankfurt are piloting these units to cut auxiliary power unit runtime. The technology is miniaturizing thermal management hardware, enabling nose-wheel integration without structural airframe modifications.
EU AI Act validation requirements for safety-critical aviation software entered force in 2024, mandating explainability documentation for autonomous flight algorithms. Developers must submit conformity assessments to national regulators before EASA type certification. Flight control system suppliers in France and Germany are restructuring engineering workflows to accommodate iterative audit cycles.
Power-by-the-hour contracts now cover 60% of engine maintenance spend among European network carriers, transferring operational risk to OEMs and MRO integrators. Fixed-wing operators favor these arrangements over traditional time-and-material billing. Lufthansa Technik and Air France Industries have expanded dedicated asset management divisions to capture recurring revenue streams.
Europe Aviation Market Segmentation
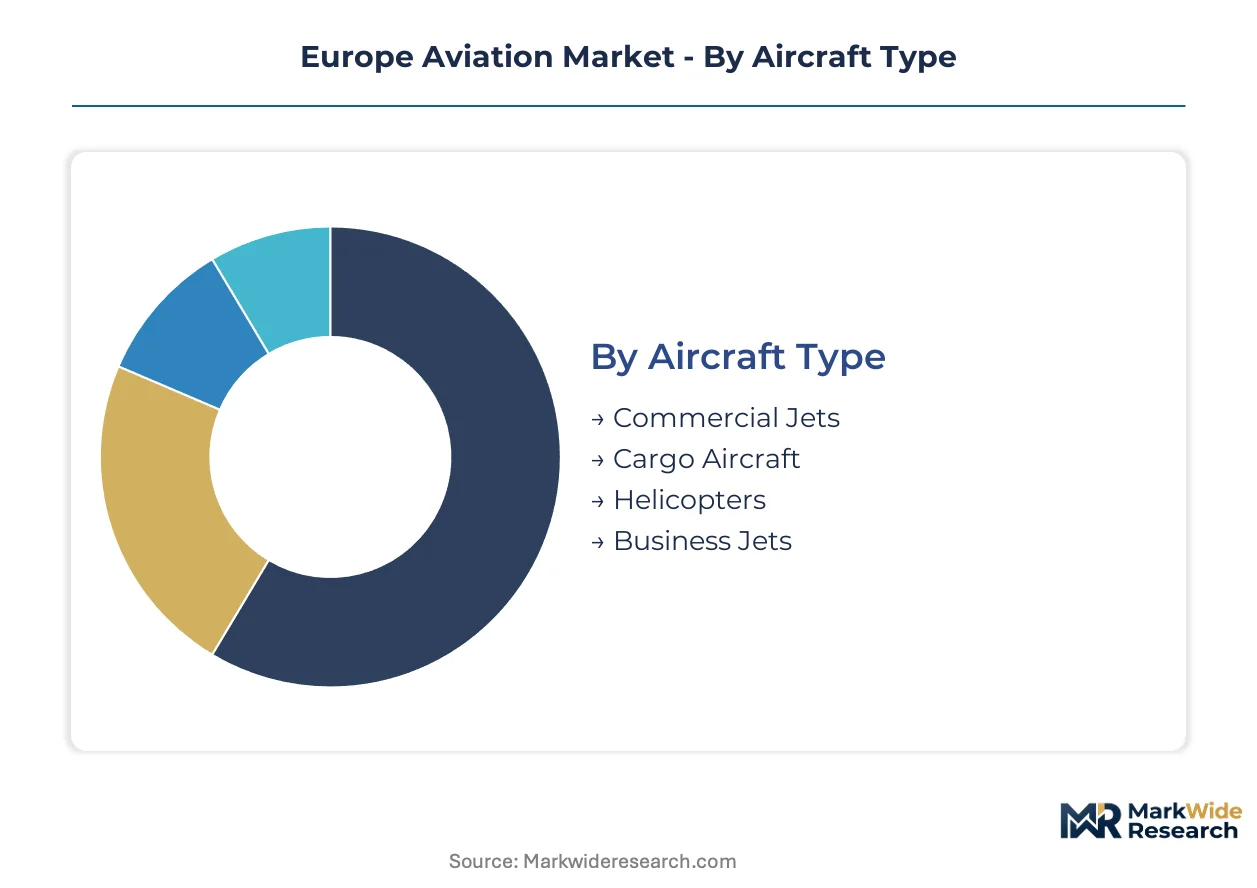
Segmentation in Europe aviation reveals how regulatory pressure and operational specialization concentrate value capture. EASA certification tiers and EU Green Deal compliance requirements create distinct competitive boundaries across aircraft categories, service models, and technology platforms.
Aircraft Type:
EASA type certification pathways differentiate airworthiness validation intensity across fixed-wing and rotary platforms, with noise and emissions thresholds tightening fastest for high-cycle commercial operations.
- Commercial Jets:Narrow-body and wide-body configurations certified for pressurized operations above ten kilometers altitude dominate fleet orders from Eastern European low-cost carriers. EASA Part-25 airworthiness mandates force continuous avionics upgrades and engine retrofit programs across Germany, France, and United Kingdom hub operations.
- Cargo Aircraft:Converted freighter fleets and factory-built dedicated cargo platforms serve e-commerce logistics networks concentrated at Leipzig, Liège, and East Midlands airports. EU Green Deal SAF mandates apply equally to cargo operators, accelerating fleet renewal timelines for aging wide-body conversions.
- Helicopters:Rotary-wing platforms certified under EASA Part-27/29 standards serve offshore energy, emergency medical, and corporate transport missions across North Sea oil fields and Alpine terrain.
- Business Jets:Light, mid-size, and long-range platforms certified for reduced crew operations connect secondary cities with limited scheduled service.
Established volume favors Commercial Jets; emerging adoption favors Cargo Aircraft as e-commerce logistics reshape intra-European air freight networks.
Service Type:
Cost tier differentiation separates capital-intensive technical services from labor-dependent ground operations, with regulatory barriers concentrating margin in certified maintenance functions.
- Maintenance:Scheduled inspections and preventive servicing governed by EASA Part-145 certification requirements sustain technical control among incumbent MRO providers. Line maintenance stations at Frankfurt, Amsterdam, and Paris-Charles de Gaulle capture highest-margin turnaround services from network carriers.
- Repair:Component-level restoration of engines, landing gear, and avionics modules requires specialized tooling investments that third-party providers struggle to replicate. Engine OEM authorized repair networks in France and Germany maintain pricing leverage through proprietary technical data access.
- Overhaul:Heavy maintenance events including C-checks and D-checks concentrate at dedicated facilities in Poland and Czech Republic where labor cost differentials offset certification compliance investments.
- Ground Handling:Aircraft marshalling, baggage processing, and fueling services face margin compression from airport privatization and consolidated slot allocations at major hubs.
Regulatory certification favors Maintenance and Repair; operational scale favors Ground Handling consolidation at privatized hub airports.
End User:
Customer type determines procurement sophistication and contract structure, with fleet scale driving power-by-the-hour adoption and small operators favoring transactional maintenance arrangements.
- Airlines:Network and low-cost carriers operating twenty-plus aircraft dominate MRO contract value, transferring operational risk to OEMs through power-by-the-hour arrangements covering sixty percent of engine maintenance spend.
- Freight Forwarders:Integrated logistics operators and cargo specialists manage dedicated freighter fleets with distinct maintenance scheduling optimized for nighttime hub operations.
- Private Owners:Individual and corporate flight departments operating single aircraft or small fleets rely on factory-authorized service centers for warranty preservation and residual value protection.
- Charter Services:On-demand and fractional operators balance fleet utilization against maintenance downtime through flexible contract structures with regional MRO providers.
Fleet scale favors Airlines; service flexibility favors Charter Services adapting to volatile demand patterns.
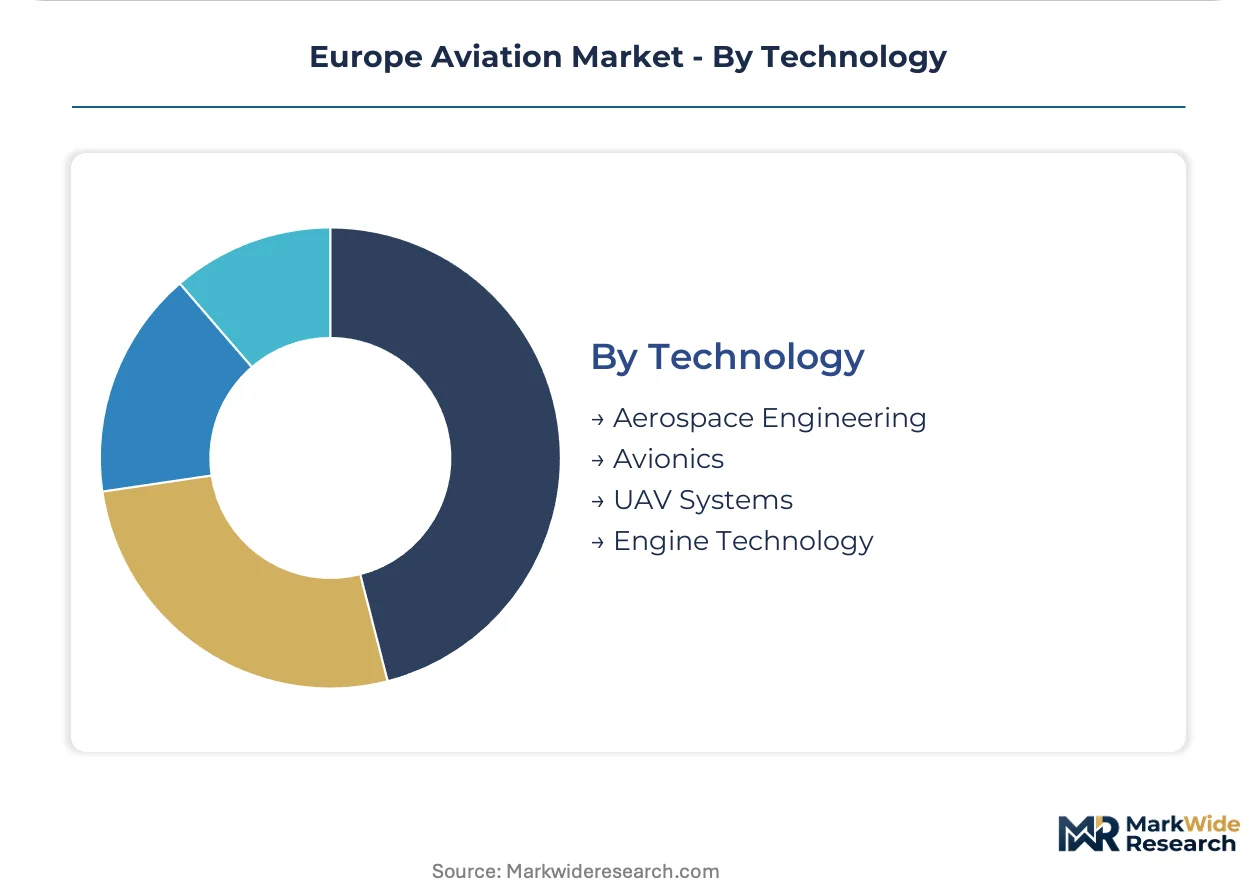
Technology:
Maturity stage separates established mechanical systems from emerging digital and autonomous platforms, with regulatory validation timelines creating distinct investment horizons.
- Aerospace Engineering:Airframe design, materials science, and structural analysis capabilities concentrate at established research clusters in Toulouse, Hamburg, and Broughton. EU funding for clean aviation initiatives channels R&D investment toward hydrogen propulsion and hybrid-electric architectures.
- Avionics:Flight control systems, navigation hardware, and cockpit displays face EU AI Act validation requirements mandating explainability documentation for autonomous functions. Silicon carbide power electronics are displacing silicon-based controllers in electric taxiing systems.
- UAV Systems:Uncrewed aerial platforms for defense, border security, and commercial inspection attract disproportionate engineering investment from European defense procurement agencies.
- Engine Technology:Turbofan propulsion systems, geared turbofans, and emerging hydrogen combustion architectures dominate OEM development budgets.
Proven revenue favors Engine Technology; steepest expansion trajectory favors UAV Systems as defense and security applications accelerate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal SAF mandates and EASA certification standards are redirecting fleet investment and MRO capacity toward regulatory-compliant jurisdictions. National aerospace clusters compete for clean aviation R&D funding and hydrogen propulsion pilot programs.
Germany
Lufthansa Technik's asset management division and Hamburg's airframe engineering cluster absorb the majority of power-by-the-hour contract value. The KBA enforces national emissions standards that align with EU Green Deal timelines. Bavaria's Munich hub concentrates narrow-body maintenance stations serving Eastern European low-cost carrier traffic.
France
Toulouse anchors Airbus manufacturing and Safran's vertically integrated engine component supply chain. ANSM and DGAC coordinate with EASA on AI Act validation for autonomous flight software. The Île-de-France corridor hosts flight control system suppliers restructuring engineering workflows for iterative audit cycles.
United Kingdom
Broughton's wing manufacturing facilities and BAE Systems' defense procurement sustain aerospace employment. The Civil Aviation Authority implements EASA-equivalent Part-145 certification for post-Brexit MRO continuity. East Midlands airport's cargo concentration attracts e-commerce freighter fleet renewal programs.
Poland
Warsaw-based maintenance stations exploit EASA regulatory alignment and labor cost differentials to capture component repair investment from Western hubs. The national aviation authority accelerates Part-66 license processing to relieve mechanic certification bottlenecks. The Poland-Czech corridor concentrates heavy maintenance events including C-checks and D-checks.
Netherlands
Amsterdam Schiphol's consolidated slot allocations and privatized ground handling operations face margin compression from airport operator fee structures. Dutch regulators enforce REACH chemical compliance for hydraulic fluid substitutions. Rotterdam-The Hague corridor hosts silicon carbide power electronics pilots for electric taxiing systems.
Europe Aviation Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and service contract structures. Three manufacturers control narrow-body propulsion supply while MRO integrators consolidate aftermarket pricing leverage. Strategic archetypes include vertically integrated OEMs, airline-captive repair networks, and independent component specialists. Competitive moves concentrate on power-by-the-hour contract expansion and geographic diversification toward lower-cost regulatory jurisdictions.
Among France-based conglomerates, Safran SA and Air France KLM SA exemplify the OEM-airline vertical integration archetype. Deutsche Lufthansa AG anchors the airline-captive MRO model through its dense network of approved repair stations. Airbus SE occupies the position of platform-scale manufacturer whose type certification pathways shape competitive boundaries for the entire supplier ecosystem.
| Leading Market Players |
|---|
| Airbus SE |
| Air France KLM SA |
| Deutsche Lufthansa AG |
| BAE Systems Plc |
| Leonardo S.p.A. |
| Dassault Aviation SA |
| Thales Group |
| Ryanair Holdings plc |
| Safran SA |
| Others |
Supply & Pricing Matrix
EASA Part-145 certification gates both supplier qualification and price differentiation across European MRO services, concentrating premium pricing power among incumbent repair stations while compressing margins for uncertified ground handlers. REACH chemical compliance and EU Green Deal SAF mandates add parallel qualification layers that segment the supply base into certified and non-certified tiers with divergent pricing trajectories.
Pricing Analysis
Certification level (EASA Part-145 versus uncertified operations) creates the primary spread between premium and standard service tiers across European aviation maintenance. Three-tier pricing structure across OEM-authorized, independent certified, and non-certified service levels reflects technical data access, tooling investment, and liability coverage differentials. Pricing pressure stems from low-cost carrier procurement teams consolidating MRO spend into fewer, larger power-by-the-hour contracts. Charter operators and private owners exhibit highest price sensitivity due to unhedged maintenance exposure, while network carriers prioritize operational reliability over unit cost minimization.
Supply Chain Analysis
Inventory lead times for turbine engine components extend 6-12 months due to single-source forging and casting dependencies concentrated in Germany, France, and the United Kingdom. Raw material supply draws from specialized nickel superalloy producers, precision casting foundries, and silicon carbide semiconductor fabricators serving electric taxiing system manufacturers. Single-source vulnerability pervades proprietary engine part technical data controlled by Safran and Rolls-Royce authorized networks. Distribution runs through OEM-captive channels for critical rotating components and independent distributors for standard hardware and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Eastern European low-cost carriers consolidating fleet orders into volume-based MRO negotiations, fragmenting pricing leverage previously held by Western European network carriers. This shift demands differentiated strategic responses across incumbent, entrant, and investor archetypes.
For Market Incumbents: Consolidate component repair station networks in Poland and Czech Republic to capture labor cost arbitrage while maintaining EASA certification compliance. Deepen backward integration into used serviceable material sourcing through digital traceability platform investments. Defensive positioning requires preemptive capacity commitment before low-cost carrier procurement teams finalize multi-year power-by-the-hour tenders.
For New Entrants and Emerging Players: Anchor in autonomous flight validation services where EU AI Act certification pathways remain underdeveloped and incumbent engineering workflows lag iterative audit cycle demands. Target Poland-Czech Republic heavy maintenance corridor where mechanic certification bottlenecks constrain incumbent staffing and create service capacity gaps. Go-to-market leverage rests on accelerated Part-66 license processing partnerships with national aviation authorities.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward flight control software developers with existing EASA conformity assessment relationships. Five-to-ten year viability favors asset-light validation service providers over capital-intensive hydrogen infrastructure plays. Acquisition target archetype: mid-cap avionics specialists with EU AI Act documentation capabilities and established national regulator access. Signal to watch: EASA publication of single-pilot operation certification timelines as autonomous flight demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Retrofit Program Commitment | Binding EU Green Deal quotas force fleet renewal cycles and expand MRO throughput at Lufthansa Technik and Air France Industries. |
| Poland-Czech MRO Corridor Expansion | Lower labor costs and EASA regulatory alignment attract component repair investment away from Frankfurt and Amsterdam hubs. |
| EU AI Act Validation Partnership | Flight control suppliers in Toulouse and Hamburg restructure engineering workflows for iterative audit cycle compliance. |
| Used Serviceable Material Platform Launch | Digital part traceability compresses documentation cycles for certified pre-owned components in engine overhaul networks. |
| Hydrogen Propulsion R&D Consortium | Clean aviation initiative funding channels investment toward Hamburg and Toulouse research clusters for combustion architecture development. |
Research Methodology
Initial hypotheses were tested against primary input from MRO operations directors, fleet procurement managers, EASA certification specialists, and airline technical planning officers and refined through secondary validation. Primary fieldwork combined structured interviews with maintenance station heads at Frankfurt, Amsterdam, and Warsaw hubs alongside regulatory affairs consultations with ANSM and KBA representatives. Secondary sources encompassed EASA type certification databases, EU Green Deal implementation trackers, REACH chemical registration filings, and airline fleet order disclosures. Bottom-up triangulation across individual service contract values and top-down reconciliation against aggregate MRO spend estimates anchored volume and value outputs.
Variance decomposition across the projection horizon isolates growth contributions from fleet expansion, regulatory-driven retrofit cycles, and power-by-the-hour contract penetration shifts. Segmentation dimensions modeled include aircraft type (commercial jets, cargo platforms, helicopters, business jets), service tier (maintenance, repair, overhaul, ground handling), end-user scale (network carriers, low-cost operators, freight forwarders, private owners), and technology maturity (established propulsion, emerging avionics, autonomous systems). CAGRs derive from logistic diffusion curves fitted to SAF mandate compliance timelines and narrow-body delivery schedules. Industry-specific inputs incorporate EASA Part-66 license processing rates and REACH chemical substitution lead times.
Material uncertainties — SAF feedstock cost volatility, hydrogen infrastructure capital commitment delays, and EASA AI Act validation timeline revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and OEM technical data sharing practices. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
US Military Aviation Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Afterburner Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Light and Very Light Jets Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Aero Wing Market
Aircraft
Global Electronic Flight Bag Market