
 Cargo Compartment Latches Market | 2026-2036
Cargo Compartment Latches Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Compartment Latches Market Analytics
Aftermarket lifecycle service contracts is decoupling hardware sales from pure unit economics in the cargo compartment latches sector. Adams Rite Aerospace leverages its aerospace pedigree to dominate MRO channel relationships. Kiekert AG anchors European automotive latch supply through captive engineering partnerships. Magna International Inc. extends manufacturing scale across multiple latch categories and geographies.
Cargo compartment latches are mechanical fastening devices engineered to secure enclosed storage volumes against vibration, pressure differentials, and unauthorized access, typically manufactured from hardened steel or aluminum alloys with specified load ratings exceeding operational failure thresholds. Their primary purpose spans commercial transportation equipment, industrial enclosures, and military logistics containers where positive retention under dynamic stress prevents cargo shift and maintains seal integrity. Rotary latches command the largest revenue pool in aerospace applications where redundant locking satisfies fail-safe requirements, while electronic locks represent the fastest-expanding segment as fleet operators adopt keyless entry protocols. Steel retains dominance in heavy-duty industrial and marine environments where corrosion resistance and impact tolerance justify weight penalties against aluminum alternatives.
FAA airworthiness standards and EASA CS-25 certification frameworks mandate redundant latch mechanisms for commercial aircraft cargo compartments, directly elevating engineering validation costs and OEM qualification timelines. NHTSA FMVSS 206 and equivalent UN ECE regulations govern automotive trunk and cargo door retention, forcing suppliers to maintain dual certification portfolios for cross-border vehicle programs. Stakeholders must monitor evolving cybersecurity standards for electronic locking interfaces as connected vehicle architectures expose cargo access systems to remote intrusion vectors.
Market Dynamics
Aftermarket lifecycle service contracts are decoupling hardware sales from pure unit economics, forcing suppliers to build recurring revenue streams through MRO channel relationships rather than transactional component sales.
Growth Catalysts
- FAA airworthiness directives:Mandates for redundant latch mechanisms in commercial aircraft cargo compartments elevate engineering standards and create sustained replacement demand across aging fleets.
- Automotive lightweighting:Aluminum alloy adoption in electric vehicle cargo systems drives material substitution cycles and new qualification programs for tier suppliers.
- German precision manufacturing clusters:Concentrated OEM and tier supplier ecosystems in Baden-Württemberg and Bavaria anchor specialized production capacity and captive engineering partnerships.
Market Restraints
- Specialized steel alloy volatility:Hardened steel input costs fluctuate with energy-intensive smelting operations, compressing margin buffers for heavy-duty industrial latch manufacturers.
- Single-source certification dependencies:EASA CS-25 qualification timelines stretch 18-24 months, freezing supplier switching and locking incumbents into rigid production schedules.
- Electronic lock substitution:Keyless entry protocols in premium automotive segments displace mechanical rotary latches in trunk and cargo applications.
Strategic Opportunities
- India commercial aviation expansion:IndiGo and Air India fleet growth creates greenfield MRO infrastructure demand for certified latch suppliers establishing local presence.
- Cybersecurity-mandated electronic interfaces:UN ECE regulations on connected vehicle access systems open retrofit markets for encrypted locking modules in existing logistics fleets.
- Digital twin integration:Predictive maintenance algorithms converging with IoT sensor networks enable condition-based latch replacement contracts in maritime container operations.
Industry Challenges
- Aerospace welding certification scarcity:Qualified technicians for titanium and Inconel latch fabrication remain concentrated in France and the United States, constraining capacity expansion.
- Legacy fleet interoperability:Boeing 737 NG and A320ceo maintenance programs require reverse-engineered spare compatibility, fragmenting inventory and complicating supply chain rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Compartment Latches Market |
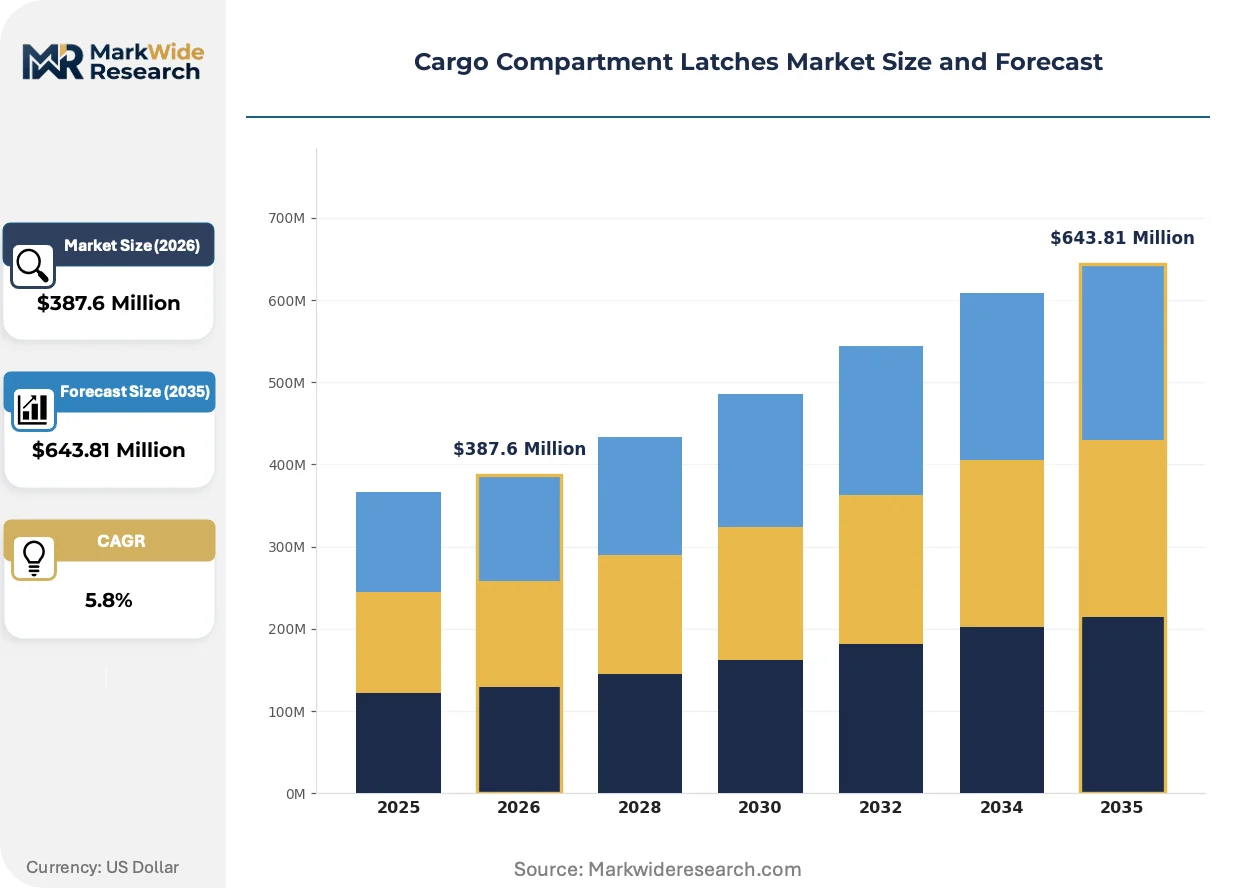
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Latches, Slide Latches, Cam Latches, Hook Latches Material: Steel, Aluminum, Plastic, Composite Application: Automotive, Aerospace, Marine, Industrial Locking Mechanism: Keyed Locks, Electronic Locks, Push Button, None |
| Companies Covered | Adams Rite Aerospace, Kiekert AG, Magna International Inc., Aisin Corporation, Mitsui Kinzoku ACT Corp., Brose Fahrzeugteile GmbH & Co. KG, Inteva Products, Strattec Security Corporation, U-Shin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Compartment Latches Market Evolving Landscape
Electronic actuation and connected monitoring systems are displacing purely mechanical designs across transportation equipment, creating new competitive battlegrounds around firmware security and predictive analytics capabilities.
Smart latch systems with integrated position sensors and CAN bus connectivity are electrifying cargo access control in commercial vehicles. Fleet operators at DHL and FedEx ground operations are piloting keyless entry protocols at scale. This convergence of mechanical hardware with digital authentication layers is electrifying traditional supplier relationships and compressing hardware margins while expanding software service attach rates.
REACH substance restrictions on hexavalent chromium coatings are forcing surface treatment conversions across European supply chains. Automotive and aerospace suppliers must retool plating lines to trivalent alternatives or zinc-nickel alloys. German tier suppliers face the steepest compliance curves as KBA type-approval deadlines accelerate qualification requirements for trunk and cargo door latches.
Airlines are unbundling component-level maintenance from airframe heavy checks, creating direct procurement relationships with latch specialists outside traditional OEM captive structures. Lufthansa Technik and ST Engineering have established dedicated cargo systems divisions sourcing latches independently. This channel disintermediation concentrates most visibly in Singapore and Germany where MRO infrastructure density supports specialized supplier ecosystems.
Cargo Compartment Latches Market Segmentation
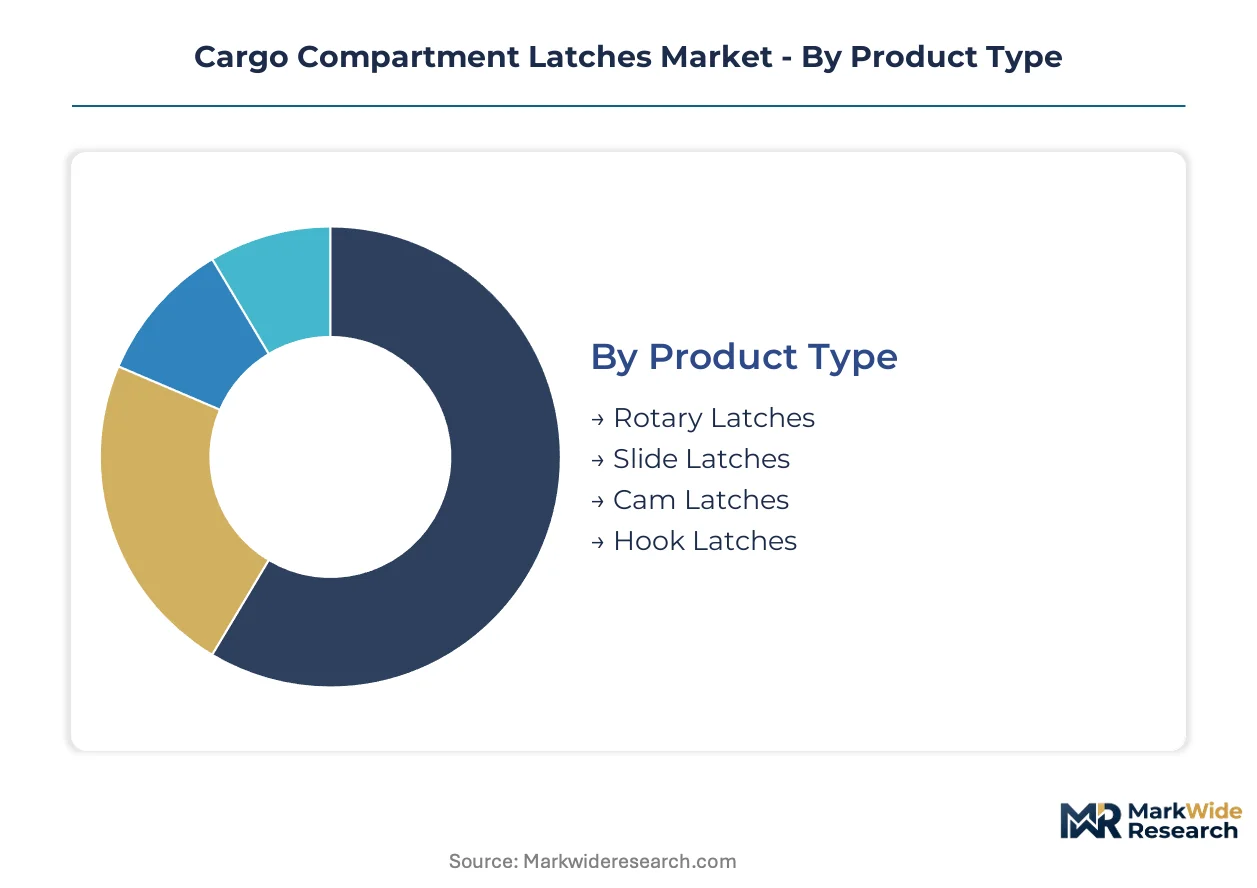
Segmentation in cargo compartment latches reflects divergent engineering requirements across transportation modes. Material selection and locking complexity vary sharply between aerospace certification demands and automotive cost optimization targets.
Product Type:
Standardization dominates rotary and slide mechanisms for high-volume automotive programs, while cam and hook variants retain customization for specialized industrial enclosures.
- Rotary Latches:Dual-pawl mechanisms with redundant engagement points satisfy FAA fail-safe mandates for commercial aircraft cargo compartments. Boeing and Airbus platforms in Germany and France anchor replacement demand as fleet operators extend service intervals.
- Slide Latches:Linear actuation systems with integrated striker plates optimize trunk closure dynamics in electric vehicle architectures. German automotive OEMs in Baden-Württemberg specify these for aluminum-intensive body structures where mass reduction overrides legacy steel designs.
- Cam Latches:Quarter-turn compression seals serve maritime container applications requiring watertight integrity under dynamic loading.
- Hook Latches:Over-center retention mechanisms secure industrial enclosures with high vibration tolerance.
Most installed capacity flows through rotary latches. Expansion is steepest in slide latches.
Material:
Cost tiers separate commodity inputs from performance-grade alloys requiring specialized heat treatment and surface engineering.
- Steel:Hardened alloy grades with zinc-nickel plating withstand impact loading in heavy-duty logistics containers. REACH substance restrictions on hexavalent chromium coatings are forcing European suppliers to retool plating lines, compressing margin buffers for tier manufacturers.
- Aluminum:6061-T6 and 7075-T6 extrusions with hard anodize finishes serve aerospace weight-critical applications. Indian commercial aviation expansion at IndiGo and Air India drives qualification programs for locally sourced aluminum latch forgings.
- Plastic:Glass-reinforced polyamide compounds reduce cost in light-duty automotive interior compartments.
- Composite:Carbon fiber reinforced polymers enable extreme weight reduction in racing and premium electric vehicle programs.
Steel retains the largest installed base. Aluminum is gaining share fastest.
Application:
Customer type determines certification burden and procurement channel structure across transportation equipment segments.
- Automotive:Trunk and cargo door retention systems governed by NHTSA FMVSS 206 and UN ECE regulations. German KBA type-approval deadlines accelerate qualification requirements for electronic locking modules in connected vehicle architectures.
- Aerospace:EASA CS-25 and FAA airworthiness directives mandate redundant mechanisms with 18-24 month qualification timelines. Singapore and Germany concentrate MRO infrastructure density supporting specialized supplier ecosystems outside traditional OEM captive structures.
- Marine:Salt spray corrosion resistance specifications dominate material selection for deck and hold applications.
- Industrial:Custom enclosure integration with lower regulatory barriers enables shorter design cycles.
Aerospace commands the highest unit margins. Automotive delivers the largest volume throughput.
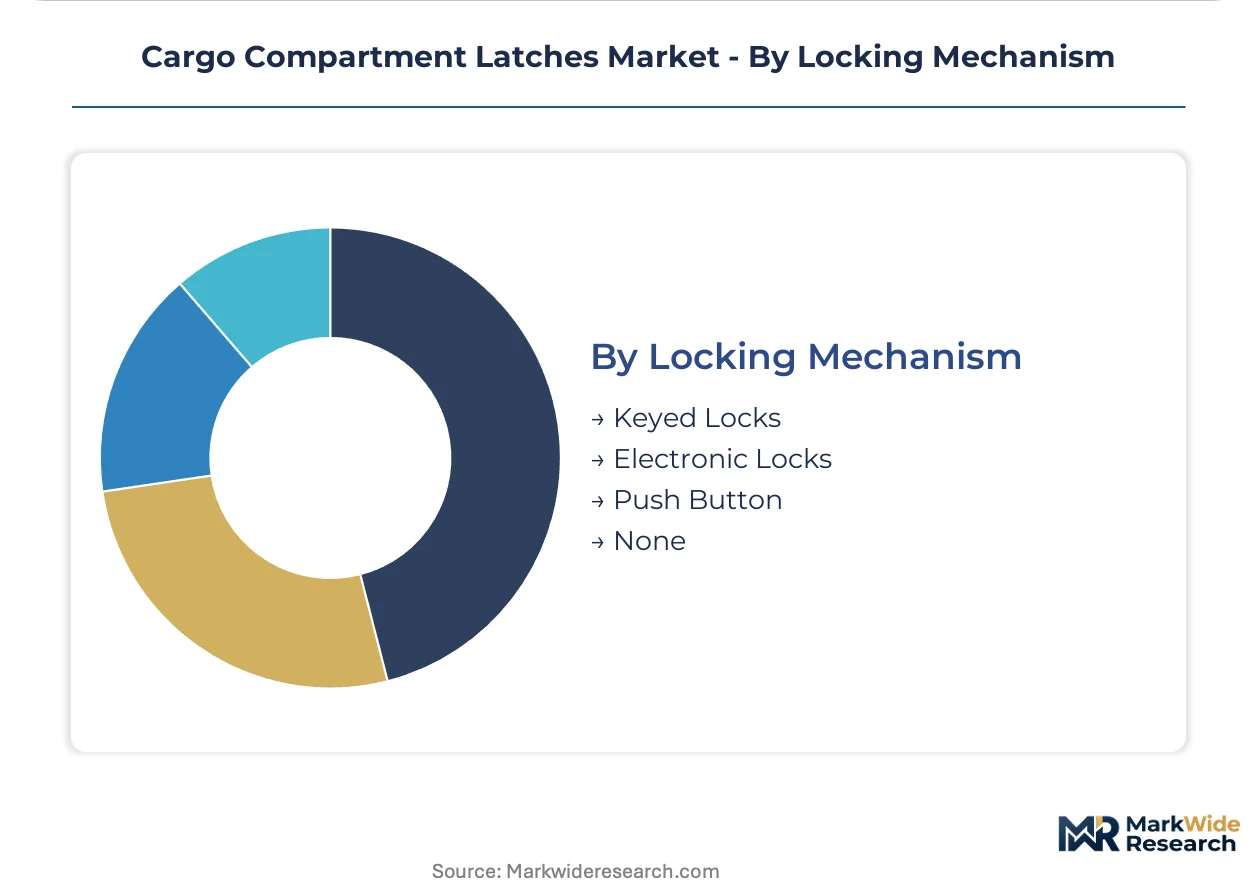
Locking Mechanism:
Maturity gradients separate established mechanical designs from emerging electronic interfaces requiring cybersecurity validation.
- Keyed Locks:Cylindrical and dimple key systems remain standard for fleet vehicles and rental equipment where physical key control satisfies insurance requirements. Legacy interoperability demands for Boeing 737 NG and A320ceo maintenance programs sustain aftermarket demand.
- Electronic Locks:Encrypted CAN bus interfaces with biometric or smartphone authentication enable keyless entry protocols. UN ECE regulations on connected vehicle access systems open retrofit markets for encrypted modules in existing logistics fleets at DHL and FedEx ground operations.
- Push Button:Spring-loaded release mechanisms serve interior automotive compartments with low security requirements.
- None:Pure retention latches without active locking for industrial enclosures with separate security systems.
Keyed locks dominate current installations. Electronic locks show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier geography as EASA CS-25 qualification timelines stretch 18-24 months, pushing some production toward jurisdictions with faster certification pathways while aerospace-grade welding expertise remains concentrated in established clusters.
United States
FAA airworthiness directives for redundant cargo compartment mechanisms sustain replacement demand across aging commercial fleets. Boeing 737 NG and A320ceo maintenance programs require reverse-engineered spare compatibility, fragmenting inventory across MRO networks. Qualified technicians for titanium and Inconel latch fabrication concentrate in Seattle and Wichita, constraining capacity expansion despite fleet growth.
Germany
Baden-Württemberg and Bavaria anchor precision manufacturing clusters where automotive OEMs and tier suppliers drive captive engineering partnerships. KBA type-approval deadlines accelerate qualification requirements for electronic locking modules in connected vehicle architectures. REACH substance restrictions on hexavalent chromium coatings force surface treatment conversions across plating lines serving trunk and cargo door latch programs.
France
Airbus platform manufacturing in Toulouse anchors aerospace latch demand for rotary mechanisms with redundant locking. EASA certification frameworks mandate fail-safe engineering validation that elevates OEM qualification costs. Qualified aerospace welding technicians for specialized alloys remain concentrated in the Occitanie region, creating supply bottlenecks for capacity expansion.
India
IndiGo and Air India fleet expansion creates greenfield MRO infrastructure demand for certified latch suppliers establishing local presence. BIS standards and DGFT import regulations shape qualification pathways for aluminum forgings sourced domestically. Karnataka and Maharashtra industrial corridors attract tier suppliers seeking proximity to emerging aviation maintenance hubs in Hyderabad and Mumbai.
Singapore
ST Engineering and Lufthansa Technik have established dedicated cargo systems divisions sourcing latches independently from traditional OEM captive structures. Channel disintermediation concentrates where MRO infrastructure density supports specialized supplier ecosystems. Maritime container operations at the Port of Singapore drive demand for cam latch mechanisms with salt spray corrosion resistance specifications.
Cargo Compartment Latches Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace qualification barriers protecting incumbent positions while automotive volume programs favor scale-driven fabricators. The vendor base organizes around three archetypes: heritage aerospace specialists with MRO channel dominance, European automotive tier suppliers with captive OEM relationships, and diversified industrial conglomerates extending manufacturing scale across multiple latch categories. Consolidation pressure operates through strategic partnerships for electronic lock cybersecurity validation and geographic expansion into Indian aviation MRO infrastructure.
Among heritage aerospace specialists, Adams Rite Aerospace exemplifies the MRO-channel archetype through its established pedigree in airworthiness-certified mechanisms. Kiekert AG and Magna International Inc. occupy positions within the European automotive supply tier, with Kiekert representing the engineering-partnership model and Magna exemplifying diversified manufacturing scale across multiple product categories and geographies.
| Leading Market Players |
|---|
| Adams Rite Aerospace |
| Kiekert AG |
| Magna International Inc. |
| Aisin Corporation |
| Mitsui Kinzoku ACT Corp. |
| Brose Fahrzeugteile GmbH & Co. KG |
| Inteva Products |
| Strattec Security Corporation |
| U-Shin Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EASA CS-25 aerospace mechanisms and commodity automotive latches manifests in pricing power concentration among German and French qualified suppliers, while cost-optimized slide latch programs for electric vehicles flow through scale-driven Asian manufacturing partnerships. This tier divergence locks premium margins to 18-24 month qualification timelines while compressing standard-tier pricing through volume consolidation.
Pricing Analysis
Distributor margins on aerospace-certified rotary latches run 15-25 points above direct-to-OEM automotive contracts due to MRO channel fragmentation and legacy fleet interoperability demands. Three-tier pricing structure across aerospace-grade, automotive-OEM, and aftermarket-standard levels separates EASA-qualified titanium mechanisms from aluminum trunk latches and steel industrial variants. Cost compression in automotive slide latches is intensifying because OEMs are consolidating supplier panels for electric vehicle platform standardization. Fleet operators at DHL and FedEx ground operations show lowest price sensitivity for encrypted electronic modules, while rental equipment buyers of keyed mechanical systems negotiate hardest on unit economics.
Supply Chain Analysis
EASA and FAA qualification gating concentrates aerospace-grade welding capacity in France, Germany, and the United States, freezing supplier switching and anchoring premium-tier production in Occitanie and Baden-Württemberg clusters. Raw material flows draw from hardened steel alloy mills in Germany, aluminum forging operations in India, and zinc-nickel plating facilities transitioning from hexavalent chromium under REACH deadlines. Single-source certification vulnerability persists where qualified technicians for titanium and Inconel fabrication remain geographically concentrated. Distribution runs through OEM captive structures for automotive volume programs and independent MRO channels for aerospace aftermarket, with channel disintermediation accelerating in Singapore and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cargo compartment latches rests on aftermarket service contract penetration and electronic lock module attach rates, with aluminum substitution in electric vehicles and predictive maintenance algorithms creating premium-tier pricing power.
For Market Incumbents: To counter electronic lock substitution in premium automotive segments, deepen MRO channel control through predictive maintenance algorithm integration and secure aerospace welding capacity expansion in France and Germany. Certification investment in UN ECE cybersecurity standards for connected vehicle interfaces protects pricing power against software-centric entrants. For New Entrants and Emerging Players: Begin with greenfield MRO infrastructure partnerships in India, where IndiGo and Air India fleet growth outpaces qualified supplier presence. Target maritime container digital twin integration as the most penetrable smart latch application, with condition-based replacement contracts offering recurring revenue outside OEM captive structures. For Investors and Strategic Acquirers: Consolidation pressure builds where electronic lock cybersecurity validation requires firmware capabilities absent from legacy mechanical specialists. Long-term viability favors suppliers with dual aerospace-automotive certification portfolios and software service attach rates. The signal to watch is airline unbundling of component-level maintenance from airframe heavy checks, which accelerates channel disintermediation and concentrates value in independent latch specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | UN ECE regulation compliance opens encrypted module retrofit markets at DHL and FedEx. |
| Indian MRO Infrastructure Partnership | Local presence captures IndiGo and Air India fleet expansion before incumbent qualification. |
| Predictive Maintenance Algorithm Development | IoT sensor integration enables condition-based replacement contracts in maritime container operations. |
| Surface Treatment Line Retooling | Trivalent chromium and zinc-nickel conversion satisfies REACH deadlines for German KBA type-approval. |
| Aerospace Welding Capacity Expansion | Titanium and Inconel technician pools in France and Germany constrain competitor replication. |
Research Methodology
Multiple input streams — executive interviews with aerospace MRO procurement directors, automotive Tier 1 supplier engineering leads, and maritime container fleet operators; regulatory filings from EASA, FAA, and UN ECE; and trade data on hardened steel and aluminum alloy flows — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K disclosures of diversified industrial conglomerates, German KBA type-approval databases, and REACH compliance documentation from surface treatment suppliers.
Data-stream reconciliation anchored volume and value outputs to product type, material grade, application segment, and locking mechanism complexity across the projection horizon. CAGRs were derived from segment-level growth rate convergence analysis. Modeled inputs included airline fleet retirement schedules, electric vehicle platform standardization timelines, and MRO infrastructure investment patterns in India and Singapore.
Several conditions sit outside the modeled scope, including sudden shifts in FAA airworthiness directive enforcement, automotive OEM insolvency events, and trade policy changes affecting aluminum alloy tariffs. Forecasts reflect assumptions about certification timeline stability and qualified technician pool expansion. A model refresh is warranted upon material change in EASA CS-25 qualification backlog or cybersecurity regulation implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Business Jets Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Commercial Helicopter Market
Aircraft
Aircraft Strut Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Aircraft Door Market
Aircraft
Medium and Heavy-Lift Helicopters Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Europe Aviation Market
Aircraft
Flight Management Systems Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market