
 Aerospace and Defense Fuel Market | 2026-2036
Aerospace and Defense Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Fuel Market Outlook
The split between conventional jet fuel and sustainable aviation alternatives is rebalancing procurement budgets across military and commercial buyers. Exxon Mobil Corporation leverages its integrated refining network to sustain long-term defense contracts. Shell plc anchors its position through specialized marine and aviation supply chains that span multiple NATO logistics hubs.
Aerospace and defense fuel encompasses refined petroleum products and synthetic alternatives formulated to meet strict energy density, freeze point, and thermal stability specifications required for turbine engines operating at altitude. Jet fuel, avgas, and biofuel each serve distinct propulsion architectures, with jet fuel dominating volume due to its use in both commercial turbofans and military gas turbines. Military aviation applications command premium pricing structures because of specialized JP-8 and JP-5 formulations with enhanced thermal oxidative stability and corrosion inhibitors. Government agencies represent the most concentrated end-user segment, consolidating procurement through national strategic petroleum reserves and direct supply agreements that bypass reseller channels.
EPA regulations govern U.S. fuel emissions profiles while the EU Green Deal mandates progressive blending thresholds for sustainable aviation fuel. FERC oversees interstate pipeline tariffs that shape distribution economics for defense fuel depots. Stakeholders must monitor how evolving carbon border adjustments and military decarbonization targets reshape long-term offtake agreements and refinery investment horizons.
Market Dynamics
The EU Green Deal's SAF blending mandates are forcing a bifurcation in refinery investment, splitting capital between conventional jet fuel infrastructure and synthetic fuel production pathways. Defense procurement agencies now face dual-sourcing requirements that complicate long-term supply agreements.
Growth Catalysts
- NATO Defense Spending Commitments:Member states are accelerating military aviation procurement, expanding jet fuel offtake through national strategic petroleum reserves and direct supply agreements.
- EU Green Deal SAF Mandates:Progressive blending thresholds are restructuring refinery output requirements and creating guaranteed demand pools for sustainable aviation fuel producers.
- Power-to-Liquid Synthesis:Fischer-Tropsch and alcohol-to-jet pathways are achieving certification parity with conventional jet fuel, unlocking military specification compliance for synthetic alternatives.
Market Restraints
- Crude Price Volatility:Feedstock cost swings compress refining margins and destabilize long-term defense fuel contract pricing structures.
- Refinery Concentration:Gulf Coast processing capacity dominates US military supply, creating geographic single-point vulnerabilities for Pentagon logistics.
- ASTM Certification Timelines:Extended approval cycles for novel synthetic pathways delay commercial deployment of next-generation fuels.
Strategic Opportunities
- India Defense Modernization:The Indian Air Force's fighter fleet expansion creates new demand centers for JP-8 equivalent formulations and strategic fuel storage infrastructure.
- Waste Feedstock Pathways:Municipal solid waste and agricultural residue conversion technologies open circular economy positioning for refiners seeking carbon intensity reductions.
- Direct Air Capture Integration:Carbon capture-to-fuel synthesis offers defense agencies pathway to carbon-neutral mission profiles without fleet re-engining.
Industry Challenges
- Synthetic Fuel Chemist Scarcity:Specialized expertise in catalytic upgrading and hydroprocessing remains concentrated at legacy petroleum research centers, constraining SAF scale-up.
- Pipeline Infrastructure Retrofit:Existing distribution networks require material compatibility upgrades to handle aggressive oxygenate and aromatic profiles of bio-derived fuels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Fuel Market |
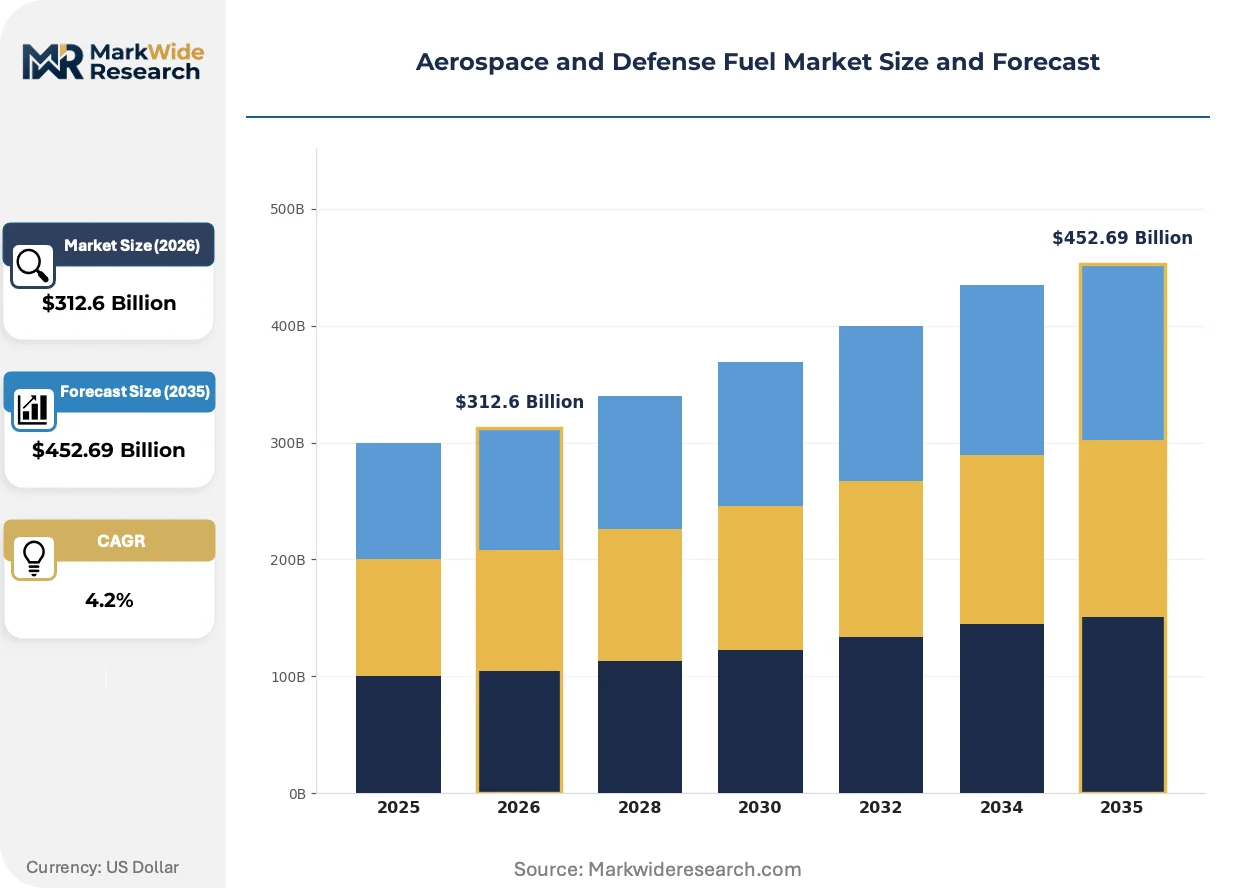
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $452.69 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet Fuel, Avgas, Biofuel, Diesel Application: Aerospace, Military Aviation, Commercial Flights, Defense Operations End User: Government Agencies, Defense Contractors, Commercial Airlines, Private Aviation Distribution Channel: Direct Supply, Resellers, Online Platforms, Fuel Depots |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, BP p.l.c., Shell plc, TotalEnergies SE, Valero Energy Corporation, Indian Oil Corporation Ltd., Phillips 66, Repsol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Fuel Market Strategic Shifts
Synthetic fuel production pathways are compressing the traditional petroleum value chain, enabling point-source fuel generation at military installations and reducing strategic supply vulnerabilities.
Hydroprocessed esters and fatty acids (HEFA) technology converts waste oils and animal fats into drop-in jet fuel with identical performance characteristics to petroleum-derived kerosene. Military logistics commands are adopting HEFA blends for non-combat training missions to accumulate operational data. Synthetic paraffinic kerosene is overtaking conventional refining as the preferred investment pathway for NATO-aligned energy security planning.
The EU Green Deal's ReFuelEU Aviation regulation imposes binding SAF blending obligations rising from two percent in 2025 to seventy percent by 2050. Refiners must reconfigure hydrocracker units and construct standalone biorefineries to meet mandated volumes. European defense procurement agencies are negotiating cost-pass-through mechanisms to absorb premium pricing without compromising mission readiness.
Defense fuel buyers are consolidating purchasing through multi-year offtake agreements that bypass spot market exposure and secure priority allocation during supply disruptions. The US Defense Logistics Agency's single-buyer model is displacing fragmented base-level contracting across NATO allied nations. Germany and France are establishing comparable centralized procurement entities to leverage volume discounts and standardize quality specifications.
Aerospace and Defense Fuel Market Segmentation
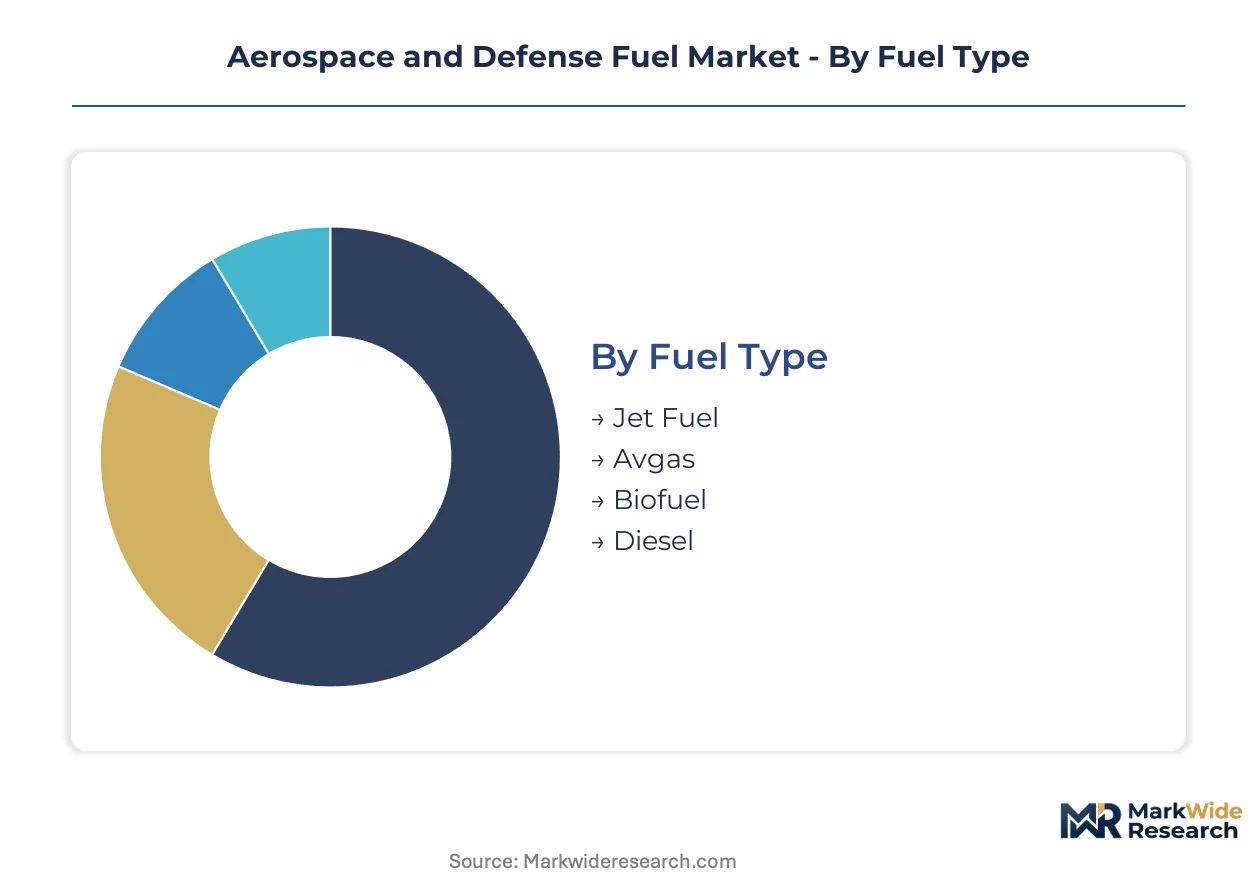
Fuel specifications vary dramatically across aerospace and defense applications, with each segment demanding distinct capital commitments for storage infrastructure, quality certification, and supply security. Procurement patterns diverge sharply between military buyers seeking strategic reserves and commercial operators optimizing for unit economics.
Fuel Type:
Jet fuel infrastructure demands the heaviest upfront investment due to cryogenic storage requirements and multi-billion-dollar refinery hydrocracker units, while biofuel pathways require parallel capital deployment for feedstock preprocessing and catalytic upgrading systems.
- Jet Fuel:Refined kerosene formulations meeting strict energy density and freeze-point specifications for turbine engines operating at altitude. Demand concentrates in the United States where the Department of Defense maintains the world's largest procurement program, driven by NATO defense spending acceleration and strategic petroleum reserve commitments.
- Avgas:High-octane aviation gasoline formulated for piston-engine aircraft with leaded and unleaded variants certified by ASTM D910. Demand clusters in private aviation and flight training sectors across Germany and France, constrained by EPA phase-out timelines for tetraethyl lead formulations and certification delays for replacement fuels.
- Biofuel:Hydroprocessed esters and fatty acids (HEFA) and Fischer-Tropsch synthetic paraffinic kerosene achieving drop-in certification parity with conventional jet fuel. EU Green Deal mandates are restructuring refinery output requirements toward these pathways.
- Diesel:Military-grade distillate fuels including F-76 marine diesel and ground vehicle applications with enhanced thermal stability and corrosion inhibitors. Defense logistics commands in India and the United Kingdom anchor procurement volumes for naval and armored vehicle fleets.
Jet fuel absorbs the bulk of installed capacity; biofuel is expanding most quickly.
Application:
Volume flows concentrate in aerospace applications where flight frequency and fleet size determine offtake scale, while defense operations command premium pricing structures due to specialized formulation requirements and strategic reserve mandates.
- Aerospace:Commercial turbofan and regional jet operations consuming conventional and sustainable aviation fuel blends across international route networks. EU Green Deal ReFuelEU Aviation regulation imposes binding SAF blending obligations rising from mandated minimums to seventy percent by mid-century, forcing refinery reconfiguration.
- Military Aviation:Fighter, transport, and rotary-wing platforms operating on JP-8 and JP-5 formulations with enhanced thermal oxidative stability. The Indian Air Force's fighter fleet expansion creates new demand centers for JP-8 equivalent formulations and strategic fuel storage infrastructure.
- Commercial Flights:Scheduled passenger and cargo services optimizing fuel procurement through long-term offtake agreements and hedging strategies. United States-based carriers dominate volume through concentrated hub-and-spoke network economics.
- Defense Operations:Ground vehicle, naval vessel, and expeditionary power generation requiring NATO-standardized fuel specifications. Germany and France are establishing centralized procurement entities to leverage volume discounts and standardize quality specifications.
Military aviation commands the steepest price premiums; aerospace applications deliver the highest absolute volumes.
End User:
Procurement concentration varies sharply by buyer type, with government agencies consolidating purchasing through national strategic petroleum reserves while commercial airlines fragment demand across competing suppliers.
- Government Agencies:National defense departments and energy ministries operating single-buyer procurement models with direct supply agreements bypassing reseller channels. The US Defense Logistics Agency's centralized purchasing displaces fragmented base-level contracting.
- Defense Contractors:Prime contractors and subsystem suppliers managing fuel logistics for military operations and testing programs. Lockheed Martin and Boeing sustain long-term supply agreements with integrated refiners.
- Commercial Airlines:Network carriers and low-cost operators negotiating cost-pass-through mechanisms for SAF premiums without compromising mission readiness. Lufthansa and Air France-KLM anchor European demand.
- Private Aviation:Fractional ownership programs, charter operators, and individual aircraft owners purchasing through fixed-base operators. Demand concentrates in Switzerland and the United Arab Emirates.
Government agencies consolidate the most purchasing power; commercial airlines are diversifying fastest into sustainable alternatives.
Distribution Channel:
Channel economics reflect security requirements, with direct supply dominating defense procurement while commercial aviation tolerates intermediary layers for geographic flexibility.
- Direct Supply:National strategic petroleum reserves and military fuel depots receiving pipeline and tanker deliveries under classified logistics protocols. FERC oversees interstate pipeline tariffs shaping distribution economics for US defense fuel depots.
- Resellers:Independent fuel distributors and jobbers serving general aviation and regional commercial operators. Shell plc anchors position through specialized marine and aviation supply chains spanning multiple NATO logistics hubs.
- Online Platforms:Digital procurement portals for commercial aviation fuel hedging and spot market transactions. These systems displace traditional telephone-based trading floors.
- Fuel Depots:Military installations and civilian airports with dedicated storage and into-plane services. Gulf Coast processing capacity dominates US military supply, creating geographic concentration vulnerabilities.
Direct supply channels handle the most volume; online platforms are gaining transaction share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors the world's densest concentration of military jet fuel refining capacity, with Gulf Coast processing complexes supplying the Pentagon's single-buyer procurement model through dedicated pipeline networks.
United States
The Department of Defense operates the largest jet fuel procurement program globally, channeling demand through the Defense Logistics Agency's centralized purchasing. EPA regulations govern emissions profiles while FERC oversees interstate pipeline tariffs shaping distribution economics. Gulf Coast refineries in Texas and Louisiana concentrate military-specification production, with strategic petroleum reserve sites in Louisiana and Texas providing buffer capacity.
Germany
The Bundeswehr's aviation modernization and NATO force commitments drive sustained JP-8 equivalent demand. The EU Green Deal's ReFuelEU Aviation regulation imposes binding SAF blending obligations that restructure refinery investment priorities. The Rhine-Ruhr industrial corridor hosts concentrated refining capacity, with Leuna and Karlsruhe complexes adapting hydrocracker units for synthetic fuel pathways.
France
The Direction Générale de l'Armement consolidates military fuel procurement alongside Air France-KLM's commercial SAF offtake agreements. EU Green Deal mandates accelerate refinery reconfiguration toward drop-in biofuel production. The Fos-sur-Mer and Gonfreville-L'Orcher refining clusters on the Mediterranean and Atlantic coasts anchor supply security for both defense and civil aviation.
India
The Indian Air Force's fighter fleet expansion creates new demand centers for JP-8 equivalent formulations and strategic fuel storage infrastructure. The Petroleum and Natural Gas Regulatory Board oversees downstream distribution while defense procurement guidelines favor domestic refinery supply. Reliance Industries' Jamnagar complex and public sector refineries in Maharashtra and Gujarat concentrate production capacity.
United Kingdom
The Ministry of Defence's single-fuel policy standardizes JP-8 procurement across RAF and Royal Navy aviation platforms. The EU Green Deal's regulatory framework continues influencing domestic SAF mandates post-Brexit through retained alignment. The Humber and Fawley refining clusters maintain military supply relationships while adapting to sustainable aviation fuel blending requirements.
Aerospace and Defense Fuel Market Competitive Environment
Premium-margin players sit above commodity-margin players across specification complexity and defense contract tenure, with integrated majors commanding long-term supply agreements while independent refiners compete on spot market flexibility. The vendor base stratifies between global integrated oil companies, national oil companies with defense mandates, and independent refiners with regional logistics advantages. Two archetypes dominate: vertically integrated majors leveraging captive crude supply and specialized aviation fuel blenders with ASTM certification depth. Competitive moves concentrate on multi-year offtake negotiations and hydrocracker unit retrofits for synthetic fuel compatibility.
Within the integrated major tier, Exxon Mobil Corporation and Shell plc occupy positions defined by global refining networks and NATO logistics hub presence. Exxon Mobil's integrated structure exemplifies the crude-to-jet-fuel value chain control that sustains defense contract renewals. Shell's specialized marine and aviation supply chains represent the multi-hub logistics model that underpins alliance fuel security planning. Chevron Corporation anchors the North American defense supply vector through Gulf Coast processing concentration.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP p.l.c. |
| Shell plc |
| TotalEnergies SE |
| Valero Energy Corporation |
| Indian Oil Corporation Ltd. |
| Phillips 66 |
| Repsol |
| Others |
Value Chain & Pricing Dynamics
Fischer-Tropsch and alcohol-to-jet synthesis pathways are compressing traditional petroleum economics while redistributing refinery margin capture toward synthetic fuel producers with captive renewable feedstock access. The EU Green Deal's progressive blending mandates force dual-sourcing investments that simultaneously inflate capital requirements and concentrate procurement leverage among integrated majors with hydrocracker retrofit capabilities.
Pricing Analysis
Defense contract tenure anchors value-based pricing for military-specification JP-8 and JP-5 formulations with enhanced thermal oxidative stability. Three-tier pricing structure separates strategic reserve commitments from commercial offtake and spot market transactions, with NATO centralized procurement commanding volume discounts. Cost compression in conventional jet fuel runs through crude price volatility and margin pressure at Gulf Coast refineries. Commercial airlines exhibit highest price sensitivity due to fuel hedging limitations, while government agencies absorb premiums through cost-pass-through mechanisms.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast processing concentration for US military supply, where Texas and Louisiana refineries channel output through FERC-regulated interstate pipelines. Raw material dependencies draw from crude petroleum, waste oils for HEFA pathways, and municipal solid waste for emerging conversion technologies. Tariff exposure on imported synthetic fuel intermediates threatens NATO logistics hub resupply. Distribution runs through direct pipeline delivery to strategic petroleum reserves and military fuel depots, with limited spot market flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated refiners with hydrocracker retrofit capabilities, as EU Green Deal mandates force sub-scale players into distressed asset sales.
For Market Incumbents: Deepen backward integration into waste feedstock preprocessing to secure circular economy positioning against emerging biorefinery competitors. Expand hydrocracker unit capacity at Rhine-Ruhr and Fos-sur-Mer clusters to capture ReFuelEU Aviation mandated volumes. Lock multi-year offtake agreements with Defense Logistics Agency and Direction Générale de l'Armement before centralized procurement standardizes specifications. For New Entrants and Emerging Players: Enter via waste-to-jet pathways in India, where Petroleum and Natural Gas Regulatory Board guidelines favor domestic refinery supply and defense procurement guidelines create local content advantages. Target Indian Air Force fighter fleet expansion for JP-8 equivalent formulations. Pursue ASTM certification for municipal solid waste conversion technologies to differentiate from established HEFA producers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated majors seeking hydroprocessing expertise and military contract tenure. Long-term viability favors refiners with dual conventional-synthetic production capability and NATO logistics hub presence. Watch for carbon border adjustment mechanism implementation as inflection indicator for synthetic fuel premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracker Unit Retrofit | Enables ReFuelEU Aviation compliance at Leuna and Karlsruhe refining clusters. |
| Long-term Supply Agreement | Secures priority allocation with Defense Logistics Agency through multi-year offtake. |
| Backward Integration into Feedstock | Captures waste oil and agricultural residue supply chains for HEFA production. |
| Joint Venture with Technology Licensor | Accelerates Fischer-Tropsch pathway certification for military specification compliance. |
| Geographic Expansion to India | Positions for Indian Air Force modernization and strategic fuel storage infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this aerospace and defense fuel analysis. Primary interviews with refinery operations directors, defense procurement officers at NATO logistics commands, sustainable aviation fuel technology licensors, and pipeline tariff specialists at FERC supplemented quantitative foundations. Secondary sources included EPA emissions compliance databases, EU Green Deal implementation reports, Defense Logistics Agency fuel procurement disclosures, and petroleum refinery SEC filings. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across fuel type and application segments.
Segment-level granularity modeled fuel type, application, end user, and distribution channel dimensions across the projection horizon. Aerospace and defense fuel specifications, military procurement contract structures, and refinery hydrocracker utilization rates informed analytical framework development. CAGRs derived from production capacity expansion timelines, NATO defense spending commitments, and sustainable aviation fuel blending mandate trajectories. Crude price scenarios and carbon border adjustment mechanism implementation risk factored into sensitivity analysis.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained crude price volatility or accelerated ASTM certification timelines for novel synthetic pathways. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency, NATO defense spending continuity, and refinery investment cycle completion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market