
 Aircraft Nacelle Systems Market | 2026-2036
Aircraft Nacelle Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Nacelle Systems Market Analysis
European composite manufacturing capacity is rebalancing toward thermoplastic processing lines after years of thermoset dominance. Safran SA leverages its vertically integrated supply chain across France and Morocco to control nacelle design-to-delivery cycles. GKN Aerospace Services Limited anchors the UK's position in engine nacelle structures through its Western Approach facility near Bristol. Leonardo S.p.A. competes in the military segment with specialized thrust reverser systems for tactical transport platforms.
Aircraft nacelle systems enclose the engine core, integrate thrust reverser mechanisms, and manage aerodynamic airflow across operating envelopes from takeoff to cruise; modern units employ carbon fiber reinforced polymer composites achieving weight reductions of 20-30% versus legacy aluminum architectures while maintaining acoustic attenuation performance. The product type dimension shows engine nacelles and thrust reversers commanding the largest value pools due to their integration complexity and replacement cycle intensity, whereas exhaust systems represent a more mature, price-competitive segment. Composite materials dominate new program specifications, yet titanium retains critical application in hot-section interfaces where thermal expansion compatibility with engine hardware remains non-negotiable.
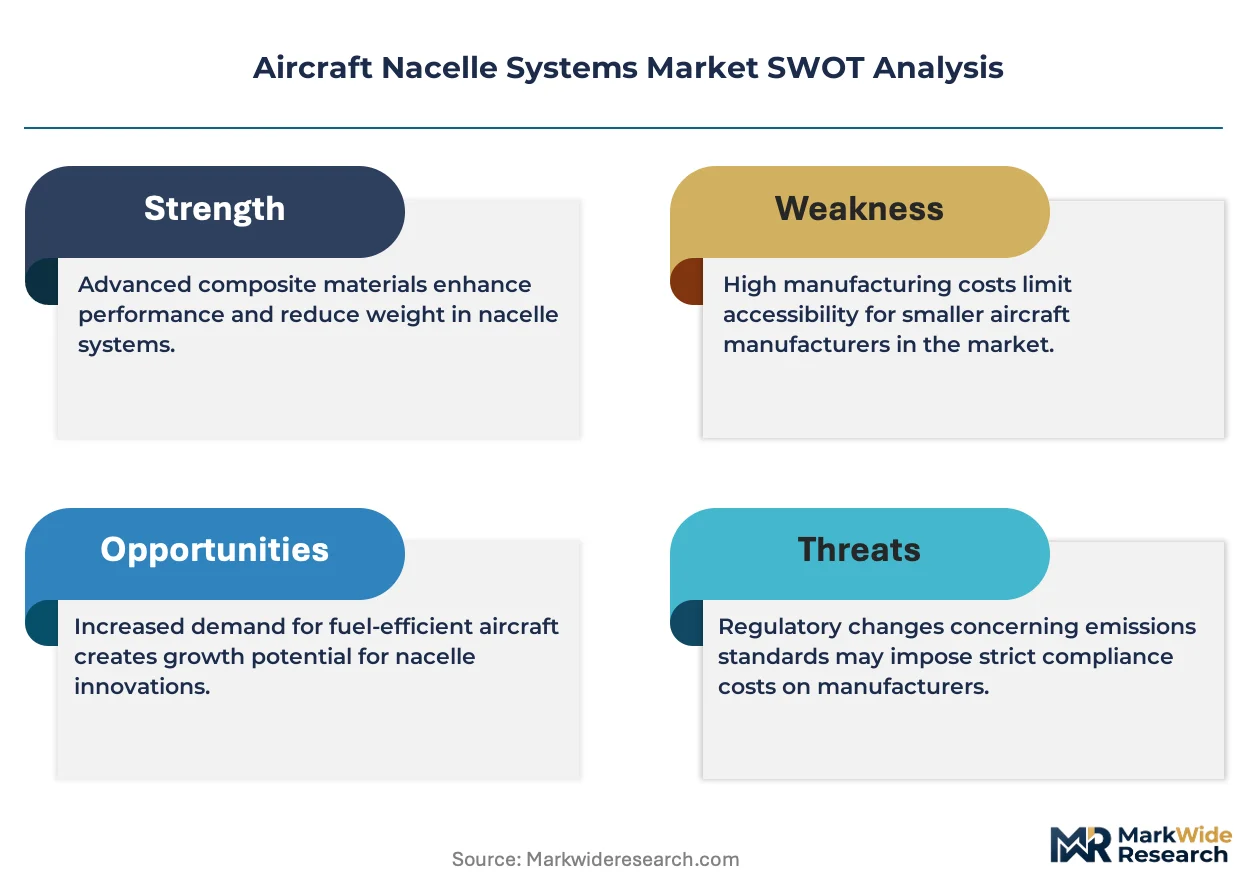
FAA Part 36 noise certification and EASA CS-34 fuel venting standards directly shape nacelle acoustic liner design and fire containment system specifications, forcing manufacturers to redesign inlet and exhaust geometries across each new engine generation. The EU Green Deal's aviation decarbonization trajectory and the FAA's ongoing sustainable aviation fuel integration timeline will progressively tighten emissions-linked product standards. Stakeholders must monitor how emerging supersonic and hybrid-electric propulsion architectures redefine nacelle form factors and thermal management requirements.
Market Dynamics
Thermoplastic composite processing lines are displacing thermoset dominance across European manufacturing bases, forcing nacelle suppliers to retool facilities while FAA Part 36 noise certification tightens inlet and exhaust geometry requirements.
Growth Catalysts
- FAA Part 36 Noise Certification:Stricter Stage 5 noise limits compel redesigned acoustic liners and chevron exhaust geometries, expanding replacement demand for legacy nacelle architectures.
- Thermoplastic Composites:Out-of-autoclave processing cuts cycle times by half versus thermoset curing, attracting aerospace OEM procurement toward suppliers with installed thermoplastic capacity.
- Narrow-Body Fleet Expansion:Single-aisle commercial jet production rates at final assembly lines in the United States, France, and China concentrate nacelle demand around high-volume engine programs.
Market Restraints
- Titanium Input Volatility:Hot-section interfaces require titanium alloys for thermal expansion compatibility with engine hardware, exposing margins to sponge and mill product price swings.
- French Supply Concentration:Vertically integrated nacelle production clusters around Toulouse and Le Havre, creating geographic vulnerability to single-point logistics disruptions or labor actions.
- Supersonic Certification Gap:FAA and EASA lack established noise and emissions frameworks for Mach-plus nacelle designs, freezing commercialization timelines for next-generation propulsion concepts.
Strategic Opportunities
- Hybrid-Electric Propulsion:Distributed thrust architectures demand novel nacelle form factors with integrated thermal management, opening design contracts outside traditional engine OEM supply chains.
- Moroccan Manufacturing:Low-cost composite fabrication capacity near Casablanca offers European suppliers tariff-advantaged export positioning into African and Middle Eastern MRO markets.
- EU Green Deal Aviation Decarbonization:Sustainable aviation fuel compatibility mandates drive nacelle fire containment system upgrades, creating retrofit revenue streams for installed fleet bases.
Industry Challenges
- Autoclave-to-Press Transition:Thermoplastic processing requires capital-intensive press systems and retrained technician workforces, straining mid-tier supplier balance sheets during facility conversions.
- Multi-Authority Certification Parallelism:Simultaneous FAA, EASA, and CAAC validation for new nacelle designs triples documentation burdens and extends program timelines without revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Nacelle Systems Market |
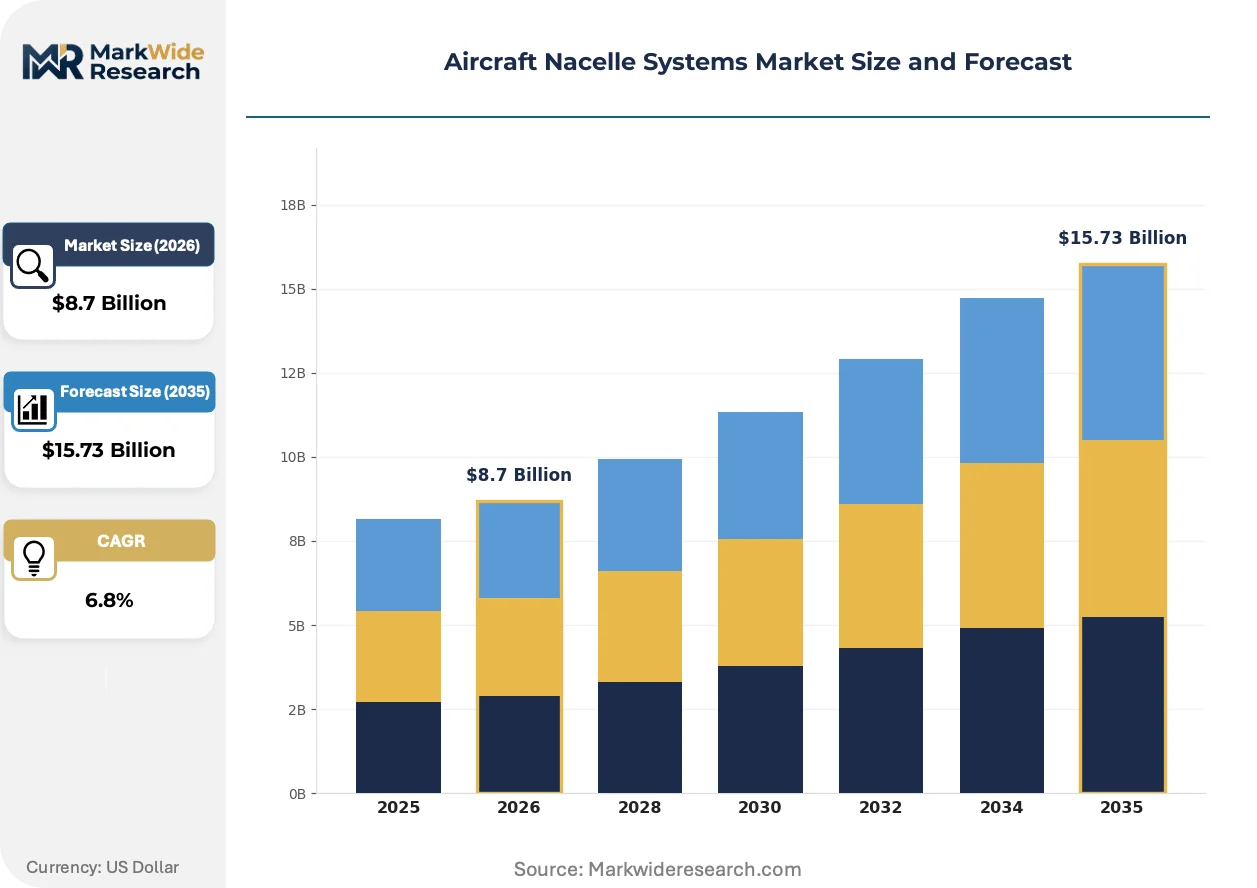
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Nacelle, Fan Cowling, Thrust Reverser, Exhaust System Material: Composite, Aluminum, Titanium, Steel End User: Aerospace OEMs, Maintenance Repair Operations, Airlines, Military Technology: Additive Manufacturing, Machining, Assembly, Testing |
| Companies Covered | Safran SA, Collins Aerospace, Leonardo S.p.A., Spirit AeroSystems, Inc., GKN Aerospace Services Limited, United Technologies Corporation, Bombardier, Aernnova Aerospace S.A., Triumph Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Nacelle Systems Market Emerging Trajectories
Active matrix thermoplastic composites are rewriting material specifications across engine nacelle programs, while regulatory pressure on noise and emissions accelerates geometric innovation in inlet and exhaust systems.
Thermoplastic resin systems with carbon fiber reinforcement are integrating acoustic attenuation functions directly into structural nacelle skins, eliminating secondary liner installations. Boeing and Airbus procurement teams are qualifying these consolidated architectures for next-generation narrow-body programs. The technology is integrating fire containment, acoustic damping, and lightning strike protection into single-mold components, compressing part counts and assembly labor hours by substantial margins.
EU Green Deal aviation decarbonization targets are tightening emissions-linked product standards through delegated acts under the RefuelEU Aviation regulation. EASA certification staff are embedding sustainable aviation fuel compatibility into nacelle fire suppression system specifications. European narrow-body operators are responding with accelerated replacement schedules for exhaust systems that cannot demonstrate SAF containment performance.
Power-by-the-hour maintenance contracts are displacing traditional component sales in nacelle aftermarket channels, concentrating procurement authority with airline fleet managers rather than MRO shops. Safran and GKN are restructuring service organizations to capture long-term revenue streams from integrated nacelle-thrust reverser packages. This behavioral shift is most visible among low-cost carriers in Europe and Southeast Asia with standardized narrow-body fleets and centralized technical operations.
Aircraft Nacelle Systems Market Segmentation
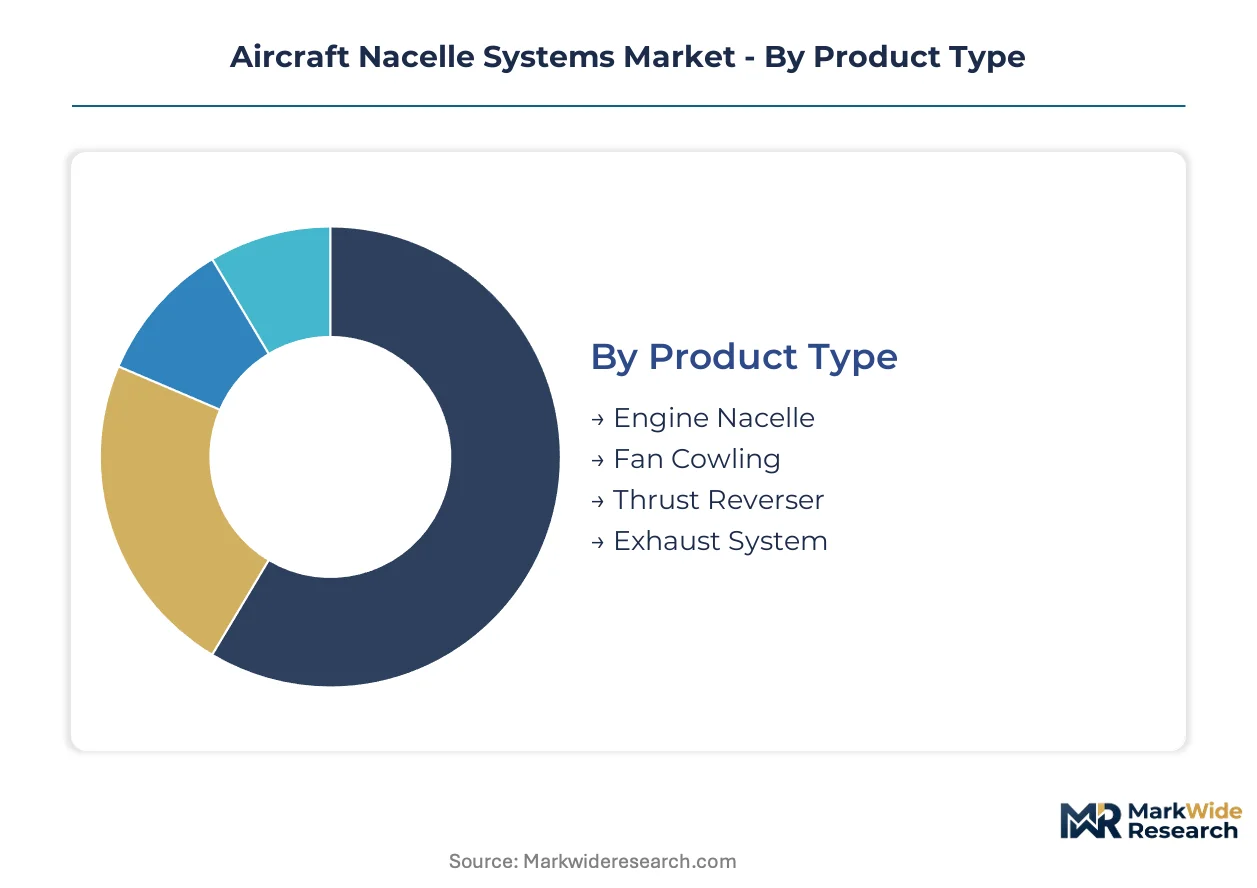
Nacelle system procurement splits sharply between high-volume narrow-body programs and low-rate wide-body or military contracts. Material certification cycles and thermal management requirements create divergent margin profiles across each segment category. Understanding these fracture lines clarifies where suppliers can capture pricing power versus where commoditization pressures dominate.
Product Type:
Volume concentration sits with thrust reverser and fan cowling shipments tied to single-aisle production rates, while premium engineering hours concentrate in integrated engine nacelle architectures.
- Engine Nacelle:Encloses the engine core, inlet lip, and fan case while integrating acoustic treatment and fire containment systems. Demand clusters at Airbus and Boeing final assembly lines in Toulouse, Mobile, and Renton where A320neo and 737 MAX output rates drive procurement volume.
- Thrust Reverser:Deploys cascade or target-type blocker doors to redirect fan airflow during landing rollout. European suppliers at Western Approach and Le Havre capture aftermarket replacement cycles as FAA Stage 5 noise limits accelerate retirement of legacy translating sleeve architectures.
- Fan Cowling:Composite clamshell panels providing aerodynamic fairing and maintenance access. Airlines specify quick-latch designs to minimize turnaround times at high-frequency hubs.
- Exhaust System:Chevron and mixer nozzle geometries managing jet noise and thermal signatures. Military platforms require infrared suppression variants with specialized coatings.
Mature deployment sits with exhaust systems on legacy wide-body fleets. Newer deployment is concentrated in thrust reverser architectures with integrated acoustic liners for next-generation narrow-body engines.
Material:
Cost tier stratification separates commodity aluminum from qualification-heavy thermoplastic composites, with titanium occupying a mid-tier niche defined by thermal expansion constraints rather than structural loading.
- Composite:Carbon fiber reinforced thermoplastics achieve 20-30% weight reduction versus aluminum while consolidating acoustic, fire, and lightning functions into single-mold components. Boeing and Airbus procurement teams are qualifying these architectures for next-generation narrow-body programs.
- Titanium:Retains critical application in hot-section interfaces where thermal expansion compatibility with nickel superalloy engine hardware remains non-negotiable. Sponge and mill product price volatility compresses margins for suppliers locked into long-term OEM contracts.
- Aluminum:Legacy architectures on freighter conversions and regional turboprops where certification costs prohibit composite retrofits.
- Steel:Retained in thrust reverser actuator linkages and firewalls where ultimate strength requirements override weight penalties.
Procurement is shifting most aggressively toward composite specifications, with aluminum relegated to aftermarket replacement on aging platforms and titanium serving as a captive requirement for engine OEMs.
End User:
Customer type determines contract structure, with aerospace OEMs demanding design-to-cost accountability while airlines and MRO channels increasingly favor power-by-the-hour arrangements.
- Aerospace OEMs:Airbus, Boeing, and COMAC integrate nacelle systems at final assembly, controlling supplier selection through platform-specific qualification gates. French and Chinese production lines concentrate procurement authority with fleet managers rather than component engineers.
- Airlines:Low-cost carriers in Europe and Southeast Asia with standardized narrow-body fleets are consolidating technical operations and pushing maintenance contracts toward integrated nacelle-thrust reverser packages.
- Maintenance Repair Operations:Independent MRO shops in the United States and Germany handle legacy fleet exhaust system replacement as EU Green Deal SAF compatibility mandates accelerate retirement schedules.
- Military:Tactical transport platforms require specialized thrust reverser systems with debris rejection and rough-field durability specifications distinct from commercial architectures.
Contracting behavior diverges most sharply between OEM design-phase engagement and airline aftermarket procurement, with MRO intermediaries losing share to direct supplier-airline power-by-the-hour structures.
Technology:
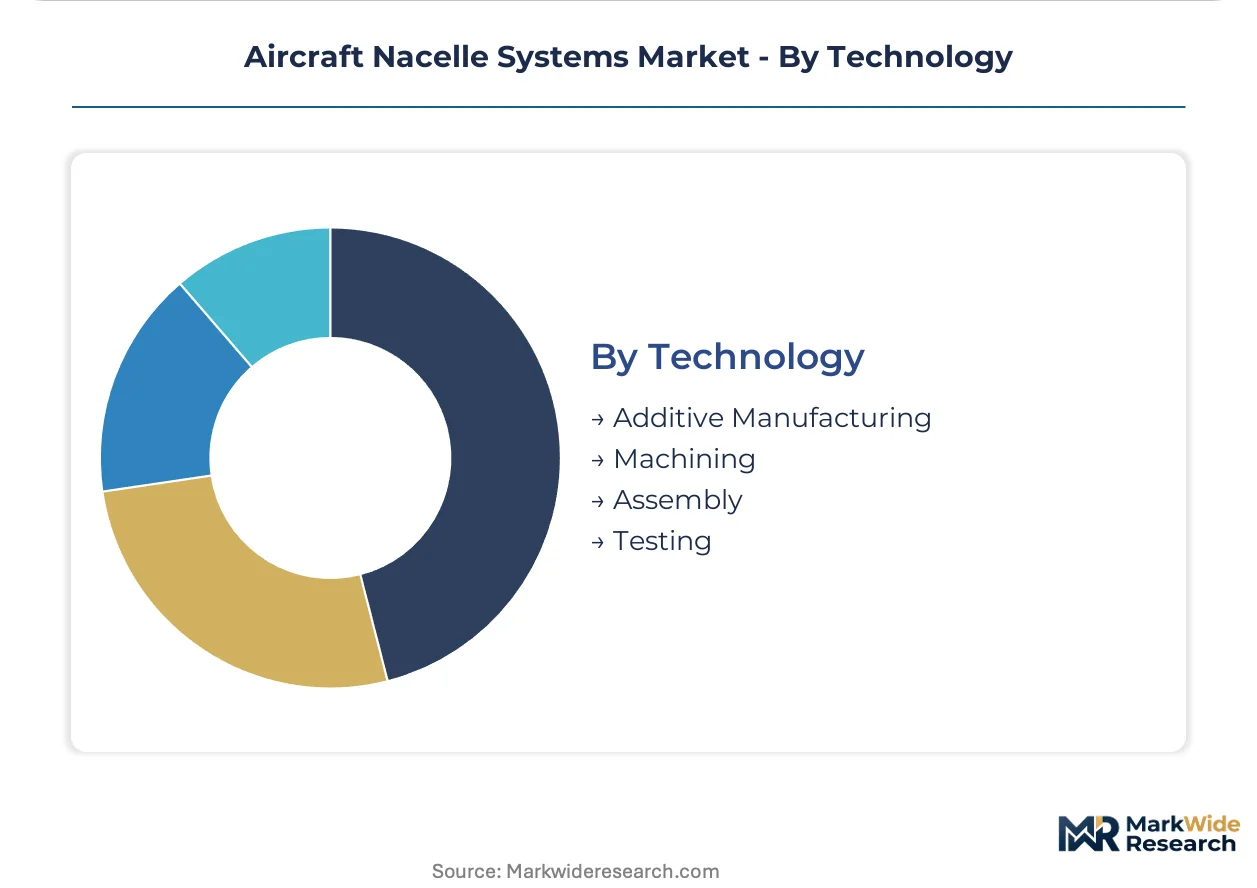
Manufacturing process selection divides capital-intensive additive qualification programs from established machining and assembly operations, with testing representing a fixed-cost barrier to market entry.
- Assembly:Dominates value-added content through integration of acoustic liners, thrust reverser mechanisms, and fire containment systems into delivered nacelle units. Moroccan facilities near Casablanca offer European suppliers tariff-advantaged positioning for African and Middle Eastern MRO markets.
- Testing:Bird strike, hail, and ice ingestion validation cycles extend program timelines without revenue recognition until FAA, EASA, and CAAC parallel certifications complete.
- Machining:Titanium hot-section brackets and aluminum structural ribs require five-axis capability concentrated in UK and German supplier bases.
- Additive Manufacturing:Qualifying laser powder bed fusion for titanium actuator brackets and inconel exhaust mixers, though build-rate economics lag forged alternatives for high-volume narrow-body programs.
Process maturity concentrates in assembly and machining, with additive manufacturing climbing fastest in military and low-rate commercial applications where part consolidation justifies unit cost premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium sponge processing in the Ural Mountains feeds Russian mill product flows, yet Western aerospace supply chains pivot toward Japanese and Kazakh feedstock to bypass sanctions exposure. This raw-material geography shapes where nacelle manufacturers source hot-section alloys.
United States
Boeing 737 MAX production at Renton and Airbus A320neo assembly at Mobile concentrate nacelle demand around high-volume engine programs. FAA Stage 5 noise certification tightens acoustic liner specifications, forcing redesigns of inlet geometries. Wichita, Kansas hosts Spirit AeroSystems fabrication facilities supplying integrated nacelle-thrust reverser packages.
France
Airbus final assembly at Toulouse and Safran's vertically integrated supply chain across Le Havre anchor European nacelle procurement. EASA CS-34 fuel venting standards shape fire containment system specifications for next-generation narrow-body programs. The Western Approach corridor near Bristol extends French supply chain influence into UK composite fabrication.
China
COMAC C919 production ramp at Shanghai Pudong drives indigenous nacelle system qualification campaigns. CAAC parallel certification requirements extend program timelines for Western suppliers seeking access. The Tianjin Airbus final assembly line concentrates demand for A320 family nacelle shipments into domestic airline fleets.
United Kingdom
GKN Aerospace's Western Approach facility near Bristol anchors UK capability in engine nacelle structures and thrust reverser mechanisms. CAA alignment with EASA certification standards streamlines cross-channel supply movements. The Midlands aerospace cluster around Birmingham supplies machined titanium brackets for hot-section interfaces.
Morocco
Casablanca-adjacent composite fabrication facilities offer European suppliers tariff-advantaged export positioning into African and Middle Eastern MRO markets. Moroccan labor costs undercut French manufacturing by substantial margins. Royal Air Maroc's narrow-body fleet expansion creates captive demand for nacelle maintenance services.
Aircraft Nacelle Systems Market Vendor Landscape
Global majors compete with regional champions across design-to-delivery cycles and aftermarket service networks. The market exhibits tiered consolidation with a handful of vertically integrated systems houses controlling OEM qualification gates while mid-tier specialists capture niche military and retrofit segments. Two strategic archetypes dominate: full-system integrators owning inlet-to-exhaust architectures, and component specialists focusing on thrust reverser mechanisms or acoustic treatment modules. Competitive moves concentrate on Moroccan manufacturing expansion and thermoplastic composite capacity installation.
Within the full-system integrator tier, Safran SA and Collins Aerospace exemplify vertically integrated supply chain control spanning design, fabrication, and aftermarket services. Leonardo S.p.A. occupies a specialized position in military thrust reverser systems distinct from commercial architectures. GKN Aerospace Services Limited anchors UK-based structural capability while Spirit AeroSystems, Inc. represents the scale-driven North American fabrication model. These companies illustrate how geographic clustering around Toulouse, Bristol, and Wichita shapes competitive positioning through proximity to final assembly lines.
| Leading Market Players |
|---|
| Safran SA |
| Collins Aerospace |
| Leonardo S.p.A. |
| Spirit AeroSystems, Inc. |
| GKN Aerospace Services Limited |
| United Technologies Corporation |
| Bombardier |
| Aernnova Aerospace S.A. |
| Triumph Group |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in European nacelle fabrication have consolidated thermoplastic capacity around Toulouse and Bristol, tightening pricing discipline through captive supply of carbon fiber prepreg and press-forming equipment while squeezing mid-tier subcontractors on legacy aluminum exhaust contracts.
Pricing Analysis
Warranty and service bundling separates power-by-the-hour contracts from transactional component sales, with Safran and Collins Aerospace capturing premium pricing through integrated nacelle-thrust reverser packages that shift operational risk to suppliers. Three-tier pricing structure across OEM-specified, airline-direct, and MRO-channel levels reflects certification grade and volume scale differentiation. Pricing pressure stems from titanium sponge volatility feeding hot-section bracket costs, squeezing margins on long-term OEM contracts. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, driving procurement toward Moroccan-assembled fan cowlings with reduced acoustic treatment.
Supply Chain Analysis
Regional distribution centers at Le Havre, Wichita, and Casablanca feed hub-and-spoke patterns into final assembly lines at Toulouse, Renton, and Mobile. Manufacturing concentrates in France, the United States, and Morocco, with composite fabrication drawing from Japanese carbon fiber feedstock and Kazakh titanium sponge. Supply chain risk centers on single-source vulnerability for thermoplastic resin systems qualified to Boeing and Airbus specifications. Distribution runs through vertically integrated OEM supply chains rather than independent wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nacelle procurement is becoming a vertical-integration race as full-system integrators pursue backward control over thermoplastic prepreg supply and aftermarket service networks to lock out component specialists.
For Market Incumbents: Deploy thermoplastic press capacity expansion in Morocco to capture tariff-advantaged export positioning into African MRO markets. Defend against emerging Chinese composite specialists by accelerating FAA-EASA-CAAC parallel certification timelines for next-generation narrow-body programs. Deepen backward integration into carbon fiber recycling streams to offset virgin prepreg cost volatility.
For New Entrants and Emerging Players: Enter via specialized thrust reverser refurbishment for legacy narrow-body fleets facing EU Green Deal SAF compatibility mandates. Target independent MRO shops in Germany and the United States losing share to power-by-the-hour structures, offering unbundled exhaust system replacement with rapid-turnaround logistics. Pursue qualification as tier-two acoustic liner supplier to Boeing 737 MAX and Airbus A320neo programs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier thermoplastic specialists in the United Kingdom with underutilized press capacity and dormant EASA certification credentials. Long-term viability hinges on positioning for hybrid-electric propulsion architectures requiring novel nacelle form factors outside traditional engine OEM supply chains. Monitor CAAC certification timeline acceleration for Western suppliers as signal of Chinese market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Composite Capacity Expansion | Out-of-autoclave processing halves cycle times versus thermoset curing, attracting Boeing and Airbus procurement. |
| Moroccan Manufacturing Footprint | Casablanca-adjacent facilities offer European suppliers tariff-advantaged export positioning into African MRO markets. |
| Power-by-the-Hour Service Restructuring | Safran and GKN capture long-term revenue streams from integrated nacelle-thrust reverser packages. |
| Hybrid-Electric Propulsion Qualification | Distributed thrust architectures demand novel nacelle form factors with integrated thermal management systems. |
| EU Green Deal Compliance Retrofit | SAF compatibility mandates create exhaust system replacement revenue for independent MRO channels. |
Methodological Framework
Independent corroboration across nacelle program managers at Airbus and Boeing, procurement executives at tier-one engine OEMs, and aftermarket directors at European low-cost carriers underwrites the qualitative findings. Primary fieldwork with thermoplastic composite specialists in France and the United Kingdom combined with secondary validation from FAA Part 36 certification databases, EASA CS-34 regulatory filings, and customs records of carbon fiber prepreg shipments. Bottom-up build of narrow-body production rates and top-down triangulation against aerospace OEM disclosed backlog data anchor volume estimates.
Comparable-period anchoring to historical A320neo and 737 MAX delivery trajectories shapes the forecast window across the projection horizon. Segmentation dimensions include product type, material specification, end-user contracting structure, and manufacturing process technology. CAGRs derive from production rate assumptions tied to final assembly line capacity expansion and replacement cycle intensity for legacy fleet exhaust systems. Forecast inputs incorporate thermoplastic qualification timelines and EASA delegated act implementation schedules for SAF compatibility.
Revisions become necessary when CAAC certification timeline acceleration, titanium sponge price dislocation, or hybrid-electric propulsion architecture standardization materially alters procurement patterns. Forecasts reflect documented assumptions regarding narrow-body production rate sustainability and regulatory harmonization across FAA, EASA, and CAAC jurisdictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Docking System Market
Aircraft
Aircraft Door Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Military Helicopters Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Japan Aviation Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Winglets Market
Aircraft
Aircraft Wheels Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Aircraft Lavatory System Market