
 Scrubber System Market | 2026-2036
Scrubber System Market Size, Share, and Industry Trends Forecast 2026-2036
Scrubber System Market Intelligence
IMO DCS certification is reorganizing supplier eligibility for maritime scrubber retrofits. Alfa Laval leverages its exhaust gas cleaning portfolio to dominate open-loop system deliveries. Wärtsilä anchors its position through integrated engine-scrubber packages. GEA Group competes with specialized compact scrubber designs for cruise and ferry segments.
A scrubber system is a gas treatment apparatus that uses liquid reagents or dry sorbents to remove pollutants—sulfur oxides, particulate matter, acid gases—from industrial exhaust streams, typically achieving removal efficiencies above 95% for SOx in marine applications. Wet scrubbers represent the most mature segment with established installed bases across power generation and chemical processing, while dry scrubber configurations are gaining traction in waste incineration where water availability constraints apply. Maritime vessels constitute the fastest-growing end user category as ship operators face compliance deadlines under international sulfur regulations.
The International Maritime Organization enforces MARPOL Annex VI sulfur limits that directly mandate scrubber adoption or fuel switching for ocean-going vessels. EPA standards for stationary sources and EU F-Gas Regulation for fluorinated greenhouse gas containment create parallel compliance obligations across industrial and maritime domains. Stakeholders must monitor regulatory divergence between port state enforcement regimes to anticipate retrofit demand timing and technology selection risks.
Market Dynamics
Retrofit deadlines for MARPOL Annex VI compliance are compressing order cycles for wet scrubber systems as shipyards in China, South Korea, and Japan absorb capacity constraints from simultaneous vessel construction and exhaust gas cleaning upgrades.
Growth Catalysts
- IMO 2020 Sulfur Cap:The International Maritime Organization's 0.5% sulfur fuel limit forces ocean-going vessels to install scrubbers or switch to compliant fuels, driving retrofit demand across container shipping and bulk carrier fleets.
- Shipbuilding Cluster Concentration:China, South Korea, and Japan host integrated shipyard ecosystems where newbuild scrubber integration costs less than aftermarket installation, accelerating specification rates.
- Open-Loop System Maturity:Established seawater-based scrubber designs offer proven SOx removal efficiency above 95% with lower capital outlay than closed-loop alternatives, appealing to deep-sea operators.
Market Restraints
- Stainless Steel Price Volatility:Grade 316L and duplex stainless inputs for scrubber housing and piping expose manufacturers to nickel and molybdenum commodity swings, compressing fabrication margins.
- Port State Enforcement Divergence:The EU, China, and Singapore maintain conflicting discharge water quality standards for open-loop scrubbers, forcing redundant engineering and regional variant production.
- LNG Fuel Substitution:Dual-fuel engine investments by container lines and cruise operators reduce scrubber dependency for sulfur compliance, constraining long-term addressable market expansion.
Strategic Opportunities
- India Ship Repair Expansion:Alang-Sosiya and Cochin Shipyard clusters are developing scrubber retrofit capabilities to capture South Asian and Middle Eastern vessel traffic outside East Asian yard queues.
- Scrubber-Wastewater Treatment Convergence:Integrated systems combining exhaust gas cleaning with onboard water treatment address tightening port discharge rules while reducing separate equipment footprints.
- EU Green Deal Alignment:The European Union's carbon border adjustment and sustainable shipping initiatives create preference for scrubber-equipped vessels in EU port calls, rewarding early adopters with operational access advantages.
Industry Challenges
- Marine Exhaust Gas Cleaning Certification:IMO DCS and port state approval timelines vary by classification society and flag administration, delaying revenue recognition for system deliveries.
- Retrofit Installation Coordination:Dry-dock scheduling conflicts between hull maintenance and scrubber integration compress available installation windows, requiring specialized project management capabilities.
- Electrical Load Integration:Modern scrubber pumps and control systems demand upgraded shipboard power distribution, complicating legacy vessel upgrades and requiring auxiliary generator assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scrubber System Market |
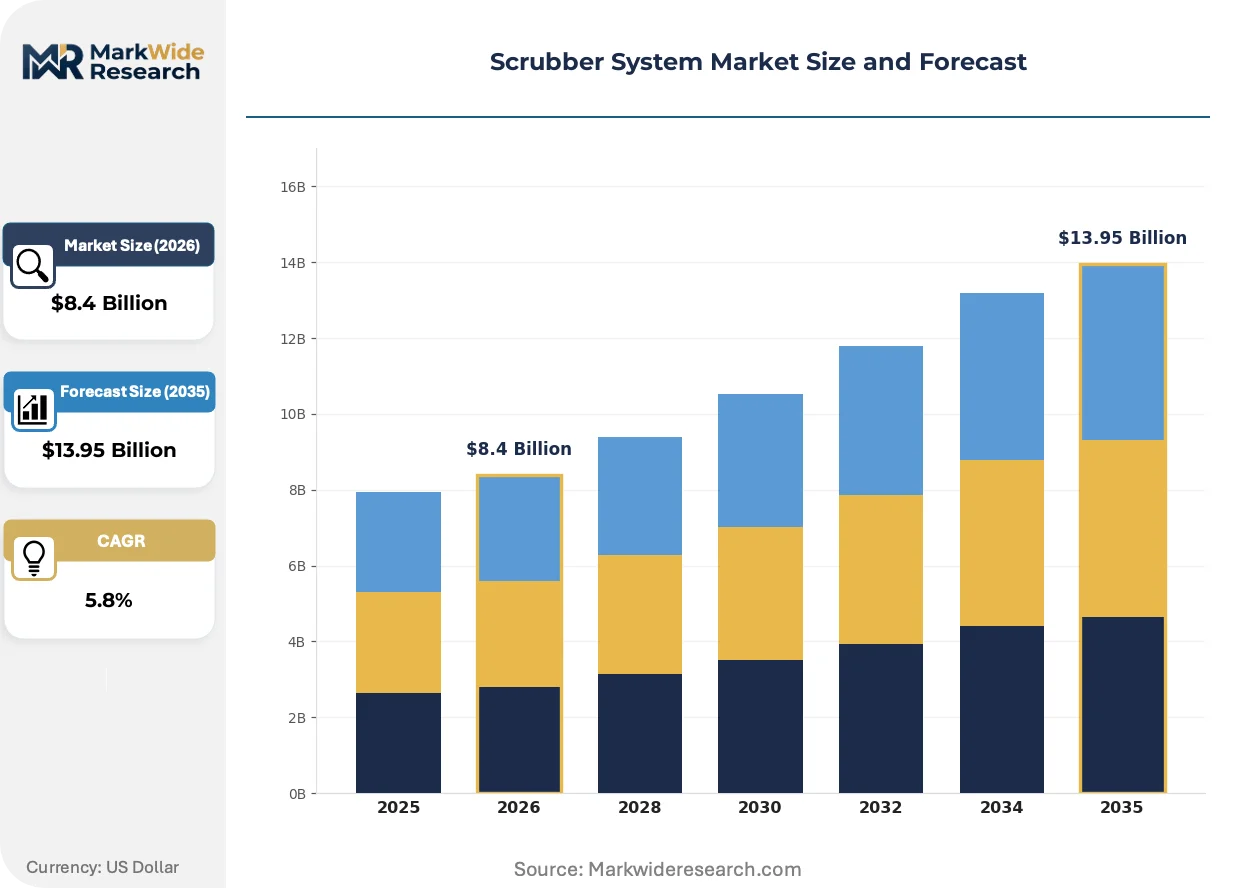
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Scrubbers, Dry Scrubbers, Semi-Dry Scrubbers, Packed Bed Scrubbers Technology: Venturi, Cyclonic, Spray Tower, Electrostatic Precipitator, Packed Column Application: Power Plants, Chemical Processing, Metal Refining, Waste Incineration, Pulp & Paper End User: Manufacturing Facilities, Mining Operations, Municipal Facilities, Maritime Vessels |
| Companies Covered | Alfa Laval, Wärtsilä, GEA Group, Babcock & Wilcox, Yara Marine Technologies, CECO Environmental, Evoqua Water Technologies, Valmet, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scrubber System Market Strategic Shifts & Innovations
Engineering focus is shifting from standalone sulfur removal toward integrated exhaust treatment platforms that combine particulate capture, nitrogen oxide reduction, and carbon monitoring in unified architectures.
Hybrid scrubber configurations that switch between open-loop and closed-loop operation are displacing single-mode systems in newbuild specifications. Container lines operating on trans-Pacific and Asia-Europe routes are specifying these dual-mode units to maintain compliance across jurisdictions with incompatible discharge regulations. This flexibility premium is compressing pure open-loop market share in segments where route variability exceeds fuel cost optimization priorities.
The EU F-Gas Regulation and parallel EPA fluorinated gas restrictions are tightening containment standards for refrigeration and fire suppression systems aboard vessels, indirectly elevating scrubber relevance as operators consolidate environmental compliance investments. Shipyards in Germany and Finland are integrating F-Gas management with exhaust gas cleaning documentation to streamline classification society approvals. This regulatory bundling most affects cruise and ferry segments where passenger vessel environmental certification influences charter rates and port access fees.
Charter contract structures now increasingly pass scrubber capital costs to vessel owners while fuel savings accrue to operators, inverting traditional newbuild equipment allocation. Bulk carrier and tanker fleets under spot market exposure are resisting this shift, while container lines with long-term charter agreements are accelerating specification. This tension is most visible in Singapore and Rotterdam hub markets where vessel utilization rates and scrubber payback calculations diverge sharply by trade lane.
Scrubber System Market Segmentation
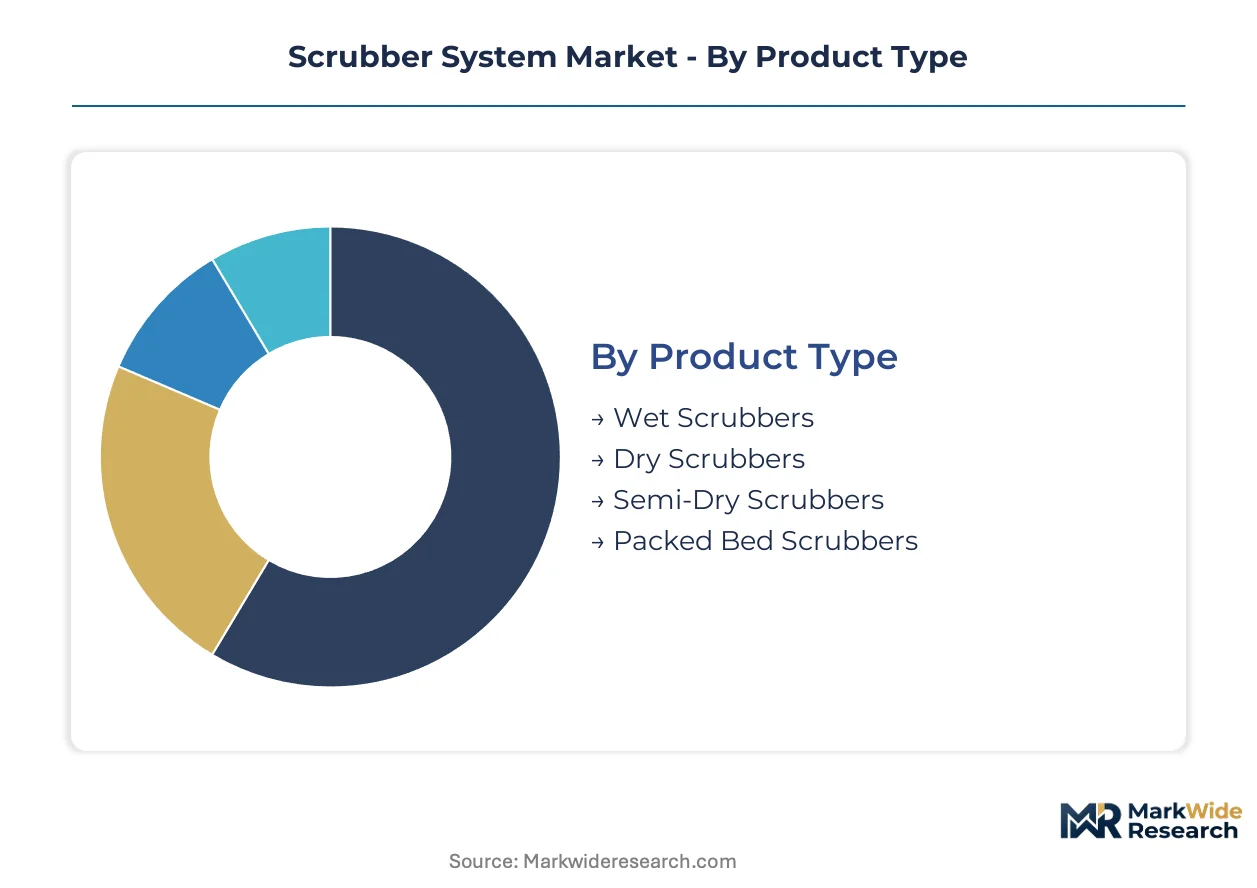
Scrubber system procurement varies sharply by regulatory exposure and operational environment. Technology selection, product configuration, and end-user category each impose distinct engineering requirements and compliance obligations that reshape supplier positioning across segments.
Product Type:
IMO MARPOL Annex VI enforcement and port state discharge rules differentiate scrubber product demand by marine versus stationary source requirements.
- Wet Scrubbers:These systems utilize liquid reagents—typically seawater or alkaline solutions—to neutralize sulfur oxides and particulate matter through gas-liquid contact. Maritime operators favor wet configurations for their proven SOx removal efficiency above 95% and lower capital outlay compared to alternatives. Shipyards in China, South Korea, and Japan specify wet scrubbers for newbuild container vessels and bulk carriers facing IMO 2020 compliance deadlines.
- Dry Scrubbers:Dry configurations inject powdered sorbents—lime or sodium bicarbonate—into exhaust streams without water consumption. Mining operations and waste incineration facilities in water-scarce regions specify dry systems to eliminate wastewater discharge liabilities. The technology appeals to desert-adjacent power generation and metal refining where cooling water availability constrains wet alternatives.
- Semi-Dry Scrubbers:Hybrid designs atomize lime slurry into hot gas streams, producing dry reaction products for collection.
- Packed Bed Scrubbers:These units force exhaust through structured packing media to maximize gas-liquid contact surface area.
Established volume favors wet configurations; emerging adoption favors dry systems in water-constrained jurisdictions.
Technology:
Cost tier differentiation separates high-efficiency precision technologies from robust low-maintenance alternatives for continuous-duty industrial applications.
- Venturi:High-velocity throat designs create intense gas-liquid mixing for sub-micron particulate capture. Chemical processing facilities specify Venturi scrubbers for acid gas neutralization where removal efficiency thresholds exceed 99%. The technology dominates hazardous waste incineration and chlor-alkali production where EPA Maximum Achievable Control Technology standards apply.
- Electrostatic Precipitator:Charged plate arrays remove fine particulates through electrostatic attraction without liquid reagents. Power plants and cement kilns integrate precipitators upstream of wet scrubbers to reduce sludge generation and reagent consumption. The configuration minimizes water use in arid-region coal-fired generation where cooling tower evaporation already strains aquifer reserves.
- Cyclonic:Tangential inlet designs generate centrifugal separation for coarse particulate pre-treatment.
- Spray Tower:Open vessel configurations distribute scrubbing liquid through nozzles for simple, low-pressure-drop operation.
- Packed Column:Structured or random packing media provides high surface area for mass transfer in compact footprints.
High-capital precision technologies concentrate in developed regulatory environments; low-maintenance robust designs penetrate cost-sensitive emerging markets.
Application:
End-use application determines pollutant profile, throughput scale, and redundancy requirements that reshape scrubber specification priorities.
- Maritime Vessels:Ocean-going ships deploy exhaust gas cleaning systems to comply with IMO sulfur caps while continuing to burn high-sulfur residual fuel. Container lines and cruise operators represent the steepest expansion trajectory as retrofit deadlines compress order cycles at shipyards in China, South Korea, and Japan. Open-loop seawater systems dominate deep-sea routes; closed-loop variants penetrate emission control areas with discharge restrictions.
- Power Plants:Coal and oil-fired generation stations deploy flue gas desulfurization for SOx, NOx, and mercury capture under EPA Mercury and Air Toxics Standards. Integrated scrubber-selective catalytic reduction configurations address multi-pollutant compliance. The segment favors high-reliability redundant designs given grid stability requirements and continuous emission monitoring enforcement.
- Chemical Processing:Petrochemical and specialty chemical facilities neutralize acid gases from chlorination, nitration, and sulfur recovery operations.
- Metal Refining:Smelters and foundries capture metal fume, SO2, and acid mist from roasting, converting, and electrolytic processes.
- Waste Incineration:Municipal and hazardous waste combustors scrub acid gases and heavy metals from flue gas under stringent residual risk standards.
- Pulp & Paper:Recovery boilers and lime kilns treat TRS compounds and particulate emissions from kraft pulping operations.
Maritime retrofit urgency is accelerating fastest; power plant replacement cycles sustain steady replacement demand.
End User:
Customer type segmentation reveals divergent procurement sophistication, financing capacity, and regulatory enforcement exposure across facility categories.
- Manufacturing Facilities:Industrial plants across automotive, electronics, and food processing deploy scrubbers for process ventilation and combustion exhaust treatment. OSHA Permissible Exposure Limits and state air quality permits drive specification. The segment favors compact modular units for retrofit constraints and phased capacity expansion.
- Municipal Facilities:Publicly owned wastewater treatment plants and waste-to-energy facilities scrub digester gas and incinerator emissions under delegated federal standards. Procurement through municipal bond financing favors lifecycle cost evaluation and extended warranty terms. The segment exhibits price sensitivity offset by availability of EPA Clean Water State Revolving Fund support for environmental infrastructure.
- Mining Operations:Mineral processing and smelting sites capture dust, acid gases, and metal vapors from crushing, grinding, and pyrometallurgical operations.
Private manufacturing procurement emphasizes rapid deployment; municipal acquisition prioritizes lifecycle cost certainty and regulatory defensibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO 2020 enforcement and port state discharge regulations are redistributing scrubber demand across major maritime economies. Shipyard capacity constraints in East Asia are diverting retrofit orders toward emerging repair clusters.
China
State subsidies for green shipbuilding and MEE enforcement of emission control area rules drive domestic scrubber specification. The dual carbon goals framework accelerates adoption across Yangtze River Delta shipyards. Shanghai and Jiangsu province host integrated newbuild facilities where scrubber integration costs run below aftermarket retrofit rates.
South Korea
KSOE and HHI order backlogs compress dry-dock availability for retrofits as newbuild deliveries prioritize scrubber-ready vessels. MFDS maritime equipment certification requirements shape supplier qualification timelines. Busan-Ulsan shipbuilding clusters anchor exhaust gas cleaning system fabrication for export markets.
Japan
METI funding for next-generation ship technology supports hybrid scrubber development for domestic coastal fleets. JIS standards compliance creates certification barriers for foreign equipment suppliers. Nagoya and Kobe shipyards specialize in cruise and ferry segment retrofits with compact system configurations.
Singapore
MPA discharge water quality standards for open-loop scrubbers force technology selection toward closed-loop or hybrid systems. The port's bunker fuel trading dominance creates fuel price spread monitoring that influences scrubber payback calculations. Tuas shipyard expansion targets regional retrofit demand from Southeast Asian flag vessels.
Germany
EU Green Deal carbon border adjustments and sustainable shipping initiatives reward scrubber-equipped vessels in EU port calls. KBA maritime safety oversight intersects with ECHA chemical discharge regulations for closed-loop effluent treatment. Hamburg and Bremen shipyards integrate scrubber-wastewater treatment convergence systems for cruise operator specifications.
Scrubber System Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with marine equipment heritage. Market structure concentrates around exhaust gas cleaning specialists with classification society pre-approval advantages and diversified environmental technology portfolios with cross-sector scrubber deployment capabilities. Strategic archetypes include integrated engine-exhaust system bundlers, standalone scrubber pure-plays, and diversified pollution control conglomerates. Dominant competitive moves encompass hybrid system development to address port state regulatory divergence and vertical integration into onboard water treatment to capture bundled compliance spending.
Among Nordic industrial conglomerates, Alfa Laval and Wärtsilä occupy positions reflecting deep maritime equipment integration. Alfa Laval represents the exhaust gas cleaning pure-play archetype with open-loop system dominance. Wärtsilä exemplifies the engine-scrubber bundling model through integrated propulsion-environmental compliance packages. GEA Group anchors the diversified industrial technology tier with specialized compact designs for passenger vessel segments. These three entities collectively illustrate the competitive spectrum from standalone exhaust treatment to embedded engine system integration.
| Leading Market Players |
|---|
| Alfa Laval |
| Wärtsilä |
| GEA Group |
| Babcock & Wilcox |
| Yara Marine Technologies |
| CECO Environmental |
| Evoqua Water Technologies |
| Valmet |
| Fuji Electric |
| Others |
Cost & Logistics Intelligence
Shipyard capacity utilization above 85% in South Korea and Japan compresses fabrication lead times and elevates price floors for scrubber retrofits, while newbuild integration slots command premiums that reshape supplier margin structures across East Asian manufacturing clusters.
Pricing Analysis
Certification level (IMO DCS/MEPC-grade) creates the primary spread between premium and standard tier offerings. Project-based contracting dominates, with price differentiation hinging on classification society pre-approval status and after-sales service bundling. Cost compression in open-loop systems is intensifying because stainless steel input volatility erodes fabrication margins. Bulk carrier operators exhibit highest price sensitivity due to spot market exposure, while cruise lines accept premium positioning for compact hybrid configurations.
Supply Chain Analysis
Inventory cycles for Grade 316L stainless and specialized pump assemblies now stretch 14-20 weeks, forcing dry-dock scheduling coordination. Manufacturing concentrates in China, South Korea, and Germany, with raw material sourcing drawing from nickel processing in Indonesia and molybdenum refining in Chile. Single-source vulnerability sits with specialized marine pump suppliers. Distribution runs through shipyard direct procurement and classification society-certified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scrubber system fabrication demands scarce welding certification for duplex stainless assemblies and integrated water treatment engineering, creating bottlenecks that favor incumbents with captive classification society relationships over pure-play entrants lacking marine equipment heritage.
For Market Incumbents: Consolidate hybrid scrubber development capabilities to address port state regulatory divergence between EU discharge rules and Asian open-loop acceptance. Add closed-loop water treatment capacity in Germany to capture bundled compliance spending from cruise operators. LNG dual-fuel engine investments by container lines threaten long-term scrubber retrofit volumes. For New Entrants and Emerging Players: Aftermarket service coverage gaps in India and the Middle East present white-space targets where Alang-Sosiya repair clusters lack OEM-certified support infrastructure. Target scrubber-wastewater treatment convergence for EU-flag vessels facing combined ECHA discharge and carbon border adjustment scrutiny. Pursue classification society pre-approval as the primary go-to-market credential. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among scrubber pure-plays with long-term service contracts tied to IMO DCS recertification cycles. Five-to-ten year viability favors suppliers with engine-scrubber bundling capabilities or integrated water treatment portfolios. Monitor LNG bunker price spreads at Singapore and Rotterdam as the inflection signal for scrubber payback economics versus fuel switching.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Scrubber Development | Dual-mode systems address EU-Singapore discharge rule conflicts for container lines. |
| Backward Integration into Water Treatment | Captive effluent processing capabilities satisfy ECHA chemical discharge regulations. |
| Classification Society Pre-Approval | IMO DCS certification accelerates revenue recognition across flag administration variations. |
| India Ship Repair Expansion | Alang-Sosiya capacity captures South Asian retrofit demand outside East Asian yard queues. |
| Long-Term Service Contracting | Recurring revenue streams attach to mandatory MARPOL Annex VI recertification cycles. |
Research Approach
The analysis maps wet scrubber retrofits, dry scrubber mining applications, hybrid maritime systems, and integrated water treatment convergence, each validated through shipyard procurement officers, classification society surveyors, marine equipment distributors, and exhaust gas cleaning engineering directors. Primary fieldwork combined with secondary validation from IMO MEPC submissions, Lloyd's Register certification databases, customs trade records for stainless steel marine equipment, and SEC filings from listed industrial conglomerates. Bottom-up vessel orderbook analysis and top-down regulatory compliance modeling were triangulated.
Consistency checks against Lloyd's List retrofit tracking and Clarksons newbuild specification data validated volume outputs across the projection horizon. Segmentation dimensions modeled include product type, technology configuration, application sector, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical installation rates against regulatory deadline clustering. Industry-specific inputs encompassed shipyard capacity utilization rates and port state enforcement variance indices.
Material uncertainties — nickel and molybdenum commodity swings, port state discharge rule harmonization failures, LNG bunker infrastructure buildout pace — sit outside the modeled envelope. Forecasts reflect documented assumptions about IMO MARPOL Annex VI adherence timelines and classification society certification throughput. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market