
 Gas Cleaning Technologies Market | 2026-2036
Gas Cleaning Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Cleaning Technologies Market Analytics
A shift from single-source equipment procurement toward multi-source service partnerships is rebalancing vendor relationships across the gas cleaning sector. ANDRITZ Group leverages its integrated engineering capabilities to anchor long-term maintenance contracts with European utilities. Siemens AG competes through digital twin diagnostics bundled with precipitator hardware. ALFA LAVAL AB specializes in compact scrubber systems for maritime and offshore applications where space constraints dominate.
Gas cleaning technologies encompass particulate capture, acid gas removal, and volatile organic compound abatement systems operating at temperatures from ambient to 400°C and pressure drops of 2-20 mbar. Wet scrubbers achieve sulfur dioxide removal efficiencies exceeding 95% through limestone-gypsum or seawater alkalinity loops, serving coal-fired power stations and marine exhaust streams. Fabric filters command the largest installed base in cement and steel manufacturing where particulate limits have tightened, while activated carbon adsorbers represent the fastest-growing segment driven by mercury and dioxin control mandates in waste incineration. Electrostatic precipitators retain margin concentration in high-volume power generation due to lower operating costs at scale.
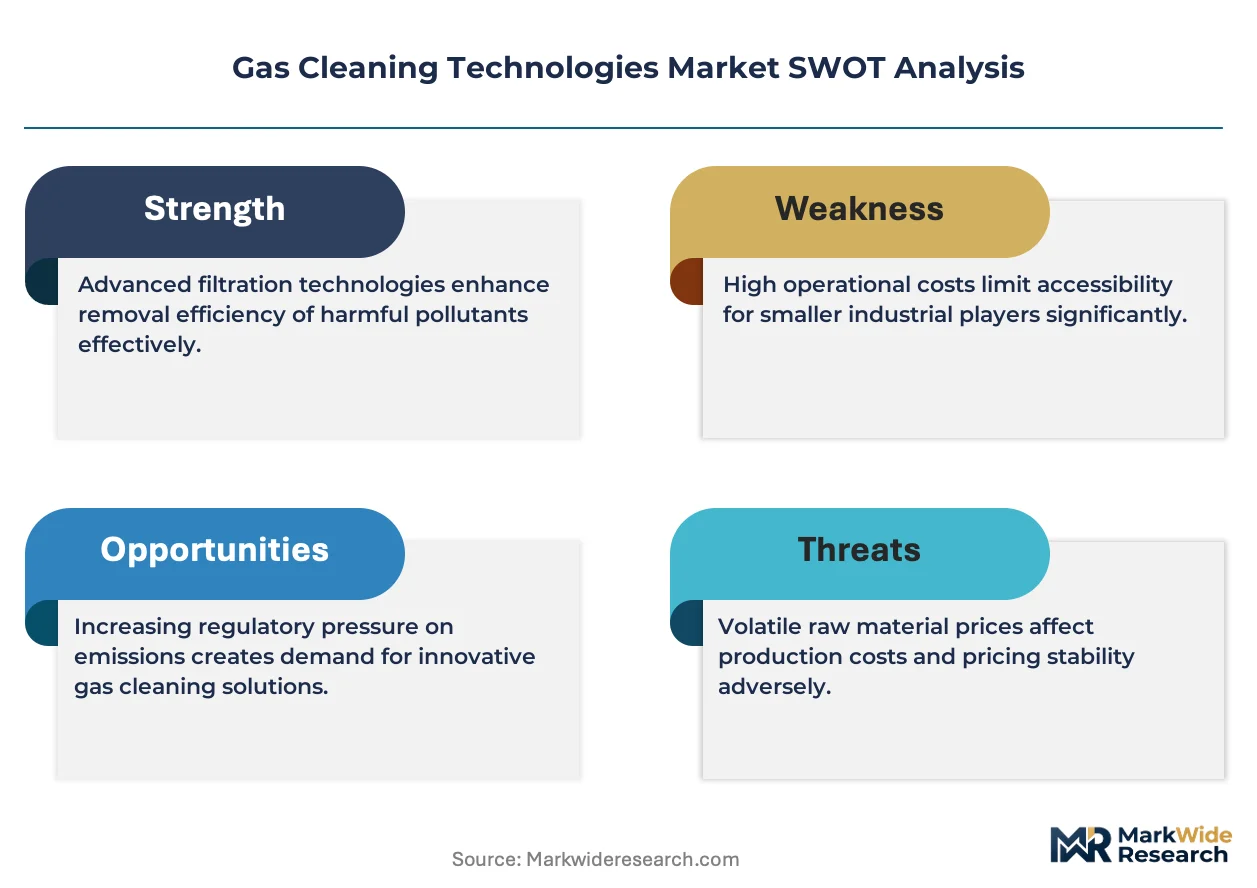
The US EPA Mercury and Air Toxics Standards and the EU Industrial Emissions Directive force continuous monitoring and retrofit investments across thermal power fleets. China's MEE enforces ultra-low emission limits of 10 mg per cubic meter for particulates, compelling utilities to stack multiple cleaning stages. Stakeholders must weigh capex intensity against operating-life cost curves as carbon border adjustments begin linking emission performance to trade access.
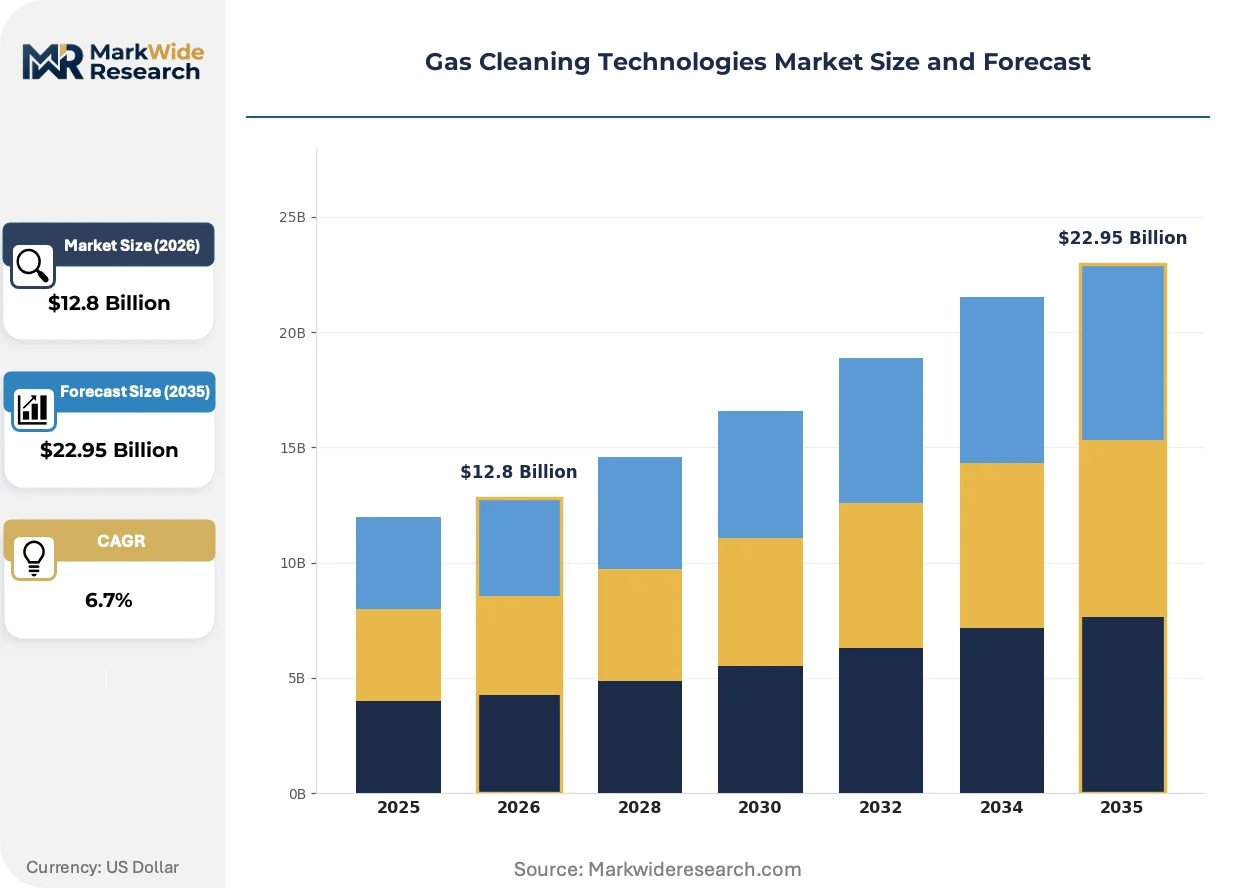
Market Dynamics
The US EPA Mercury and Air Toxics Standards and China's ultra-low emission mandates are forcing coal-fired utilities to stack wet scrubbers, fabric filters, and activated carbon injection in multi-stage configurations. This regulatory layering is compressing equipment replacement cycles and rebalancing vendor relationships toward integrated service partnerships.
Growth Catalysts
- EU Industrial Emissions Directive:Continuous monitoring mandates across thermal power fleets in Germany, Poland, and Italy are accelerating electrostatic precipitator retrofits and digital twin diagnostics adoption.
- Maritime sulfur caps:The International Maritime Organization's 0.5% sulfur limit has opened demand for seawater scrubber systems on container vessels and cruise ships operating in European and Asian waters.
- Waste-to-energy expansion:Dioxin and mercury control mandates in Japanese and South Korean incineration plants are driving activated carbon adsorber installations for flue gas polishing.
Market Restraints
- Specialty alloy costs:Nickel and molybdenum price volatility directly impacts wet scrubber vessel fabrication costs, squeezing margins on large utility contracts.
- Limestone supply concentration:High-purity limestone for flue gas desulfurization concentrates in specific mining districts, exposing scrubber operators to regional supply disruptions.
- Electrostatic precipitator limitations:Sub-micron particulate capture inefficiencies below 1 micrometer restrict ESP deployment in cement kiln applications without upstream conditioning.
Strategic Opportunities
- Indian utility compliance:Central Electricity Authority deadlines for particulate, sulfur dioxide, and nitrogen oxide limits are creating retrofit demand across 166 gigawatts of coal capacity.
- Carbon capture integration:Amine-based post-combustion capture systems are converging with existing scrubber infrastructure, opening bundled engineering contracts for dual-purpose gas treatment trains.
- Green hydrogen off-gas treatment:Electrolyzer facilities require hydrogen sulfide and moisture removal systems, representing emerging demand from renewable hydrogen clusters in Spain and Australia.
Industry Challenges
- Wet chemistry expertise scarcity:Operating limestone-gypsum scrubber loops requires specialized process engineers familiar with pH control, oxidation air management, and dewatering optimization.
- Legacy control system integration:Retrofitting digital monitoring and automated reagent dosing onto 1980s-vintage precipitator and scrubber installations demands custom PLC programming and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Cleaning Technologies Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrostatic Precipitators, Wet Scrubbers, Fabric Filters, Activated Carbon Adsorbers Application: Power Generation, Petrochemical, Manufacturing, Waste Incineration End User: Utilities, Industrial Sector, Oil & Gas, Thermal Plants Service Type: Installation, Maintenance, Consulting, Upgradation |
| Companies Covered | Yara Marine Technologies AS, ANDRITZ Group, Siemens AG, GEA Group AG, Fuji Electric Co. Ltd., General Electric Company, Johnson Matthey, ALFA LAVAL AB, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Cleaning Technologies Market Evolving Landscape
Equipment vendors are bundling hardware with predictive maintenance software, while membrane and catalytic materials science opens new temperature and pressure operating windows. These shifts are compressing pure equipment margins and elevating service contract value capture.
Ceramic membrane filtration for hot gas cleaning is converging with existing baghouse infrastructure in steel and cement applications. Nippon Steel and ArcelorMittal facilities in Japan and Belgium are piloting silicon carbide membranes operating at 350°C, eliminating upstream cooling requirements. This convergence is compressing footprint and energy penalties associated with traditional fabric filter arrangements.
China's Ministry of Ecology and Environment enforcement of 10 mg per cubic meter particulate limits is forcing utilities to install wet electrostatic precipitators downstream of dry ESPs and scrubbers. Shandong and Hebei province power plants are deploying three-stage cleaning trains. The incremental capital burden is accelerating equipment finance leasing structures and performance-guaranteed service contracts.
Asset owners are unbundling after-sales service from original equipment procurement, creating openings for independent maintenance specialists. European utilities in Germany and the Netherlands are separating 10-year spare parts and inspection contracts from initial scrubber or precipitator purchases. This pattern is most visible in biomass co-firing retrofits where operational risk transfer outweighs first-cost minimization.
Gas Cleaning Technologies Market Segmentation
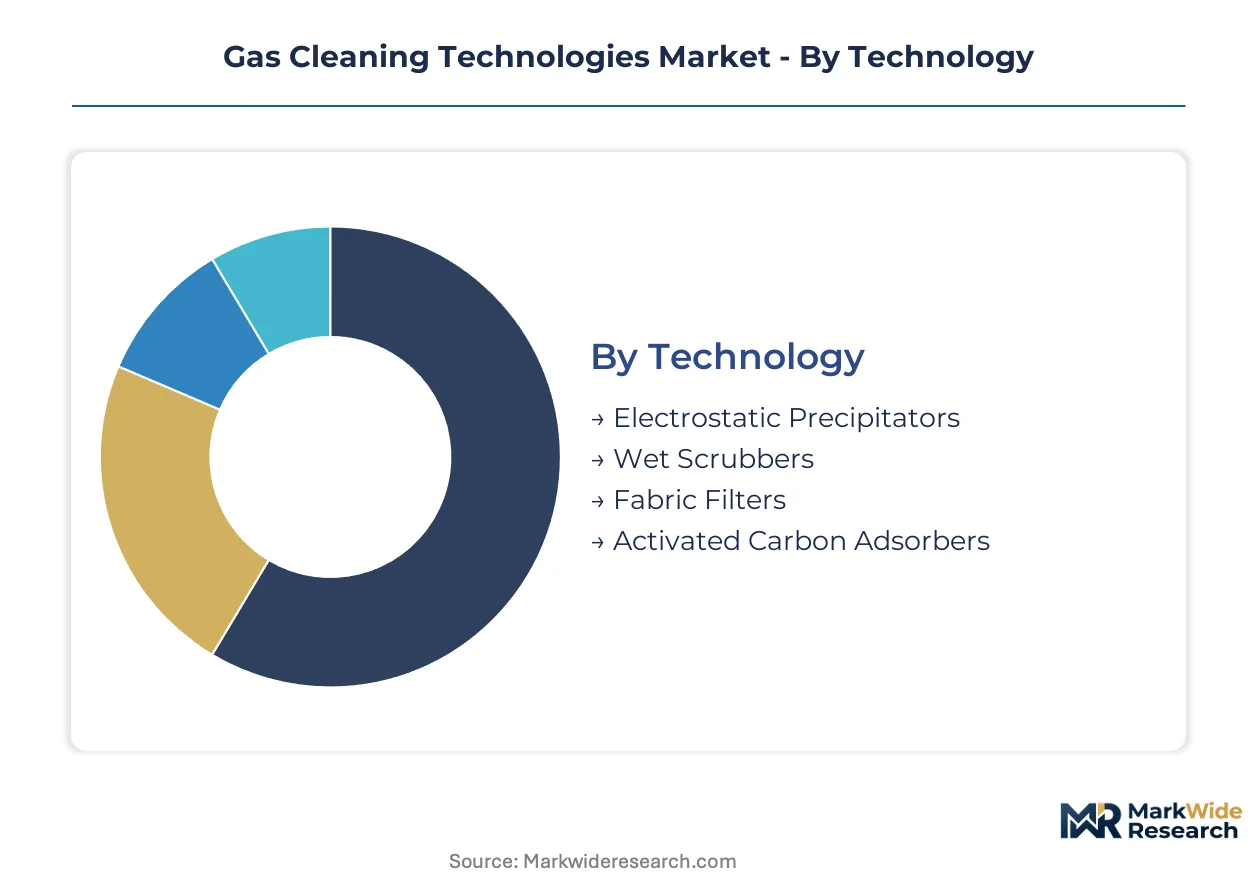
Technology selection in gas cleaning hinges on particulate size distribution, gas temperature, and contaminant chemistry. Vendors configure multi-stage trains when single-system efficiency falls short of regulatory limits.
Technology:
Supply concentration in high-temperature materials and precision electrode fabrication shapes competitive dynamics across equipment categories.
- Electrostatic Precipitators:High-voltage discharge electrodes ionize particulate matter for collection on grounded plates. Coal-fired utilities in India and China deploy dry ESPs as first-stage capture before wet polishing systems. Operating costs scale favorably above 500,000 cubic meters per hour.
- Wet Scrubbers:Limestone-gypsum or seawater alkalinity loops absorb sulfur dioxide and acid gases through liquid-gas contact. German and Polish power stations favor these for retrofit compatibility with existing stacks. Nickel-alloy vessel fabrication concentrates among specialty metal fabricators in northern Europe.
- Fabric Filters:Woven or felted media achieve sub-micron capture in cement and steel manufacturing. Baghouse suppliers in Japan and Belgium are piloting ceramic membrane integration.
- Activated Carbon Adsorbers:Porous carbon structures capture mercury and dioxins in waste incineration flue gas. Japanese and South Korean facilities drive demand for mobile injection systems.
Electrostatic precipitators absorb the bulk of installed capacity; activated carbon adsorbers are expanding most quickly.
Application:
Cost tier differentiation separates continuous-duty base load operations from intermittent industrial processes with variable contaminant loading.
- Power Generation:Coal and biomass-fired stations require multi-stage particulate, sulfur, and nitrogen oxide control. China's MEE enforcement of 10 mg per cubic meter particulate limits forces three-stage cleaning trains in Shandong and Hebei provinces.
- Petrochemical:Fluid catalytic cracker regenerators and sulfur recovery units handle high-temperature, corrosive streams. Gulf Coast US facilities prioritize wet scrubber reliability for continuous refinery operations.
- Manufacturing:Cement kilns and steel electric arc furnaces emit alkaline dust and metal fumes. ESP limitations below 1 micrometer drive fabric filter adoption in European cement plants.
- Waste Incineration:Municipal and medical waste combustion releases dioxins, furans, and heavy metals. EU Industrial Emissions Directive mandates activated carbon injection for flue gas polishing.
Power generation commands the highest absolute investment; waste incineration shows the steepest expansion trajectory.
End User:
Customer type determines procurement structure, with utilities favoring long-term service contracts and industrial operators prioritizing capital efficiency.
- Utilities:State-owned and independent power producers operate under continuous emission monitoring mandates. India's Central Electricity Authority deadlines are accelerating retrofit demand across 166 gigawatts of coal capacity.
- Industrial Sector:Cement, steel, and chemical manufacturers face site-specific permit limits. German industrial clusters bundle scrubber maintenance through regional service consortiums.
- Oil & Gas:Refineries and LNG terminals treat acid gas and volatile organic compound streams. Maritime sulfur caps are extending scrubber demand to bunker fuel treatment at port facilities.
- Thermal Plants:Cogeneration and district heating facilities balance efficiency against emission performance. Biomass co-firing retrofits in the Netherlands separate equipment purchase from 10-year operational risk contracts.
Utilities absorb the bulk of installed capacity; the industrial sector is gaining share fastest.
Service Type:
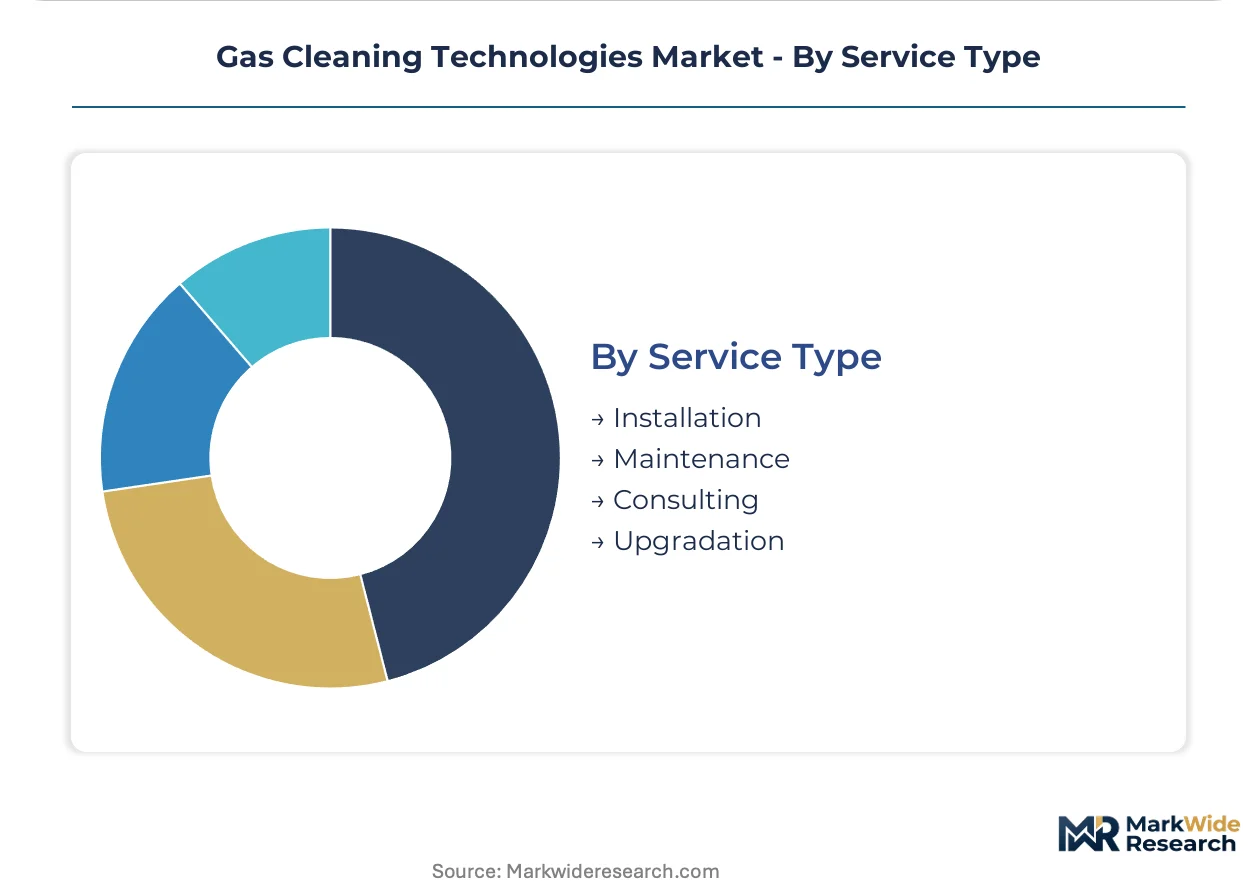
Margin structure shifts from hardware toward recurring revenue as asset owners unbundle after-sales support from original equipment procurement.
- Installation:Turnkey erection of precipitator fields, scrubber vessels, and ductwork requires heavy-lift coordination and welded pressure vessel certification.
- Maintenance:Scheduled inspection, electrode rapping system adjustment, and bag replacement contracts. European utilities are separating 10-year spare parts agreements from initial purchases.
- Consulting:Process optimization studies for reagent dosing, pH control, and dewatering efficiency. Wet chemistry expertise scarcity limits supplier pool depth.
- Upgradation:Digital twin diagnostics and automated control retrofits onto 1980s-vintage installations. Siemens AG bundles predictive software with precipitator hardware in German utility contracts.
Installation absorbs the bulk of historical revenue; maintenance is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal-fired utilities in China, India, and Germany absorb the largest retrofit investments as emission deadlines compress procurement cycles. Maritime scrubber demand concentrates in European and Asian port clusters responding to IMO sulfur enforcement.
China
Shandong and Hebei province power plants deploy three-stage cleaning trains combining dry ESPs, wet scrubbers, and wet electrostatic precipitators. MEE enforcement of 10 mg per cubic meter particulate limits forces equipment stacking. Utilities in these northern industrial corridors accelerate performance-guaranteed service contracts to spread capital burdens.
Germany
Rhineland and Lusatian lignite stations drive electrostatic precipitator retrofits and digital monitoring upgrades. EU Industrial Emissions Directive continuous monitoring mandates compress replacement timelines. Industrial clusters around Cologne and Leipzig bundle scrubber maintenance through regional service consortiums.
India
Maharashtra and Gujarat utilities face Central Electricity Authority deadlines for particulate, sulfur dioxide, and nitrogen oxide compliance across 166 gigawatts of coal capacity. CEA enforcement timelines create concentrated demand for fabric filter and wet scrubber installations. Plants in the western industrial belt prioritize operational risk transfer contracts over first-cost minimization.
United States
Gulf Coast refineries prioritize wet scrubber reliability for fluid catalytic cracker regenerators and sulfur recovery units. EPA Mercury and Air Toxics Standards force continuous monitoring investments across thermal power fleets. Houston and Port Arthur facilities anchor demand for high-temperature, corrosive stream handling systems.
Japan
Kanto and Kansai waste-to-energy plants drive activated carbon adsorber installations for dioxin and mercury control. METI-backed emission standards for incineration facilities mandate flue gas polishing. Tokyo and Osaka metropolitan clusters represent concentrated demand for mobile injection systems.
Gas Cleaning Technologies Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle hardware with long-term service agreements. The vendor base splits between integrated engineering conglomerates and specialized materials fabricators. Two strategic archetypes prevail: full-service providers anchoring multi-decade utility contracts, and niche specialists capturing maritime and industrial segments. M&A activity and technology licensing agreements represent the primary competitive moves reshaping positioning.
Within the integrated engineering tier, ANDRITZ Group and Siemens AG exemplify full-service providers leveraging digital diagnostics and maintenance bundling. ALFA LAVAL AB occupies a specialist position targeting space-constrained maritime applications. These three companies represent divergent strategic postures across the equipment-service spectrum.
| Leading Market Players |
|---|
| Yara Marine Technologies AS |
| ANDRITZ Group |
| Siemens AG |
| GEA Group AG |
| Fuji Electric Co. Ltd. |
| General Electric Company |
| Johnson Matthey |
| ALFA LAVAL AB |
| Mitsubishi Heavy Industries |
| Others |
Value Network & Pricing Analysis
Nickel and molybdenum alloy costs cascade through wet scrubber fabrication tiers, compressing margins on large utility contracts while elevating premium pricing for seawater scrubber systems serving IMO-compliant maritime fleets. Limestone supply concentration in specific mining districts exposes operators to regional disruptions, forcing buyers into long-term offtake agreements that lock in reagent costs across the equipment lifecycle.
Pricing Analysis
Volume-driven utility contracts trade margin for market share while specialized maritime and waste incineration systems capture premium returns. Three-tier pricing structure across premium, standard, and economy levels separates performance-guaranteed service bundles from bare equipment procurement. Pricing pressure stems from nickel price volatility squeezing vessel fabricators in northern Europe. Industrial operators in cement and steel manufacturing exhibit highest price sensitivity, whereas utilities prioritize operational risk transfer over first-cost minimization.
Supply Chain Analysis
Welding specialists and pressure vessel certified fabricators concentrate in Germany, Poland, and northern China where industrial gas cleaning demand is densest. Supply chains draw from high-purity limestone deposits, nickel alloy stock, and ceramic membrane substrates. Single-source vulnerability in specialty alloy supply creates exposure to commodity price swings. Distribution runs through EPC contractors and regional service consortiums that bundle installation with long-term maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply-constrained conditions where wet chemistry expertise scarcity props pricing power for service-integrated vendors. Fabric filter and ceramic membrane capacity expansion lags demand acceleration from China's MEE enforcement timelines.
For Market Incumbents: Deepen backward integration into nickel alloy vessel fabrication to defend margins against specialty metal price volatility. Anchor multi-decade utility contracts through digital twin diagnostics bundling, neutralizing emerging independent maintenance specialists. Prioritize certification investment for ultra-low emission compliance in Shandong and Hebei province power plants. For New Entrants and Emerging Players: Launch via independent maintenance contracts unbundled from original equipment procurement, targeting European biomass co-firing retrofits where operational risk transfer outweighs first-cost sensitivity. Penetrate green hydrogen off-gas treatment clusters in Spain and Australia before electrolyzer capacity scales. Lead with modular scrubber skids for space-constrained maritime applications. For Investors and Strategic Acquirers: Indian CEA deadline enforcement is the leading indicator that retrofit demand across 166 gigawatts of coal capacity will concentrate procurement cycles and elevate service contract valuations. Long-term viability centers on vendors with integrated engineering capabilities spanning hardware, digital diagnostics, and wet chemistry expertise. Monitor limestone supply disruption frequency as the signal for reagent cost pass-through pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | Captive nickel and molybdenum supply insulates German fabricators from commodity volatility squeezing wet scrubber margins. |
| Digital Twin Diagnostics Bundling | Siemens AG anchors German utility contracts by combining predictive software with electrostatic precipitator hardware retrofits. |
| Seawater Scrubber Capacity Expansion | IMO sulfur enforcement in European and Asian waters opens demand for compact systems from Yara Marine and ALFA LAVAL. |
| Performance-Guaranteed Service Contracts | Chinese utilities in Shandong spread capital burdens through leasing structures tied to 10 mg particulate compliance outcomes. |
| Ceramic Membrane Pilot Scale-Up | Nippon Steel and ArcelorMittal facilities in Japan and Belgium validate 350°C operation eliminating upstream cooling. |
Research Methodology
Multi-period observation of EPA MATS enforcement timelines, EU Industrial Emissions Directive adoption curves, and MEE ultra-low emission compliance rates anchored the trend analysis, supplemented by interviews with plant engineers at coal-fired utilities, scrubber procurement leads at EPC contractors, aftermarket service heads, and wet chemistry process specialists. Secondary validation drew from EPA enforcement databases, EU ETS emissions disclosures, Chinese MEE inspection reports, and customs data on nickel alloy imports. Bottom-up equipment installation tracking and top-down regulatory mandate sizing were triangulated to constrain forecast variance.
Input-output matrices mapped technology adoption across power generation, petrochemical, manufacturing, and waste incineration applications, with segmentation dimensions spanning equipment type, end-use industry, service model, and regional regulatory framework. CAGRs were derived from installed base turnover rates and retrofit cycle compression under compliance deadlines. Forecast inputs incorporated limestone reagent cost trajectories, specialty alloy price indices, and maritime sulfur cap enforcement intensity.
Regulatory deadline delays, nickel supply disruption events, and ceramic membrane scale-up failures are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about continuous monitoring mandate adherence and multi-stage cleaning train adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Natural Refrigerants Market