
 Europe Nuclear Reactor Construction Market | 2026-2036
Europe Nuclear Reactor Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuclear Reactor Construction Market Foresight
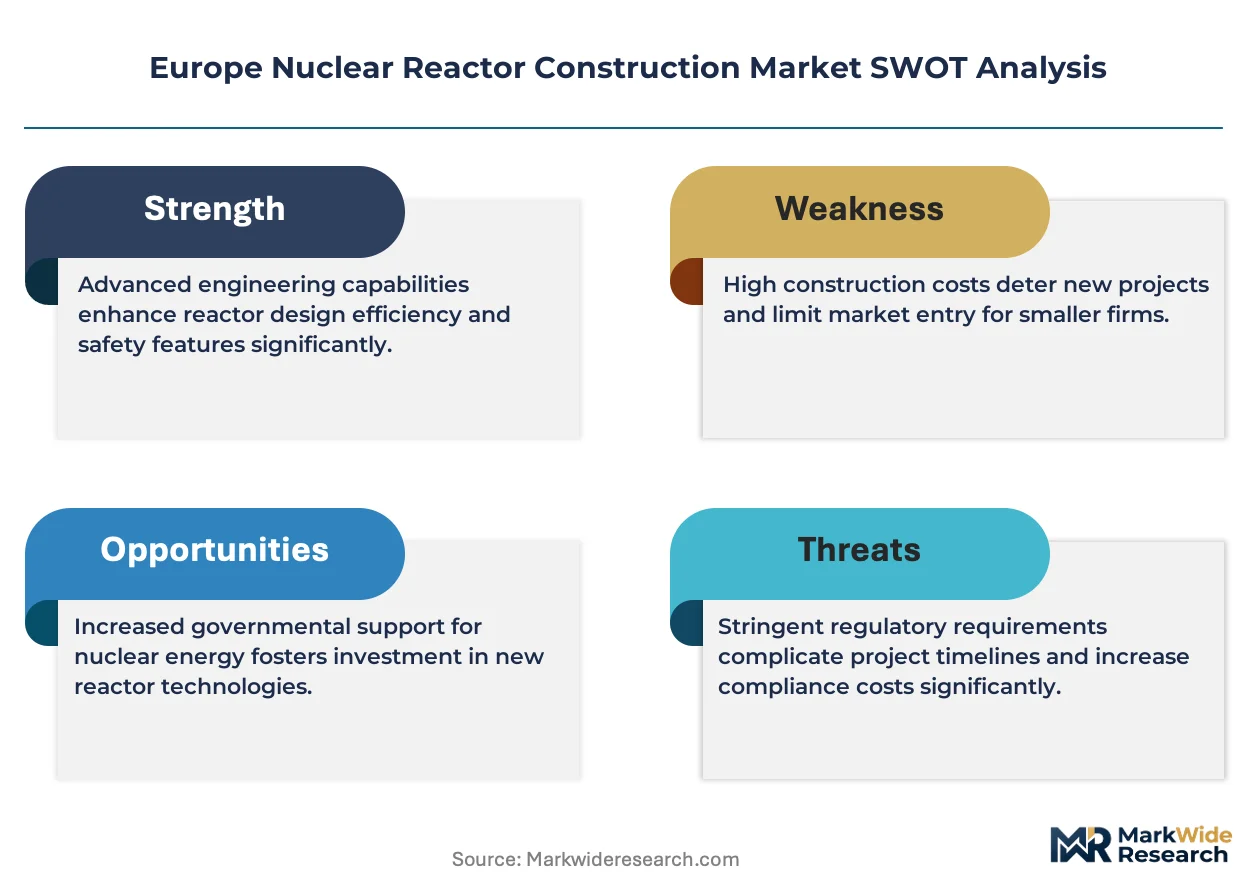
A specialized welding and reactor pressure vessel fabrication workforce shortage is redrawing project timelines across Europe. Framatome leverages its integrated fuel and reactor design capabilities to sustain long-term service contracts with French operators. Electricite de France SA anchors the continent's largest new-build pipeline with multiple EPR units under development. Westinghouse Electric Company LLC competes on AP1000 technology transfer and localization potential in Eastern European markets.
Europe nuclear reactor construction encompasses the engineering, procurement, and assembly of fission-based power systems requiring steel containment structures rated for seismic loads and loss-of-coolant accidents, with primary purpose of delivering grid-scale baseload electricity. Pressurized Water Reactor deployments dominate committed capacity due to decades of operational experience and established supply chains, while Generation IV Reactor concepts attract public R&D funding for longer-term commercialization. Modular Reactor technology is gaining traction among private investors seeking smaller capital commitments and faster deployment schedules compared to gigawatt-scale projects.
France's ASN, Finland's STUK, and the UK's ONR each enforce distinct licensing frameworks that shape vendor qualification requirements and construction quality assurance protocols. The EU Green Deal classification of nuclear as transitional energy under the Taxonomy Regulation unlocks green financing channels for eligible projects. Stakeholders must monitor evolving national position statements on nuclear inclusion in renewable energy targets and corresponding grid interconnection priority rules.
Market Dynamics
Utility commitments to baseload expansion are colliding with a contracting specialized welding workforce, forcing reactor vendors to restructure project delivery models across the continent. This labor scarcity is compressing construction timelines and elevating quality assurance costs for steel containment fabrication.
Growth Catalysts
- EU Green Deal Taxonomy:The EU Green Deal classification of nuclear as transitional energy unlocks green financing channels for eligible reactor projects. Institutional investors now channel capital toward construction programs that meet EU Taxonomy technical screening criteria.
- Finland's STUK licensing:STUK's streamlined design certification process for evolutionary reactor designs accelerates vendor qualification timelines. Finnish regulatory precedent reduces duplication costs for subsequent European deployments.
- Modular reactor technology:Small Modular Reactor designs attract private capital seeking reduced capital exposure and faster deployment schedules compared to gigawatt-scale builds.
Market Restraints
- Forged component supply concentration:Reactor pressure vessel forging capacity concentrates among a handful of specialized facilities, creating single-point-of-failure exposure for European new-build schedules.
- ASN construction code stringency:France's ASN enforces seismic and loss-of-coolant accident standards that elevate engineering man-hours and extend pre-construction licensing phases.
- Renewable energy substitution:Grid-scale solar and offshore wind projects compete for offtake contracts and transmission interconnection priority in national energy plans.
Strategic Opportunities
- Eastern European new-build programs:Poland and the Czech Republic are advancing first-of-a-kind reactor commitments where AP1000 technology transfer agreements create localization partnerships.
- Generation IV R&D funding:Public research programs for sodium-cooled fast reactors and high-temperature gas reactors open long-term commercialization pathways beyond conventional PWR designs.
- Digital twin integration:Convergence of physics-based modeling and real-time sensor networks enables predictive maintenance contracts that extend vendor revenue streams across reactor operating lifetimes.
Industry Challenges
- Reactor pressure vessel welding certification:The specialized workforce capable of ASME Section IX-qualified nuclear welding is aging out faster than training pipelines can replenish.
- Multi-jurisdiction licensing complexity:France's ASN, Finland's STUK, and the UK's ONR each enforce distinct quality assurance protocols that fragment vendor standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuclear Reactor Construction Market |
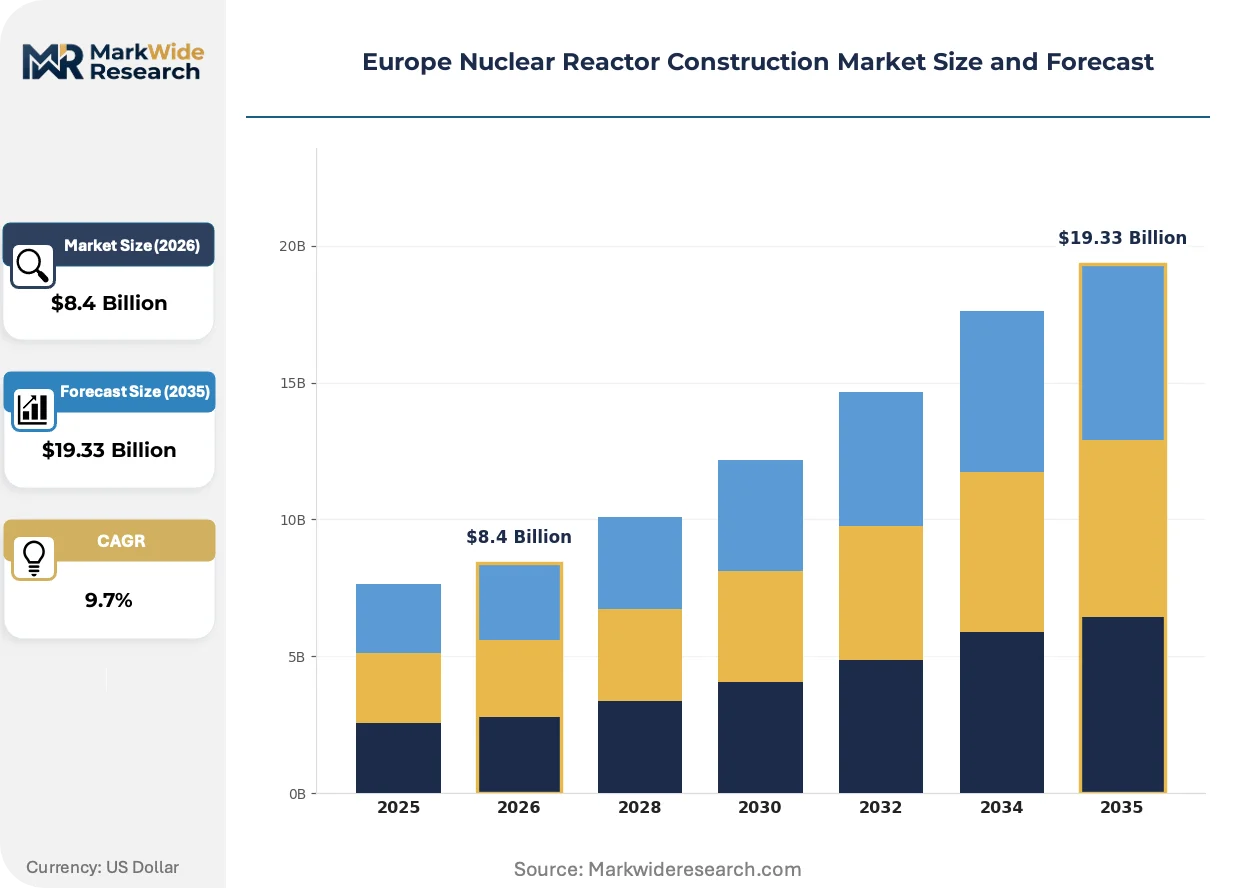
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Generation IV Reactor Technology: Modular Reactor, Advanced Reactor, Fuel Cycle Technology, Hybrid Reactor End User: Utility Companies, Government Agencies, Research Institutions, Private Investors Application: Power Generation, Research, Desalination, Medical Isotope Production |
| Companies Covered | Mitsubishi Heavy Industries Ltd, Framatome, Rosatom State Nuclear Energy Corporation, KEPCO Engineering & Construction, SKODA JS a.s., Electricite de France SA, GE Hitachi Nuclear Energy, Doosan Heavy Industries & Construction, Westinghouse Electric Company LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuclear Reactor Construction Market Shifts & Advancements
Reactor construction methodology is pivoting from field-erected gigawatt units toward factory-fabricated modular systems that compress site assembly duration. This shift is redrawing supply chain geography and vendor competitive positioning.
Small Modular Reactor technology is miniaturizing core nuclear steam supply system components for rail-transportable delivery. Utility buyers in Poland and the Czech Republic are evaluating SMR deployments for district heating and industrial process steam applications. Factory fabrication is compressing construction risk exposure and enabling serial production economics previously unavailable to nuclear project developers.
The EU Green Deal Taxonomy Regulation is mandating disclosure standards for sustainable finance eligibility. Project developers must now document lifecycle greenhouse gas emissions and waste management plans to access green-labeled capital pools. French and Finnish reactor programs are restructuring procurement specifications to satisfy EU Taxonomy technical screening criteria for climate change mitigation.
Long-term service agreements are displacing traditional equipment-only sales in vendor-customer relationships. EDF and Framatome are contracting integrated fuel-cycle and maintenance packages that span reactor operating lifetimes. This bundling concentrates buyer-vendor interdependence and locks out competing service providers from installed base access.
Europe Nuclear Reactor Construction Market Segmentation
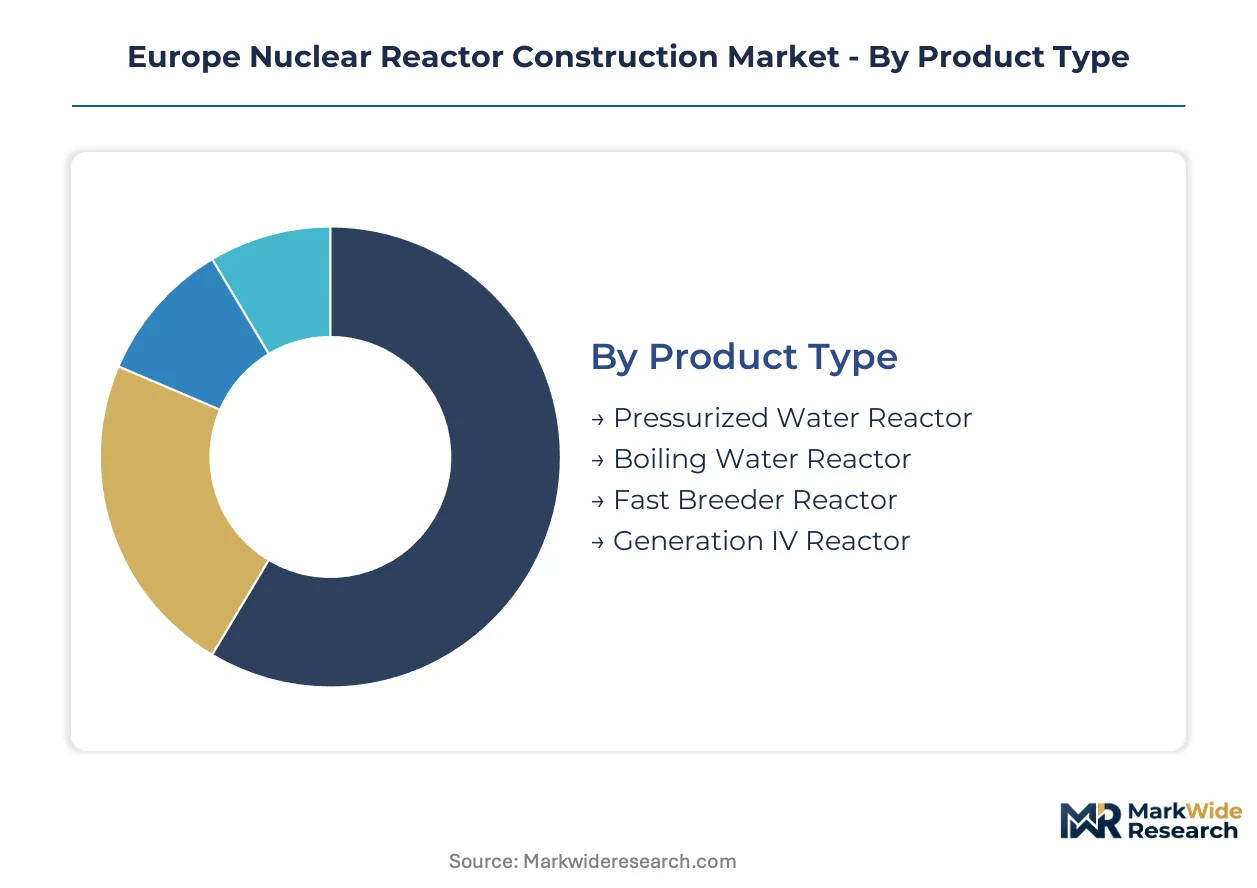
Segmentation reveals how reactor construction demand fragments across technology readiness levels and financing structures. Vendors must align project delivery models with distinct procurement channels serving utilities versus research institutions.
Product Type:
Pressurized Water Reactors dominate utility procurement channels, while Generation IV designs flow through government-funded research programs. Boiling Water and Fast Breeder units occupy narrower application niches with specialized supply chains.
- Pressurized Water Reactor:Steel containment structures rated for seismic loads and loss-of-coolant accidents anchor France's EDF new-build pipeline. Finnish STUK licensing precedent reduces vendor qualification costs for subsequent European deployments.
- Generation IV Reactor:Sodium-cooled fast reactor and high-temperature gas reactor concepts attract public R&D funding for longer-term commercialization beyond conventional PWR designs. French and German research institutions channel grants toward demonstrator projects.
- Boiling Water Reactor:Limited European presence concentrates in Scandinavian markets with specific grid stability requirements.
- Fast Breeder Reactor:Closed fuel cycle capabilities drive interest in France and Russia for plutonium management applications.
By volume, Pressurized Water Reactors lead committed capacity. By growth pace, Generation IV concepts are climbing the fastest through public funding channels.
Technology:
Modular designs reduce capital exposure for private investors, while Advanced Reactors command premium engineering fees from utility buyers. Fuel Cycle and Hybrid technologies serve specialized research and industrial process markets with distinct margin profiles.
- Modular Reactor:Rail-transportable core components enable factory fabrication economics that compress site assembly duration. Polish and Czech utility buyers evaluate SMR deployments for district heating and industrial steam applications.
- Advanced Reactor:Evolutionary PWR designs with passive safety systems qualify for streamlined STUK certification processes. EDF anchors European demand with multiple EPR units under development.
- Fuel Cycle Technology:Integrated enrichment and reprocessing services lock in long-term vendor relationships across reactor operating lifetimes.
- Hybrid Reactor:Dual-purpose configurations serving electricity and process heat markets attract industrial offtake commitments in Eastern Europe.
Modular technology captures the steepest expansion trajectory among private capital sources. Advanced Reactors retain the largest committed order backlog.
End User:
Utility procurement concentrates gigawatt-scale commitments, while Research Institutions drive technology demonstration programs. Government Agencies and Private Investors occupy emerging financing channels reshaping project ownership structures.
- Utility Companies:Baseload capacity expansion commitments from EDF, Fortum, and British Energy anchor continental new-build demand. Long-term power purchase agreements secure project finance for multi-reactor sites.
- Private Investors:Reduced capital exposure through SMR equity structures attracts infrastructure funds seeking faster deployment schedules than gigawatt-scale projects permit.
- Government Agencies:State-backed guarantees de-risk first-of-a-kind deployments in Poland and the Czech Republic.
- Research Institutions:CEA in France and VTT in Finland channel EU framework program funding toward Generation IV demonstrators.
Utility Companies account for the dominant share of committed construction spend. Private Investors are gaining share fastest through modular reactor partnerships.
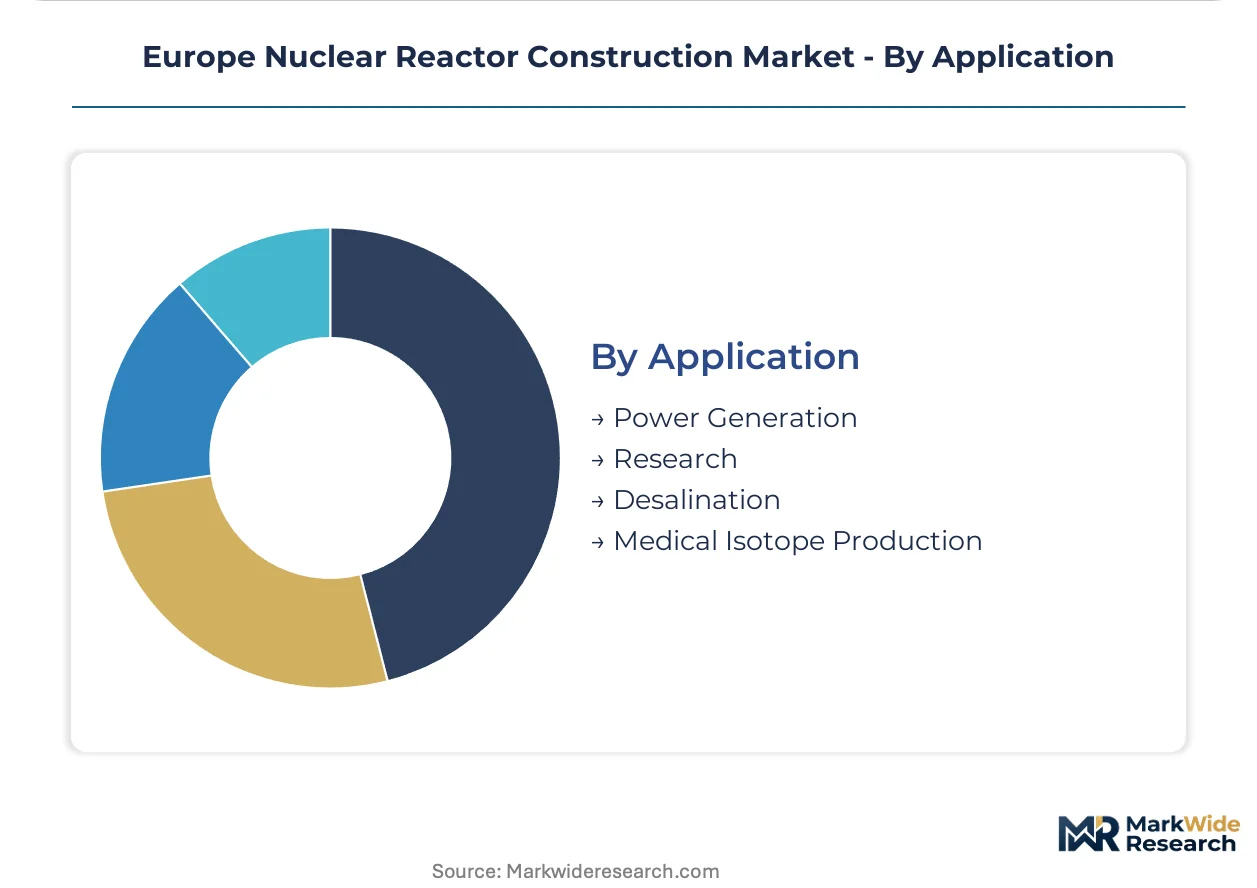
Application:
Power Generation commands standardized containment and turbine island procurement, while Research and Medical Isotope applications require specialized shielding and regulatory pathways. Desalination hybrids attract coastal utility interest in water-stressed Southern European markets.
- Power Generation:Grid-scale baseload electricity delivery drives standardized EPR and AP1000 deployments across France, Finland, and the United Kingdom. EU Green Deal Taxonomy eligibility unlocks green financing for qualifying projects.
- Desalination:Cogeneration configurations serving electricity and potable water markets attract utility interest in Spain and Italy. Process steam integration elevates engineering complexity for containment design.
- Research:Materials testing and neutron science applications drive specialized reactor commissioning at Grenoble and Petten facilities.
- Medical Isotope Production:Molybdenum-99 and iodine-131 supply security motivates dedicated reactor investments in the Netherlands and Belgium.
Power Generation leads by installed capacity commitment. Desalination hybrids are expanding most quickly among coastal utility planners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France deploys gigawatt-scale EPR units for grid baseload, while Poland and the Czech Republic pilot smaller modular designs for industrial process heat. Finland and the United Kingdom pursue evolutionary PWR technology with distinct regulatory pathways. This consumption-mix differential fragments vendor qualification requirements across the continent.
France
EDF anchors the continent's largest new-build pipeline with multiple EPR units under active development. ASN enforces seismic and loss-of-coolant accident standards that elevate engineering man-hours and extend pre-construction licensing phases. The Flamanville site in Normandy hosts first-of-a-kind construction experience that shapes vendor training protocols.
Finland
Olkiluoto-3 commissioning established STUK's streamlined design certification process for evolutionary reactor designs. The Finnish regulator's precedent reduces duplication costs for subsequent European deployments. The Eurajoki municipality clusters specialized welding contractors and containment fabrication specialists serving Nordic markets.
United Kingdom
Hinkley Point C and Sizewell C anchor utility commitments to standardized PWR construction with long-term power purchase agreements. ONR enforces distinct quality assurance protocols that fragment vendor standardization efforts. The Somerset and Suffolk sites concentrate civil engineering capacity for nuclear-grade concrete placement.
Poland
State-backed guarantees de-risk first-of-a-kind deployments as the country advances reactor commitments without prior nuclear generation experience. Government agencies structure technology transfer agreements with AP1000 vendors to build localization partnerships. The Pomeranian region evaluates coastal sites for combined electricity and district heating applications.
Czech Republic
The Dukovany and Temelin operator ČEZ evaluates new-build options to replace aging Soviet-era capacity reaching end-of-design-life. National position statements on EU Taxonomy eligibility unlock green financing channels for eligible projects. The South Bohemian region clusters existing nuclear workforce expertise that vendors target for SMR deployment skills transfer.
Europe Nuclear Reactor Construction Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European nuclear construction. Tier-one vendors bundle reactor design, fuel supply, and lifetime service contracts to lock out competitors from installed base access. Specialist fabricators concentrate on forged pressure vessel components and seismic-rated steel containment where ASME Section IX welding certification creates capability scarcity. The dominant competitive moves are long-term service agreement bundling and technology transfer localization partnerships in Eastern European markets.
Among French-integrated vendors, Electricite de France SA and Framatome exemplify the bundled-service archetype combining construction ownership with fuel-cycle and maintenance packages. Westinghouse Electric Company LLC occupies a position representing Western technology transfer potential in Polish and Czech procurement channels. SKODA JS a.s. anchors Czech-based specialist fabrication capacity serving Central European containment and component requirements.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| Framatome |
| Rosatom State Nuclear Energy Corporation |
| KEPCO Engineering & Construction |
| SKODA JS a.s. |
| Electricite de France SA |
| GE Hitachi Nuclear Energy |
| Doosan Heavy Industries & Construction |
| Westinghouse Electric Company LLC |
| Others |
Supply & Pricing Matrix
Factory-fabricated modular reactor components are displacing field-erected gigawatt units, simultaneously compressing site assembly duration in Eastern Europe and elevating pricing premiums for rail-transportable fabrication capacity. This substitution redraws supply chain geography toward serial production economics while fragmenting vendor competitive positioning across distinct procurement channels.
Pricing Analysis
Long-term power purchase agreements dominate utility procurement, with price differentiation anchored in certification grade under France's ASN codes and volume scale across multi-reactor sites. Cost compression in steel containment fabrication is intensifying because specialized ASME Section IX welding certification creates capability scarcity. Utility buyers demonstrate lowest price sensitivity due to state-backed offtake guarantees, while private SMR investors exhibit highest sensitivity to capital exposure thresholds.
Supply Chain Analysis
Reactor pressure vessel forging capacity concentrates in France, Japan, and South Korea, creating single-point-of-failure exposure for European new-build schedules. The supply chain draws from ultra-heavy steel ingots, zirconium alloy fuel cladding, and seismic-rated concrete aggregates. Single-source vulnerability sits with forged component supply concentration. Distribution runs through EPC contractors bundling engineering, procurement, and construction risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal Taxonomy Regulation's classification of nuclear as transitional energy constitutes a regulatory inflection that unlocks green financing channels and accelerates private capital deployment into modular reactor platforms.
For Market Incumbents: Shield installed base access through long-term service agreement bundling that locks out competing fuel-cycle and maintenance providers. Pursue backward integration into specialized welding certification pipelines to counter workforce aging. Vertical control over reactor pressure vessel forging capacity in France and Finland secures delivery timelines against Eastern European localization demands. For New Entrants and Emerging Players: Anchor in Poland and Czech Republic first-of-a-kind deployments where state-backed guarantees de-risk technology transfer partnerships. District heating and industrial process steam applications represent the most penetrable SMR segment. Pursue AP1000 localization agreements as the primary go-to-market angle. For Investors and Strategic Acquirers: EU Green Deal Taxonomy eligibility reshapes the acquisition landscape by concentrating viable targets among vendors with demonstrable lifecycle emissions documentation. Five-to-ten year viability hinges on factory-fabrication capabilities rather than field-erection expertise. Monitor Finnish STUK licensing precedent as the signal indicating which vendor qualification protocols will propagate across subsequent European deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Transfer Localization | AP1000 agreements in Poland build indigenous fabrication capacity under Czech regulatory alignment. |
| Long-Term Service Agreement Bundling | EDF and Framatome contracts span reactor lifetimes, excluding competitor maintenance access. |
| Factory Fabrication Scale-Up | Rail-transportable SMR components compress site duration and enable serial production economics. |
| EU Taxonomy Compliance Certification | Green financing eligibility requires documented lifecycle emissions and waste management protocols. |
| Specialized Workforce Pipeline Investment | ASME Section IX welding certification programs counter aging-out of European nuclear fabricators. |
Research Methodology
Cross-validation between primary interviews with utility planning officers, EPC contractors, and nuclear regulatory affairs specialists and secondary validation through IEA nuclear development databases, ASN licensing records, and STUK design certification filings anchors the qualitative findings. Bottom-up project pipeline aggregation triangulates against top-down macroeconomic capacity demand models.
Sensitivity analysis across the projection horizon tests reactor deployment pace under varying EU Taxonomy implementation stringency and Finnish regulatory precedent adoption rates. Segmentation dimensions span product type, technology readiness, end-user financing structure, and regional regulatory cluster. CAGRs derive from installed capacity commitment trajectories and public R&D funding flows for Generation IV demonstrators.
Material uncertainties — licensing timeline extensions under France's ASN, workforce replenishment rates, and renewable energy substitution in national grid plans — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and supply chain concentration. Revision becomes warranted when STUK-qualified vendor counts cross thresholds that enable streamlined multi-country deployment protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Thorium Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Global Nuclear Fusion Market