
 North America Industrial Emission Control Systems Market | 2026-2036
North America Industrial Emission Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Emission Control Systems Market Insights
Buyer concentration across North American power utilities and petrochemical complexes is rebalancing as independent refineries merge into larger operating groups while chemical manufacturers fragment into specialized mid-scale facilities. Babcock & Wilcox leverages its scrubber technology portfolio to anchor utility-sector contracts. General Electric sustains turbine-integrated emission control R&D across multiple fuel types. BASF competes through catalyst formulations that differentiate its selective catalytic reduction offerings.
Industrial emission control systems encompass particulate capture, gas treatment, and thermal oxidation equipment engineered to reduce sulfur oxides, nitrogen oxides, mercury, and particulate matter from stationary combustion and process sources, typically operating at temperatures between 300°F and 1,200°F depending on the pollutant target. These installations serve primary commercial purposes of regulatory compliance, occupational safety, and community air quality protection. Selective catalytic reduction technology leads the technology segment due to its established deployment base across coal and gas-fired power generation, while flue gas desulfurization occupies the mature margin pool with predictable replacement cycles. Retrofit installations represent the fastest-growing installation category as aging facilities face accelerated EPA compliance deadlines without full plant replacement.
The EPA enforces National Ambient Air Quality Standards and Cross-State Air Pollution Rule requirements that directly mandate emission control upgrades across power generation and industrial sources. State-level regulators in Texas and California implement complementary rules that exceed federal minimums, creating differentiated product certification requirements. OSHA workplace exposure limits and the Department of Energy efficiency guidelines further constrain equipment design parameters. Stakeholders must monitor pending revisions to mercury standards and carbon capture integration mandates that will reshape capital allocation priorities across the installed base.
Market Dynamics
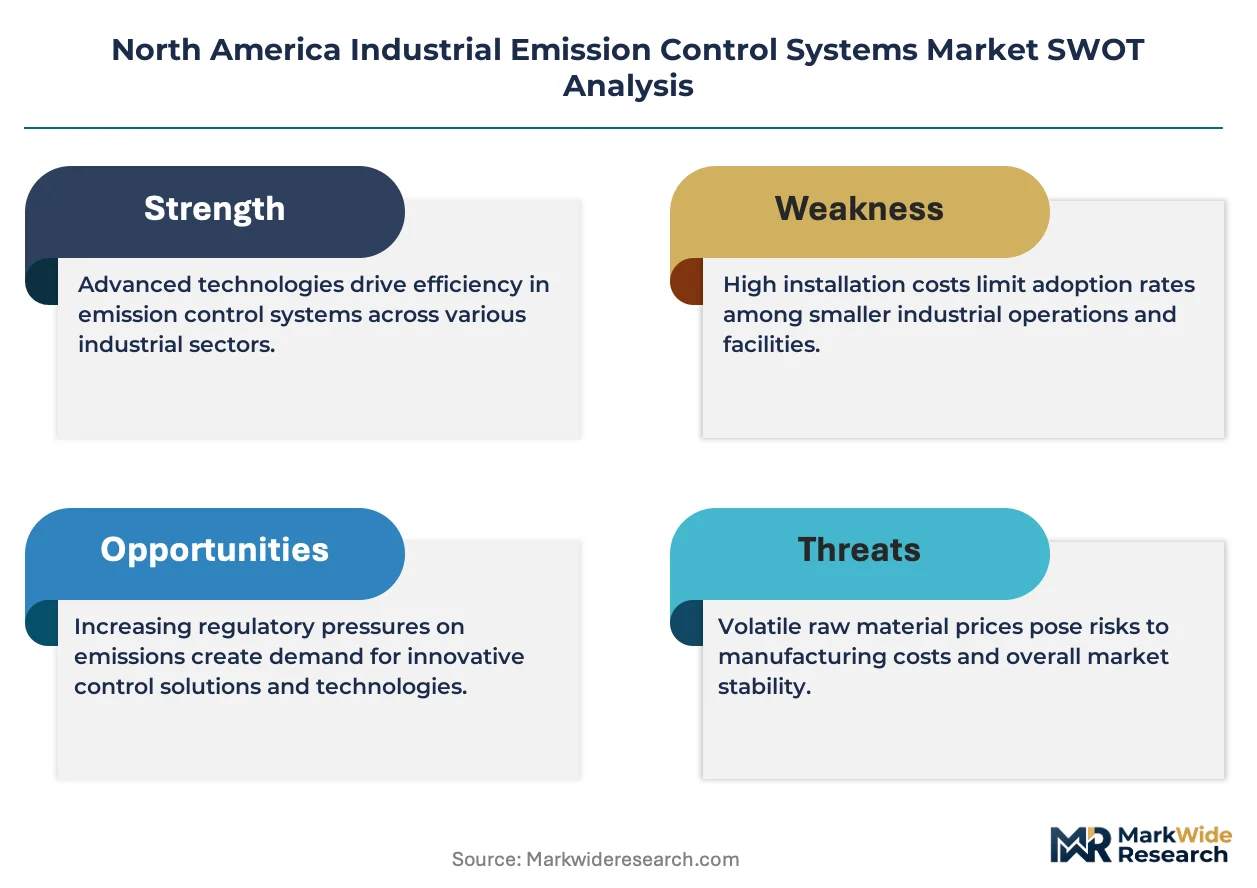
Retrofit installations are compressing equipment replacement cycles across coal and gas-fired power generation as EPA compliance deadlines accelerate without permitting full plant rebuilds. This structural pressure is reallocating capital from greenfield projects toward secondary emission control upgrades.
Growth Catalysts
- EPA Mercury and Air Toxics Standards:Enforcement timelines tighten compliance windows for coal-fired units, forcing selective catalytic reduction and scrubber retrofits across the Midwest and Southeast.
- Texas refinery corridor concentration:Petrochemical complex expansions in the Gulf Coast generate concentrated demand for flue gas desulfurization systems and thermal oxidizers.
- Selective catalytic reduction technology:Established deployment base across combined-cycle gas turbines creates predictable replacement revenue streams as catalyst degradation cycles mature.
Market Restraints
- Titanium and vanadium supply concentration:Catalyst manufacturing depends on concentrated rare earth processing capacity, creating input cost volatility for selective catalytic reduction systems.
- Cross-State Air Pollution Rule friction:Interstate trading complexity and state implementation plan disputes delay project approvals in the Ohio River Valley.
- Carbon capture substitution threat:Emerging post-combustion capture pilots at power utilities threaten to displace standalone nitrogen oxide control investments if integrated designs prove scalable.
Strategic Opportunities
- California low-carbon fuel standard integration:Refinery operators face overlapping state and federal mandates, creating bundled service contracts for multi-pollutant control systems.
- Digital twin convergence with predictive maintenance:Sensor-enabled catalyst monitoring platforms enable performance-based service contracts extending vendor revenue beyond equipment sales.
- Ohio-Pennsylvania shale gas processing:Expanding cryogenic gas plants and fractionation facilities require new thermal oxidizer installations for volatile organic compound control.
Industry Challenges
- Scrubber-weld inspection certification backlog:American Society of Mechanical Engineers pressure vessel recertification queues stretch engineering contractor capacity, delaying outage windows.
- Legacy distributed control system integration:Retrofit projects must interface with 1990s-era plant automation architectures, multiplying commissioning complexity and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Emission Control Systems Market |
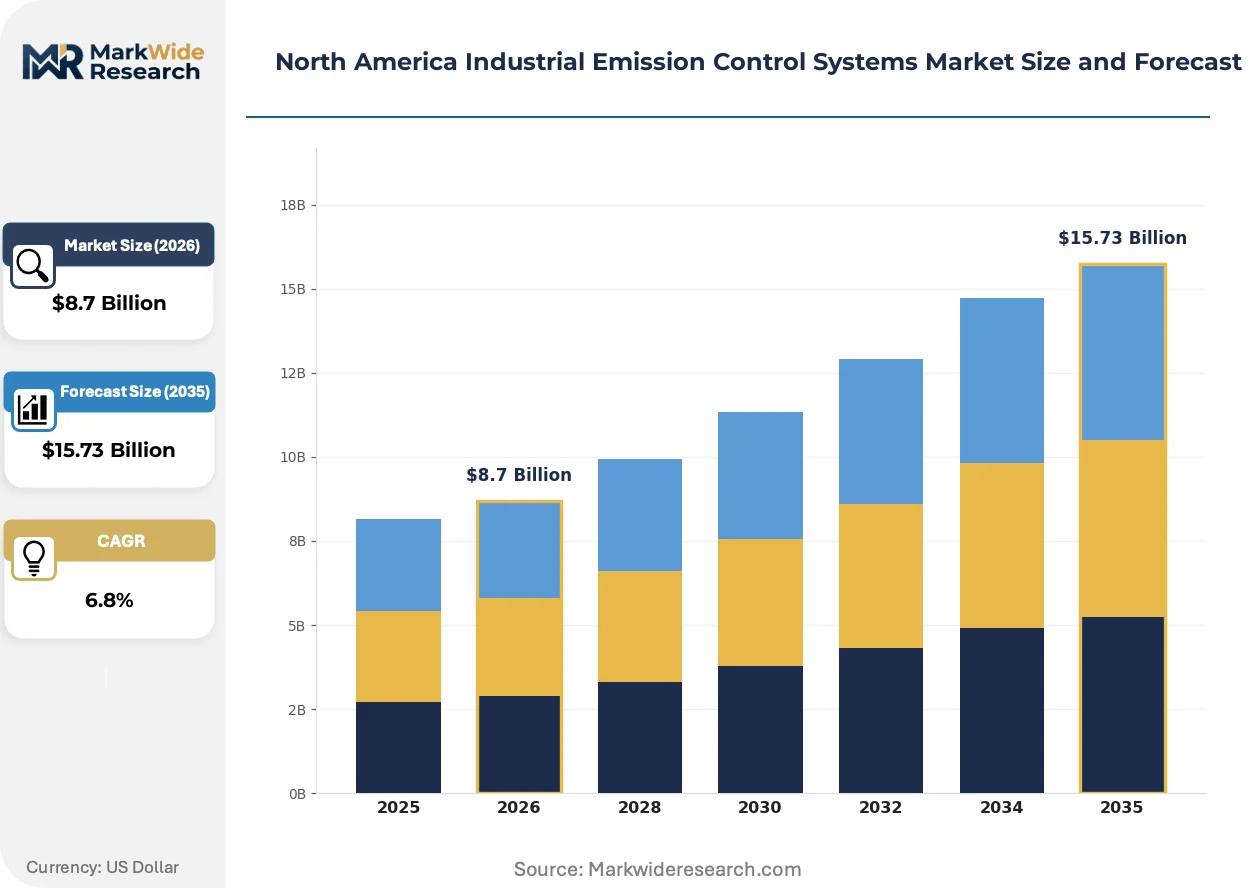
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SCR, ESP, Bag Filters, Flue Gas Desulfurization End User: Power Generation, Chemical Manufacturing, Oil & Gas, Metal Processing Application: Air Pollution Control, Waste Treatment, Industrial Processes, Abatement Systems Installation: Onshore, Retrofit, New Build, Expansion Projects |
| Companies Covered | Babcock & Wilcox, General Electric, BASF, Durr Group, Mitsubishi Heavy Industries, FLSmidth, Fuel Tech, GEA Group, Hamon, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Emission Control Systems Market Trends and Innovations
Equipment intelligence and modular system architectures are compressing project delivery timelines while expanding remote service capabilities. These shifts are redefining vendor-customer relationships across the installed base.
Advanced catalyst formulations incorporating zeolite structures are converging with real-time exhaust gas monitoring to enable dynamic ammonia injection optimization. Combined-cycle operators in the ERCOT and PJM interconnection regions are adopting these integrated packages to minimize operating costs while maintaining compliance margins. This convergence is compressing the performance gap between original equipment manufacturer and aftermarket catalyst suppliers.
The EPA's proposed Good Neighbor Plan updates are tightening ozone transport requirements for twenty-three upwind states, forcing nitrogen oxide reduction commitments from industrial boilers and cement kilns. Facilities in the Chicago and Dallas-Fort Worth non-attainment zones face accelerated compliance schedules. Refinery operators are responding by pre-purchasing selective catalytic reduction capacity ahead of formal rule finalization.
Equipment-as-a-service contracting is displacing traditional capital purchase models among independent power producers facing balance sheet constraints. Third-party ownership structures transfer operational risk to specialized emission control vendors while preserving utility offtake agreements. This shift is most visible in the merchant gas turbine fleet across Texas and the Mid-Atlantic, where tolling arrangements now bundle catalyst replacement into fixed per-megawatt-hour fees.
North America Industrial Emission Control Systems Market Segmentation
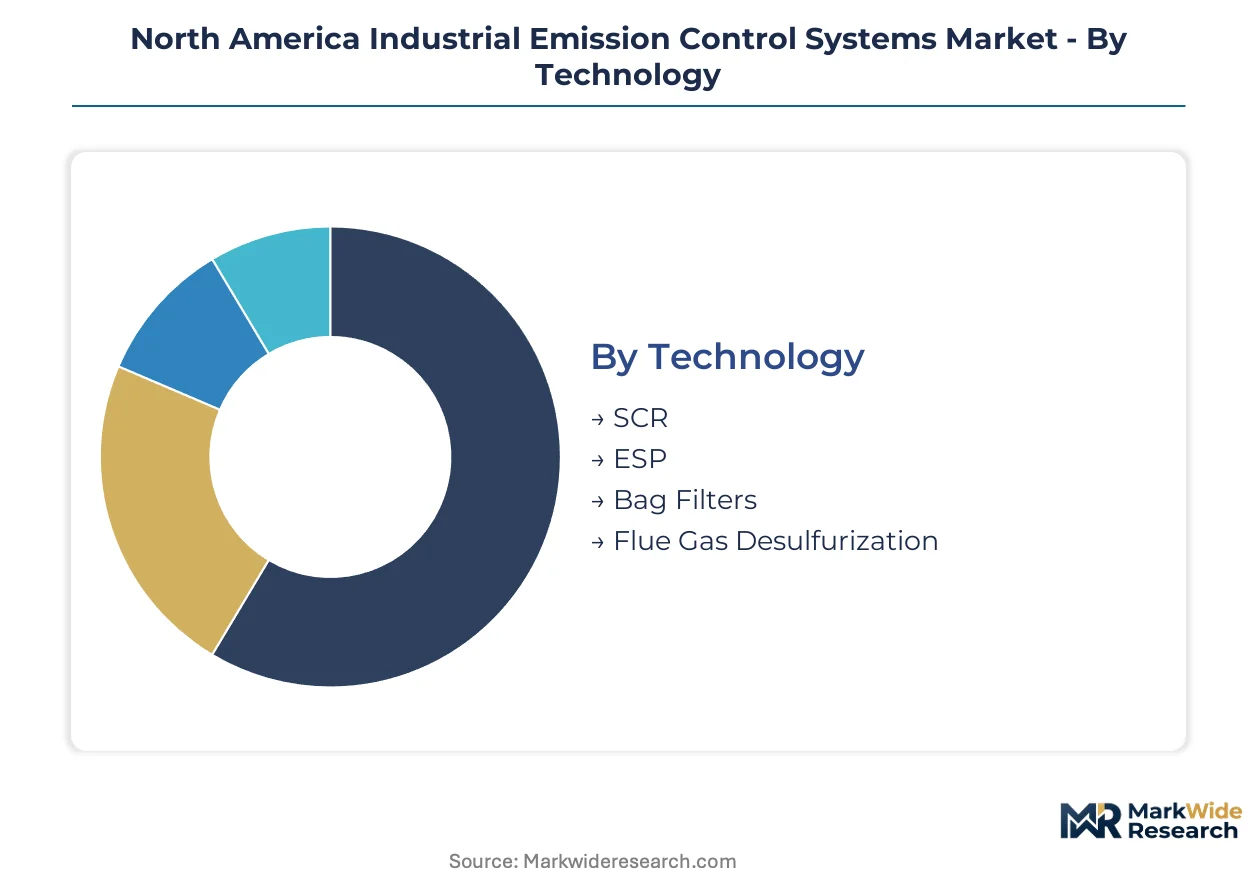
Emission control procurement in North America splits sharply between standardized utility-scale systems and customized petrochemical configurations. Technology selection and installation mode together determine capital intensity, vendor relationships, and compliance risk exposure across the installed base.
Technology:
Standardization dominates particulate capture while catalytic systems demand extensive customization for site-specific exhaust chemistries and temperature profiles.
- SCR:Zeolite and vanadium-based catalyst formulations operate between 300°F and 800°F to reduce nitrogen oxides through ammonia injection. Texas and Ohio coal-gas corridors drive retrofit demand as EPA Mercury and Air Toxics Standards compress compliance timelines for aging units.
- ESP:Electrostatic precipitators apply high-voltage fields to ionize and collect particulate matter across 0.01 to 100 micron ranges. Baseload coal plants in the PJM interconnection anchor replacement cycles as precipitator rappers and power supplies reach end-of-life.
- Bag Filters:Fabric filtration systems capture sub-micron particulates through mechanically cleaned or pulse-jet bag configurations.
- Flue Gas Desulfurization:Wet scrubber and dry sorbent injection systems remove sulfur oxides through limestone or lime slurry contact.
Leading the category by volume: ESP. Growing fastest: SCR.
End User:
Capital commitment scale separates centralized utility buyers from fragmented industrial operators with diverging procurement sophistication.
- Power Generation:Coal, combined-cycle gas, and biomass-fired plants deploy multi-pollutant control trains to satisfy Cross-State Air Pollution Rule obligations. Midwest and Southeast utilities concentrate scrubber and SCR retrofit spending ahead of accelerated EPA enforcement schedules.
- Chemical Manufacturing:Petrochemical complexes and specialty chemical producers require thermal oxidizers and carbon adsorption systems for volatile organic compound control. Gulf Coast ethylene crackers and ammonia plants in Louisiana and Texas generate concentrated demand for integrated abatement packages.
- Oil & Gas:Refinery fluid catalytic crackers and sulfur recovery units drive selective catalytic reduction and tail gas treating investments.
- Metal Processing:Electric arc furnaces and sintering operations generate particulate and heavy metal emissions requiring specialized capture.
Highest capital deployment: Power Generation. Most fragmented procurement: Chemical Manufacturing.
Application:
Regulatory mandate type determines system complexity — continuous compliance applications command higher monitoring integration than intermittent waste treatment.
- Air Pollution Control:Continuous emission monitoring systems paired with catalytic or filtration hardware satisfy National Ambient Air Quality Standards for nitrogen oxides, sulfur oxides, and particulate matter. Coal and gas-fired generators across the Ohio River Valley and ERCOT regions anchor equipment replacement cycles.
- Waste Treatment:Thermal oxidation and scrubber systems neutralize hazardous process streams and off-gases from chemical manufacturing. California refineries face overlapping state low-carbon fuel standards and federal mandates, driving bundled multi-pollutant system procurement.
- Industrial Processes:Cement kilns, glass furnaces, and steel mills deploy high-temperature filtration and gas conditioning.
- Abatement Systems:Emergency relief and vent gas treatment protects against episodic release events.
Deepest regulatory integration: Air Pollution Control. Steepest expansion trajectory: Waste Treatment.
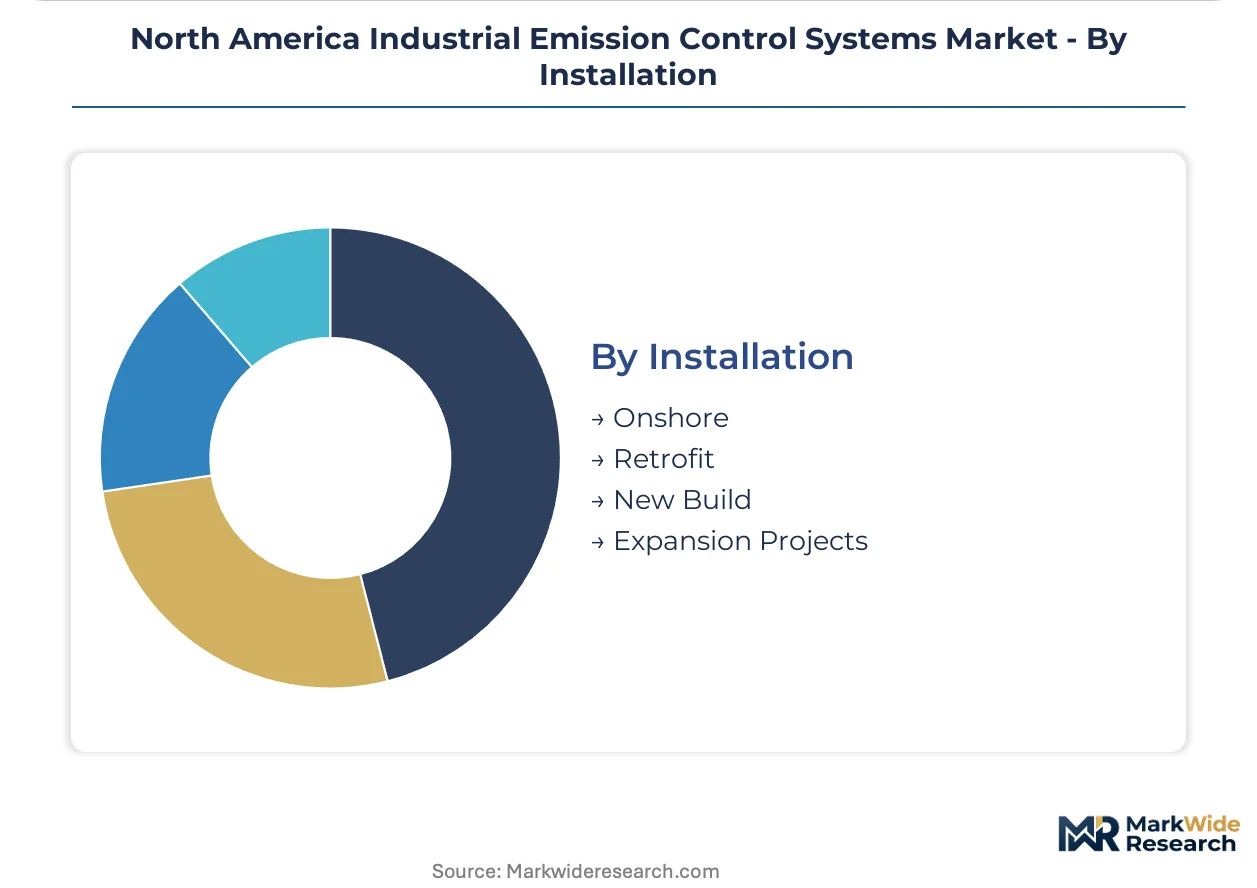
Installation:
Greenfield construction permits optimized system architecture while retrofits demand forced compatibility with legacy infrastructure and constrained outage windows.
- Retrofit:Secondary emission control additions to existing combustion and process units compress project timelines without full plant replacement. Independent power producers and merchant generators across Texas and the Mid-Atlantic favor equipment-as-a-service contracts to transfer operational risk while preserving offtake agreements.
- New Build:Integrated emission control design in greenfield power and chemical plants enables optimized catalyst bed sizing and duct routing. Ohio-Pennsylvania shale gas processing expansions require new thermal oxidizer installations for cryogenic plant volatile organic compound control.
- Onshore:Fixed industrial facility installations dominate capital allocation.
- Expansion Projects:Capacity additions to existing sites blend brownfield constraints with some design flexibility.
Largest revenue pool: Retrofit. Gaining share fastest: New Build.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian shale formations anchor feedstock supply for emission-intensive processing across the eastern United States. Gulf Coast petrochemical corridors concentrate refinery and chemical manufacturing demand. Midwest power generation clusters drive retrofit equipment procurement.
United States
Texas and Ohio refinery corridors generate concentrated demand for flue gas desulfurization and thermal oxidizer installations. EPA Mercury and Air Toxics Standards enforcement tightens compliance timelines for coal-fired units across the Midwest and Southeast. The Ohio River Valley hosts accelerated scrubber and selective catalytic reduction retrofit spending as utilities face Cross-State Air Pollution Rule obligations.
Canada
Alberta oil sands processing and Ontario manufacturing anchor industrial emission control demand. Environment and Climate Change Canada enforces equivalency agreements with federal standards while provinces maintain facility-specific operating permits. The Sarnia-Lambton petrochemical corridor in Ontario requires integrated abatement systems for refinery and chemical complex operations.
Mexico
Pemex refinery modernization and northern border manufacturing expansion drive emission control procurement. SEMARNAT implements federal atmospheric emission standards with state-level enforcement variations across industrial zones. Tamaulipas and Nuevo León petrochemical facilities face escalating regulatory scrutiny as cross-border air quality commitments tighten.
North America Industrial Emission Control Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-enabled service models and modular system architectures. The vendor base stratifies across three tiers: integrated engineering conglomerates with full technology portfolios, specialized catalyst and component suppliers, and regional installation contractors. Two dominant competitive moves reshape positioning: equipment-as-a-service contracting transfers operational risk to vendors, and predictive maintenance platforms extend revenue beyond initial equipment sales.
Within the integrated engineering tier, Babcock & Wilcox and General Electric exemplify full-technology-portfolio positioning. BASF occupies a specialized supplier archetype focused on catalyst formulations. These three anchors represent divergent strategic vectors: scrubber-integrated utility contracting, turbine-embedded emission control R&D, and materials-science-driven selective catalytic reduction differentiation.
| Leading Market Players |
|---|
| Babcock & Wilcox |
| General Electric |
| BASF |
| Durr Group |
| Mitsubishi Heavy Industries |
| FLSmidth |
| Fuel Tech |
| GEA Group |
| Hamon |
| Others |
Pricing and Supply Chain Analysis
Captive catalyst manufacturing by integrated engineering conglomerates anchors both supply security and pricing power across selective catalytic reduction system procurement. This backward integration into vanadium and zeolite processing insulates tier-one vendors from raw material volatility while compressing margins for aftermarket suppliers competing on unbundled catalyst replacement.
Pricing Analysis
Warranty and catalyst replacement bundling separates original equipment manufacturer contracts from unbundled aftermarket supply. Project-based capital sales dominate utility-scale procurement, while equipment-as-a-service contracts transfer operational risk to vendors for independent power producers. Price differentiation rests on ASME certification tier and outage window guarantees. Cost compression in standard catalyst formulations is intensifying because Chinese rare earth processing expansion feeds global supply. Merchant generators exhibit highest price sensitivity; regulated utilities with rate-base recovery show lowest.
Supply Chain Analysis
ASME pressure vessel certification gates engineering contractor participation and stretches lead capacity across outage seasons. Catalyst manufacturing draws from South African vanadium, Chinese rare earth separation, and German zeolite synthesis. Supply chain risk centers on single-source dependency for aerospace-grade titanium used in high-temperature SCR housings. Distribution runs through regional EPC contractors with established utility relationships rather than direct vendor-to-plant sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service capacity constraints prop pricing power as engineering contractor availability tightens across compressed EPA compliance windows. This supply bottleneck favors incumbents with captive installation crews.
For Market Incumbents: Extend predictive maintenance platform coverage to capture recurring revenue beyond catalyst replacement cycles. Secure ASME recertification capacity through exclusive contractor arrangements before outage season peaks. Carbon capture integration pilots threaten standalone NOx control investments; deepen R&D in combined capture-catalysis systems to preserve technology relevance. For New Entrants and Emerging Players: Begin with digital twin deployment for independent refinery operators in the Texas Gulf Coast corridor, where fragmented procurement sophistication creates white-space opportunity. Target equipment-as-a-service contracts for merchant gas turbine fleets facing balance sheet constraints. Pursue partnerships with regional EPC contractors lacking proprietary catalyst monitoring capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated engineering conglomerates seeking catalyst formulation capabilities. Long-term viability favors specialized suppliers with captive rare earth processing relationships or predictive maintenance platforms with demonstrated utility adoption. Watch for EPA finalization of Good Neighbor Plan ozone transport requirements as inflection signal for accelerated NOx control procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Precursors | Captive vanadium and zeolite supply secures margin control against Chinese rare earth volatility. |
| Equipment-as-a-Service Contracting | Risk transfer to vendors unlocks independent power producer procurement frozen by balance sheet constraints. |
| Predictive Maintenance Platform Deployment | Sensor-enabled ammonia injection optimization extends vendor revenue beyond equipment replacement cycles. |
| ASME Recertification Capacity Expansion | Exclusive contractor relationships compress competitor access to constrained outage windows. |
| Carbon Capture Integration R&D | Combined post-combustion capture and SCR design preserves relevance against standalone displacement threat. |
Research Methodology
Independent corroboration across EPA enforcement databases, EIA power plant emissions filings, and ASME pressure vessel registration records underwrites the qualitative findings. Primary interviews with utility environmental compliance officers, refinery maintenance directors, catalyst procurement managers, and EPC project engineers combined with secondary validation from FERC interconnection queues, state implementation plan submissions, and SEC 10-K equipment supplier disclosures. Bottom-up installation tracking and top-down regulatory mandate sizing triangulate market scope.
Comparable historical retrofit cycles across Mercury and Air Toxics Standards implementation anchor projection methodology across the analysis window. Segmentation models incorporate technology type, installation mode, end-user industry, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and compliance deadline acceleration patterns. Forecast inputs include EPA rulemaking timelines and catalyst degradation curves by operating temperature profile.
Underlying measurement precision varies by segment; power generation retrofit tracking carries tighter precision than fragmented chemical manufacturing procurement. Forecasts reflect documented assumptions on EPA enforcement intensity and rare earth supply continuity. A model refresh is warranted upon material change in Cross-State Air Pollution Rule state implementation plan approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market