
 Sailboat Ballast Water Treatment Technology Market | 2026-2036
Sailboat Ballast Water Treatment Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Sailboat Ballast Water Treatment Technology Market Insights
Marine equipment distribution through specialty chandleries and direct OEM supply is tilting toward integrated system bundling. Alfa Laval leverages its filtration heritage to anchor premium sailboat retrofit programs. Wärtsilä competes through scaled electrochlorination platforms adapted from commercial shipping. Optimarin specializes in compact UV architectures purpose-built for sub-500-tonne pleasure craft.
Sailboat ballast water treatment technology encompasses physical filtration, ultraviolet irradiation, and chemical disinfection systems engineered to eliminate invasive aquatic organisms from bilge and ballast tanks while maintaining vessel stability profiles. These units typically operate at flow rates under 50 cubic meters per hour with footprint constraints below 0.5 square meters to fit cramped sailboat engine rooms. Ultraviolet treatment leads installed base among recreational applications due to minimal consumable requirements and neutral pH discharge chemistry. Electrochlorination occupies the fastest-expanding segment as cell-stack miniaturization reduces power draw to levels compatible with sailboat battery banks. Chemical injection retains niche positioning in research expedition configurations where extreme latitude sailing demands redundant biological kill mechanisms.
The International Maritime Organization Ballast Water Management Convention shapes product certification pathways through its D-2 biological performance standard, while the US Coast Guard enforces parallel type-approval requirements that fragment market access for European suppliers. ISO 11716 testing protocols govern equipment validation for smaller vessels, creating compliance cost barriers for modular unit entrants. Stakeholders must monitor pending EPA small vessel discharge rulemakings and flag-state implementation variances that will determine which technology architectures achieve regulatory portability across cruising grounds.
Market Dynamics
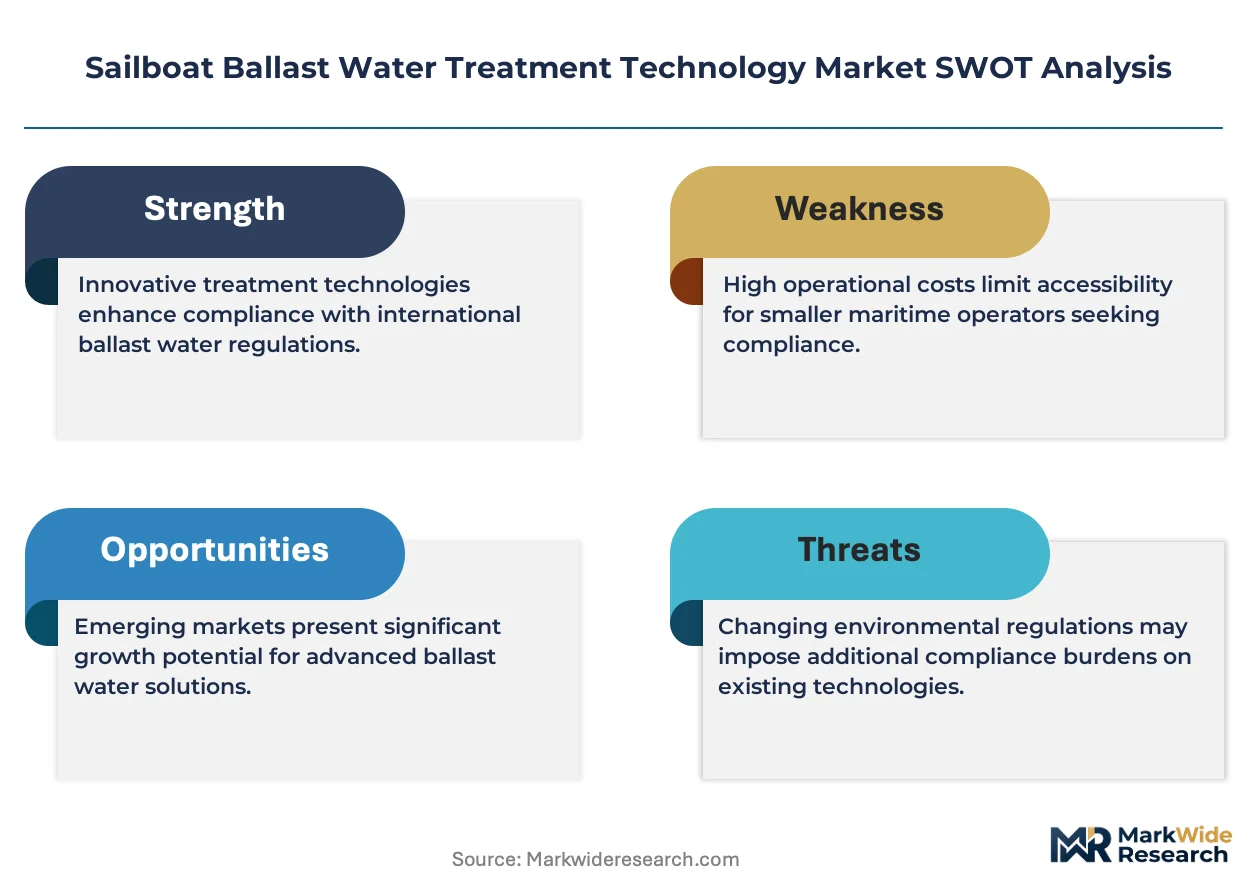
The IMO Ballast Water Management Convention's phased implementation timeline for sub-500-tonne vessels is compressing supplier lead times and forcing rapid certification cycles across compact system architectures.
Growth Catalysts
- Mediterranean enforcement waves:Italian and Spanish port authorities are conducting unannounced discharge inspections at charter hubs, creating immediate retrofit demand from leisure fleet operators.
- UV-C LED miniaturization:Solid-state ultraviolet sources eliminate mercury lamp replacement cycles, reducing total ownership burden for seasonal sailors.
- Scandinavian racing circuit mandates:Offshore regatta organizers now require documented treatment compliance for entry, converting competitive sailors into early adopters.
Market Restraints
- Titanium electrode supply concentration:Electrochlorination cell-stack production depends on Russian and Chinese titanium sponge, exposing manufacturers to raw material access risk.
- USCG type-approval fragmentation:Parallel American certification requirements duplicate testing costs for European UV system suppliers seeking trans-Atlantic market access.
- Power budget physics:Sailboat battery banks below 400 ampere-hours cannot sustain continuous electrochlorination without engine-running, limiting technology choice for bluewater cruisers.
Strategic Opportunities
- Greek island charter density:The Aegean's concentrated bareboat fleet presents bundling potential for treatment system OEM partnerships with local marina operators.
- EPA small vessel discharge rulemaking:Pending American regulations for recreational boats under 79 feet may extend ballast rules to bilge water, expanding addressable equipment base.
- Filtration-UV convergence:Integrated single-unit designs combining screen filtration with ultraviolet stages reduce installation footprint and plumbing complexity.
Industry Challenges
- Marine electrical technician scarcity:Installation of electrochlorination systems requires certified DC power integration skills that charter fleet maintenance crews often lack.
- ISO 11716 testing backlog:Validation queue times at notified bodies now exceed 14 months, delaying product launches and freezing development capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sailboat Ballast Water Treatment Technology Market |
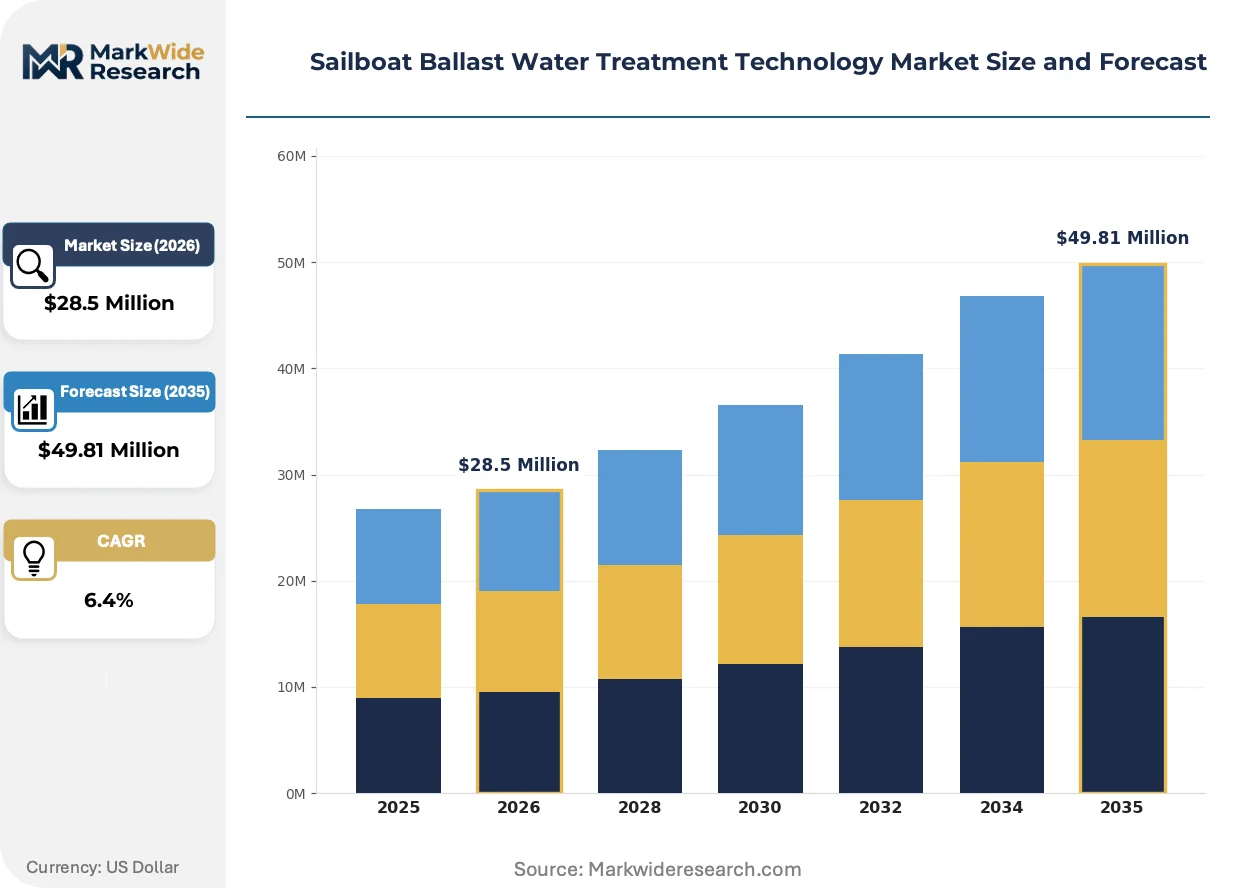
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $49.81 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Filtration, Ultraviolet, Electrochlorination, Chemical Injection, Ozone Treatment Application: Coastal Navigation, Offshore Sailing, Racing, Recreational Cruising, Research Expeditions End User: Private Owners, Sailing Clubs, Charter Companies, Maritime Researchers, Yacht Manufacturers Installation Type: New Build, Retrofit, Modular Units, Fixed Systems, Portable Devices |
| Companies Covered | Alfa Laval, Wärtsilä, Optimarin, Evoqua Water Technologies, Xylem, Veolia Water Technologies, Ecochlor, Headway Technology Group, ERMA FIRST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sailboat Ballast Water Treatment Technology Market Trends and Innovations
System miniaturization and power efficiency are redefining what treatment architectures fit sailboat constraints, while regulatory harmonization efforts attempt to reduce certification duplication across flag states.
Ultraviolet LED arrays are collapsing the physical envelope for effective biological inactivation. These solid-state emitters achieve D-2 standard compliance at flow rates under 25 cubic meters per hour while drawing half the amperage of legacy mercury vapor systems. Scandinavian racing yacht builders are specifying UV-C LED modules as standard equipment, compressing the viable market for electrochlorination in sub-30-foot hulls.
REACH chemical authorization processes are restricting certain biocide formulations used in legacy chemical injection systems. The European Chemicals Agency's substance evaluation program has placed specific active ingredients under scrutiny, forcing suppliers to reformulate or abandon chemistries that previously satisfied IMO guidelines. Expedition yacht operators requiring redundant kill mechanisms are now evaluating ozone-based alternatives to maintain dual-technology compliance.
Direct-to-owner digital sales channels are displacing traditional chandlery distribution for retrofit installations. Online configurators allowing sailors to match treatment capacity to tank volume and pump flow rates are capturing educated buyers who previously relied on yard recommendations. This pattern concentrates in the Pacific Northwest and New England cruising grounds where technical literacy runs high and DIY installation is culturally accepted.
Sailboat Ballast Water Treatment Technology Market Segmentation
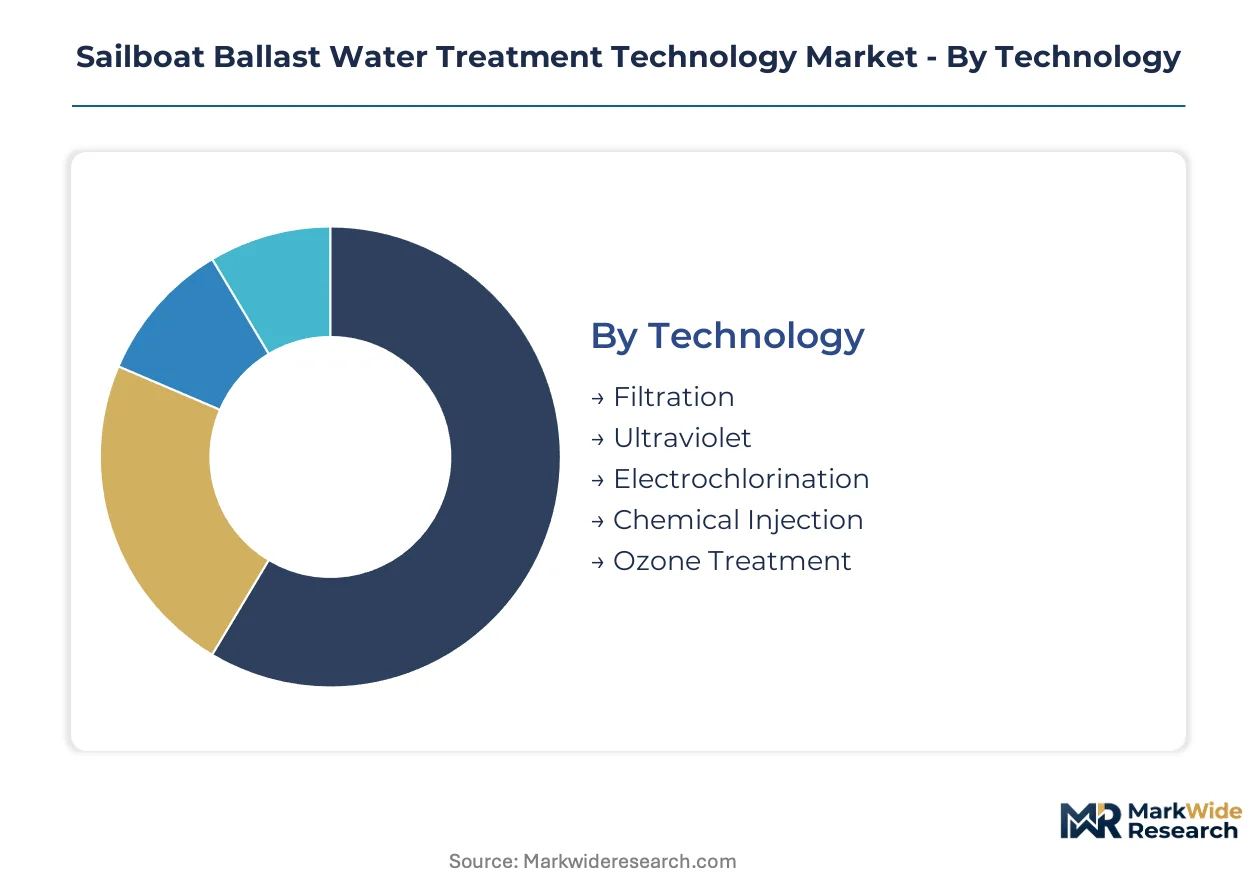
Sailboat ballast water treatment technology fragments across multiple dimensions that determine unit specifications, certification pathways, and commercial viability. Technology choice constrains power budgets and physical footprints, while application context dictates regulatory exposure and operational intensity.
Technology:
Filtration, ultraviolet irradiation, and electrochlorination architectures serve distinct use-case spectra from Mediterranean weekend cruising to Antarctic research missions.
- Filtration:Physical screening systems remove particulates and larger organisms through mesh or membrane barriers, typically as a pretreatment stage. Demand concentrates in charter fleets operating from Italian and Spanish ports where IMO D-2 compliance mandates multi-stage configurations.
- Ultraviolet:UV-C irradiation inactivates microorganisms through DNA disruption without chemical residuals. Scandinavian racing circuits favor mercury-vapor and emerging LED arrays for neutral pH discharge chemistry that protects sensitive hull coatings.
- Electrochlorination:In-situ chlorine generation through electrolytic cell stacks achieves biological kill with minimal storage requirements. Bluewater cruisers with substantial battery banks and engine-running capacity drive retrofit demand.
- Chemical Injection:Biocide dosing systems deliver precise active ingredient concentrations for extreme latitude sailing. Research expedition operators requiring redundant kill mechanisms specify chemical backup for UV-primary configurations.
- Ozone Treatment:Ozone generation systems oxidize organic contaminants through corona discharge or UV irradiation. REACH authorization pressures on legacy biocides are redirecting expedition yacht specifications toward ozone-based alternatives.
Established volume favors ultraviolet systems; emerging adoption favors electrochlorination as cell-stack miniaturization progresses.
Application:
Operational context determines flow rate requirements, certification urgency, and redundancy specifications across the recreational and professional sailing spectrum.
- Coastal Navigation:Short-range cruising within national waters faces variable flag-state enforcement intensity. Greek and Croatian charter hubs generate concentrated equipment demand from bareboat operators seeking port-entry documentation.
- Offshore Sailing:Extended ocean passages require self-sufficient treatment capacity independent of shore power. Atlantic circuit cruisers prioritize UV-C LED systems for minimal amperage draw during multi-day passages.
- Racing:Competitive sailing mandates documented compliance for regatta entry without performance-compromising weight or drag. Scandinavian offshore race organizers now require treatment certification, converting competitive sailors into technology adopters.
- Recreational Cruising:Leisure sailing across mixed jurisdictions demands regulatory portability. Mediterranean seasonal sailors favor systems with minimal consumable replacement cycles.
- Research Expeditions:Scientific missions to polar or tropical ecosystems face stringent biosecurity protocols. Dual-technology configurations combining UV and chemical or ozone stages satisfy institutional review requirements.
Recreational cruising commands current installed base; research expeditions show steepest expansion trajectory as institutional funding for marine science increases.
End User:
Procurement authority and technical sophistication vary sharply between individual owners and institutional operators.
- Private Owners:Individual sailors purchasing through chandleries or direct digital channels. Pacific Northwest and New England cruising grounds exhibit high technical literacy and DIY installation acceptance.
- Sailing Clubs:Fleet operators managing multiple vessels with centralized maintenance capabilities. Scandinavian clubs drive standardization through collective procurement.
- Charter Companies:Commercial leisure fleet operators facing regulatory inspection exposure. Italian and Spanish port authority enforcement waves compress retrofit timelines for bareboat operators.
- Maritime Researchers:Institutional operators with dedicated compliance staff and redundant system requirements. Polar research programs specify dual-technology configurations.
- Yacht Manufacturers:OEM integrators specifying factory-installed systems for new builds. Scandinavian racing yacht builders are specifying UV-C LED modules as standard equipment.
Charter companies dominate current procurement volume; yacht manufacturers represent the fastest-climbing segment as OEM integration becomes competitive standard.
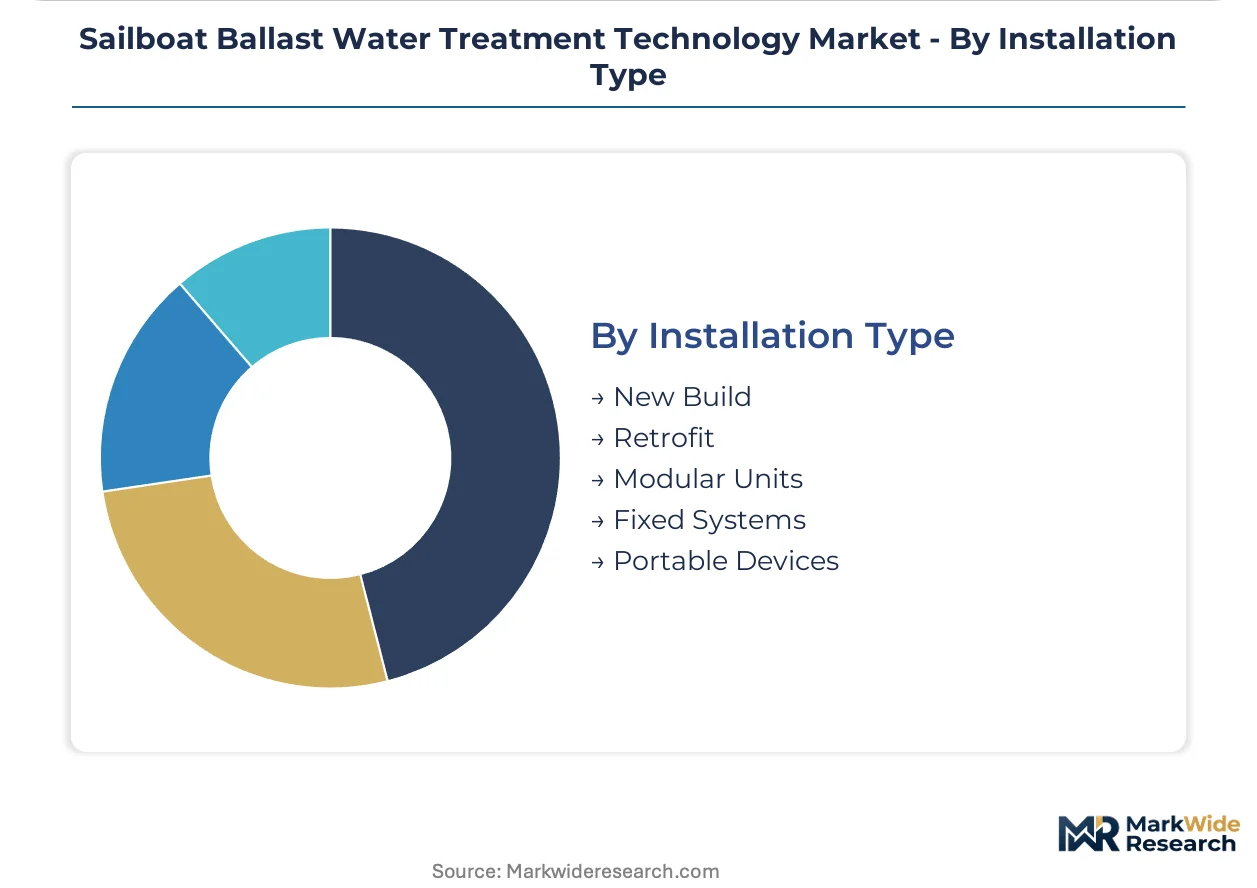
Installation Type:
Physical integration approach determines capital allocation, yard time requirements, and upgrade flexibility.
- New Build:Factory-integrated systems specified during hull construction. OEM partnerships with treatment system suppliers concentrate in Scandinavian and Mediterranean yacht building centers.
- Retrofit:Post-construction installation into existing engine rooms and tank configurations. Italian and Spanish charter hubs generate immediate demand from enforcement-driven compliance deadlines.
- Modular Units:Pre-assembled skid-mounted systems minimizing yard installation time. Charter fleet operators favor modularity for rapid deployment across vessel classes.
- Fixed Systems:Permanently installed equipment with dedicated plumbing and electrical integration. Private owners with single-vessel commitment prefer fixed installations for reliability.
- Portable Devices:Temporary treatment equipment for seasonal or transitional compliance. Research expeditions evaluating treatment technologies before permanent specification drive limited demand.
Retrofit installations absorb current capacity; new build integration gains share as OEM relationships deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian charter operators command pricing premiums unavailable to Croatian bareboat fleets due to stricter enforcement of IMO discharge standards at Mediterranean ports. Scandinavian racing circuits generate equipment demand through mandatory compliance documentation for regatta entry.
Italy
Italian port authorities conduct unannounced ballast discharge inspections at charter hubs from Sardinia to the Amalfi Coast. The country's coast guard enforces IMO D-2 biological standards with fines that compress retrofit timelines for leisure fleet operators. Marina di Ragusa and Portorosa concentrate bareboat operators installing UV-C LED systems before peak season.
Spain
Spanish charter companies face simultaneous pressure from Balearic Islands environmental regulators and mainland port authorities. The country's merchant marine directorate coordinates with Italian enforcement patterns to prevent regulatory arbitrage. Barcelona and Palma de Mallorca anchor the Mediterranean's densest concentration of retrofit installation yards.
Greece
Greek island bareboat density creates bundling opportunities for treatment system suppliers partnering with marina operators. The country's shipping ministry defers to flag-state conventions while port police selectively inspect charter vessels at Piraeus and Corfu. Aegean charter bases from Paros to Rhodes drive seasonal procurement spikes.
Sweden
Swedish offshore racing organizers require documented treatment compliance for entry into Gotland Runt and other signature events. The country's transport agency enforces parallel national standards that exceed baseline IMO requirements. Stockholm archipelago sailing clubs standardize fleet specifications through collective procurement agreements.
Norway
Norwegian polar research programs specify redundant dual-technology configurations for Antarctic expedition yachts. The country's environmental directorate applies strict biosecurity protocols to vessels operating in Svalbard waters. Tromsø and Bergen concentrate maritime research institutions driving institutional procurement.
Sailboat Ballast Water Treatment Technology Market Competitive Landscape
Filtration heritage conglomerates and electrochlorination specialists split the market between premium retrofit programs and scaled commercial adaptations. Supplier concentration remains moderate with three to five dominant players controlling certification pathways. Equipment fabricators cluster into maritime engineering conglomerates, UV technology pure-plays, and chemical treatment specialists. Dominant competitive moves include OEM partnership deepening for new build integration and certification queue positioning to compress time-to-market.
Within the maritime engineering tier, Alfa Laval and Wärtsilä occupy positions anchored by commercial shipping heritage and scaled manufacturing infrastructure. Optimarin exemplifies the UV-specialist archetype with purpose-built architectures for sub-500-tonne pleasure craft. These three represent distinct strategic postures: conglomerate diversification, commercial-downmarket adaptation, and recreational-native specialization.
| Leading Market Players |
|---|
| Alfa Laval |
| Wärtsilä |
| Optimarin |
| Evoqua Water Technologies |
| Xylem |
| Veolia Water Technologies |
| Ecochlor |
| Headway Technology Group |
| ERMA FIRST |
| Others |
Pricing and Supply Chain Analysis
Titanium sponge concentration in Russian and Chinese smelters anchors electrochlorination cell-stack production, compressing margin pools for UV system suppliers who source solid-state emitters from diversified East Asian foundries. Equipment fabricators pass raw material volatility through to charter fleet operators via configured-to-order premiums, while Mediterranean retrofit yards absorb pricing pressure through bundled installation services.
Pricing Analysis
Configured-to-order pricing for expedition-grade dual-technology systems commands spreads exceeding standard UV-C LED configurations by certification tier and redundancy specification. Pricing stratifies across IMO D-2 premium, USCG type-approved standard, and economy grades lacking trans-Atlantic portability. Cost compression in electrochlorination segments is intensifying because titanium electrode supply constraints force cell-stack manufacturers into long-term offtake commitments. Charter companies bareboating from Italian ports exhibit acute price sensitivity, while polar research institutions demonstrate minimal elasticity due to institutional compliance mandates.
Supply Chain Analysis
Contract manufacturing for UV-C LED arrays concentrates in Taiwanese and South Korean foundries with dedicated semiconductor packaging lines, while electrochlorination cell-stack assembly clusters in German and Italian maritime engineering centers. Titanium sponge draws from Russian VSMPO-Avisma and Chinese Pangang facilities, with quartz sleeve components sourced from German specialty glassmakers. Single-source vulnerability runs through titanium supply given geopolitical export restrictions. Distribution runs through Mediterranean chandlery networks and direct OEM supply to Scandinavian yacht builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sailboat ballast water treatment technology is approaching a platform-economics inflection as certification interoperability between IMO D-2 and USCG standards creates ecosystem lock-in for integrated system suppliers. Interoperability shifts favor bundled filtration-UV architectures that satisfy multiple regulatory regimes through single-unit specification.
For Market Incumbents: Build certification moats through accelerated ISO 11716 queue positioning at notified bodies to freeze development capital for modular competitors. Deepen backward integration into UV-C LED emitter supply through captive partnerships with Taiwanese foundries. Electrification of charter fleets and titanium supply disruption represent primary threats requiring dual-sourcing strategies. For New Entrants and Emerging Players: Establish a beachhead in Greek island charter density where marina operator partnerships enable rapid fleet-wide deployment. Target modular skid-mounted configurations for bareboat operators facing compressed retrofit timelines from unannounced Italian port inspections. Direct-to-owner digital configurators offer the most penetrable go-to-market angle in Pacific Northwest cruising grounds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrochlorination specialists holding stranded titanium inventory and delayed certification pipelines. Long-term viability hinges on technology portfolios spanning both UV and electrochemical architectures with regulatory portability across Mediterranean and North American cruising grounds. Watch for EPA small vessel discharge rulemaking as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Queue Positioning | ISO 11716 validation backlog exceeding fourteen months freezes competitor development capital at notified bodies. |
| UV-C LED Foundry Partnership | Taiwanese semiconductor packaging capacity anchors solid-state emitter supply for Scandinavian racing yacht specifications. |
| Marina Operator Bundling | Aegean bareboat fleet density enables rapid deployment across vessel classes through centralized procurement agreements. |
| Dual-Technology Integration | Filtration-UV convergence reduces installation footprint for cramped sailboat engine rooms below half-square-meter constraints. |
| Direct-to-Owner Digital Channel | Pacific Northwest and New England cruising grounds exhibit technical literacy supporting DIY installation without yard intermediation. |
Research Methodology
A standing panel of yacht manufacturer platform engineers, charter fleet maintenance directors, Mediterranean chandlery procurement managers, and maritime regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from IMO circulars, USCG type-approval databases, ISO 11716 testing protocols, and customs trade records for titanium sponge and UV-C LED components. Bottom-up vessel fleet analysis triangulated against top-down equipment supplier revenue segmentation.
Scenario bracketing around enforcement intensity variations and titanium supply disruption magnitudes bounded projection ranges across the analysis window. Segmentation dimensions modeled include technology architecture, application context from coastal navigation to research expeditions, end-user procurement authority, and installation type from new build to retrofit. CAGRs were derived from equipment unit economics and fleet replacement cycles, with explicit modeling of Scandinavian racing mandate adoption curves and Mediterranean port inspection frequency.
Stress conditions across USCG-IMO regulatory divergence, titanium export restriction severity, and UV-C LED cost reduction trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enforcement harmonization and cell-stack miniaturization progress. Quarterly review of EPA small vessel discharge rulemaking developments and notified body queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Residential Water Softening Systems Market