
 North America Nitrogen Oxide Control Systems Market | 2026-2036
North America Nitrogen Oxide Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nitrogen Oxide Control Systems Market Analytics
Power purchase agreement-backed leasing for emissions control retrofits is reconfiguring capital deployment across the North American utility sector. Babcock & Wilcox Enterprises leverages its boiler heritage to anchor long-term service contracts at coal-to-gas conversion sites. Johnson Matthey sustains catalyst technology leadership through proprietary vanadium-titanium formulations optimized for fluctuating exhaust temperatures. Siemens Energy competes on integrated digital controls that merge NOx reduction with plant-wide efficiency optimization.
Nitrogen oxide control systems encompass engineered assemblies of catalysts, reagent injection hardware, and process controls designed to chemically reduce NOx concentrations in combustion exhaust streams to below regulated thresholds, typically achieving 85-95% removal efficiency in selective catalytic reduction configurations. These systems serve primarily to enable power generation, transportation, and industrial facilities to comply with ambient air quality standards while maintaining operational throughput. Selective catalytic reduction dominates installed capacity across North American power plants due to its proven performance at high flue-gas volumes, though exhaust gas recirculation gains traction in automotive applications as OEMs seek thermal management synergies with electrified powertrains. Catalysts command the largest component margin pool because their deactivation-driven replacement cycles generate recurring revenue streams independent of new system installations.
The EPA enforces National Ambient Air Quality Standards for nitrogen dioxide through state implementation plans, while CARB operates parallel zero-emission vehicle and in-use fleet rules that directly shape mobile source control system specifications. The U.S. Department of Energy funds demonstration projects for advanced ammonia slip controls and alternative reductants, indirectly steering R&D investment toward next-generation catalyst formulations. Stakeholders must monitor emerging state-level clean heat standards and potential federal power plant greenhouse gas rules that could bundle NOx controls with carbon capture retrofits, altering system design priorities and vendor selection criteria.
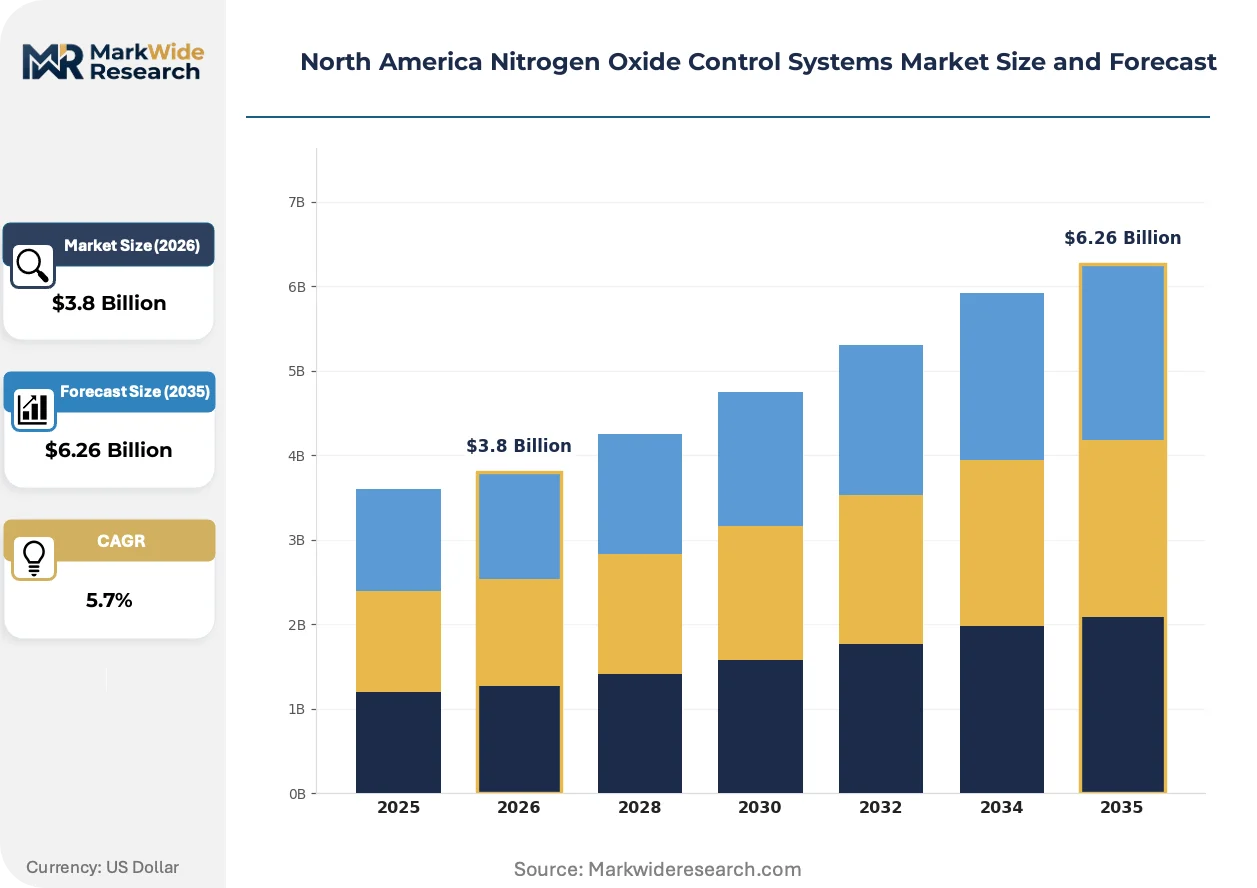
Market Dynamics
Power plant operators across the United States face compressed retrofit timelines as EPA Mercury and Air Toxics Standards compliance deadlines converge with aging coal fleet decommissioning schedules, forcing simultaneous decisions on selective catalytic reduction upgrades versus full unit replacement.
Growth Catalysts
- EPA Tier 4 mandates:Heavy-duty diesel engine manufacturers must achieve deeper NOx reductions, expanding demand for integrated exhaust aftertreatment systems across trucking and off-highway equipment fleets.
- Petrochemical corridor concentration:Refinery and chemical processing clusters along the U.S. Gulf Coast drive recurring catalyst replacement cycles tied to continuous operations and sulfur exposure degradation.
- Vanadium-titanium formulations:Advanced catalyst compositions optimized for fluctuating exhaust temperatures enable higher removal efficiency at lower ammonia slip rates, improving operational economics for cyclical power generation.
Market Restraints
- Ammonia supply volatility:Reagent costs fluctuate with agricultural fertilizer demand cycles and natural gas feedstock prices, compressing margins for continuous SCR operations.
- Catalyst manufacturing concentration:Specialty ceramic substrate and active material production clusters in select jurisdictions create supply vulnerability for North American system integrators.
- Exhaust gas recirculation substitution:Automotive OEMs pursuing thermal management synergies with electrified powertrains are displacing SCR hardware in certain light-duty segments.
Strategic Opportunities
- Canadian oil sands expansion:Alberta upgrading facilities face tightening provincial air quality standards, creating demand for high-capacity SCR trains processing heavy sour crude exhaust streams.
- Power purchase agreement leasing:Emissions control retrofit financing through long-term offtake contracts reconfigures capital deployment, lowering barriers for municipal utilities.
- Digital control convergence:Integration of NOx reduction optimization with plant-wide efficiency management creates bundled value propositions for integrated equipment vendors.
Industry Challenges
- Catalyst deactivation modeling:Predictive service scheduling requires specialized chemical engineering expertise scarce in regional maintenance contractor networks.
- Retrofit engineering complexity:Existing ductwork and structural steel constraints at mid-century power plants demand custom fabrication extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nitrogen Oxide Control Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Selective Catalytic Reduction, Non-Catalytic Reduction, Exhaust Gas Recirculation, Ammonia Injection Application: Power Plants, Automotive, Industrial Manufacturing, Marine Component: Catalysts, Control Units, Sensors, Valves End User: Utilities, OEMs, Manufacturing Facilities, Shipping Companies |
| Companies Covered | Babcock & Wilcox Enterprises, Johnson Matthey, CECO Environmental, Honeywell International, Ducon Technologies, John Wood Group, Siemens Energy, GE Vernova, ANDRITZ, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nitrogen Oxide Control Systems Market Evolving Landscape
Selective catalytic reduction technology is converging with digital process controls and alternative reductant chemistry, compressing the traditional separation between hardware supply and continuous optimization services.
Ceramic honeycomb catalyst substrates with engineered pore structures are hybridizing with embedded temperature and ammonia slip sensors, enabling real-time performance adjustment. Combined cycle gas turbine operators in Texas and Louisiana are adopting these intelligent catalyst systems to manage load-following operations. This convergence is compressing the vendor landscape toward integrated solution providers capable of delivering both materials and algorithmic optimization.
The EPA enforces National Ambient Air Quality Standards for nitrogen dioxide through state implementation plans requiring demonstrated attainment in non-attainment zones. Industrial facilities in the Ohio River Valley and California Central Valley face accelerated compliance schedules. Refinery operators are responding by front-loading SCR catalyst replacements ahead of mandated testing windows.
Long-term service contracts are displacing transactional equipment purchases among regulated utilities seeking to transfer performance risk to vendors. Babcock & Wilcox Enterprises anchors multi-decade agreements at coal-to-gas conversion sites. This model concentrates most visibly in the U.S. Southeast where municipal power authorities lack in-house emissions engineering capabilities.
North America Nitrogen Oxide Control Systems Market Segmentation
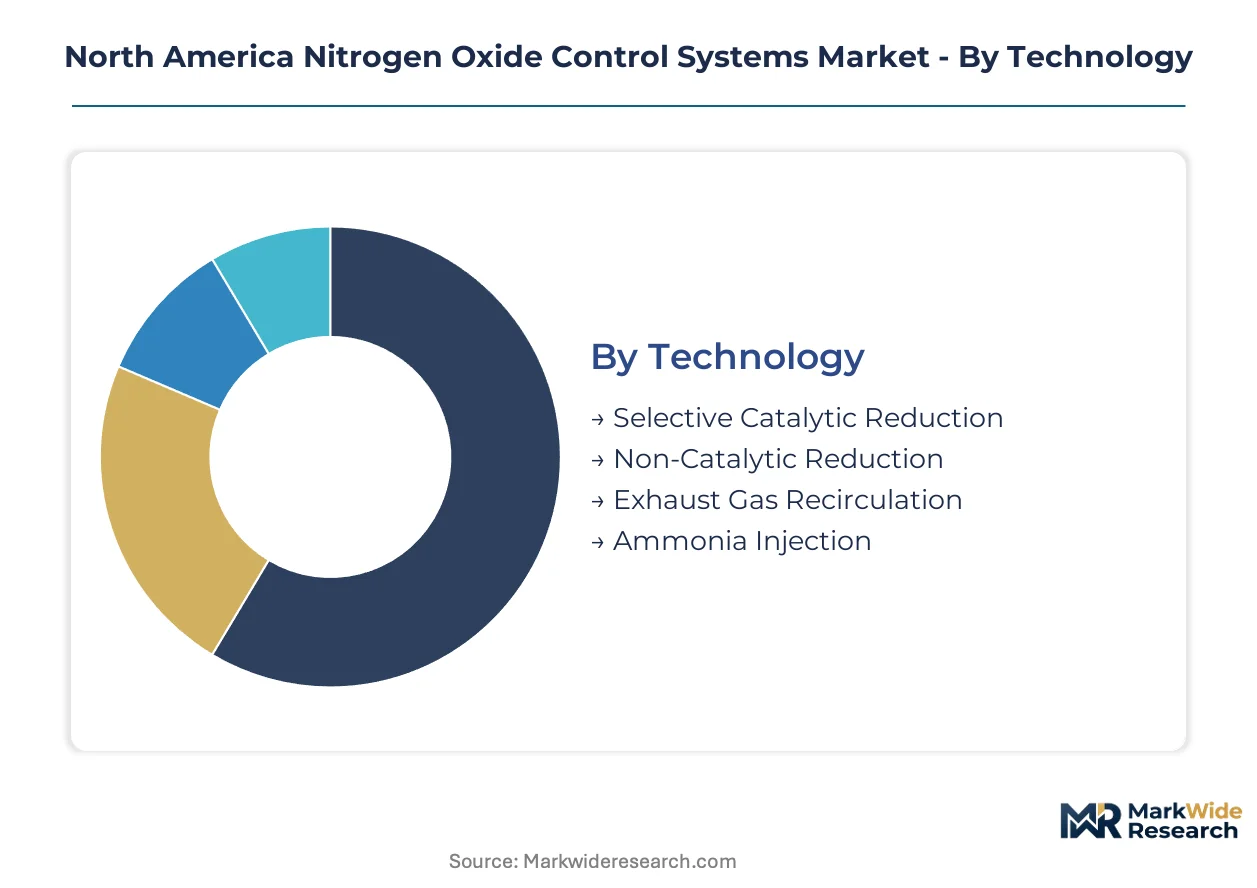
Technology selection in the North America Nitrogen Oxide Control Systems Market directly determines capital intensity, operating expenditure profiles, and regulatory compliance pathways. Component lifecycle variability and application-specific duty cycles create distinct margin pools and vendor specialization opportunities across each segment boundary.
Technology:
Selective catalytic reduction systems turn over on 3-5 year catalyst replacement cycles, while exhaust gas recirculation hardware persists for vehicle lifespans exceeding a decade.
- Selective Catalytic Reduction:Ceramic honeycomb substrates impregnated with vanadium-titanium or zeolite formulations achieve 85-95% NOx removal efficiency at 300-400°C operating windows. Demand concentrates at coal and gas-fired power plants across the Ohio River Valley and Texas ERCOT grid, where EPA MATS compliance deadlines force simultaneous retrofit decisions.
- Exhaust Gas Recirculation:Cooled exhaust stream recirculation lowers combustion temperatures to suppress thermal NOx formation without reagent consumption. Heavy-duty diesel OEMs in Michigan and Indiana integrate these systems with electrified powertrain thermal management, though CARB zero-emission mandates are compressing addressable market scope.
- Non-Catalytic Reduction:Urea or ammonia injection at 850-1100°C achieves moderate NOx reduction without catalyst substrates. Industrial boilers in California Central Valley non-attainment zones deploy these systems for cost-constrained compliance.
- Ammonia Injection:Reagent delivery skids and vaporization equipment enable precise NH3 distribution upstream of catalyst beds. Gulf Coast petrochemical facilities specify corrosion-resistant alloys for sour gas environments.
Selective catalytic reduction dominates installed base. Exhaust gas recirculation is where expansion concentrates in off-highway equipment segments.
Application:
Power plant retrofits command the highest per-unit value, while automotive volumes scale through OEM platform standardization.
- Power Plants:Flue gas treatment trains processing 1-5 million cubic feet per minute require modular SCR reactor designs. Utilities in the U.S. Southeast prioritize long-term service contracts over capital purchases.
- Automotive:EPA Tier 4 and CARB regulations mandate integrated aftertreatment architectures combining SCR, diesel oxidation catalysts, and diesel particulate filters. Heavy-duty truck demand clusters along I-75 and I-95 freight corridors.
- Industrial Manufacturing:Cement kilns, glass furnaces, and steel reheat furnaces exhibit highly variable exhaust compositions. Ohio and Pennsylvania facilities face accelerated state implementation plan compliance schedules.
- Marine:IMO Tier III standards in North American Emission Control Areas drive scrubber and SCR hybrid installations. Port authorities in Long Beach and Vancouver enforce at-berth emission limits.
Power plants anchor revenue concentration. Marine applications are climbing the fastest as ECAs expand.
Component:
Catalyst replacement generates recurring revenue independent of new system installations, while sensors and control units attach to plant digitalization budgets.
- Catalysts:Ceramic or metallic substrates with engineered pore structures degrade through thermal sintering, poisoning, and masking. Gulf Coast refineries front-load replacement cycles ahead of regulatory testing windows.
- Control Units:Distributed control system integration enables real-time ammonia slip optimization and load-following performance adjustment. Texas combined cycle operators specify these for ERCOT grid volatility.
- Sensors:NOx, NH3, and temperature probes embedded in catalyst layers feed model predictive control algorithms. California facilities require redundant measurement for compliance documentation.
- Valves:High-temperature butterfly and slide gate designs manage reagent flow distribution across large duct cross-sections. Custom fabrication extends lead times at constrained foundries.
Catalysts command the largest margin pool. Control units are gaining share fastest through digital convergence.
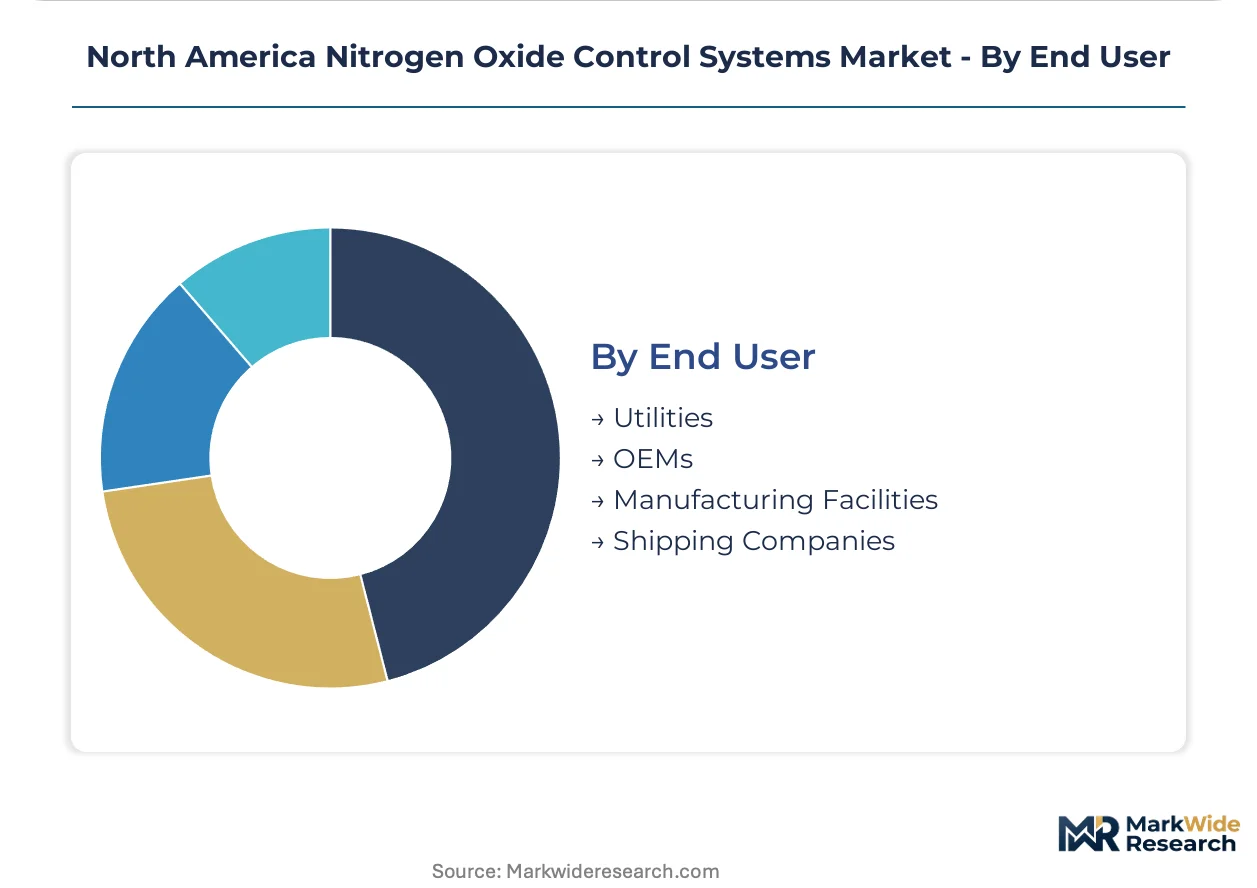
End User:
Utilities outsource engineering expertise through performance contracts, while manufacturing facilities retain in-house maintenance capabilities.
- Utilities:Municipal power authorities and investor-owned generators transfer operational risk to vendors via multi-decade service agreements. Southeast municipal utilities lack in-house emissions engineering depth.
- OEMs:Engine manufacturers integrate aftertreatment as factory-standard equipment rather than aftermarket retrofit. Detroit and Columbus engineering centers specify platform-common architectures.
- Manufacturing Facilities:Process industries with continuous operations prioritize catalyst durability and reagent cost predictability. Alberta oil sands upgraders face tightening provincial air quality standards.
- Shipping Companies:Container lines and tanker operators amortize scrubber-SCR capital across 20-year vessel lifespans. Vancouver and Seattle port calls trigger at-berth emission control requirements.
Utilities dominate contract value. Manufacturing facilities represent the steepest expansion trajectory as provincial standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Mercury and Air Toxics Standards compliance deadlines are accelerating retrofit investments across North American power generation infrastructure. CARB zero-emission mandates and state implementation plans for National Ambient Air Quality Standards create parallel regulatory pressure corridors. Industrial clusters in petrochemical corridors and freight corridors concentrate equipment deployment and catalyst replacement cycles.
United States
Power plant operators in the Ohio River Valley and Texas ERCOT grid face compressed SCR retrofit timelines as MATS deadlines converge with coal fleet decommissioning schedules. EPA enforcement of National Ambient Air Quality Standards through state implementation plans demands demonstrated attainment in non-attainment zones. The U.S. Gulf Coast petrochemical corridor drives recurring catalyst replacement cycles at refinery and chemical processing clusters in Texas and Louisiana.
Canada
Alberta oil sands upgraders face tightening provincial air quality standards that mandate high-capacity SCR trains processing heavy sour crude exhaust streams. Environment and Climate Change Canada coordinates with provincial regulators on industrial emission reduction frameworks. Upgrading facilities in the Athabasca region front-load catalyst replacements ahead of regulatory testing windows to maintain continuous operations.
Mexico
Heavy-duty diesel fleet modernization programs expand demand for integrated exhaust aftertreatment systems across trucking corridors connecting Mexico City to Laredo and Monterrey to Houston. SEMARNAT implements vehicle emission standards aligned with EPA Tier 4 trajectories. Manufacturing clusters in Nuevo León and the Bajío Region specify factory-standard SCR equipment for export-oriented production.
North America Nitrogen Oxide Control Systems Market Competitive Landscape
On the supply side, the industry is consolidating around integrated solution providers capable of delivering catalyst materials, reagent injection hardware, and algorithmic process controls as unified offerings. Engineering heritage from boiler manufacturing and power plant construction anchors long-term service contract positioning. Two strategic archetypes dominate: vertically integrated catalyst formulators with proprietary material science capabilities, and industrial conglomerates bundling emissions hardware with plant-wide digitalization platforms. Competitive moves concentrate on multi-decade performance contracts that transfer operational risk to vendors, and convergence of NOx reduction optimization with broader plant efficiency management systems.
Among North American engineering specialists, Babcock & Wilcox Enterprises and CECO Environmental exemplify the long-term service contract archetype, anchoring agreements at coal-to-gas conversion sites and industrial boiler installations. Siemens Energy occupies a position within the integrated digital controls tier, representing convergence of emissions hardware with plant-wide automation platforms. Johnson Matthey sits within the catalyst technology specialization vector, exemplifying proprietary formulation capabilities optimized for fluctuating exhaust conditions.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises |
| Johnson Matthey |
| CECO Environmental |
| Honeywell International |
| Ducon Technologies |
| John Wood Group |
| Siemens Energy |
| GE Vernova |
| ANDRITZ |
| Others |
Value Network & Pricing Analysis
Specialty ceramic substrate manufacturing clusters in Germany and Japan anchor margin capture for North American system integrators, concentrating pricing power among catalyst formulators with proprietary vanadium-titanium active material capabilities while compressing margins for downstream reagent injection hardware assemblers.
Pricing Analysis
Certification level creates the primary spread across the market, with EPA MATS-compliant systems commanding substantial premiums over non-attainment zone baseline configurations. Project-based contracting dominates capital equipment, while long-term service agreements bundle catalyst replacement cycles with ammonia supply management. Price differentiation stems from ammonia slip performance guarantees and digital control integration depth. Municipal utilities in the U.S. Southeast exhibit acute price sensitivity due to constrained capital budgets, whereas Gulf Coast petrochemical operators prioritize uptime assurance over unit economics.
Supply Chain Analysis
Upstream titanium dioxide and vanadium pentoxide feedstock production concentrates in China, South Africa, and Russia, creating raw material dependencies for catalyst formulators. Ceramic honeycomb substrates draw from cordierite and silicon carbide suppliers clustered in Germany and Japan. Single-source vulnerability runs through specialty alloy foundries producing corrosion-resistant ammonia injection hardware. Distribution runs through EPC contractors and direct OEM relationships, with digital control modules increasingly shipping through automation system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
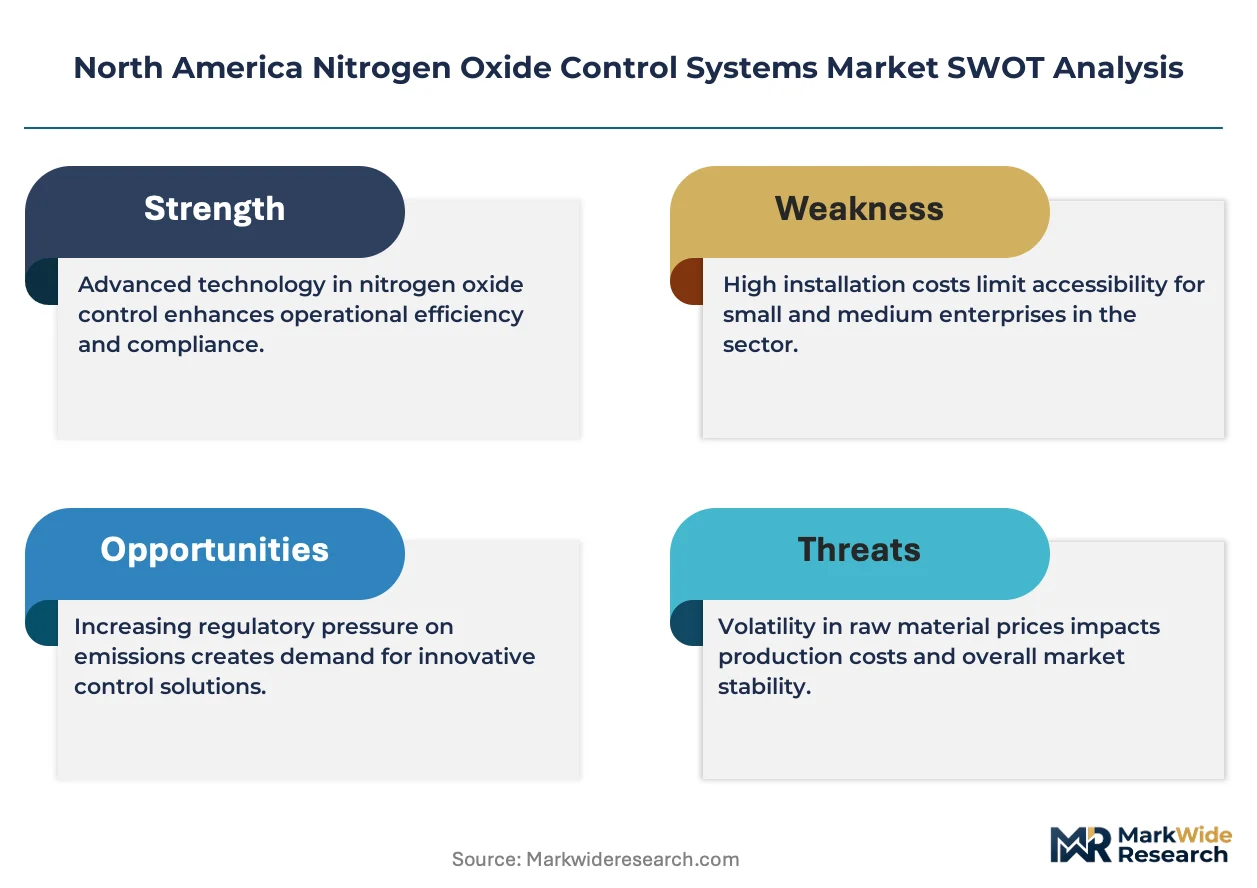
North American nitrogen oxide control systems sit in early-cycle expansion as EPA MATS compliance deadlines force simultaneous retrofit decisions across aging coal and gas-fired infrastructure, compressing vendor selection timelines and accelerating contract velocity.
For Market Incumbents: Entrench multi-decade performance contracts at coal-to-gas conversion sites before competitors replicate Babcock & Wilcox's service model. Deepen backward integration into ceramic substrate production to offset catalyst manufacturing concentration risk. Lock in ammonia supply partnerships to defend margin position against agricultural fertilizer demand cycles. For New Entrants and Emerging Players: Mid-market industrial boilers in California Central Valley non-attainment zones represent the most penetrable entry point, with cost-constrained compliance demand for non-catalytic reduction systems. Alberta oil sands upgraders facing tightening provincial standards offer white-space expansion for high-capacity SCR trains. Partner with regional maintenance contractors lacking predictive catalyst deactivation modeling capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated catalyst formulators with proprietary material science IP and recurring replacement revenue streams. Long-term viability hinges on digital control convergence capabilities that merge NOx reduction with plant-wide efficiency optimization. Monitor EPA enforcement patterns in Ohio River Valley non-attainment zones as inflection indicators for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Service Contract Expansion | Babcock & Wilcox anchors multi-decade agreements that transfer operational risk from municipal utilities. |
| Backward Integration into Ceramic Substrates | Johnson Matthey's proprietary formulations reduce supply vulnerability from German and Japanese substrate suppliers. |
| Digital Control Convergence | Siemens Energy bundles NOx optimization with plant-wide automation platforms for ERCOT grid volatility management. |
| Ammonia Supply Partnership | Reagent cost predictability contracts defend margins against agricultural fertilizer demand cyclicality. |
| Regional Maintenance Contractor Alliance | Predictive catalyst deactivation expertise scarcity creates partnership opportunities for algorithmic service providers. |
Research Methodology
Cross-validation between primary interviews with power plant operators, EPC contractors, catalyst procurement managers, and emissions engineering consultants and secondary sources including EPA enforcement databases, FERC filings, and EIA power plant inventory records anchors the qualitative findings. Bottom-up unit installation tracking triangulates against top-down utility capital expenditure disclosures.
Calibration against historical MATS compliance wave patterns and catalyst replacement cycle data informs the projection framework across technology, application, component, and end-user segmentation dimensions. CAGRs derive from regression analysis of retrofit decision timelines correlated with regulatory deadline proximity. Forecast inputs incorporate natural gas price trajectories affecting ammonia production economics and coal fleet decommissioning schedules.
Practitioners should monitor EPA state implementation plan enforcement acceleration and CARB zero-emission mandate expansion for early signals of demand inflection. Cross-checking against EIA generator survey data and utility IRP filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market