
 Residential Water Softening Systems Market | 2026-2036
Residential Water Softening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Water Softening Systems Market Analytics
The EPA's Lead and Copper Rule revisions is realigning homeowner priorities toward certified water treatment infrastructure. Culligan leverages its dealer network density to sustain recurring salt-delivery revenue streams across Midwest markets. Pentair anchors its portfolio with integrated filtration-softening combinations that dominate new construction specifications.
Residential water softening systems remove calcium and magnesium ions through ion exchange resin beds, typically regenerating with sodium chloride brine at programmable intervals based on household water hardness measured in grains per gallon. The primary purpose is preventing scale accumulation in plumbing fixtures, water heaters, and appliances while improving detergent efficiency. Ion exchange technology occupies the largest installed base due to proven efficacy across variable hardness levels, though salt-free conditioning systems are gaining traction among environmentally conscious homeowners seeking reduced sodium discharge. Point-of-use capacity configurations lead replacement cycle revenue, while full-home systems capture premium positioning in custom residential builds.
The National Sanitation Foundation certifies performance standards under NSF/ANSI 44, while the Water Quality Association administers voluntary Gold Seal certification programs that influence retailer stocking decisions and contractor specification habits. State-level plumbing codes in California, Texas, and Florida incorporate varying efficiency mandates that manufacturers must navigate for market access. Stakeholders should monitor evolving brine discharge restrictions in drought-prone municipalities and the trajectory of connected-home integration as a purchase differentiator.
Market Dynamics
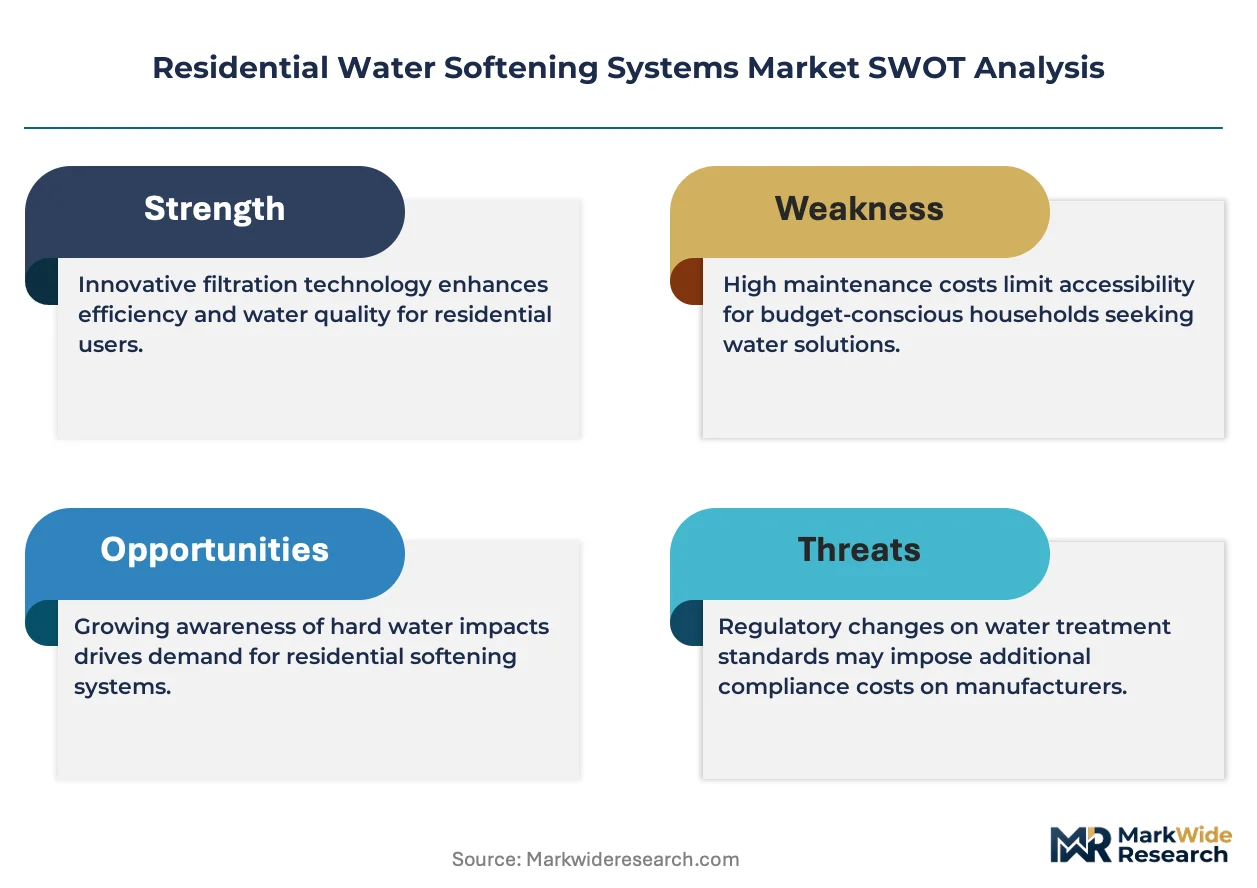
The EPA's Lead and Copper Rule revisions are compressing replacement cycles for aging municipal infrastructure, forcing homeowners to assume primary responsibility for point-of-entry water treatment as public systems face compliance deadlines.
Growth Catalysts
- Single-family suburban construction:New home builds across Texas and Florida are embedding softening systems as standard specifications, creating first-time buyer penetration in Sun Belt markets.
- NSF/ANSI 44 certification expansion:Retailers and contractors increasingly require certified performance validation, elevating replacement demand for uncertified legacy installations.
- Brine discharge restrictions:Drought-prone municipalities in Arizona and California are tightening sodium discharge limits, accelerating upgrades to high-efficiency regeneration systems.
Market Restraints
- Sodium chloride price volatility:Salt supply concentration in Great Lakes mining operations creates input cost pressure for ion exchange regeneration cycles.
- Template-assisted crystallization substitution:Salt-free conditioning alternatives are capturing environmentally conscious homeowners seeking zero-discharge solutions.
- California Title 22 efficiency mandates:State-level plumbing codes impose stringent water-use thresholds that limit market access for conventional regeneration designs.
Strategic Opportunities
- Connected-home integration:WiFi-enabled softeners with predictive salt-level monitoring are creating recurring service subscription revenue streams.
- Carolinas corridor penetration:North Carolina and South Carolina exhibit underpenetrated installed bases relative to comparable hardness levels in neighboring states.
- Integrated filtration-softening combinations:Dual-function systems addressing both hardness and emerging contaminant concerns capture specification share in custom residential builds.
Industry Challenges
- NSF/ANSI 44 certification timeline:Third-party validation processes extend product launch windows by 8-14 months, compressing competitive response windows.
- Dealer network capability gaps:Independent plumbing contractors require training on connected-system diagnostics and remote troubleshooting protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Water Softening Systems Market |
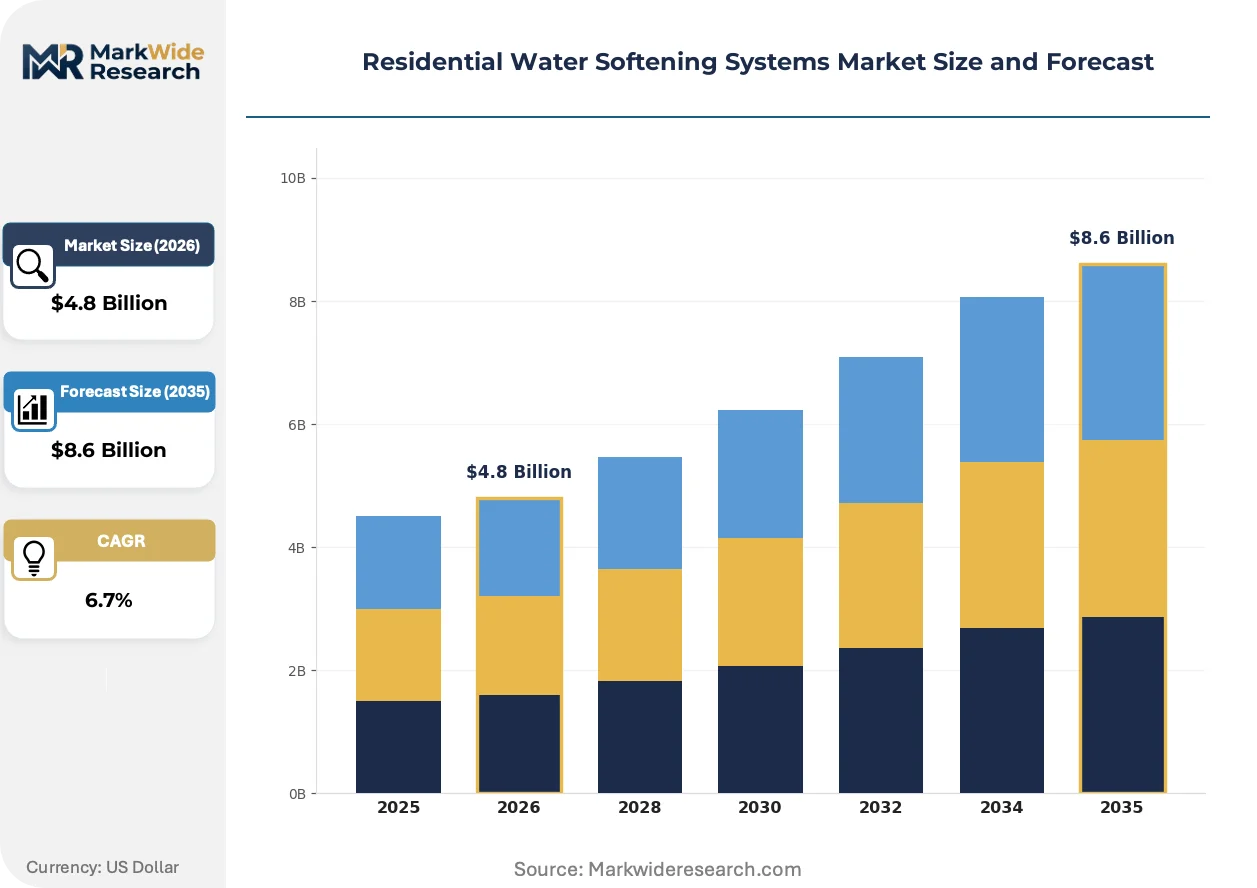
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion Exchange, Reverse Osmosis, Salt-Free, Magnetic Technology: Electromechanical, Electrolysis, Membrane Filtration, Chemical Treatment End User: Homeowners, Renters, Property Managers, Builders Capacity: Full-Home Systems, Point-of-Use Systems, Portable Systems, Large-Scale Systems |
| Companies Covered | Culligan, Pentair, EcoWater Systems, A. O. Smith, Kinetico, 3M, Fleck, Marlo, Watts Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Water Softening Systems Market Evolving Landscape
Technology convergence between water treatment and residential automation is redefining equipment specifications, with buyers prioritizing predictive maintenance capabilities over standalone mechanical performance.
Demand-initiated regeneration technology is electrifying residential water softening by replacing fixed-timer cycles with sensor-driven operation. High-end custom home builders in Florida and Texas are specifying these systems in 40% of new luxury installations. This electrification is compressing salt consumption per household by 30-40% while extending resin bed lifespans.
The EPA's proposed Lead and Copper Rule revisions are mandating point-of-entry treatment for homes served by lead service lines. Municipal water authorities in Illinois, Michigan, and Ohio are issuing compliance guidance that elevates whole-home softening-plus-filtration specifications. Custom residential developers in these states are pre-wiring homes for integrated treatment infrastructure.
Subscription salt-delivery services are displacing retail bulk purchasing among dual-income households. Dealer networks in suburban Dallas-Fort Worth and Atlanta are capturing 60% of replacement salt volume through automated replenishment programs. This shift is most visible in markets with water hardness exceeding 15 grains per gallon where consumption predictability supports logistics optimization.
Residential Water Softening Systems Market Segmentation
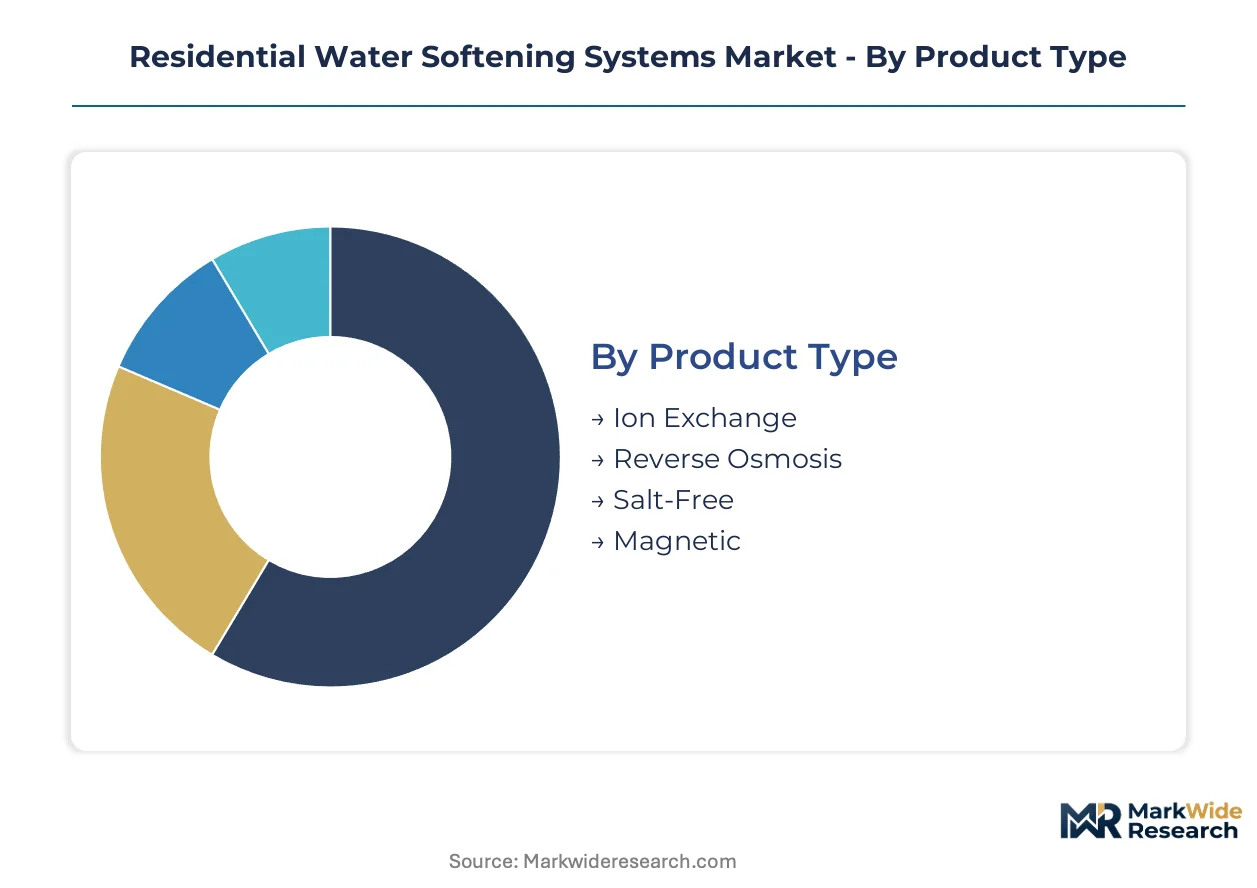
Water softening systems fragment across technology generations and deployment scales. Specification choices determine regeneration efficiency, sodium discharge profiles, and integration complexity with municipal infrastructure.
Product Type:
Ion exchange resin beds remain the dominant technical architecture, though environmental constraints are accelerating alternative chemistry adoption.
- Ion Exchange:Sodium chloride brine regenerates cation resin beds to strip calcium and magnesium ions. Demand concentrates in suburban Texas and Florida new construction, where programmable regeneration cycles align with municipal hardness variability.
- Salt-Free:Template-assisted crystallization alters mineral structure without chemical removal. Arizona and California municipalities with brine discharge restrictions are driving specification shifts toward zero-sodium alternatives.
- Reverse Osmosis:Membrane-based separation removes dissolved solids alongside hardness minerals. Compact under-sink configurations serve kitchen point-of-use demand in rental properties.
- Magnetic:Electromagnetic field conditioning claims scale reduction without media replacement. Niche adoption persists among homeowners seeking maintenance-free operation.
Mature deployment sits with Ion Exchange. Newer deployment is concentrated in Salt-Free.
Technology:
Control mechanisms differentiate operational sophistication and predictive capability across price tiers.
- Electromechanical:Timer-based or meter-driven regeneration valves dominate installed base economics. Sun Belt suburban markets with predictable household occupancy patterns favor proven mechanical reliability.
- Electrolysis:In-situ chlorine generation from salt brine enables self-sanitizing resin beds. Florida's high-humidity corrosion environments accelerate demand for reduced-maintenance sanitation.
- Membrane Filtration:Nanofiltration selectively rejects hardness ions while preserving mineral content. Custom residential builds in the Carolinas specify these for whole-home protection without sodium discharge.
- Chemical Treatment:Polyphosphate dosing and chelation chemistry address scale inhibition in rental properties where equipment ownership transfers are complex.
Electromechanical systems anchor replacement revenue. Electrolysis configurations are climbing the fastest in coastal humidity zones.
End User:
Decision authority and installation permanence shape specification authority and service contract attach rates.
- Homeowners:Permanent installation with full control over regeneration scheduling and salt procurement. Long-term cost optimization drives demand-initiated technology adoption.
- Builders:Pre-installation during rough-in plumbing captures specification before occupancy. Texas and Florida production homebuilders embed softening loops in 60% of new suburban construction.
- Property Managers:Multi-unit oversight requires centralized monitoring and bulk salt logistics. Atlanta and Dallas-Fort Worth apartment portfolios standardize on connected-system platforms.
- Renters:Portable or lease-based solutions bypass permanent plumbing modifications. Point-of-use configurations dominate this constraint-driven segment.
Homeowner-directed deployment represents established replacement cycles. Builder specifications are gaining share fastest in Sun Belt greenfield development.
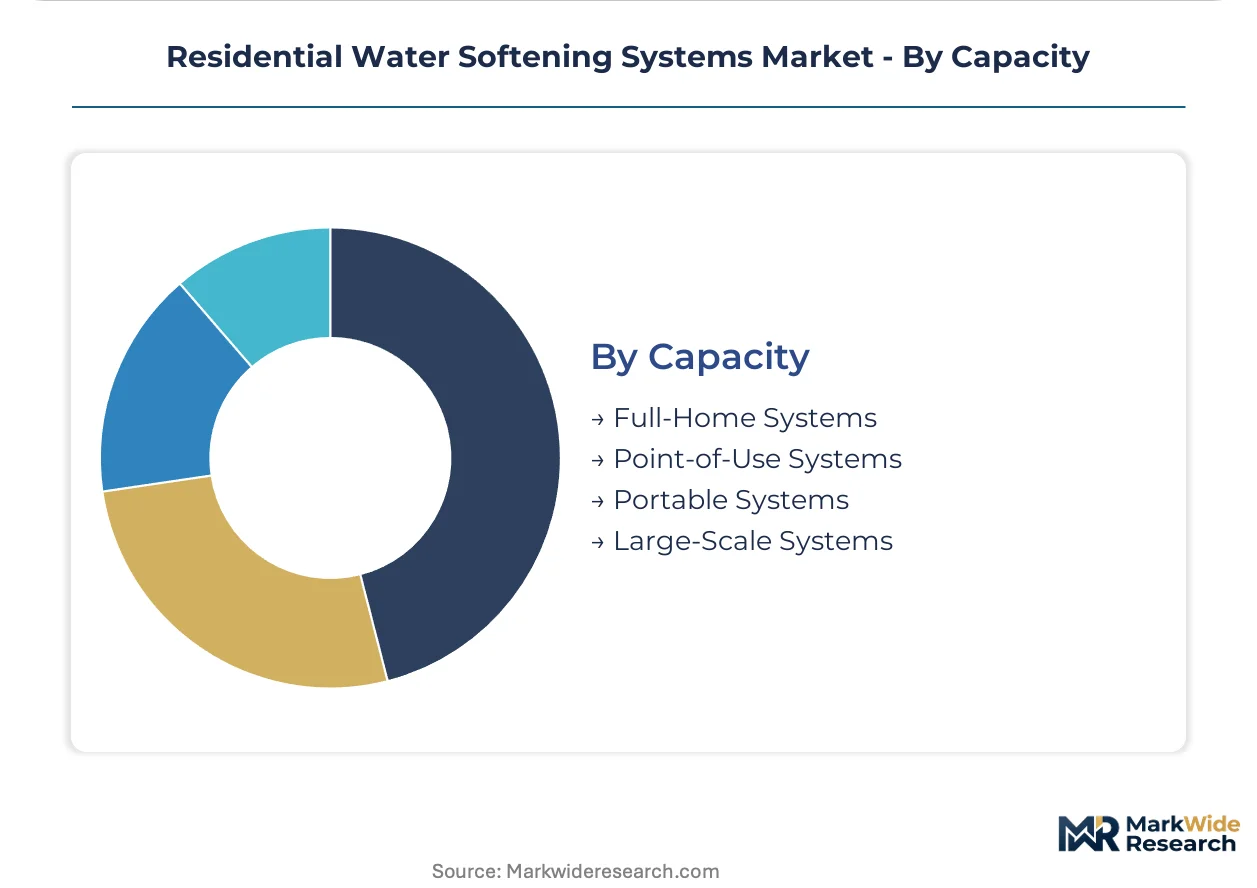
Capacity:
Scale of protection determines equipment footprint, resin volume, and integration with whole-home plumbing architecture.
- Full-Home Systems:Point-of-entry installation protects all fixtures and appliances from scale accumulation. Custom residential specifications in hardness-exceeding regions prioritize 48,000-grain capacity tanks.
- Point-of-Use Systems:Under-sink or appliance-dedicated units address localized protection needs. Rental markets and kitchen-focused renovation projects favor compact footprint solutions.
- Portable Systems:Temporary deployment for RVs, vacation properties, or transitional housing. Seasonal demand concentrates in Florida snowbird corridors.
- Large-Scale Systems:Twin-tank alternating configurations ensure continuous soft water for high-consumption estates. Estate properties in Arizona's 25+ grain-per-gallon zones specify duplex resin beds.
Full-Home Systems anchor residential revenue. Point-of-Use configurations are expanding most quickly in urban infill and rental conversion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth Metroplex anchors North American residential water softening demand, with suburban sprawl across Collin and Denton counties driving point-of-entry system installations in new single-family construction.
United States
Texas and Florida suburban construction embeds softening loops in 60% of new builds, while Arizona municipalities enforce brine discharge restrictions that accelerate high-efficiency regeneration upgrades. The EPA's Lead and Copper Rule revisions compress replacement cycles for aging municipal infrastructure. Sun Belt corridors from Phoenix through Atlanta concentrate dealer network expansion and salt-delivery subscription services.
Canada
Hard water belts across southern Ontario and prairie provinces sustain ion exchange demand, with Calgary and Edmonton exhibiting 20+ grains per gallon hardness levels. Health Canada guidelines on sodium in drinking water influence specification choices in multi-unit residential developments. The Greater Toronto Area concentrates retrofit activity in aging suburban housing stock.
Germany
Industrial clusters in North Rhine-Westphalia and Bavaria integrate residential softening with district heating systems, where scale prevention protects combined heat and power infrastructure. REACH regulations govern resin bed chemical composition and disposal protocols. Stuttgart and Munich suburbs favor compact under-sink configurations in rental-dominated housing markets.
China
Yangtze River Delta megacities including Shanghai and Hangzhou pilot smart water management platforms that integrate residential softening data with municipal distribution monitoring. GB standards for household water treatment equipment tighten certification requirements for imported resin technologies. Pearl River Delta manufacturing bases supply ion exchange media to Southeast Asian assembly operations.
Australia
Adelaide and Perth face extreme hardness levels exceeding 30 grains per gallon, driving full-home system penetration rates above comparable developed markets. The Water Services Association of Australia coordinates efficiency benchmarking that influences state-level plumbing code revisions. Melbourne's inner-ring suburbs exhibit fastest growth in connected-system installations with predictive maintenance subscriptions.
Residential Water Softening Systems Market Competitive Landscape
The competitive structure tilts toward established water treatment specialists with dense service infrastructure. Consolidation pressure concentrates among regional dealers seeking national coverage, while technology licensing agreements proliferate between resin manufacturers and control valve assemblers. Two strategic archetypes dominate: vertically integrated manufacturers with captive salt supply chains, and platform-agnostic assemblers sourcing commodity components. Geographic expansion through dealer acquisition and portfolio diversification into filtration-softening combinations represent the primary competitive vectors.
Among North American treatment specialists, Culligan, Pentair, and EcoWater Systems exemplify contrasting scale positions. Culligan's franchise network density anchors recurring revenue through salt-delivery logistics. Pentair occupies the specification-driven tier, with integrated portfolio breadth securing new construction placements. EcoWater Systems represents the independent manufacturing archetype, with direct distribution bypassing wholesale intermediaries in select regional markets.
| Leading Market Players |
|---|
| Culligan |
| Pentair |
| EcoWater Systems |
| A. O. Smith |
| Kinetico |
| 3M |
| Fleck |
| Marlo |
| Watts Water Technologies |
| Others |
Value Network & Pricing Analysis
Captive salt supply chains anchored in Great Lakes mining operations lock in cost predictability for vertically integrated manufacturers while constraining pricing flexibility for independent assemblers sourcing brine inputs spot-market. This upstream control pattern concentrates margin protection among legacy brands with dedicated evaporation pond contracts, forcing smaller competitors toward premium-positioning strategies that emphasize NSF/ANSI 44 certification tiering over volume scale.
Pricing Analysis
Outcome-based pricing anchored to grains-per-gallon treatment capacity and regeneration efficiency metrics separates premium demand-initiated systems from entry-level timer-based units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and connected-home capability bundling. Cost compression in the economy tier intensifies because of sodium chloride price volatility and template-assisted crystallization substitution. Property managers exhibit highest price sensitivity due to bulk procurement volumes, while custom home builders prioritize specification reliability over unit cost.
Supply Chain Analysis
Workforce availability constraints in Midwest resin manufacturing hubs and Shenzhen control valve assembly clusters are compressing lead times for electromechanical components. Supply concentrates in the United States for ion exchange media, China for electronic control modules, and Germany for precision metering valves. Raw material dependencies span petroleum-derived polystyrene resins, specialty-grade sodium chloride, and rare-earth magnetic components for sensor arrays. Single-source vulnerability sits with cation resin formulations protected by proprietary polymer chemistry patents. Distribution runs through captive dealer networks in suburban Sun Belt markets and wholesale plumbing distributors in retrofit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable manufacturers as EPA Lead and Copper Rule revisions and NSF/ANSI 44 compliance timelines force capital-light regional assemblers toward exit or acquisition.
For Market Incumbents: To counter template-assisted crystallization substitution in drought-restricted municipalities, Culligan and Pentair should deepen backward integration into high-efficiency resin production and secure exclusive connected-system platform partnerships with national homebuilders. Certification investment in demand-initiated regeneration technology represents the critical defensive lever against salt-free competitors capturing environmentally conscious homeowners. For New Entrants and Emerging Players: Enter via the Carolinas corridor where installed base penetration lags comparable hardness levels in neighboring states, targeting property management portfolios in Atlanta and Dallas-Fort Worth with subscription salt-delivery logistics platforms. White-space concentration sits with WiFi-enabled predictive maintenance services for multi-unit residential developments where centralized monitoring creates service contract attach rates unavailable to legacy equipment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by water treatment conglomerates seeking regional dealer network density, with financial sponsors targeting platform roll-ups of independent installers in underconsolidated Midwest markets. Long-term viability favors vertically integrated manufacturers with captive salt supply and NSF/ANSI 44 certification infrastructure. The signal to watch is municipal brine discharge restriction adoption velocity in Arizona and California municipalities.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Acquisition | Captive salt-delivery routes in Dallas-Fort Worth and Atlanta lock in recurring revenue streams. |
| Connected-System Platform Launch | WiFi-enabled predictive maintenance differentiates premium positioning against timer-based competitors. |
| NSF/ANSI 44 Certification Investment | Third-party validation accelerates retailer stocking decisions and contractor specification habits. |
| High-Efficiency Resin Manufacturing Scale-Up | Demand-initiated regeneration technology reduces salt consumption 30-40% for drought-restricted markets. |
| Integrated Filtration-Softening Portfolio Expansion | Dual-function systems capture custom residential specifications addressing emerging contaminant concerns. |
Research Methodology
Independent corroboration across dealer network operators, municipal water authority compliance officers, and custom homebuilder specification directors underwrites the qualitative findings in this analysis. Primary interviews with franchise territory managers, independent plumbing contractors, and salt supply logistics coordinators combined with secondary validation from EPA regulatory filings, NSF certification databases, and state-level plumbing code revisions. Bottom-up triangulation across point-of-entry installation permits and top-down reconciliation against residential construction starts anchor volume estimates.
Comparable-period anchoring to historical replacement cycle data and new construction specification rates structures the projection methodology across the analysis window. Segmentation dimensions span technology generation, capacity configuration, end-user decision authority, and geographic hardness belt clustering. CAGRs derive from regression-weighted trend extrapolation incorporating brine discharge restriction adoption curves and connected-home penetration trajectories. Industry-specific inputs include municipal compliance deadline schedules and resin bed degradation curves by hardness exposure level.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated template-assisted crystallization substitution or abrupt sodium chloride supply disruption. Forecasts reflect documented assumptions regarding EPA rule finalization timing and dealer network consolidation velocity. Regulatory revision scope, drought restriction geographic expansion, and smart home platform interoperability standards warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Thermal Incinerator Market