
 Global Leak Detection and Repair (LDAR) Market | 2026-2036
Global Leak Detection and Repair (LDAR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Leak Detection and Repair (LDAR) Market Foresight
EPA Method 21 precision standards is collapsing the gap between manual sniffing programs and continuous monitoring architectures. ABB leverages its distributed control systems footprint to anchor LDAR integration within process automation suites. Honeywell International sustains technology leadership through its infrared camera portfolio for optical gas imaging. Emerson Electric differentiates via ultrasonic detector arrays that operate in hazardous area classifications without hot-work permits.
Leak Detection and Repair comprises systematic identification, quantification, and remediation of fugitive emissions from pressurized equipment using portable gas detectors, optical infrared cameras, and acoustic sensors operating at detection thresholds below 500 parts per million methane equivalent. The practice serves regulatory compliance and operational safety across hydrocarbon handling facilities where uncontrolled vapor releases create ignition hazards and greenhouse gas liabilities. Infrared cameras dominate solution type revenue due to their ability to visualize hydrocarbon plumes in real time without direct contact. Petrochemical plants represent the fastest-growing application segment as crackers and aromatics complexes face intensified benzene and volatile organic compound monitoring obligations. Onshore installations occupy the largest installation environment share, though offshore platforms command premium pricing for corrosion-resistant and explosion-proof sensor housings.
The US EPA enforces New Source Performance Standards under Clean Air Act Section 111 that mandate quarterly or semiannual monitoring frequency depending on facility type and component count. Europe's Industrial Emissions Directive and F-Gas Regulation impose parallel obligations on refineries and chemical complexes across Germany, the Netherlands, and Belgium. China's Ministry of Ecology and Environment integrates LDAR into national carbon intensity reduction protocols through provincial environmental protection bureaus. Stakeholders must monitor regulatory divergence between prescriptive inspection intervals and emerging continuous monitoring performance standards that redefine capital deployment timelines.
Market Dynamics
EPA Method 21 precision standards are compressing detection thresholds below 500 ppm methane equivalent, forcing oil and gas operators to retire manual sniffing programs in favor of continuous monitoring architectures that integrate optical gas imaging with distributed control systems.
Growth Catalysts
- US EPA methane regulations:New Source Performance Standards under Clean Air Act Section 111 mandate quarterly or semiannual monitoring frequency, creating compliance-driven hardware refresh cycles across upstream facilities.
- Optical gas imaging adoption:Infrared cameras visualize hydrocarbon plumes in real time without direct contact, displacing legacy portable gas detectors in Permian Basin operations.
- Petrochemical cracker expansions:Benzene and volatile organic compound monitoring obligations at aromatics complexes in Texas and Louisiana are accelerating sensor deployment timelines.
Market Restraints
- Explosion-proof sensor housing costs:Corrosion-resistant stainless steel enclosures for offshore platforms carry 3-4x material premiums versus onshore aluminum alternatives.
- Calibration gas supply concentration:Certified methane-in-air reference standards originate from a limited set of specialty gas suppliers in Germany and the United States.
- Acoustic sensor range limitations:Ultrasonic detector arrays suffer degraded performance in high-velocity gas flow environments above 30 meters per second.
Strategic Opportunities
- China provincial carbon intensity protocols:Ministry of Ecology and Environment integration of LDAR into national dual carbon goals creates first-mover positioning for continuous monitoring vendors.
- Drone-mounted sensor convergence:Unmanned aerial vehicles paired with miniaturized infrared cameras enable pipeline corridor surveys without ground crew mobilization.
- Belgium-Netherlands refinery cluster:Industrial Emissions Directive enforcement at Antwerp-Rotterdam chemical hubs generates concentrated demand for benzene leak detection retrofit programs.
Industry Challenges
- Certified thermographer scarcity:Optical gas imaging operation requires EPA Method 21-qualified personnel, with training backlogs extending deployment timelines at Texas midstream operators.
- Legacy SCADA integration friction:Continuous monitoring data streams require protocol translation layers to interface with decades-old distributed control systems at onshore tank farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Leak Detection and Repair (LDAR) Market |
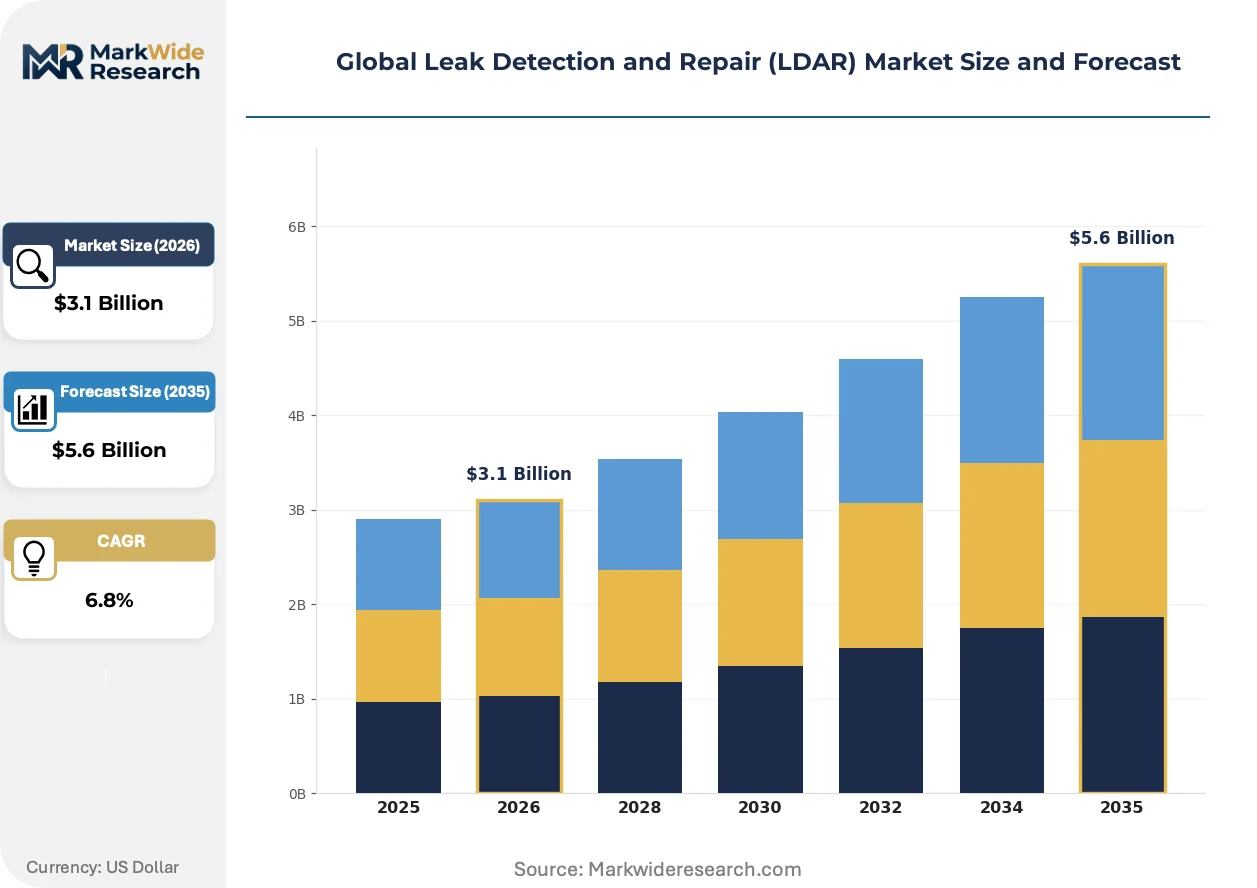
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Gas Detectors, Infrared Cameras, Ultrasonic Detectors, Optical Sensors, Vapor Analyzers Application: Petrochemical Plants, Chemical Processing, Pharmaceutical Manufacturing, Refining Operations, Power Generation Installation Environment: Onshore Installations, Offshore Platforms, Underground Pipelines, Storage Facilities, Distribution Networks End User: Oil & Gas Operators, Chemical Manufacturers, Utility Companies, Environmental Agencies, Facility Management |
| Companies Covered | Aeris Technologies, Bridger Photonics, Picarro, ABB, Honeywell International, Emerson Electric, Schneider Electric, Teledyne FLIR, Kairos Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Leak Detection and Repair (LDAR) Market Shifts & Advancements
Detection technology architectures are bifurcating between portable compliance tools and permanent sensor networks, with capital deployment decisions increasingly tied to regulatory monitoring frequency mandates rather than operational risk calculations alone.
Continuous emissions monitoring systems are fragmenting the traditional LDAR service model. These sensor networks stream methane concentration data to cloud analytics platforms, enabling predictive maintenance triggers. Majors in the Permian Basin are piloting 24/7 coverage at compressor stations, collapsing the window between leak onset and repair initiation from quarterly intervals to hours.
Europe's F-Gas Regulation is tightening hydrofluorocarbon phase-down schedules, indirectly pressuring refrigerant leak detection protocols at German chemical complexes. The regulation's quota allocation mechanism is redirecting capital toward alternative cooling technologies with lower global warming potential. Refinery operators in the Netherlands are responding by retrofitting ammonia detection arrays alongside hydrocarbon sensors.
Asset owner procurement patterns are consolidating vendor relationships around integrated automation suppliers. Single-source contracting for sensors, analytics software, and maintenance services is displacing point-solution purchasing at integrated oil companies. This concentration is most visible in Texas, where operators favor vendors with existing distributed control system footprints over standalone LDAR specialists.
Global Leak Detection and Repair (LDAR) Market Segmentation
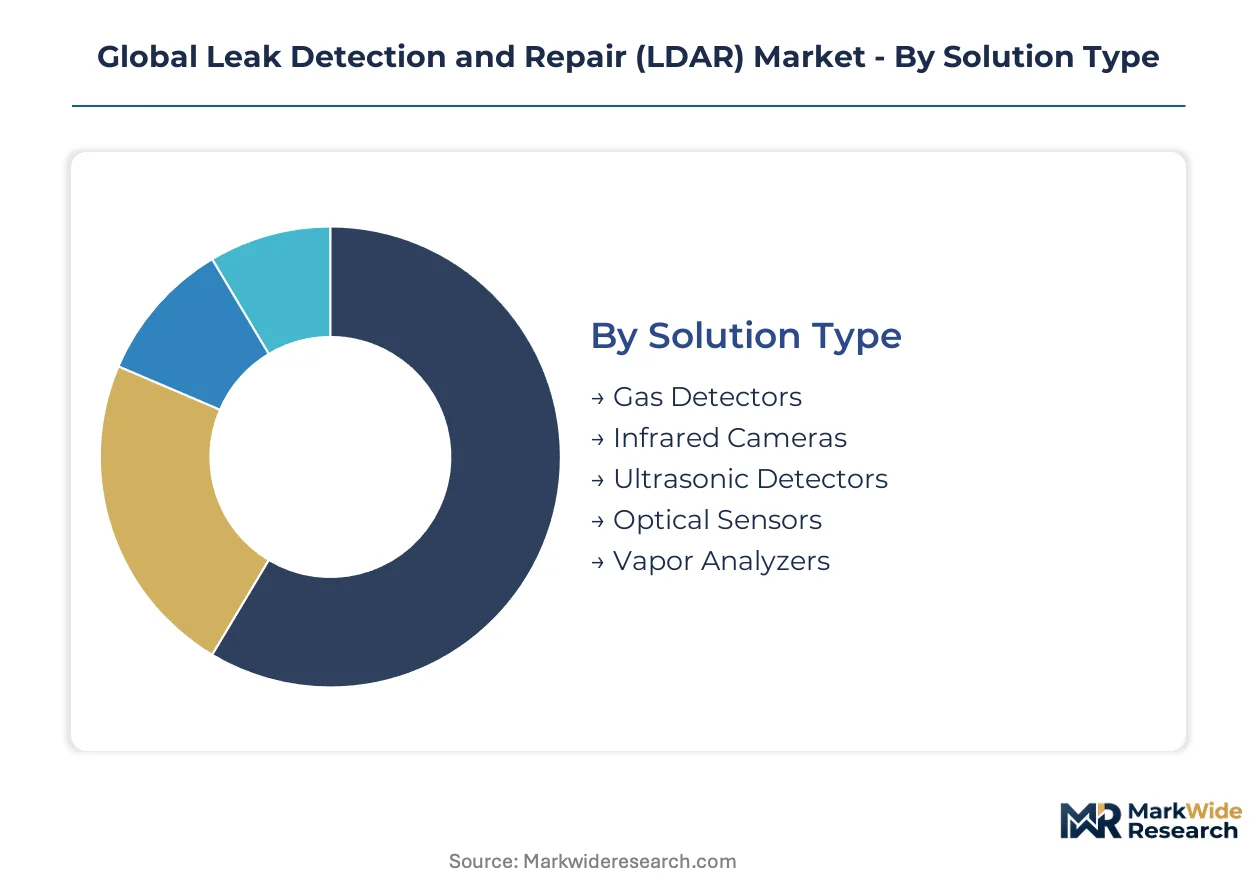
LDAR procurement patterns diverge sharply across technology platforms and operational contexts. Equipment specifications must align with detection threshold mandates, hazardous area classifications, and integration requirements with legacy control systems.
Solution Type:
Portable sniffing technologies face substitution pressure from continuous monitoring architectures as EPA Method 21 precision standards tighten detection thresholds below 500 ppm methane equivalent.
- Infrared Cameras:Optical gas imaging systems visualize hydrocarbon plumes in real time without direct contact, operating at detection thresholds unattainable by legacy methods. Demand concentrates in Texas Permian Basin upstream operations where quarterly compliance windows require rapid survey turnaround. The technology commands premium positioning due to thermographer certification requirements and real-time visualization capabilities.
- Ultrasonic Detectors:Acoustic sensor arrays detect high-pressure gas leaks through sound signature analysis, functioning in hazardous area classifications without hot-work permits. Chemical processing facilities in Louisiana and Texas deploy these for compressor station monitoring where ignition risk prohibits electrical equipment. Detection range degrades above 30 meters per second gas velocity, constraining deployment at high-flow pipeline segments.
- Gas Detectors:Portable catalytic and infrared point detectors remain the compliance baseline for Method 21 walkthrough surveys.
- Optical Sensors:Tunable diode laser absorption spectroscopy enables path-integrated concentration measurements across facility fencelines.
- Vapor Analyzers:Flame ionization and photoionization instruments quantify total organic compound concentrations for benzene monitoring at aromatics complexes.
Infrared cameras retain volume leadership; ultrasonic detectors hold the steepest expansion curve.
Application:
Capital deployment intensity varies by emission profile complexity and regulatory inspection frequency, with benzene-handling operations commanding sensor density multiples above methane-only facilities.
- Petrochemical Plants:Steam crackers and aromatics complexes integrate multi-technology detection architectures for benzene, 1,3-butadiene, and volatile organic compound monitoring. Texas Gulf Coast expansions are accelerating fixed sensor network deployment timelines. China's provincial environmental protection bureaus are mandating LDAR integration into carbon intensity reduction protocols at new ethylene complexes.
- Refining Operations:Fluid catalytic crackers, alkylation units, and storage tank farms require continuous emission monitoring for benzene and fugitive hydrocarbon control. California refineries face the most stringent leak detection frequency mandates under state-level benzene regulations. Capital allocation favors permanent sensor networks over portable survey programs due to component count and accessibility constraints.
- Chemical Processing:Specialty chemical and polymer production facilities deploy vapor analyzers for toxic vapor release prevention.
- Pharmaceutical Manufacturing:Solvent recovery operations and cleanroom environments require low-level volatile organic compound detection for occupational exposure compliance.
- Power Generation:Natural gas turbine facilities and combined cycle plants monitor fuel gas delivery systems for methane leakage.
Refining operations retain volume leadership; petrochemical plants are climbing the fastest.
Installation Environment:
Material specification and certification requirements create cost tier separation, with offshore and subterranean deployments carrying hardware premiums that reshape procurement decision frameworks.
- Onshore Installations:Tank farms, compressor stations, and processing facilities represent the baseline deployment environment with aluminum enclosures and standard explosion-proof certifications. The Permian Basin and Texas Eagle Ford shale regions concentrate demand for rapid-deployment portable systems. Integration with existing distributed control systems drives vendor selection toward automation suppliers with established protocol compatibility.
- Offshore Platforms:Corrosion-resistant stainless steel housings, marine-grade cable glands, and enhanced ingress protection ratings multiply hardware costs substantially. North Sea and Gulf of Mexico operators require redundant detection architectures due to evacuation complexity and ignition consequence severity. Procurement cycles extend through marine certification processes and platform modification engineering.
- Underground Pipelines:Cathodic protection interference and soil moisture ingress constrain sensor selection to specialized probe configurations.
- Storage Facilities:Floating roof tank seal monitoring and vapor recovery unit leak detection demand continuous coverage architectures.
- Distribution Networks:Urban natural gas distribution systems deploy vehicle-mounted survey equipment for mains and service line leak detection.
Onshore installations retain volume leadership; offshore platforms command the steepest pricing tier.
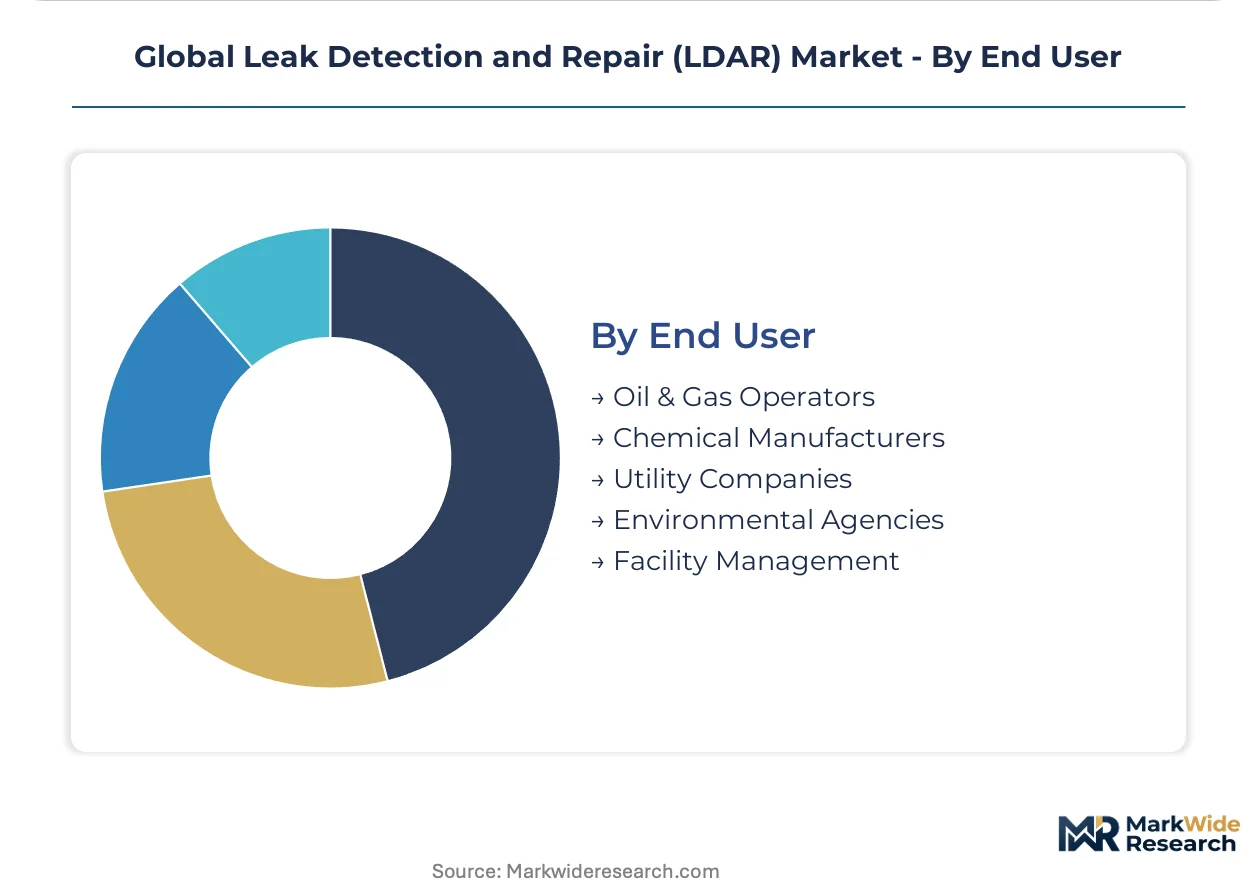
End User:
Procurement sophistication and compliance driver intensity segment the customer base, with integrated oil companies consolidating vendor relationships around single-source automation contracts.
- Oil & Gas Operators:Upstream, midstream, and downstream divisions deploy heterogeneous technology portfolios scaled to component count and regulatory jurisdiction. Majors in the Permian Basin are piloting 24/7 continuous monitoring at compressor stations, collapsing repair initiation windows from quarterly intervals to hours. Procurement is consolidating around vendors with existing distributed control system footprints.
- Chemical Manufacturers:Benzene and toxic vapor monitoring obligations drive sensor density at aromatics complexes and specialty chemical plants. Germany's Industrial Emissions Directive enforcement and REACH obligations create compliance-driven refresh cycles. Belgium-Netherlands refinery cluster operators are retrofitting ammonia detection arrays alongside hydrocarbon sensors.
- Utility Companies:Natural gas distribution utilities deploy mobile leak survey crews for pipeline integrity management.
- Environmental Agencies:Regulatory bodies specify detection methodology and calibration protocols for third-party verification programs.
- Facility Management:Industrial site contractors procure portable detection equipment for turnaround maintenance and construction safety.
Oil and gas operators retain volume leadership; chemical manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in the United States, where pipeline density and environmental scrutiny intersect to drive hardware deployment. Germany and China follow as regulatory enforcement tightens detection thresholds. Brazil and Saudi Arabia round out the geography as energy infrastructure expansion accelerates LDAR adoption.
United States
The Permian Basin and Texas Eagle Ford shale regions concentrate upstream demand for portable optical gas imaging systems. EPA New Source Performance Standards under Clean Air Act Section 111 mandate quarterly monitoring frequency at upstream facilities. Houston anchors midstream procurement for compressor station continuous monitoring pilots that collapse repair windows from months to hours.
Germany
Industrial Emissions Directive enforcement drives retrofit demand at chemical complexes in North Rhine-Westphalia and Bavaria. REACH obligations and F-Gas Regulation phase-down schedules redirect capital toward alternative cooling leak detection at Ludwigshafen and Leverkusen industrial hubs. Specialty gas suppliers in Frankfurt maintain calibration standard concentration for cross-border European operations.
China
Ministry of Ecology and Environment provincial bureaus integrate LDAR into national dual carbon goals at new ethylene complexes. Yangtze River Delta petrochemical expansions in Zhejiang and Jiangsu provinces accelerate fixed sensor network deployment timelines. Shandong Province refineries face intensified benzene monitoring obligations under updated air quality protocols.
Brazil
Pre-salt offshore field development in the Santos Basin commands corrosion-resistant stainless steel sensor housings with marine-grade certifications. Petrobras-led procurement cycles extend through platform modification engineering for redundant detection architectures. Rio de Janeiro state environmental agencies align leak detection protocols with international lender sustainability requirements.
Saudi Arabia
Eastern Province gas processing and NGL fractionation facilities deploy continuous emissions monitoring for methane management under national circular carbon economy targets. Jubail Industrial City aromatics complexes integrate multi-technology detection for benzene and volatile organic compound control. Saudi Aramco procurement favors vendors with existing distributed control system footprints for single-source contracting consolidation.
Global Leak Detection and Repair (LDAR) Market Competitive Landscape
Concentration sits with diversified industrial automation conglomerates that anchor LDAR integration within process control suites. The market structure tiers between integrated automation suppliers with existing distributed control system footprints and standalone detection specialists with point-solution portfolios. Two strategic archetypes dominate: sensor technology originators with infrared and ultrasonic patent estates, and system integrators that bundle hardware with predictive analytics platforms. Competitive moves center on strategic partnerships for cloud analytics integration and geographic expansion through marine certification acquisition for offshore platform access.
Among the diversified automation tier, ABB, Honeywell International, and Emerson Electric exemplify the integrated supplier archetype. ABB leverages its distributed control systems footprint to anchor LDAR within process automation suites. Honeywell International sustains technology positioning through infrared camera portfolios for optical gas imaging. Emerson Electric occupies a position in ultrasonic detector arrays for hazardous area classifications. These three represent the consolidation vector where single-source contracting displaces point-solution purchasing at integrated oil companies.
| Leading Market Players |
|---|
| Aeris Technologies |
| Bridger Photonics |
| Picarro |
| ABB |
| Honeywell International |
| Emerson Electric |
| Schneider Electric |
| Teledyne FLIR |
| Kairos Aerospace |
| Others |
Supply & Pricing Matrix
Specialty gas calibration capacity utilization in Germany and the United States anchors cost floors across detection hardware tiers, concentrating supplier leverage among certified reference standard producers while compressing margins for peripheral component manufacturers.
Pricing Analysis
EPA Method 21 dictates the pricing tier structure across LDAR hardware procurement, separating optical gas imaging systems with thermographer certification requirements from portable catalytic detectors. Three-tier pricing structure across premium, standard, and economy levels reflects detection threshold precision, hazardous area certification grade, and integration complexity with distributed control systems. Cost compression in economy-tier portable sniffers is intensifying because continuous monitoring architectures are displacing quarterly survey programs. Midstream operators in Texas exhibit highest price sensitivity due to component count scale, while offshore platform operators absorb premium corrosion-resistant housing costs with limited negotiation leverage.
Supply Chain Analysis
Just-in-time inventory strategies dominate sensor procurement for onshore installations, whereas offshore platform operators maintain strategic stockpiles of marine-certified spare units due to extended marine certification lead times. Component manufacturing concentrates in the United States, Germany, and China, with infrared detector arrays sourcing mercury cadmium telluride substrates from limited specialty foundries. Calibration gas supply rests on certified methane-in-air reference standards originating from Frankfurt and Houston specialty gas suppliers. Single-source vulnerability in explosion-proof housing castings creates procurement risk for North Sea and Gulf of Mexico deployments. Distribution runs through automation vendor direct sales forces for integrated oil company accounts, with regional distributors serving independent midstream operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LDAR market expansion sits in early-cycle territory as EPA methane regulations force hardware refresh cycles across upstream facilities still operating legacy manual sniffing programs.
For Market Incumbents: Secure thermographer training capacity to collapse deployment backlogs at Texas midstream operators facing quarterly compliance windows. Deepen backward integration into specialty gas calibration standards to defend margin position against supply concentration in Frankfurt and Houston. Cloud analytics platform integration represents the priority lever for displacing standalone LDAR specialists at integrated oil companies. For New Entrants and Emerging Players: Anchor in China's provincial environmental protection bureaus where LDAR integration into dual carbon goals creates first-mover positioning for continuous monitoring vendors. Drone-mounted optical gas imaging for pipeline corridor surveys offers the most penetrable white space, bypassing certified thermographer scarcity constraints. Go-to-market traction requires marine certification acquisition for offshore platform access in Brazil's Santos Basin. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among continuous monitoring system vendors with cloud analytics subscriptions, outperforming transactional hardware sales across the analysis window. Viability over the 5-10 year horizon favors sensor technology originators with patent estates in infrared and ultrasonic detection. Acquisition target archetype: standalone detection specialists with point-solution portfolios facing consolidation pressure from integrated automation suppliers. Signal to watch: EPA transition from prescriptive inspection intervals to continuous monitoring performance standards as inflection indicator for capital deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Analytics Platform Integration | Enables predictive maintenance triggers at Permian Basin compressor stations piloting 24/7 coverage. |
| Marine Certification Acquisition | Unlocks offshore platform procurement cycles in North Sea and Gulf of Mexico markets. |
| Thermographer Training Program Expansion | Addresses certified personnel scarcity extending deployment timelines at Texas midstream operators. |
| Specialty Gas Calibration Backward Integration | Captures margin from concentrated reference standard supply in Germany and United States. |
| Drone-Mounted Sensor Miniaturization | Enables pipeline corridor surveys without ground crew mobilization in remote shale regions. |
Research Methodology
A standing panel of plant engineers at petrochemical complexes, LDAR program managers at integrated oil companies, procurement leads at automation distributors, and regulatory compliance officers at environmental agencies provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA enforcement databases, FERC filings, customs records for detection equipment imports, and SEC 10-K disclosures from industrial automation conglomerates. Bottom-up equipment deployment estimates triangulated against top-down regulatory mandate calculations.
Consistency checks validated volume and value outputs against external benchmarks including EIA methane emission inventories and IEA oil and gas facility counts across the projection horizon. Segmentation modeling incorporated solution type, application, installation environment, and end-user procurement sophistication dimensions. CAGRs were derived from equipment replacement cycle analysis tied to regulatory inspection frequency mandates. Industry-specific forecast inputs included EPA Method 21 precision threshold evolution and provincial carbon intensity protocol adoption timelines in China.
Underlying assumptions cover regulatory enforcement continuity, with deviation risk concentrated in EPA monitoring frequency mandate modifications or China dual carbon goal acceleration. Forecasts reflect these assumptions with sensitivity analysis around continuous monitoring performance standard adoption rates. Revision becomes warranted when prescriptive inspection interval regulations cross thresholds toward performance-based continuous monitoring obligations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market