
 Electrostatic Precipitator Market | 2026-2036
Electrostatic Precipitator Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Precipitator Market Analysis
EPA Mercury and Air Toxics Standards is realigning capital deployment across North American power generation. Babcock & Wilcox leverages its installed base of utility-scale dry systems to sustain aftermarket revenue streams. Mitsubishi Heavy Industries anchors Asian procurement through integrated boiler-ESP packages for ultra-supercritical plants.
An electrostatic precipitator applies high-voltage corona discharge—typically 30–100 kV—to ionize particulate-laden gas streams, collecting charged particles on grounded collection surfaces for removal via rapping or washing systems. Wire-type configurations dominate heavy industrial applications where resistivity conditions favor dry collection, while wet electrostatic precipitators command premium positioning in acid gas and fine particulate environments such as waste incineration and chemical processing. Dry electrostatic precipitators occupy the mature volume tier across coal-fired power and cement kilns, whereas high-efficiency models capture margin concentration where sub-5 mg per normal cubic meter compliance is mandatory.
EPA standards, China's MEE emission benchmarks, and India's CEA technical guidelines collectively mandate particulate thresholds that force retrofit cycles and technology upgrades. The EU Industrial Emissions Directive and REACH compliance frameworks add certification complexity for equipment imports into European cement and steel installations. Stakeholders must weigh dry-to-wet conversion economics against emerging sorbent injection hybrids that promise single-system multipollutant capture.
Market Dynamics
Retrofit cycles across aging coal fleets and cement kilns are compressing replacement windows as particulate emission thresholds tighten simultaneously across US EPA, China's MEE, and India's CEA frameworks. Equipment suppliers face compressed bid cycles and specification complexity that favors integrated system providers over component specialists.
Growth Catalysts
- EPA Mercury and Air Toxics Standards:MATS enforcement is forcing utility-scale dry ESP upgrades across the US Midwest and Southeast coal corridors, sustaining aftermarket parts demand.
- India's cement capacity expansion:PLI-linked incentives are accelerating kiln construction in Rajasthan and Madhya Pradesh, requiring parallel precipitator procurement for clinker production lines.
- Wet ESP technology maturation:Acid gas handling improvements are opening waste-to-energy and chemical processing applications where resistivity conditions defeated dry collection.
Market Restraints
- High-voltage transformer supply concentration:Specialist transformer manufacturing clusters in Germany and Japan create procurement bottlenecks during retrofit peak seasons.
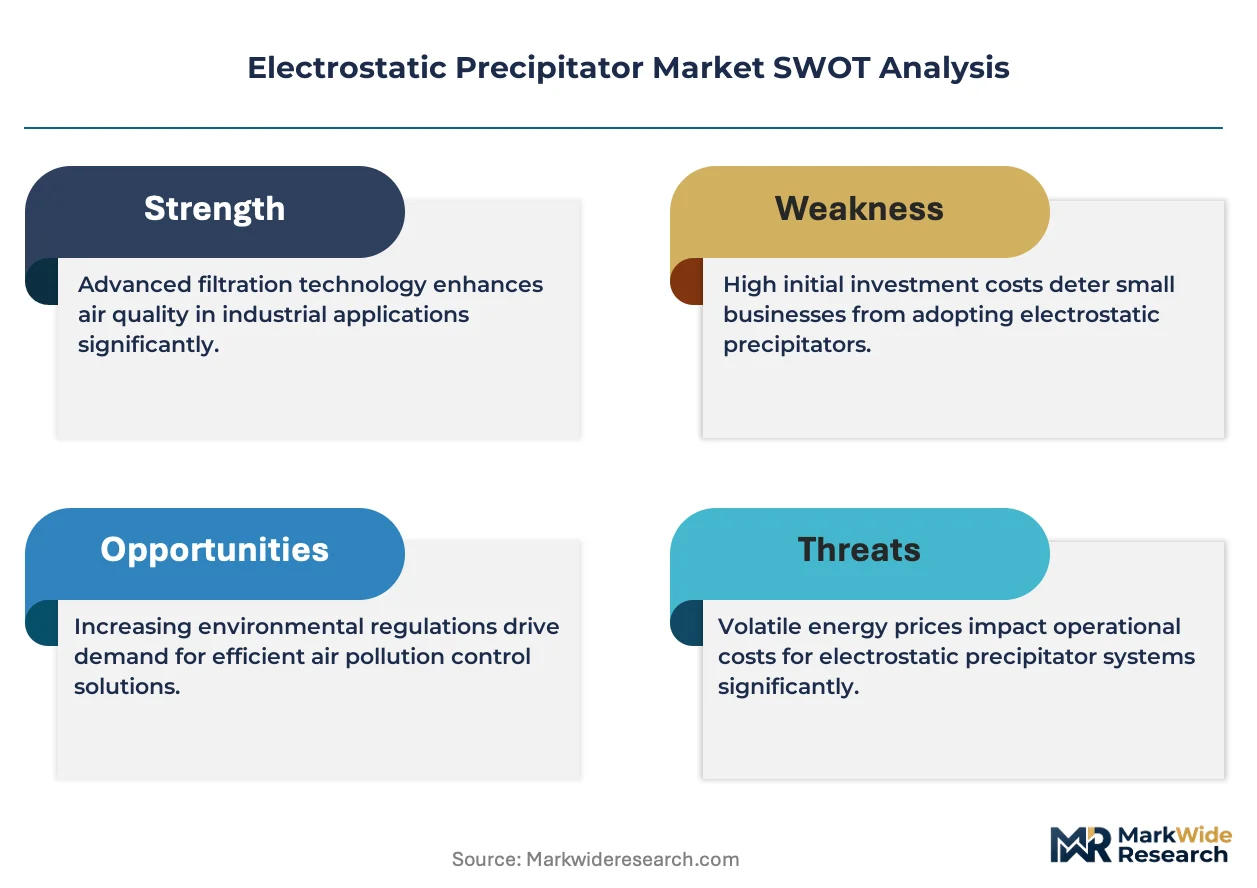
- Construction cost inflation:Steel enclosure fabrication and civil foundation work now represent 35-45% of total installed cost, compressing equipment margins.
- Baghouse substitution in sub-50 MW plants:Pulse-jet fabric filters are capturing biomass and industrial boiler applications where ESP capex cannot be justified.
Strategic Opportunities
- Vietnam's coal-fired power buildout:Vinacomin's generation expansion in Quang Ninh province lacks legacy ESP infrastructure, creating greenfield specification battles.
- Sorbent injection hybridization:Combining dry ESP with activated carbon or lime injection enables single-system multipollutant capture for mercury and SO3 compliance.
- Digital rapping optimization:Vibration frequency algorithms tied to particulate loading sensors are reducing re-entrainment losses in cement kiln applications.
Industry Challenges
- Corona electrode fabrication expertise:Precision wire-to-frame welding and tensioning requires skilled technicians that equipment OEMs struggle to retain.
- Legacy control system integration:1980s-vintage analog voltage controllers in US power plants resist seamless integration with modern SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Precipitator Market |
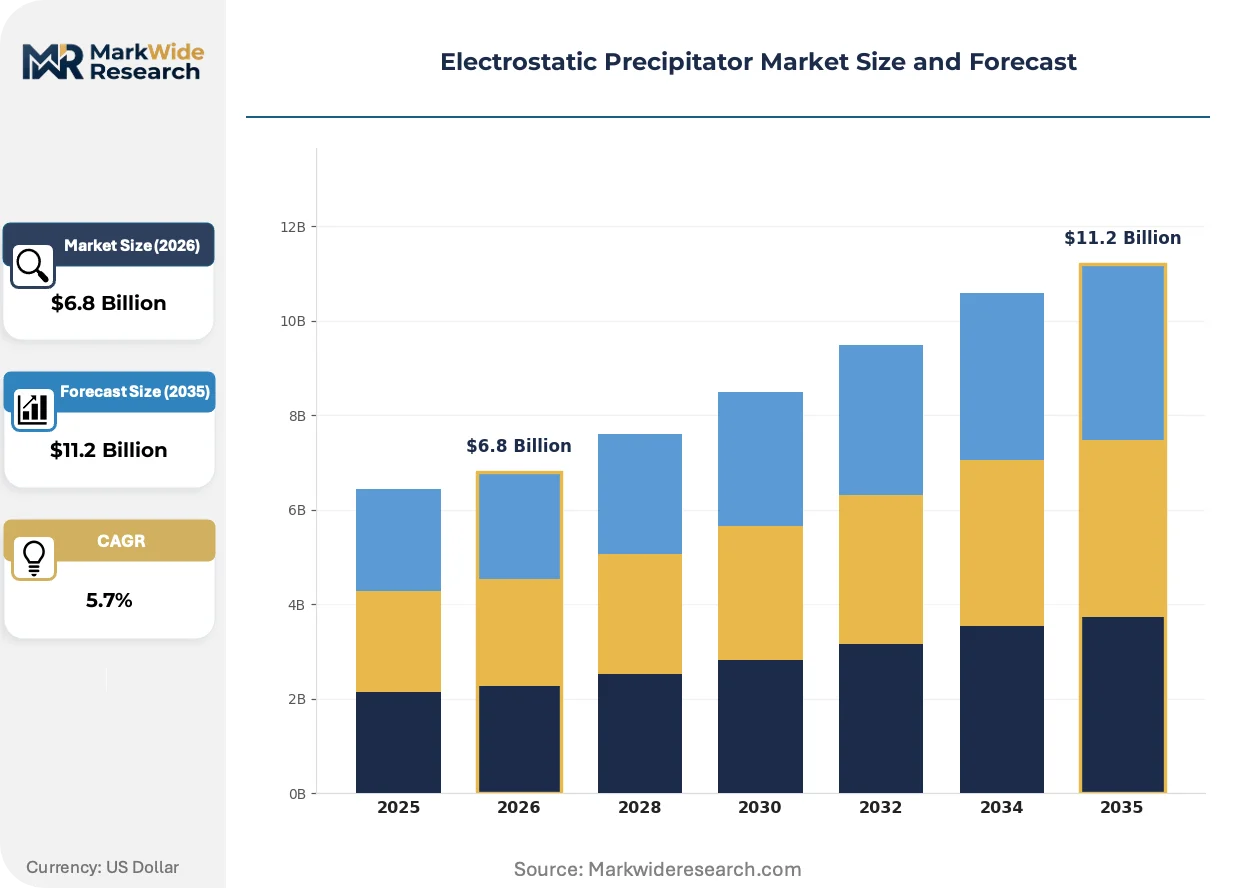
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wire-Type, Plate-Type, Tubular-Type, Hybrid-Type End User: Power Plants, Cement Industry, Steel Manufacturing, Chemical Plants Application: Air Pollution Control, Waste Incineration, Industrial Emission Control, Odor Treatment Product Type: Dry Electrostatic Precipitators, Wet Electrostatic Precipitators, Mobile Units, High-Efficiency Models |
| Companies Covered | ANDRITZ Group, GE, Siemens, Ducon Technologies, Alstom, Mitsubishi Heavy Industries, Thermax Limited, Elex AG, Babcock & Wilcox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Precipitator Market Emerging Trajectories
Equipment architecture is pivoting from standalone particulate capture toward integrated multipollutant platforms. Vendors are embedding sensing and actuation intelligence that enables real-time resistivity compensation and predictive maintenance scheduling.
Pulsed energization systems are absorbing corona power modulation duties that once required mechanical rappers. Cement producers in the US Southeast and Germany's Ruhr district are retrofitting existing dry ESP fields with microprocessor-controlled pulse supplies to handle high-resistivity kiln dust without conditioning agent injection. This voltage waveform innovation is absorbing maintenance budget share from mechanical collection upgrades.
China's MEE is tightening particulate limits for ultra-low emission retrofits in the Yangtze River Delta and Pearl River Delta industrial clusters. Steel mills in Tangshan and power generators in Jiangsu province must achieve sub-5 mg per normal cubic meter opacity, forcing wet ESP adoption where dry systems previously sufficed. Equipment suppliers are responding with compact wet ESP designs that fit existing ductwork footprints.
Aftermarket service contracts are unbundling from original equipment supply across Indian cement and steel procurement. Buyers in Chhattisgarh and Odisha are separating rapping system rebuilds, transformer overhauls, and emission testing into discrete vendor relationships rather than single-source OEM dependencies. This fragmentation is most pronounced among mid-cap cement producers seeking to reduce spare parts inventory carrying costs.
Electrostatic Precipitator Market Segmentation
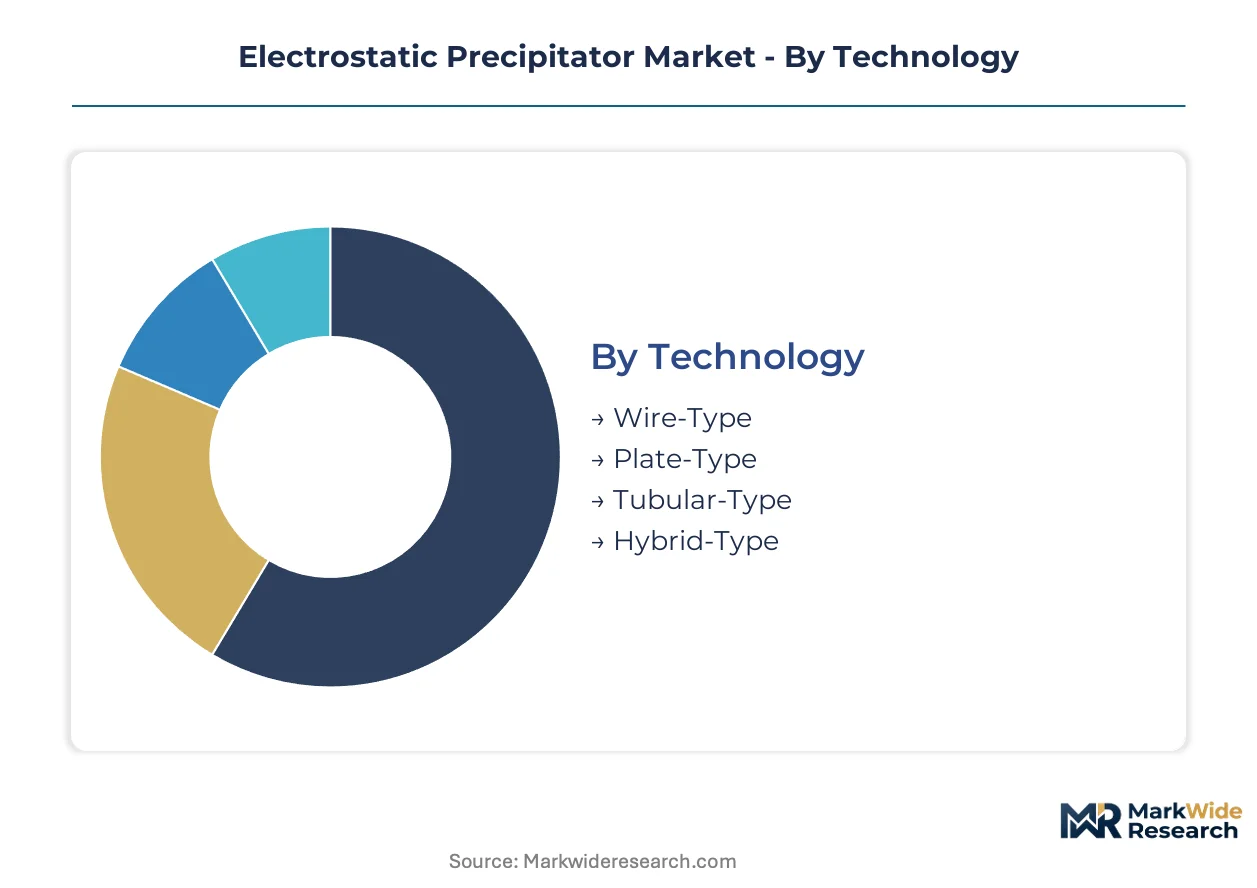
Electrostatic precipitator procurement decisions hinge on resistivity conditions, gas stream chemistry, and emission stringency. Technology selection directly determines capital outlay, operating voltage requirements, and maintenance burden across industrial deployments.
Technology:
Wire-type configurations demand the heaviest upfront investment due to precision electrode fabrication and high-voltage transformer integration.
- Wire-Type:Discharge electrodes suspended between grounded collection plates create corona fields across 30–100 kV potentials. Power plant operators in the US Midwest and Southeast favor these systems for high-volume flue gas handling where particulate resistivity stays within 10^4–10^10 ohm-cm ranges.
- Plate-Type:Flat collection surfaces with distributed discharge electrodes suit space-constrained retrofits. Cement producers in Rajasthan and Madhya Pradesh specify compact plate arrays when existing ductwork limits field extension, though rapping efficiency constraints elevate maintenance frequency.
- Tubular-Type:Cylindrical collection tubes with central discharge wires dominate wet ESP applications for acid gas streams.
- Hybrid-Type:Combined wire-plate geometries optimize collection efficiency across variable loading conditions.
Wire-type systems absorb the bulk of installed capacity; hybrid-type configurations are expanding most quickly as multipollutant capture requirements intensify.
End User:
Customer scale and emission scrutiny create divergent specification patterns across heavy industry verticals.
- Power Plants:Utility-scale coal and gas-fired generators require field-proven dry ESP architectures with 99.9% particulate capture efficiency. EPA Mercury and Air Toxics Standards enforcement across Ohio, Indiana, and Kentucky coal corridors sustains retrofit demand for transformer upgrades and rapping system modernization.
- Cement Industry:Clinker kiln exhaust carries high-resistivity dust demanding conditioning agents or pulse energization. India's PLI-linked capacity expansion in Chhattisgarh and Odisha drives precipitator procurement for new production lines, though procurement fragmentation favors discrete service contracts over bundled OEM supply.
- Steel Manufacturing:Sinter plant and electric arc furnace off-gases contain metallic particulates with challenging resistivity profiles.
- Chemical Plants:Process vent streams with corrosive constituents require alloy-wetted surfaces and specialized gas distribution design.
Power plants anchor historical installation base; cement industry procurement is climbing the fastest under capacity expansion programs.
Application:
Regulatory threshold stringency varies sharply across emission control contexts, reshaping technology deployment.
- Air Pollution Control:General industrial particulate capture spans coal combustion, mineral processing, and metallurgical operations where China's MEE ultra-low emission benchmarks now mandate sub-5 mg per normal cubic meter opacity in Yangtze River Delta clusters.
- Waste Incineration:Municipal and medical waste combustion generates acid gases and fine particulates that defeat dry collection. Wet ESP adoption is accelerating in European waste-to-energy plants under EU Industrial Emissions Directive compliance deadlines.
- Industrial Emission Control:Cross-cutting manufacturing vent streams with moderate particulate loading.
- Odor Treatment:Nuisance emission abatement for food processing and rendering facilities.
Air pollution control retains dominant deployment share; waste incineration applications are gaining share fastest as circular economy infrastructure expands.
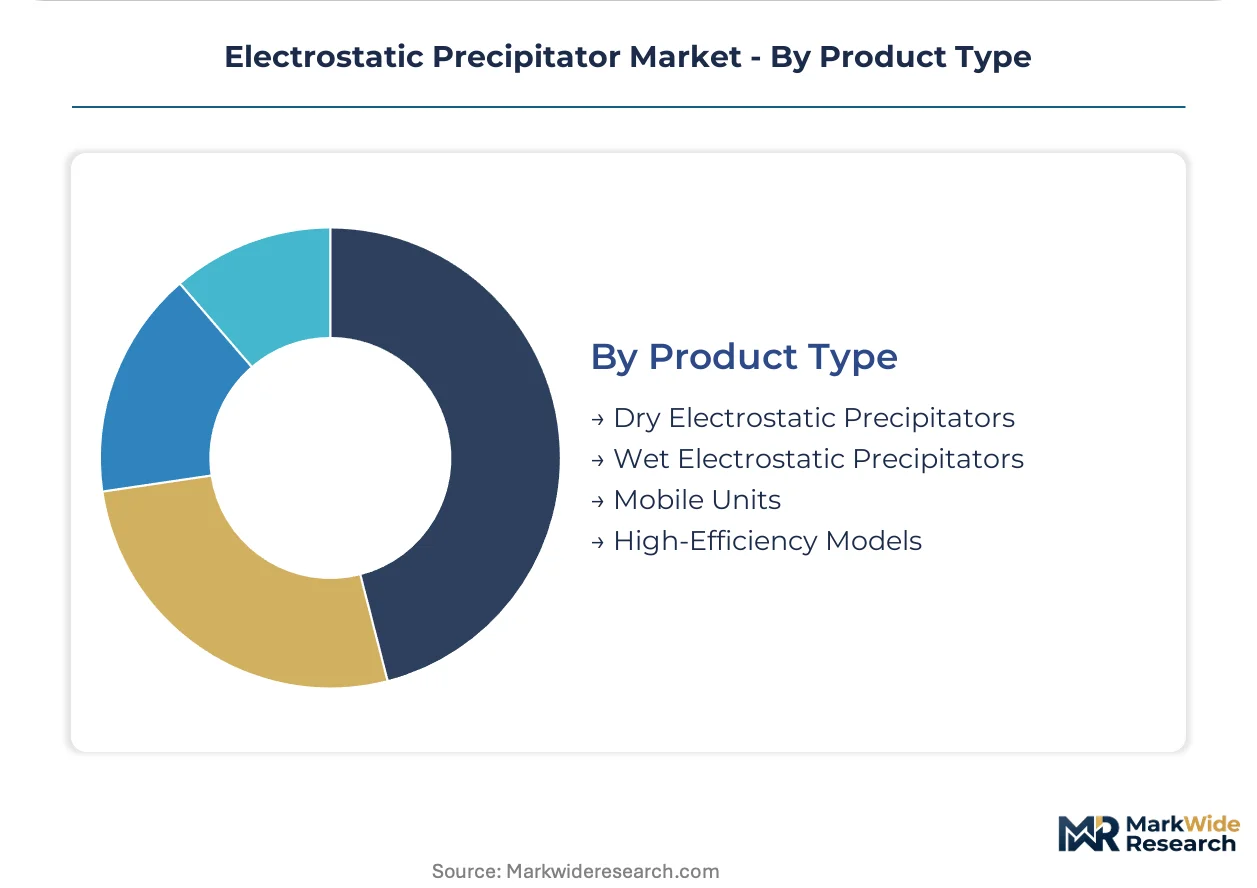
Product Type:
Moisture tolerance and efficiency tier define capital allocation and operating cost structures.
- Dry Electrostatic Precipitators:Mature volume tier across coal-fired power and cement kilns where gas streams remain above dew point. Dry systems dominate Tangshan steel mill and Jiangsu power generator retrofits, though China's tightening MEE limits are forcing wet ESP substitution in some legacy installations.
- Wet Electrostatic Precipitators:Premium positioning for acid gas and sub-micron particulate environments. Compact wet designs are penetrating waste-to-energy and chemical processing sectors where resistivity conditions previously excluded electrostatic collection entirely.
- Mobile Units:Temporary emission control for construction, demolition, and emergency industrial maintenance.
- High-Efficiency Models:Multi-field architectures with optimized gas distribution and advanced rapping.
Dry electrostatic precipitators hold the largest installed base; wet electrostatic precipitators are expanding most quickly as fine particulate standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI-linked industrial corridors and China's MEE ultra-low emission zones concentrate retrofit demand across Asia-Pacific cement and steel clusters. Germany's Ruhr district and the US Midwest coal corridors anchor European and North American procurement volumes respectively.
United States
EPA Mercury and Air Toxics Standards enforcement compresses replacement windows across Ohio, Indiana, and Kentucky coal fleets. Utility operators in these states prioritize transformer upgrades and rapping system modernization over full greenfield installations. The Southeast cement corridor spanning Alabama and Georgia drives pulse energization retrofits for high-resistivity kiln dust handling.
China
MEE ultra-low emission benchmarks mandate sub-5 mg per normal cubic meter opacity in Yangtze River Delta and Pearl River Delta industrial clusters. Steel mills in Tangshan and power generators in Jiangsu province accelerate wet ESP adoption where dry systems previously sufficed. Compact wet designs penetrate existing ductwork footprints to avoid civil reconstruction costs.
India
PLI-linked incentives accelerate cement kiln construction in Rajasthan and Madhya Pradesh under the Ministry of Heavy Industries scheme. Chhattisgarh and Odisha steel corridors drive precipitator procurement for sinter plant and electric arc furnace off-gas handling. Procurement fragmentation favors discrete service contracts over bundled OEM supply among mid-cap cement producers.
Germany
EU Industrial Emissions Directive compliance deadlines tighten particulate thresholds across Ruhr district cement and chemical processing installations. REACH certification complexity elevates specification barriers for equipment imports into European steel and cement facilities. Pulsed energization retrofits absorb maintenance budget share from mechanical collection upgrades in legacy dry ESP fields.
Vietnam
Vinacomin's generation expansion in Quang Ninh province lacks legacy ESP infrastructure, creating greenfield specification battles among integrated system providers. The country's coal-fired power buildout attracts boiler-ESP package vendors seeking anchor positions in Southeast Asian procurement. Equipment suppliers face compressed bid cycles as emission standards converge toward Chinese MEE benchmarks.
Electrostatic Precipitator Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement cycles that favor integrated system providers over component fabricators. The vendor base spans heavy industrial engineering groups, power generation equipment specialists, and regional emission control contractors. Two strategic archetypes dominate: full-stack boiler-ESP integrators leveraging captive boiler relationships, and aftermarket service specialists unbundling maintenance contracts from original equipment supply. Competitive moves concentrate on geographic expansion into Vietnam's greenfield coal corridor and technology licensing for sorbent injection hybridization.
Among diversified industrial engineering groups, Mitsubishi Heavy Industries anchors Asian procurement through integrated boiler-ESP packages for ultra-supercritical plants. Babcock & Wilcox occupies a position within the North American aftermarket tier, leveraging installed base relationships across utility-scale dry systems. Thermax Limited represents the India-focused specialist archetype, capturing cement and steel corridor demand under PLI-linked capacity expansion programs.
| Leading Market Players |
|---|
| ANDRITZ Group |
| GE |
| Siemens |
| Ducon Technologies |
| Alstom |
| Mitsubishi Heavy Industries |
| Thermax Limited |
| Elex AG |
| Babcock & Wilcox |
| Others |
Supply Flow & Price Mechanics
China's MEE ultra-low emission benchmarks gate qualified supply access and premium-tier pricing power for wet ESP configurations serving Yangtze River Delta steel mills. Equipment vendors meeting sub-5 mg per normal cubic meter certification thresholds command pricing premiums while excluded fabricators compete on margin-thin dry system retrofits.
Pricing Analysis
Lead-time compression drives sharp pricing differentiation between spot inventory and engineered-to-order systems. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and after-sales bundling intensity. Cost compression in economy-tier dry ESPs is intensifying because steel enclosure fabrication now absorbs 35-45% of installed cost. Mid-cap cement producers in Chhattisgarh exhibit highest price sensitivity, while ultra-supercritical power generators in Jiangsu province prioritize performance guarantees over capital outlay.
Supply Chain Analysis
REACH certification and EU Industrial Emissions Directive compliance documentation gate European market access for Asian fabricators. High-voltage transformer manufacturing concentrates in Germany and Japan, drawing from specialty steel and precision winding inputs. Single-source vulnerability in corona electrode wire supply creates procurement bottlenecks during peak retrofit seasons. Distribution runs through EPC contractors and boiler OEM package integrators rather than direct end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as equipment vendors pursue captive control over high-voltage transformer supply to defend margin structure against steel cost inflation.
For Market Incumbents: Lock in aftermarket service contracts across India's PLI-linked cement corridors before procurement fragmentation accelerates. Secure backward integration into precision wire-to-frame welding capacity to offset technician retention challenges. Pulse-jet fabric filter substitution in sub-50 MW biomass plants threatens ESP incumbents in the economy tier. For New Entrants and Emerging Players: Enter via Vietnam's greenfield coal corridor where Vinacomin's Quang Ninh expansion lacks legacy ESP infrastructure and specification battles remain open. Target wet ESP retrofits in European waste-to-energy plants facing EU Industrial Emissions Directive deadlines. Partner with regional EPC contractors lacking in-house emission control engineering. For Investors and Strategic Acquirers: Sorbent injection hybridization patent filings accelerating is the leading indicator that multipollutant capture platforms will consolidate technology licensing value over the next decade. Acquisition targets should display captive transformer manufacturing or digital rapping optimization IP. Watch for MEE benchmark tightening announcements in new Chinese industrial clusters as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transformer Manufacturing | German and Japanese transformer clusters create margin vulnerability for pure-play ESP vendors without captive supply. |
| Digital Rapping Optimization Licensing | Cement producers in Alabama and Germany's Ruhr district absorb maintenance budget share through microprocessor-controlled pulse supplies. |
| Wet ESP Compact Design Development | Tangshan steel mills and Jiangsu power generators retrofit existing ductwork footprints to avoid civil reconstruction costs. |
| Aftermarket Service Contract Unbundling | Mid-cap cement producers in Odisha reduce spare parts inventory carrying costs through discrete vendor relationships. |
| Sorbent Injection Hybridization | Single-system mercury and SO3 capture enables premium positioning against standalone particulate collectors in MATS compliance corridors. |
Methodological Framework
EPA enforcement databases, China's MEE emission disclosure filings, and Indian CEA technical guideline releases formed the secondary backbone for regulatory trajectory mapping. Primary interviews with plant maintenance directors, OEM procurement teams, EPC contract engineers, and aftermarket service heads validated equipment specification trends and procurement fragmentation patterns. Bottom-up and top-down triangulation reconciled field-level retrofit cycle data with national capacity expansion announcements.
Bottom-up modeling aggregated individual project pipelines across coal fleet retrofits, cement kiln construction, and steel sinter plant upgrades. Segmentation dimensions included technology type, end-user vertical, application stringency tier, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and greenfield procurement schedules. Forecast inputs incorporated transformer lead-time fluctuations and steel price index movements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden MEE benchmark acceleration or trade restriction escalation affecting German transformer exports. A model refresh is warranted upon material change in EPA MATS enforcement intensity or India's PLI scheme expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market