
 Emission Control Technology Market | 2026-2036
Emission Control Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Control Technology Market Analysis
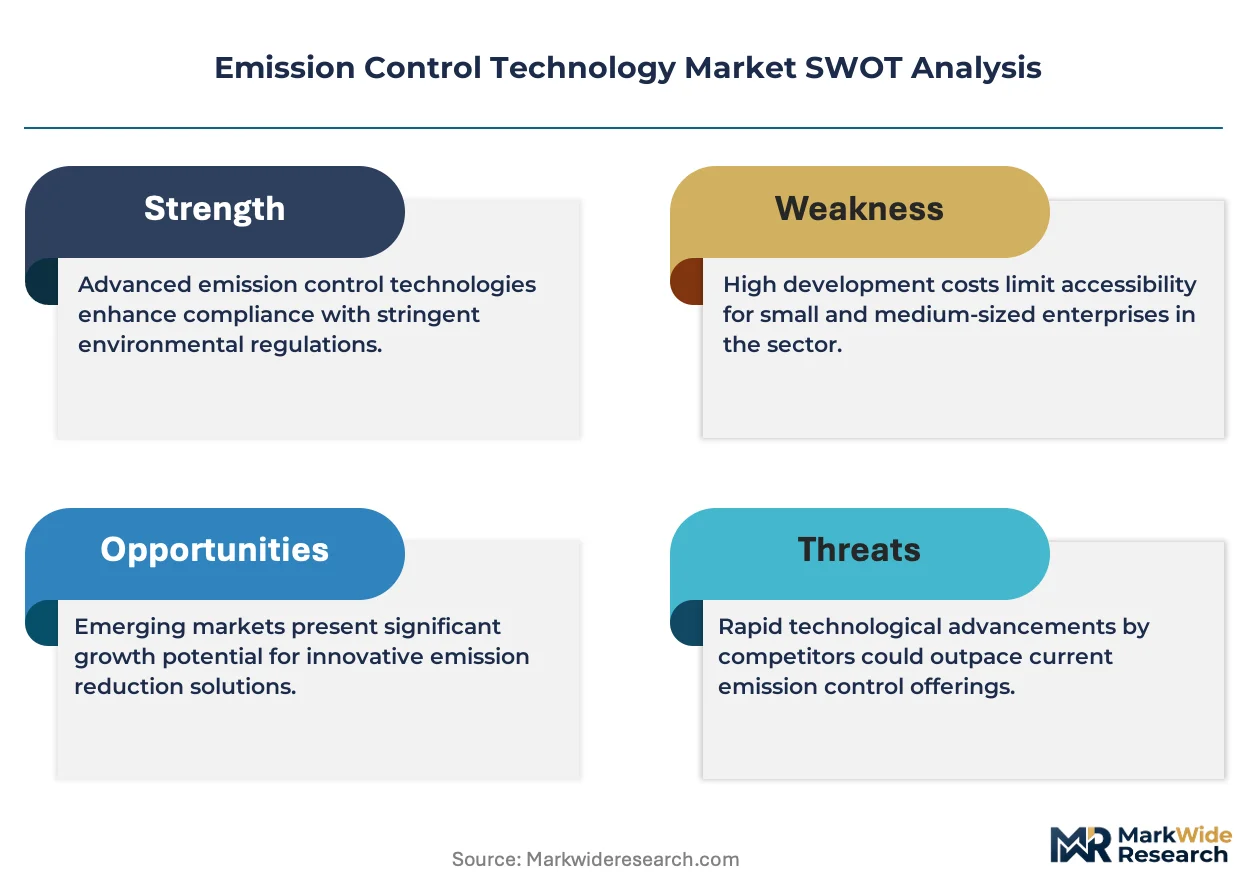
The EU Green Deal's 2030 climate target is repositioning automotive supplier priorities across the European value chain. Johnson Matthey leverages its platinum group metal refining capabilities to sustain catalyst supply security for European OEMs. BASF anchors its competitive stance through backward integration into zeolite manufacturing for selective catalytic reduction substrates. Tenneco competes aggressively in the aftermarket channel, controlling distribution networks across North American exhaust repair shops.
Emission control technology encompasses catalytic and non-catalytic systems engineered to chemically convert or physically capture pollutants including nitrogen oxides, particulate matter, hydrocarbons, and carbon monoxide from combustion exhaust streams. Selective catalytic reduction units operate at temperatures between 250°C and 450°C, injecting aqueous urea to reduce NOx into nitrogen and water vapor for heavy-duty diesel compliance. Diesel particulate filters represent the most mature product category with established regeneration protocols, while catalytic enhancement technologies command premium positioning due to precious metal loading requirements and tighter performance tolerances. Exhaust gas recirculation systems serve as baseline architecture across light-duty gasoline platforms, competing primarily on thermal management efficiency and valve durability.
The US EPA Tier 4 standards and California Air Resources Board mandates compel engine manufacturers to integrate multi-stage aftertreatment, directly expanding addressable hardware demand. China's MEE enforces GB VI emission limits that mirror Euro 6 technical parameters, forcing domestic truck producers to source foreign catalyst formulations or license patented coating technologies. Japan's METI coordinates JIS standard harmonization with UN ECE regulations, smoothing certification pathways for suppliers serving multiple export markets. Stakeholders must monitor regulatory divergence between US federal and state-level standards, as fragmented compliance obligations multiply product variant complexity and inventory carrying costs.
Market Dynamics
Platinum group metal supply concentration is forcing emission control catalyst manufacturers to reconfigure sourcing strategies and accelerate material substitution programs across the value chain.
Growth Catalysts
- EU Green Deal enforcement:The 2030 climate target mandates compel European automotive OEMs to accelerate selective catalytic retrofits across heavy-duty fleets, expanding hardware demand for urea injection systems and zeolite substrates.
- China MIIT dual carbon goals:Enforcement concentrates procurement for diesel particulate filters in Shanghai's port logistics corridor, where container truck operators face non-compliance penalties and accelerated fleet turnover deadlines.
- Industrial retrofit wave:German power generation and steel producers are installing selective catalytic reduction systems to meet Bundesimmissionsschutzverordnung limits, creating sustained aftermarket demand for catalyst replacement cycles.
Market Restraints
- Palladium-rhodium price volatility:Precious metal input costs swing unpredictably based on South African and Russian supply disruptions, compressing margin predictability for catalyst coaters locked into long-term automotive supply contracts.
- Zeolite substrate concentration:Three chemical conglomerates control over 70% of high-silica zeolite manufacturing capacity, creating supply security vulnerabilities for selective catalytic reduction system assemblers dependent on just-in-time delivery.
- Hydrogen combustion uncertainty:Fuel cell and hydrogen internal combustion engine development threatens long-term demand for conventional three-way catalyst architectures in light-duty applications beyond the forecast window.
Strategic Opportunities
- India BS-VI Phase II compliance gap:Domestic commercial vehicle producers lag foreign competitors in catalyst formulation expertise, creating licensing and joint-venture openings for technology holders with proven heavy-duty diesel aftertreatment platforms.
- Marine scrubber-catalyst convergence:International Maritime Organization 2020 sulfur limits are pushing ship operators toward integrated exhaust cleaning systems that combine wet scrubbers with selective catalytic reduction, opening a new equipment category.
- US IRA clean manufacturing credits:Domestic content incentives for emission control component production are reshaping investment location decisions, favoring North American catalyst coating and canning facilities over Asian import dependency.
Industry Challenges
- Catalyst calibration complexity:Each engine platform requires bespoke precious metal loading profiles and substrate geometries, multiplying engineering validation cycles and straining technical workforce capacity at coating facilities.
- Multi-jurisdiction certification timelines:Simultaneous US EPA, CARB, and UN ECE homologation processes extend product launch schedules by 18-24 months, delaying revenue recognition and complicating inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Control Technology Market |
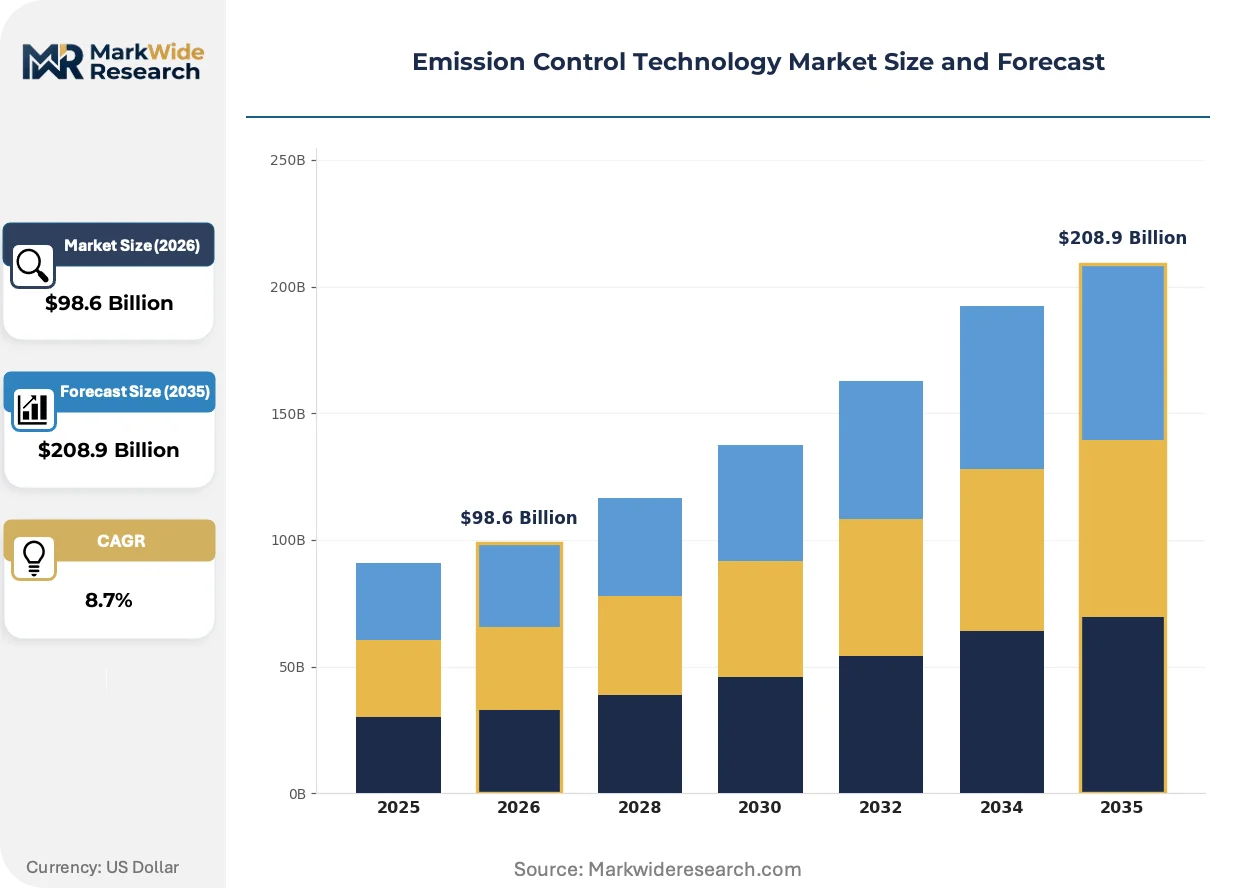
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidation Catalysts, Selective Catalytic Reduction, Diesel Particulate Filters, Exhaust Gas Recirculation Technology: Active Regeneration, Passive Regeneration, Non-Catalytic Reduction, Catalytic Enhancement End Use: Automotive, Industrial, Marine, Power Generation Installation Type: OEM, Aftermarket, Retrofit, Modular Solutions |
| Companies Covered | Johnson Matthey, Umicore, BASF, Tenneco, Cataler, Cormetech, Honeywell, Cummins, GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Control Technology Market Emerging Trajectories
Ceramic matrix catalyst architectures are absorbing development resources as manufacturers pursue thermal durability beyond 900°C for next-generation gasoline particulate filter integration.
Copper-exchanged zeolite formulations are absorbing research priority from iron-based alternatives due to superior NOx conversion efficiency at low exhaust temperatures. Light-duty diesel producers in Germany and South Korea are accelerating adoption for Euro 6d and equivalent domestic compliance. This transition is absorbing coating capacity at specialized substrate facilities and compressing lead times for iron-zeolite legacy formulations.
The US EPA's proposed Good Neighbor Plan tightening ozone transport requirements is compelling stationary source operators in 23 states to install selective catalytic reduction ahead of original compliance schedules. Industrial boiler and cement kiln segments face compressed installation windows. Catalyst suppliers are responding by pre-positioning modular skid systems in Ohio River Valley manufacturing clusters.
Aftermarket channel consolidation is compressing distributor margins as national exhaust repair chains centralize procurement through direct manufacturer relationships. Independent repair shops in the US Midwest and Canadian Prairie provinces are losing price leverage. This pattern is most visible in heavy-duty truck service networks where telematics-enabled predictive maintenance is bundling catalyst replacement with scheduled downtime windows.
Emission Control Technology Market Segmentation
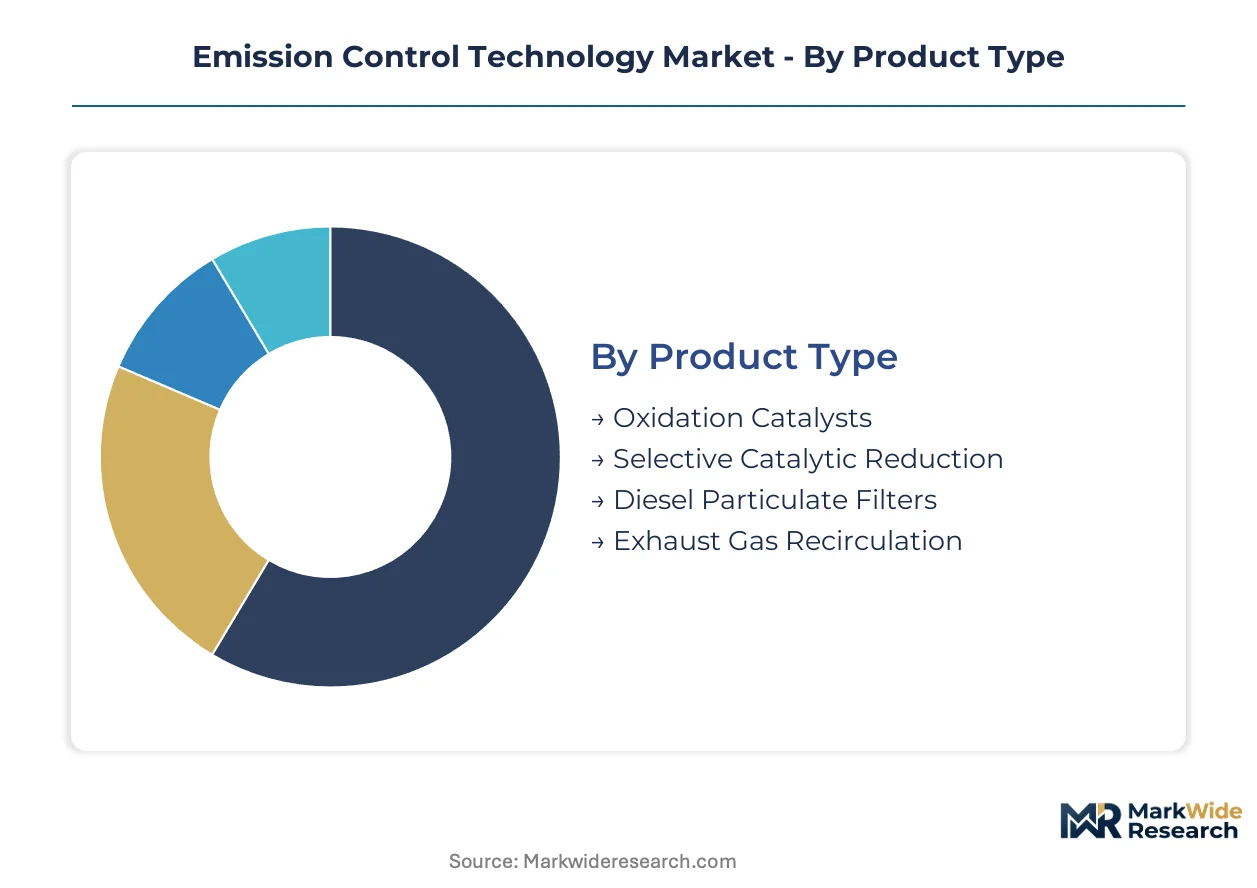
Segmentation in emission control technology reflects divergent procurement priorities across regulatory jurisdictions and end-use applications. Buyers prioritize thermal durability, precious metal loading efficiency, or regeneration protocol compatibility based on fleet composition and compliance deadlines.
Product Type:
Procurement teams differentiate primarily by exhaust temperature range and pollutant target, with heavy-duty diesel operators prioritizing NOx reduction while gasoline platforms favor particulate capture.
- Selective Catalytic Reduction:Aqueous urea injection systems reduce nitrogen oxides to nitrogen and water vapor across 250°C to 450°C operating windows. German power generators and Shanghai port logistics operators are concentrating procurement for Euro 6 and China VI compliance, with zeolite substrate supply security emerging as a critical constraint.
- Diesel Particulate Filters:Ceramic wall-flow substrates physically trap soot particles with established active and passive regeneration protocols. Aftermarket demand concentrates in North American heavy-duty truck service networks where telematics-enabled predictive maintenance bundles replacement with scheduled downtime.
- Oxidation Catalysts:Platinum and palladium coatings convert carbon monoxide and hydrocarbons to carbon dioxide and water across gasoline and diesel applications.
- Exhaust Gas Recirculation:Valve-controlled exhaust stream recirculation reduces combustion temperatures and NOx formation in light-duty gasoline architectures.
Diesel particulate filters lead volumes today; selective catalytic reduction is gaining share fastest.
Technology:
Technology selection tracks fuel sulfur content, duty cycle predictability, and the trade-off between hardware complexity and operating cost burden.
- Active Regeneration:Fuel injection or electric heating initiates soot oxidation when filter loading exceeds thresholds, enabling operation across variable-duty cycles. US EPA Tier 4 and California Air Resources Board mandates for non-road equipment are accelerating hardware demand where passive thermal conditions prove insufficient.
- Catalytic Enhancement:Precious metal coatings lower regeneration initiation temperatures and improve conversion efficiency at low exhaust temperatures. Premium positioning reflects platinum group metal loading requirements and tighter coating tolerance specifications.
- Passive Regeneration:Continuous soot oxidation occurs when exhaust temperatures sustain thermal conditions without supplemental energy input.
- Non-Catalytic Reduction:Thermal or selective non-catalytic processes reduce NOx through controlled ammonia injection without substrate coatings.
Passive regeneration leads volumes today; catalytic enhancement is climbing the fastest.
End Use:
End-use segmentation reveals divergent compliance timelines, with automotive facing the most accelerated retrofit deadlines and marine operators confronting sulfur cap enforcement.
- Automotive:Light-duty gasoline and heavy-duty diesel platforms drive catalyst volume, with Euro 6d and equivalent domestic standards in Germany and South Korea accelerating copper-zeolite adoption. OEM procurement locks in multi-year supply agreements while aftermarket channels consolidate through direct manufacturer relationships.
- Marine:International Maritime Organization sulfur limits are pushing ship operators toward integrated exhaust cleaning systems combining wet scrubbers with selective catalytic reduction, opening a new equipment category with extended service intervals.
- Industrial:Cement kilns, steel mills, and power boilers install selective catalytic reduction to meet stationary source emission limits.
- Power Generation:Gas turbine and reciprocating engine operators deploy oxidation catalysts and selective catalytic reduction for grid-scale and distributed generation compliance.
Automotive leads volumes today; marine is expanding most quickly.
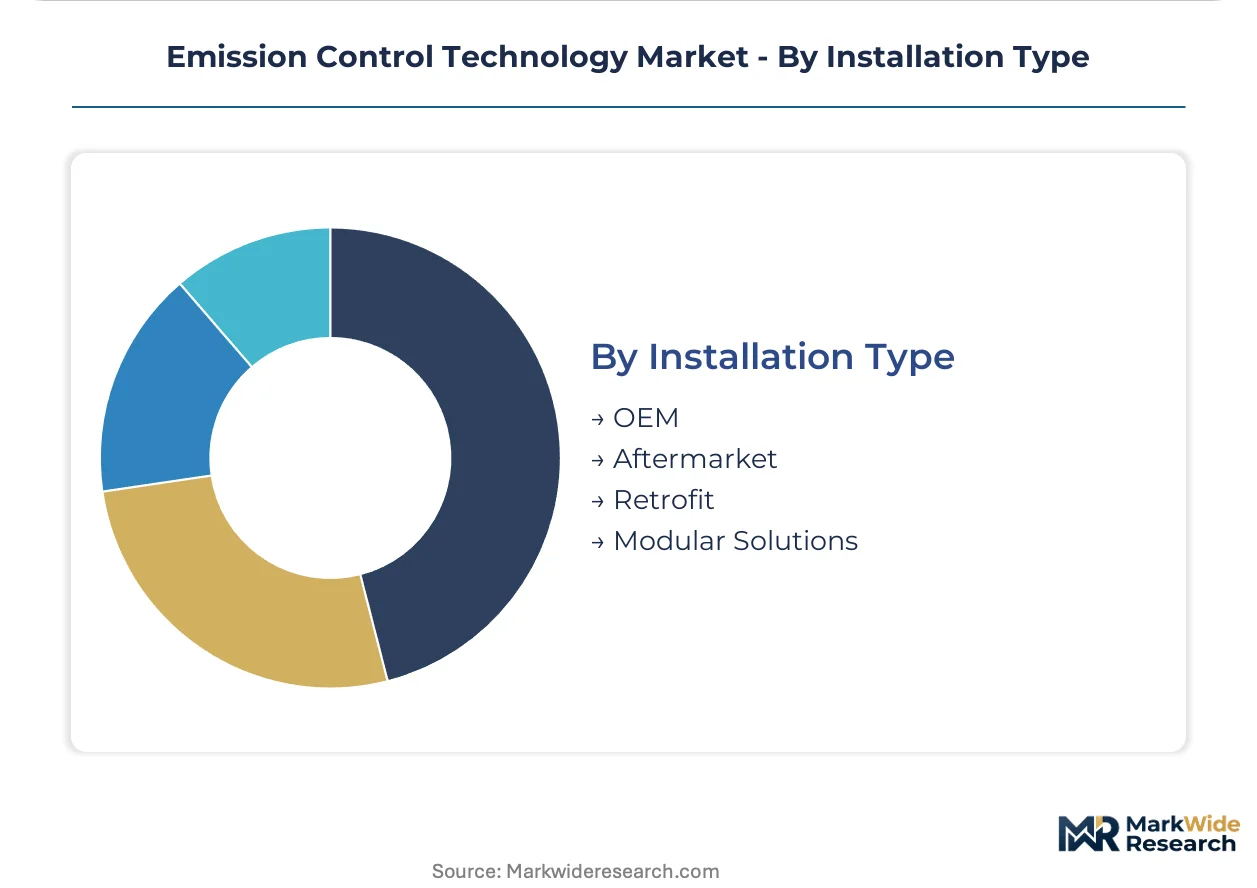
Installation Type:
Installation segmentation tracks asset ownership structure, with fleet operators favoring OEM integration and independent owners prioritizing aftermarket flexibility.
- OEM:Factory-integrated systems enable optimized thermal management and calibration during powertrain development, locking in catalyst specifications through platform lifecycle. Johnson Matthey and BASF compete for multi-year supply agreements with European and Asian automotive manufacturers.
- Retrofit:Post-manufacture installation addresses compliance gaps in in-service fleets, with German steel producers and power generators installing selective catalytic reduction ahead of Bundesimmissionsschutzverordnung deadlines.
- Aftermarket:Replacement catalysts and filters serve independent repair shops and national exhaust chains, with distribution consolidation compressing distributor margins.
- Modular Solutions:Pre-engineered skid systems enable compressed installation windows for stationary source operators facing accelerated compliance schedules.
OEM leads volumes today; retrofit is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emission control technology first achieved industrial scale in Germany's Ruhr Valley during the 1980s, where steel producers deployed selective catalytic reduction to meet early Bundesimmissionsschutzverordnung limits. This German foundation established the technical templates now replicated across automotive and stationary source applications worldwide.
United States
Heavy-duty truck fleet operators and power utilities drive hardware procurement. EPA Tier 4 standards and the proposed Good Neighbor Plan ozone transport rules compel multi-stage aftertreatment adoption. Catalyst suppliers pre-position modular skid systems in Ohio River Valley manufacturing clusters ahead of compressed compliance windows.
Germany
Automotive OEMs and industrial retrofit operators concentrate demand. EU Green Deal 2030 mandates accelerate selective catalytic retrofits across heavy-duty fleets. BASF anchors zeolite substrate supply from Ludwigshafen, while Johnson Matthey refines platinum group metals for European catalyst coaters.
China
Shanghai port logistics operators and domestic truck producers dominate procurement volume. MIIT enforcement of dual carbon goals concentrates diesel particulate filter demand in container transport corridors. MEE's GB VI emission limits mirror Euro 6 technical parameters, forcing technology licensing from foreign formulation holders.
Japan
Light-duty gasoline platform developers and export-oriented suppliers shape regional demand. METI coordinates JIS standard harmonization with UN ECE regulations, smoothing certification pathways for multi-market suppliers. Copper-zeolite research absorbs coating capacity at specialized substrate facilities serving South Korean and European automakers.
India
Commercial vehicle producers and aftermarket retrofit operators present compliance gaps. BS-VI Phase II enforcement lags foreign competitors in catalyst formulation expertise. Domestic truck manufacturers in Maharashtra and Gujarat seek joint-venture openings with proven heavy-duty diesel aftertreatment technology holders.
Emission Control Technology Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the emission control value chain. Precious metal refiners and zeolite substrate manufacturers anchor the upstream, while system integrators and coating specialists occupy midstream positions. Three strategic archetypes dominate: integrated chemical conglomerates with captive material supply, specialized catalyst coaters focused on formulation IP, and diversified automotive suppliers leveraging exhaust system integration. Competitive moves concentrate on backward integration into zeolite manufacturing and strategic partnerships to secure platinum group metal offtake.
Among UK-based material specialists, Johnson Matthey occupies a position exemplifying precious metal refining and catalyst formulation integration. German chemical conglomerate BASF represents the archetype of backward integration into zeolite substrate manufacturing. US automotive supplier Tenneco sits within the diversified tier, anchoring aftermarket distribution network control.
| Leading Market Players |
|---|
| Johnson Matthey |
| Umicore |
| BASF |
| Tenneco |
| Cataler |
| Cormetech |
| Honeywell |
| Cummins |
| GEA Group Aktiengesellschaft |
| Others |
Supply Flow & Price Mechanics
Ceramic substrate coating specialists concentrated in Germany's Rhineland-Palatinate region command wage premiums that compress pricing spreads between premium and standard catalyst tiers. Labor-cost differentials between Western European coating facilities and emerging Asian substrate producers widen the gap between precious metal-loaded premium formulations and economy-grade iron-zeolite alternatives.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between automotive OEMs and catalyst coaters, with pricing stratifying across premium, standard, and economy tiers based on precious metal loading intensity and certification grade. Price differentiation hinges on platinum group metal content and Euro 6d versus Euro 6b compliance certification. Cost compression in the standard tier intensifies as Chinese substrate producers expand coating capacity and compress lead times. Fleet operators in North American heavy-duty trucking exhibit the highest price sensitivity, while German automotive OEMs prioritize supply security over unit cost.
Supply Chain Analysis
US IRA domestic content incentives are reshaping sourcing patterns for catalyst coaters previously dependent on Asian import channels. Geographic supply concentration centers on South Africa and Russia for platinum group metal refining, China for rare earth processing, and Germany for high-silica zeolite substrate manufacturing. Raw material dependencies include palladium, rhodium, and copper-exchanged zeolite formulations. Single-source vulnerability in South African platinum mining creates supply disruption exposure. Distribution runs through direct OEM supply agreements and consolidated national aftermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in emission control technology rests on copper-zeolite formulation premiums displacing legacy iron-based alternatives and coating automation reducing labor intensity at substrate facilities.
For Market Incumbents: Deepen backward integration into zeolite manufacturing to offset supply concentration risk among three chemical conglomerates controlling high-silica capacity. Expand captive precious metal refining partnerships in North America to capture US IRA clean manufacturing credits and reduce tariff exposure on South African imports. Hydrogen combustion engine development threatens long-term three-way catalyst demand; accelerate R&D into fuel cell membrane catalysts to defend platform relevance. For New Entrants and Emerging Players: Copper-exchanged zeolite coating technology offers a technology-first wedge into the India BS-VI Phase II compliance gap where domestic commercial vehicle producers lack formulation expertise. Target joint-venture structures with Maharashtra and Gujarat truck manufacturers seeking heavy-duty diesel aftertreatment licensing. Marine scrubber-catalyst convergence presents underdeveloped white space; pursue International Maritime Organization certification pathways ahead of established automotive suppliers. For Investors and Strategic Acquirers: Chemical conglomerates with captive zeolite substrate capacity are the most active acquirer in this space, consolidating coating specialists to secure formulation IP. Long-term viability favors integrated producers controlling upstream material supply through the hydrogen transition window. Watch copper-zeolite adoption rates in South Korean and German Euro 6d platforms as the inflection signal for premium-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Manufacturing | BASF's Ludwigshafen captive supply secures substrate security for European SCR system assemblers. |
| Domestic Content Production Expansion | US IRA credits favor Ohio River Valley catalyst coating facilities over Asian import dependency. |
| Copper-Zeolite Formulation Licensing | Technology holders capture India BS-VI Phase II joint-venture openings with domestic truck producers. |
| Marine SCR-Scrubber System Development | International Maritime Organization sulfur limits create new equipment category with extended service intervals. |
| Precious Metal Refining Partnership | Johnson Matthey's platinum group metal capabilities sustain catalyst supply security for European OEMs. |
Methodological Framework
Bottom-up automotive and industrial end-use modeling reconciled against top-down platinum group metal supply tracking forms the analytical core of this study. Primary interviews with catalyst coating facility technical directors, automotive OEM procurement leads, aftermarket distribution managers, and stationary source environmental compliance officers combined with secondary validation from EPA regulatory filings, EU ECE type-approval databases, China MEE GB standard publications, and SEC 10-K disclosures from precious metal refiners. Top-down customs data on zeolite substrate trade flows and bottom-up fleet turnover projections for Shanghai port logistics and German heavy-duty segments were cross-referenced to triangulate demand estimates.
Input-output matrices map precious metal loading requirements per emission control system configuration against projected vehicle production and industrial retrofit installations across the projection horizon. Segmentation dimensions modeled include product type, regeneration technology, end-use application, and installation channel. CAGRs were derived from regression analysis of historical compliance deadline impacts on hardware procurement cycles, incorporating catalyst replacement frequency assumptions and regulatory enforcement intensity scoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen combustion engine commercialization timelines and platinum group metal supply disruptions from South African mining operations. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, substrate manufacturing capacity expansion, and automotive platform electrification rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Ozone Generator Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Vapor Recovery Services Market