
 Tide Gauge Market | 2026-2036
Tide Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Tide Gauge Market Analytics
ISO 4363-grade accuracy certification is collapsing the gap between research-grade and operational tide gauge deployments. Valeport Limited leverages in-house sensor calibration to sustain premium positioning across North Sea installations. Kongsberg Maritime anchors its market presence through captive supply of pressure-transducer modules for subsea applications. RBR Ltd. differentiates via compact digital architectures that reduce power draw at remote Pacific Island stations.
A tide gauge measures vertical sea-surface elevation relative to a fixed geodetic benchmark using float, pressure, acoustic, or radar sensing principles with typical resolution of one millimeter over sampling intervals from one second to one hour; the instrument serves coastal engineering, tsunami warning systems, and climate research by generating long-term water-level records tied to terrestrial reference frames. Acoustic and radar product types command margin pools where non-contact measurement eliminates sensor fouling in estuarine environments. GPS-enabled technology segments attract investment as real-time kinematic positioning allows direct geodetic linkage without separate land-leveling surveys. Maritime industry end users dominate volume, though environmental agencies represent the fastest-growing demand channel as national adaptation plans mandate expanded monitoring networks.
FDA marine equipment guidelines, EPA coastal zone management criteria, and ISO 4363 hydrometric standards collectively shape product specifications and procurement eligibility for tide gauge installations. The EU's Copernicus Marine Service and Australia's Bureau of Meteorology enforce data-format compliance that favors digital-output instruments with standardized telemetry protocols. Stakeholders must weigh sensor interoperability against proprietary ecosystem lock-in when selecting platforms for multi-decadal sea-level observation programs.
Market Dynamics
ISO 4363-grade accuracy certification is compressing the distinction between research-grade and operational tide gauge deployments, forcing vendors to recalibrate product tiers and pricing architectures around certification tiers rather than hardware specifications alone.
Growth Catalysts
- Copernicus Marine Service mandates:The EU's standardized sea-level data submission requirements are accelerating replacement cycles for legacy analog installations across German and British port authorities.
- Tsunami warning network expansion:Pacific Island nations are deploying continuous tidal monitoring infrastructure as climate adaptation plans harden into statutory obligations.
- Pressure-transducer miniaturization:Advances in MEMS fabrication are enabling subsea deployments at depths previously requiring acoustic alternatives, opening new installation geometries.
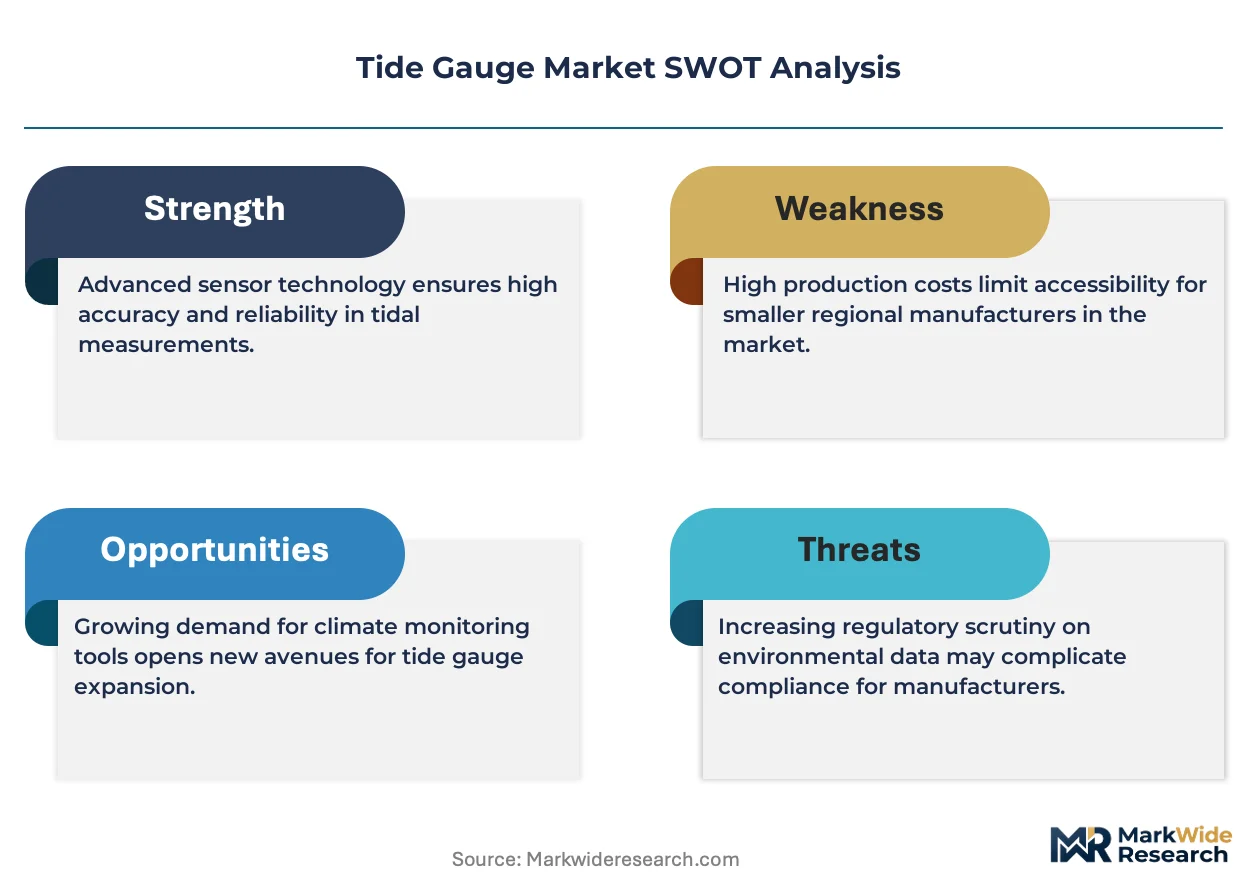
Market Restraints
- Sensor fouling costs:Estuarine biofouling on contact-based instruments drives maintenance expenditure cycles that erode total-cost-of-ownership advantages in brackish water zones.
- Geodetic benchmark scarcity:Stable terrestrial reference frames suitable for millimeter-resolution measurement are concentrated in coastal urban corridors, limiting rural and remote deployment feasibility.
- Telemetry protocol fragmentation:Proprietary data formats from established vendors create interoperability barriers that extend procurement timelines for multi-vendor network expansions.
Strategic Opportunities
- Real-time kinematic GPS convergence:Direct geodetic linkage without separate land-leveling surveys is opening municipal coastal engineering budgets previously captured by survey contractors.
- Australia's Bureau of Meteorology compliance pathways:Digital-output standardization mandates are creating first-mover advantages for vendors with pre-certified telemetry architectures.
- Environmental agency channel development:National adaptation plans in Japan and the United States are mandating expanded monitoring networks outside traditional maritime procurement channels.
Industry Challenges
- ISO 4363 certification timelines:Hydrometric standard compliance testing extends product development cycles by 18-24 months for new sensor architectures.
- Multi-decadal calibration drift:Long-term sea-level observation programs require field-interchangeable sensor modules that maintain traceability across manufacturer generations.
- Legacy analog integration:Coastal management agencies with 30-year water-level records face data continuity risks when migrating to digital telemetry platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tide Gauge Market |
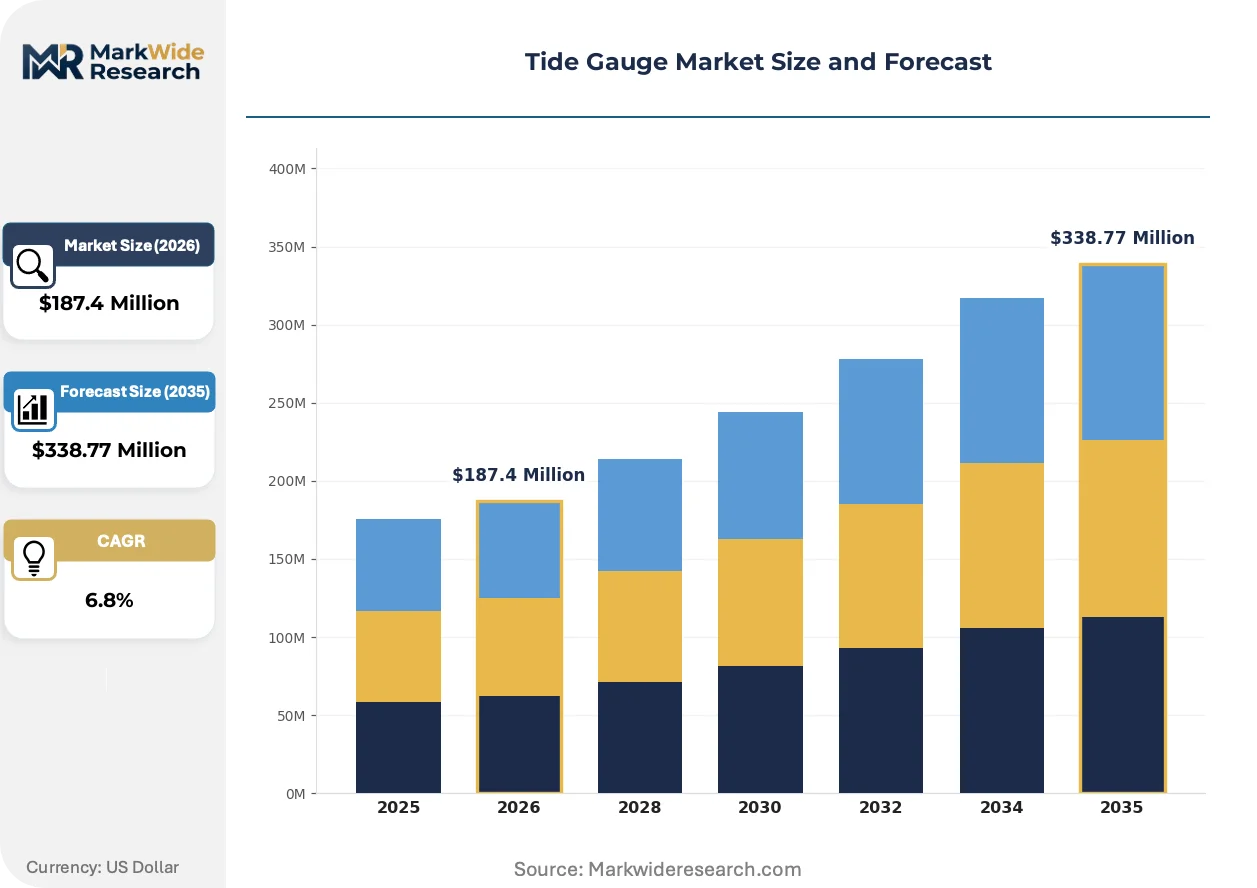
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Type, Pressure Type, Acoustic Type, Radar Type Technology: GPS, Ultrasonic, Mechanical, Digital End User: Maritime Industry, Coastal Management, Research Institutions, Environmental Agencies Installation: Fixed Installation, Portable Installation, Offshore Installation, Onshore Installation |
| Companies Covered | OTT HydroMet GmbH, Valeport Limited, RBR Ltd., Kongsberg Maritime AS, Teledyne RD Instruments, Inc., Xylem Inc., Ohmex Ltd, Campbell Scientific, Inc., Sea-Bird Electronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tide Gauge Market Evolving Landscape
Non-contact measurement modalities and embedded geodetic positioning are restructuring competitive advantage around sensor longevity and data sovereignty rather than raw precision specifications.
Radar tide gauges is fragmenting the mid-market segment previously dominated by pressure-transducer installations. Port modernization programs in Hamburg and Rotterdam are specifying radar units for estuarine environments where biofouling previously mandated quarterly maintenance windows. The technology is fragmenting vendor revenue concentration by enabling new entrants to compete on total-cost-of-ownership metrics without matching legacy calibration infrastructure.
REACH substance restrictions on marine coatings are reshaping sensor housing material specifications across European procurement channels. Manufacturers are accelerating ceramic and titanium alloy adoption to preempt compliance-driven disqualification from public tenders. German coastal authorities are now specifying coating-free exterior architectures for all new North Sea installations.
Subscription telemetry services are displacing capital-intensive private network builds among Pacific Island monitoring stations. Environmental agencies in Tuvalu and Kiribati are procuring data-as-a-service contracts that bundle satellite uplink, cloud storage, and quality assurance. This model concentrates vendor selection criteria around data sovereignty guarantees and regional server presence rather than hardware durability alone.
Tide Gauge Market Segmentation
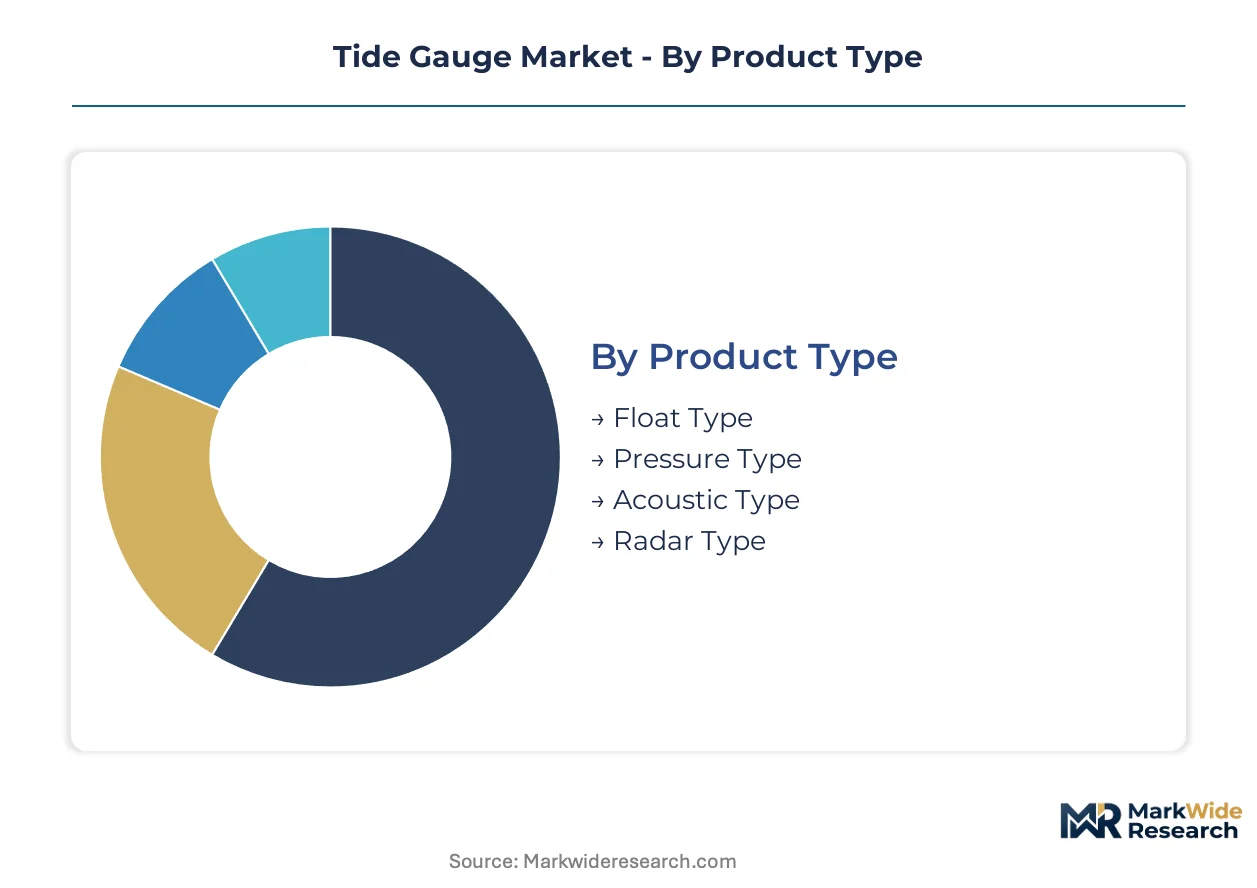
Precision requirements differ sharply between operational port monitoring and climate research applications. Segmentation reveals how certification tiers and installation constraints reshape procurement patterns across coastal infrastructure programs.
Product Type:
Float-type gauges dominate domestic coastal installations in the United States and Japan, while acoustic and radar variants concentrate in export-led deployments to Pacific Island nations and Australian port authorities.
- Float Type:Mechanical lever-arm systems with stilling wells dampen wave action to yield millimeter-grade resolution. Demand concentrates in German and British harbor authorities where legacy infrastructure favors proven analog-to-digital conversion pathways.
- Pressure Type:Submerged transducers measure hydrostatic head to infer water level, enabling compact deployments without surface structures. Pacific Island tsunami warning networks drive volume as climate adaptation funds harden into statutory monitoring obligations.
- Acoustic Type:Non-contact air-gap sensors eliminate biofouling risks in estuarine environments.
- Radar Type:Microwave pulse-echo systems penetrate precipitation and fog for continuous offshore operations.
Pressure-type instruments command the established base. The steepest expansion runs through radar-type deployments.
Technology:
Cost tiers separate capital-intensive GPS-enabled installations from maintenance-heavy mechanical legacy systems, with digital architectures capturing mid-budget coastal engineering contracts.
- GPS:Real-time kinematic positioning enables direct geodetic linkage without separate land-leveling surveys. Municipal coastal engineering budgets in Japan and the United States increasingly specify GPS-enabled units to displace survey contractor costs.
- Digital:Compact architectures with standardized telemetry protocols reduce power draw at remote stations. Australia's Bureau of Meteorology compliance pathways favor pre-certified digital-output instruments, creating first-mover procurement advantages.
- Ultrasonic:Time-of-flight sensors suit protected inland waterway applications.
- Mechanical:Chart-recorder legacy systems persist where data continuity spans multi-decadal records.
Mechanical technology retains the installed base. Digital architectures are climbing the fastest as regulatory mandates accelerate replacement cycles.
End User:
Customer type determines specification rigor, with maritime procurement favoring operational durability and environmental agencies prioritizing telemetry standardization for national network integration.
- Maritime Industry:Port authorities and shipping operators require continuous availability for navigation safety. Hamburg and Rotterdam modernization programs specify coating-free exterior architectures to satisfy REACH substance restrictions on marine coatings.
- Environmental Agencies:National adaptation plans mandate expanded monitoring networks outside traditional maritime channels. Tuvalu and Kiribati are procuring data-as-a-service contracts bundling satellite uplink and cloud storage.
- Coastal Management:Engineering departments require geodetic stability for infrastructure design.
- Research Institutions:Climate scientists demand traceable calibration chains for sea-level trend analysis.
Maritime industry procurement commands volume concentration. Environmental agency channel development shows the steepest trajectory as statutory obligations expand.
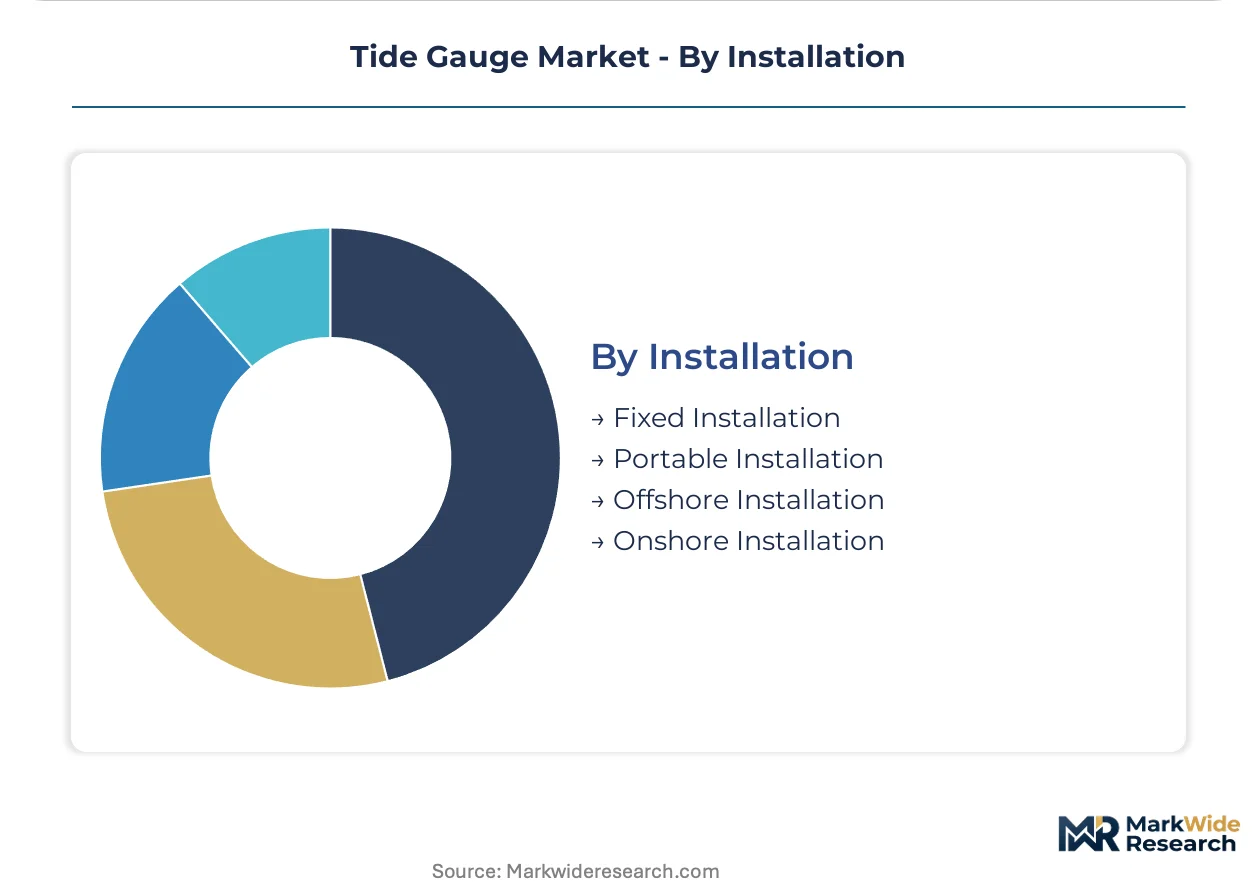
Installation:
Maturity gradients separate established onshore benchmarks from emerging offshore subsea geometries enabled by pressure-transducer miniaturization.
- Fixed Installation:Permanent structures tied to terrestrial geodetic benchmarks serve long-term sea-level observation. Stable reference frames suitable for millimeter resolution concentrate in coastal urban corridors, limiting rural deployment feasibility.
- Offshore Installation:Subsea pressure transducers at depths previously requiring acoustic alternatives open new installation geometries. MEMS fabrication advances enable compact deployments for deep-water tsunami detection arrays.
- Portable Installation:Rapid-deployment units support temporary construction and dredging surveys.
- Onshore Installation:Pier-mounted systems dominate estuarine and harbor environments.
Fixed installations retain the core revenue base. Offshore geometries are gaining share fastest as subsea sensor capabilities advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led supply from German and British sensor manufacturers balances against import-dependent deployment programs across Pacific Island nations and emerging coastal infrastructure markets. Trade flows concentrate precision instruments toward port modernization hubs while domestic production serves established North Sea and North American installations.
United States
EPA coastal zone management criteria and FDA marine equipment guidelines shape procurement specifications for harbor authorities from San Diego to Norfolk. The Army Corps of Engineers mandates ISO 4363-grade installations for federal navigation projects. Gulf Coast ports in Texas and Louisiana are replacing legacy analog systems with digital telemetry architectures ahead of hurricane season intensification.
Germany
REACH substance restrictions on marine coatings are accelerating specification shifts across Hamburg and Bremerhaven port authorities. The Federal Maritime and Hydrographic Agency enforces standardized data submission aligned with EU Copernicus Marine Service requirements. North Sea coastal states are procuring coating-free exterior architectures for all new tidal monitoring infrastructure.
Japan
METI adaptation mandates and tsunami warning network obligations drive continuous deployment of subsea pressure transducers along the Pacific Ring of Fire. The Japan Meteorological Agency maintains statutory monitoring density thresholds for seismic risk zones. Port and Harbor Research Institute collaborations in Tokyo Bay are testing GPS-enabled real-time kinematic positioning for direct geodetic linkage.
Australia
Bureau of Meteorology compliance pathways favor pre-certified digital-output instruments with standardized telemetry protocols. National adaptation plans mandate expanded monitoring networks across Queensland and Western Australian coastlines. Darwin and Fremantle port modernization programs are specifying radar tide gauges for estuarine environments with high biofouling risk.
United Kingdom
Environment Agency coastal erosion programs and National Oceanography Centre research collaborations sustain demand for traceable calibration chains. The UK Hydrographic Office enforces data-format compliance for maritime safety-critical installations. Scottish coastal management authorities are deploying portable installations for temporary infrastructure surveys in the Highlands and Islands.
Tide Gauge Market Competitive Landscape
Listed leaders compete with private specialists across certification-tier positioning and telemetry protocol standardization. The vendor base clusters around three concentration nodes: precision sensor manufacturers with captive calibration infrastructure, marine electronics conglomerates with diversified subsea portfolios, and compact digital specialists serving remote station deployments. Two strategic archetypes dominate competitive moves: backward integration into MEMS fabrication for pressure-transducer miniaturization, and strategic partnerships with satellite telemetry providers for data-as-a-service bundling.
Among UK-based private specialists, Valeport Limited and RBR Ltd. exemplify contrasting positioning within the precision instrument tier. Valeport occupies a position anchored in North Sea calibration infrastructure and in-house sensor verification, while RBR Ltd. represents the compact digital architecture archetype optimized for Pacific Island power-constrained deployments. Norwegian conglomerate Kongsberg Maritime AS sits within the marine electronics diversified tier, leveraging subsea application breadth across pressure-transducer module supply. These three anchors illustrate how competitive advantage stratifies around certification depth, power efficiency, and subsea integration capability rather than raw precision specifications alone.
| Leading Market Players |
|---|
| OTT HydroMet GmbH |
| Valeport Limited |
| RBR Ltd. |
| Kongsberg Maritime AS |
| Teledyne RD Instruments, Inc. |
| Xylem Inc. |
| Ohmex Ltd |
| Campbell Scientific, Inc. |
| Sea-Bird Electronics, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term data-as-a-service contracts bundling satellite telemetry and quality assurance lock in both supply access and price visibility for Pacific Island environmental agencies, compressing procurement cycles while shifting vendor selection toward regional server presence and data sovereignty guarantees rather than hardware durability alone.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Certification tiers—ISO 4363-grade, research-grade, operational-grade—separate pricing bands more sharply than raw sensor specifications. Cost compression in the economy tier intensifies as MEMS fabrication advances commoditize pressure-transducer modules. Environmental agencies exhibit highest price sensitivity due to grant-funded procurement cycles, while maritime port authorities prioritize total-cost-of-ownership over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for German and British sensor manufacturers sourcing MEMS components. Manufacturing concentration rests on Germany, the United Kingdom, and Norway for precision instrument assembly, with Japan and the United States contributing specialized pressure-transducer and GPS module technologies. Single-source vulnerability runs through titanium alloy and ceramic housing suppliers facing REACH substance restriction compliance. Distribution feeds from captive calibration facilities directly to port authority procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry protocol standardization is shifting competitive advantage from hardware precision to platform interoperability, as EU Copernicus Marine Service and Australia's Bureau of Meteorology compliance pathways favor vendors with pre-certified digital architectures over legacy analog specialists.
For Market Incumbents: Consolidate backward integration into MEMS fabrication to defend margin position against pressure-transducer commoditization. Lock in calibration infrastructure control across North Sea installations while accelerating ISO 4363 certification timelines to preempt new sensor architecture entrants. Channel control through captive telemetry service bundling offers defensive leverage against subscription-based challengers. For New Entrants and Emerging Players: Differentiate on radar-type non-contact measurement modalities that eliminate biofouling maintenance cycles in estuarine environments. Target Pacific Island environmental agencies with power-constrained compact digital architectures and data-as-a-service go-to-market models. Australia's Bureau of Meteorology compliance pathways represent the most penetrable regulatory entry point for pre-certified digital-output instruments. For Investors and Strategic Acquirers: Compact digital specialists with satellite telemetry partnerships offer the strongest acquisition target archetype for platform-economy exposure. Long-term viability hinges on data sovereignty guarantees and regional server presence rather than hardware manufacturing scale. Watch for inflection where subscription telemetry services displace capital-intensive private network builds among remote monitoring stations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 4363 Certification Investment | Accelerates product eligibility for EU Copernicus Marine Service mandates and Australian Bureau of Meteorology procurement pathways. |
| MEMS Fabrication Backward Integration | Captures margin pool from pressure-transducer miniaturization enabling subsea deployments at previously inaccessible depths. |
| Satellite Telemetry Partnership | Enables data-as-a-service bundling for Pacific Island environmental agencies replacing capital-intensive private network builds. |
| Radar Sensor Architecture Launch | Eliminates biofouling maintenance costs in estuarine environments where Hamburg and Rotterdam port authorities specify non-contact systems. |
| Coating-Free Housing Material Transition | Preempts REACH substance restriction disqualification from German coastal authority tenders for North Sea installations. |
Research Methodology
Cross-validation between primary interviews with coastal engineering directors, port authority procurement officers, environmental agency program managers, and tide gauge calibration technicians anchors the qualitative findings. Secondary validation draws from EPA coastal zone management filings, EU Copernicus Marine Service technical specifications, ISO 4363 hydrometric standards documentation, and national adaptation plan statutory instruments. Bottom-up installation demand modeling triangulates against top-down maritime infrastructure budget allocations.
Sensitivity analysis across pressure-transducer miniaturization curves, GPS-enabled adoption rates, and telemetry protocol standardization timelines shapes the analytical framework. Segmentation dimensions span product type, technology tier, end-user channel, and installation geometry. CAGRs derive from replacement cycle acceleration under regulatory mandates and climate adaptation funding trajectories. Subsea deployment depth capabilities and real-time kinematic positioning penetration serve as industry-specific forecast inputs.
Material uncertainties—tariff exposure on titanium alloy imports, REACH restriction scope expansion, satellite uplink cost volatility—sit outside the modeled envelope. Forecasts reflect assumptions regarding ISO certification timeline stability and statutory monitoring density thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market