
 Oil and Gas Processing Seals Market | 2026-2036
Oil and Gas Processing Seals Market Size, Share, and Industry Trends Forecast 2026-2036
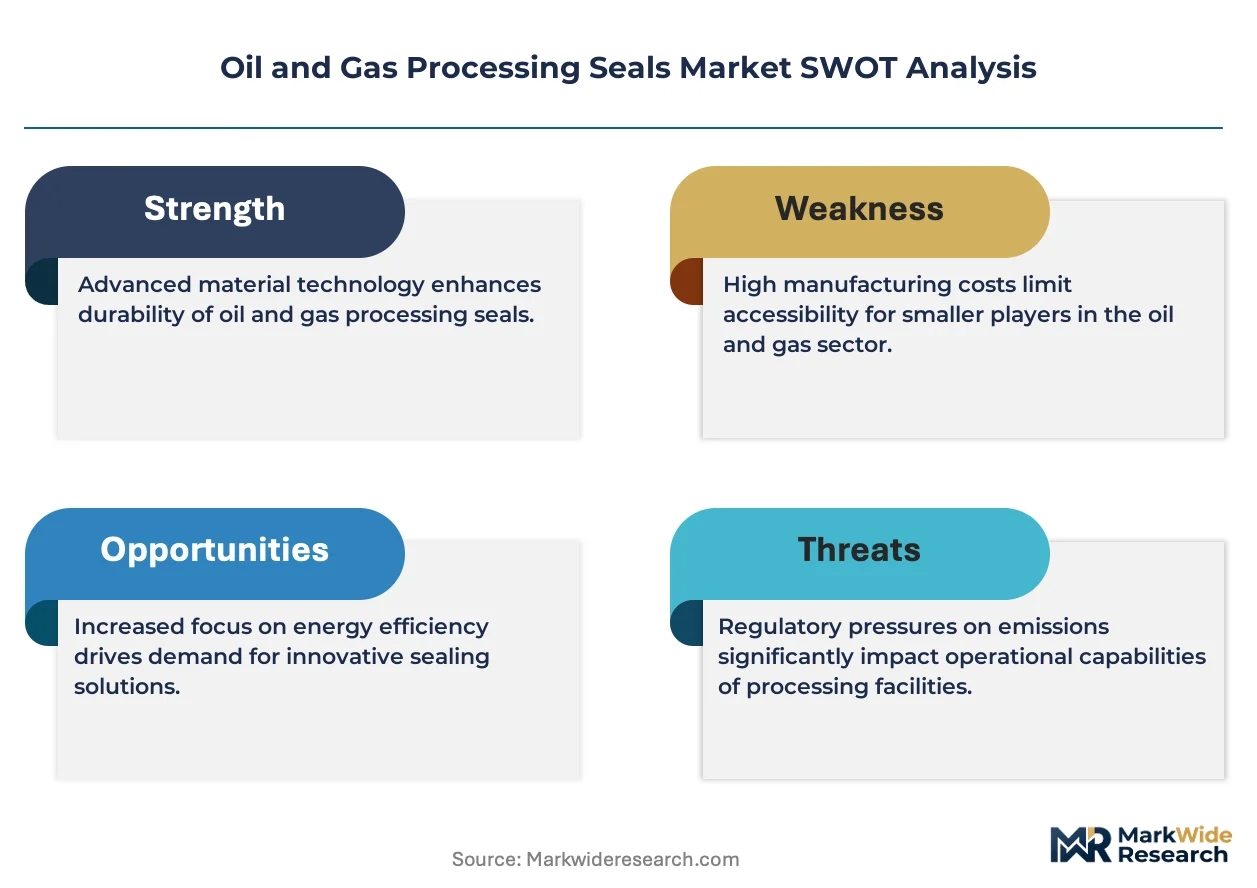
Oil and Gas Processing Seals Market Analysis
Upstream capital expenditure from supermajors is collapsing toward integrated LNG developers and offshore contractors as the dominant buyer archetype. Flowserve Corporation leverages its integrated aftermarket service network to anchor long-term frame agreements with Middle Eastern national oil companies. EagleBurgmann competes through specialized sealing solutions for extreme temperature hydrocarbon processing. SKF dominates magnetic bearing and seal combination systems for subsea compression stations.
Oil and gas processing seals are engineered containment devices manufactured from elastomeric compounds, thermoplastics, or metal alloys, typically rated for pressures exceeding 15,000 psi and temperatures from cryogenic to 350°C, designed to prevent fugitive emissions and process fluid loss in hydrocarbon handling equipment. Fluoroelastomer formulations command premium positioning due to hydrogen sulfide resistance and extended service intervals in sour gas applications. By application, downstream refining and petrochemical processing sustains the largest volume base while upstream subsea installations represent the fastest margin expansion segment. Metallic seals occupy critical infrastructure in high-pressure wellhead assemblies where elastomer degradation risks catastrophic failure.
API standards, ISO 23936-2 sour service specifications, and EPA methane emission regulations collectively dictate material selection, testing protocols, and replacement cycles across the value chain. The US Environmental Protection Agency enforces fugitive emission monitoring that accelerates seal replacement frequency in refining complexes. Stakeholders must monitor evolving hydrogen blending requirements in pipeline infrastructure that will redefine seal compatibility specifications and qualification testing regimes.
Market Dynamics
Deepwater exploration economics are compressing replacement cycles for high-pressure sealing systems as operators prioritize reliability over first-cost procurement. API 6A certification requirements now function as a de facto barrier to vendor participation in sour service tenders.
Growth Catalysts
- EPA Methane Rules:Fugitive emission monitoring mandates accelerate seal replacement frequency in US refining corridors. Downstream operators budget for predictive maintenance to avoid regulatory penalties.
- Fluoroelastomer Formulations:Hydrogen sulfide-resistant compounds extend service intervals in sour gas applications. Material science advances reduce unplanned shutdowns.
- US Gulf Coast Concentration:Petrochemical capacity expansion along the Texas-Louisiana corridor concentrates demand for API-certified sealing systems. Integrated complexes require standardized component specifications.
Market Restraints
- Raw Material Volatility:Perfluoroelastomer precursor costs fluctuate with fluorochemical supply constraints. Formulation margins compress during feedstock price spikes.
- Supplier Concentration:Specialized fluoroelastomer compounders cluster in Germany and Japan. Geographic concentration creates single-source vulnerability for critical formulations.
- Metallic Seal Limitations:Metal-to-metal sealing systems require precision machining tolerances that extend lead times. Fabrication bottlenecks constrain rapid deployment.
Strategic Opportunities
- Hydrogen Infrastructure:Pipeline blending specifications will require seal compatibility recertification. First-mover compounders capture specification-setting influence.
- Subsea Compression:Magnetic bearing and seal combination systems address ultra-deepwater pressure requirements. Offshore contractors seek integrated supplier partnerships.
- Aftermarket Service Unbundling:Frame agreement structures separate hardware procurement from installation support. Service revenue streams decouple from capital equipment cycles.
Industry Challenges
- API 6A Certification Timelines:Sour service qualification testing extends product development cycles. Laboratories face backlog congestion for high-pressure validation.
- Legacy System Integration:Retrofit sealing solutions must interface with decades-old wellhead geometries. Custom engineering erodes standard product margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Processing Seals Market |
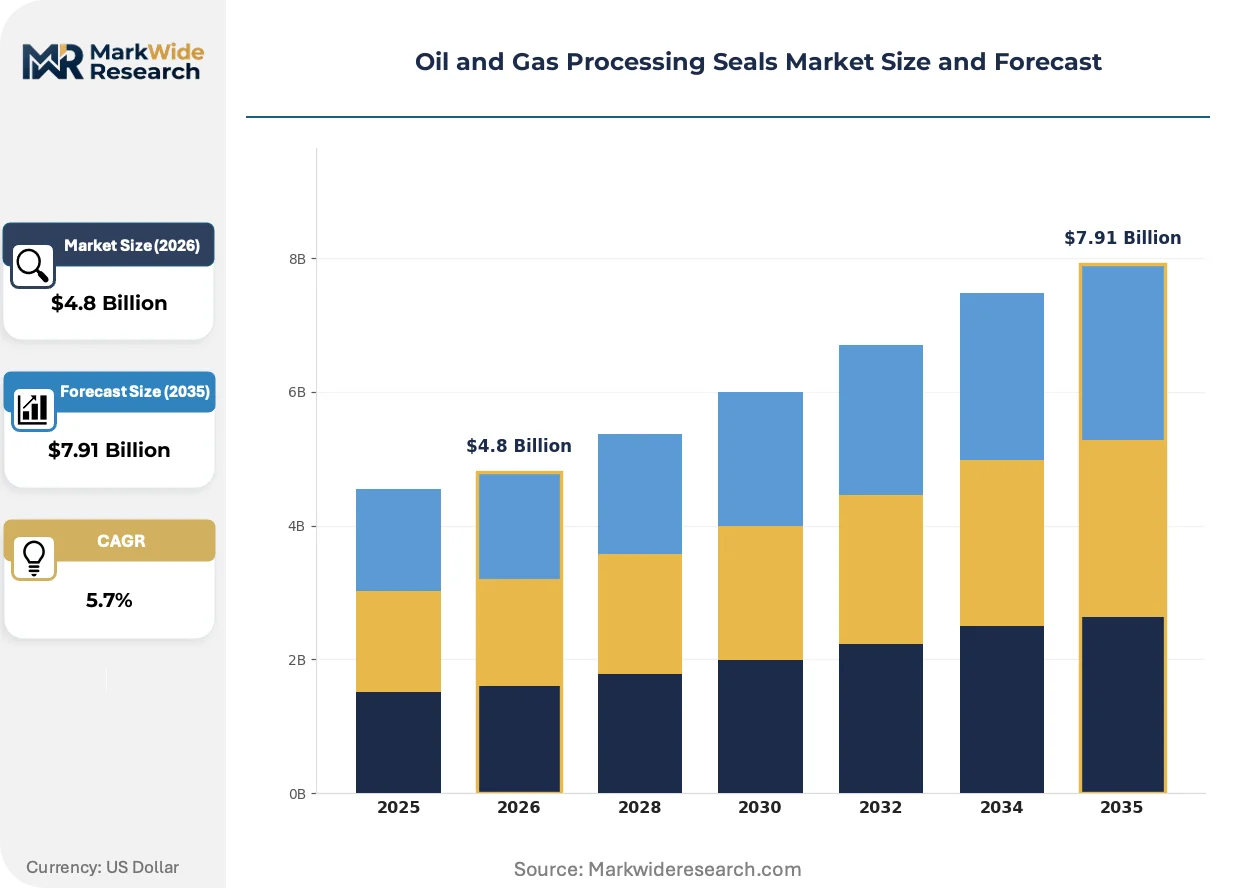
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seal Type: O-Rings, Gaskets, Sealing Washers, Lip Seals Material: PTFE, Nitrile Rubber, Fluoroelastomer, Metallic Application: Upstream, Midstream, Downstream, Petrochemical Processing Installation Method: Bolted, Adhesive Bonding, Mechanical Compression, Press Fit |
| Companies Covered | Flowserve Corporation, EagleBurgmann, Trelleborg AB, Smiths Group, SKF, John Crane, Parker Hannifin Corporation, DuPont de Nemours, Freudenberg SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Processing Seals Market Emerging Trajectories
Material science convergence with digital monitoring capabilities is redefining performance guarantees in hydrocarbon containment applications. Seal manufacturers now embed sensing elements directly into elastomeric compounds.
Perfluoroelastomer grades with enhanced mechanical stability are displacing conventional fluoroelastomer formulations in high-pressure wellhead assemblies. Subsea contractors specify these materials for 20-year design life requirements. The technology is displacing scheduled replacement regimes with condition-based maintenance models.
EPA fugitive emission enforcement is tightening material traceability requirements across the value chain. Refinery operators must document seal origin and batch certification for audit compliance. Downstream facilities in Texas and Louisiana are consolidating supplier bases to reduce documentation burden.
Long-term frame agreements are supplanting spot procurement for critical path sealing components. National oil companies in the Middle East anchor multi-year supply contracts with integrated service provisions. This restructuring concentrates purchasing authority with engineering-procurement-construction contractors rather than end operators.
Oil and Gas Processing Seals Market Segmentation
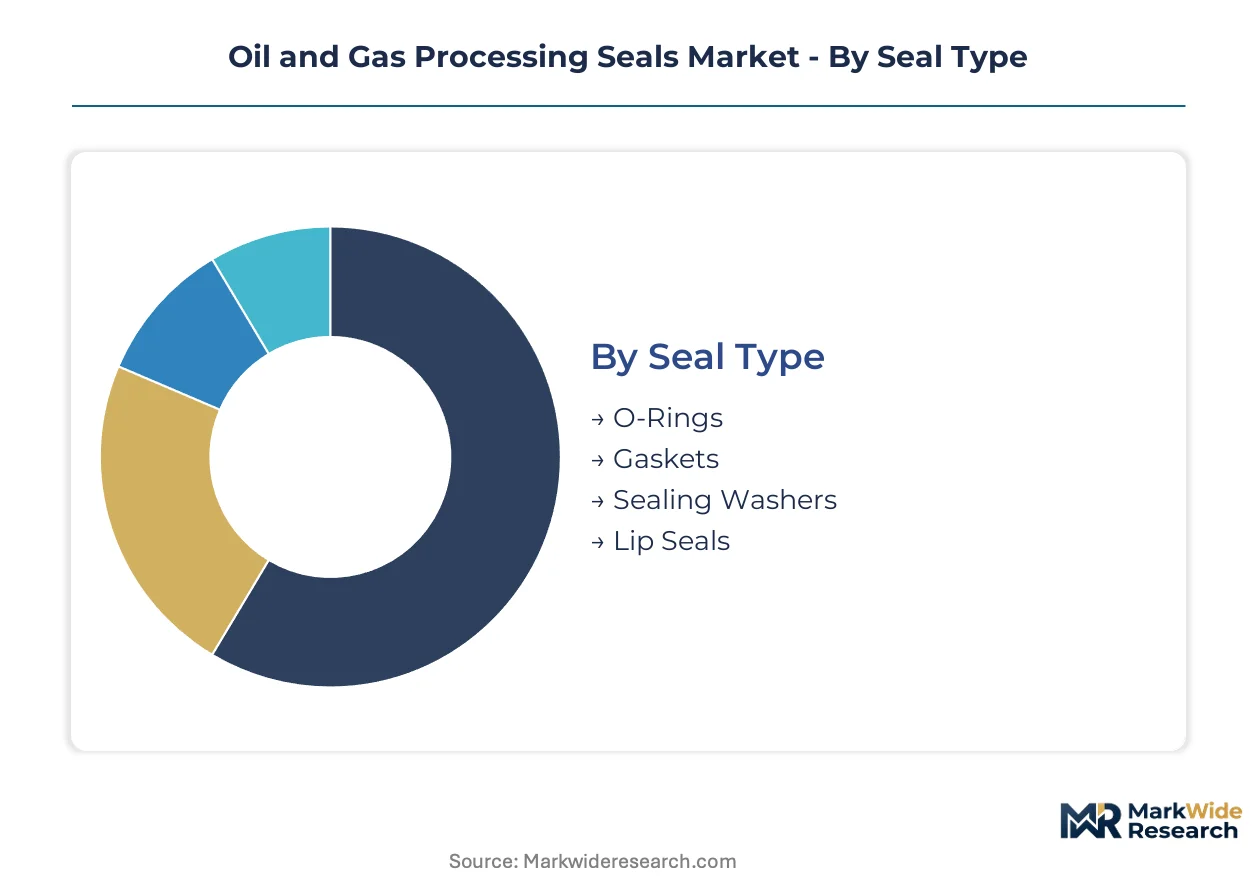
Seal specification diversity across hydrocarbon processing creates distinct procurement patterns. Material selection and installation geometry determine replacement cycles, certification requirements, and supplier qualification pathways for each segment cluster.
Seal Type:
Mechanical face seals and static gaskets face intensifying substitution pressure from integrated metal-to-metal designs in high-pressure wellhead applications.
- O-Rings:Toroidal elastomeric seals manufactured from nitrile, fluoroelastomer, or perfluoroelastomer compounds, typically deployed in dynamic reciprocating equipment and valve bonnet assemblies. Demand concentrates in downstream Texas refining corridors where EPA fugitive emission monitoring mandates accelerate replacement frequency.
- Gaskets:Static sealing elements fabricated from compressed fiber, spiral-wound metal, or reinforced graphite laminates, engineered for flange connections in piping systems. Petrochemical processing complexes along the US Gulf Coast specify API 6A certified gaskets for sour service hydrogen sulfide exposure.
- Sealing Washers:Metallic or composite flat rings providing load distribution and secondary sealing in bolted joints.
- Lip Seals:Radial shaft seals with flexible elastomeric lips maintaining contact against rotating surfaces.
O-Rings retain volume leadership; Gaskets hold the steepest expansion curve.
Material:
Cost tier stratification separates premium formulations from commodity elastomers based on hydrogen sulfide resistance and temperature rating.
- Fluoroelastomer:Fluorocarbon polymer compounds delivering superior chemical resistance and thermal stability across -20°C to 200°C operating ranges, with specialized grades rated for 350°C intermittent exposure. Sour gas operators in the Permian Basin specify hydrogen sulfide-resistant formulations to extend service intervals.
- Metallic:Stainless steel, Inconel, or Monel alloys precision-machined for metal-to-metal sealing in wellhead assemblies and Christmas tree equipment. Subsea installations off Louisiana require 20-year design life certification for high-pressure metallic seal systems.
- PTFE:Polytetrafluoroethylene seals offering chemical inertness and low friction coefficients.
- Nitrile Rubber:Acrylonitrile-butadiene copolymers serving cost-sensitive applications with moderate temperature and chemical exposure.
Fluoroelastomer commands premium positioning; Metallic seals gain share fastest in deepwater procurement.
Application:
Customer type differentiation separates integrated supermajors from independent operators and engineering-procurement-construction contractors.
- Downstream:Refining and petrochemical processing facilities utilizing static sealing systems in distillation columns, reactors, and heat exchanger bundles. EPA methane enforcement in Texas and Louisiana drives predictive maintenance investment and seal replacement documentation.
- Upstream:Exploration and production operations spanning onshore unconventional wells and offshore platform installations. Deepwater contractors in the Gulf of Mexico prioritize reliability-centered procurement for high-pressure subsea sealing systems.
- Midstream:Pipeline transportation and storage infrastructure requiring gaskets and O-rings for compressor stations and terminal facilities.
- Petrochemical Processing:Ethylene crackers and derivative units with specialized high-temperature sealing requirements.
Downstream sustains the largest installed base; Upstream subsea installations climb the fastest.
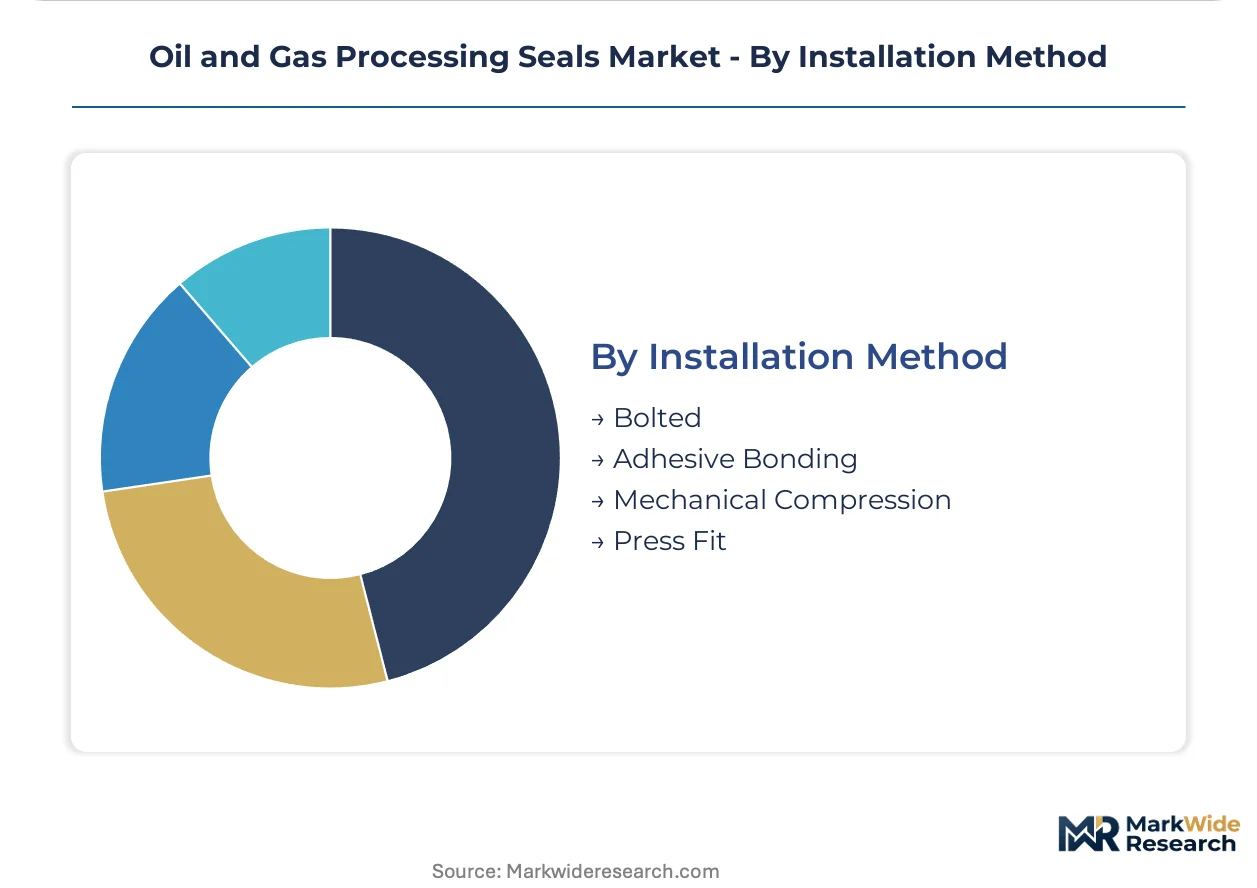
Installation Method:
Supply concentration in precision machining capabilities favors bolted and mechanical compression techniques over adhesive-dependent systems.
- Bolted:Flange connections utilizing gasket compression through controlled bolt torque sequences, enabling field replacement without specialized equipment. Refinery turnaround schedules in Louisiana depend on standardized bolted joint specifications for maintenance efficiency.
- Mechanical Compression:Spring-energized or pressure-assisted seal designs maintaining contact force independent of bolt load relaxation. Subsea wellhead contractors specify mechanical compression seals for 15,000 psi rated assemblies.
- Press Fit:Interference-fit seal installation requiring precision dimensional control.
- Adhesive Bonding:Structural adhesive attachment for specialized composite seal carriers.
Bolted installations dominate maintenance volumes; Mechanical compression systems expand most quickly in newbuild procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fluoroelastomer compounders export specialized formulations to Gulf of Mexico operators facing sour service certification deadlines. This trade corridor channels European material science into North American deepwater procurement cycles.
United States
EPA methane enforcement drives predictive maintenance budgets across Texas and Louisiana refining corridors. The agency's fugitive emission monitoring mandates accelerate seal replacement frequency in petrochemical complexes. Houston anchors the largest concentration of API 6A certification laboratories serving domestic upstream contractors.
Saudi Arabia
National oil company frame agreements concentrate procurement authority with integrated engineering-procurement-construction contractors. The country's national petroleum regulator enforces sour service specifications aligned with API standards. The Eastern Province hosts the densest cluster of high-pressure wellhead installations requiring metallic seal systems.
Norway
North Sea subsea compression projects demand magnetic bearing and seal combination systems for ultra-deepwater deployment. The country's national petroleum safety authority mandates 20-year design life certification for subsea containment equipment. Stavanger anchors specialized supplier engineering offices serving Barents Sea exploration licenses.
China
State-owned refinery expansions along the Bohai Rim concentrate demand for hydrogen sulfide-resistant fluoroelastomer formulations. The national standards administration enforces GB standards for pressure equipment sealing that increasingly reference ISO sour service protocols. Shandong Province hosts the fastest-growing cluster of domestic seal fabricators targeting midstream pipeline infrastructure.
Brazil
Pre-salt deepwater development contracts prioritize reliability-centered procurement for high-pressure Christmas tree assemblies. The national petroleum regulator enforces local content requirements that reshape supplier qualification pathways. Rio de Janeiro anchors engineering offices for international seal manufacturers bidding on Libra and Buzios field developments.
Oil and Gas Processing Seals Market Vendor Landscape
Player mix skews toward integrated multinational industrial conglomerates with diversified fluid handling portfolios. Market structure concentrates procurement influence among three to five dominant sealing system suppliers holding API 6A laboratory accreditation. Two strategic archetypes define competitive positioning: integrated aftermarket service providers anchoring multi-year frame agreements, and specialized material compounders commanding premium positioning in extreme environment formulations. Dominant competitive moves include backward integration into fluoroelastomer precursor supply and geographic expansion through local content partnerships in pre-salt and Middle Eastern markets.
Among the integrated service providers, Flowserve Corporation and SKF occupy positions exemplifying divergent strategic vectors. Flowserve anchors long-term agreements through combined hardware and installation support bundling. SKF represents the specialized technology archetype, with its company name signaling Nordic engineering heritage in rotating equipment integration. EagleBurgmann, identifiable as a German GmbH structure from its designation, sits within the premium material specialization tier. These three company names from the raw data illustrate how supplier positioning maps to distinct procurement channels: frame agreement anchoring, technology integration, and extreme environment material science.
| Leading Market Players |
|---|
| Flowserve Corporation |
| EagleBurgmann |
| Trelleborg AB |
| Smiths Group |
| SKF |
| John Crane |
| Parker Hannifin Corporation |
| DuPont de Nemours |
| Freudenberg SE |
| Others |
Supply Flow & Price Mechanics
Long-term frame agreements with integrated service provisions lock in supply access for national oil companies while anchoring price visibility across multi-year procurement cycles. These structures concentrate purchasing authority with engineering-procurement-construction contractors and insulate qualified suppliers from spot-market volatility in fluoroelastomer feedstocks.
Pricing Analysis
Perfluoroelastomer formulations command a 40-60% premium over conventional fluoroelastomer grades in high-pressure wellhead applications, while metallic seals for subsea installations occupy a separate tier above both elastomer categories. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—API 6A sour service qualification functions as the primary price escalator alongside material hydrogen sulfide resistance ratings. Cost compression in standard-grade nitrile rubber compounds is intensifying because of oversupply in Asian manufacturing capacity. Downstream refining operators in Texas and Louisiana exhibit the highest price sensitivity due to budget pressure from EPA compliance costs, whereas deepwater contractors in the Gulf of Mexico prioritize reliability specifications over first-cost procurement.
Supply Chain Analysis
Container availability constraints on the Hamburg-Houston trade lane elevate inbound logistics costs for German fluoroelastomer compounders serving Gulf of Mexico operators. Precision machining capacity for metallic seals concentrates in Germany, Japan, and the United States, while specialized elastomer formulation draws from captive supply networks in the same geographies. Single-source vulnerability pervades perfluoroelastomer precursor supply, with fluorochemical feedstock production anchored in Chinese and German chemical complexes. Distribution runs through authorized distributor networks serving regional oilfield service hubs, with direct procurement relationships reserved for supermajor frame agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against metal-to-metal sealing systems displacing elastomeric solutions in high-pressure wellhead assemblies. Incumbents must navigate the shift toward integrated magnetic bearing and seal combination technologies that redefine performance specifications.
For Market Incumbents: Compound API 6A laboratory accreditation with backward integration into fluoroelastomer precursor supply to defend margin position against specialty compounders. Anchor multi-year frame agreements with Middle Eastern national oil companies before competitors capture specification-setting influence in hydrogen infrastructure recertification cycles. Prioritize aftermarket service unbundling to decouple revenue streams from capital equipment procurement volatility.
For New Entrants and Emerging Players: Anchor in subsea compression system integration partnerships where magnetic bearing and seal combination technologies create white-space opportunities outside incumbent elastomer strongholds. Target predictive maintenance software layers for downstream refining corridors in Texas and Louisiana, where EPA documentation burdens drive demand for digital monitoring solutions. Pursue local content qualification pathways in Brazil's pre-salt developments to bypass established supplier certification backlogs.
For Investors and Strategic Acquirers: Capital is best deployed toward fluoroelastomer compounders with hydrogen sulfide-resistant formulation IP and existing API 6A certification infrastructure, positioned for hydrogen infrastructure recertification cycles. Long-term viability hinges on material science capabilities rather than fabrication scale, favoring targets with 20-year design life validation records. Watch for inflection in hydrogen blending pipeline specifications that would trigger wholesale seal compatibility recertification and specification churn.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoroelastomer Precursors | Captive supply of hydrogen sulfide-resistant compounds insulates margins from feedstock volatility in German and Japanese chemical markets. |
| API 6A Laboratory Accreditation Expansion | Certification capacity constraints in Houston and Stavanger create bottlenecks that accredited suppliers exploit for tender participation rights. |
| Hydrogen Infrastructure Recertification Programs | First-mover compounders capturing pipeline blending specifications gain durable influence over emerging compatibility standards. |
| Aftermarket Service Unbundling | Separating hardware procurement from installation support generates recurring revenue streams independent of capital equipment cycles. |
| Local Content Partnership in Pre-Salt Markets | Brazilian regulatory requirements reshape supplier qualification pathways and concentrate procurement with domestically-anchored entities. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from fluid handling conglomerates, API certification registries, and EPA enforcement records. The research program incorporated structured interviews with procurement directors at supermajors, maintenance engineers at Gulf Coast refineries, technical directors at fluoroelastomer compounders, and aftermarket service heads at sealing system distributors. Bottom-up triangulation across seal type, material grade, and application segments was validated against top-down expenditure analysis from national oil company budget disclosures.
Segmentation dimensions modeled span seal type, material formulation, application category, and installation method across the projection horizon. The analytical framework derived CAGRs from replacement cycle frequency analysis, regulatory-driven maintenance interval compression, and deepwater capital expenditure trajectories. Industry-specific forecast inputs incorporated EPA methane enforcement intensity curves and hydrogen infrastructure deployment assumptions for pipeline blending specifications.
Decision-makers should treat outputs as directional under sustained oil prices supporting deepwater exploration economics and stable API certification timelines; material deviation would warrant model refresh. Specific risk factors include fluorochemical supply disruptions, laboratory accreditation backlogs, and accelerated hydrogen specification shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
North America Proppants Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Pumpjack Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Europe Oil and Gas Drones Market