
 Industrial Power Monitoring System Market | 2026-2036
Industrial Power Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Power Monitoring System Market Foresight
Market Context
The direct sales channel for industrial power monitoring hardware is narrowing as system integrators and energy service companies capture more project flow. Schneider Electric SE leverages its EcoStruxure platform to anchor large manufacturing deployments across Europe and Asia. ABB Ltd competes through its Ability Energy Manager suite, which specializes in real-time analytics for process industries. Siemens AG dominates the German utility retrofit segment with its Sentron portfolio, extending its influence through certified partner networks.
Technical Definition and Segment Structure
An industrial power monitoring system comprises intelligent electronic devices, communication gateways, and analytics software that measure voltage, current, power factor, and harmonic distortion across three-phase electrical networks to enable predictive maintenance and tariff optimization. Manufacturing plants represent the most mature end user segment, with margin pools shifting toward software subscriptions and cloud-based diagnostics as hardware commoditizes. IoT Platforms and Edge Computing are the fastest-expanding technology categories, driven by latency requirements in critical power applications and the need for localized decision-making before cloud transmission.
Regulatory Frame and Outlook
The EU Green Deal and F-Gas Regulation shape European demand by mandating energy audits and refrigerant leak detection that require integrated power and environmental monitoring. In the United States, OSHA electrical safety standards and EPA greenhouse gas reporting rules compel facilities to install continuous monitoring infrastructure for compliance documentation. Stakeholders must weigh the capital expense of edge-native architectures against the operational flexibility that cloud-hybrid deployments offer as grid codes and carbon accounting standards tighten.
Market Dynamics
The industrial power monitoring system market is undergoing structural compression as edge-native architectures displace traditional SCADA-centric deployments, forcing vendors to reconfigure revenue models around software subscriptions rather than hardware margins.
Growth Catalysts
- EU Green Deal efficiency mandates:European industrial facilities face binding energy audit requirements that necessitate continuous power monitoring infrastructure, accelerating retrofit cycles across Germany, France, and Italy.
- Data center load expansion:Hyperscale operators in Northern Virginia, Frankfurt, and Singapore are deploying three-phase monitoring at substation level to manage density-driven thermal and electrical constraints.
- Edge computing latency requirements:Critical power applications in semiconductor fabrication and pharmaceutical cold chain now demand sub-10 millisecond local analytics, bypassing cloud-only architectures.
Market Restraints
- Silicon carbide component shortages:Power quality sensors rely on SiC substrates concentrated in Taiwanese and Japanese foundries, creating 16-24 week lead times for high-precision current transformers.
- Cybersecurity certification friction:IEC 62443 compliance timelines for industrial control systems extend deployment cycles by 8-14 months in regulated sectors.
- Legacy protocol fragmentation:Proprietary Modbus and Profibus installations in brownfield manufacturing plants obstruct seamless integration with IP-based monitoring platforms.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Production-linked subsidies for electronics and automotive sectors are driving greenfield facility construction requiring integrated power and environmental monitoring.
- Carbon accounting software convergence:Power monitoring data feeds directly into Scope 2 emissions reporting platforms, creating bundled service opportunities for energy service companies.
- Microgrid islanding applications:Industrial campuses in Texas and California are deploying distributed energy resource management systems with embedded power quality analytics.
Industry Challenges
- Field commissioning complexity:Three-phase network configuration demands certified electrical engineers, with talent scarcity concentrated in Midwestern US manufacturing corridors and Eastern European industrial zones.
- Interoperability testing burden:Multi-vendor deployments require protocol gateway validation that consumes 20-30% of project implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Power Monitoring System Market |
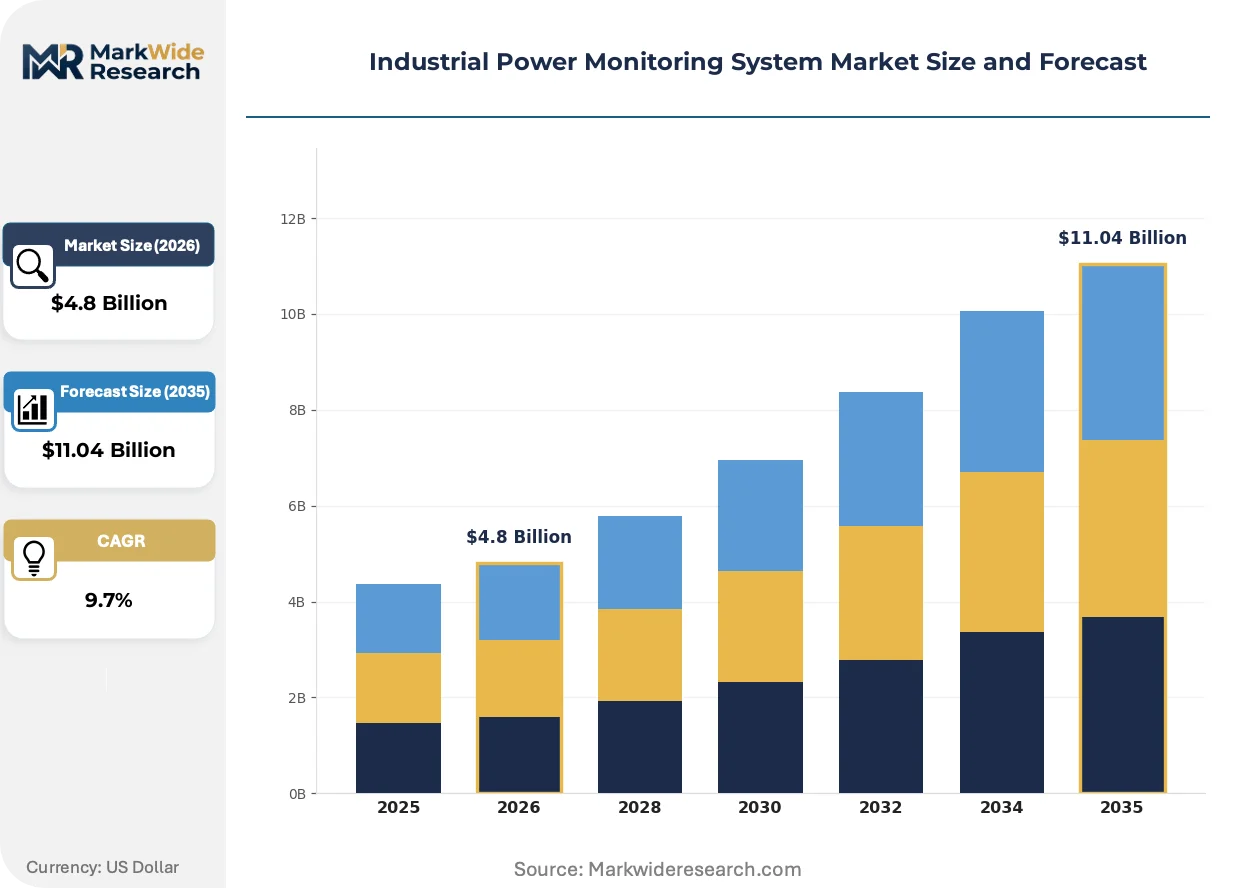
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Devices, Software Solutions, Control Panels, Sensors End User: Manufacturing Plants, Data Centers, Utilities, Oil & Gas Technology: IoT Platforms, Cloud Computing, Edge Computing, SCADA Application: Energy Management, Process Optimization, Equipment Monitoring, Demand Response |
| Companies Covered | Schneider Electric SE, ABB Ltd, Siemens AG, Eaton Corporation PLC, Emerson Electric Co., General Electric Company, Rockwell Automation, Inc., Honeywell International, Inc., Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Power Monitoring System Market Shifts & Advancements
Digital twin architectures are redefining how industrial operators simulate electrical network behavior before physical deployment, compressing commissioning risk and enabling predictive scenario modeling.
Edge-native power analytics with embedded machine learning inference engines is rendering obsolete centralized SCADA architectures that relied on polling-based data aggregation. Semiconductor fabs and battery gigafactories in Germany and South Korea are adopting these systems at 40% faster replacement cycles than process industries. The shift collapses hardware margin pools while expanding recurring software revenue streams.
The EU F-Gas Regulation mandates refrigerant leak detection integrated with electrical load monitoring for compliance documentation. Industrial cold storage operators must install continuous environmental and power quality surveillance to satisfy audit requirements. German chemical and food processing facilities are responding by consolidating vendor relationships to reduce integration complexity.
Energy-as-a-service contracting is displacing capital purchase models for monitoring infrastructure. Large manufacturing groups in the US Midwest now procure power analytics through performance-based agreements where vendors retain hardware ownership. This restructuring concentrates buyer power among industrial real estate investment trusts and contract manufacturing organizations.
Industrial Power Monitoring System Market Segmentation
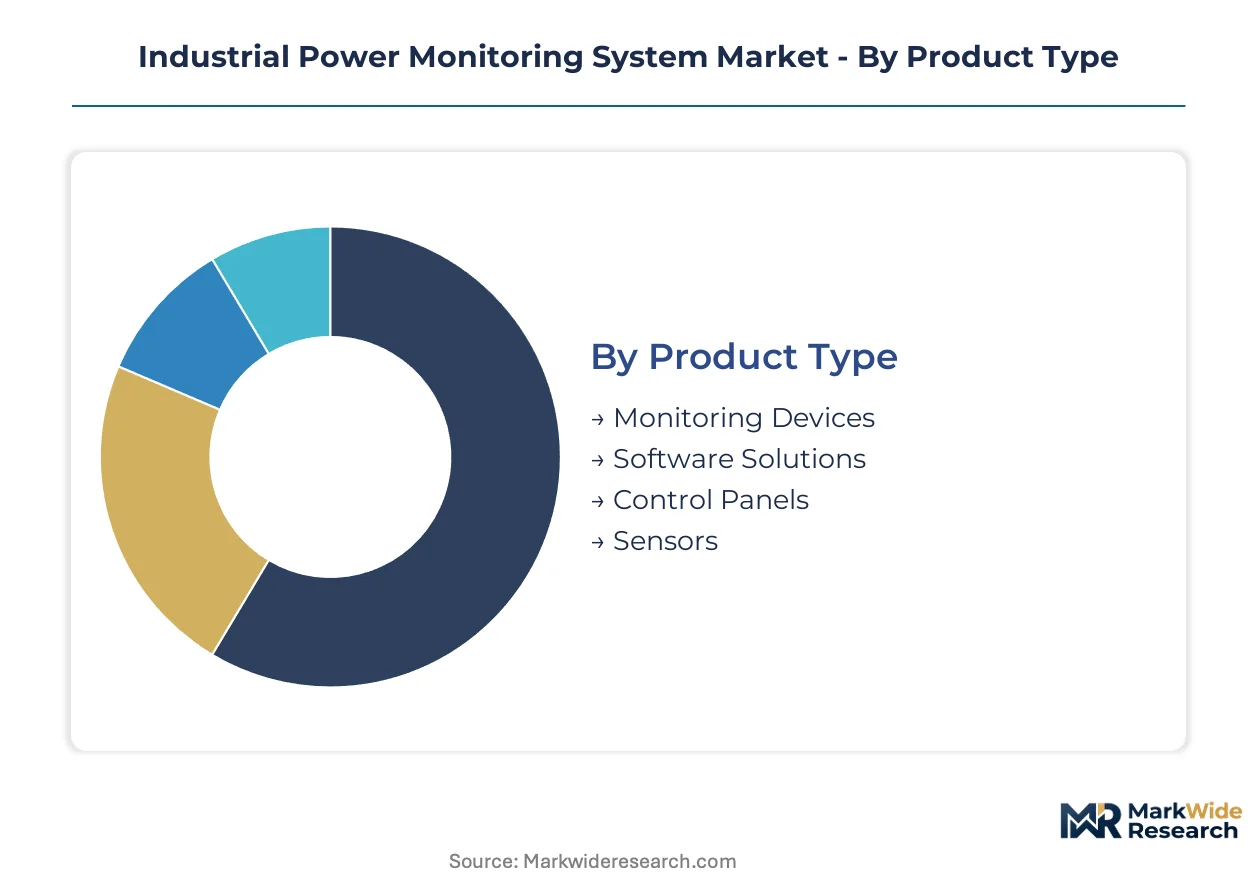
Industrial power monitoring systems serve divergent operational requirements across voltage classes, latency tolerances, and integration depths. Segmentation reveals where hardware commoditization pressures concentrate versus where software and edge-native architectures command premium positioning.
Product Type:
Product selection tracks the facility's digital maturity and the balance between capital deployment flexibility versus operational control.
- Monitoring Devices:Intelligent electronic devices with three-phase measurement capabilities form the physical sensing layer. Demand concentrates in German automotive and chemical complexes where EU Green Deal audit mandates require certified power quality documentation at distribution board level.
- Software Solutions:Analytics platforms delivering predictive maintenance algorithms and tariff optimization engines. Data center operators in Northern Virginia and Frankfurt are expanding subscriptions fastest as density-driven thermal constraints demand real-time load balancing visualization.
- Control Panels:Human-machine interface assemblies for localized operator oversight. Brownfield manufacturing corridors in the US Midwest retain these for legacy SCADA integration.
- Sensors:Current transformers and voltage transducers with silicon carbide substrates. Taiwanese foundry bottlenecks are extending procurement cycles for high-precision variants.
The dominant share belongs to Monitoring Devices, while Software Solutions is closing the gap fastest.
End User:
End user economics vary sharply between continuous process industries with high availability premiums and batch operations with interruptible load profiles.
- Manufacturing Plants:Discrete and process manufacturing facilities with multi-shift operations. Semiconductor fabs in South Korea and battery gigafactories in Germany are replacing SCADA architectures at accelerated cycles.
- Data Centers:Hyperscale and colocation facilities managing density-driven electrical and thermal constraints. Singapore and Northern Virginia operators deploy substation-level monitoring to track power usage effectiveness.
- Utilities:Grid operators and distribution companies modernizing feeder automation. German utilities leverage certified partner networks for retrofit deployments.
- Oil & Gas:Upstream and downstream facilities with hazardous area classification requirements. EPA greenhouse gas reporting rules compel continuous monitoring infrastructure for compliance documentation.
Manufacturing Plants retain the largest installed base, though Data Centers demonstrate the steepest expansion trajectory.
Technology:
Technology selection hinges on latency requirements, data sovereignty constraints, and the trade-off between capital intensity and operational agility.
- IoT Platforms:IP-connected sensor networks with cloud-native data aggregation. Indian electronics manufacturing zones under PLI scheme incentives are adopting these for greenfield facility commissioning.
- Cloud Computing:Centralized analytics with elastic compute scaling. Carbon accounting convergence is driving bundled service opportunities for energy service companies.
- Edge Computing:Localized inference engines with sub-10 millisecond response times. Pharmaceutical cold chain and semiconductor fabrication demand this for critical power applications.
- SCADA:Traditional polling-based architectures with proprietary protocol stacks. Legacy Modbus and Profibus installations obstruct seamless integration with modern platforms.
Edge Computing commands the fastest adoption velocity, while SCADA retains substantial legacy lock-in.
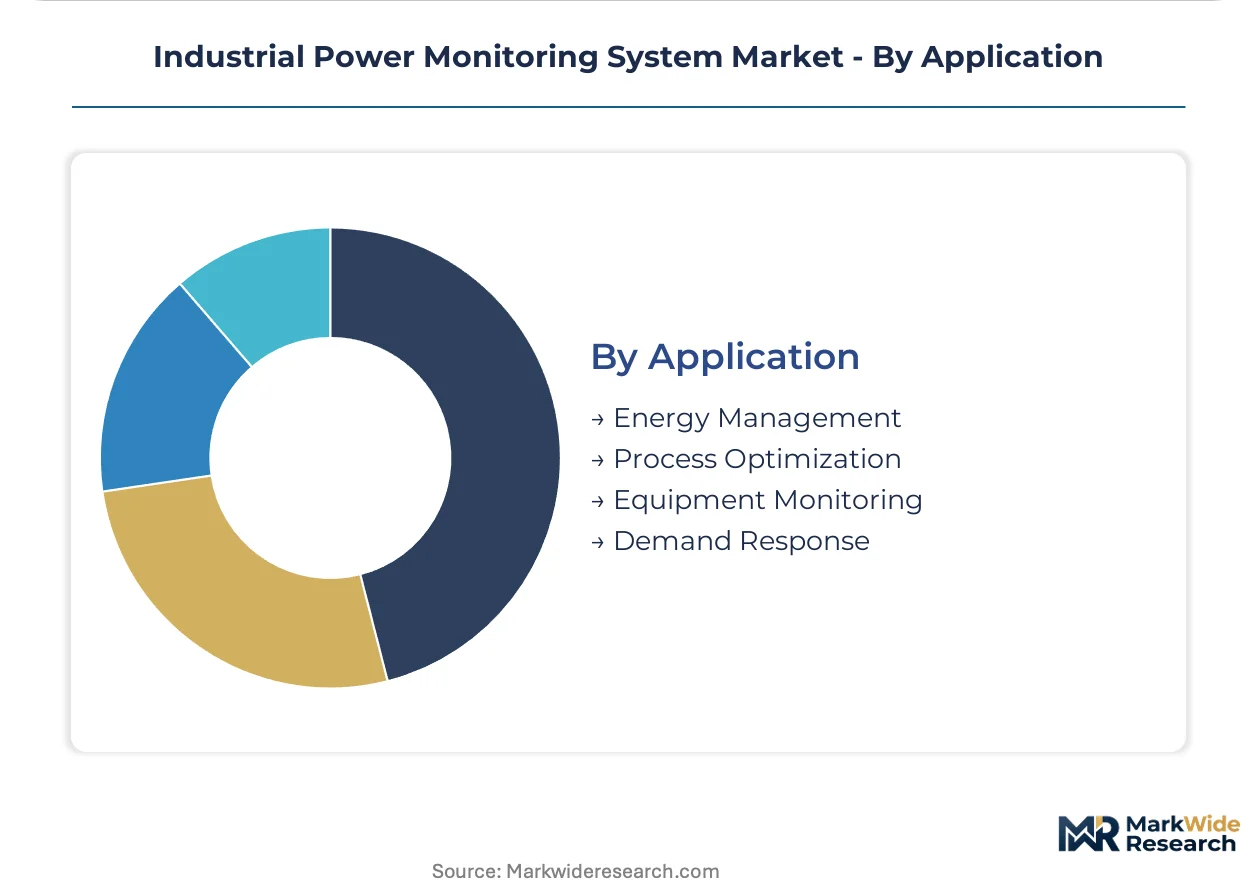
Application:
Application prioritization reflects whether facilities optimize for cost reduction, asset protection, or grid-interactive revenue streams.
- Energy Management:Load profiling and tariff optimization for demand charge reduction. Industrial real estate investment trusts procure these through energy-as-a-service contracts.
- Process Optimization:Power quality correlation with production yield metrics. German chemical facilities integrate this with F-Gas Regulation compliance documentation.
- Equipment Monitoring:Predictive maintenance algorithms for transformer and motor health. Battery gigafactories deploy these to prevent thermal runaway conditions.
- Demand Response:Grid-interactive load modulation for ancillary service revenue. Texas and California industrial campuses with microgrid islanding capabilities leverage this.
Energy Management holds the dominant deployment share, while Demand Response is gaining traction fastest in deregulated electricity markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's centrality in European industrial power monitoring demand, connecting Bavarian manufacturing clusters to North Sea ports and enabling just-in-time component logistics for facility retrofit cycles.
Germany
Automotive electrification and chemical process digitization drive hardware and software upgrades across Baden-Württemberg and North Rhine-Westphalia. The EU Green Deal mandates binding energy audits that require certified power quality documentation at distribution board level. Siemens AG leverages certified partner networks to dominate utility retrofit deployments in the Frankfurt-Rhine-Main metropolitan region.
United States
Hyperscale data center construction in Northern Virginia and semiconductor fab expansion in Arizona create substation-level monitoring demand for density-driven thermal management. OSHA electrical safety standards and EPA greenhouse gas reporting rules compel continuous monitoring infrastructure for compliance documentation. The Permian Basin oil patch and Gulf Coast petrochemical corridor require hazardous area classification systems.
China
Battery gigafactory construction in the Yangtze River Delta and Fujian province accelerates three-phase monitoring deployment for thermal runaway prevention. The MIIT dual carbon goals and GB standards for industrial energy consumption mandate granular power measurement across state-owned steel and cement complexes. Shenzhen electronics manufacturing zones under electronics industry stimulus programs adopt IP-connected sensor networks for greenfield commissioning.
India
Production-linked incentive schemes for electronics and automotive sectors drive greenfield facility construction requiring integrated power and environmental monitoring in Tamil Nadu and Gujarat. The CEA grid code amendments and Bureau of Energy Efficiency mandates strengthen enforcement of continuous energy consumption tracking. The Delhi-Mumbai Industrial Corridor and Bangalore-Tumkur electronics cluster anchor deployment concentration.
South Korea
Semiconductor fabrication capacity expansion in Pyeongtaek and Yongin demands sub-10 millisecond edge analytics for critical power applications. METI-aligned industrial efficiency programs and KOSHA electrical safety standards enforce predictive maintenance infrastructure. The Gyeonggi-do province battery materials complex and Ulsan petrochemical hub represent concentrated end-user demand.
Industrial Power Monitoring System Market Competitive Landscape
On the supply side, the industry is consolidating around platform-centric vendors with certified partner ecosystems, compressing margins for pure hardware manufacturers while elevating software-native entrants. Three archetypes dominate: diversified electrical equipment conglomerates with end-to-end portfolios, automation specialists with process industry expertise, and emerging edge-native analytics pure-plays. Strategic moves center on M&A for protocol gateway capabilities and vertical integration into silicon carbide sensor substrates.
Within the diversified equipment tier, Schneider Electric SE and ABB Ltd exemplify platform-centric positioning through subscription-anchored energy management suites. Siemens AG occupies a distinct position in German-speaking utility retrofit markets through legacy infrastructure relationships. These three conglomerates represent the dominant competitive anchors against which mid-tier specialists and edge-native challengers define differentiation strategies.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Siemens AG |
| Eaton Corporation PLC |
| Emerson Electric Co. |
| General Electric Company |
| Rockwell Automation, Inc. |
| Honeywell International, Inc. |
| Yokogawa Electric Corporation |
| Others |
Supply & Pricing Matrix
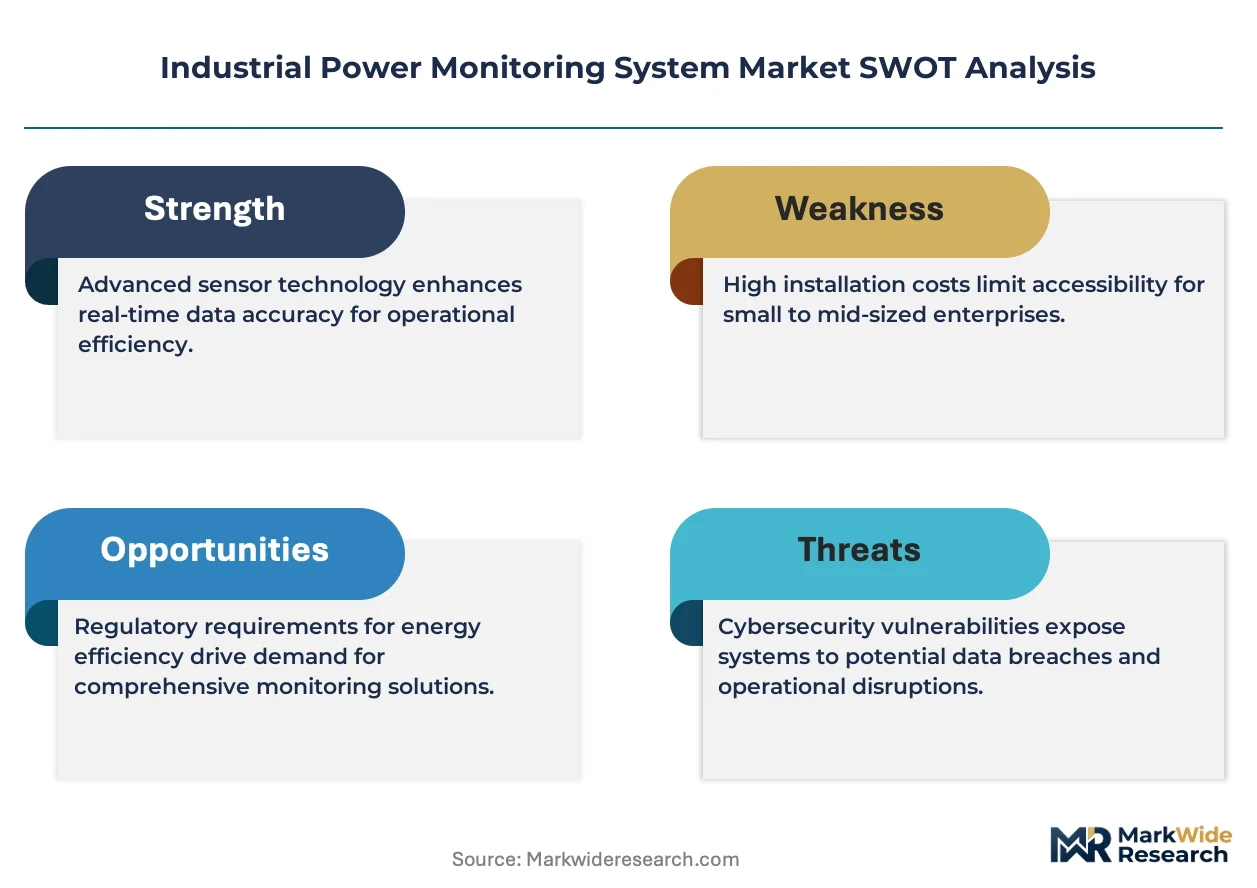
Taiwanese silicon carbide foundry concentration for high-precision current transformers anchors margin capture at the sensor substrate tier, forcing downstream vendors to absorb procurement volatility or cede position to integrated conglomerates with captive supply arrangements.
Pricing Analysis
Volume-discount tiering separates enterprise SaaS subscriptions from per-device transactional hardware sales. Certification grade under IEC 62443 and customization depth for brownfield protocol integration drive price differentiation. Pricing pressure stems from hardware commoditization as edge-native software claims recurring revenue streams. Data center operators demonstrate lowest price sensitivity due to density-driven thermal constraints, while Midwestern US manufacturing plants resist subscription migration.
Supply Chain Analysis
Export-control regimes restricting semiconductor manufacturing equipment flows to Chinese battery gigafactories are rerouting component sourcing through South Korean and Japanese channels. Taiwanese foundries and Japanese substrate suppliers anchor silicon carbide sensor production. Supply chain risk centers on single-source vulnerability for SiC wafers. Distribution runs through certified system integrator networks in Germany and energy service companies in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through IEC 62443 certification timelines and proprietary protocol integration creates structural switching costs that protect incumbent positions.
For Market Incumbents: Insulate core revenue by deepening backward integration into silicon carbide sensor substrates and securing exclusive distribution through German certified partner networks. Edge-native analytics pure-plays threaten software margin pools. Vertical control over Taiwanese foundry relationships serves as the priority defensive lever. For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat electronics manufacturing corridors offer underpenetrated greenfield deployment opportunities under PLI scheme incentives. Pharmaceutical cold chain applications in South Korea demand sub-10 millisecond edge analytics where incumbent SCADA architectures face replacement pressure. Target energy-as-a-service contracting models to bypass capital purchase resistance among Midwestern industrial real estate trusts. For Investors and Strategic Acquirers: Capital is best deployed toward edge-native analytics pure-plays with embedded machine learning inference engines and established protocol gateway validation capabilities. Long-term viability rests on software subscription recurrence rather than hardware replacement cycles. Watch for accelerated SCADA displacement signals in South Korean semiconductor fabrication facilities as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Captive supply of silicon carbide wafers from Taiwanese foundries insulates against 16-24 week lead time volatility. |
| Protocol Gateway Acquisition | Modbus and Profibus translation capabilities compress brownfield integration timelines for European manufacturing retrofits. |
| Edge-Native Platform Launch | Sub-10 millisecond inference engines displace polling-based SCADA in German battery gigafactory deployments. |
| Energy-as-a-Service Partnership | Performance-based agreements with Midwestern industrial real estate trusts bypass capital budget constraints. |
| Certified Partner Network Expansion | Siemens-style utility retrofit positioning in Frankfurt-Rhine-Main metropolitan region accelerates German market penetration. |
Research Methodology
Cross-validation between primary interviews with plant engineers, energy service company procurement leads, and system integrator technical directors and secondary validation through SEC filings, EIA power consumption data, and EU Green Deal implementation reports anchors the qualitative findings. Bottom-up facility deployment tracking and top-down industrial energy consumption aggregates enable triangulation.
Calibration against historical SCADA replacement cycles and edge computing adoption curves in semiconductor fabrication informs the analytical framework across the projection horizon. Segmentation dimensions span voltage class, latency tolerance, deployment architecture, and end-user digital maturity. CAGRs derive from facility retrofit cycle compression rates and software subscription conversion velocity in data center and manufacturing verticals.
Practitioners should monitor silicon carbide foundry capacity expansion and IEC 62443 certification timeline compression for early signals. Forecasts reflect assumptions about EU Green Deal enforcement continuity and hyperscale data center construction trajectories. Material shifts in Taiwanese semiconductor export controls or German grid modernization funding would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Europe Water Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Digital Water Meters Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
North America Gas Meter Market