
 Ozone Generator Market | 2026-2036
Ozone Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Ozone Generator Market Analysis
Chinese electrolytic cell manufacturers are broadening output capacity for large-scale ozone systems. SUEZ Water Technologies & Solutions leverages its water treatment engineering footprint across European utility contracts. Xylem sustains competitive positioning through vertical integration into pump and disinfection system portfolios. Mitsubishi Electric Corporation anchors regional supply chains with corona discharge expertise in Japanese industrial markets.
An ozone generator produces ozone gas through electrical discharge across a dielectric gap, typically generating concentrations between 1-10 weight percent for industrial oxidation processes. The device serves primarily to disinfect water, degrade organic contaminants, and neutralize airborne pathogens without persistent chemical residuals. Industrial Systems dominate capital deployment due to scale requirements in municipal water infrastructure, while Corona Discharge technology leads installed capacity because of its energy efficiency at high throughput volumes. Portable Units occupy a narrower margin pool serving commercial remediation and healthcare spot-treatment applications where mobility outweighs unit economics.
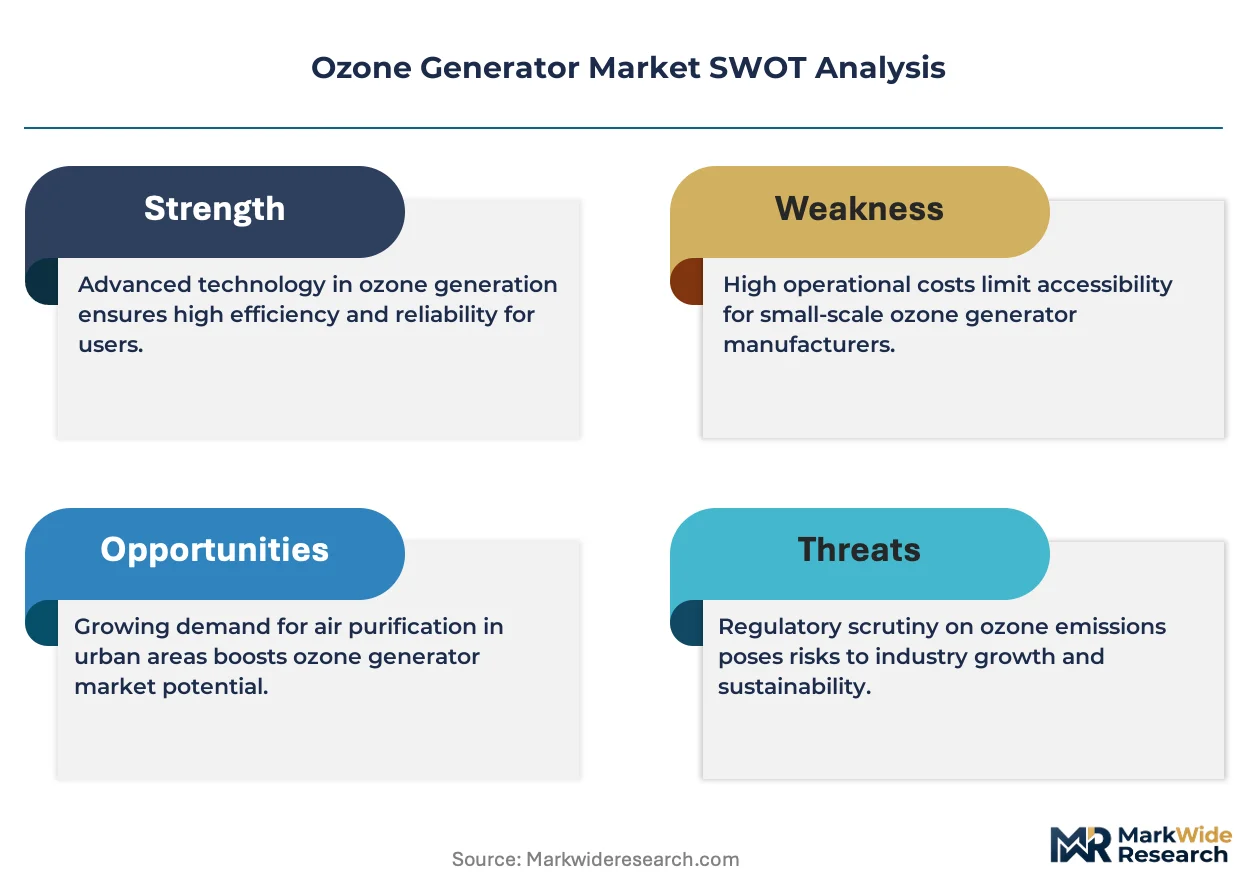
The US EPA Safe Drinking Water Act and EU Drinking Water Directive shape product certification requirements for municipal procurement across North American and European jurisdictions. China's MEE enforces effluent standards that mandate advanced oxidation for pharmaceutical and chemical manufacturing discharge. Japan's METI promotes ozone heat pump integration through efficiency benchmarks tied to industrial decarbonization roadmaps. Stakeholders must weigh electrolysis technology maturation against corona discharge economies of scale when committing to next-generation platform investments.
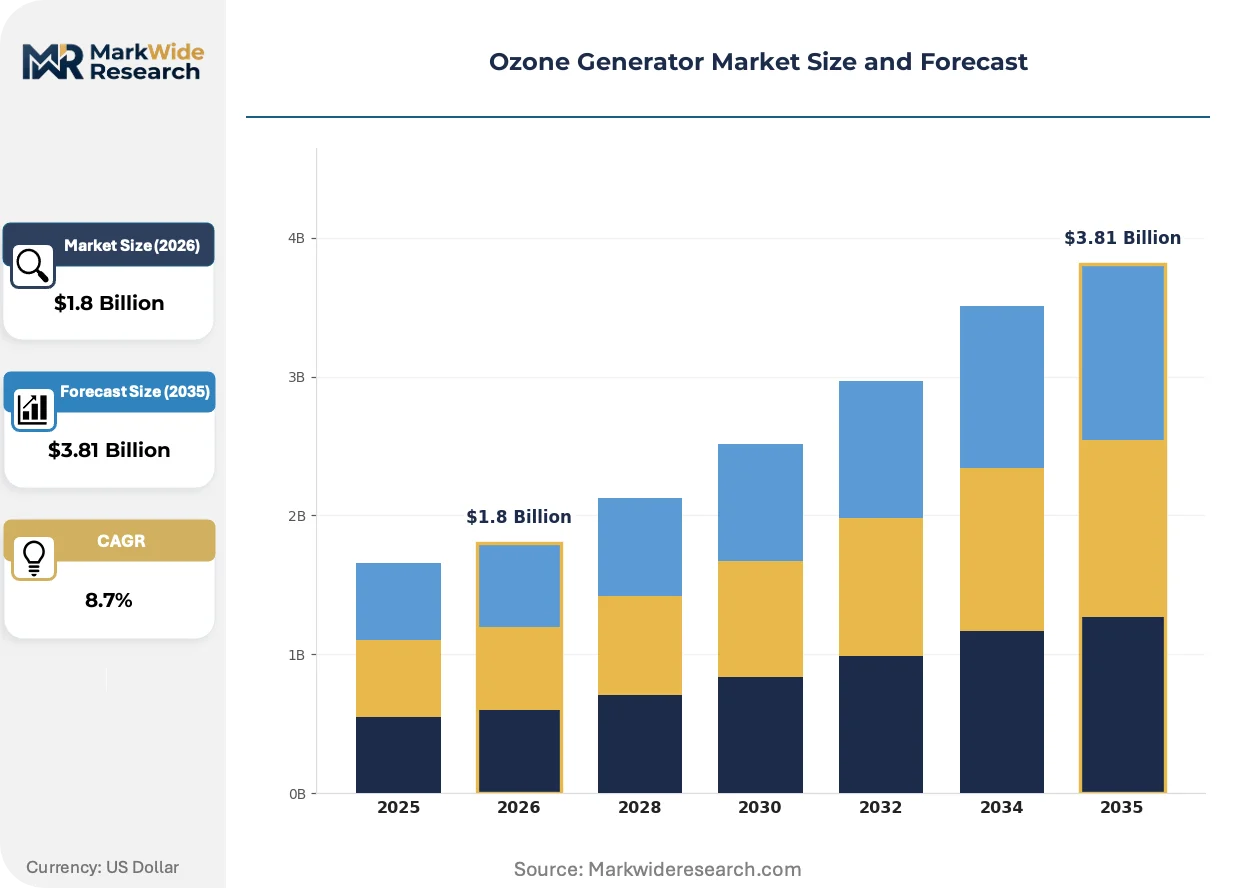
Market Dynamics
The ozone generator market is being restructured by China's dual carbon goals, which redirect industrial procurement toward energy-efficient corona discharge systems and away from legacy electrolytic platforms with higher energy intensity.
Growth Catalysts
- Stricter Drinking Water Standards:Germany's municipal water treatment utilities are expanding ozone adoption to meet tighter EU Drinking Water Directive thresholds for disinfection byproduct control.
- Industrial Decarbonization Mandates:Japan's METI efficiency benchmarks promote ozone heat pump integration across chemical manufacturing facilities.
- Electrolytic Cell Capacity Expansion:Chinese manufacturers are scaling output for large-scale ozone systems serving pharmaceutical effluent treatment under MEE discharge standards.
Market Restraints
- Platinum Group Metal Input Costs:Electrolytic ozone generators depend on iridium-coated anodes, exposing manufacturers to volatile PGM commodity markets.
- Supply Concentration Risk:Dielectric barrier discharge tube production clusters in East Asian manufacturing hubs create single-source vulnerability for European system integrators.
- Technical Limitation in Low-Concentration Applications:Corona discharge systems struggle to achieve sub-1% ozone concentrations economically, limiting penetration in sensitive food processing applications.
Strategic Opportunities
- Underpenetrated Pharmaceutical Manufacturing:India's CDMO sector shows minimal ozone adoption for active pharmaceutical ingredient synthesis despite stringent effluent norms from the central pollution control framework.
- Technology Convergence:Integration of UV-ozone hybrid systems is opening municipal contracts where single-technology bids previously dominated.
- Distribution Innovation:Equipment-as-a-service models are displacing capital purchase in North American commercial remediation, with service providers retaining asset ownership.
Industry Challenges
- Specialized Field Engineering Gap:Commissioning large-scale municipal ozone systems requires rare expertise in dielectric gap calibration and off-gas destruction system integration.
- Capex Intensity for Utility-Scale Projects:Contact vessel construction and oxygen feed systems require substantial upfront investment, stretching municipal procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ozone Generator Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Industrial Systems, Residential Units, Aquaculture Applications Technology: UV Light, Corona Discharge, Electrolysis, Cold Plasma Application: Water Treatment, Air Purification, Wastewater Management, Food Processing End User: Municipalities, Food & Beverage, Healthcare Providers, Residential Consumers |
| Companies Covered | SUEZ Water Technologies & Solutions, Xylem, Mitsubishi Electric Corporation, Ebara Corporation, MKS Instruments, Daikin Industries, Industrie De Nora, METAWATER, Ozonetech Systems OTS AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ozone Generator Market Emerging Trajectories
Active transformation in the ozone generator market centers on energy efficiency imperatives, regulatory tightening around disinfection byproducts, and evolving procurement structures that favor operational expenditure models over capital deployment.
Corona discharge technology is consolidating its position as the dominant industrial platform through continuous dielectric material improvements and modular system architectures. Municipal water utilities in Japan and Germany are standardizing procurement specifications around high-frequency power supply configurations. This technology trajectory is compressing market space for electrolytic alternatives in applications above 5 kg per hour ozone demand.
The EU F-Gas Regulation is accelerating phase-out of refrigerants with high global warming potential, indirectly boosting ozone-based cooling system adoption in industrial heat pump applications. Chemical manufacturers face compliance deadlines that favor ozone integration over conventional compression cooling. German industrial facilities are responding fastest, with ozone heat pump installations expanding in Rhine-Ruhr manufacturing clusters.
Contracting structures are evolving from equipment purchase toward performance-guaranteed service agreements. Municipal utilities now favor vendors assuming operational risk for disinfection efficacy and energy consumption. This shift is most visible in East Asian manufacturing clusters, where state-owned water treatment operators prioritize budget predictability over asset ownership.
Ozone Generator Market Segmentation
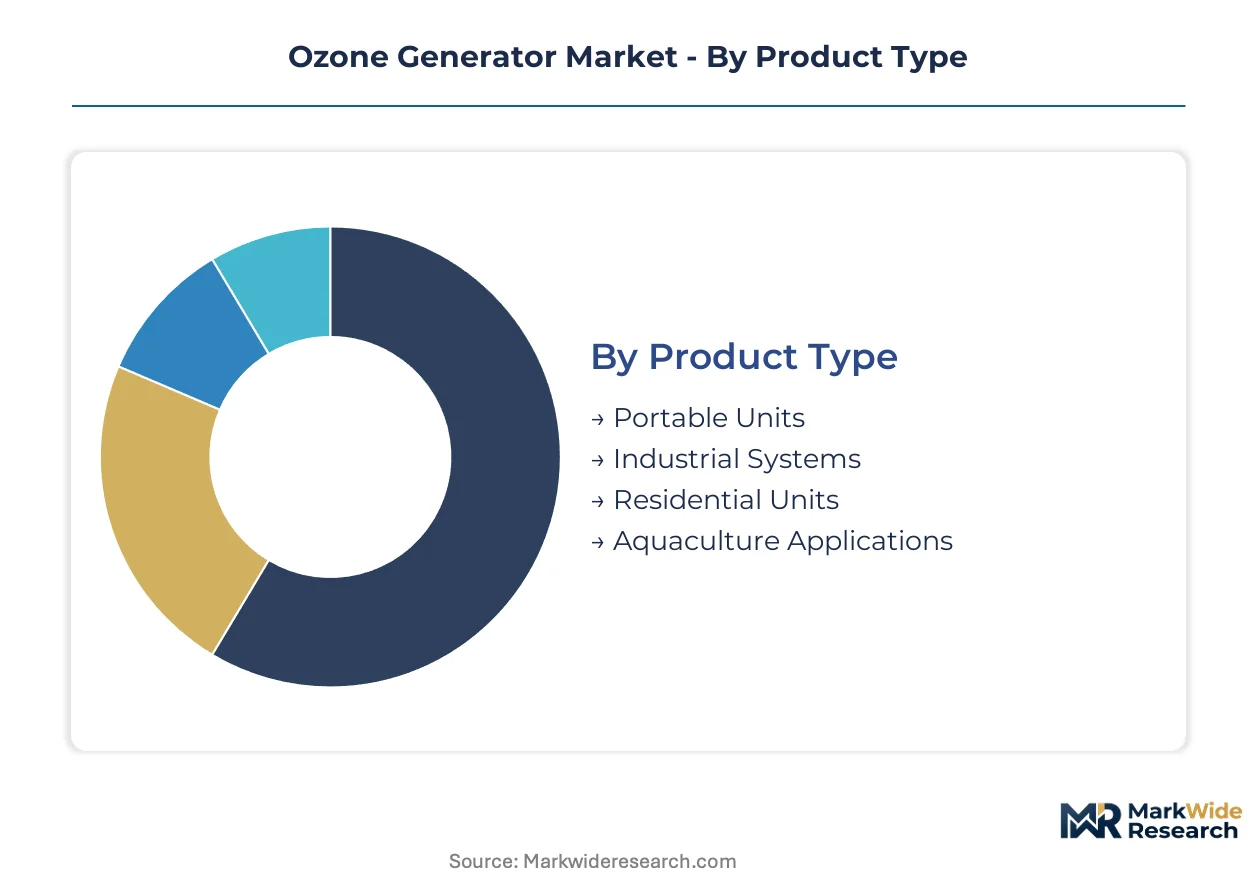
Ozone generator segmentation reveals distinct procurement patterns between standalone point-of-use units and integrated infrastructure systems. Equipment specification, energy intensity, and service architecture vary sharply across product tiers and technology platforms.
Product Type:
Standalone portable units serve spot-treatment needs with minimal integration requirements, while industrial systems embed into centralized water and air handling infrastructure with substantial civil works and control system interfaces.
- Industrial Systems:These configurations generate ozone at scale through corona discharge or electrolytic cells, typically producing 5 kg per hour or more for municipal contact basins and pharmaceutical oxidation reactors. German municipal utilities and Japanese chemical manufacturers anchor procurement volume under tightening EU Drinking Water Directive and METI efficiency benchmarks.
- Portable Units:Compact, mobile generators deploy ozone at 1-10 grams per hour for commercial remediation, healthcare surface disinfection, and emergency response scenarios. Demand clusters in North American commercial service providers where equipment-as-a-service models displace capital purchase.
- Residential Units:Small-scale systems integrate into home water treatment lines and air purification setups, typically employing UV or low-output corona discharge at sub-gram hourly rates.
- Aquaculture Applications:Specialized units maintain dissolved ozone levels in recirculating aquaculture systems for pathogen control and water quality management in intensive fish farming operations.
Volume placements concentrate in Industrial Systems; the faster expansion belongs to Portable Units.
Technology:
Energy efficiency separates competitive positioning, with high-frequency power supply configurations commanding premium positioning against legacy electrolytic platforms.
- Corona Discharge:Dielectric barrier discharge across a gap between electrodes generates ozone at 6-10 weight percent concentration with superior energy efficiency above 5 kg per hour throughput. Chinese procurement under dual carbon goals and German utility standardization drive platform consolidation.
- Electrolysis:Direct water electrolysis through iridium-coated anodes produces high-purity ozone without feed gas preparation, though platinum group metal input costs create margin volatility. Japanese industrial markets retain preference for electrolytic integration with heat pump systems.
- UV Light:Mercury vapor lamps photolyze oxygen at lower concentrations, suiting small-scale residential and commercial applications where capital cost outweighs operating efficiency.
- Cold Plasma:Non-equilibrium plasma discharge at ambient temperatures enables emerging applications in sensitive food processing where thermal degradation risks constrain alternatives.
Installed capacity concentrates in Corona Discharge; Electrolysis retains defensive positioning in pharmaceutical-grade applications.
Application:
Regulatory stringency varies by end-use, with drinking water and pharmaceutical discharge standards mandating validated oxidation performance against less stringent commercial air treatment specifications.
- Water Treatment:Municipal drinking water disinfection and process water conditioning dominate capital deployment, with contact vessel engineering and off-gas destruction systems representing substantial project scope. Germany and Japan lead infrastructure renewal cycles.
- Wastewater Management:Advanced oxidation processes degrade refractory organics in pharmaceutical and chemical manufacturing effluent under China's MEE discharge standards and EU Industrial Emissions Directive requirements.
- Air Purification:Commercial and industrial HVAC integration neutralizes airborne pathogens and volatile organic compounds in healthcare, hospitality, and food service environments.
- Food Processing:Surface sanitation and storage atmosphere modification extend shelf life in meat, produce, and beverage operations, with sub-1% concentration requirements favoring UV and cold plasma alternatives.
Capital deployment concentrates in Water Treatment; Wastewater Management is climbing the fastest under industrial effluent tightening.
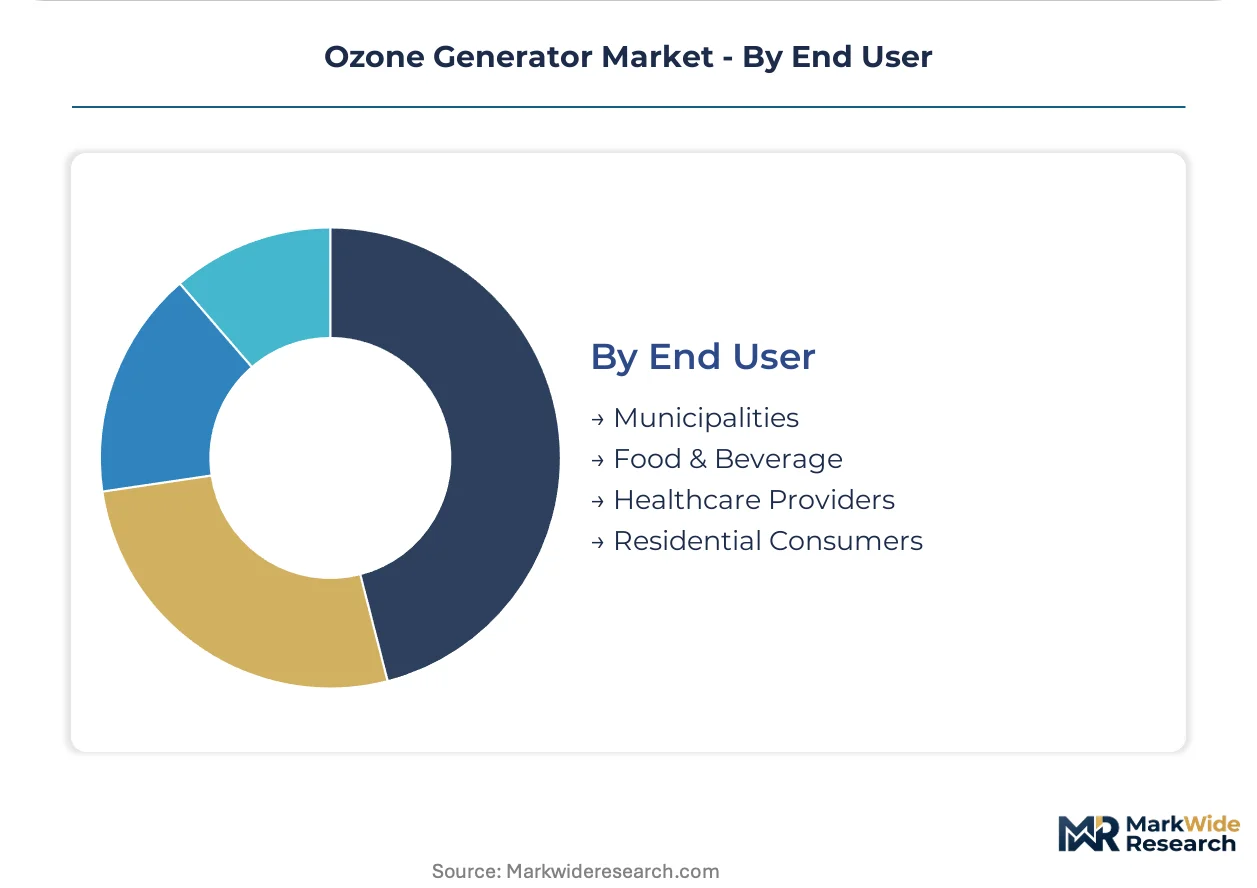
End User:
Procurement sophistication diverges between municipal tender processes with multi-year validation requirements and commercial spot purchasing driven by immediate operational needs.
- Municipalities:Water treatment utilities specify ozone systems through competitive bidding with performance guarantees for disinfection efficacy, energy consumption, and residual byproduct control. EU Drinking Water Directive and US EPA Safe Drinking Water Act shape certification requirements.
- Food & Beverage:Processors deploy ozone for CIP systems, bottle rinsing, and cold storage atmosphere management, with hygiene validation protocols driving equipment selection.
- Healthcare Providers:Hospitals and long-term care facilities employ ozone for surface disinfection, laundry sanitation, and HVAC pathogen control, particularly in infection-sensitive wards.
- Residential Consumers:Point-of-entry water treatment and standalone air purifiers represent discretionary purchase with limited technical specification depth.
Contract value concentrates in Municipalities; Food & Beverage is gaining share fastest through process integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal deposits in South Africa and Russia anchor upstream supply chains for electrolytic anode coatings, while dielectric barrier discharge tube fabrication concentrates in East Asian electronics manufacturing clusters.
China
Dual carbon goals redirect procurement toward energy-efficient corona discharge systems for pharmaceutical effluent treatment. MEE discharge standards mandate advanced oxidation for chemical manufacturing. Yangtze River Delta manufacturers scale electrolytic cell output for large-scale municipal contracts.
Germany
Municipal utilities expand ozone adoption under tightened EU Drinking Water Directive thresholds for disinfection byproduct control. The F-Gas Regulation accelerates ozone heat pump integration in Rhine-Ruhr industrial facilities. North Rhine-Westphalia anchors procurement volume for utility-scale contact vessel projects.
Japan
METI efficiency benchmarks promote ozone heat pump integration across chemical manufacturing. Industrial decarbonization roadmaps favor corona discharge with high-frequency power supplies. Kansai manufacturing clusters standardize procurement specifications for validated oxidation performance.
United States
EPA Safe Drinking Water Act certification requirements shape municipal procurement for disinfection efficacy. Equipment-as-a-service models displace capital purchase in commercial remediation markets. Texas and California utilities drive infrastructure renewal cycles with performance-guaranteed contracts.
India
CDMO sector shows minimal ozone adoption for active pharmaceutical ingredient synthesis despite central pollution control effluent norms. Central Pollution Control Board mandates remain unevenly enforced across manufacturing states. Maharashtra and Gujarat pharmaceutical clusters represent underpenetrated demand for validated oxidation systems.
Ozone Generator Market Vendor Landscape
Global majors compete with regional champions across engineering depth and utility relationship density. The vendor base separates into three tiers: integrated water technology conglomerates with vertical control over pump and disinfection portfolios, specialized ozone system fabricators with captive dielectric barrier discharge expertise, and regional equipment-as-a-service operators capturing commercial spot-treatment demand. Consolidation pressure concentrates among mid-scale system integrators lacking oxygen feed system capabilities or off-gas destruction engineering depth. Strategic moves center on backward integration into dielectric material supply and geographic expansion through municipal utility framework agreements.
Within the integrated water technology tier, SUEZ Water Technologies & Solutions and Xylem exemplify global positioning through captive engineering footprints across European utility contracts. Mitsubishi Electric Corporation anchors regional supply chain concentration with corona discharge specialization in Japanese industrial markets. These three represent divergent archetypes: the European utility-focused integrator, the North American vertically structured water technology platform, and the Asia-Pacific industrial oxidation specialist.
| Leading Market Players |
|---|
| SUEZ Water Technologies & Solutions |
| Xylem |
| Mitsubishi Electric Corporation |
| Ebara Corporation |
| MKS Instruments |
| Daikin Industries |
| Industrie De Nora |
| METAWATER |
| Ozonetech Systems OTS AB |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals gate qualified supply and premium-tier pricing access, as energy-efficient corona discharge systems command procurement preference over legacy electrolytic platforms. Municipal utilities in Germany and Japan now require validated oxidation performance guarantees that bundle after-sales service into long-term contracts, compressing margins for unbundled equipment-only vendors.
Pricing Analysis
Extended warranty and field engineering coverage increasingly separate premium bids from unbundled equipment-only alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and oxygen feed system integration depth. Cost compression in economy-tier portable units intensifies because Chinese manufacturers scale electrolytic cell output. Commercial remediation service providers show highest price sensitivity, while German municipal utilities prioritize lifecycle cost predictability over upfront capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with dielectric barrier discharge tube production clusters concentrated in China, South Korea, and Japan. Iridium-coated anodes draw from South African and Russian platinum group metal deposits, exposing manufacturers to commodity volatility. Tariff exposure runs through East Asian electronics manufacturing hubs serving European system integrators. Distribution runs through municipal tender processes with multi-year framework agreements and equipment-as-a-service operators capturing North American commercial spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ozone generator market functions as a vertical-integration race where captive dielectric material supply and oxygen feed system engineering depth determine competitive survival. Players are pursuing backward integration into high-frequency power supply manufacturing to secure margin control.
For Market Incumbents: Extend dielectric barrier discharge expertise into modular system architectures that reduce commissioning complexity for municipal utilities. Add captive oxygen concentrator production capacity in Rhine-Ruhr manufacturing clusters to defend against emerging Chinese electrolytic cell manufacturers. METI efficiency benchmarks and EU F-Gas Regulation compliance deadlines create urgency for integrated heat pump offerings.
For New Entrants and Emerging Players: Capture India's underpenetrated CDMO sector for active pharmaceutical ingredient synthesis oxidation systems, where central pollution control effluent norms remain unevenly enforced. Target Maharashtra and Gujarat pharmaceutical clusters with validated performance contracting that assumes operational risk for discharge compliance. Equipment-as-a-service models offer lower capital barriers to entry than utility-scale project bids.
For Investors and Strategic Acquirers: Japanese chemical manufacturers standardizing procurement specifications around high-frequency power supplies is the leading indicator that corona discharge platform consolidation will accelerate. Mid-scale system integrators lacking off-gas destruction engineering depth represent distressed acquisition targets. Watch for municipal framework agreement awards in North Rhine-Westphalia as inflection signals for European utility market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Materials | Captive supply of ceramic barrier tubes reduces single-source exposure to East Asian manufacturing clusters. |
| Long-term Municipal Framework Agreements | Multi-year German utility contracts under EU Drinking Water Directive lock in recurring service revenue streams. |
| Joint Venture for Heat Pump Integration | Partnerships with Japanese chemical manufacturers align with METI industrial decarbonization roadmaps. |
| Geographic Expansion into Indian CDMO Sector | Maharashtra pharmaceutical clusters show minimal ozone adoption despite central pollution control mandates. |
| Equipment-as-a-Service Model Launch | North American commercial remediation markets favor operational expenditure over capital deployment. |
Methodological Framework
Document review covered trade customs data, SEC filings from water technology conglomerates, and EU procurement registry databases, complemented by interviews with municipal utility engineering directors, pharmaceutical plant managers, and ozone system commissioning specialists. Primary fieldwork included discussions with dielectric material suppliers and oxygen feed system integrators. Secondary validation drew from MEE discharge standard filings, METI efficiency benchmark publications, and EPA Safe Drinking Water Act certification records. Bottom-up unit economics modeling and top-down sector sizing were triangulated against disclosed contract values.
Segment-level outputs across the analysis window reflect technology platform splits, application verticals, and end-user procurement sophistication tiers. The analytical framework modeled corona discharge versus electrolytic cell penetration rates, municipal versus commercial contracting structures, and regional regulatory enforcement variance. CAGRs were derived from installed capacity buildout trajectories and replacement cycle timing. Industry-specific forecast inputs included platinum group metal price volatility assumptions and F-Gas Regulation compliance deadline clustering.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese dual carbon goal enforcement intensity and EU Drinking Water Directive threshold revisions. Forecasts reflect assumptions around electrolytic cell cost curves and dielectric material supply expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market