
 Bin Vent Filter Market | 2026-2036
Bin Vent Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Bin Vent Filter Market Insights
Filter media replacement subscription programs is hardening into a core revenue stream for equipment vendors. Donaldson Company leverages its aftermarket logistics network to lock in recurring revenue from cement and mining clients. Baghouse America anchors its competitiveness on custom-engineered baghouse configurations for abrasive chemical environments. Camcorp specializes in integrated venting solutions that extend from filter supply to ductwork engineering.
A bin vent filter is a self-contained dust collection device mounted on storage silos, bins, and hoppers, typically operating at air-to-cloth ratios between 5:1 and 10:1 ft/min to capture fugitive particulates during material filling and discharge. Its primary purpose is to prevent dust emissions into the workplace and surrounding atmosphere while equalizing internal vessel pressure during pneumatic conveying operations. Bag filter configurations dominate in high-temperature cement applications where polyester and PTFE media withstand thermal stress, while cartridge filters are gaining ground in food processing and pharmaceutical facilities where compact footprints and rapid changeout matter more than absolute temperature tolerance. HEPA-grade bin vent installations remain niche but command premium positioning in pharmaceutical cleanroom material handling where FDA validation requirements apply.
EPA National Emission Standards for Hazardous Air Pollutants and OSHA Permissible Exposure Limits directly shape filter efficiency specifications and inspection frequencies in United States process industries. The EU Green Deal and associated Industrial Emissions Directive are tightening particulate discharge thresholds for European cement and chemical plants, forcing upgrades from standard bag filters to PTFE membrane configurations. Stakeholders must monitor how regional carbon border adjustments and emerging state-level air quality rules reshape total cost of ownership calculations across their installed base.
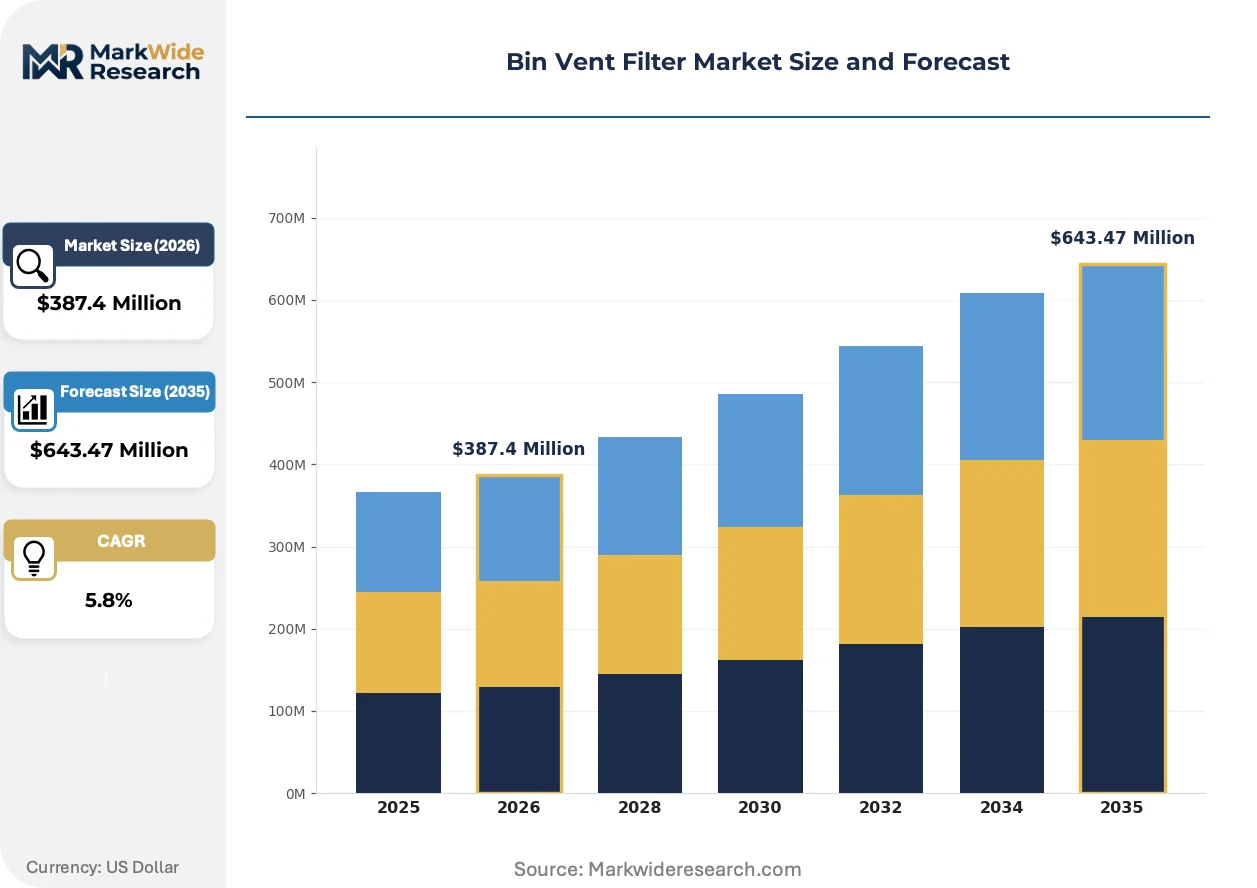
Market Dynamics
PTFE membrane media is compressing filter replacement cycles from 24 months to 12-18 months in cement applications, forcing vendors to rebuild revenue models around aftermarket subscription contracts rather than equipment sales alone.
Growth Catalysts
- OSHA Permissible Exposure Limits:Tightened silica dust thresholds in United States manufacturing are compelling bulk material handlers to upgrade from standard polyester bags to high-efficiency cartridge systems with automated pulse-cleaning.
- Carbon-intensive industries:Cement producers in Germany face EU Green Deal carbon border adjustments that treat fugitive dust emissions as reportable scope 1 liabilities, accelerating capital deployment toward sealed bin vent configurations.
- Pleated cartridge technology:Compact filter designs with 2-3x the surface area of conventional bags are penetrating food processing facilities where space constraints previously blocked dust collection retrofits.
Market Restraints
- Stainless steel housing costs:Acidic chemical environments require 316L stainless construction, which carries 40-60% raw material premiums over carbon steel and compresses project margins for mid-size integrators.
- Filter media supply concentration:Woven fiberglass and PTFE membrane production clusters in China create vulnerability to export license delays and tariff volatility for North American OEMs.
- Temperature ceiling limitations:Standard cartridge adhesives degrade above 200°F, excluding them from clinker cooling applications where baghouses with high-temperature felts remain mandatory.
Strategic Opportunities
- India's cement capacity expansion:The country's Bureau of Indian Standards is finalizing PM10 discharge limits for bulk material storage, creating first-mover advantage for vendors offering integrated venting and pneumatic conveying packages.
- Pharmaceutical containment integration:Isolator technology and bin vent filters are converging in potent compound handling suites where HEPA-grade venting must interface with closed transfer systems.
- Filter-as-a-service contracts:Predictive pressure-drop monitoring and automated media replenishment are displacing capital purchase models in multi-site food manufacturing chains.
Industry Challenges
- Combustible dust hazard assessment:NFPA 68 and 654 compliance requires facility-specific explosion protection documentation that extends sales cycles 4-6 months for chemical and metals processors.
- Legacy pneumatic system integration:Aging positive pressure conveying lines in 1970s-era grain elevators lack instrumentation ports, forcing costly structural modifications to accommodate modern vent filter installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bin Vent Filter Market |
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Panel Filter, Cartridge Filter, Bag Filter, HEPA Filter Application: Food Processing, Chemical Processing, Pharmaceuticals, Cement Manufacturing End User Industry: Mining, Construction, Agriculture, Manufacturing Plants Product Material: Polyester, Polypropylene, PTFE, Cellulose |
| Companies Covered | Donaldson Company, Baghouse America, Carmeuse Systems, Airex Industries, US Air Filtration, ACT Dust Collectors, Camcorp, Venturedyne, Cyclonaire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bin Vent Filter Market Trends and Innovations
Wireless differential pressure sensors and cloud-based filter monitoring are collapsing the information gap between equipment vendors and end-users, enabling predictive maintenance models that were technically impossible five years ago.
Smart cartridge filters with embedded RFID tags and IoT pressure transducers are decentralizing maintenance decision-making from centralized plant engineering to equipment OEMs who now receive real-time performance data. Cement producers in the United States are piloting these systems at 15-20 sites each, with vendors offering guaranteed uptime clauses that transfer operational risk from buyer to supplier. This telemetry infrastructure is compressing the traditional 12-month inspection cycle toward continuous remote diagnostics.
The EU Industrial Emissions Directive's 2024 amendment tightens Best Available Technique reference levels for particulate matter from 20 mg/Nm³ to 10 mg/Nm³ across cement, lime, and minerals processing. German and Polish facilities are responding with membrane-bag hybrid configurations that combine PTFE surface filtration with woven fiberglass structural support. Chemical plants in the Netherlands face parallel pressure from the National Emission Guidelines for Air, forcing comparable upgrades in phthalic anhydride and titanium dioxide handling operations.
Equipment leasing with bundled media replacement is displacing outright purchase in mid-cap food and chemical processors who prioritize operational expenditure predictability over capital ownership. Distributors in the United Kingdom and France are building captive service teams to capture recurring revenue streams that OEMs previously dominated. This channel evolution is most pronounced in dairy powder and infant formula manufacturing, where FDA and EFSA validation requirements make single-source vendor relationships preferable to multi-supplier procurement fragmentation.
Bin Vent Filter Market Segmentation
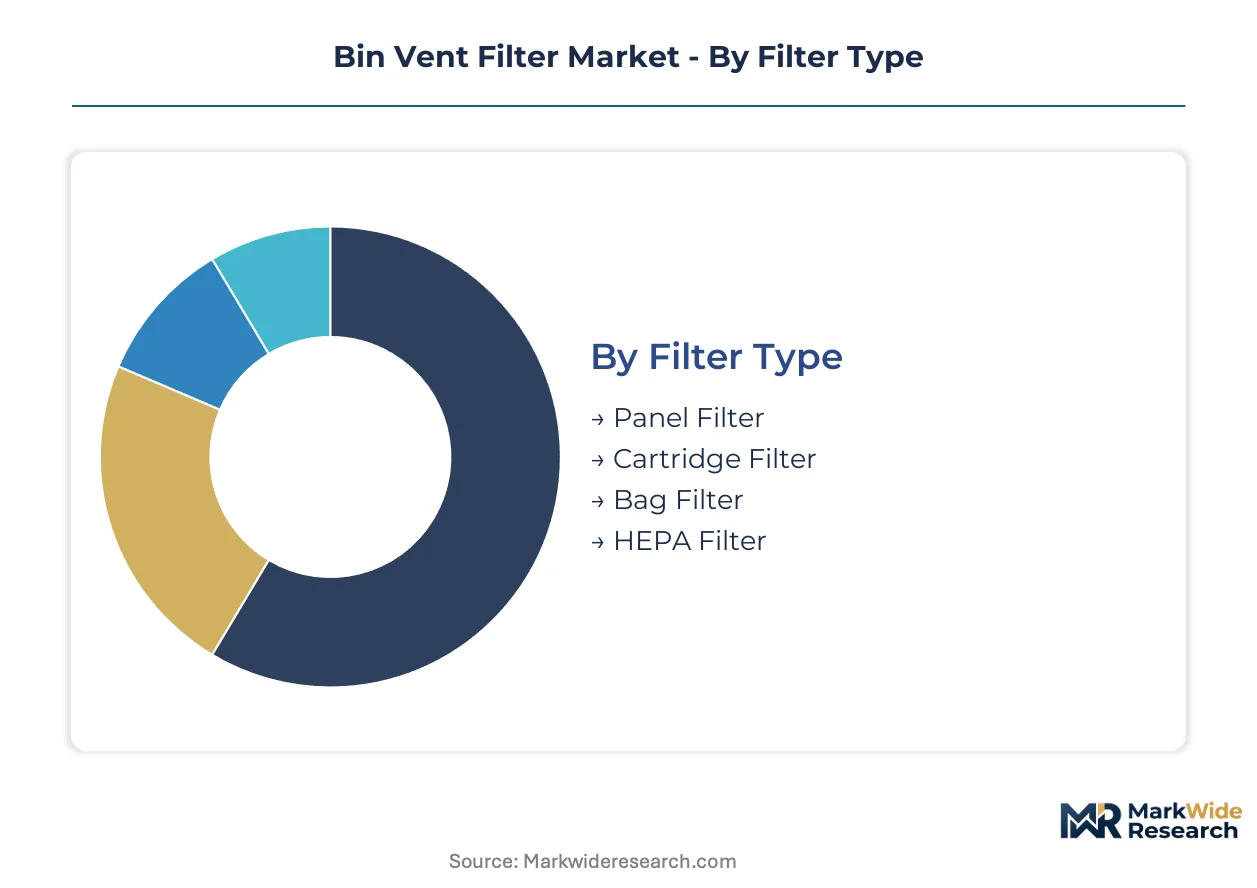
Bin vent filter procurement decisions hinge on thermal tolerance, particulate loading, and regulatory validation requirements that vary sharply across process industries. Segmentation reveals where certification burdens concentrate and which material specifications command premium positioning.
Filter Type:
Bag Filter configurations require only standard EPA opacity compliance for cement applications, while HEPA-grade installations trigger FDA validation protocols in pharmaceutical suites.
- Bag Filter:Woven fiberglass or polyester felt media withstand continuous operating temperatures above 250°F in clinker cooling operations. Cement plants in the United States deploy these for silica dust capture under tightened OSHA Permissible Exposure Limits.
- Cartridge Filter:Pleated cellulose or synthetic media deliver 2-3x surface area density in compact footprints. Food processors in Germany adopt these where EU Green Deal carbon accounting treats fugitive emissions as scope 1 liabilities.
- Panel Filter:Flat-sheet construction suits low-dust-load agricultural grain handling with minimal regulatory overlay.
- HEPA Filter:99.97% efficiency at 0.3 microns mandates FDA process validation in potent compound pharmaceutical suites.
Leading the category by volume: Bag Filter. Growing fastest: Cartridge Filter.
Application:
Cost tiers separate commodity dust control from validated containment systems with recurring compliance documentation.
- Cement Manufacturing:High-temperature baghouses handle abrasive alkaline dust from clinker grinding. German facilities face EU Industrial Emissions Directive thresholds tightening from 20 to 10 mg/Nm³.
- Pharmaceuticals:HEPA-grade bin vents integrate with isolator technology for FDA-compliant potent compound handling. Cleanroom validation requirements sustain 40-60% pricing premiums over industrial equivalents.
- Food Processing:Compact cartridge systems retrofit tight spaces in dairy powder plants where EFSA hygiene standards apply.
- Chemical Processing:Acid-resistant PTFE membranes capture phthalic anhydride and titanium dioxide particulates under Dutch National Emission Guidelines.
Highest margin concentration: Pharmaceuticals. Steepest expansion trajectory: Food Processing.
End User Industry:
Customer type determines whether procurement favors capital ownership or operational expenditure predictability through service contracts.
- Mining:Abrasive ore dust loading drives 12-18 month PTFE membrane replacement cycles. Australian iron ore handlers prioritize filter-as-a-service contracts for remote site logistics.
- Manufacturing Plants:Multi-site food chains adopt predictive pressure-drop monitoring with automated replenishment. This segment concentrates vendor subscription revenue.
- Construction:Mobile cement batching requires portable vent filters with rapid deployment specifications.
- Agriculture:Grain elevator retrofits face legacy pneumatic system integration challenges from 1970s-era infrastructure lacking instrumentation ports.
Dominant procurement volume: Manufacturing Plants. Fastest contract model shift: Mining.
Product Material:
Supply concentration for woven fiberglass and PTFE membrane in China creates tariff exposure for North American OEMs sourcing specialty media.
- PTFE:Membrane surface filtration achieves sub-10 mg/Nm³ discharge thresholds for EU Green Deal compliance. Cement applications in Poland deploy PTFE-fiberglass hybrids for structural support.
- Polyester:Standard needle-felt construction serves moderate-temperature food and agricultural applications at lowest media cost.
- Polypropylene:Moisture-resistant properties suit humid chemical processing environments.
- Cellulose:Pleated cartridge cores deliver high surface area for compact pharmaceutical and food installations.
Highest value concentration: PTFE. Volume leader: Polyester.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Filter manufacturing concentrates in Germany, China, and the United States, while consumption spreads across cement corridors and pharmaceutical clusters worldwide. Procurement patterns diverge sharply between regions with mature environmental enforcement and those with emerging compliance frameworks.
United States
OSHA's tightened silica Permissible Exposure Limits are forcing cement terminals and bulk material handlers toward automated pulse-cleaning cartridge systems. EPA National Emission Standards for Hazardous Air Pollutants shape inspection frequencies and filter efficiency specifications across process industries. The Gulf Coast chemical corridor and Midwest grain belt drive concentrated demand for stainless-steel bin vent configurations.
Germany
Cement producers face EU Green Deal carbon border adjustments that classify fugitive dust as reportable scope 1 liabilities. The EU Industrial Emissions Directive's 2024 amendment tightened Best Available Technique thresholds from 20 to 10 mg/Nm³. Industrial clusters in North Rhine-Westphalia and Bavaria are deploying PTFE membrane-bag hybrid systems to meet these discharge limits.
China
Woven fiberglass and PTFE membrane production clusters create supply-side concentration for global filter media. The Ministry of Ecology and Environment enforces tightening PM10 standards for bulk material storage and cement manufacturing. Yangtze River Delta cement producers are upgrading sealed bin vent configurations to comply with dual carbon goals and regional air quality mandates.
India
The Bureau of Indian Standards is finalizing PM10 discharge limits for bulk material storage, creating first-mover opportunities for integrated venting suppliers. Cement capacity expansion concentrates in Rajasthan, Gujarat, and Andhra Pradesh. Domestic and international vendors are positioning integrated venting and pneumatic conveying packages ahead of enforcement rollout.
Netherlands
Chemical plants face National Emission Guidelines for Air pressure comparable to EU Industrial Emissions Directive stringency. Phthalic anhydride and titanium dioxide handling operations require acid-resistant PTFE membrane configurations. The Rotterdam-Antwerp petrochemical corridor sustains premium demand for validated containment systems with recurring compliance documentation.
Bin Vent Filter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the bin vent filter supply base. Equipment fabricators with captive steel forming and welding capacity face off against engineering houses that outsource housing construction and concentrate on filter media specification and system integration. Three archetypes dominate: integrated venting specialists with ductwork-to-filter capabilities, aftermarket-focused vendors with subscription logistics networks, and regional fabricators competing on custom engineering for abrasive chemical environments. Consolidation pressure is building through strategic partnerships between media suppliers and housing fabricators, while geographic expansion into India's cement corridor accelerates.
Among North American filtration specialists, Donaldson Company exemplifies the aftermarket-centric archetype with logistics networks designed for recurring media replenishment. Baghouse America occupies a position within custom-engineered configurations for abrasive environments. Camcorp represents the integrated venting specialist model, anchoring competitiveness on system-level engineering that extends beyond component supply. These three patterns illustrate how vendor strategies diverge between capital ownership models and operational expenditure predictability through service contracts.
| Leading Market Players |
|---|
| Donaldson Company |
| Baghouse America |
| Carmeuse Systems |
| Airex Industries |
| US Air Filtration |
| ACT Dust Collectors |
| Camcorp |
| Venturedyne |
| Cyclonaire |
| Others |
Pricing and Supply Chain Analysis
Stainless steel 316L price indices cascade through bin vent filter manufacturing into three-tier pricing stratification across premium PTFE membrane systems, standard polyester configurations, and economy cellulose cartridge units. Raw material premiums of 40-60% over carbon steel compress margins for mid-size housing fabricators while concentrating pricing power with integrated vendors who control captive steel forming capacity.
Pricing Analysis
Margin tightening in standard polyester bag tiers reflects woven fiberglass supply concentration in China and tariff volatility exposure for North American OEMs. Three-tier pricing structure across premium PTFE membrane, standard needle-felt, and economy cellulose levels separates FDA-validated pharmaceutical containment from industrial cement applications. Cost-down pressure on cartridge systems accelerates as food processors prioritize operational expenditure predictability through filter-as-a-service contracts. Manufacturing plants exhibit lowest price sensitivity due to bundled predictive maintenance subscriptions, while agricultural grain elevators face acute budget constraints on legacy retrofit projects.
Supply Chain Analysis
Dual-sourcing mandates from cement and pharmaceutical end-users require qualified PTFE membrane suppliers in China, Germany, and the United States to mitigate single-source vulnerability. Woven fiberglass yarn, PTFE resin, and 316L stainless steel sheet constitute critical input dependencies. Tariff exposure on Chinese filter media exports creates pricing volatility for North American equipment fabricators lacking backward integration into membrane production. Distribution runs through OEM direct sales for large cement producers, regional integrators for mid-cap chemical processors, and captive service teams in United Kingdom and France for dairy powder manufacturers seeking single-source validation compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA National Emission Standards for Hazardous Air Pollutants and EU Industrial Emissions Directive thresholds erect regulatory moats favoring validated incumbents over unqualified challengers.
For Market Incumbents: Hedge against PTFE membrane supply disruption by qualifying secondary media sources in Germany and the United States alongside Chinese primaries. Cement sector consolidation in India demands localized housing fabrication capacity to defend position against emerging regional fabricators. Subscription logistics networks for automated filter replenishment represent the priority defensive lever against asset-light competitors. For New Entrants and Emerging Players: Mobile cement batching operators in India's Rajasthan and Gujarat corridors present an underserved buyer archetype requiring rapid-deployment portable vent filters ahead of Bureau of Indian Standards enforcement rollout. Pharmaceutical isolator integration partnerships offer white-space penetration where FDA validation requirements deter commodity vendors. Target first-mover positioning through integrated venting and pneumatic conveying packages rather than component-only supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor aftermarket-centric filtration specialists with established logistics networks in the United States Midwest and Gulf Coast chemical corridors. Long-term viability hinges on recurring revenue density from filter-as-a-service contracts displacing capital purchase models. Monitor India's cement capacity expansion announcements as the inflection signal for integrated system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Filter-as-a-Service Contract Expansion | Predictive pressure-drop monitoring transfers operational risk from cement producers to OEMs under guaranteed uptime clauses. |
| Backward Integration into PTFE Membrane Production | Captive membrane manufacturing insulates North American fabricators from Chinese export license delays and tariff volatility. |
| India Manufacturing Footprint Establishment | Localized housing fabrication captures Bureau of Indian Standards compliance-driven demand in Rajasthan cement clusters. |
| Pharmaceutical Isolator Technology Partnership | HEPA-grade bin vent integration with closed transfer systems penetrates FDA-validated potent compound handling suites. |
| Wireless Telemetry Infrastructure Deployment | Cloud-based differential pressure sensors enable continuous remote diagnostics compressing traditional 12-month inspection cycles. |
Research Methodology
Document review covered EPA enforcement databases, EU Industrial Emissions Directive amendment texts, and cement industry trade publications, complemented by interviews with plant engineers at bulk material handling facilities, procurement leads at multi-site food manufacturers, aftermarket service heads at filtration OEMs, and regulatory compliance officers at pharmaceutical manufacturers. Secondary validation drew from OSHA Permissible Exposure Limit filings, customs records for woven fiberglass and PTFE membrane trade flows, and SEC 10-K disclosures from publicly traded filtration specialists. Bottom-up equipment unit economics and top-down industry demand modeling were cross-referenced for triangulation.
Historical capacity deployment patterns were cross-referenced against panel input from plant engineering directors to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated filter type, application industry, end-user procurement model, and regional regulatory cluster dimensions. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and enforcement timeline phasing. Forecast inputs included PTFE membrane replacement frequency compression in cement applications and pharmaceutical validation protocol adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation timing and India Bureau of Indian Standards enforcement rollout schedules. Deviation in China's export licensing regime for specialty filter media would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Tide Gauge Market
Environmental Control Solutions
Global Flue Gas Treatment Systems Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Flue Gas Desulfurization Systems Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Thermal Incinerator Market