
 Indonesia Oilfield Equipment Rental Services Market | 2026-2036
Indonesia Oilfield Equipment Rental Services Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Oilfield Equipment Rental Services Market Foresight
The shift from asset ownership to outsourced equipment provisioning is realigning capital deployment across Indonesia's upstream sector. Schlumberger Limited anchors deepwater drilling packages through integrated project structures. PT Elnusa Tbk dominates domestic well services with state-linked procurement channels. Weatherford International plc competes on pressure control specialization across marginal field developments.
Indonesia oilfield equipment rental services encompass the temporary provision of drilling rigs, well intervention systems, pumps, and blowout preventers for hydrocarbon extraction operations, typically rated for high-pressure sour service conditions exceeding 10,000 psi. These assets reduce upfront capital intensity for operators managing reservoir decline in maturing concessions. Drilling rigs command the largest equipment type share due to jack-up and platform rig demand in the Java Sea. Short-term rental structures are expanding fastest among independent operators seeking flexibility on exploration commitments. Maintenance services capture disproportionate margin pools through OEM-certified refurbishment protocols and spare parts captive supply.
SKK Migas, Indonesia's upstream oil and gas regulator, mandates local content thresholds that shape equipment sourcing decisions for international contractors. BIS-equivalent certification requirements and Ministry of Energy and Mineral Resources drilling safety directives govern pressure control equipment deployment standards. Stakeholders must monitor regulatory enforcement consistency across devolved licensing authorities as marginal field awards accelerate contractor qualification demands.
Market Dynamics
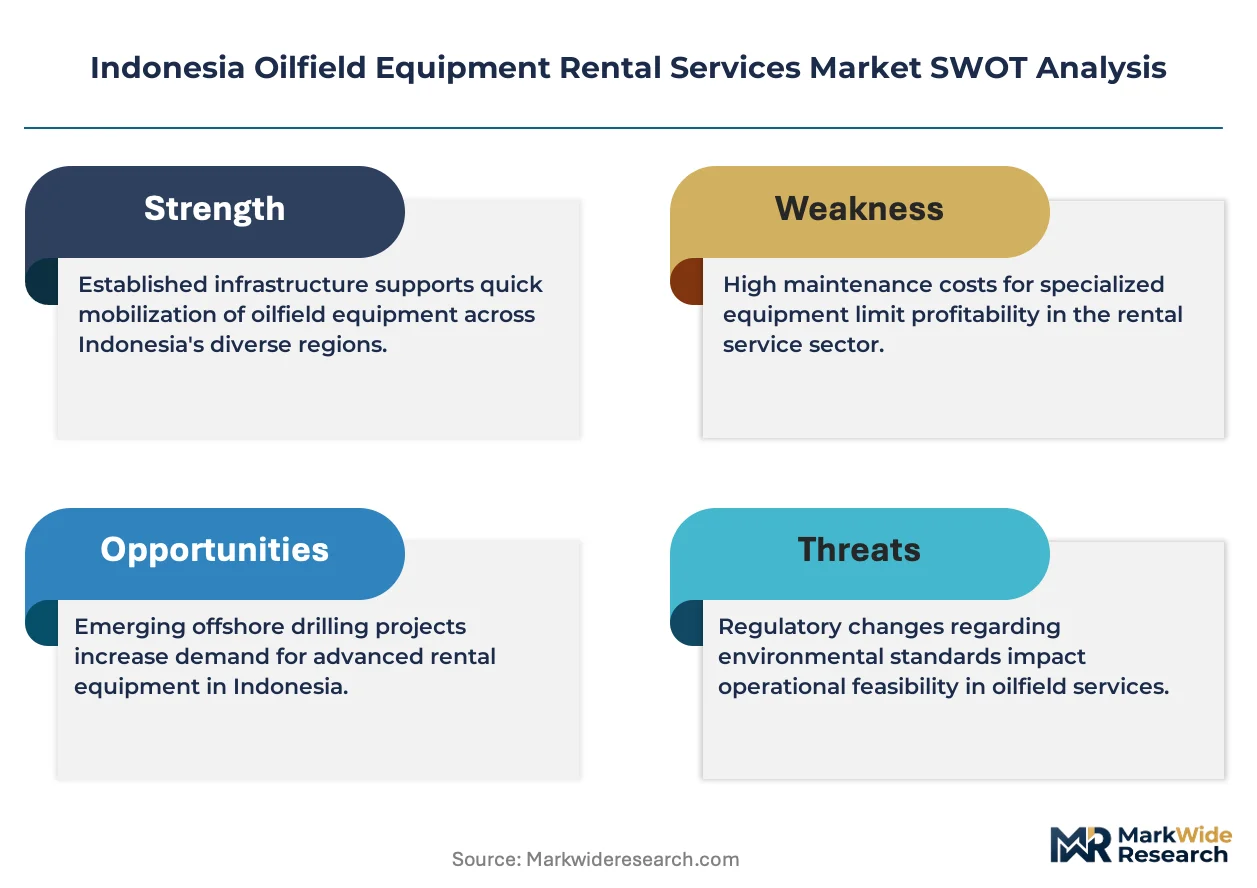
SKK Migas local content mandates are compressing procurement timelines for international contractors while rerouting equipment sourcing toward domestic fabrication yards in Batam and Surabaya. This regulatory pressure is accelerating joint venture formations between global OEMs and Indonesian fabricators to maintain contract eligibility.
Growth Catalysts
- SKK Migas TKDN thresholds:Domestic content requirements above 35% for drilling packages are forcing contractors to source blowout preventers and wellheads from certified local workshops, expanding the addressable base for indigenous rental providers.
- Duri steamflood rehabilitation:Chevron's mature field revitalization in Rokan Block is generating demand for high-pressure pumping units and thermal wellhead assemblies on short-cycle rental terms.
- Modular rig skidding systems:Pad drilling campaigns in Sumatra's heavy oil belts are adopting walking systems that reduce rig-up time from fourteen days to four, accelerating rental turnover rates.
Market Restraints
- Steel alloy input volatility:Chromium-molybdenum grades for sour service pressure control equipment face price swings tied to South African mining output, compressing refurbishment margin pools.
- Deepwater rig supply concentration:Jack-up availability for Java Sea development is bottlenecked through Singapore-based lessors, limiting Indonesian operators' negotiating leverage on day rates.
- BIS-equivalent certification delays:Ministry of Energy and Mineral Resources pressure equipment approvals average eleven months, freezing asset deployment for new market entrants.
Strategic Opportunities
- East Kalimantan marginal fields:Pertamina's awarded blocks in Kutei Basin lack established service infrastructure, creating first-mover advantage for mobile rig and well intervention system providers.
- Carbon capture readiness retrofits:SKK Migas production sharing contract amendments are incentivizing CO2 handling package integration into existing gas compression rental fleets.
- Digital twin integration:Real-time asset performance monitoring is converging with predictive maintenance protocols, enabling outcome-based rental pricing for critical path equipment.
Industry Challenges
- API Q1 welding inspector scarcity:Certified technicians for high-pressure repair work command premium wages that inflate maintenance service delivery costs.
- Legacy wellhead compatibility:Decades-old casing designs in North Sumatra fields require custom adapter fabrication, extending engineering lead times for rental package assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Oilfield Equipment Rental Services Market |
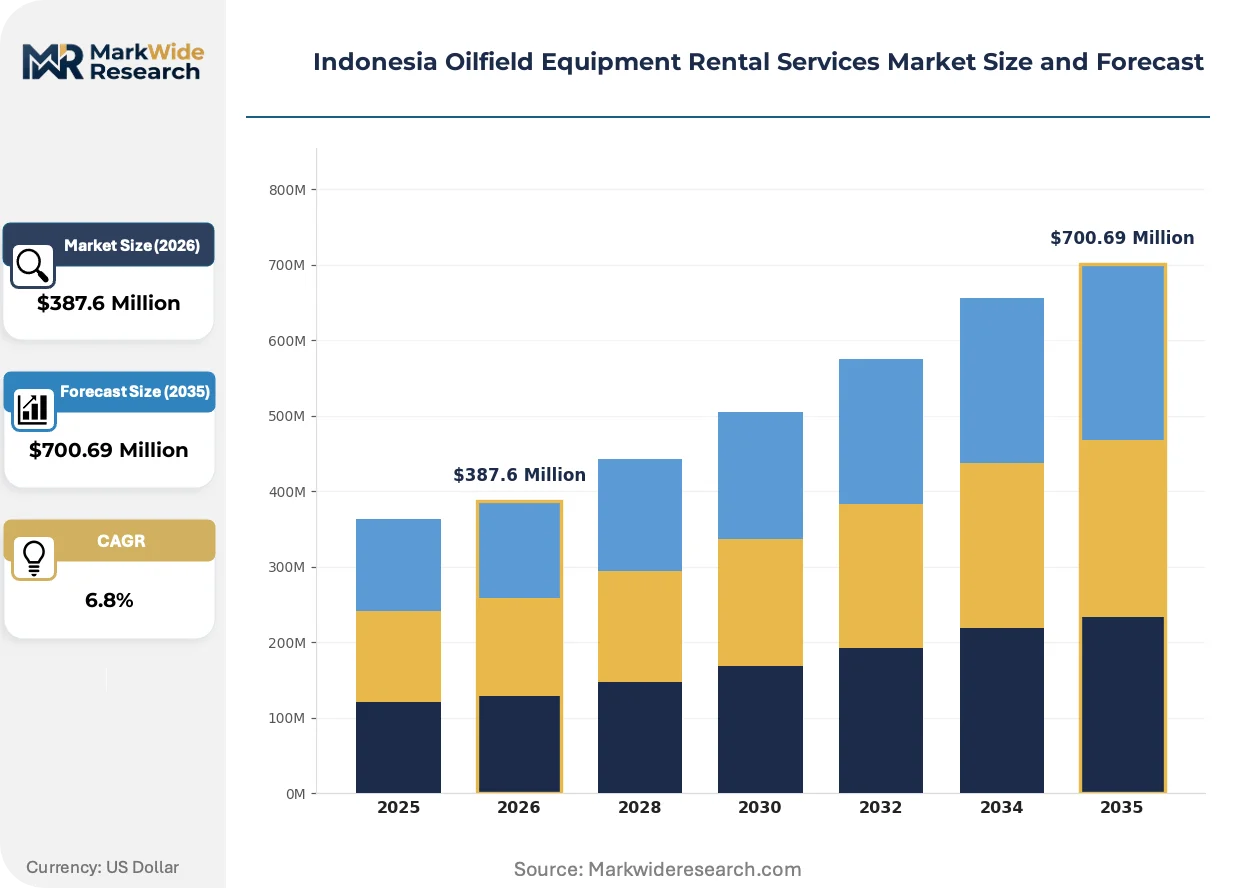
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Drilling Rigs, Well Services Equipment, Pumps, Pressure Control Equipment Service Type: Short-term Rental, Long-term Rental, Maintenance Services, Support Services Client Type: Independent Operators, Major Oil Companies, Service Contractors, Research Institutions Application: Onshore Operations, Offshore Operations, Exploration, Production |
| Companies Covered | Weatherford International plc, National Oilwell Varco, Inc., Schlumberger Limited, Pertamina, PT Elnusa Tbk, Halliburton Company, Atlas Copco AB, OFS Energy, Baker Hughes Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Oilfield Equipment Rental Services Market Shifts & Advancements
Remote monitoring architectures are collapsing the information asymmetry between equipment lessors and field operators. This transparency shift is enabling usage-based billing models and predictive intervention scheduling that were structurally impossible under paper-based maintenance logs.
Telemetry-enabled blowout preventer control systems are decentralizing maintenance decision-making from centralized workshops to platform-based technicians. Independent operators in the Java Sea corridor are adopting these systems fastest, driven by helicopter logistics constraints that penalize unplanned shutdowns. The technology is compressing mean time to repair for critical pressure control functions from seventy-two hours to under eighteen.
SKK Migas drilling safety directive revisions are mandating real-time kick detection integration across all rented drilling packages. This regulatory tightening is forcing rental providers to retrofit legacy rigs with automated flow monitoring or face contract disqualification. Offshore contractors in the Mahakam Delta are absorbing the highest compliance costs due to saltwater corrosion exposure on sensor housings.
Short-term rental structures are displacing traditional five-year bareboat charters among Pertamina's exploration subsidiaries. These operators now preference ninety-day rolling contracts with maintenance-inclusive terms, transferring residual value risk to equipment owners. The behavioral shift is most pronounced in frontier basin wildcatting where drilling commitment timelines remain uncertain.
Indonesia Oilfield Equipment Rental Services Market Segmentation
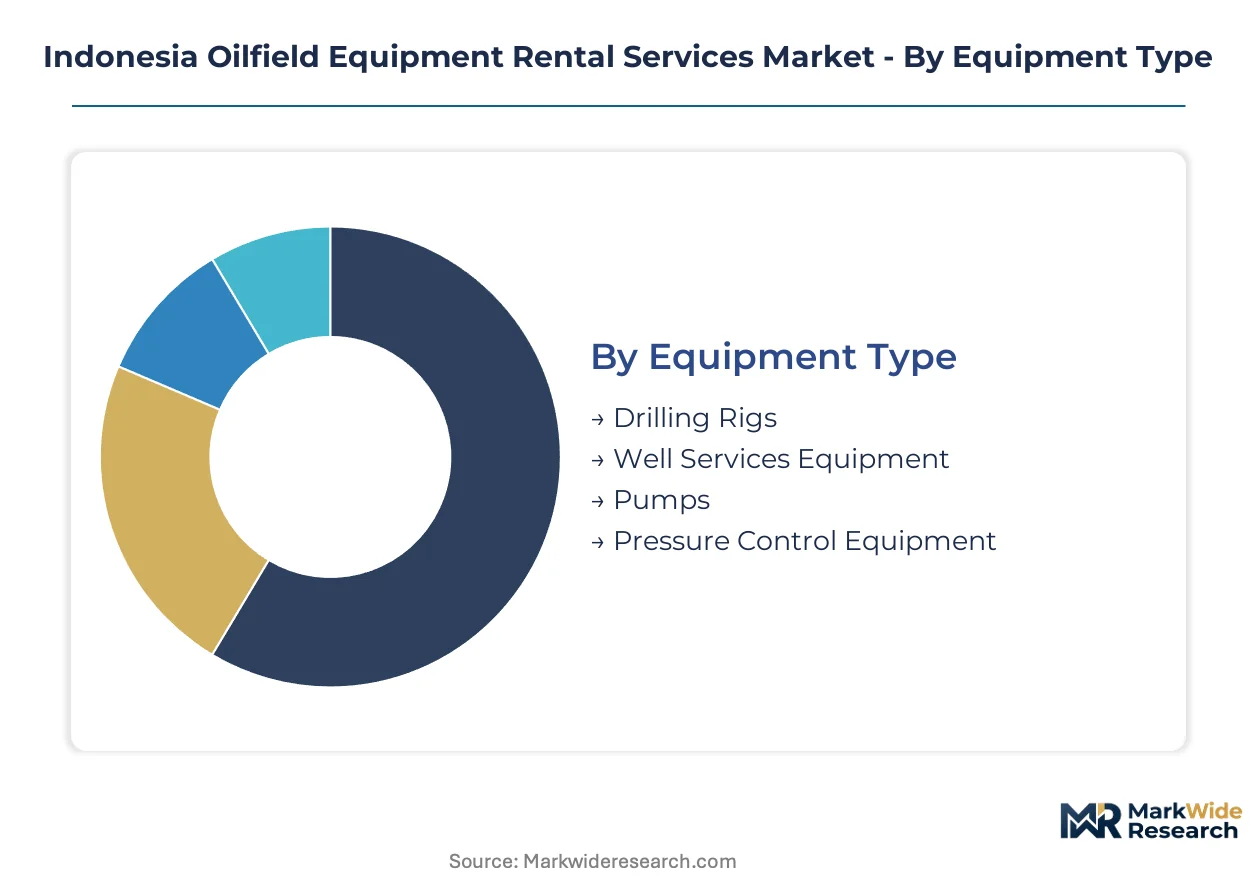
Equipment rental segmentation in Indonesia tracks how capital discipline and regulatory mandates reshape contractor procurement patterns. Each dimension reveals distinct margin pools and competitive positioning strategies for lessors navigating SKK Migas compliance requirements.
Equipment Type:
Replacement cycles for high-pressure sour service equipment are compressing as operators push assets harder to maintain production from maturing concessions.
- Drilling Rigs:Jack-up and platform rig configurations dominate offshore deployment in the Java Sea corridor. Chevron's Rokan Block drilling commitments and Pertamina's frontier basin wildcatting concentrate demand for mobile units with rapid skidding capabilities.
- Pressure Control Equipment:Blowout preventers and wellhead assemblies rated above 10,000 psi face accelerated turnaround requirements under revised SKK Migas drilling safety directives. Saltwater corrosion exposure in the Mahakam Delta drives replacement frequency above onshore basins.
- Well Services Equipment:Coiled tubing units and wireline trucks serve thermal recovery campaigns in Sumatra's heavy oil belts.
- Pumps:High-pressure pumping units support Duri steamflood rehabilitation with modular configurations for pad drilling efficiency.
Drilling rigs sit at the top of the volume ranking, with pressure control equipment climbing the fastest.
Service Type:
Contract duration preferences are fragmenting as exploration uncertainty and capital constraints reshape operator risk allocation.
- Short-term Rental:Ninety-day rolling contracts with maintenance-inclusive terms now dominate Pertamina subsidiary exploration programs. Independent operators in frontier basins favor this structure to preserve balance sheet flexibility on unproven commitments.
- Maintenance Services:OEM-certified refurbishment protocols and captive spare parts supply capture disproportionate margin pools. API Q1 welding inspector scarcity inflates service delivery costs for high-pressure repair work across the archipelago.
- Long-term Rental:Traditional five-year bareboat charters persist for established production assets with predictable utilization profiles.
- Support Services:Logistics coordination and field engineering supplement core equipment provision in remote East Kalimantan developments.
Maintenance services command the widest margin spread, while short-term rental structures expand most quickly among independent operators.
Client Type:
Procurement authority concentration varies sharply across Indonesia's upstream landscape, shaping lessor sales force deployment.
- Major Oil Companies:Chevron and Pertamina operate integrated procurement systems with stringent TKDN compliance verification. Their Rokan Block and Mahakam Delta operations drive standardized equipment specifications across drilling packages.
- Independent Operators:Domestic exploration specialists and foreign wildcatters prioritize rental flexibility over asset ownership. Their capital-constrained positions accelerate adoption of usage-based billing models with predictive maintenance integration.
- Service Contractors:International drilling contractors face compressed procurement timelines under SKK Migas local content mandates, rerouting sourcing toward Batam and Surabaya fabrication yards.
- Research Institutions:Limited demand concentrates on specialized well testing and reservoir characterization equipment for collaborative government-university programs.
Major oil companies anchor contract value, with independent operators representing the steepest expansion trajectory.
Application:
Geographic deployment patterns reflect infrastructure maturity and regulatory jurisdiction fragmentation across Indonesia's archipelagic basins.
- Offshore Operations:Java Sea development and Mahakam Delta gas production drive jack-up rig demand through Singapore-based lessor channels. Helicopter logistics constraints penalize unplanned shutdowns, accelerating telemetry-enabled remote monitoring adoption.
- Onshore Operations:Sumatra's Duri-Rokan heavy oil fields and North Sumatra legacy assets generate demand for thermal wellhead assemblies and custom adapter fabrication. Decades-old casing designs require engineering lead time extensions for rental package assembly.
- Production:Mature field revitalization programs dominate equipment utilization with predictable, high-volume demand profiles.
- Exploration:Frontier basin wildcatting in Kutei Basin and eastern acreage exhibits erratic commitment timelines favoring short-cycle rental structures.
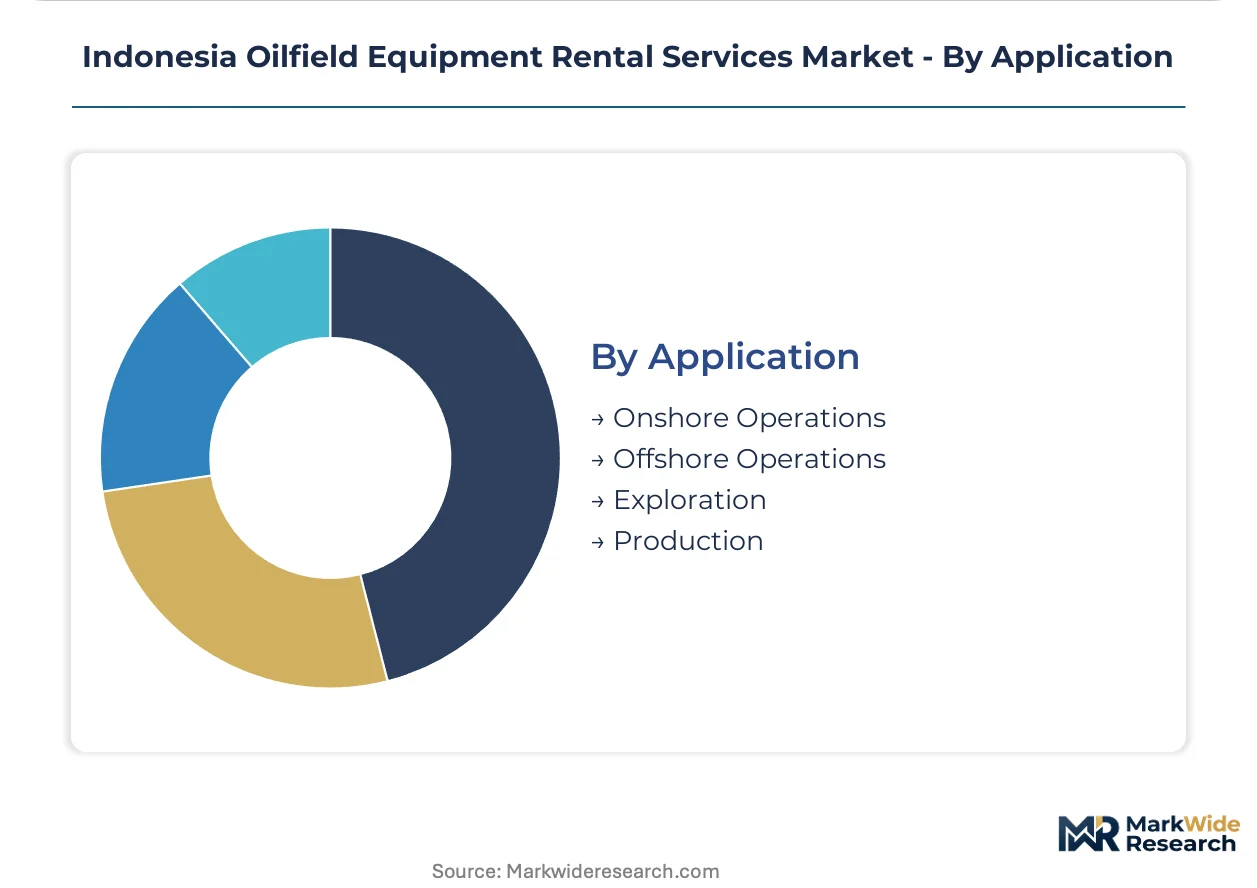
Offshore operations capture the largest equipment deployment base, with onshore production applications delivering the most stable utilization rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Java Sea offshore corridor anchors Indonesia's oilfield equipment rental demand through jack-up rig deployment and platform-based drilling packages. Sumatra's mature onshore basins generate parallel demand for thermal recovery equipment and modular skidding systems. Regulatory jurisdiction fragments across devolved licensing authorities, complicating contractor qualification timelines.
Java Sea Offshore Corridor
Chevron's Rokan Block drilling commitments and Pertamina's frontier wildcatting concentrate jack-up rig demand through Singapore-based lessor channels. SKK Migas drilling safety directives mandate real-time kick detection integration across all rented packages. Contractors operating Mahakam Delta gas fields absorb elevated compliance costs from saltwater corrosion exposure on sensor housings.
Sumatra Onshore Basins
Duri steamflood rehabilitation drives demand for high-pressure pumping units and thermal wellhead assemblies on short-cycle rental terms. Ministry of Energy and Mineral Resources BIS-equivalent certification requirements govern pressure equipment deployment standards. Decades-old casing designs in North Sumatra fields require custom adapter fabrication from Batam workshops.
East Kalimantan Marginal Fields
Pertamina's awarded Kutei Basin blocks lack established service infrastructure, creating first-mover positioning for mobile rig providers. TKDN local content thresholds above 35% reroute equipment sourcing toward Surabaya fabrication yards. Helicopter logistics constraints penalize unplanned shutdowns, accelerating telemetry-enabled remote monitoring adoption.
Riau Heavy Oil Belts
Pad drilling campaigns adopt walking rig systems that compress rig-up time from fourteen days to four, accelerating rental turnover rates. SKK Migas production sharing contract amendments incentivize CO2 handling package integration into gas compression fleets. Independent operators preference ninety-day rolling contracts with maintenance-inclusive terms.
Indonesia Oilfield Equipment Rental Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-enabled service differentiation and carbon capture readiness retrofits. The vendor base stratifies across integrated international contractors, state-linked domestic champions, and specialized pressure control specialists. Three archetypes dominate: global OEMs with integrated project structures, indigenous fabricators with TKDN certification advantages, and technology-focused specialists in predictive maintenance protocols. Competitive moves center on joint venture formations with local fabricators and retrofit investments in telemetry-enabled asset monitoring.
Within the integrated contractor tier, Schlumberger Limited and Weatherford International plc exemplify global OEMs navigating SKK Migas compliance requirements. PT Elnusa Tbk anchors the state-linked domestic segment with procurement channel proximity to Pertamina operations. These three occupy positions that reflect the market's structural tension between international technical capability and local content mandates.
| Leading Market Players |
|---|
| Weatherford International plc |
| National Oilwell Varco, Inc. |
| Schlumberger Limited |
| Pertamina |
| PT Elnusa Tbk |
| Halliburton Company |
| Atlas Copco AB |
| OFS Energy |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
SKK Migas carbon capture readiness mandates gate qualified supply access and premium-tier pricing for equipment lessors retrofitting gas compression fleets with CO2 handling packages. Contractors absorbing these compliance costs pass through elevated day rates to operators in the Mahakam Delta, while uncertified providers face contract disqualification from Pertamina procurement channels.
Pricing Analysis
Input-cost pass-through from chromium-molybdenum alloy volatility flows directly into pressure control equipment refurbishment pricing. Three-tier pricing structure across API Q1-certified premium, TKDN-compliant standard, and non-certified economy levels differentiates rental packages. Cost compression in the economy tier is intensifying because Batam fabrication yards absorb steel price swings without hedging mechanisms. Independent operators in frontier basins exhibit highest price sensitivity, while Chevron's integrated procurement accepts premium certification tiers for Rokan Block commitments.
Supply Chain Analysis
Helicopter logistics constraints and archipelagic freight costs inflate equipment mobilization expenses for Java Sea offshore contractors. Manufacturing concentrates in Singapore for jack-up rigs, South Korea for pressure control systems, and domestic Batam-Surabaya yards for TKDN-compliant assemblies. Raw material dependencies rest on South African chromium-molybdenum mining, Japanese high-grade steel, and German precision sensors. Single-source vulnerability runs through Singapore-based rig lessors controlling jack-up availability. Distribution runs through integrated project structures for majors, direct rental contracts for independents, and subcontractor tiers for service contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Indonesia oilfield equipment rental market functions as a geographic-arbitrage play where TKDN compliance costs in domestic fabrication yards run 15-20% below equivalent certified imports, creating margin expansion for local-integrated providers against pure international contractors.
For Market Incumbents: Extend predictive maintenance protocols into outcome-based rental pricing to defend against digital-native entrants offering telemetry-enabled asset monitoring. Deepen backward integration into Surabaya fabrication capacity to secure TKDN thresholds above 35% as SKK Migas enforcement tightens. Lock in long-term spare parts supply agreements to offset API Q1 welding inspector scarcity inflating service delivery costs.
For New Entrants and Emerging Players: Launch via mobile rig deployment partnerships targeting East Kalimantan's Kutei Basin marginal fields where established service infrastructure remains absent. Penetrate the short-term rental segment among independent operators preferenceing ninety-day rolling contracts over traditional bareboat charters. Lead with carbon capture readiness retrofits as SKK Migas production sharing contract amendments incentivize CO2 handling package integration.
For Investors and Strategic Acquirers: Roll-up economics work for telemetry-enabled pressure control specialists because operator demand for real-time kick detection integration is forcing legacy fleet obsolescence across the archipelago. Target acquisition archetypes include Batam-based fabricators with TKDN certification and established Pertamina procurement channels. Watch for inflection when SKK Migas drilling safety directive revisions accelerate retrofit mandates beyond current eleven-month BIS-equivalent certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| TKDN Certification Investment | Domestic content thresholds above 35% reroute procurement toward Batam-Surabaya fabrication yards. |
| Predictive Maintenance Platform Integration | Real-time asset monitoring enables usage-based billing models previously structurally impossible. |
| Carbon Capture Readiness Retrofit | SKK Migas production sharing contract amendments incentivize CO2 handling package deployment. |
| Joint Venture with Local Fabricator | Global OEMs partner with Indonesian workshops to maintain contract eligibility under local content mandates. |
| Mobile Rig Fleet Expansion | East Kalimantan marginal fields lack established service infrastructure, creating first-mover positioning. |
Research Methodology
Coverage spans Java Sea offshore corridor, Sumatra onshore basins, and East Kalimantan marginal fields, with primary inputs from each. The analysis combines interviews with SKK Migas regulatory affairs officers, Pertamina procurement managers, drilling contractor operations heads, and Batam fabrication yard technical directors with secondary validation. Secondary sources include Ministry of Energy and Mineral Resources drilling safety directives, SKK Migas production sharing contract amendments, customs import records for pressure control equipment, and Singapore Maritime Authority jack-up rig registry data. Bottom-up equipment deployment counts triangulate against top-down concession commitment valuations.
Granularity-level modeling tracks equipment type, service duration structure, client procurement authority, and geographic application at the basin level. Segmentation dimensions include drilling rigs versus pressure control equipment versus well services assets, short-term versus long-term rental structures, major oil companies versus independent operators versus service contractors, and offshore versus onshore deployment. CAGRs derive from equipment replacement cycle compression, regulatory mandate acceleration curves, and operator capital discipline behavioral shifts. Industry-specific forecast inputs incorporate Duri steamflood rehabilitation timelines and Kutei Basin marginal field award pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SKK Migas local content threshold adjustments or BIS-equivalent certification processing delays. Forecasts reflect assumptions around operator preference shifts toward rental flexibility, TKDN compliance enforcement consistency, and chromium-molybdenum price trajectory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Sucker Rod Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
US Sand Control Systems Market